
 Cider Brewing Equipment Market | 2026-2036
Cider Brewing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Cider Brewing Equipment Market Outlook
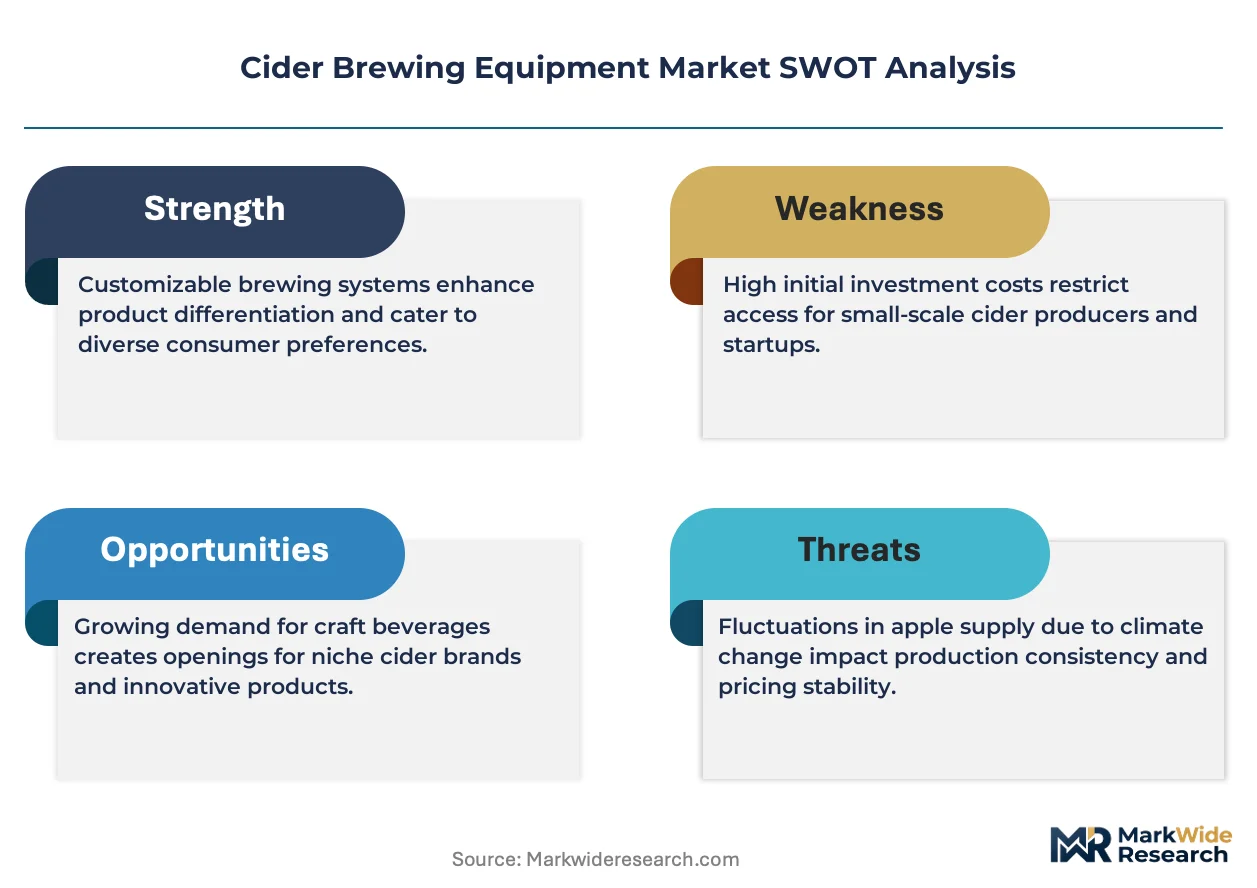
Aftermarket service revenue is tilting toward automated system calibration and predictive maintenance contracts. Stout Tanks and Kettles leverages its Oregon manufacturing base to dominate North American craft brewery supply. Della Toffola anchors European demand through specialized Italian press engineering. Micet Group extends its position in Asian markets with modular fermentation skids designed for rapid installation.
Cider brewing equipment encompasses vessels, presses, bottling lines, and thermal processing units engineered to convert apple or pear must into finished alcoholic beverages, typically operating at pressures between 0.5 and 3.0 bar during primary fermentation. Stainless steel fermenters command the largest installed base due to corrosion resistance and clean-in-place compatibility, while automated bottling lines represent the fastest-expanding segment as labor costs climb. Hybrid technologies that blend traditional oak conditioning with programmable logic controllers are capturing margin pools from pure traditional methods.
EFSA hygiene standards shape pasteurizer design specifications across European cideries, while FDA Title 21 CFR Part 110 governs equipment sanitation protocols for US exports. The EU Green Deal's energy efficiency directives are pressuring manufacturers to redesign thermal systems. Stakeholders must monitor how carbon accounting rules alter equipment procurement criteria before committing to long-term capital plans.
Market Dynamics
EU Green Deal energy efficiency directives are forcing thermal system redesigns across cider equipment manufacturing, compressing payback periods for pasteurizer upgrades and accelerating stainless steel vessel replacement cycles.
Growth Catalysts
- EFSA pasteurization mandates:Tightening hygiene standards under EFSA Regulation 2073/2005 are compelling Normandy and Brittany cideries to replace aging thermal processing units with automated pasteurization lines.
- Oak conditioning hybrids:Programmable logic controllers integrated with traditional barrel aging are capturing margin pools from pure craft methods in premium positioning.
- Clean-in-place compatibility:Stainless steel fermenter demand concentrates in United Kingdom craft cideries expanding production capacity.
Market Restraints
- Nickel price volatility:Stainless steel input costs fluctuate with Indonesian and Philippine nickel ore export restrictions, squeezing fermenter margins.
- Italian press engineering concentration:Specialized screw press manufacturing clusters in Veneto and Emilia-Romagna create supply bottleneck risk for European equipment buyers.
- Technical limitation in rapid chilling:Thermal shock resistance gaps in existing jacketed vessel designs constrain high-throughput cider production scaling.
Strategic Opportunities
- Modular fermentation skids:Rapid-installation systems designed for Asian markets with limited technical infrastructure are opening distribution channels in Southeast Asian cider startups.
- Carbon accounting procurement criteria:EU Green Deal Scope 3 disclosure requirements are creating first-mover advantage for equipment vendors with lifecycle-certified thermal systems.
- Predictive maintenance contracts:Automated system calibration services are unbundling from equipment sales into recurring revenue streams.
Industry Challenges
- PLC programming skill scarcity:Cideries struggle to source technicians capable of integrating programmable logic controllers with legacy pneumatic valve systems.
- CE-MDR dual certification timelines:Equipment manufacturers face 14-18 month approval delays for pressure vessel designs seeking simultaneous CE marking and Machinery Directive compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cider Brewing Equipment Market |
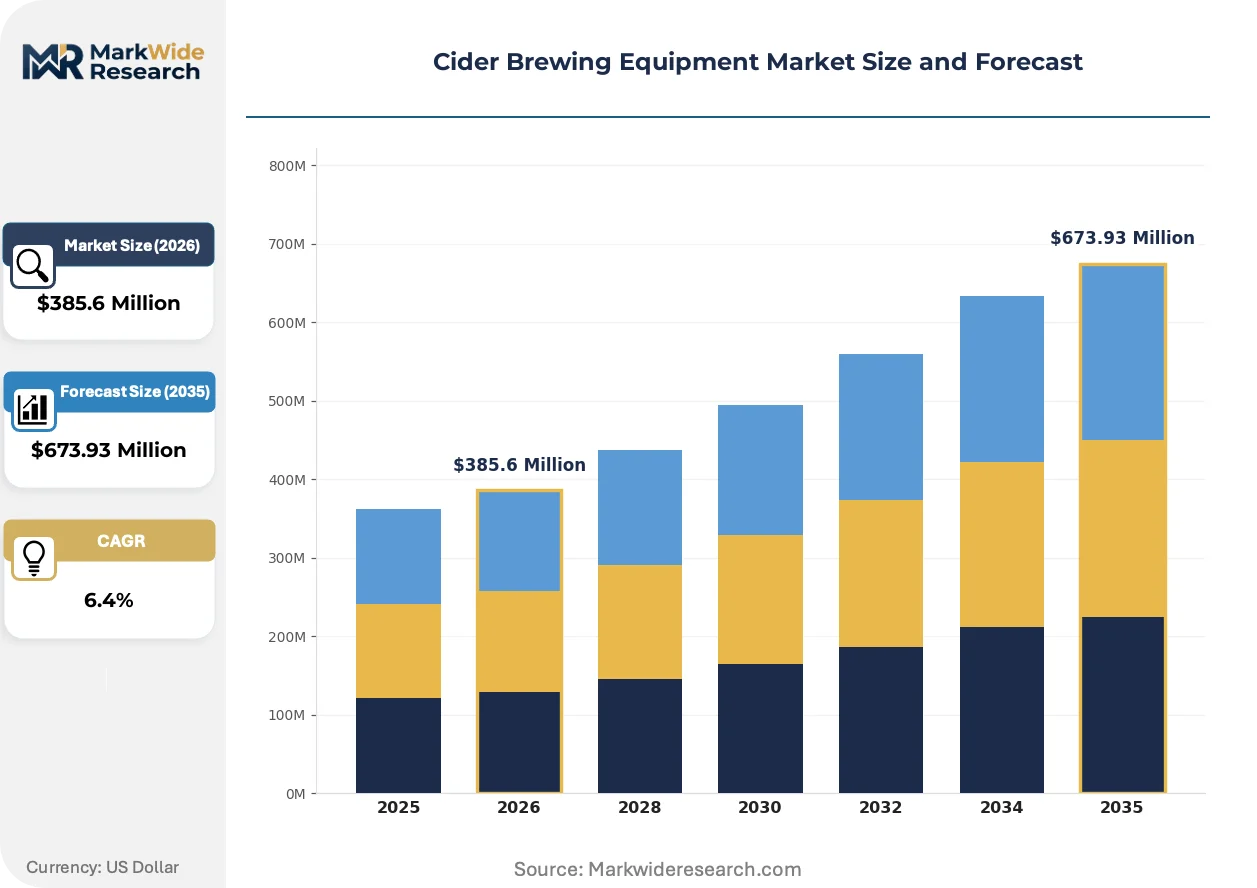
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Fermenters, Presses, Bottling Lines, Pasteurizers Material: Stainless Steel, Plastic, Wood, Glass End User: Craft Breweries, Large Producers, Home Brewers, Cideries Technology: Traditional Methods, Automated Systems, Hybrid Technologies, Mobile Units |
| Companies Covered | SRAML, Stout Tanks and Kettles, Cidernet, Inc., Micet Group, Della Toffola, Heineken NV, Vitikit, Criveller, Anheuser-Busch InBev SA/NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cider Brewing Equipment Market Strategic Shifts
Sensor networks and automation layers are penetrating cider production workflows, compressing labor dependence while tightening process control tolerances. Equipment vendors are racing to embed predictive capabilities before regulatory compliance costs escalate.
Programmable logic controllers paired with in-line refractometers are digitizing fermentation monitoring across mid-sized United Kingdom cideries. Adoption concentrates in operations exceeding 500,000 liter annual capacity. Real-time density tracking is digitizing quality assurance workflows, reducing manual sampling labor by enabling automated tank-to-tank transfers triggered by specific gravity thresholds.
EU F-Gas Regulation 2024/573 is phasing down hydrofluorocarbon refrigerants in cider chilling systems. Equipment manufacturers must redesign glycol chiller architectures to accommodate natural refrigerant alternatives. French and Spanish cideries face compressed retrofit timelines as 2027 bans on high-GWP refrigerants approach, accelerating heat pump-based thermal system procurement.
Aftermarket service unbundling is disrupting traditional equipment sales bundling. Craft cideries in Oregon and Washington now purchase fermentation vessels and bottling lines without mandatory maintenance contracts, sourcing calibration and predictive services through third-party automation specialists. This fragmentation concentrates in North American markets where technical labor mobility supports vendor-switching.
Cider Brewing Equipment Market Segmentation
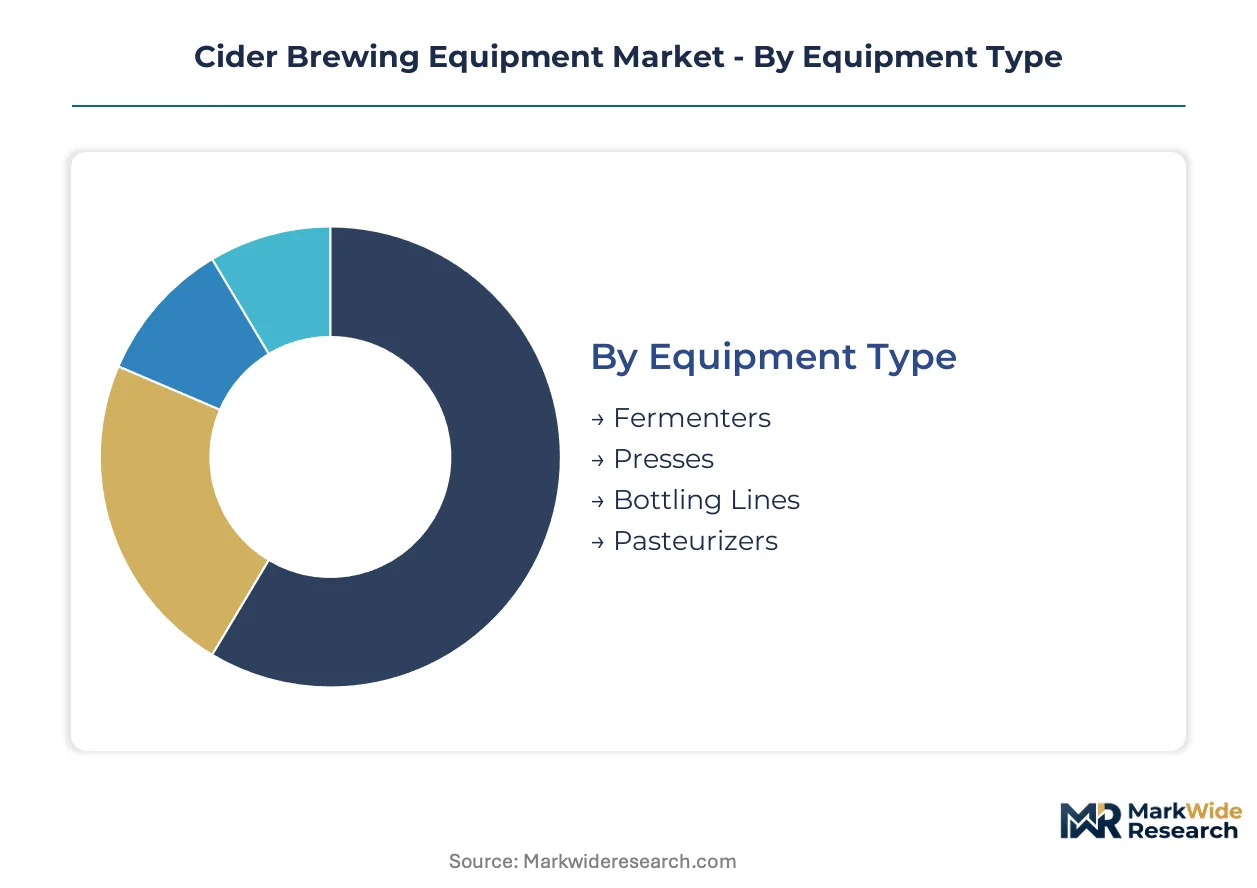
Equipment segmentation in cider brewing determines aftermarket service intensity, with automated systems requiring predictive maintenance contracts while traditional methods need periodic refurbishment. Stainless steel fermenters and hybrid technologies concentrate service revenue through calibration and spare parts programs.
Equipment Type:
After-sales service intensity varies sharply across vessel categories, with thermal processing units demanding the most intensive technical support due to EFSA compliance requirements.
- Fermenters:Stainless steel vessels with jacketed cooling systems dominate capital expenditure in United Kingdom craft cideries expanding production capacity. Demand clusters in Normandy and Brittany where EFSA pasteurization mandates are accelerating stainless steel replacement cycles.
- Presses:Italian-engineered screw presses with specialized pomace handling represent the highest-margin equipment category. Supply bottlenecks in Veneto and Emilia-Romagna constrain delivery timelines for European buyers seeking high-throughput apple processing.
- Bottling Lines:Automated filling and capping systems reduce labor dependence in mid-sized operations exceeding 500,000 liter annual capacity.
- Pasteurizers:Thermal processing units face compressed retrofit timelines under EU F-Gas Regulation 2024/573 phasing down hydrofluorocarbon refrigerants.
Fermenters hold the largest share; momentum sits with pasteurizers as regulatory deadlines approach.
Material:
Raw material cost tiers shape procurement patterns, with nickel price volatility directly impacting stainless steel vessel margins and hybrid oak-steel configurations commanding premium positioning.
- Stainless Steel:Corrosion-resistant 304 and 316 grade alloys enable clean-in-place compatibility across commercial cideries. Nickel ore export restrictions from Indonesia and the Philippines squeeze fermenter margins and extend replacement cycles.
- Wood:Traditional oak conditioning barrels integrate with programmable logic controllers in premium positioning strategies. French cideries in Normandy maintain heritage methods while digitizing temperature monitoring.
- Plastic:Polyethylene fermentation tanks serve home brewers and small-scale operations with limited capital budgets.
- Glass:Secondary fermentation carboys persist in artisanal production despite handling constraints.
Stainless steel holds the largest share; hybrid wood-steel configurations are gaining share fastest.
End User:
Customer scale determines equipment specification complexity, with large producers standardizing on integrated lines while craft operations prioritize modular upgrade paths.
- Craft Breweries:Small-batch operations in Oregon and Washington source fermentation vessels without mandatory maintenance contracts, fragmenting aftermarket service toward third-party automation specialists. Equipment purchases emphasize rapid-installation skids with limited technical infrastructure requirements.
- Large Producers:Industrial-scale cideries deploy fully automated bottling lines with in-line refractometers and real-time density tracking. These operations digitize quality assurance workflows and reduce manual sampling labor through automated tank-to-tank transfers.
- Home Brewers:Entry-level plastic fermenters and small presses dominate this price-sensitive segment.
- Cideries:Dedicated apple and pear wine producers balance traditional methods with regulatory compliance across France, Spain, and the United Kingdom.
Large producers hold the largest share; craft breweries are expanding most quickly.
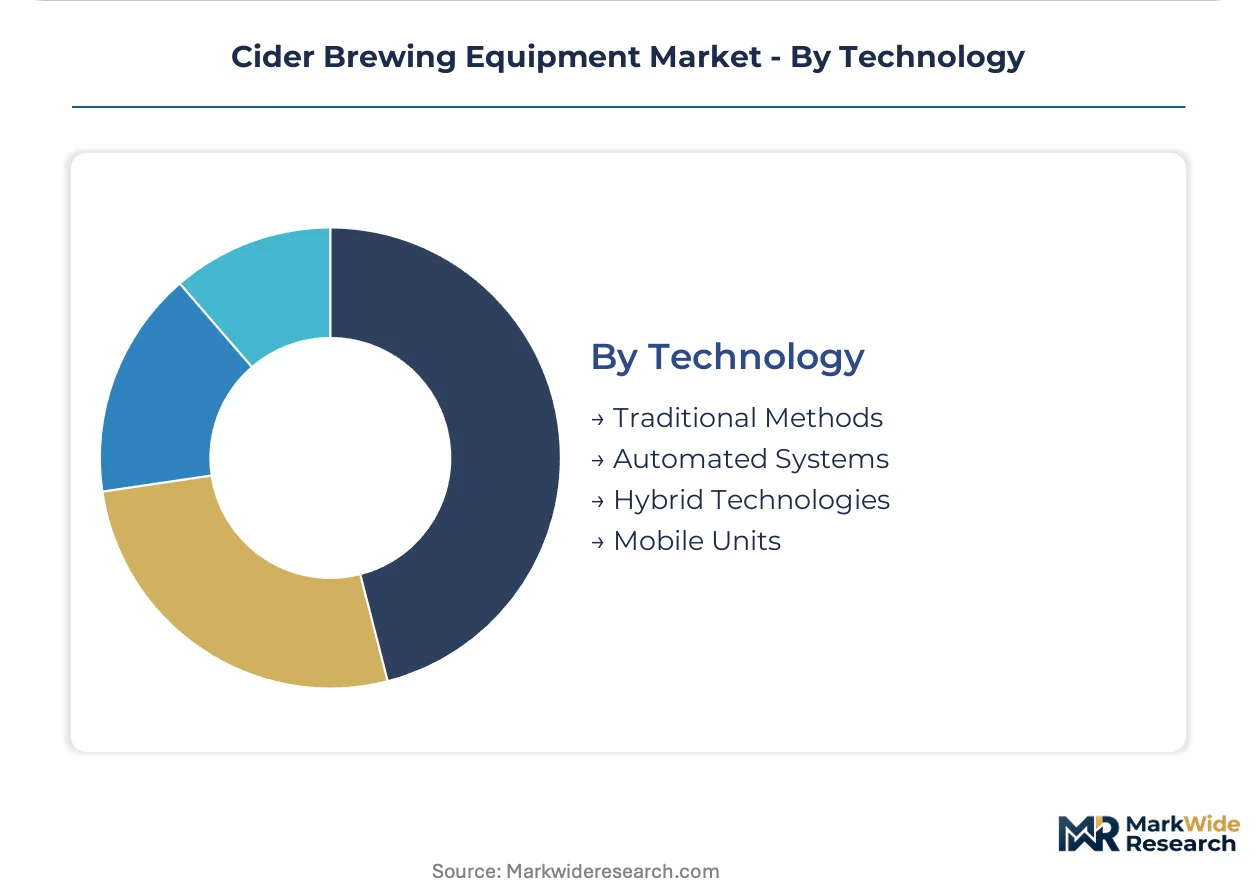
Technology:
Technology maturity curves separate established pneumatic systems from digital retrofit opportunities, with PLC integration creating skill scarcity challenges for equipment operators.
- Automated Systems:Programmable logic controllers paired with sensor networks compress labor dependence while tightening process control tolerances. United Kingdom cideries above 500,000 liter capacity adopt real-time fermentation monitoring to trigger specific gravity thresholds.
- Hybrid Technologies:Oak conditioning barrels with integrated temperature and humidity controls capture margin pools from pure craft methods. These systems bridge heritage positioning with programmable precision in premium market tiers.
- Traditional Methods:Pneumatic valve systems and manual sampling persist in smaller Normandy and Brittany operations despite technician recruitment challenges.
- Mobile Units:Containerized fermentation skids designed for rapid installation open distribution channels in Southeast Asian cider startups with limited technical infrastructure.
Traditional methods hold the largest share; automated systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France consumes cider brewing equipment through heritage-driven premium positioning, while the United Kingdom deploys identical hardware for high-volume craft scaling. The United States applies these systems within beverage diversification strategies. Spain and China round out demand concentration with divergent regulatory and infrastructure contexts.
France
Normandy and Brittany cideries anchor equipment demand through EFSA pasteurization mandates under Regulation 2073/2005. The EU Green Deal pressures thermal system redesigns ahead of 2027 F-Gas refrigerant phase-downs. French oak conditioning traditions now integrate programmable logic controllers in premium tier positioning.
United Kingdom
Craft cideries in England and Wales expand stainless steel fermenter purchases to meet clean-in-place compatibility requirements. EFSA hygiene standards shape pasteurizer specifications for export-oriented producers. Birmingham and Manchester clusters concentrate mid-sized operations adopting automated bottling lines above 500,000 liter capacity.
United States
Oregon and Washington craft breweries source fermentation vessels without mandatory maintenance contracts, fragmenting aftermarket service toward third-party automation specialists. FDA Title 21 CFR Part 110 governs sanitation protocols for equipment exports. The Pacific Northwest anchors North American demand through beverage diversification into hard cider.
Spain
Asturian and Basque cider producers face compressed retrofit timelines under EU F-Gas Regulation 2024/573 phasing down hydrofluorocarbon refrigerants by 2027. Spanish cideries accelerate heat pump-based thermal system procurement. Barcelona and Madrid industrial zones concentrate equipment distribution for Iberian Peninsula markets.
China
Modular fermentation skids designed for rapid installation open distribution channels in Southeast Asian cider startups with limited technical infrastructure. Chinese manufacturers supply cost-optimized vessels to emerging Asian markets. Zhengzhou and Shanghai fabrication hubs serve regional demand through scaled production of polyethylene fermentation tanks.
Cider Brewing Equipment Market Competitive Environment
Capability concentration sits with Italian and German engineering specialists; scale advantage sits with Chinese and North American volume fabricators. The market structures around three tiers: heritage European press engineers, modular Asian skid assemblers, and North American craft-focused tank fabricators. Consolidation pressures concentrate among thermal system specialists facing EU refrigerant mandates. Dominant competitive moves include geographic expansion into Asian startup markets and backward integration into nickel alloy supply chains.
Among Oregon-based fabricators, Stout Tanks and Kettles occupies a position exemplifying North American craft brewery supply concentration. Della Toffola represents Italian press engineering heritage within European equipment architecture. Micet Group anchors the modular skid tier for Asian market penetration. These three company structures illustrate how geographic origin and organizational form map onto divergent competitive strategies across the equipment landscape.
| Leading Market Players |
|---|
| SRAML |
| Stout Tanks and Kettles |
| Cidernet, Inc. |
| Micet Group |
| Della Toffola |
| Heineken NV |
| Vitikit |
| Criveller |
| Anheuser-Busch InBev SA/NV |
| Others |
Value Chain & Pricing Dynamics
Nickel ore export restrictions from Indonesia and the Philippines compress fermenter margins and simultaneously determine pricing tier spreads across stainless steel vessel categories while forcing supply chain consolidation toward captive alloy sourcing. Equipment buyers face widened cost differentials between standard 304-grade fermenters and premium 316-grade systems as raw material volatility feeds directly into procurement decisions.
Pricing Analysis
Long-term offtake contracts dominate procurement for large producers securing thermal processing units, while spot purchasing persists among craft cideries sourcing modular fermentation skids. Three-tier pricing structure across premium, standard, and economy levels separates Italian-engineered screw presses with specialized pomace handling from Chinese polyethylene tanks and mid-range stainless steel vessels. Cost compression in standard-grade equipment is intensifying because nickel price volatility squeezes fabricator margins. Craft breweries in Oregon and Washington exhibit highest price sensitivity, unbundling aftermarket services to reduce upfront capital outlay, while Normandy cideries pursuing heritage positioning show lowest sensitivity due to premium tier anchoring.
Supply Chain Analysis
EU F-Gas Regulation 2024/573 restricts hydrofluorocarbon refrigerant flows and forces thermal system redesigns, compressing retrofit timelines for pasteurizer manufacturers. Manufacturing concentrates in Italy for specialized press engineering, China for cost-optimized vessel fabrication, and Germany for precision thermal processing components. Raw material sourcing draws from Indonesian and Philippine nickel ore deposits, Italian stainless steel rolling capacity, and Chinese glycol chiller component ecosystems. Single-source vulnerability concentrates in Veneto and Emilia-Romagna screw press manufacturing clusters. Distribution runs through equipment distributors in Barcelona and Madrid industrial zones serving Iberian markets, Birmingham and Manchester clusters for United Kingdom craft operations, and Zhengzhou and Shanghai fabrication hubs for Asian market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cider brewing equipment market sits in cyclical recovery as regulatory compliance deadlines compress replacement cycles and restock capital expenditure pipelines. EFSA pasteurization mandates and EU F-Gas refrigerant phase-downs create synchronized demand pulses across European cideries.
For Market Incumbents: Entrench position through backward integration into nickel alloy supply chains and captive stainless steel rolling capacity to defend margins against Indonesian export restriction volatility. Della Toffola anchors demonstrate how specialized Italian press engineering heritage creates defensible positioning against Asian cost competition. Prioritize CE-MDR dual certification investment to compress 14-18 month approval timelines and accelerate revenue recognition on pressure vessel sales.
For New Entrants and Emerging Players: Establish a beachhead in Southeast Asian cider startups requiring rapid-installation modular fermentation skids with limited technical infrastructure. Mobile containerized units represent the most penetrable segment as Asian craft beverage production scales from zero-base. Micet Group's Asian market penetration illustrates how modular skid design opens distribution channels without legacy service network requirements. Pursue third-party automation specialist partnerships rather than captive aftermarket service buildout to reduce capital intensity.
For Investors and Strategic Acquirers: EU F-Gas Regulation 2024/573 reshapes the acquisition landscape toward thermal system specialists with heat pump-based refrigerant transition capabilities and lifecycle-certified equipment portfolios. Long-term viability over the five-to-ten year window hinges on carbon accounting procurement criteria integration and predictive maintenance contract recurring revenue streams. Target acquisition archetype: mid-cap fabricators with installed base conversion potential and deficient aftermarket service penetration. Watch for nickel price stabilization signals as inflection indicator for stainless steel vessel margin recovery and replacement cycle normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Alloy Supply | Captive raw material sourcing defends margins against Indonesian export restriction volatility. |
| CE-MDR Dual Certification Investment | Compressed approval timelines accelerate revenue recognition on pressure vessel designs. |
| Modular Fermentation Skid Development | Rapid-installation systems penetrate Southeast Asian markets with limited technical infrastructure. |
| Predictive Maintenance Contract Unbundling | Recurring revenue streams displace one-time equipment sales in North American craft brewery segments. |
| Heat Pump Thermal System Transition | EU F-Gas Regulation 2024/573 compliance captures 2027 retrofit deadline demand concentration. |
Study Parameters
A spread of perspectives from cidery operations managers, equipment procurement leads at large producers, aftermarket service technicians, and thermal system engineering directors converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation against EFSA regulatory filings, EU Green Deal directive documentation, SEC equipment manufacturer disclosures, and customs trade data on nickel ore flows. Bottom-up unit economics triangulated against top-down market sizing from fermentation vessel installation records and pasteurizer retrofit permit databases.
Demand-supply balance framing anchored the analytical framework across the projection horizon, modeling equipment type segmentation by vessel category, material grade tiering, end-user scale classification, and technology maturity curve positioning. CAGRs derived from replacement cycle analysis, regulatory compliance deadline clustering, and capacity expansion announcements. Industry-specific forecast inputs incorporated EFSA pasteurization mandate implementation timelines and EU F-Gas refrigerant phase-down enforcement schedules.
Macroeconomic conditions sit as an overlay; deviation in nickel price volatility, Indonesian export policy shifts, or European energy cost trajectories would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement consistency and craft cider production scaling rates. Material shifts in CE-MDR certification timeline extensions or F-Gas refrigerant ban delays would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Cold Storage Equipment Market
Food Processing Equipment
Automatic Deboner Market
Food Processing Equipment
Industrial Food Slicers Market
Food Processing Equipment
Commercial Oven Market
Food Processing Equipment
Walk-In Refrigerators & Freezers Market
Food Processing Equipment
Global Carbonated Beverage Processing Equipment Market
Food Processing Equipment
Commercial Food Processors Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Vacuum Cooling Equipment Market
Food Processing Equipment
Food Industry Pulsed Electric Field (PEF) Systems Market
Food Processing Equipment
Defrosting & Thawing Equipment for Food Market
Food Processing Equipment
Global Food Dehydrators Market
Food Processing Equipment
Food Processing Blades Market
Food Processing Equipment
Bottled Water Processing Equipment Market
Food Processing Equipment
Beer Brewing Equipment Market
Food Processing Equipment
Hot Food Processing Equipment Market