
 North America Edible Insects Market | 2026-2036
North America Edible Insects Market Size, Share, and Industry Trends Forecast 2026-2036
North America Edible Insects Market Analytics
Ingredient supply revenue is tilting from raw commodity sales toward processed protein isolates and finished formulations. Aspire Food Group leverages its vertically integrated cricket farming and processing infrastructure across Texas and Mexico. EnviroFlight sustains a dominant position in black soldier fly larvae production for animal nutrition applications. Entomo Farms anchors Canadian supply through its Ontario-based mealworm and cricket operations serving food and feed channels.
Edible insects encompass farm-raised arthropods processed for human consumption or animal nutrition, typically containing 40-75% protein by dry weight with complete amino acid profiles and favorable omega-6 to omega-3 ratios. Crickets lead product type volumes due to established farming protocols and mild flavor profiles suited to Western palates, while mealworms command premium positioning in protein supplement applications for their superior digestibility scores. Application segmentation shows protein supplements capturing expanding margin pools as branded consumer products displace bulk ingredient sales, though animal feed retains volume dominance through regulatory acceptance in poultry and aquaculture diets.
The FDA's Food Safety Modernization Act requirements and pending Generally Recognized as Safe determinations for specific insect species shape product development timelines and capital deployment decisions across the United States. Health Canada's Novel Food Regulations and CFIA oversight of insect-based feed ingredients create parallel compliance frameworks affecting cross-border product strategies. Stakeholders must monitor the trajectory of state-level cottage food law expansions and provincial permitting regimes, as these localized pathways will determine which entrants achieve scalable market access before federal harmonization advances.
Market Dynamics
Protein supplement adoption by nutraceutical companies is compressing traditional commodity margins and forcing upstream suppliers to develop finished formulation capabilities. The FDA's evolving food additive guidance for insect-derived ingredients is simultaneously creating approval bottlenecks and first-mover advantages for compliant producers.
Growth Catalysts
- California's functional food startup cluster:Venture-backed formulators in the San Francisco-Los Angeles corridor are contracting directly with cricket processors for proprietary protein isolate supply, bypassing commodity intermediaries.
- CFIA feed ingredient oversight:Health Canada's regulatory clarity on black soldier fly larvae in poultry and aquaculture diets has unlocked capital deployment into Ontario-based production infrastructure.
- Precision fermentation integration:Hybrid processing combining insect biomass with microbial protein expression is expanding amino acid completeness beyond what either platform achieves independently.
Market Restraints
- Input cost volatility:Organic feedstock prices for cricket farming fluctuate with regional grain markets, squeezing margin predictability for Texas and Ontario operations.
- Supply concentration risk:Black soldier fly larvae production clusters in the southeastern United States create geographic vulnerability to climate-driven harvest disruption.
- Regulatory friction:Pending FDA Generally Recognized as Safe determinations for specific insect species are freezing product launch timelines and capital commitment decisions.
Strategic Opportunities
- Quebec's underpenetrated market:Provincial cottage food law expansions in French-speaking Canada remain underexploited by English-language protein supplement brands.
- Pet nutrition channel innovation:Direct-to-consumer subscription models for insect-based dog and cat food are bypassing conventional retail slotting fee barriers.
- USDA sustainable agriculture incentives:Conservation Reserve Program flexibilities for insect farming on marginal land are creating cost-advantaged production sites.
Industry Challenges
- Entomological expertise scarcity:Industrial-scale insect rearing requires specialized knowledge in arthropod pathology and controlled environment agriculture that outpaces academic program output.
- Multi-jurisdictional compliance complexity:Parallel FDA and CFIA approval pathways for cross-border products demand redundant testing and documentation investment.
- Legacy food manufacturing integration:Conventional protein processing equipment requires modification to handle chitin content and particle size distribution of insect-derived inputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Edible Insects Market |
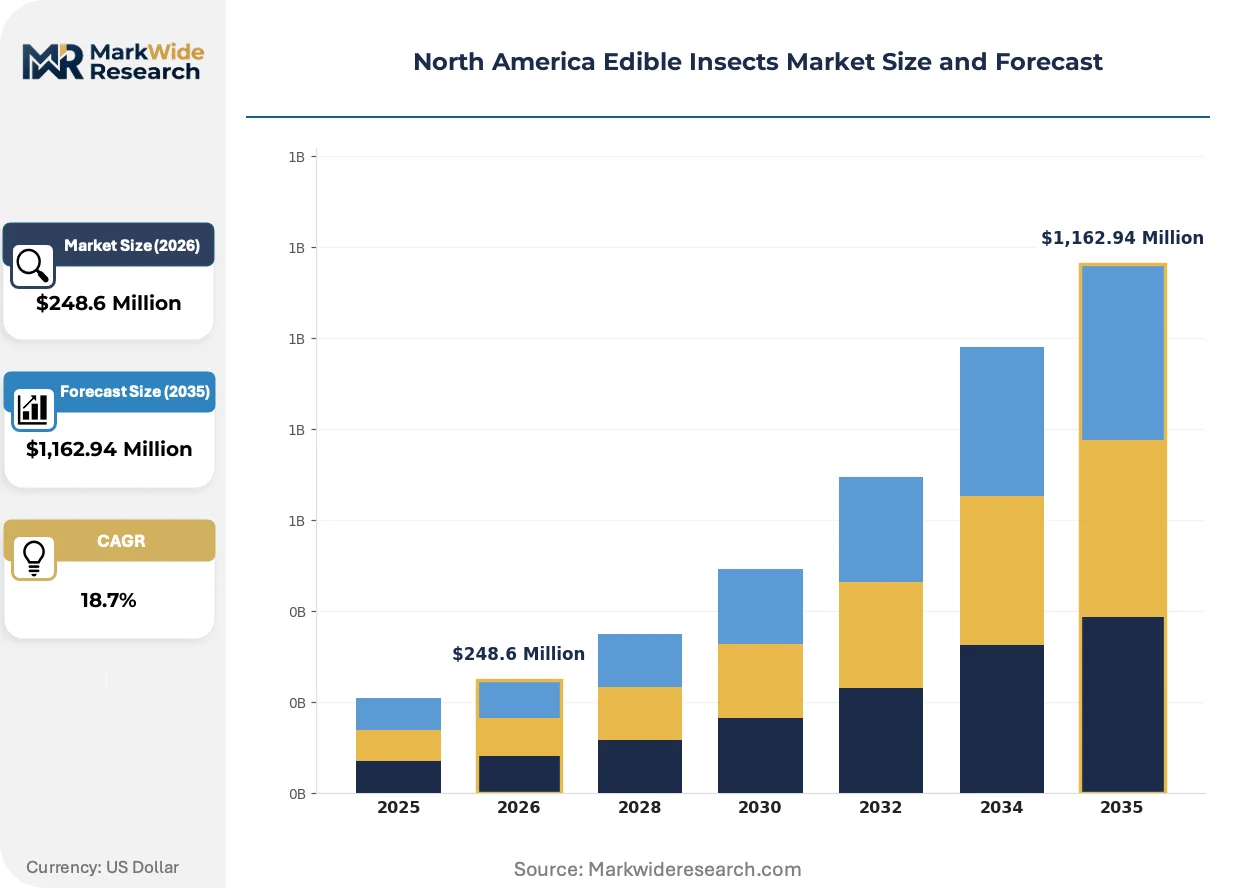
| Market Size in 2026 | $248.6 Million |
| Market Size in 2035 | $1,162.94 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crickets, Mealworms, Grasshoppers, Ants End User: Food Manufacturers, Snack Producers, Nutraceutical Companies, Restaurants Application: Food Products, Protein Supplements, Animal Feed, Pet Treats Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Aspire Food Group, EnviroFlight, Entomo Farms, Chapul, All Things Bugs, Exo Protein, Cricket Flours, Cowboy Cricket Farms, Beta Hatch, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Edible Insects Market Evolving Landscape
Automation and biotechnology convergence is restructuring production economics while regulatory clarity and consumer positioning experiments are reshaping go-to-market strategies across the United States and Canada.
Automated cricket farming systems are hybridizing machine vision for molting detection with climate-controlled rearing chambers. Nutraceutical contract manufacturers in California are adopting these platforms to secure captive protein supply. The technology is hybridizing commodity agriculture with pharmaceutical-grade bioprocessing standards, compressing the gap between farm output and finished supplement quality.
FDA's pending Generally Recognized as Safe framework for whole insects and derived ingredients is forcing reformulation of existing product lines. Companies are pre-positioning application dossiers for cricket and mealworm species ahead of determinations. Protein supplement brands targeting CrossFit and endurance athlete segments are most affected, accelerating partnerships with academic toxicology labs to generate safety data.
Direct sourcing contracts between protein supplement brands and single-origin insect farms are displacing spot-market ingredient purchasing. This procurement consolidation concentrates volume commitments with vertically integrated producers in Texas and Ontario. The shift is most visible in California's functional food cluster, where venture-backed startups are trading volume guarantees for supply security and origin-story marketing claims.
North America Edible Insects Market Segmentation
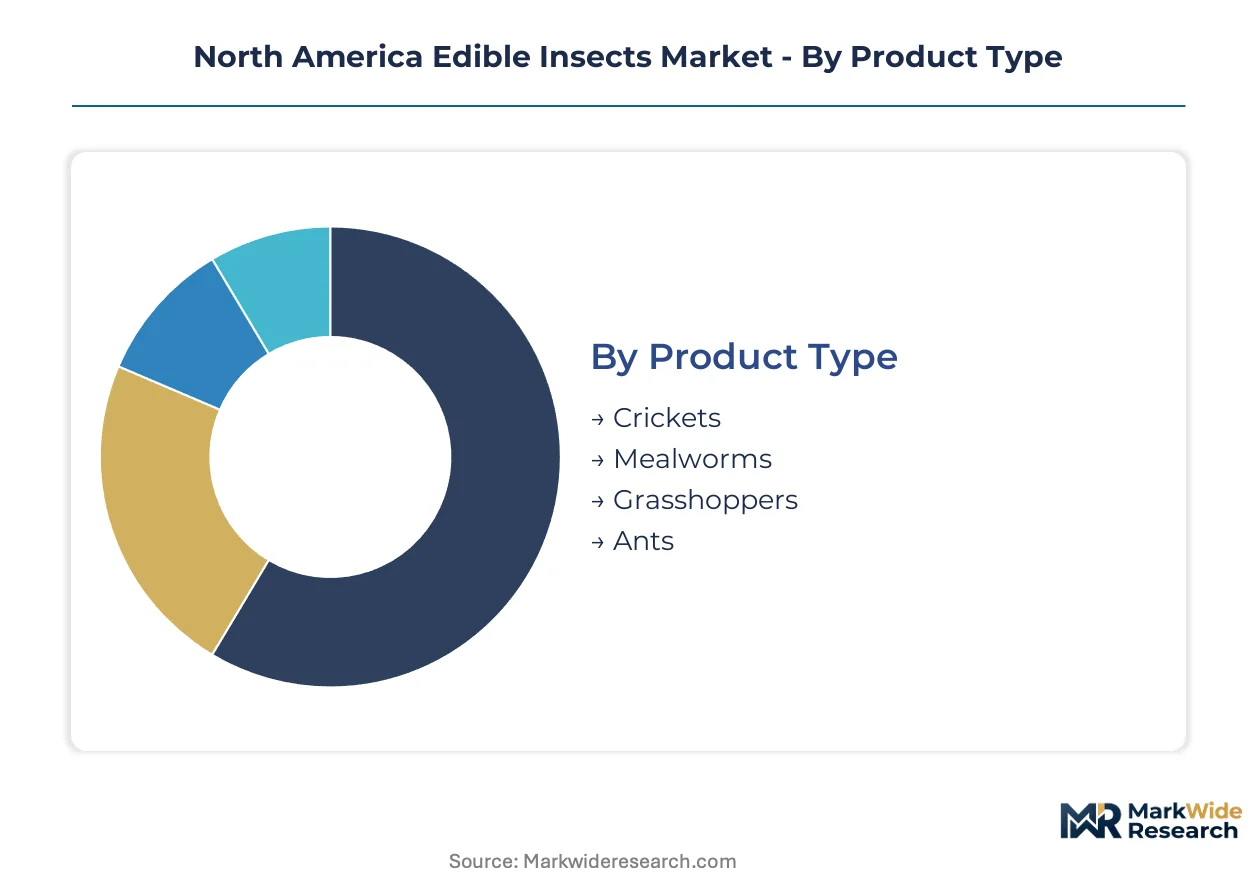
Segmentation in the North America edible insects market reveals divergent margin profiles and regulatory pathways. Product type determines farming infrastructure requirements, while application choice dictates whether FDA food additive rules or CFIA feed regulations apply.
Product Type:
Cycle times vary dramatically across species, with some generational turnovers measured in weeks versus months directly affecting working capital intensity.
- Crickets:Farm-raised Acheta domesticus achieve harvest maturity in six to eight weeks under controlled temperature and humidity protocols. California functional food startups and Texas vertical farming operations concentrate procurement here, drawn by established processing standards and mild flavor profiles suited to Western palates.
- Mealworms:Tenebrio molitor larvae contain superior protein digestibility scores and favorable chitin-to-protein ratios for supplement formulations. Ontario agri-tech processors and Quebec cottage food producers anchor demand, though longer ten-week grow cycles constrain inventory turns.
- Grasshoppers:Locusta migratoria and related species require specialized containment infrastructure due to migration capabilities under Canadian and US biosecurity protocols.
- Ants:Leafcutter and honeypot varieties occupy niche positioning within high-end restaurant channels, limited by harvest scalability and seasonal supply fluctuations.
Crickets anchor the volume base while mealworms gain share at the steepest rate.
End User:
Cost tier stratification separates commodity-scale purchasers from premium-positioned formulators willing to absorb certificate-of-analysis premiums.
- Food Manufacturers:Industrial bakeries and pasta producers in the US Midwest integrate cricket flour at sub-five-percent inclusion rates to achieve protein content claims without sensory alteration.
- Snack Producers:Venture-backed California startups deploy whole-roasted and seasoned formats for direct-to-consumer subscription channels, bypassing conventional retail slotting economics.
- Nutraceutical Companies:Branded protein isolate demand concentrates among CrossFit and endurance athlete segments, where contract manufacturers specify heavy metal testing and amino acid completeness documentation exceeding commodity grades.
- Restaurants:Fine-dining establishments in Toronto, Montreal, and Austin deploy whole insects for experiential menu differentiation, though volume remains constrained by supply inconsistency and front-of-house training requirements.
Nutraceutical companies command the steepest expansion trajectory while food manufacturers provide the volume foundation.
Application:
Margin pools concentrate where regulatory clarity permits branded positioning rather than commodity ingredient sales.
- Food Products:Protein-fortified pasta, baked goods, and beverage formulations incorporate insect-derived ingredients at inclusion rates optimized for labeling compliance and sensory masking.
- Protein Supplements:Isolate and concentrate formats for sports nutrition and meal replacement applications achieve the highest per-kilogram valuations, contingent on FDA GRAS determination timelines for specific species.
- Animal Feed:CFIA regulatory clarity on black soldier fly larvae in poultry and aquaculture diets has unlocked Ontario production infrastructure, though human-grade specifications command premium pricing over feed-channel equivalents.
- Pet Treats:Direct-to-consumer subscription models for insect-based dog and cat food bypass conventional retail slotting fee barriers, with California and Texas startups leading format innovation.
Animal feed anchors the volume base while protein supplements expand most quickly.
Distribution Channel:
Supply concentration in Texas and Ontario production clusters shapes fulfillment economics and origin-story marketing claims.
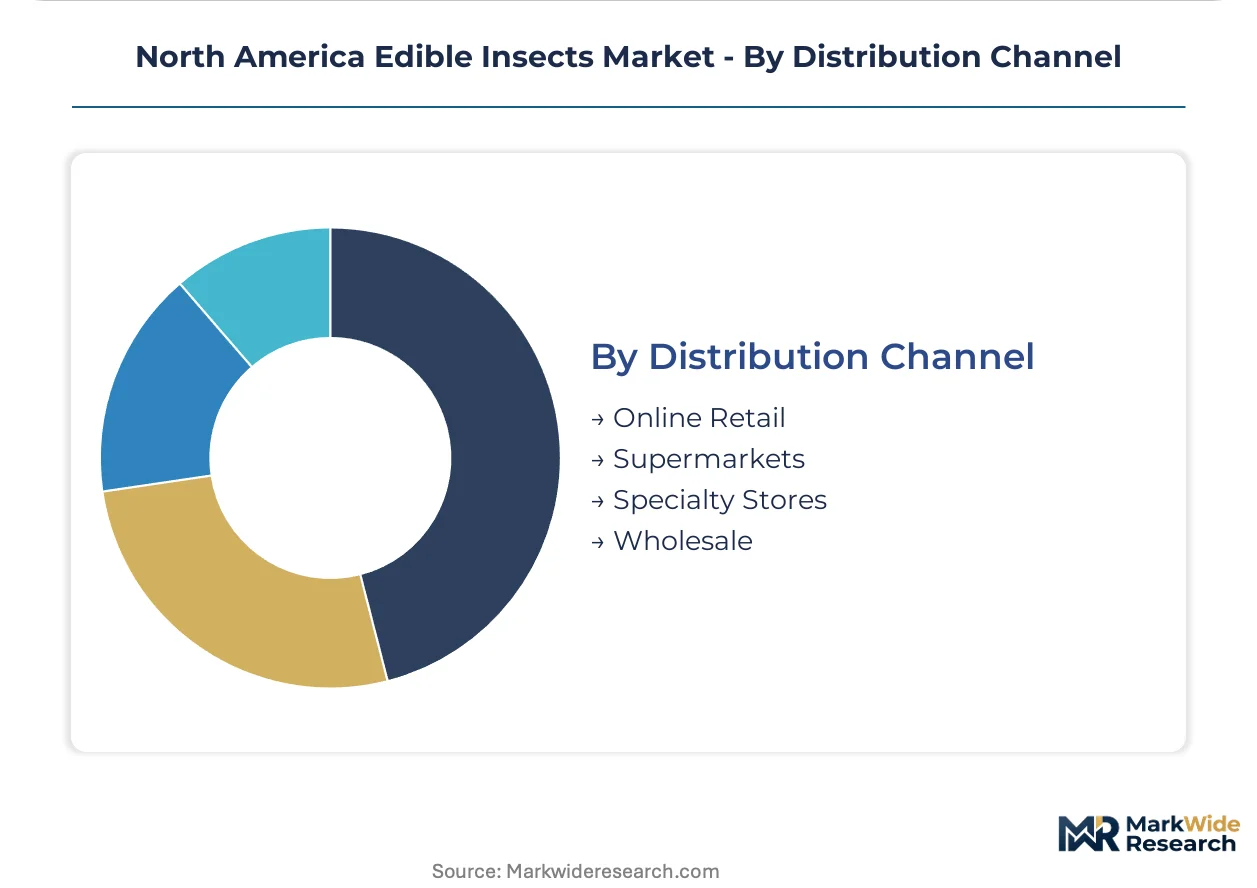
- Online Retail:Direct-to-consumer platforms capture the highest margin percentages by eliminating wholesale markups, though customer acquisition costs and cold-chain shipping constraints limit geographic reach.
- Supermarkets:Conventional grocery placement requires slotting fee commitments and refrigerated section access that favor established CPG conglomerates over insect-native startups.
- Specialty Stores:Natural products retailers and outdoor outfitters in Colorado, Oregon, and British Columbia provide curated discovery environments for early-adopter consumers.
- Wholesale:Ingredient distributors serving foodservice and manufacturing channels concentrate volume throughput but compress margins through bulk pricing negotiations.
Wholesale channels anchor the volume base while online retail climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the North American edible insects landscape. Nutraceutical buyers in California absorb certificate-of-analysis premiums without volume contraction, while Midwest food manufacturers demand sub-five-percent inclusion rates to protect margin structures. This elasticity divergence shapes where suppliers deploy captive production versus spot-market sales.
United States
FDA's pending GRAS determinations for cricket and mealworm species are freezing product launch timelines for CrossFit-focused protein brands. The Food Safety Modernization Act mandates hazard analysis protocols that smaller Texas cricket farms struggle to document. California's San Francisco-Los Angeles corridor hosts venture-backed formulators contracting directly with processors for proprietary isolate supply, bypassing commodity intermediaries entirely.
Canada
Health Canada's Novel Food Regulations and CFIA feed ingredient oversight have unlocked capital deployment into Ontario-based black soldier fly larvae infrastructure. CFIA clarity on poultry and aquaculture diet approvals distinguishes human-grade specifications from feed-channel equivalents. Ontario's agri-tech corridor anchors mealworm and cricket operations serving both food and feed channels with integrated processing capabilities.
Mexico
Traditional entomophagy practices in Oaxaca and Puebla provide cultural foundation for commercial scaling, though regulatory harmonization with US FDA standards remains incomplete. Mexico's national health regulator evaluates insect-derived ingredients under food additive frameworks that lag US guidance timelines. Aspire Food Group leverages cross-border cricket farming infrastructure spanning Texas and Mexican production sites to optimize cost structures.
North America Edible Insects Market Competitive Landscape
Vertically integrated producers and specialized ingredient formulators split the market along value-chain positioning lines. The competitive structure tilts toward consolidation as capital requirements for automated rearing systems and regulatory compliance documentation favor scaled entrants. Three archetypes dominate: captive supply operators controlling farm-to-formulation pipelines, toll processors converting third-party biomass into isolate and concentrate formats, and brand marketers outsourcing production to secure origin-story claims. Capacity expansion into Ontario and Texas production clusters and strategic partnerships between California nutraceutical brands and single-origin farms represent the dominant competitive moves compressing spot-market margins.
Within the captive supply tier, Aspire Food Group exemplifies backward integration into cricket farming and processing infrastructure across multiple jurisdictions. EnviroFlight occupies a position representing black soldier fly larvae specialists focused on animal nutrition applications. Entomo Farms anchors Canadian supply representation through Ontario-based mealworm and cricket operations spanning food and feed regulatory channels.
| Leading Market Players |
|---|
| Aspire Food Group |
| EnviroFlight |
| Entomo Farms |
| Chapul |
| All Things Bugs |
| Exo Protein |
| Cricket Flours |
| Cowboy Cricket Farms |
| Beta Hatch |
| Others |
Value Network & Pricing Analysis
Ontario's agri-tech corridor and Texas vertical farming clusters concentrate cricket and mealworm processing capacity, granting compliant producers outsized leverage over nutraceutical buyers facing FDA GRAS determination delays. This geographic supply concentration enables certificate-of-analysis premiums for human-grade specifications while feed-channel equivalents compete on spot-market terms.
Pricing Analysis
After-sales formulation services and technical support contracts drive lifetime value for insect protein isolate suppliers serving California functional food startups. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels separates premium human nutrition applications from commodity animal feed channels. Pricing pressure stems from organic feedstock cost volatility squeezing Texas cricket farm margins. Midwest food manufacturers exhibit highest price sensitivity, demanding sub-five-percent inclusion rates, while CrossFit-focused protein brands absorb heavy metal testing premiums without volume contraction.
Supply Chain Analysis
Organic grain feedstocks for cricket rearing draw from US Midwest agricultural surplus and Canadian prairie output, with both sources tethered to regional commodity price swings. Supply concentrates in Ontario mealworm operations, Texas cricket farms, and southeastern black soldier fly larvae clusters. Single-source vulnerability to climate-driven harvest disruption threatens southeastern larvae production. Distribution runs through direct sourcing contracts between California nutraceutical brands and single-origin farms, displacing wholesale ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America edible insects market represents a high-growth protein disruption where FDA GRAS determinations for cricket and mealworm species constitute the decisive regulatory inflection point.
For Market Incumbents: Entrench regulatory compliance advantages by accelerating toxicology dossier submissions ahead of FDA determinations for Acheta domesticus and Tenebrio molitor. Lock in multi-year offtake agreements with California functional food startups to defend against emerging toll processors offering lower-cost isolate conversion. Prioritize captive supply chain control through backward integration into Ontario and Texas farming infrastructure.
For New Entrants and Emerging Players: Build out Quebec's underexploited French-language protein supplement market before English-language brands establish localized distribution. Target direct-to-consumer pet nutrition subscriptions in Texas and California where conventional retail slotting barriers do not apply. Lead with sustainability origin-story marketing anchored to single-farm provenance claims.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated producers with in-house pathology expertise and automated rearing platforms over pure-play brand marketers. Long-term viability hinges on regulatory clarity enabling human-grade product expansion rather than feed-channel commoditization. Watch FDA GRAS determination timelines as the critical inflection signal for capital deployment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Positioning | Advance FDA GRAS dossiers ahead of determinations to secure first-mover product launch windows. |
| Backward Integration | Acquire Ontario or Texas farming assets to control feedstock costs and origin-story claims. |
| Direct Sourcing Contracts | Bypass commodity intermediaries by linking California formulators to single-origin insect farms. |
| Pet Nutrition Channel Entry | Launch subscription-based dog and cat food formats avoiding conventional retail slotting fees. |
| Automation Platform Deployment | Adopt machine vision and climate-controlled rearing systems to compress farm-to-isolate cycle times. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary fieldwork spanning entomology researchers at Texas A&M and University of Guelph, regulatory affairs leads at FDA and Health Canada, procurement managers at California nutraceutical contract manufacturers, and Ontario-based cricket farm operations directors. Secondary validation drew from FDA GRAS notice filings, CFIA feed ingredient approvals, USDA Conservation Reserve Program documentation, and state-level cottage food law expansions. Bottom-up volume modeling triangulated against top-down protein supplement demand projections.
Calibration against historical CAGRs in alternative protein categories anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include insect species, application tier, end-user category, and distribution channel structure. Growth rates derived from elasticity analysis linking protein isolate pricing to conventional whey and pea protein substitutes. Forecast inputs incorporated FDA guidance timeline scenarios and CFIA regulatory clarity trajectories.
Stress conditions across FDA GRAS determination delays, organic feedstock price spikes, and climate-driven harvest disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization progress and consumer acceptance curves. Cross-checking against alternative protein investment flow data and venture-backed startup funding rounds is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
North America Meal Products Replacement Market
Alternative Food Sources
Soy Leghemoglobin Market
Alternative Food Sources
Pet Food Microalgae Market
Alternative Food Sources
Fishless Fillets Market
Alternative Food Sources
Hemp-Based Products Market
Alternative Food Sources
North America Precision Fermentation Market
Alternative Food Sources
Sugar Alternative Market
Alternative Food Sources
Asia-Pacific Algae Protein Market
Alternative Food Sources
Algal Protein Market
Alternative Food Sources
Single Cell Oil Market
Alternative Food Sources
Global Konjac Glucomannan Market
Alternative Food Sources
Dunaliella Salina Market
Alternative Food Sources
Vegan Caviar Market
Alternative Food Sources
Algae Fats Market
Alternative Food Sources
Emergency Food Market
Alternative Food Sources
Synthetic Food Market