
 Wine Crusher Market | 2026-2036
Wine Crusher Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Crusher Market Analytics
Italy's Veneto region is rewriting equipment sourcing patterns for European wine producers. Bucher Vaslin leverages its French engineering heritage to dominate high-throughput pneumatic crusher installations across Bordeaux and Champagne. Zambelli Enotech anchors mid-scale winery demand in Northern Italy through specialized electric crusher lines with integrated must-pump systems. Puleo Srl competes on Sicilian and Southern Italian terrain with compact stainless steel designs suited for historic cellar footprints.
A wine crusher is a mechanical device that ruptures grape berries to release juice, must, and skins prior to fermentation, typically operating at throughput rates from 500 kg/hour for manual units to 20+ tonnes/hour for industrial hydraulic systems. The equipment separates stems, controls oxidation exposure, and preserves phenolic compounds critical to tannin extraction and color stability in red wine production. Electric crushers hold the largest installed base among wineries due to consistent torque delivery and programmable speed settings, while pneumatic crushers represent the fastest-expanding segment as Champagne houses and sparkling wine producers prioritize gentle whole-berry processing to limit skin contact. Stainless steel construction commands premium positioning across all product tiers because it satisfies sanitary welding standards and resists tartaric acid corrosion during extended harvest campaigns.
EU machinery directives and CE marking requirements enforce minimum safety guarding and emergency stop protocols on all crusher sales within member states, pushing smaller Italian manufacturers toward certified component suppliers. The US OSHA and FDA food-contact material regulations shape import specifications for European equipment entering American winery markets, particularly on polymer seal compositions and surface finish roughness. Stakeholders must monitor evolving sustainability mandates from the EU Green Deal and national organic certification bodies, as energy consumption metrics and waterless cleaning protocols become procurement criteria for environmentally committed vineyard operations.
Market Dynamics
Stainless steel construction mandates under EU machinery directives are compressing equipment replacement cycles while elevating capital requirements for boutique winery expansions across estate-bottled programs.
Growth Catalysts
- EU machinery directives:CE marking requirements for sanitary welding standards and emergency stop protocols are forcing equipment upgrades across member-state wineries, creating replacement demand for compliant crushing systems.
- Pneumatic processing technology:Champagne houses and sparkling wine producers are adopting gentle whole-berry crushers to limit skin contact and preserve delicate phenolic profiles during harvest.
- Veneto and Piedmont concentration:Prosecco and Barolo production volumes in these Italian regions are driving premium crusher procurement with integrated must-pump configurations.
Market Restraints
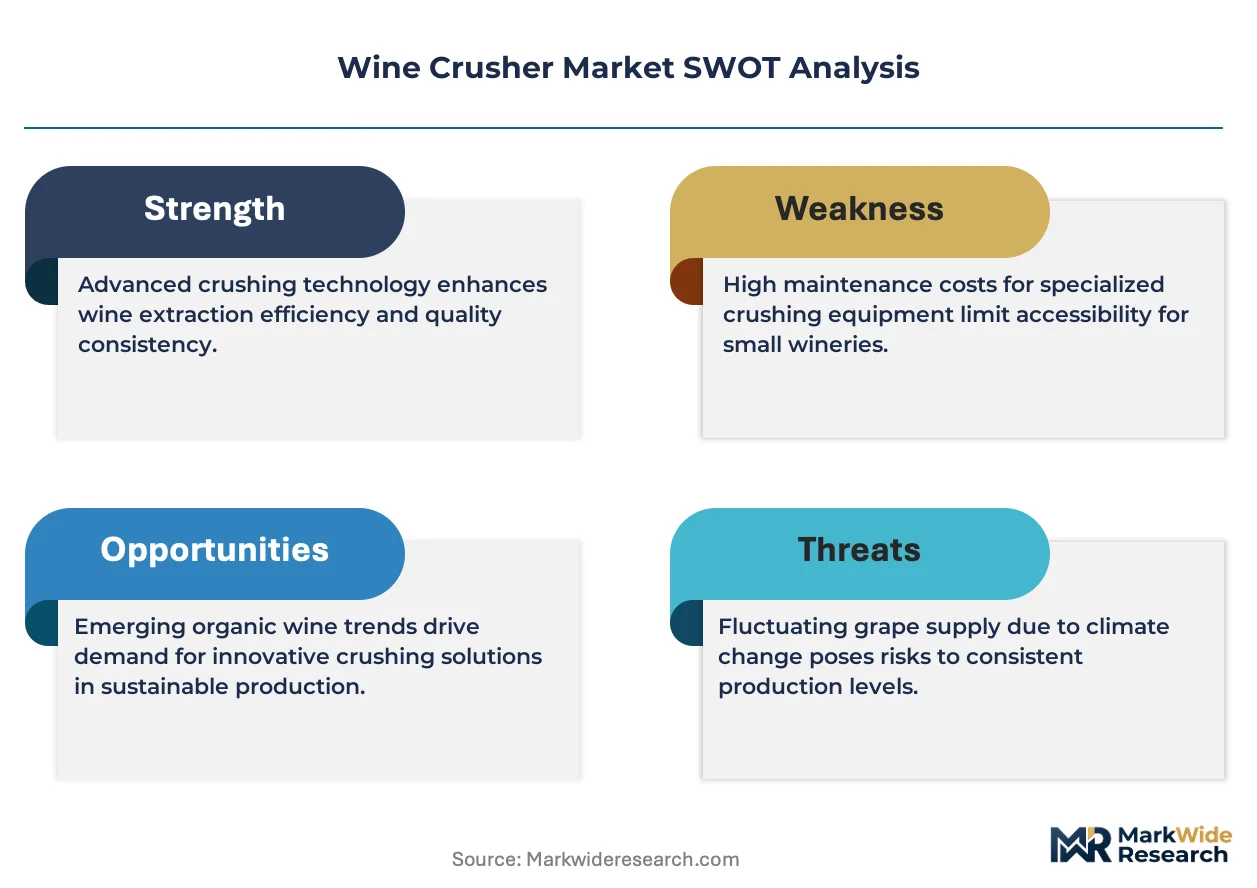
- Stainless steel input volatility:Nickel and chromium price swings directly impact manufacturing costs for corrosion-resistant equipment meeting tartaric acid exposure standards.
- Supply concentration in Northern Italy:Specialized electric crusher component fabrication clusters around Bologna and Modena create geographic vulnerability for just-in-time harvest equipment delivery.
- Historic cellar footprint constraints:Compact crushing equipment for UNESCO-protected underground cellars in Champagne and Burgundy limits throughput scalability for expanding producers.
Strategic Opportunities
- Waterless cleaning protocols:EU Green Deal sustainability mandates are creating procurement preference for crushers with CIP-compatible designs and reduced wastewater discharge profiles.
- Sicilian terrain adaptation:Puleo Srl's compact stainless steel formats demonstrate viable entry points for equipment optimized to Southern Italy's confined historic structures.
- Energy consumption metrics:National organic certification bodies in France and Italy are incorporating kWh-per-tonne standards into equipment approval workflows, favoring variable-speed electric drives.
Industry Challenges
- Sanitary welding certification timelines:Third-party validation of orbital weld integrity for FDA food-contact compliance adds 8-12 weeks to equipment delivery schedules for US-bound exports.
- Legacy must-pump integration:Retrofitting programmable speed crushers into existing cellar workflows requires matched flow-rate engineering that many mid-scale wineries lack in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Crusher Market |
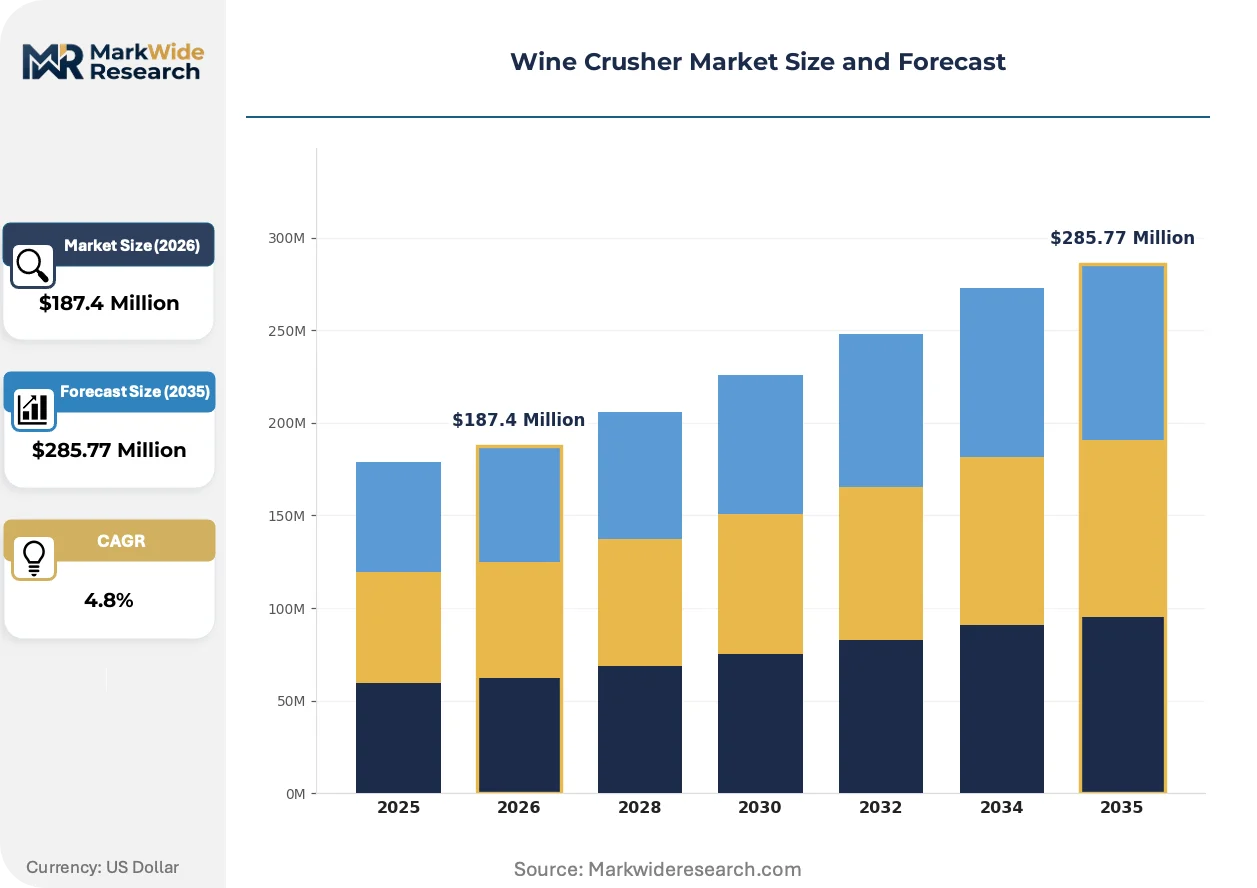
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Crushers, Electric Crushers, Pneumatic Crushers, Hydraulic Crushers Material: Stainless Steel, Wood, Plastic, Aluminum End User: Wineries, Home Brew Enthusiasts, Commercial Distilleries, Beverage Manufacturers Size: Small, Medium, Large, Custom |
| Companies Covered | Bucher Vaslin, Zambelli Enotech, Puleo Srl, Enoitalia, Marchisio, Pellenc Group, Della Toffola, Enoveneta, Gai Macchine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Crusher Market Evolving Landscape
Equipment functionality is converging around oxidation control and phenolic preservation as red wine producers prioritize color stability and tannin extraction precision in crusher specification.
Pneumatic bladder crushing technology is hybridizing with traditional destemming architectures to deliver programmable pressure curves that rupture berries without macerating seeds. Barolo and Barbaresco estates in Piedmont are adopting these systems at 15-20% annual replacement rates for vintage-differentiated tannin management. The technology is hybridizing equipment categories previously segmented by grape variety, compressing the distinction between red and white wine crushing workflows.
EU Green Deal sustainability mandates are embedding energy consumption disclosure requirements into machinery procurement guidelines for vineyard operations seeking organic certification. France's national environmental labeling scheme now requires kWh-per-tonne documentation for equipment entering estate-bottled supply chains. Sparkling wine producers in Champagne are responding with variable-frequency drive retrofits that reduce peak power draw during harvest compression periods.
After-sales service unbundling is fragmenting traditional distributor relationships as direct-to-winery parts provisioning and remote diagnostic subscriptions displace bundled maintenance contracts. Northern Italian equipment manufacturers are piloting telemetry-enabled crushers that transmit bearing temperature and torque load data to cloud platforms. This shift is most visible in Napa Valley operations where labor scarcity for on-site mechanical support accelerates predictive maintenance adoption.
Wine Crusher Market Segmentation
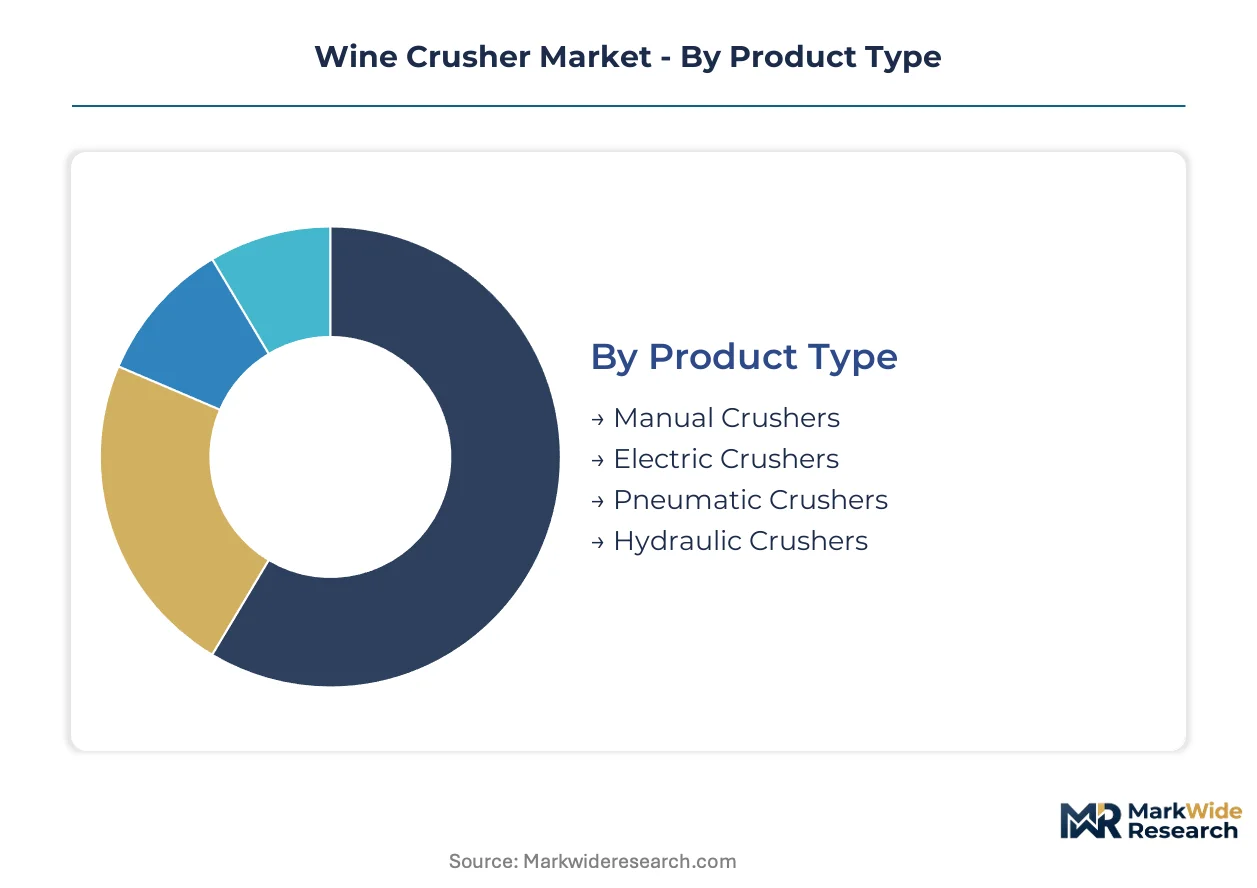
Wine crusher procurement patterns diverge sharply across operational scales and regulatory environments. Equipment specification varies with cellar infrastructure constraints, organic certification requirements, and estate-bottled program ambitions.
Product Type:
After-sales service intensity escalates with automation complexity, driving divergent vendor retention strategies across manual versus pneumatic system deployments.
- Manual Crushers:Hand-cranked cast iron or wooden drum designs operate at sub-500 kg/hour throughput for heritage vineyard operations and entry-level estate programs. Demand clusters in UNESCO-protected cellars across Champagne and Burgundy where electrical infrastructure restrictions preserve traditional processing workflows.
- Electric Crushers:Motorized roller systems with programmable speed settings deliver consistent torque for 2-8 tonne/hour operations. Napa Valley boutique wineries favor integrated must-pump configurations for estate-bottled red wine programs requiring precise phenolic extraction control.
- Pneumatic Crushers:Gentle bladder-press technology limits seed maceration for whole-berry processing. Champagne houses prioritize these systems for sparkling wine base wines demanding minimal skin contact.
- Hydraulic Crushers:Industrial-scale piston architectures achieve 20+ tonne/hour throughput for cooperative wineries in Veneto processing Prosecco harvest volumes.
By volume, electric crushers lead. By growth pace, pneumatic systems are expanding most quickly.
Material:
Capital deployment thresholds separate corrosion-resistant specifications from cost-optimized alternatives in equipment replacement cycles.
- Stainless Steel:Orbital-welded 304 and 316 grades resist tartaric acid corrosion during extended harvest campaigns. EU machinery directives mandate sanitary welding standards that elevate stainless steel to default specification for CE-marked equipment entering French and Italian markets.
- Wood:Traditional oak or chestnut construction persists in historic Piedmont cellars where aesthetic continuity supports tourism-integrated winery positioning. Regulatory exemption pathways for heritage equipment preserve niche demand despite sanitation compliance burdens.
- Plastic:Polymer hopper and roller components reduce unit weight for portable field crushing operations. FDA food-contact material regulations constrain polymer seal compositions for US-bound exports from European manufacturers.
- Aluminum:Lightweight frame construction targets home brew enthusiasts and mobile contract crushing services prioritizing transportability over durability metrics.
By installed base, stainless steel dominates. By substitution risk, wood faces steepest decline trajectories.
End User:
Volume concentration and specification sophistication create tiered procurement workflows with distinct tender processes and approval timelines.
- Wineries:Estate-bottled programs across Bordeaux and Napa Valley drive premium specification for integrated destemmer-crusher combinations with variable-frequency drives. Organic certification requirements in France and Italy embed energy consumption metrics into equipment selection criteria.
- Home Brew Enthusiasts:Entry-level manual and small electric units serve hobbyist production scales below 500 kg annually. Direct-to-consumer e-commerce channels displace traditional agricultural equipment distribution for this segment.
- Commercial Distilleries:Grape-based spirit producers in Cognac and Armagnac require modified crushing parameters for higher-sugar must extraction prior to distillation.
- Beverage Manufacturers:Bulk juice processors for private-label wine brands prioritize throughput maximization over phenolic precision in equipment specification.
By revenue contribution, wineries lead. By volume expansion, home brew enthusiasts are gaining share fastest.
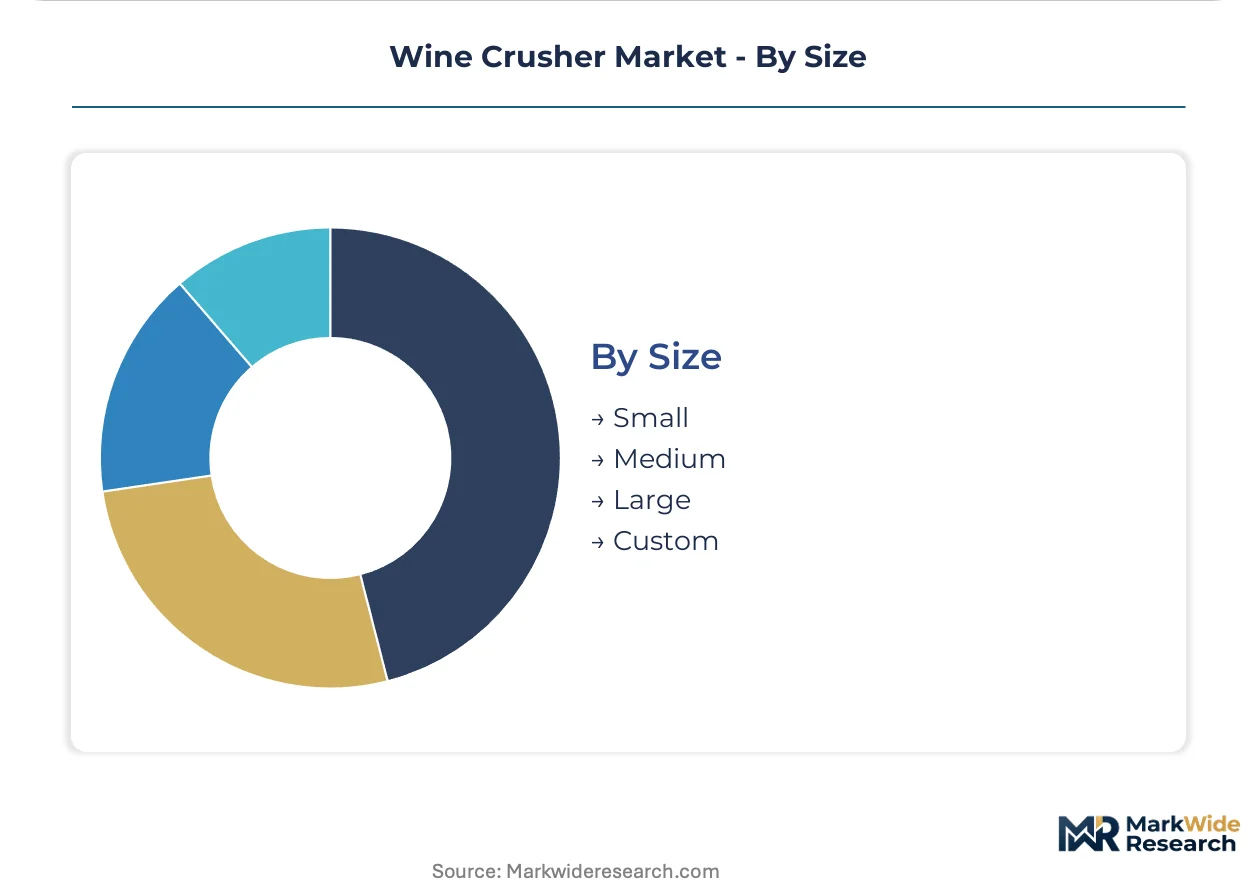
Size:
Physical footprint constraints in historic structures compress demand toward compact formats despite throughput limitations.
- Small:Sub-1 metre width designs navigate confined cellar staircases in Champagne's underground chalk tunnels. Puleo Srl's Sicilian-adapted formats demonstrate viability for Southern Italy's constrained historic infrastructure.
- Medium:2-5 tonne/hour systems balance scalability with retrofit compatibility for expanding Veneto Prosecco operations.
- Large:Industrial hydraulic installations serve cooperative wineries processing consolidated harvest volumes across multiple vineyard holdings.
- Custom:Bespoke engineering addresses unique architectural constraints or specialized varietal processing requirements for premium Barolo and Barbaresco estates.
By unit shipments, medium sizes lead. By margin expansion, custom configurations show steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU machinery directives and CE marking requirements anchor equipment procurement standards across European wine regions, while FDA compliance protocols govern cross-Atlantic export specifications for stainless steel crushing systems.
Italy
Prosecco production volumes in Veneto and Barolo aging programs in Piedmont drive premium crusher procurement with integrated must-pump configurations. The EU Green Deal embeds energy consumption disclosure requirements into machinery procurement guidelines for organic certification pathways. Bologna and Modena host specialized electric crusher component fabrication clusters that create geographic concentration for just-in-time harvest equipment delivery.
France
Champagne houses prioritize gentle whole-berry pneumatic processing to limit skin contact in sparkling wine base production. France's national environmental labeling scheme mandates kWh-per-tonne documentation for equipment entering estate-bottled supply chains. Bordeaux and Champagne cellars face UNESCO-protected underground infrastructure constraints that compress demand toward compact crushing formats.
United States
Napa Valley boutique wineries expand crushing capacity to support estate-bottled red wine programs requiring precise phenolic extraction control. OSHA and FDA food-contact material regulations shape import specifications for European equipment, particularly on polymer seal compositions and surface finish roughness. California operations accelerate predictive maintenance adoption as labor scarcity for on-site mechanical support intensifies.
Spain
Cava producers in Catalonia adopt modified crushing parameters for sparkling wine base wines alongside traditional still wine operations. CE marking requirements for sanitary welding standards and emergency stop protocols force equipment upgrades across member-state wineries. Historic cellar footprints in Rioja and Ribera del Duero limit throughput scalability for expanding producers.
Germany
Riesling producers in Mosel and Rheingau prioritize oxidation control systems for white wine phenolic preservation. REACH compliance and RoHS directives constrain polymer component specifications for food-contact equipment entering German winery markets. Stuttgart and Munich industrial zones concentrate precision engineering capabilities for variable-frequency drive retrofits.
Wine Crusher Market Competitive Landscape
Italian engineering heritage and French agricultural technology specialists split the market into distinct capability clusters. Equipment fabrication concentrates around Northern Italian industrial zones with French competitors anchoring pneumatic processing innovation. Three archetypes dominate: heritage cellar specialists optimizing compact formats for historic infrastructure, scale-driven manufacturers serving cooperative winery volumes, and precision engineering houses delivering programmable control systems. Geographic expansion through certified component supplier networks and portfolio diversification into integrated destemmer-crusher combinations represent the dominant competitive moves.
Among Italian specialists, Bucher Vaslin, Zambelli Enotech, and Puleo Srl occupy positions reflecting distinct regional adaptation strategies. Bucher Vaslin represents the precision engineering archetype with French engineering heritage visible in its name structure. Zambelli Enotech exemplifies Northern Italian mid-scale specialization through its geographic identifier and corporate form. Puleo Srl anchors Southern Italian terrain adaptation with its compact format positioning for confined historic cellar footprints. These three names illustrate how vendor capability maps to regional demand fragmentation across estate-bottled programs, cooperative volumes, and heritage infrastructure constraints.
| Leading Market Players |
|---|
| Bucher Vaslin |
| Zambelli Enotech |
| Puleo Srl |
| Enoitalia |
| Marchisio |
| Pellenc Group |
| Della Toffola |
| Enoveneta |
| Gai Macchine |
| Others |
Value Network & Pricing Analysis
The Rotterdam-Genoa maritime corridor shapes landed cost differentials for Northern Italian crusher manufacturers, compressing margin buffers for Bologna-based fabricators while amplifying price spreads between CE-certified premium systems and non-compliant economy alternatives in Southern European markets.
Pricing Analysis
Italian-French price spreads exceed 15% for equivalent pneumatic crusher specifications, reflecting divergent labor cost structures and certification overhead. Three-tier pricing structure across premium CE-marked, standard EU-compliant, and economy non-certified levels dominates procurement workflows. Pricing pressure stems from nickel and chromium volatility in 304-grade stainless steel feedstock. Cooperative wineries in Veneto exhibit highest price sensitivity, while Champagne houses prioritize phenolic precision over unit economics.
Supply Chain Analysis
Dual-use technology export controls on precision variable-frequency drives constrain component flows from Stuttgart engineering zones to non-EU assembly operations. Manufacturing gravity centers on Italy, France, and Germany. Supply chains draw from specialty steel mills in Northern Italy, polymer seal fabricators in Southern Germany, and precision bearing suppliers in Switzerland. Single-source vulnerability concentrates in Bologna-Modena electric motor clusters. Distribution runs through agricultural equipment dealers with harvest-season stocking obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Boutique winery consolidation across Napa Valley and Bordeaux is shifting procurement leverage toward estate-bottled programs, fragmenting buyer power historically concentrated among cooperative processors.
For Market Incumbents: Build regulatory certification moats through accelerated CE marking and FDA food-contact compliance investments. Bucher Vaslin and Zambelli Enotech should deepen orbital welding capabilities to compress third-party validation timelines. Defend against pneumatic technology substitution by integrating must-pump systems into legacy electric crusher retrofits. Channel control through direct telemetry-enabled service subscriptions displaces bundled maintenance contracts. For New Entrants and Emerging Players: Sicilian and Southern Italian confined cellar footprints represent the most penetrable entry point for compact stainless steel formats. Cava producers in Catalonia seeking oxidation control systems for sparkling wine base production offer secondary white-space. Waterless cleaning protocol compliance under EU Green Deal mandates provides differentiated go-to-market positioning against established Northern Italian vendors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision engineering houses with programmable control capabilities over scale-driven cooperative suppliers. Five-to-ten year viability hinges on telemetry integration and predictive maintenance revenue streams. Acquisition targets should demonstrate certified component supplier networks and integrated destemmer-crusher portfolio breadth. Watch kWh-per-tonne disclosure mandates from France's national environmental labeling scheme as inflection indicator for variable-frequency drive adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Acceleration | Third-party validation timelines determine competitive positioning in EU member-state procurement tenders. |
| Telemetry-Enabled Service Subscriptions | Predictive maintenance revenue streams offset hardware margin compression in Napa Valley operations. |
| Waterless Cleaning Protocol Development | EU Green Deal compliance creates procurement preference for CIP-compatible crusher designs. |
| Variable-Frequency Drive Integration | Energy consumption metrics from French organic certification bodies favor kWh-per-tonne documentation. |
| Compact Format Engineering | UNESCO-protected cellar constraints in Champagne and Burgundy limit throughput scalability without architectural adaptation. |
Research Methodology
The analysis maps manual, electric, pneumatic, and hydraulic crusher sub-sectors, each validated through equipment procurement managers at boutique wineries, cooperative processing directors, and agricultural equipment distributors. Primary interviews with maintenance directors, plant engineers, and aftermarket service heads combined with secondary validation from EU machinery directive filings, CE marking databases, and stainless steel trade flow records. Bottom-up shipment data and top-down value estimates triangulate market sizing across Italian, French, and American wine regions.
Assumptions held fixed include EU machinery directive enforcement continuity and tartaric acid corrosion standards for food-contact equipment. Variables tested across the analysis window encompass nickel price volatility, pneumatic technology adoption curves, and organic certification penetration rates. Segmentation dimensions modeled include product type, material grade, end-user scale, and physical footprint constraints. CAGRs derive from installed base replacement cycles and capacity expansion announcements in Veneto and Napa Valley.
Practitioners should monitor EU Green Deal sustainability mandate acceleration and FDA surface finish roughness standard revisions for early signals. Forecasts reflect assumptions about harvest volume stability and estate-bottled program expansion. Material shifts in stainless steel input costs or CE marking timeline extensions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Bread Slicer Market
Food Processing Equipment
Portable Clean-In-Place Market
Food Processing Equipment
Fish Processing Equipment Market
Food Processing Equipment
Pan Feeder Market
Food Processing Equipment
Hydrostatic Steam Blancher Market
Food Processing Equipment
Ice Cream Equipment Market
Food Processing Equipment
Food Sorting Machines Market
Food Processing Equipment
Global Fermenters Market
Food Processing Equipment
Used Commercial Freezer Market
Food Processing Equipment
Beverage Processing Equipment Market
Food Processing Equipment
Commercial Food Refrigeration Equipment Market
Food Processing Equipment
Fish Deboning Machine Market
Food Processing Equipment
Wine Processing Equipment Market
Food Processing Equipment
Air Cooled Cube Ice Machines Market
Food Processing Equipment
Canada Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Global Food Deaerators Market