
 Mixer Settler Market | 2026-2036
Mixer Settler Market Size, Share, and Industry Trends Forecast 2026-2036
Mixer Settler Market Insights
Buyer concentration in mining is decoupling as tier-one copper producers consolidate orders while mid-tier lithium and rare earth developers fragment procurement across smaller equipment packages. ANDRITZ AG leverages its vertical integration into pump and separation technology to capture bundled contracts. Multotec Group (Pty) Ltd anchors its position through dense media and classification expertise that extends into African platinum group metal circuits. Metso Outotec Oyj dominates the Finnish-Russian technology corridor with in-house production of agitator mechanisms and settler tank designs.
A mixer settler is a staged liquid-liquid extraction device comprising mechanically agitated mixing chambers followed by gravity settling zones, typically operating at phase ratios between 1:1 and 5:1 organic-to-aqueous with residence times of two to five minutes per stage. Its primary industrial purpose is selective recovery and purification of dissolved metals or nuclear materials from pregnant leach solutions through repeated contact with immiscible solvent phases. Horizontal mixer settlers currently occupy the largest installed base in copper solvent extraction due to lower capital footprint and simpler civil works, while rotor-stator configurations represent the fastest-growing technology segment as they reduce entrainment losses in high-value rare earth separations. Hydrometallurgy commands the deepest margin pools among applications because equipment specifications tie directly to downstream electrowinning performance guarantees.
The EPA enforces effluent limitation guidelines that compel U.S. mining operations to upgrade from single-stage to multistage extraction trains, while REACH registration requirements in Europe restrict solvent chemistry choices and extend qualification timelines for new equipment installations. ISO 14001 environmental management certification has become a de facto bid prerequisite for contracts with major mining companies across Australia and Canada. Stakeholders must monitor how China's NMPA and SAMR alignment with GB standards for nuclear-grade equipment reshapes supplier qualification protocols for reprocessing applications.
Market Dynamics
The solvent extraction circuit expansion across Chilean copper mines and Australian uranium operations is fragmenting procurement patterns, as tier-one producers consolidate multistage train orders while mid-tier rare earth developers disaggregate equipment packages across specialized vendors.
Growth Catalysts
- EPA Effluent Guidelines:U.S. mining operations face mandatory upgrades from single-stage to multistage extraction trains, compelling capital deployment into closed-loop liquid-liquid recovery systems.
- Rare Earth Separation Demand:Western Australia's Kalgoorlie region and Chile's Atacama Desert hydrometallurgical hubs are driving rotor-stator configuration adoption for high-purity rare earth element recovery.
- EU REACH Compliance:Chemical plants across Germany and France are replacing open solvent systems with contained mixer settler circuits to satisfy registration and authorization timelines for organic phase chemistry.
Market Restraints
- Stainless Steel Input Volatility:Settler tank fabrication depends on austenitic stainless steel grades whose nickel and molybdenum content exposes project budgets to London Metal Exchange price swings.
- Agitator Mechanism Supply Concentration:Precision gearbox and impeller assemblies for high-shear mixing chambers concentrate among German and Japanese precision engineering suppliers, creating single-source vulnerability.
- Organic Phase Entrainment Limits:Conventional horizontal designs face hard technical ceilings on phase ratio flexibility below 1:1 organic-to-aqueous, restricting application in dilute pregnant leach solutions.
Strategic Opportunities
- Brazilian Lithium Triangle:Minas Gerais and Bahia province hard-rock lithium projects lack established solvent extraction infrastructure, creating first-mover equipment positioning for spodumene-derived lithium chemical purification.
- Modular Skid Packaging:Pre-assembled mixer settler units with integrated instrumentation are compressing field installation timelines and enabling rental-service business models for junior mining financings.
- China Nuclear-Grade Alignment:SAMR and NMPA convergence with GB equipment standards for reprocessing applications is opening qualification pathways for Western suppliers in spent fuel solvent extraction.
Industry Challenges
- Computational Fluid Dynamics Expertise Gap:Optimized impeller and weir geometry design requires specialized simulation talent that mining equipment vendors struggle to retain against aerospace and automotive poaching.
- ISO 14001 Certification Burden:Australian and Canadian major miners now mandate environmental management system documentation as a bid prerequisite, extending vendor qualification cycles by six to twelve months for uncertified suppliers.
- Legacy DCS Integration Complexity:Brownfield copper solvent extraction circuits running proprietary distributed control systems from the 1990s resist seamless interface with modern mixer settler automation packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mixer Settler Market |
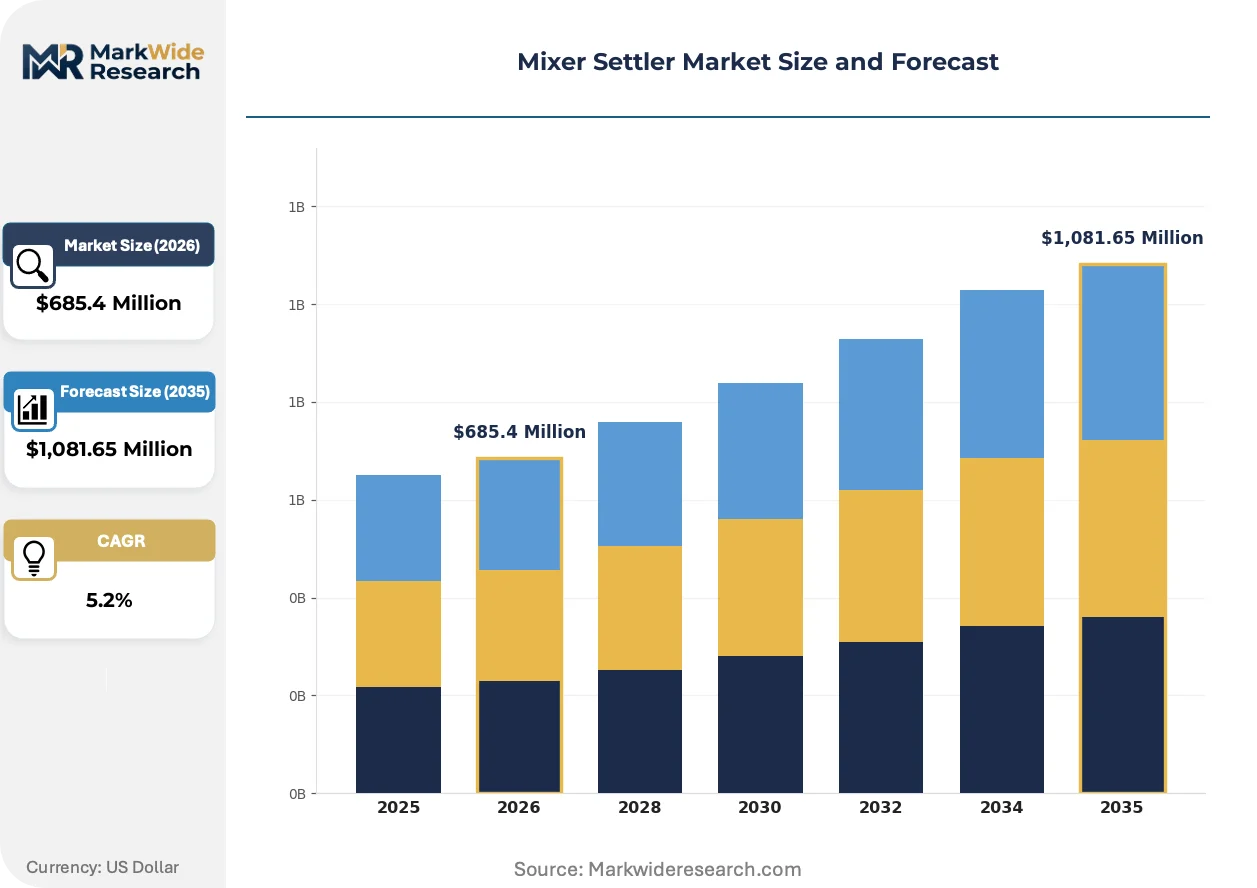
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Mixer Settler, Horizontal Mixer Settler, Mechanical Agitator, Rotor-Stator Mixer Settler Technology: Solvent Extraction, Liquid-Liquid Extraction, Disperser, Phase Separation Application: Hydrometallurgy, Nuclear Reprocessing, Chemical Manufacturing, Wastewater Treatment End User Industry: Mining Companies, Chemical Plants, Waste Management Firms, Energy Enterprises |
| Companies Covered | ANDRITZ AG, Multotec Group (Pty) Ltd, Metso Outotec Oyj, NETZSCH Holding GmbH, Eriez Manufacturing Co., FLSmidth & Co. A/S, Tenova S.p.A., Sulzer, The Weir Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mixer Settler Market Trends and Innovations
Rotor-stator agitation technology is compressing entrainment losses in high-value separations while regulatory chemistry restrictions and buyer procurement fragmentation are simultaneously reshaping equipment specification and vendor selection protocols.
Pulsed sieve plate mixer settlers is absorbing the functional role of traditional mechanical agitation in nuclear fuel reprocessing and high-purity rare earth circuits. French and Japanese reprocessing facilities are adopting these units for their reduced maintenance exposure and elimination of rotating seals in radioactive environments. This technology is absorbing market share from conventional designs by enabling continuous operation with fifteen-year maintenance intervals.
REACH authorization requirements for C10-C13 chlorinated paraffins and certain phosphorus-based extractants are forcing European hydrometallurgical operators to reformulate solvent systems and requalify equipment materials compatibility. The industrial consequence is extended commissioning timelines as new organic phases require extended stability testing against elastomer seals and gasket materials. Copper solvent extraction circuits in Poland and Spain are most affected, responding by pre-qualifying alternative diluent chemistries during front-end engineering design phases.
Fragmented procurement among mid-tier lithium and rare earth developers is displacing bundled turnkey contracts with equipment-only purchases paired with third-party integration services. Engineering-procurement-construction firms are capturing the systems integration margin that OEMs previously retained. This pattern is most visible in Western Australia's emerging rare earth processing projects, where developers source mixer settlers separately from pump and filtration packages to optimize capital allocation across financing tranches.
Mixer Settler Market Segmentation
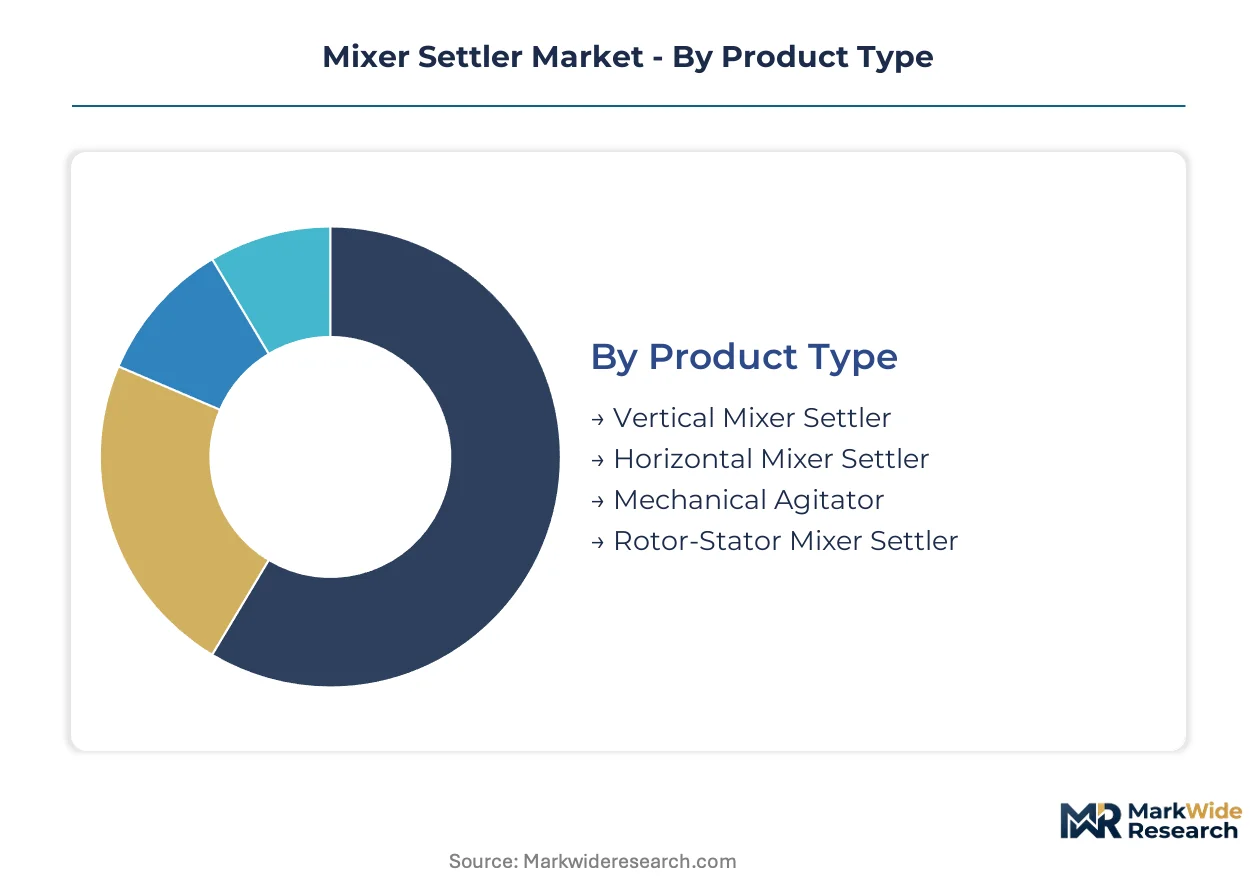
Mixer settler procurement patterns diverge sharply across product configurations and end-use intensity. Equipment specification in copper solvent extraction differs fundamentally from rare earth separation or nuclear fuel reprocessing.
Product Type:
Buyers select configurations based on phase ratio flexibility needs and capital constraints for civil works.
- Horizontal Mixer Settler:These units arrange mixing chambers and settling zones side-by-side, minimizing vertical elevation changes and reducing concrete foundation requirements. Chilean copper solvent extraction circuits in the Atacama Desert favor this design for its lower installed cost and simpler maintenance access in remote locations.
- Rotor-Stator Mixer Settler:High-shear agitation mechanisms generate intense interfacial contact, cutting entrainment losses below 0.5% in high-value rare earth separations. Western Australian rare earth developers are specifying these units for dysprosium and terbium purification where organic phase losses dominate operating economics.
- Vertical Mixer Settler:Stacked chamber arrangements reduce footprint in constrained European chemical plant revamps.
- Mechanical Agitator:Conventional paddle and turbine designs persist in legacy uranium recovery circuits.
Horizontal configurations dominate installed volumes today; rotor-stator systems are climbing the fastest as rare earth project pipelines mature.
Technology:
Process chemistry requirements dictate technology selection more than equipment cost.
- Solvent Extraction:Selective transfer of dissolved metals between immiscible liquid phases using organic extractants and aqueous feed solutions. Copper producers across Chile and Australia specify this technology for electrowinning feed preparation, with circuit designs tying directly to cathode purity guarantees.
- Liquid-Liquid Extraction:Broader category encompassing all immiscible phase contact operations beyond metals recovery. German and French chemical manufacturers deploy these systems for organic synthesis intermediate purification under REACH-controlled solvent chemistries.
- Disperser:High-energy phase contact devices for rapid mass transfer in short-residence applications.
- Phase Separation:Gravity-driven coalescence and settling without mechanical agitation for stable emulsion systems.
Solvent extraction anchors current revenue; liquid-liquid extraction is expanding most quickly as European chemical plants retrofit for containment compliance.
Application:
Regulatory exposure and product value concentration determine application-level procurement intensity.
- Hydrometallurgy:Leach solution processing for base and precious metals recovery using staged counter-current extraction. Australian and Chilean mining operations drive specification here, with equipment warranties tied to downstream electrowinning current efficiency performance.
- Nuclear Reprocessing:Spent fuel dissolution and fissile material recovery using tributyl phosphate in hydrocarbon diluents. French La Hague and Japanese Rokkasho facilities specify pulse column alternatives for reduced maintenance in high-radiation environments.
- Chemical Manufacturing:Organic intermediate purification and byproduct recovery in specialty chemical production.
- Wastewater Treatment:Metal recovery from industrial effluents prior to discharge under EPA and EU effluent guidelines.
Hydrometallurgy generates the deepest margins today; nuclear reprocessing shows the steepest expansion trajectory as China's SAMR aligns GB standards with Western qualification protocols.
End User Industry:
Contracting sophistication and technical specification authority vary dramatically across buyer categories.
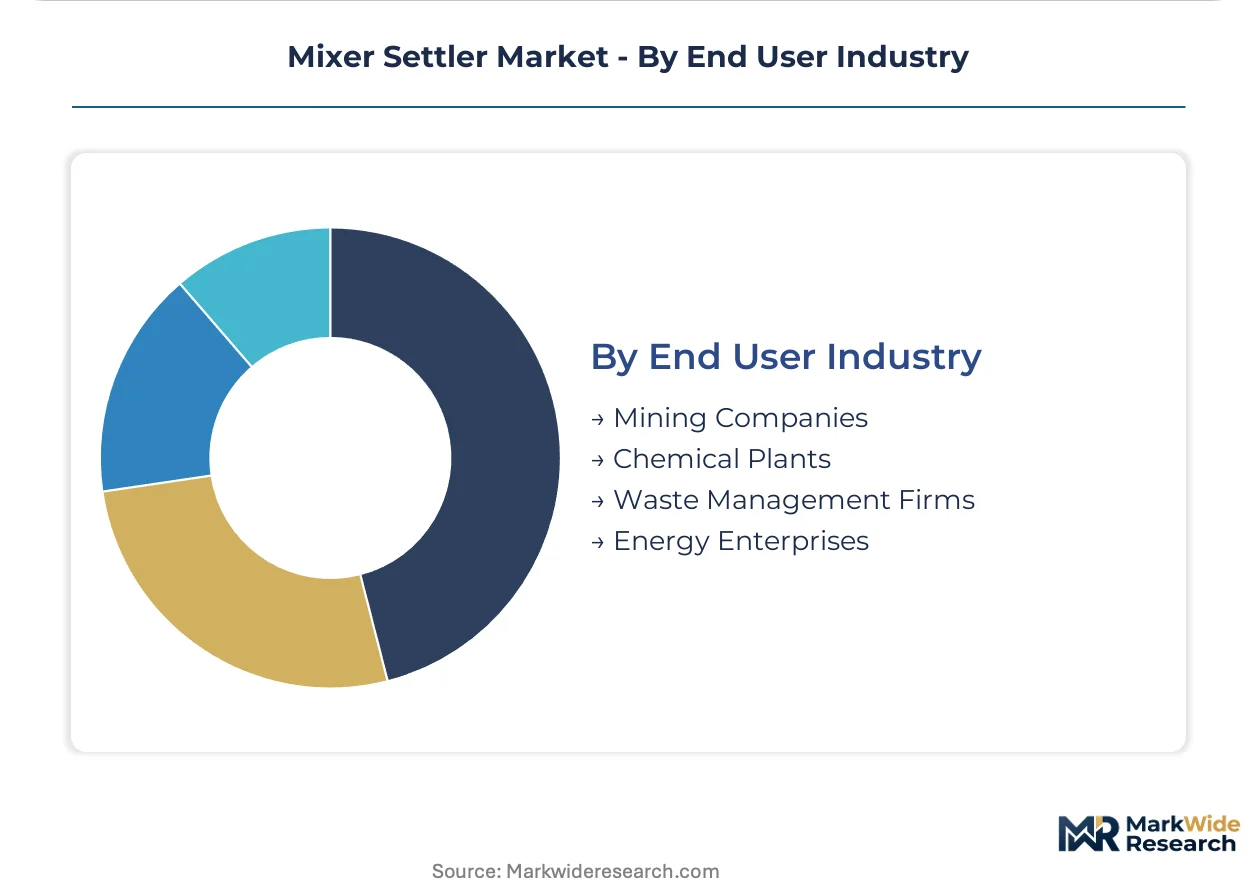
- Mining Companies:Tier-one copper producers consolidate multistage train procurement with integrated pump and filtration packages, while mid-tier lithium developers fragment orders across specialized vendors. Western Australia's emerging rare earth projects exemplify this bifurcation.
- Chemical Plants:European operators under REACH authorization timelines prioritize solvent system reformulation over equipment replacement, extending qualification cycles for new installations in Germany and Poland.
- Waste Management Firms:EPA effluent guideline compliance drives upgrades from single-stage to multistage extraction in U.S. metal recovery operations.
- Energy Enterprises:Uranium in-situ recovery and geothermal brine processing create specialized demand for corrosion-resistant materials.
Mining companies command the largest procurement volumes today; chemical plants are gaining share fastest as REACH enforcement tightens across European manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's Atacama Desert operations deploy more horizontal mixer settler capacity than Australia's Kalgoorlie region, yet both jurisdictions face divergent regulatory pressures on solvent extraction circuit design.
Chile
Copper solvent extraction expansion across state-owned and private mining complexes drives multistage train procurement. The country's environmental regulator enforces progressively stricter effluent standards for pregnant leach solution containment. Antofagasta and Calama industrial corridors concentrate new rotor-stator installations for high-purity cathode feed preparation.
Australia
Uranium in-situ recovery operations and emerging rare earth processing projects fragment equipment procurement across specialized vendors. The TGA and state-level environmental agencies mandate ISO 14001 certification for mining equipment suppliers. Western Australia's Kalgoorlie-Norseman belt anchors the deepest concentration of hydrometallurgical circuit upgrades.
United States
EPA effluent limitation guidelines compel mining operations to retrofit single-stage extraction systems with closed-loop multistage trains. The agency's metal mining category standards tighten discharge limits for copper, molybdenum, and rare earth processing facilities. Arizona's Morenci copper district and Wyoming's uranium in-situ recovery fields concentrate compliance-driven capital deployment.
Germany
Chemical manufacturers under ECHA REACH authorization timelines prioritize solvent system reformulation over equipment replacement. The regulatory body restricts C10-C13 chlorinated paraffins and phosphorus-based extractants, extending qualification cycles for new organic phases. Industrial clusters along the Rhine-Ruhr corridor retrofit contained mixer settler circuits for specialty chemical intermediate purification.
China
SAMR and NMPA alignment with GB standards for nuclear-grade equipment reshapes supplier qualification protocols for spent fuel reprocessing. The national regulator's convergence with international protocols opens pathways for Western technology transfer. Gansu Province's nuclear fuel cycle facilities and Jiangxi rare earth separation plants concentrate adoption of pulse column alternatives for reduced maintenance exposure.
Mixer Settler Market Competitive Landscape
European producers anchor the precision-engineering tier; Australian and South African specialists hold regional fabrication positions in mining-intensive jurisdictions. The vendor base organizes around three strategic archetypes: vertically integrated process technology conglomerates, regional mining equipment fabricators with dense media expertise, and precision agitation component specialists. Competitive dynamics center on bundled contract capture versus fragmented equipment-only procurement, with technology licensing and modular skid packaging emerging as dominant expansion vectors.
Within the integrated technology tier, ANDRITZ AG and Metso Outotec Oyj exemplify archetypes combining in-house pump, separation, and agitation capabilities. Sulzer occupies a position among precision component specialists serving high-shear mixing chamber applications. Multotec Group (Pty) Ltd anchors the regional specialist category, leveraging African platinum group metal circuit presence into broader hydrometallurgical positioning.
| Leading Market Players |
|---|
| ANDRITZ AG |
| Multotec Group (Pty) Ltd |
| Metso Outotec Oyj |
| NETZSCH Holding GmbH |
| Eriez Manufacturing Co. |
| FLSmidth & Co. A/S |
| Tenova S.p.A. |
| Sulzer |
| The Weir Group PLC |
| Others |
Pricing and Supply Chain Analysis
London Metal Exchange nickel and molybdenum price volatility cascades through settler tank fabrication costs into three-tier pricing structures across premium, standard, and economy levels. Stainless steel input swings compress margins for German and Japanese precision gearbox suppliers while Chilean mining procurement teams negotiate long-term offtake clauses to lock in project economics.
Pricing Analysis
Capacity additions in China's Jiangxi rare earth separation corridor are reshaping price floors for rotor-stator configurations as domestic suppliers compete on delivery timelines. Project-based contracting dominates copper solvent extraction circuits, with price differentiation anchored in ISO 14001 certification tier and agitator mechanism origin. Cost compression in standard horizontal designs is intensifying because Brazilian lithium developers prioritize capital efficiency over entrainment performance. Junior mining financings show highest price sensitivity; nuclear-grade reprocessing operators demonstrate lowest.
Supply Chain Analysis
Freight cost spikes from German precision engineering clusters to Chilean Atacama Desert sites extend delivery timelines and inflate landed equipment costs. Supply concentrates in Germany, Japan, and Finland for agitator mechanisms; China dominates stainless steel semifinished products. The chain draws from austenitic steel grades, precision gearboxes, and elastomer seal compounds. Single-source vulnerability concentrates among Japanese impeller assembly suppliers. Distribution runs through engineering-procurement-construction firms capturing systems integration margin previously retained by original equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mixer settler market reads as a late-cycle quality story as rare earth separation demand shifts specifications toward sub-0.5% entrainment guarantees that only rotor-stator configurations deliver.
For Market Incumbents: Extend warranty coverage into downstream electrowinning current efficiency performance to defend against emerging modular skid packaging competitors. Deepen backward integration into precision casting capabilities for impeller geometries to reduce exposure to Japanese gearbox supply concentration. Capture bundled contracts with integrated pump and filtration packages before engineering-procurement-construction firms disaggregate procurement further. For New Entrants and Emerging Players: Computational fluid dynamics simulation platforms offer a technology-first wedge into the expertise gap afflicting incumbent vendors. Target Brazil's Minas Gerais hard-rock lithium triangle where established solvent extraction infrastructure remains absent. Pursue rental-service business models for junior mining financings unable to deploy capital into permanent installations. For Investors and Strategic Acquirers: Asymmetric upside sits with precision agitation component specialists holding nuclear-grade qualification pathways as China's SAMR aligns with international protocols. Five-to-ten year viability favors vendors with captive GB standards compliance capability. Monitor spent fuel reprocessing facility commissioning announcements as inflection indicators for qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Skid Packaging | Pre-assembled units compress field installation timelines for Australian rare earth developers. |
| Backward Integration into Precision Casting | In-house impeller production reduces dependency on German and Japanese gearbox suppliers. |
| Nuclear-Grade Qualification Investment | GB standards alignment opens Chinese spent fuel reprocessing to Western technology transfer. |
| Computational Fluid Dynamics Talent Acquisition | Simulation expertise defends against aerospace and automotive poaching of specialized engineers. |
| Rental-Service Business Model Launch | Equipment-as-a-service enables junior lithium project financing in Brazil's emerging triangle. |
Research Methodology
Bottom-up hydrometallurgical circuit modeling reconciled against top-down fabrication capacity tracking forms the analytical core of this study. Primary interviews with plant engineers at Chilean copper operations, procurement leads at Australian rare earth developers, maintenance directors at nuclear reprocessing facilities, and aftermarket service heads at OEMs combined with secondary validation from customs trade data, SEC filings of listed mining equipment vendors, EPA effluent guideline documentation, and ECHA REACH authorization registers.
Historical trendline analysis across installed base expansion patterns and replacement cycle timing informed projection framework construction. Segmentation dimensions span product configuration, technology type, application intensity, and end-user contracting sophistication. CAGRs derive from regression against capital deployment trajectories in identified hydrometallurgical hubs. Forecast inputs incorporate stainless steel price elasticity coefficients and regulatory qualification timeline assumptions.
The model holds under stable London Metal Exchange nickel pricing and consistent EPA enforcement intensity; deviation in tariff regimes or sudden ECHA chemistry restrictions would shift equipment specification timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Nigeria Cocoa Processing Market
Food Processing Equipment
Industrial Food Slicers Market
Food Processing Equipment
Brewing Boiler Market
Food Processing Equipment
Water Cooled Cube Ice Machines Market
Food Processing Equipment
Gas Convection Oven Market
Food Processing Equipment
Europe Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Smart Food Machine Market
Food Processing Equipment
Automatic Deboner Market
Food Processing Equipment
Global Snack Pellet Equipment Market
Food Processing Equipment
Refrigerated Vending Machines Market
Food Processing Equipment
Brewery Heat Exchanger Market
Food Processing Equipment
North America Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Sandwich Preparation Refrigerators Market
Food Processing Equipment
Spray Dryer Market
Food Processing Equipment
Optical Sorter Market
Food Processing Equipment
Portable Clean-In-Place Market