
 Food Preservation Equipment Market | 2026-2036
Food Preservation Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Food Preservation Equipment Market Foresight
Food distributors is recalibrating procurement priorities as e-commerce grocery fulfillment demands tighter temperature integrity across last-mile networks. Emerson Electric Co. leverages compressor technology leadership across industrial refrigeration architectures. Thermo Fisher Scientific anchors its position through precision-controlled laboratory and biopharma cold storage systems. True Manufacturing competes on domestic manufacturing scale and rapid custom fabrication for commercial kitchens.
Food preservation equipment encompasses engineered systems designed to inhibit microbial growth, enzymatic activity, and oxidative degradation through precise temperature, atmosphere, or moisture control, typically operating between minus 40 degrees Celsius and plus 10 degrees Celsius depending on application. These systems serve commercial and industrial users by extending shelf stability, maintaining nutritional integrity, and enabling geographic decoupling of production from consumption. Refrigeration units capture the largest installed base across supermarkets and processing plants, while blast freezing technology commands premium positioning in seafood and meat processing due to superior ice crystal management that preserves cellular structure. Modified atmosphere technology is gaining traction in fruits and vegetables distribution as retailers seek to reduce shrink and extend case life.
The FDA enforces Hazard Analysis Critical Control Point protocols that mandate continuous temperature logging and rapid cooling requirements for high-risk foods, directly shaping equipment specification and validation procedures. The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is forcing equipment redesign toward lower global warming potential working fluids and system architectures. Stakeholders must monitor evolving energy efficiency standards and refrigerant transition timelines to avoid stranded asset risk in installed base decisions.
Market Dynamics
The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is forcing a system-wide redesign toward lower global warming potential working fluids, compressing replacement cycles and reshaping supplier relationships across the installed base.
Growth Catalysts
- Export cold chain expansion:Meat processing facilities in Brazil and Australia are scaling blast freezing capacity to meet destination-country sanitary protocols, driving equipment upgrades.
- FSMA traceability mandates:The FDA's enhanced Food Safety Modernization Act requirements for continuous temperature logging are pulling processors toward automated monitoring architectures.
- Post-harvest loss reduction:China's domestic cold chain infrastructure buildout is concentrating demand for modular refrigeration units in agricultural distribution hubs.
Market Restraints
- Refrigerant supply concentration:Hydrofluorocarbon feedstock production clusters in select Chinese chemical manufacturing zones, exposing equipment makers to input volatility.
- Copper and aluminum price cycles:Heat exchanger and coil fabrication depends on base metal inputs subject to commodity exchange fluctuations.
- Technical retrofit barriers:Lower global warming potential refrigerants often require compressor architecture changes incompatible with legacy system footprints.
Strategic Opportunities
- Rural cold chain penetration:India's agricultural hinterlands remain underpenetrated for controlled-atmosphere storage, creating white space for distributed small-scale units.
- Biopharma convergence:Precision temperature control expertise from food preservation is modularizing into cell therapy logistics, opening adjacent revenue pools.
- EU F-Gas Regulation acceleration:The European Union's refrigerant phase-down timeline creates pull-forward demand for natural refrigerant systems ahead of mandatory dates.
Industry Challenges
- Refrigerant technician scarcity:The transition to ammonia, CO2, and hydrocarbon systems outpaces vocational training pipeline output for safe handling certification.
- Validation timeline compression:FDA equipment qualification protocols for thermal processing extend factory acceptance testing cycles, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Preservation Equipment Market |
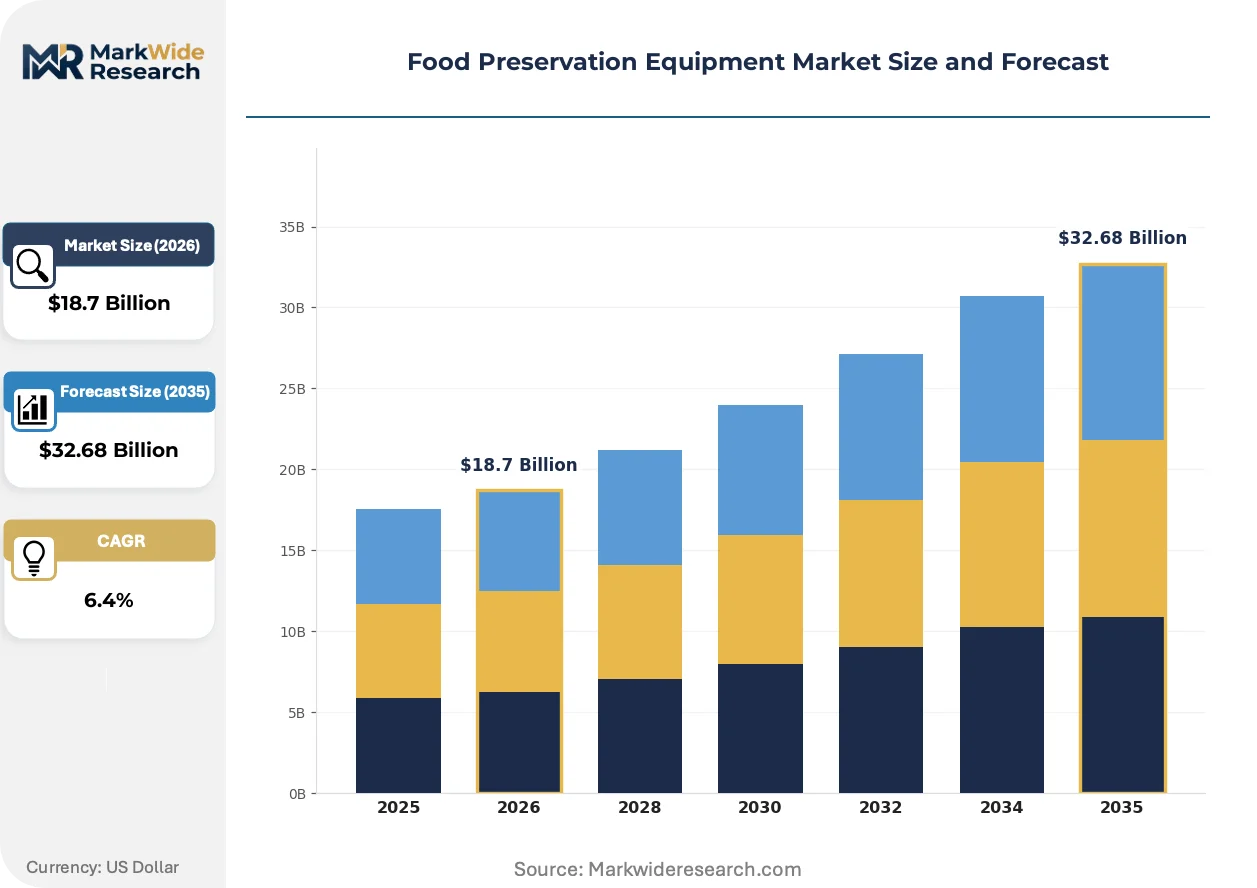
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Refrigeration Units, Vacuum Sealers, Freezers, Dehydrators, Cold Storage Rooms Technology: Modified Atmosphere, Cryogenic, Chilling, Blast Freezing, Drying Application: Dairy Products, Meat Processing, Seafood Storage, Fruits & Vegetables, Bakery Goods End User: Food Processing Plants, Supermarkets, Restaurants, Catering Services, Food Distributors |
| Companies Covered | Emerson Electric Co., Frigidaire, Thermo Fisher Scientific, Hoshizaki, Alto-Shaam, GE Appliances, Liebherr Group, True Manufacturing, Carrier, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Preservation Equipment Market Shifts & Advancements
Equipment architectures are fragmenting into configurable subsystems as buyers demand application-specific performance without full custom engineering, while refrigerant chemistry and digital monitoring converge to redefine compliance and efficiency baselines.
Natural refrigerant technology—specifically transcritical CO2 and ammonia-based systems—is modularizing industrial refrigeration architectures. Food retailers with net-zero commitments are adopting these platforms fastest in Northern Europe and coastal US markets. The shift is compressing the viable lifecycle of hydrofluorocarbon-dependent installed bases and forcing compressor OEMs to restructure service networks around toxic and high-pressure gas handling capabilities.
The European Union's F-Gas Regulation revision tightens refrigerant phase-down quotas and bans certain hydrofluorocarbons in new equipment categories. Industrial cold storage developers in Germany and the Netherlands are accelerating project timelines to secure grandfathered refrigerant allocations. The regulation is concentrating supplier technical resources on natural refrigerant system validation and away from incremental hydrofluorocarbon efficiency improvements.
Consolidated food retailers are unbundling equipment procurement from lifecycle service contracts, compressing vendor selection criteria toward total cost of ownership transparency. This buying-pattern change disrupts traditional OEM-captive service models in the US and UK supermarket segments. Equipment suppliers are responding with open-protocol monitoring architectures that enable third-party maintenance competition and reduce switching costs.
Food Preservation Equipment Market Segmentation
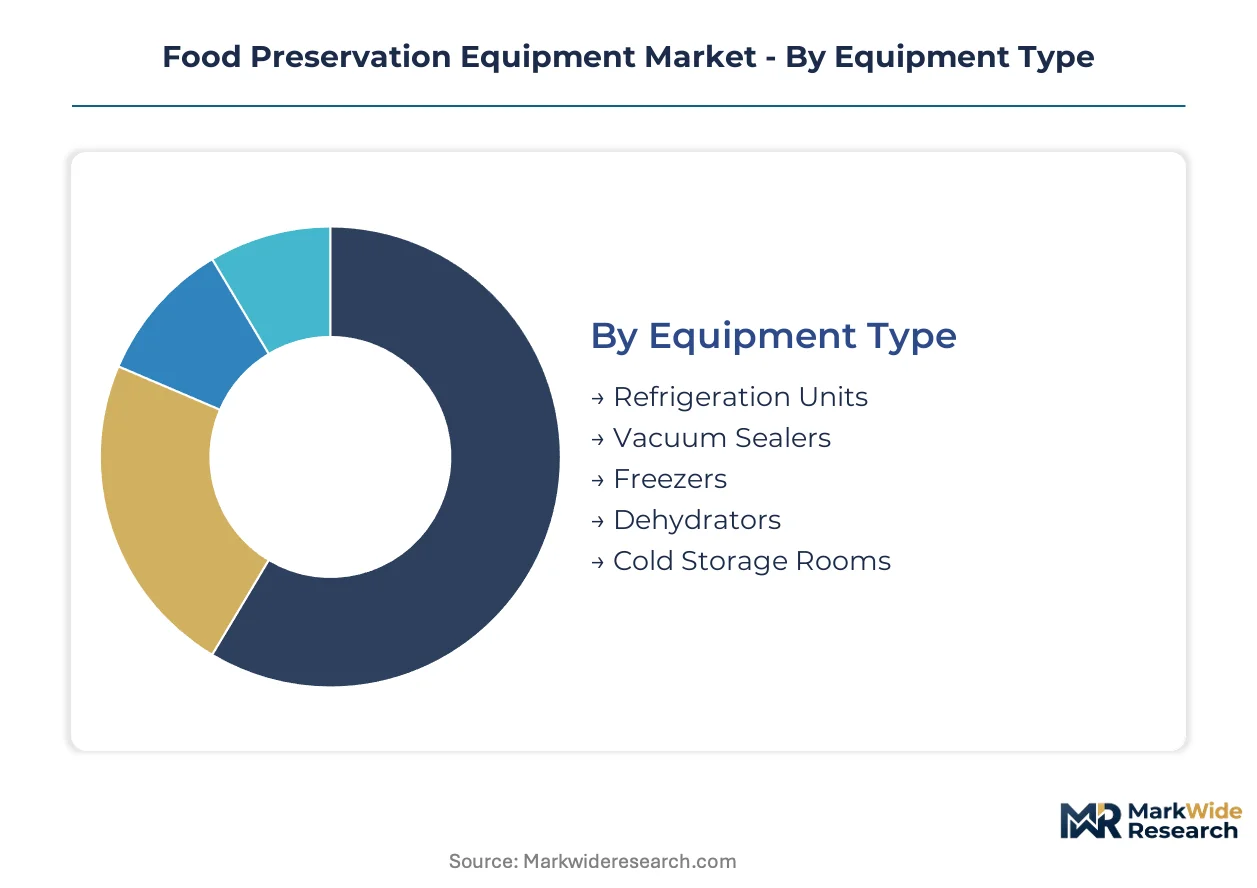
Equipment specification diverges sharply across preservation intensity requirements, with blast freezing and modified atmosphere systems commanding premium positioning against commodity refrigeration. End-user procurement patterns fragment between centralized industrial scale and distributed retail networks, each demanding incompatible service architectures.
Equipment Type:
Supply concentration clusters around compressor and coil fabrication capabilities, with integrated manufacturers capturing margin in high-performance systems while assemblers compete on standard units.
- Refrigeration Units:Compression-cycle systems utilizing vapor-compression refrigeration with temperature ranges from minus 2 to plus 8 degrees Celsius. Demand concentrates in China's agricultural distribution hubs where post-harvest loss reduction drives modular unit deployment. Cold chain infrastructure buildout in Brazil's protein export corridors pulls capacity toward industrial-scale installations.
- Freezers:Static and blast configurations operating at minus 18 degrees Celsius and below, with forced-air designs managing ice crystal formation for cellular integrity. Australia's meat processing facilities scale blast freezing capacity to meet destination-country sanitary protocols. Static cabinet systems dominate supermarket back-of-house replacement cycles.
- Vacuum Sealers:Chamber and external suction systems removing atmospheric oxygen to inhibit aerobic spoilage organisms. Commercial kitchen operators in the United States deploy tabletop units for sous-vide preparation workflows.
- Dehydrators:Convection and conductive heat systems reducing water activity below 0.6 for shelf-stable production. Artisan food producers in Italy and California adopt cabinet configurations for specialty ingredient manufacturing.
- Cold Storage Rooms:Modular panel construction with polyurethane insulation and integrated refrigeration machinery. Third-party logistics providers in Germany expand ambient-to-frozen convertible chambers for e-commerce grocery fulfillment.
Today's leader: Refrigeration Units. Tomorrow's challenger: Cold Storage Rooms.
Technology:
Cost tier stratification separates validated pharmaceutical-grade precision from commercial food service acceptability, with regulatory burden determining viable price floors.
- Blast Freezing:High-velocity forced-air systems achieving core temperatures of minus 18 degrees Celsius within 240 minutes for protein products. Seafood processors in Norway and Alaska deploy these configurations to preserve texture for export markets. The cellular structure protection justifies energy intensity versus static freezing alternatives.
- Modified Atmosphere:Controlled gas composition systems replacing oxygen with nitrogen or carbon dioxide to slow respiration in fresh produce. Retailers in the Netherlands and United Kingdom adopt transportable units to extend case life and reduce shrink in fruits and vegetables distribution. The technology commands premium positioning where waste reduction economics justify equipment investment.
- Cryogenic:Liquid nitrogen or carbon dioxide direct-contact freezing achieving ultra-rapid temperature reduction. Prepared food manufacturers in Japan deploy spiral tunnel configurations for individually quick-frozen applications.
- Chilling:Hydrocooler and forced-air systems reducing field heat in harvested produce. California's central valley vegetable packers utilize hydrocooler immersion for leafy green precooling.
- Drying:Thermal and non-thermal moisture reduction technologies including freeze-drying for high-value applications. Coffee processors in Colombia and Ethiopia deploy mechanical drying for cherry processing.
Modified Atmosphere is gaining share fastest in fresh produce logistics. Blast Freezing defends its position in protein export infrastructure.
Application:
Volume concentration tracks protein consumption patterns, with meat and dairy commanding equipment scale that fruits and vegetables distribution cannot match.
- Meat Processing:Integrated slaughter-to-storage operations requiring HACCP-compliant rapid chilling and frozen storage. Brazilian and Australian export facilities drive blast freezing capacity expansion to meet destination-country sanitary protocols. The segment demands continuous temperature logging architectures under FDA's enhanced Food Safety Modernization Act requirements.
- Dairy Products:Pasteurization-to-packaging cold chains maintaining 4 degrees Celsius through fluid milk, cheese aging, and ice cream hardening. Processors in Wisconsin and Bavaria invest in ammonia-based industrial refrigeration for energy efficiency at scale.
- Seafood Storage:Flash freezing and controlled thawing systems preserving texture in high-value species. Norwegian salmon exporters deploy cryogenic tunnel freezing for Asian market access.
- Fruits & Vegetables:Pre-cooling, controlled atmosphere, and cold storage extending market windows for seasonal production. India's agricultural hinterlands present white space for distributed small-scale controlled-atmosphere units.
- Bakery Goods:Blast freezing for par-baked products and frozen dough distribution. Industrial bakeries in France and Canada utilize spiral freezers for croissant and pastry production.
Meat Processing anchors current equipment revenue. Fruits & Vegetables shows steepest expansion trajectory as retail shrink reduction economics improve.
End User:
Customer type determines service model viability, with food processing plants accepting capital intensity that restaurant operators reject.
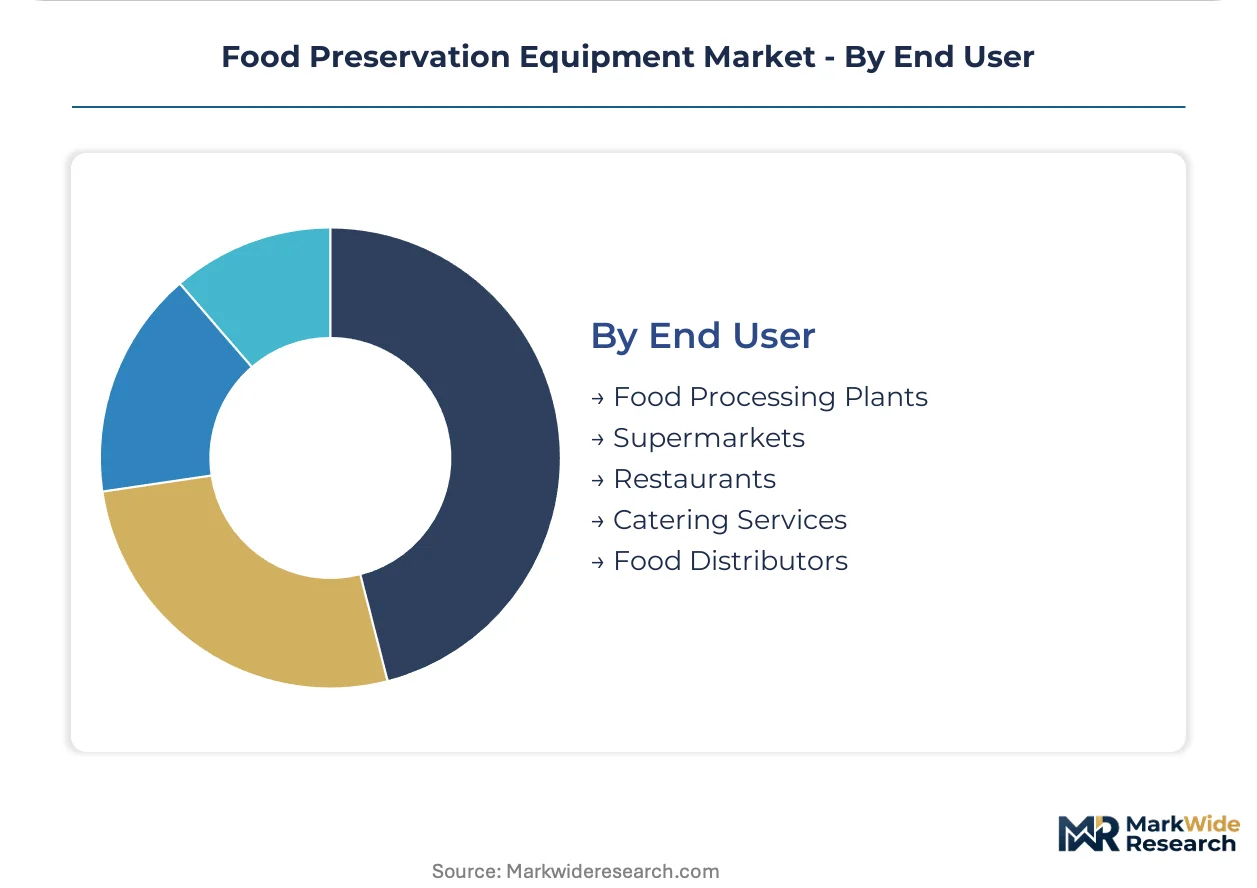
- Food Processing Plants:Centralized facilities with 24-hour production cycles requiring redundant refrigeration capacity and automated monitoring. The FDA's continuous temperature logging mandates pull these operators toward integrated control architectures. Scale economics justify ammonia and CO2 system investments with decade-long amortization horizons.
- Supermarkets:Distributed display case and back-of-house storage networks with high visibility requirements and energy cost sensitivity. Retailers in Northern Europe and coastal United States markets adopt transcritical CO2 platforms fastest to meet net-zero commitments.
- Food Distributors:Third-party logistics operations with ambient-to-frozen convertible requirements for e-commerce grocery fulfillment. Last-mile temperature integrity demands reshape procurement priorities toward modular and monitor-enabled configurations.
- Restaurants:Reach-in and walk-in configurations with space constraints and technician service dependency. Commercial kitchen operators prioritize rapid custom fabrication and domestic parts availability.
- Catering Services:Mobile and temporary cold storage for event-based food service. Operators in the United Arab Emirates and Saudi Arabia deploy containerized refrigeration for outdoor hospitality venues.
Food Processing Plants dominate capital deployment. Food Distributors are climbing the fastest as e-commerce fulfillment reconfigures cold chain requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is shifting equipment sourcing decisions as manufacturers relocate assembly to jurisdictions with extended refrigerant phase-down timelines. Cost-of-compliance gaps between the EPA's AIM Act schedule and the EU's F-Gas Regulation acceleration create procurement migration incentives.
United States
Protein export facilities in Nebraska and Iowa are scaling blast freezing capacity to meet destination-country sanitary protocols. The FDA's enhanced Food Safety Modernization Act mandates continuous temperature logging architectures that pull processors toward automated monitoring systems. Cold storage developers in California's Central Valley accelerate ammonia-based industrial refrigeration adoption ahead of utility incentive deadlines.
Germany
Third-party logistics providers in the Ruhr industrial corridor expand ambient-to-frozen convertible chambers for e-commerce grocery fulfillment. The EU's F-Gas Regulation revision tightens refrigerant phase-down quotas and bans certain hydrofluorocarbons in new equipment categories. Industrial cold storage developers in Lower Saxony compress project timelines to secure grandfathered refrigerant allocations.
China
Domestic cold chain infrastructure buildout concentrates demand for modular refrigeration units in agricultural distribution hubs. The country's dual carbon goals accelerate natural refrigerant system adoption in state-backed logistics parks. Equipment fabricators in Zhengzhou and Qingdao scale production of transcritical CO2 compressors for domestic supermarket retrofit programs.
Brazil
Meat processing facilities in Mato Grosso and São Paulo states scale blast freezing capacity to meet European Union and Chinese sanitary protocols. ANVISA enforcement of Hazard Analysis Critical Control Point protocols mandates equipment validation procedures that favor integrated supplier relationships. Cold chain operators in the Mercosur corridor invest in modular cold storage to reduce post-slaughter losses in beef export logistics.
India
Agricultural hinterlands in Maharashtra and Gujarat remain underpenetrated for controlled-atmosphere storage, creating white space for distributed small-scale units. The FSSAI's cold chain infrastructure guidelines under the Pradhan Mantri Kisan SAMPADA Yojana subsidize post-harvest loss reduction equipment. Food processors in the Delhi-NCR cluster deploy hydrocooler systems for leafy green precooling to extend market windows.
Food Preservation Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs capturing margin in high-performance systems while regional assemblers compete on standard units. The vendor base clusters around compressor technology leadership, precision-controlled laboratory systems, and domestic manufacturing scale with rapid custom fabrication capabilities. Three archetypes dominate: industrial refrigeration specialists, laboratory-grade precision equipment providers, and commercial kitchen fabricators. Consolidated food retailers are unbundling equipment procurement from lifecycle service contracts, while compressor OEMs restructure service networks around toxic and high-pressure gas handling capabilities.
Among diversified industrial technology conglomerates, Emerson Electric Co. and Carrier occupy positions anchored in compressor architecture leadership across industrial refrigeration. Thermo Fisher Scientific exemplifies the precision-controlled laboratory and biopharma cold storage specialist archetype. True Manufacturing represents domestic manufacturing scale with rapid custom fabrication capabilities for commercial kitchen operators.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Frigidaire |
| Thermo Fisher Scientific |
| Hoshizaki |
| Alto-Shaam |
| GE Appliances |
| Liebherr Group |
| True Manufacturing |
| Carrier |
| Others |
Supply & Pricing Matrix
Consolidated food retailers unbundling equipment procurement from lifecycle service contracts compress vendor selection toward total cost of ownership transparency, forcing suppliers to absorb validation costs and restructure pricing architectures around open-protocol monitoring systems.
Pricing Analysis
Distributor margins in commercial refrigeration equipment compress as direct-to-processor sales channels expand for large-scale ammonia and CO2 system deployments. Three-tier pricing structure across premium precision-controlled units, standard modular configurations, and economy-grade commercial kitchen equipment separates validated pharmaceutical-grade systems from commodity refrigeration. Cost compression in standard refrigeration tiers intensifies because Chinese fabricators scale transcritical CO2 compressor production for domestic retrofit programs. Food processing plants exhibit lowest price sensitivity due to decade-long amortization horizons, while restaurant operators prioritize rapid custom fabrication over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with hydrofluorocarbon feedstock production clustering in Chinese chemical manufacturing zones, exposing equipment makers to input volatility during refrigerant transition timelines. Component fabrication draws from China for compressor assemblies, Germany for precision control systems, and the United States for polyurethane insulation panels. Copper and aluminum price cycles in heat exchanger and coil fabrication create commodity exposure that amplifies margin pressure during base metal exchange fluctuations. Distribution runs through regional equipment distributors for commercial kitchen segments and direct OEM relationships for industrial-scale installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where the EPA's AIM Act phasedown of hydrofluorocarbon refrigerants forces system-wide redesign and pulls forward replacement demand ahead of mandatory transition dates.
For Market Incumbents: Lock in service network restructuring around toxic and high-pressure gas handling capabilities for ammonia and CO2 systems before technician scarcity widens competitive moats. Defend margin position by backward integration into compressor architecture leadership and securing grandfathered refrigerant allocations in EU jurisdictions ahead of F-Gas Regulation acceleration. Channel control through open-protocol monitoring architectures reduces switching costs but enables third-party maintenance competition that threatens captive service revenue. For New Entrants and Emerging Players: Begin with distributed small-scale controlled-atmosphere storage units in India's agricultural hinterlands where FSSAI subsidies under the Pradhan Mantri Kisan SAMPADA Yojana reduce customer acquisition friction. Target modular cold storage configurations for third-party logistics providers in Germany's Ruhr corridor where e-commerce grocery fulfillment demands ambient-to-frozen convertibility. Go-to-market positioning as natural refrigerant system specialists captures pull-forward demand from EU F-Gas Regulation timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with precision-controlled laboratory and biopharma cold storage specialists where modularization into cell therapy logistics opens adjacent revenue pools beyond food applications. Long-term viability favors equipment fabricators with transcritical CO2 compressor production capabilities and validated FDA qualification protocols. Watch for inflection signals in ANVISA enforcement intensity across Brazilian protein export corridors as integrated supplier relationships concentrate.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant System Validation | Secures market position ahead of EPA AIM Act and EU F-Gas Regulation mandatory phase-down dates. |
| Backward Integration into Compressor Technology | Captures margin in high-performance systems while reducing exposure to Chinese feedstock volatility. |
| Open-Protocol Monitoring Architecture Development | Enables third-party maintenance competition that aligns with retailer unbundling of service contracts. |
| Biopharma Cold Storage Modularization | Translates precision temperature control expertise into cell therapy logistics revenue pools. |
| Rural Cold Chain Penetration in India | Leverages FSSAI subsidy frameworks to establish distributed small-scale unit deployment at scale. |
Research Methodology
Coverage spans the United States, Germany, China, Brazil, and India, with primary inputs from each market combining interviews with maintenance directors at food processing plants, OEM procurement teams, aftermarket service heads, and regulatory affairs leads with secondary validation from EPA refrigerant phasedown schedules, FDA FSMA guidance documents, EU F-Gas Regulation amendments, and ANVISA enforcement protocols. Bottom-up equipment shipment data triangulates against top-down cold chain infrastructure investment disclosures.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon, with segmentation modeling across equipment type, preservation technology intensity, protein versus produce application, and end-user service architecture requirements. CAGRs derive from installed base replacement cycles intersecting with regulatory mandate timelines, incorporating natural refrigerant adoption curves and biopharma logistics convergence as industry-specific forecast inputs.
Caveats apply where refrigerant technician training pipeline output, copper and aluminum commodity exchange fluctuations, or FDA equipment qualification timeline compression could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Cider Brewing Equipment Market
Food Processing Equipment
Shrimp Peeling Machine Market
Food Processing Equipment
Commercial Oven Market
Food Processing Equipment
Portable Clean-In-Place Market
Food Processing Equipment
Walk-In Coolers and Freezers Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Pan Feeder Market
Food Processing Equipment
Smart Meat Thermometer Market
Food Processing Equipment
US Cold Storage Market
Food Processing Equipment
Global Meat Mixer Market
Food Processing Equipment
Sorbitol Production Equipment Market
Food Processing Equipment
Gas Convection Oven Market
Food Processing Equipment
Cold Storage Equipment Market
Food Processing Equipment
Water Cooled Cube Ice Machines Market
Food Processing Equipment
Dry Ice Market
Food Processing Equipment
Brewing Equipment Market