
 Commercial Grills Market | 2026-2036
Commercial Grills Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Grills Market Analysis
Commercial kitchen technician shortages across the United States is rotating toward manufacturers that simplify installation and remote diagnostics. Weber-Stephen Products LLC leverages its dealer network density to capture replacement cycles in independent restaurants. Middleby Corporation anchors its position through captive supply of combustion systems and control modules. Traeger Pellet Grills LLC specializes in wood-fired flavor profiles that differentiate its lineup in the fast-casual segment.
Commercial grills are thermally insulated cooking enclosures designed to sustain surface temperatures exceeding 500°F for sustained protein and vegetable preparation, typically constructed from 304-grade stainless steel with cast-iron or ceramic heat distribution elements. These units serve high-throughput foodservice operations requiring consistent output across extended operating hours. Gas grills retain the largest installed base across full-service restaurants due to existing utility infrastructure and familiar technician training. Wood pellet grills represent the fastest-expanding product category as smoke-flavor customization attracts fast-casual chains seeking menu distinction. Electric grills are gaining share in indoor installations where municipal fire codes restrict open-flame equipment in multi-story buildings.
The EPA regulates commercial cooking equipment emissions under Clean Air Act provisions, while NSF International certifies sanitation and materials safety for food-contact surfaces. OSHA standards govern ventilation and heat-exposure limits in commercial kitchen environments, shaping enclosure design and operator-side safety features. Stakeholders must monitor evolving municipal electrification mandates and building code amendments that increasingly determine allowable fuel types for new construction and renovation permits.
Market Dynamics
Commercial kitchen technician shortages across the United States are compressing replacement cycles and forcing buyers toward manufacturers that simplify installation and remote diagnostics. This labor scarcity is reshaping procurement criteria more than price or brand loyalty.
Growth Catalysts
- EPA emissions standards:The EPA's Clean Air Act provisions for commercial cooking equipment are accelerating electric and infrared technology shifts. Full-service restaurants in Texas and California are retrofitting outdoor kitchens to comply.
- Wood pellet flavor customization:Fast-casual chains seeking menu distinction are expanding smoke-flavor programs. This technology attracts operators wanting differentiation without kitchen complexity.
- Texas and California construction:Elevated hospitality permitting in these states is driving new-installation demand for thermally insulated cooking enclosures. Multi-unit operators are standardizing specifications across regional footprints.
Market Restraints
- 304-grade stainless steel input volatility:Nickel and chromium price swings squeeze margin predictability for enclosure fabricators. Foundry capacity constraints in Asia-Pacific amplify this pressure.
- Combustion system supply concentration:Captive production of control modules and burner assemblies sits with a limited supplier base. This bottleneck extends lead times for gas grill manufacturers.
- Municipal fire code fragmentation:Multi-story building restrictions on open-flame equipment create compliance patchwork. Electric alternatives carry higher capital cost per BTU output.
Strategic Opportunities
- Remote diagnostics integration:IoT-enabled thermal monitoring and predictive maintenance address technician scarcity. Independent restaurants in secondary metros represent underserved adopters.
- NSF sanitation certification premium:Food-contact surface standards are tightening procurement specifications. Manufacturers with pre-certified materials capture specification lock-in.
- Infrared-electric convergence:Hybrid heating systems combining radiant and convective elements open indoor installation markets. Fast-casual operators in urban cores are piloting these configurations.
Industry Challenges
- Commercial kitchen ventilation integration:OSHA heat-exposure limits and enclosure design requirements demand specialized engineering. Retrofit installations face structural compatibility constraints with legacy hood systems.
- NSF certification timeline compression:Materials safety validation for new ceramic heat distribution elements extends product launch schedules. Testing backlog at certification bodies delays revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Grills Market |
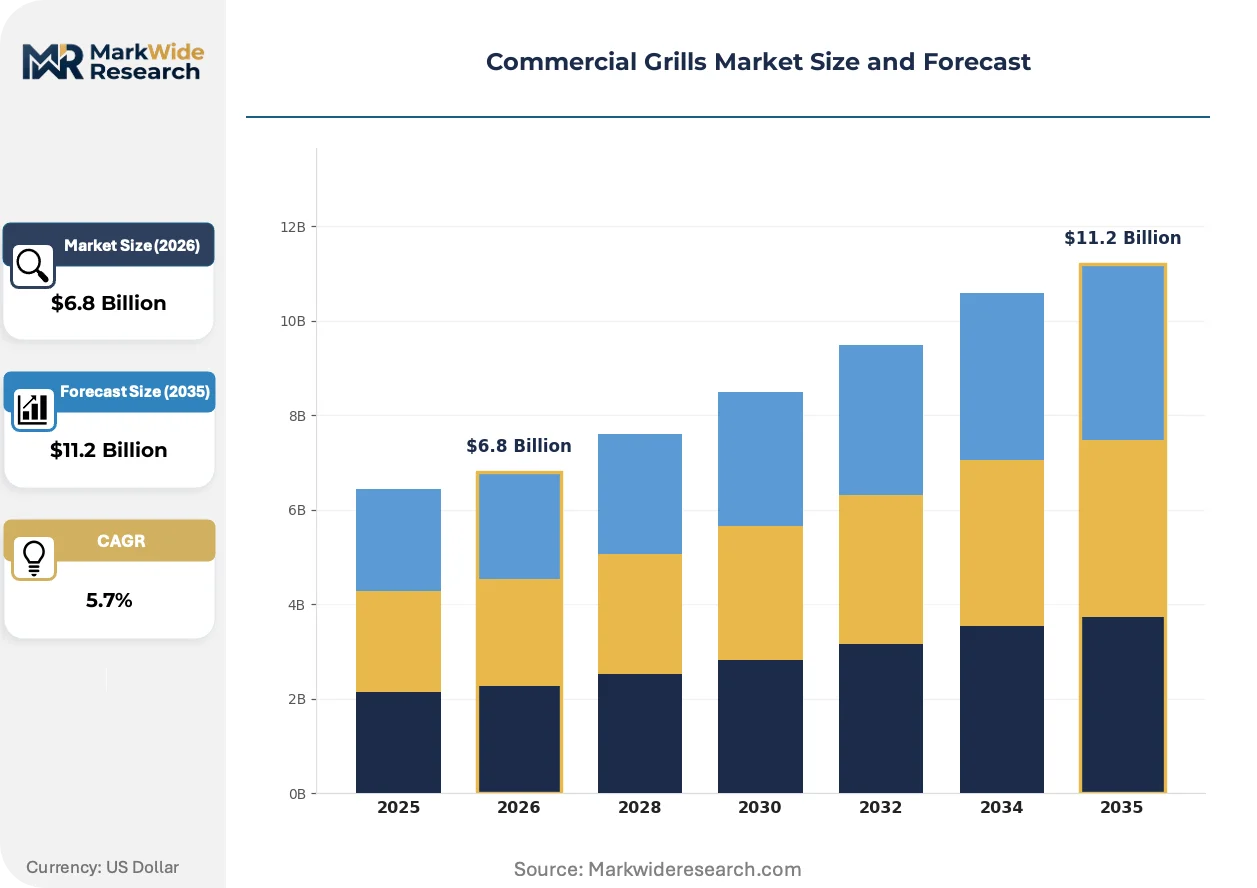
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Grills, Charcoal Grills, Electric Grills, Wood Pellet Grills End User: Restaurants, Food Trucks, Catering Services, Hotels Installation Type: Built-in Grills, Portable Grills, Outdoor Grills, Indoor Grills Grilling Technology: Infrared Cooking, Conventional Grilling, Smoker Technology, Rotisserie |
| Companies Covered | Weber-Stephen Products LLC, Middleby Corporation, Traeger Pellet Grills LLC, Napoleon, Crown Verity, Blackstone, Char-Broil LLC, Pit Boss Grills, Dyna-Glo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Grills Market Emerging Trajectories
Infrared heating technology is fragmenting the traditional gas-electric dichotomy in commercial kitchen specification. Equipment buyers now face expanded thermal source options that alter kitchen layout economics and operator training requirements.
Infrared radiant panels convert electrical energy to surface temperatures exceeding 900°F without open flame. Fast-casual chains in urban cores are adopting these systems to bypass municipal fire restrictions. This technology is bifurcating the indoor grill market between flame-restricted and flame-permitted installation environments.
The EPA's commercial cooking equipment emissions standards under Clean Air Act provisions are tightening allowable particulate output from gas combustion systems. Manufacturers are redesigning burner geometries and adding catalytic converters to maintain compliance. Full-service restaurants in jurisdictions with air quality management districts face accelerated replacement timelines.
After-sales service unbundling is altering how independent restaurants contract for equipment maintenance. Buyers are separating warranty coverage from preventive service agreements, comparing third-party technician networks against manufacturer-direct programs. This pattern is most visible in Texas and California where hospitality labor markets remain tightest.
Commercial Grills Market Segmentation
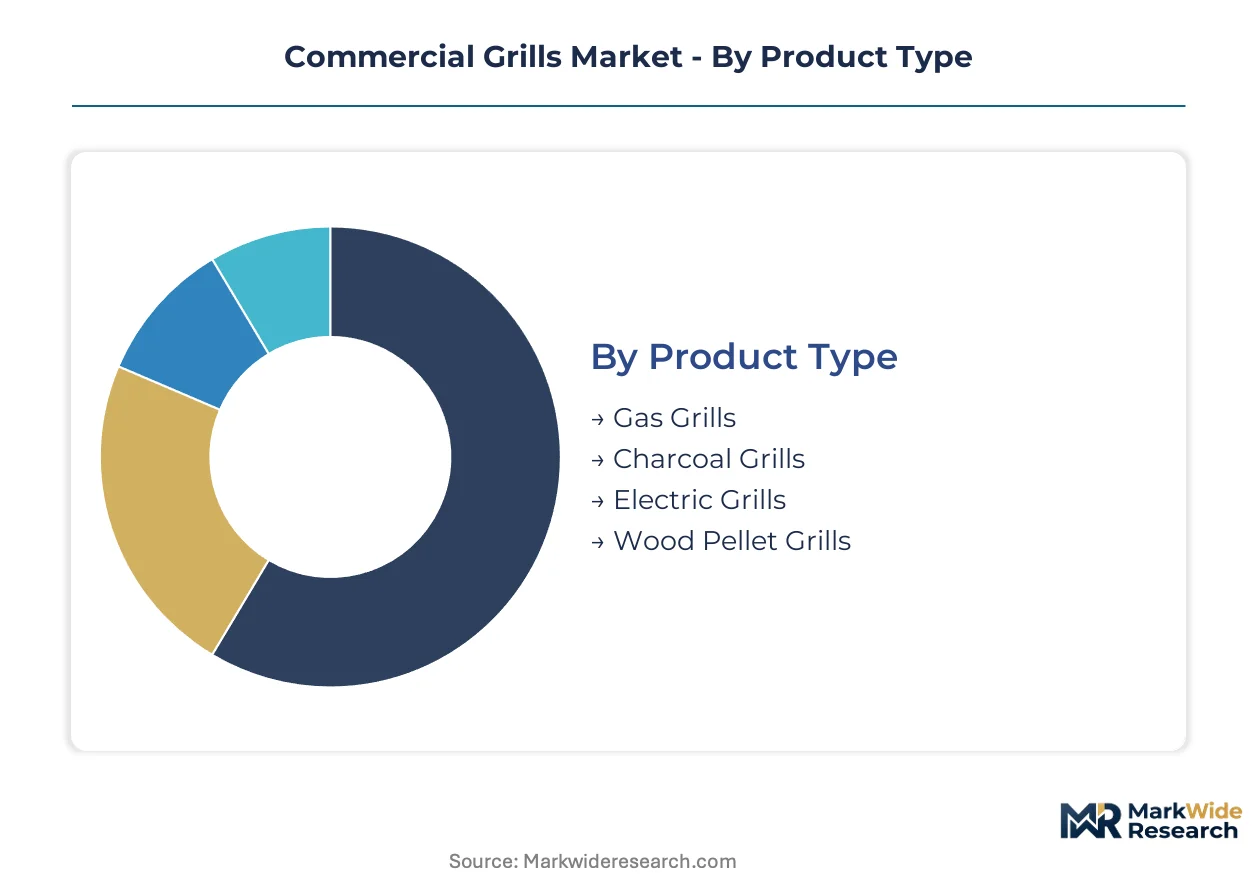
Equipment specification in commercial grilling diverges sharply by thermal source and installation environment. Procurement committees weigh combustion infrastructure, municipal code constraints, and flavor-program requirements when segmenting purchase decisions.
Product Type:
Gas grills face intensifying substitution pressure from electric and infrared alternatives as EPA emissions standards tighten and urban fire codes proliferate.
- Gas Grills:These units utilize propane or natural gas combustion systems with cast-iron or ceramic heat distribution elements. Full-service restaurants across Texas and California retain gas infrastructure for outdoor kitchen installations where emissions regulations permit open-flame operation.
- Wood Pellet Grills:Automated auger systems feed compressed hardwood pellets into fire pots, generating controlled smoke-flavor profiles. Fast-casual chains in the United States are expanding pellet programs to differentiate menus without kitchen complexity.
- Electric Grills:Resistance-heating elements enclosed in 304-grade stainless steel housings deliver thermal output without combustion. Multi-story building operators in fire-restricted municipalities specify these for indoor installations.
- Charcoal Grills:Traditional lump or briquette combustion systems requiring manual temperature management. Limited adoption persists in specialty barbecue concepts and high-end steakhouse formats.
Gas grills retain volume leadership; wood pellet grills hold the steepest expansion curve.
End User:
Cost-tier stratification separates high-volume chain operators from independent single-unit buyers with diverging capital deployment timelines.
- Restaurants:Full-service and fast-casual establishments requiring sustained thermal output across extended operating hours. Specifications prioritize NSF-certified surfaces and OSHA-compliant ventilation integration for high-throughput protein preparation.
- Hotels:Multi-outlet hospitality properties standardizing equipment across banquet kitchens, poolside grills, and room-service operations. Procurement favors manufacturers with national service networks and remote diagnostic capabilities.
- Catering Services:Mobile and event-based foodservice operators requiring transportable thermal systems. Demand concentrates in units with rapid heat-up cycles and simplified cleaning protocols.
- Food Trucks:Constrained-space mobile kitchens prioritizing compact footprints and multi-fuel flexibility. Operators in Texas and California are retrofitting propane systems to comply with evolving emissions standards.
Restaurants command the largest equipment volume; food trucks are climbing the fastest.
Installation Type:
Application context dictates enclosure engineering, with permanent built-in systems diverging fundamentally from mobile configurations on structural and regulatory dimensions.
- Outdoor Grills:Weather-resistant enclosures with enhanced insulation for ambient temperature fluctuation. Full-service restaurants in Texas and California are expanding patio kitchen installations to capture al fresco dining demand.
- Built-in Grills:Custom-fabricated enclosures integrated into permanent masonry or stainless steel structures. These units require specialized ventilation engineering and structural load assessment during construction permitting.
- Indoor Grills:Electric or infrared systems designed for enclosed kitchen environments with integrated hood compatibility. Municipal fire code restrictions in multi-story buildings are accelerating specification of these configurations.
- Portable Grills:Compact units with caster-mounted or collapsible frames for temporary deployment. Catering operators and event venues utilize these for off-premise service flexibility.
Outdoor grills dominate current installations; indoor configurations are gaining share fastest.
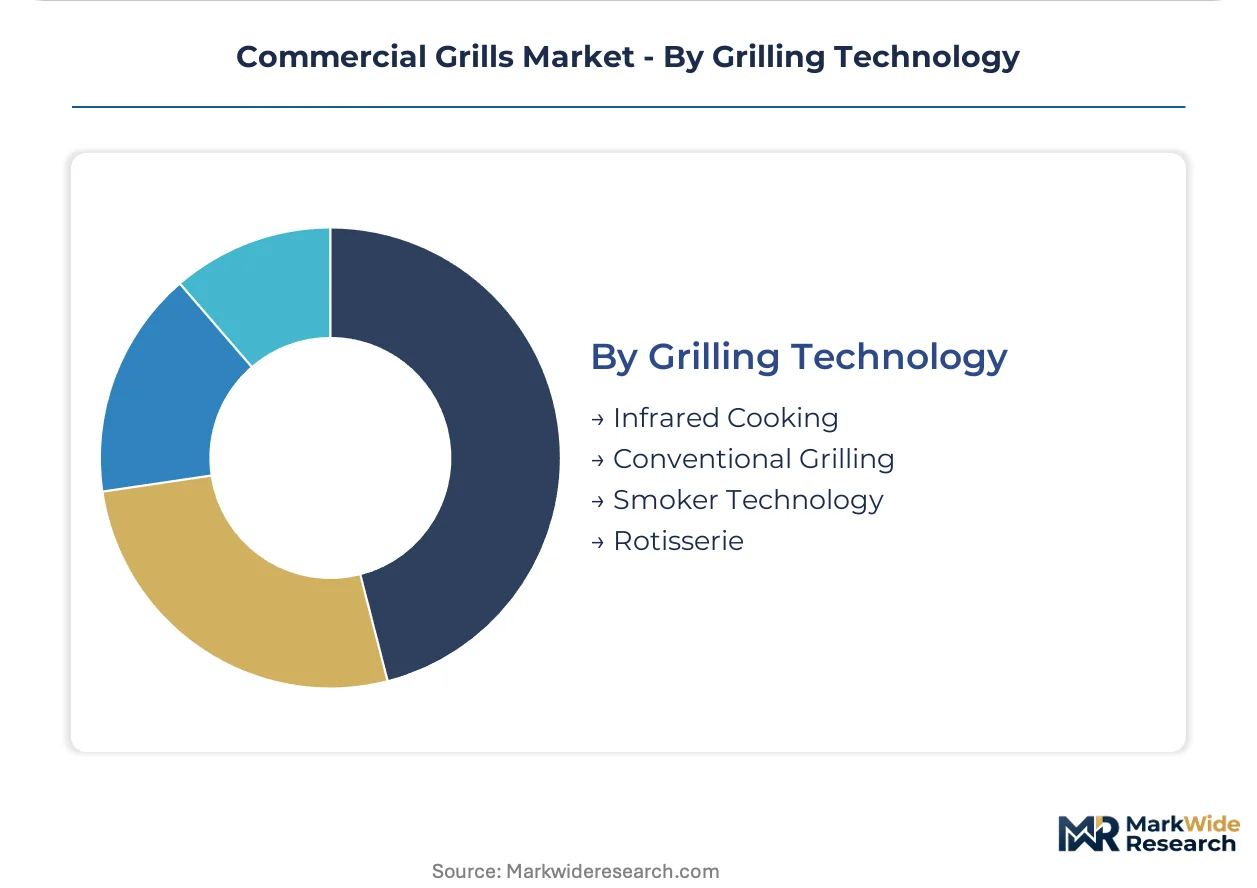
Grilling Technology:
Maturity curves separate established conventional systems from emerging thermal technologies with diverging technician training requirements and capital intensity.
- Conventional Grilling:Direct flame or radiant heat transfer through metal grates, the baseline technology across gas and charcoal platforms. Technician familiarity and replacement part availability sustain specification in independent restaurants.
- Infrared Cooking:Radiant panels converting electrical or gas energy to surface temperatures exceeding 900°F without open flame. Fast-casual operators in urban cores are piloting these systems to bypass municipal fire restrictions.
- Smoker Technology:Low-temperature wood combustion with extended cook times for collagen breakdown and smoke-ring formation. Wood pellet automation is expanding this category beyond traditional barbecue specialists.
- Rotisserie:Motorized spit systems for even heat distribution around whole proteins. Limited adoption persists in high-end steakhouse and hotel banquet applications.
Conventional grilling maintains installed-base dominance; infrared cooking shows the steepest adoption trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment specification diverges sharply by geography, with fire-code density and emissions enforcement determining fuel-type selection. Outdoor kitchen penetration remains highest in jurisdictions with permissive combustion regulations and extended dining seasons.
United States
Texas and California hospitality construction permits are driving new-installation demand for thermally insulated cooking enclosures. EPA Clean Air Act provisions are accelerating electric and infrared retrofits in air quality management districts. Independent restaurants in secondary metros represent underserved adopters of remote diagnostics.
Germany
Commercial kitchen operators are navigating REACH compliance for ceramic heat distribution elements and stainless steel alloys. The country's national environmental regulator is tightening particulate thresholds for gas combustion systems. Fabricators in North Rhine-Westphalia are piloting hybrid infrared-electric configurations for urban hotel installations.
Japan
METI efficiency standards are reshaping procurement specifications for high-throughput protein preparation equipment. JIS certification requirements for food-contact surfaces extend product validation timelines. Tokyo-based fast-casual chains are standardizing compact electric systems for multi-story building compliance.
Australia
Outdoor dining culture sustains demand for weather-resistant grilling enclosures across hospitality properties. State-level fire safety codes vary in open-flame permissibility for urban cores. Melbourne and Sydney operators are expanding patio kitchen footprints to capture al fresco revenue.
United Arab Emirates
Hospitality construction in Dubai and Abu Dhabi is standardizing built-in grill specifications across resort and hotel banquet operations. MOHAP food safety protocols are tightening sanitation certification requirements for food-contact surfaces. Premium hotel operators are specifying manufacturers with regional service network density.
Commercial Grills Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in commercial grill manufacturing. The upper tier commands captive supply of combustion systems and control modules, while specialists differentiate through flavor-program technologies and regional service density. Two archetypes dominate: vertically integrated enclosure fabricators with in-house burner production, and technology-focused specialists leveraging automated fuel-feed systems. Competitive moves concentrate on strategic partnerships for certification acceleration and geographic expansion through dealer network density.
Among North American manufacturers, Weber-Stephen Products LLC exemplifies the scale-driven archetype with established distribution infrastructure. Middleby Corporation occupies a position reflecting integrated supply chain control over thermal system components. Traeger Pellet Grills LLC represents the specialization vector in automated wood-fired flavor delivery systems.
| Leading Market Players |
|---|
| Weber-Stephen Products LLC |
| Middleby Corporation |
| Traeger Pellet Grills LLC |
| Napoleon |
| Crown Verity |
| Blackstone |
| Char-Broil LLC |
| Pit Boss Grills |
| Dyna-Glo |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between enclosure fabricators and nickel-chromium suppliers lock in both raw material access and margin predictability for 304-grade stainless steel procurement. These arrangements concentrate pricing power with foundries in Asia-Pacific while insulating North American grill manufacturers from spot market volatility.
Pricing Analysis
Contract-based long-term offtake structures dominate procurement between tier-one manufacturers and alloy suppliers, though spot purchases persist for specialty ceramic heat distribution elements. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified systems with remote diagnostics from basic gas configurations. Cost compression in economy-tier electric grills is intensifying because municipal fire code proliferation accelerates specification shifts. Independent restaurants in secondary metros exhibit highest price sensitivity; hotel chains with national service network requirements show lowest.
Supply Chain Analysis
Strait of Malacca transit underwrites critical nickel and chromium flows from Indonesian and Philippine extraction sites to Taiwanese and South Korean foundries. 304-grade stainless steel production draws from captive mining in Australia and Brazil alongside Chinese ferrochrome processing. Single-source vulnerability concentrates in ceramic heat distribution element fabrication, where German and Japanese suppliers control specialized refractory formulations. Distribution runs through manufacturer-direct dealer networks for independent restaurants and GPO-negotiated contracts for multi-unit hospitality operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial grills sit in early-cycle expansion as EPA emissions enforcement and municipal electrification mandates accelerate technology turnover across installed bases. Wood pellet automation and infrared-electric convergence represent underpenetrated vectors with runway for specification capture.
For Market Incumbents: Secure captive supply of combustion control modules through backward integration or exclusive supplier agreements to defend against emerging electric-specialist entrants. Lock in NSF certification pre-approval for ceramic heat distribution elements to compress launch timelines and capture specification lock-in from procurement committees. For New Entrants and Emerging Players: After-sales service unbundling in Texas and California represents the most penetrable white-space where incumbents under-serve independent restaurants with third-party technician networks. Target fast-casual chains piloting infrared-electric hybrid configurations with flavor-program customization as the go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with IoT-enabled remote diagnostics and preventive service agreements rather than transactional equipment sales. Over a multi-year horizon, vertically integrated enclosure fabricators with in-house burner production offer superior margin durability. Watch EPA enforcement intensity in Texas and California air quality management districts as the inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Remote Diagnostics Integration | IoT-enabled thermal monitoring addresses technician scarcity in secondary metros. |
| NSF Certification Pre-Approval | Pre-certified materials compress product launch schedules and capture specification lock-in. |
| Backward Integration into Combustion Systems | In-house control module production defends margin position against supply concentration. |
| Infrared-Electric Hybrid Development | Hybrid configurations open indoor installation markets in fire-restricted municipalities. |
| Dealer Network Density Expansion | Regional service coverage captures replacement cycles in independent restaurant segments. |
Methodological Framework
A standing panel of commercial kitchen equipment procurement managers, NSF certification engineers, hospitality construction contractors, and aftermarket service technicians provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with these stakeholders against secondary validation from EPA emissions filings, NSF certification databases, OSHA ventilation standards, and hospitality permitting records in Texas and California. Bottom-up equipment shipment analysis triangulated against top-down construction spending data across the forecast framework.
Consistency checks validated volume and value outputs against external benchmarks including foundry capacity utilization rates and stainless steel alloy pricing indices. The analytical framework segmented modeled outputs by thermal source, installation environment, end-user type, and grilling technology across the projection horizon. CAGRs were derived from replacement cycle analysis, regulatory compliance timelines, and construction permit trajectories without year-specific anchoring.
Forecasts assume regulatory continuity in EPA Clean Air Act enforcement and municipal fire code frameworks; material policy shifts would require re-modeling of technology substitution curves. Practitioners should keep alternative scenarios live as electrification mandate adoption rates and nickel-chromium supply disruptions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Commercial Charbroiler Market
Food Service
Commercial Deep Fryer Parts and Accessories Market
Food Service
North America Online Grocery Delivery Market
Food Service
Online Grocery Market
Food Service
Europe Online Grocery Market
Food Service
Bahrain Food Service Market
Food Service
Airport Quick Service Restaurants Market
Food Service
Asia-Pacific Halal Food and Beverage Market
Food Service
Europe Inflight Catering Market
Food Service
Latin America Inflight Catering Market
Food Service
Chained Consumer Foodservice Market
Food Service
China Retail Bubble Tea Kits Market
Food Service
Indonesia Foodservice Market
Food Service
Australia Foodservice Market
Food Service
Sandwich Toasters Market
Food Service
Ice Cream Carts Market