
 Europe Cloud Kitchen Market | 2026-2036
Europe Cloud Kitchen Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cloud Kitchen Market Analytics
Enterprise foodservice buyers is bifurcating from independent restaurant operators as the dominant tenant archetype in European cloud kitchen facilities. Rebel Foods leverages its multi-brand technology stack to sustain high kitchen utilization rates across multiple European cities. Kitopi anchors its competitive position through integrated back-of-house operations that control ingredient sourcing and quality consistency at scale.
A cloud kitchen is a delivery-optimized food preparation facility operating without customer-facing dining areas, typically requiring commercial-grade ventilation systems, temperature-controlled storage, and order aggregation software to synchronize output with third-party delivery platforms. The primary commercial purpose centers on decoupling food production from real estate-intensive front-of-house operations to achieve lower per-unit overhead and faster geographic scaling. Delivery-only service type leads current facility deployment across Europe, while shared-space business models capture disproportionate interest from venture-backed entrants seeking capital efficiency. Order management technology sits at the core of margin preservation, as kitchen throughput optimization directly determines unit-level profitability in high-rent urban locations.
EU F-Gas Regulation and national food safety frameworks enforced by EFSA-aligned agencies shape equipment specifications and refrigeration system choices across member states. REACH compliance obligations extend to packaging materials and cleaning agents used in centralized production environments. GDPR constraints on consumer data handling influence how order management platforms architect customer analytics and retention systems. Stakeholders must weigh the trade-off between rapid facility expansion and the operational complexity of harmonizing cross-border regulatory compliance as the competitive set densifies.
Market Dynamics
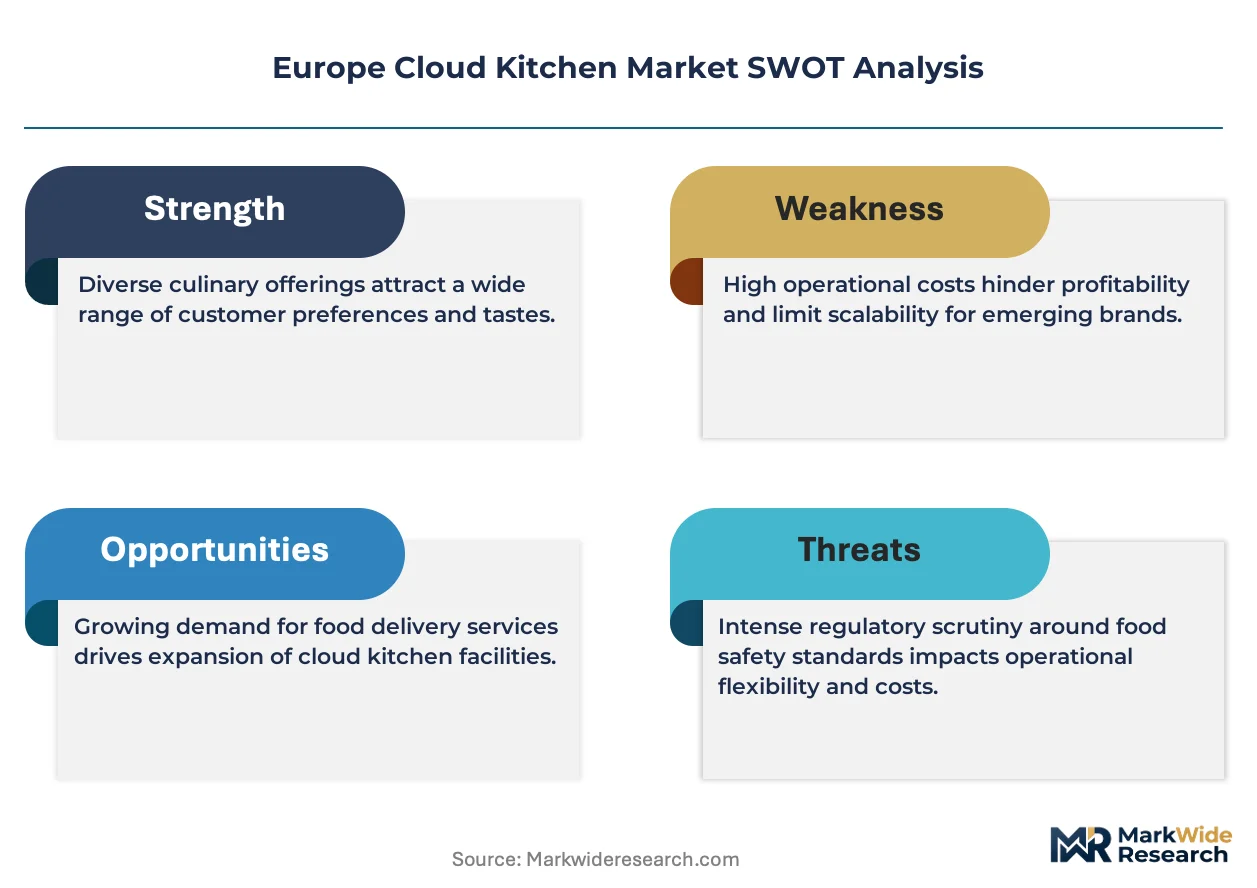
EU Green Deal sustainability mandates are forcing rapid equipment procurement cycles across European cloud kitchen facilities as operators retrofit ventilation and refrigeration systems to meet tightening F-Gas Regulation phase-down schedules.
Growth Catalysts
- Urban Density Concentration:Germany, France, and the United Kingdom exhibit the highest digital food ordering penetration rates in Europe. This density creates favorable unit economics for delivery-only operations seeking rapid geographic scaling.
- Corporate Catering Expansion:Enterprise foodservice buyers now dominate tenant archetypes in European cloud kitchen facilities. Quick-service restaurant chains are actively expanding off-premise food production capacity across the region.
- REACH-Compliant Packaging Innovation:New sustainable packaging materials meeting ECHA registration requirements are reducing compliance friction for centralized production environments. This accelerates facility rollout timelines in member states.
Market Restraints
- Commercial Real Estate Cost Escalation:High-rent urban locations in London, Paris, and Berlin compress unit-level profitability. Kitchen throughput optimization becomes critical for margin preservation in these markets.
- Refrigeration System Retrofit Burden:F-Gas Regulation phase-down mandates require costly equipment upgrades. Smaller independent operators face disproportionate capital burdens compared to integrated chains.
- Third-Platform Commission Structures:Order aggregation software dependencies on delivery platforms extract significant revenue share. This structural cost concentration limits pricing flexibility for facility operators.
Strategic Opportunities
- Shared-Space Business Models:Venture-backed entrants are capturing capital efficiency through multi-tenant kitchen facilities. This model spreads fixed costs across rotating brand portfolios in high-density European cities.
- GDPR-Compliant Customer Analytics:Order management platforms are architecting retention systems within strict data handling constraints. First-party data strategies create competitive differentiation against platform-dependent rivals.
- Back-of-House Integration Control:Operators capturing ingredient sourcing and quality consistency at scale can expand across multiple European cities. Vertical control over supply chains reduces per-unit variability.
Industry Challenges
- Cross-Border Regulatory Harmonization:EFSA-aligned national food safety frameworks vary across member states. Operators expanding facility networks face operational complexity in standardizing compliance protocols.
- CE Marking Equipment Certification:Commercial-grade ventilation and temperature-controlled storage systems require extended approval timelines. Procurement delays compress facility launch windows in competitive urban markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cloud Kitchen Market |
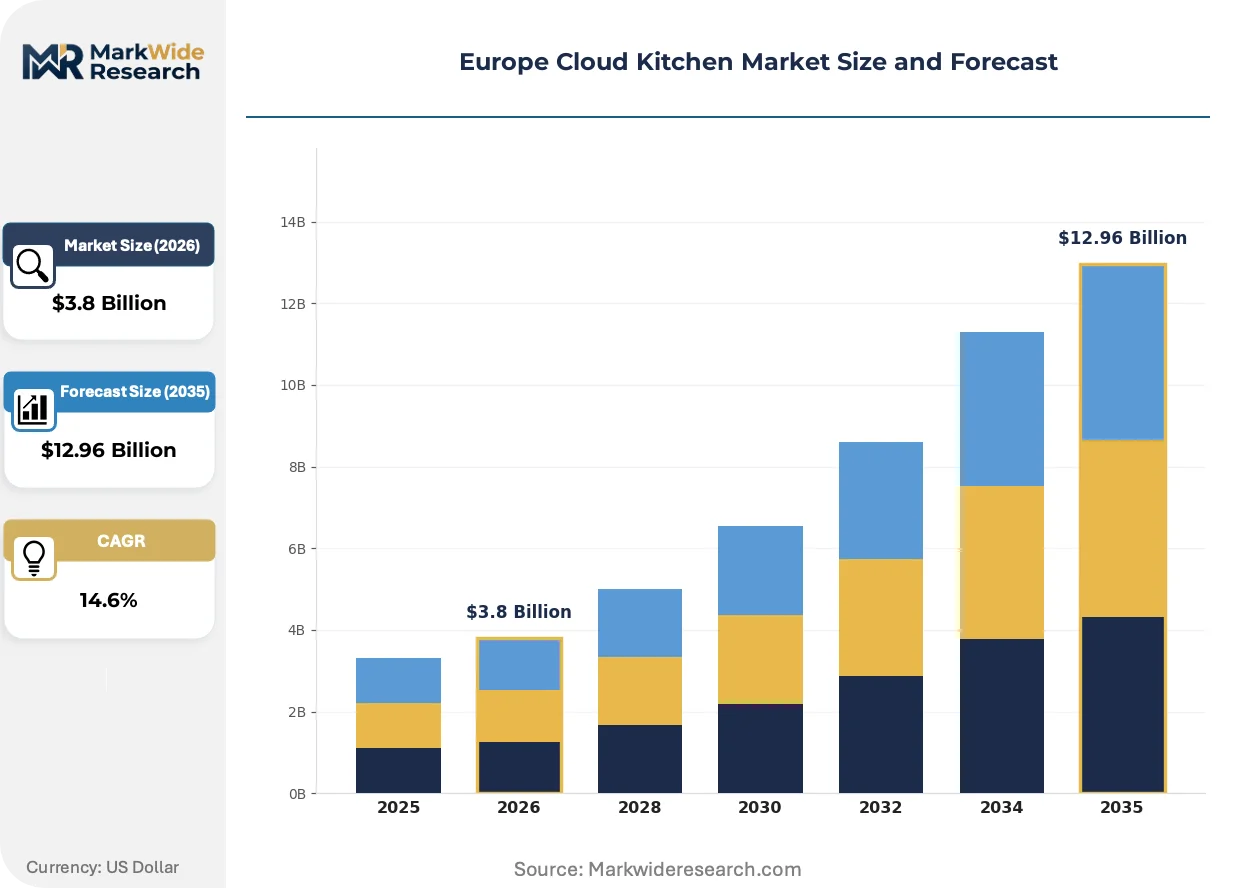
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Delivery Only, Dine-In, Pickup, Mixed-Use Business Model: Franchise, Multi-Brand, Shared Space, Virtual Brand Cuisine Type: Italian, Asian, American, Mexican Technology: Order Management, Cloud Computing, IoT Solutions, Food Safety Tech |
| Companies Covered | Rebel Foods, Kitopi, Keatz, Kitchen United, Zuul Kitchen, Dahmakan, DoorDash Kitchen, CloudKitchens, POSist Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cloud Kitchen Market Evolving Landscape
Order management technology sits at the core of competitive positioning as kitchen throughput optimization directly determines survival in high-rent European urban locations. Three developments are actively restructuring how facilities capture and retain demand.
Artificial intelligence-driven demand forecasting is decomposing traditional batch-cooking workflows in cloud kitchen operations. Enterprise foodservice buyers deploy these systems to synchronize output with third-party delivery platform order patterns. The technology compresses food waste ratios and labor idle time in facilities across Germany and France.
F-Gas Regulation phase-down schedules are accelerating heat pump adoption in commercial kitchen refrigeration systems. Equipment manufacturers must redesign product lines to meet lower global warming potential refrigerant requirements. French and German facility operators face the steepest retrofit obligations under national implementation timelines.
Enterprise procurement teams are consolidating vendor relationships around integrated back-of-house service providers. Independent restaurant operators lose negotiating leverage as large chains capture volume-based equipment and ingredient pricing. This concentration is most visible in United Kingdom urban markets where facility density has matured fastest.
Europe Cloud Kitchen Market Segmentation
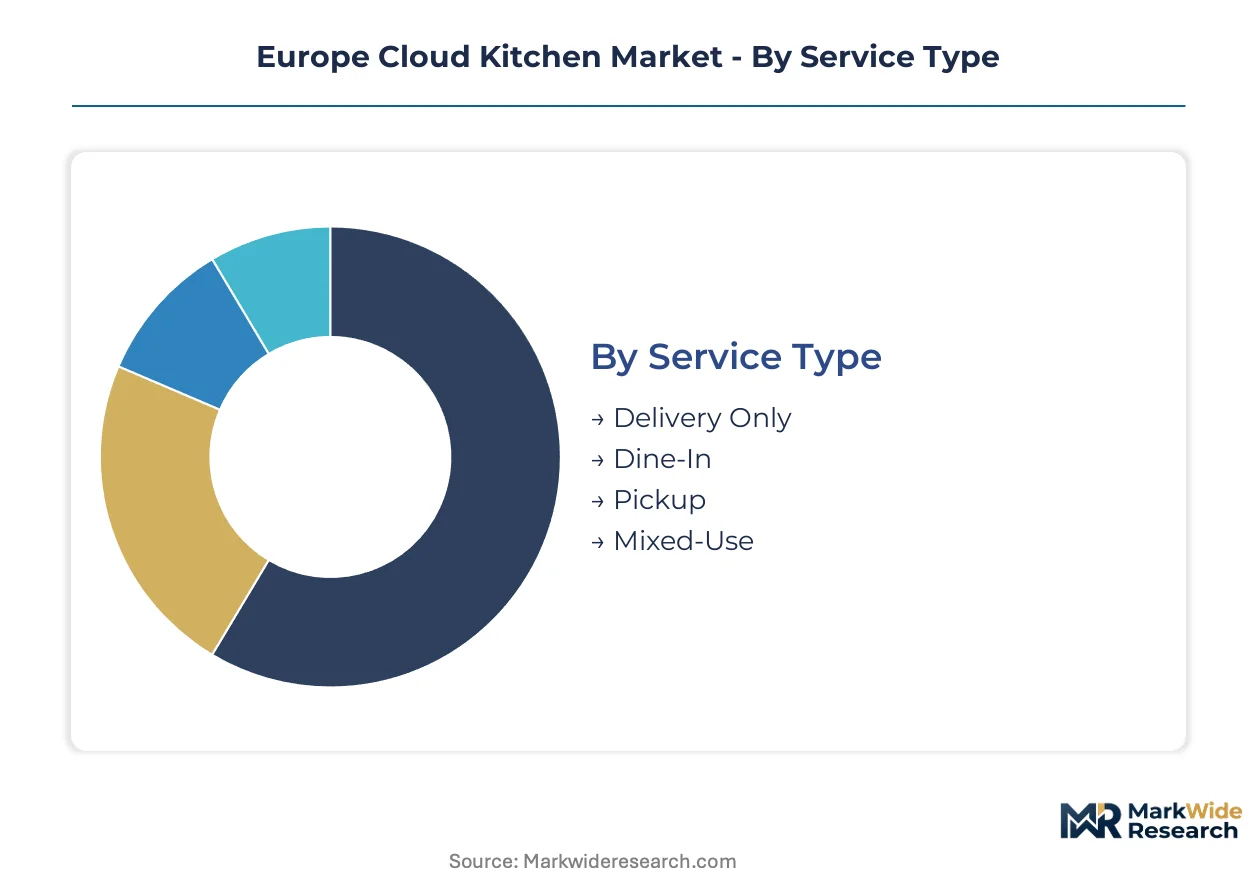
Cloud kitchen segmentation in Europe reveals divergent scaling economics across service configurations and technology stacks. Facility operators align capital deployment with urban density patterns and regulatory compliance burdens in Germany, France, and the United Kingdom.
Service Type:
Delivery Only dominates facility deployment across Paris, Berlin, and London where real estate costs force decoupling from front-of-house operations; Dine-In and Pickup retain niche positions in secondary cities with lower commercial rent burdens.
- Delivery Only:Facilities operate without customer-facing dining areas, requiring commercial-grade ventilation systems and order aggregation software to synchronize output with third-party delivery platforms. Demand concentrates in German, French, and British urban cores where digital food ordering penetration creates favorable unit economics for rapid geographic scaling.
- Dine-In:Hybrid facilities maintain limited seating capacity alongside delivery-optimized production lines, typically occupying converted restaurant spaces in gentrifying districts. Operators face higher compliance burdens under national food safety frameworks enforced by EFSA-aligned agencies across member states.
- Pickup:Customer-facing collection points reduce last-mile delivery costs while retaining centralized production efficiency. This model spreads fixed real estate costs across multiple revenue streams in mid-density European cities.
- Mixed-Use:Facilities combine delivery, pickup, and limited on-premise consumption in adaptive kitchen designs. The configuration requires flexible zoning approvals that compress launch timelines in competitive urban markets.
Delivery Only holds the largest share; momentum sits with Mixed-Use as operators seek revenue diversification under third-platform commission pressure.
Business Model:
Capital efficiency separates venture-backed shared-space entrants from integrated chains controlling back-of-house operations; franchise models face regulatory fragmentation across EU member states.
- Franchise:Brand licensors delegate facility operations to regional partners, accelerating footprint expansion without direct capital deployment. EFSA-aligned national food safety frameworks create operational complexity in standardizing compliance protocols across borders.
- Multi-Brand:Single facilities house rotating brand portfolios under unified kitchen infrastructure, maximizing equipment utilization rates through demand aggregation. This model captures disproportionate interest from operators seeking capital efficiency in high-rent London, Paris, and Berlin locations.
- Shared Space:Venture-backed entrants spread fixed costs across independent restaurant operators and enterprise foodservice buyers. The model concentrates in United Kingdom urban markets where facility density has matured fastest.
- Virtual Brand:Delivery-only concepts operate without physical restaurant presence, leveraging existing cloud kitchen infrastructure for rapid market testing. GDPR constraints on consumer data handling influence how these brands architect customer analytics and retention systems.
Multi-Brand holds the largest share; Shared Space is expanding most quickly as capital efficiency priorities reshape competitive positioning.
Cuisine Type:
Menu standardization determines supply chain sourcing radius and ingredient freshness requirements across European cloud kitchen networks.
- Italian:Pasta and pizza concepts dominate facility utilization in German cities with established Mediterranean food demand. Operators source specialized equipment meeting CE Marking certification for high-temperature ovens.
- Asian:Stir-fry and noodle operations require distinct ventilation configurations under F-Gas Regulation phase-down schedules. Demand concentrates in French and British urban markets with diverse ethnic food preferences.
- American:Burger and fried chicken brands leverage standardized prep workflows that maximize kitchen throughput optimization. The segment anchors enterprise foodservice buyer procurement decisions in United Kingdom facilities.
- Mexican:Burrito and taco concepts face ingredient sourcing challenges for authentic components across EU member states. REACH compliance obligations extend to specialized packaging materials used for hot-held products.
Italian holds the largest share; Asian is gaining share fastest as operators diversify beyond saturated Western quick-service categories.
Technology:
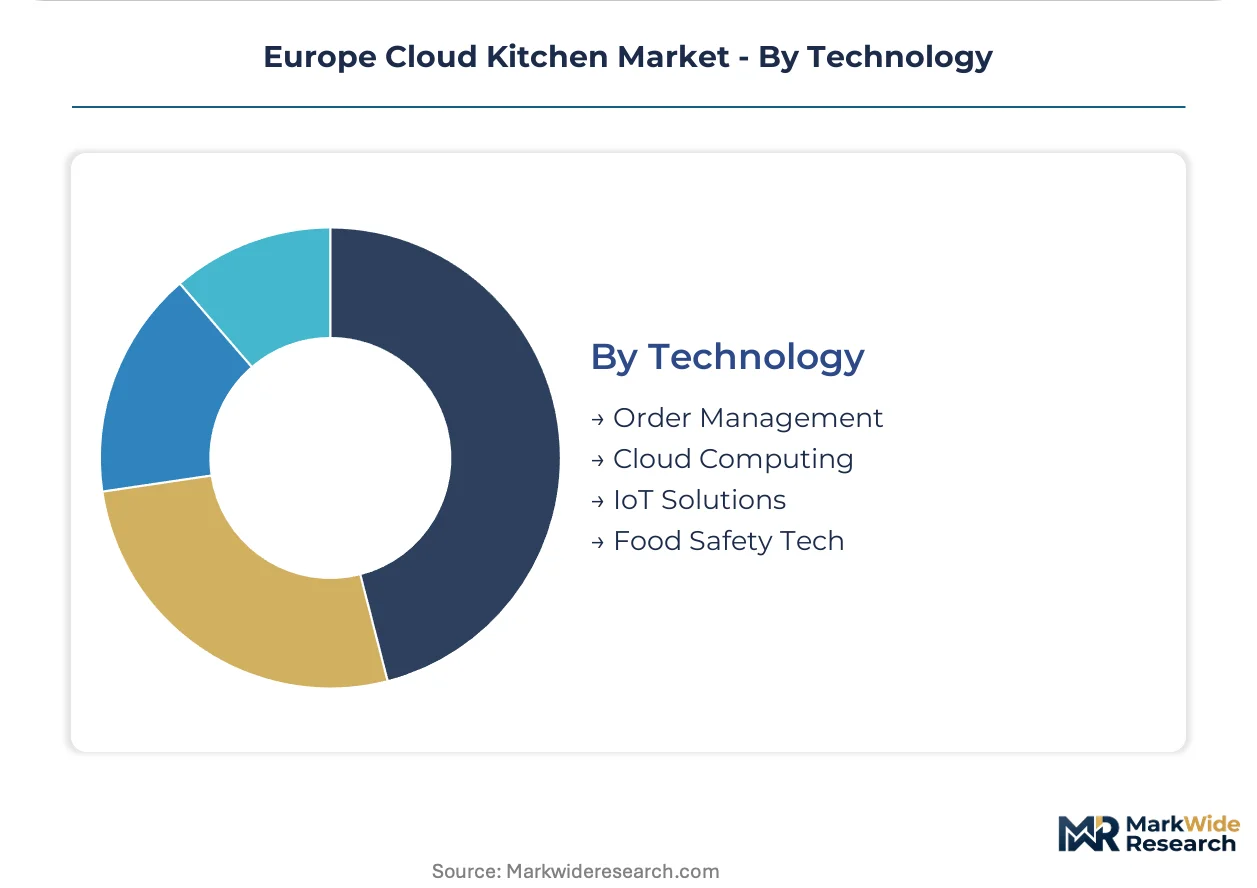
Regulatory compliance and margin preservation drive divergent investment priorities across order management, infrastructure, and food safety systems.
- Order Management:Software platforms synchronize kitchen output with third-party delivery platform order patterns, compressing food waste ratios and labor idle time. GDPR constraints influence customer analytics architecture in facilities across Germany and France.
- Cloud Computing:Scalable data infrastructure supports multi-location demand forecasting and inventory optimization. The technology enables rapid geographic scaling without proportional IT capital deployment.
- IoT Solutions:Connected sensors monitor temperature-controlled storage and equipment performance in real time. CE Marking certification requirements extend approval timelines for sensor hardware procurement.
- Food Safety Tech:Automated compliance documentation systems align with EFSA-aligned national framework variations across member states. Operators expanding facility networks face operational complexity in harmonizing cross-border protocols.
Order Management holds the largest share; Food Safety Tech shows the steepest expansion trajectory as EU Green Deal mandates accelerate equipment retrofit cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-speed rail corridors and dense last-mile delivery networks across Northern Europe compress delivery windows and enable rapid scaling of centralized food production facilities. The region's urban agglomerations concentrate demand for delivery-only kitchen operations.
Germany
Corporate catering procurement from DAX-listed companies drives enterprise demand for cloud kitchen capacity in Berlin and Munich. The F-Gas Regulation mandates heat pump retrofits in commercial refrigeration systems, accelerating equipment replacement cycles. The Rhine-Ruhr corridor hosts the densest cluster of multi-tenant facilities, with operators in Düsseldorf and Cologne optimizing kitchen throughput for quick-service restaurant chains.
United Kingdom
Digital food ordering penetration in London exceeds other European capitals, creating favorable unit economics for delivery-only operations. GDPR constraints shape how order management platforms architect customer retention systems. The Greater London Authority's planning frameworks restrict ground-floor conversions, pushing cloud kitchen development into industrial zones in Croydon and Stratford.
France
Urban density in Paris and Lyon supports shared-space business models that spread fixed costs across rotating brand portfolios. ANSM-aligned food safety frameworks enforce strict HACCP documentation requirements in centralized production environments. The Île-de-France region attracts venture-backed entrants seeking capital efficiency in high-rent metropolitan locations.
Netherlands
Rotterdam's port infrastructure enables rapid ingredient sourcing for cloud kitchen networks serving the Randstad conurbation. REACH compliance obligations extend to sustainable packaging materials used in delivery-only operations. Amsterdam's municipal zoning permits adaptive reuse of warehouse spaces, accelerating facility launch timelines relative to other European capitals.
Spain
Barcelona and Madrid exhibit growing demand for virtual brands operating without physical restaurant presence. ECHA registration requirements for cleaning agents create compliance friction for smaller independent operators. The Catalan capital hosts emerging clusters of Asian cuisine-focused facilities targeting diverse ethnic food preferences.
Europe Cloud Kitchen Market Competitive Landscape
Listed leaders compete with private specialists across capital deployment cycles and geographic expansion timelines. The vendor base separates into integrated chains controlling back-of-house operations and venture-backed shared-space entrants pursuing capital efficiency. Three archetypes dominate: multi-brand technology stacks, integrated back-of-house operators, and platform-dependent virtual brands. Competitive moves concentrate on M&A for facility networks and strategic partnerships with third-party delivery platforms.
Within the integrated operations tier, Kitopi exemplifies back-of-house control over ingredient sourcing and quality consistency at scale. Rebel Foods occupies a position representing multi-brand technology deployment across multiple European cities. Keatz anchors the venture-backed shared-space model, spreading fixed costs across independent restaurant operators in high-density urban locations.
| Leading Market Players |
|---|
| Rebel Foods |
| Kitopi |
| Keatz |
| Kitchen United |
| Zuul Kitchen |
| Dahmakan |
| DoorDash Kitchen |
| CloudKitchens |
| POSist Technologies |
| Others |
Value Network & Pricing Analysis
CE Marking certification gates equipment qualification and price differentiation simultaneously across European cloud kitchen procurement. The regulatory burden compresses launch timelines while creating tiered vendor access that separates integrated chains from independent operators in negotiating leverage.
Pricing Analysis
Volume-discount tiering structures dominate equipment procurement as enterprise foodservice buyers consolidate vendor relationships around integrated back-of-house service providers. Three-tier pricing stratifies across premium CE-certified ventilation systems, standard refrigeration units, and economy-grade order aggregation software. Pricing pressure stems from third-platform commission structures that extract significant revenue share from facility operators. Independent restaurant operators exhibit highest price sensitivity as they lose negotiating leverage against large chains capturing volume-based equipment pricing.
Supply Chain Analysis
Germany and France anchor commercial-grade kitchen equipment manufacturing for ventilation and refrigeration systems serving European cloud kitchen networks. Italy produces specialized high-temperature oven components for pizza and pasta concepts. Raw material dependencies include stainless steel for food-grade surfaces, refrigerants meeting F-Gas Regulation phase-down requirements, and semiconductor chips for IoT-enabled temperature sensors. Single-source vulnerability concentrates in heat pump refrigeration technology where few suppliers meet EU Green Deal mandates. Distribution runs through industrial equipment distributors and direct OEM relationships with facility operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent cloud kitchen operators must defend against ghost kitchen substitution from retail and convenience store prepared food expansion. The substitute threat intensifies as grocers and petrol stations deploy delivery-optimized hot food counters with lower real estate overhead.
For Market Incumbents: Compound kitchen utilization rates through multi-brand technology stacks that sustain high equipment turnover across rotating concepts. Defend margin position by capturing backward integration into ingredient sourcing and quality consistency at scale. Prioritize F-Gas Regulation compliance investment ahead of 2025-2030 retrofit deadlines to avoid operational disruption.
For New Entrants and Emerging Players: Anchor in secondary European cities with lower commercial rent burdens where facility density remains underdeveloped. Target mixed-use service configurations that spread fixed real estate costs across delivery, pickup, and limited on-premise consumption. Pursue GDPR-compliant customer analytics as a go-to-market differentiator against platform-dependent rivals.
For Investors and Strategic Acquirers: EU Green Deal implementation timelines reshape the acquisition landscape toward operators with certified sustainable equipment portfolios. Long-term viability favors integrated back-of-house specialists controlling supply chain variability across multiple European cities. Watch F-Gas Regulation enforcement intensity as the signal indicating which facility networks face disproportionate capital burdens versus compliance-ready targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Brand Technology Stack Deployment | Rebel Foods sustains high kitchen utilization rates across Berlin, Paris, and London facilities. |
| Back-of-House Integration Control | Kitopi captures ingredient sourcing consistency at scale across European city networks. |
| Shared-Space Capital Efficiency Model | Keatz spreads fixed costs across independent operators in high-density United Kingdom urban markets. |
| GDPR-Compliant Customer Analytics Architecture | Order management platforms differentiate retention systems against delivery platform dependency. |
| F-Gas Regulation Heat Pump Retrofit | French and German operators face steepest equipment replacement obligations under national timelines. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU regulatory filings, EFSA-aligned national food safety frameworks, and commercial real estate transaction databases. Primary interviews engaged cloud kitchen facility operators, enterprise foodservice procurement directors, commercial kitchen equipment manufacturers, and third-party delivery platform partnership leads. Secondary validation drew from REACH registration databases, CE Marking certification records, and urban planning authority zoning disclosures. Bottom-up facility deployment counts triangulate against top-down market sizing from digital food ordering penetration metrics.
Segmentation dimensions modeled include service type configuration, business model archetype, cuisine category standardization, and technology stack composition across the projection horizon. CAGRs derive from regression analysis of facility rollout velocity against urban density and rent cost variables. Industry-specific forecast inputs incorporate F-Gas Regulation phase-down schedules and GDPR enforcement patterns affecting customer data monetization.
Decision-makers should treat outputs as directional under assumptions of sustained urban commercial rent escalation and stable third-platform commission structures; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Supermarkets Market
Food Service
Beverage Vending Machine Market
Food Service
Mexico Foodservice Market
Food Service
Gas Floor Fryers Market
Food Service
Tabletop Pizza Oven Market
Food Service
Global Delivery Takeaway Food Market
Food Service
Global Meal Kit Market
Food Service
Asia-Pacific Halal Food and Beverage Market
Food Service
Europe Smokeless Indoor Grills Market
Food Service
Ice Cream Carts Market
Food Service
Commercial Restaurant Rangers Market
Food Service
Onboard Rail Catering Market
Food Service
Chile Food Delivery Market
Food Service
Global Food Platform-To-Consumer Delivery Market
Food Service
Australia Foodservice Market
Food Service
Europe Food Away from Home Market