
 Canada Food Service Market | 2026-2036
Canada Food Service Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Food Service Market Insights
Ontario's commercial kitchen capacity build-out is narrowing the supply gap for franchise expansion in the Greater Toronto Area. McDonald's Corporation leverages its real estate footprint to sustain drive-through throughput across suburban corridors. Tim Hortons anchors morning-daypart loyalty through beverage-centric menu architecture. RECIPE Unlimited Corporation competes via multi-brand portfolio density in mid-scale casual dining.
Canada food service denotes prepared-meal commerce through commercial establishments operating licensed kitchens, governed by provincial health codes and HACCP temperature-control protocols. The sector exists to deliver ready-to-consume food and beverage solutions outside domestic preparation environments. Quick service operations command the largest revenue pool due to labor-efficiency and speed-of-service economics. Full service segments retain higher per-check margins but face slower table-turn velocity. Menu type differentiation around vegan and gluten-free offerings is capturing dietary-restriction demand as product development cycles accelerate.
Health Canada sets national nutrition labeling standards while the Canadian Food Inspection Agency enforces Safe Food for Canadians Regulations across interprovincial supply chains. Provincial liquor boards and municipal zoning authorities further constrain site selection and operating-hour flexibility for operators. Franchise disclosure law under provincial securities regulators adds compliance layers for multi-unit expansion strategies. Stakeholders must monitor evolving plastic-waste reduction mandates and minimum-wage escalations as these forces reshape unit-level profitability thresholds.
Market Dynamics
Health Canada and the Canadian Food Inspection Agency are tightening enforcement of Safe Food for Canadians Regulations, forcing operators to reconfigure kitchen workflows and temperature-monitoring infrastructure to avoid penalties and supply chain suspensions.
Growth Catalysts
- Provincial Minimum-Wage Escalations:Ontario and British Columbia wage floors are accelerating automation investment in back-of-house operations as labor costs compress margins.
- Interprovincial Supply Chain Integration:CFIA harmonized inspection protocols are reducing cross-border friction for central commissaries serving multiple provinces from single production nodes.
- Urban Density Concentration:Toronto and Vancouver metropolitan growth is concentrating addressable demand within delivery-radius economics for ghost kitchen operators.
Market Restraints
- Protein Input Volatility:Beef and poultry commodity swings are destabilizing menu pricing power for full-service operators locked into quarterly contract structures.
- Real Estate Supply Bottleneck:Municipal zoning boards in the Greater Toronto Area are restricting 24-hour operating permits for drive-through formats in residential-adjacent corridors.
- Substitution Threat from Meal Kits:Grocery-retailer prepared-meal sections are capturing occasion-based demand previously flowing to quick-service dinner dayparts.
Strategic Opportunities
- Atlantic Canada Expansion:Halifax and Moncton metro areas show underpenetrated quick-service density relative to comparable US secondary markets.
- Provincial Liquor Board Modernization:Ontario's Alcohol and Gaming Commission streamlined licensing timelines are enabling alcohol-forward casual dining formats previously delayed by approval backlogs.
- Cloud Kitchen Convergence:Integration of third-party delivery aggregation with centralized production facilities is collapsing last-mile costs for suburban corridor penetration.
Industry Challenges
- Certified Food Handler Scarcity:Provincial health authority training backlogs are delaying new unit openings as operators cannot staff HACCP-compliant kitchen supervision.
- Legacy POS Integration Friction:Franchise systems running on decade-old point-of-sale infrastructure face middleware complexity when connecting to modern delivery platform APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Food Service Market |
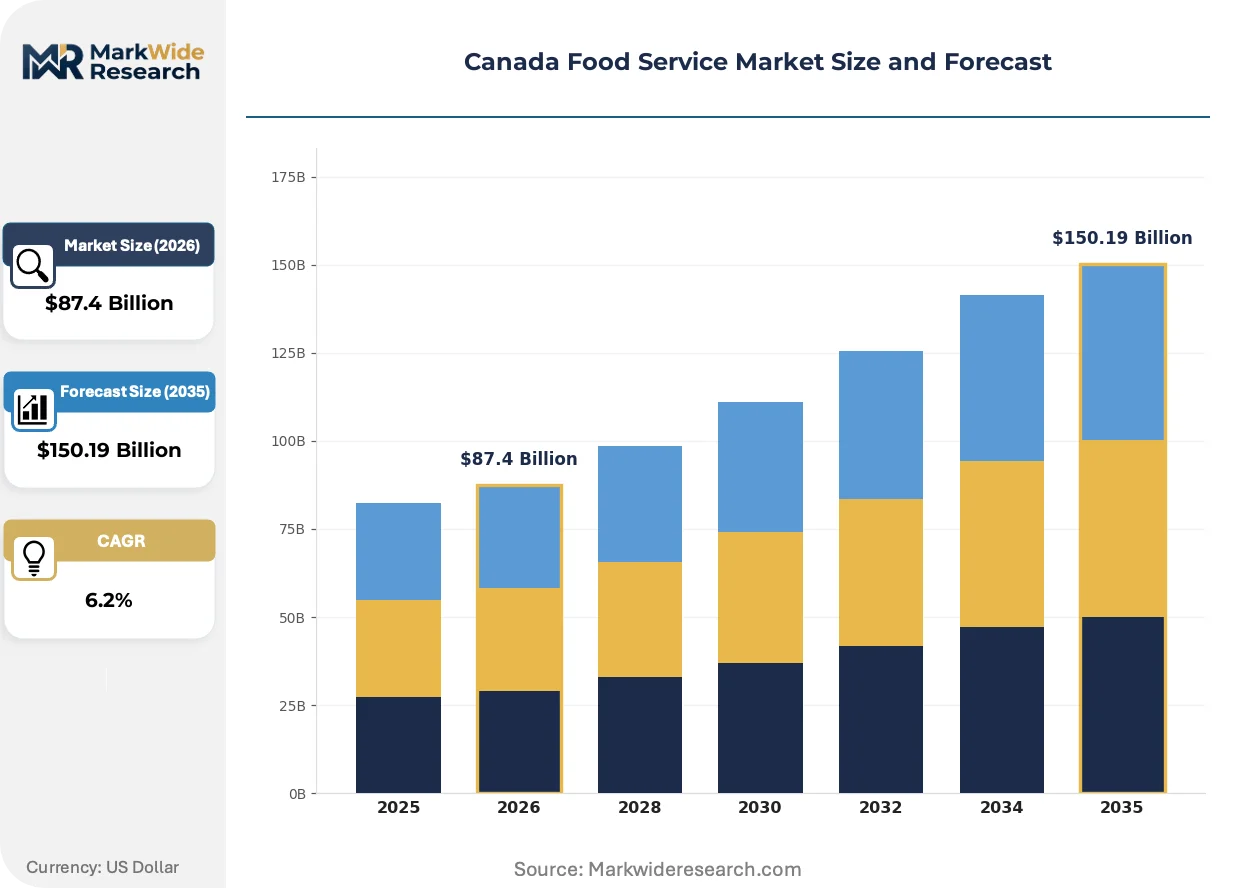
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $150.19 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Quick Service, Full Service, Cafeteria, Catering Customer Type: Millennials, Families, Business Professionals, Students End Use: Restaurants, Food Trucks, Delis, Cafes Menu Type: Vegetarian, Vegan, Gluten-Free, Organic |
| Companies Covered | McDonald's Corporation, Tim Hortons Inc., Yum! Brands Inc., RECIPE Unlimited Corporation, Compass Group PLC, Aramark Corporation, Sodexo, Inspire Brands Inc., Doctor's Associates, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Food Service Market Trends and Innovations
Kitchen automation and digital ordering infrastructure are compressing labor dependency while regulatory pressure on food safety documentation is elevating traceability technology adoption across Canadian provinces.
Kitchen display systems integrated with predictive prep algorithms are virtualizing traditional expediter roles in high-volume quick-service environments. Chains operating above 500 transactions daily are deploying these systems to synchronize fryer and grill output with real-time order velocity. This virtualization is compressing labor hours per transaction while reducing ticket-time variance during peak dayparts.
Health Canada's updated nutrition labeling regulations for pre-packaged restaurant items are mandating sodium and saturated fat disclosure on menu boards for chains exceeding 20 locations. The industrial consequence is reformulation pressure on legacy recipes that built brand identity around flavor profiles now classified as high-risk. Quick-service burger and pizza segments are responding fastest, deploying R&D resources to sodium-reduction trials without sacrificing craveability metrics.
Third-party delivery platform dependence has concentrated buyer power in the hands of DoorDash and Uber Eats, forcing operators to absorb commission structures that erode unit-level contribution margins. Independent full-service restaurants in Vancouver and Montreal are responding by building proprietary ordering apps and subscription loyalty programs to reclaim direct customer relationships. This channel disintermediation is most visible in mid-scale casual dining where check averages support the technology investment required for platform independence.
Canada Food Service Market Segmentation
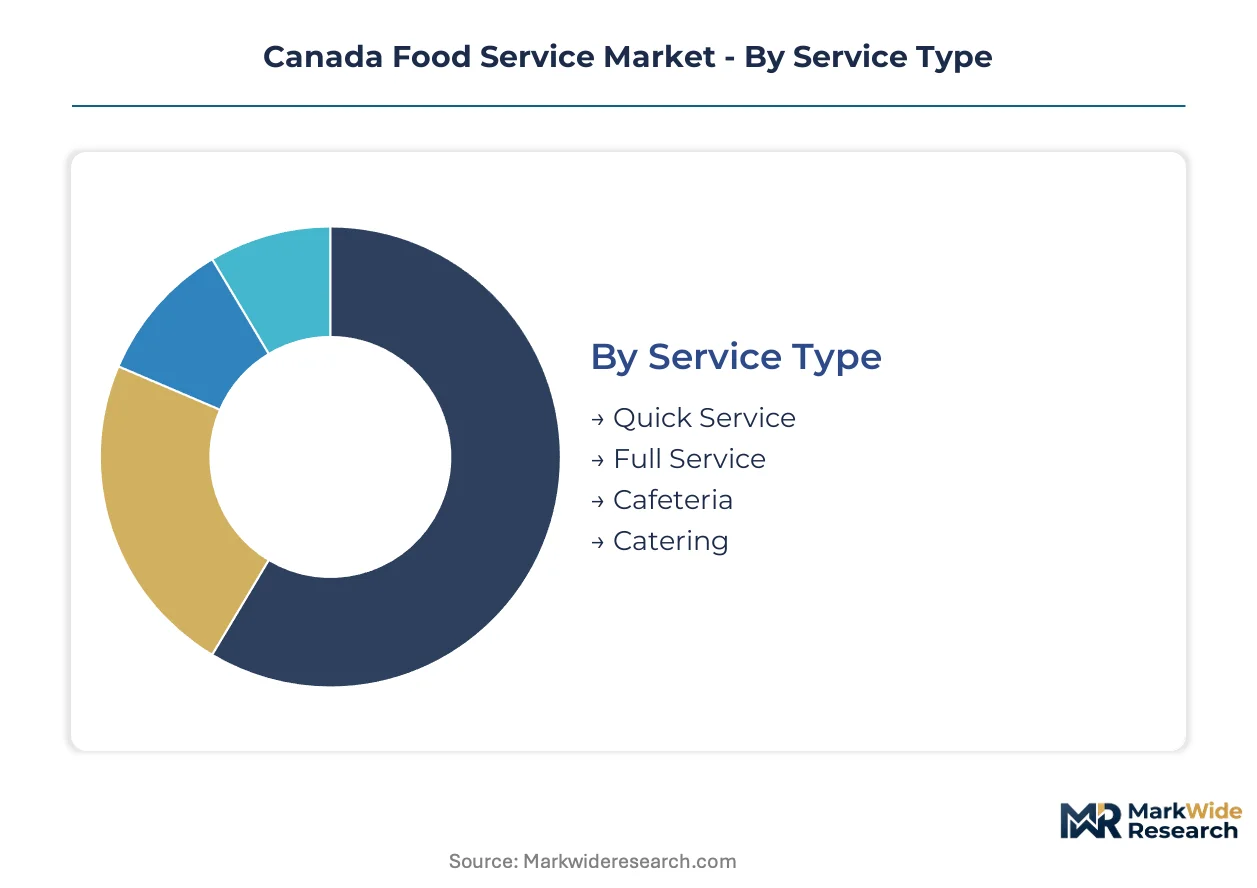
Segmentation in the Canada food service market reveals how distinct operational models and consumer cohorts allocate spending across provinces. Understanding these divides helps operators calibrate kitchen infrastructure, labor deployment, and site selection to match demand density.
Service Type:
Mature formats dominate transaction volume while emerging models reshape capital deployment patterns across Canadian metros.
- Quick Service:Drive-through and counter-service formats optimized for sub-three-minute ticket times. Ontario and British Columbia corridors concentrate demand as suburban commuters prioritize speed over experience during compressed lunch windows.
- Full Service:Table-service operations with segmented front-of-house labor and extended meal duration. Vancouver and Toronto entertainment districts sustain check averages sufficient to cover higher labor intensity, though table-turn velocity limits peak-hour capacity.
- Cafeteria:Self-serve formats with tray-line assembly and limited customization. University campuses and hospital complexes in Quebec and Alberta anchor steady traffic with contracted meal-plan commitments.
- Catering:Off-premise production for events and corporate functions. Seasonal demand spikes in wedding corridors of Niagara and Okanagan Valley strain cold-chain logistics during summer peak months.
Quick Service retains volume leadership; Catering holds the steepest expansion curve as event-format hybridization accelerates post-pandemic.
Customer Type:
Demographic concentration patterns vary by daypart and geography, shaping menu architecture and promotional timing.
- Millennials:Digital-native cohort prioritizing mobile ordering and experiential dining. Toronto's downtown core and Montreal's Plateau district show dense clustering of this segment during evening and weekend dayparts.
- Families:Multi-generational units seeking value bundles and child-accommodating environments. Suburban power centers in Calgary and Ottawa generate concentrated weekend traffic for mid-scale casual formats.
- Business Professionals:Expense-account diners with compressed meal windows. Vancouver's Coal Harbour and Toronto's Financial District sustain premium quick-service and fast-casual density during weekday lunch hours.
- Students:Price-sensitive cohort with irregular meal timing and high delivery-platform usage. University towns including Waterloo, Kingston, and Halifax exhibit elevated third-party delivery penetration relative to household income levels.
Business Professionals anchor weekday revenue concentration; Students are expanding most quickly as ghost kitchen formats penetrate campus-adjacent corridors.
End Use:
Physical format selection determines regulatory exposure and capital intensity thresholds for market entry.
- Restaurants:Fixed-location establishments with permanent kitchen infrastructure and municipal occupancy permits. Health Canada and provincial health authority inspection regimes impose standardized HACCP documentation requirements across all provinces.
- Food Trucks:Mobile units operating under municipal vendor permits with commissary kitchen dependencies. Vancouver and Toronto have streamlined licensing pathways, while smaller municipalities maintain restrictive proximity buffers from brick-and-mortar competitors.
- Delis:Counter-service formats emphasizing prepared-meal retail and grab-and-go protein offerings. Montreal's smoked-meat heritage and Toronto's Italian-Canadian enclaves sustain differentiated competitive positioning.
- Cafes:Beverage-forward operations with limited hot-food preparation. British Columbia's independent coffee culture and Ontario's franchise-dominated morning dayparts represent divergent maturity profiles within this segment.
Restaurants maintain installed-base dominance; Food Trucks are gaining share fastest as municipal permitting modernizes across secondary Canadian cities.
Menu Type:
Dietary restriction accommodation has shifted from niche positioning to baseline operational requirement.
- Vegetarian:Plant-forward formulations excluding meat proteins while retaining dairy and egg inputs. Toronto's diverse immigrant corridors generate sustained demand for South Asian and Mediterranean vegetarian traditions.
- Vegan:Exclusion of all animal-derived ingredients requiring reformulation of binding agents and flavor bases. Vancouver and Victoria show North American-leading per-capita vegan menu penetration.
- Gluten-Free:Celiac-safe preparation protocols with segregated equipment and ingredient sourcing. CFIA allergen labeling mandates have elevated kitchen compliance costs for operators serving this segment.
- Organic:Certification-dependent sourcing from CFIA-accredited organic producers. Supply chain constraints in Atlantic Canada limit menu penetration relative to Pacific and Central Canadian markets.
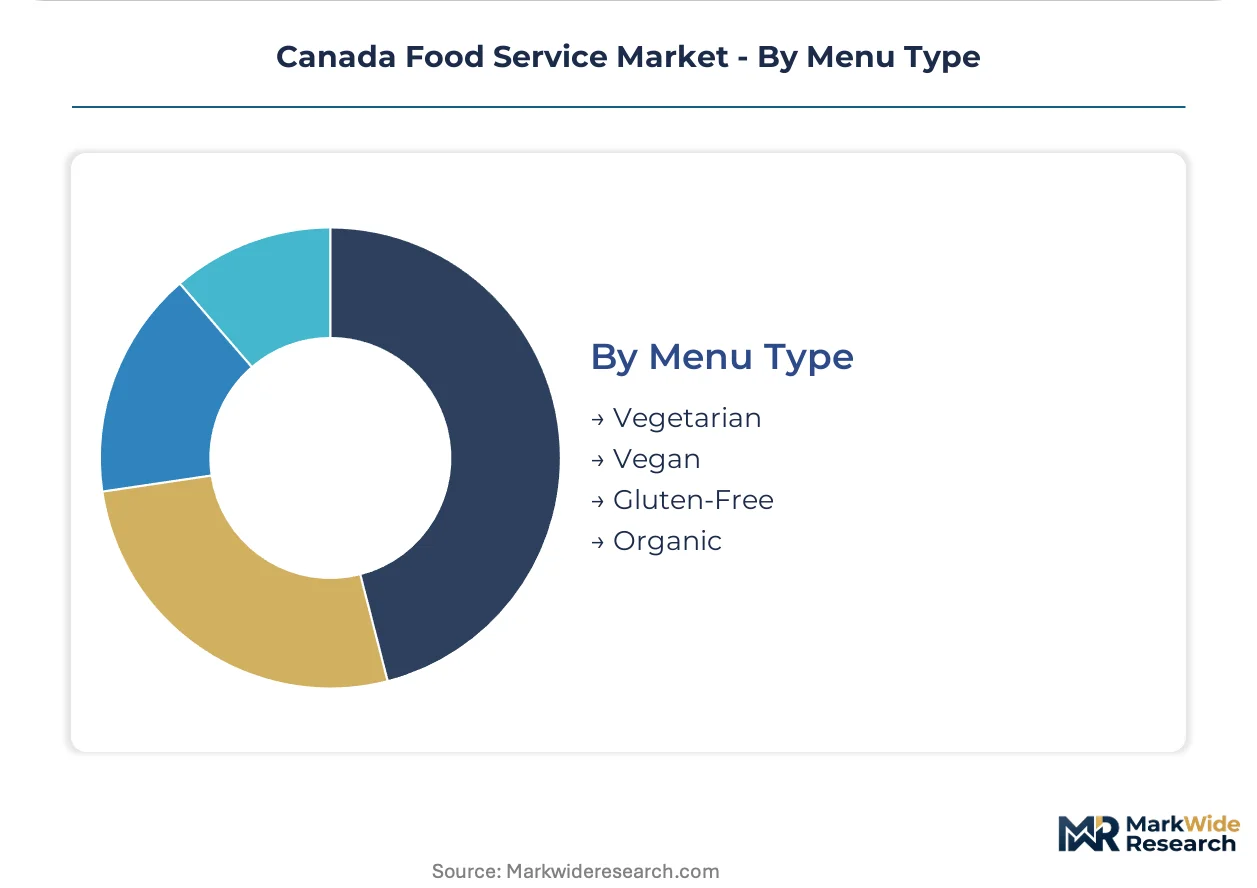
Vegetarian offerings command the broadest addressable base; Vegan options show the steepest trajectory as ingredient technology closes sensory gaps with conventional preparations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health Canada anchors national food safety governance while provincial authorities drive localized operational constraints across Canadian food service corridors.
Ontario
Greater Toronto Area commuter density and suburban power-center expansion sustain quick-service transaction volumes. The Alcohol and Gaming Commission of Ontario streamlined liquor licensing timelines for alcohol-forward casual formats. Toronto's downtown core and Mississauga corridor concentrate ghost kitchen infrastructure as delivery-radius economics tighten.
Quebec
Montreal's entertainment districts and Plateau neighborhood sustain experiential dining demand among digital-native cohorts. The Régie des alcools, des courses et des jeux enforces province-specific beverage service protocols. Laval and Longueuil submarkets show underpenetrated quick-service density relative to comparable Ontario secondary metros.
British Columbia
Vancouver metropolitan growth and Victoria's independent coffee culture anchor divergent format maturity profiles. WorkSafeBC and Vancouver Coastal Health coordinate kitchen safety enforcement with municipal zoning boards. The Coal Harbour financial district and Yaletown corridor concentrate premium quick-service and fast-casual density during weekday lunch windows.
Alberta
Calgary suburban power centers and Edmonton university-adjacent corridors generate concentrated weekend traffic for family-oriented formats. Alberta Health Services provincial inspection regimes impose standardized HACCP documentation requirements. The Calgary-Edmonton corridor sustains mid-scale casual dining portfolio density as energy-sector employment stabilizes.
Atlantic Canada
Halifax and Moncton metro areas exhibit quick-service penetration gaps relative to comparable US secondary markets. Provincial health authorities in Nova Scotia and New Brunswick maintain training backlogs that delay new unit openings. Halifax's waterfront tourism flows and university-town corridors in Fredericton show elevated third-party delivery penetration relative to household income levels.
Canada Food Service Market Competitive Landscape
Capability concentration sits with real estate-heavy legacy chains; scale advantage sits with multi-brand portfolio operators and contract foodservice conglomerates. The market structures around three tiers: quick-service volume leaders, full-service portfolio aggregators, and institutional contract caterers. Dominant competitive moves include multi-brand portfolio diversification and drive-through format real estate capture.
Within the quick-service tier, McDonald's Corporation and Tim Hortons Inc. exemplify divergent daypart anchoring strategies. Among portfolio aggregators, RECIPE Unlimited Corporation occupies a position representing multi-brand density in mid-scale casual dining. Compass Group PLC and Aramark Corporation anchor the institutional contract segment, serving education and healthcare complexes under long-term service agreements.
| Leading Market Players |
|---|
| McDonald's Corporation |
| Tim Hortons Inc. |
| Yum! Brands Inc. |
| RECIPE Unlimited Corporation |
| Compass Group PLC |
| Aramark Corporation |
| Sodexo |
| Inspire Brands Inc. |
| Doctor's Associates, Inc. |
| Others |
Pricing and Supply Chain Analysis
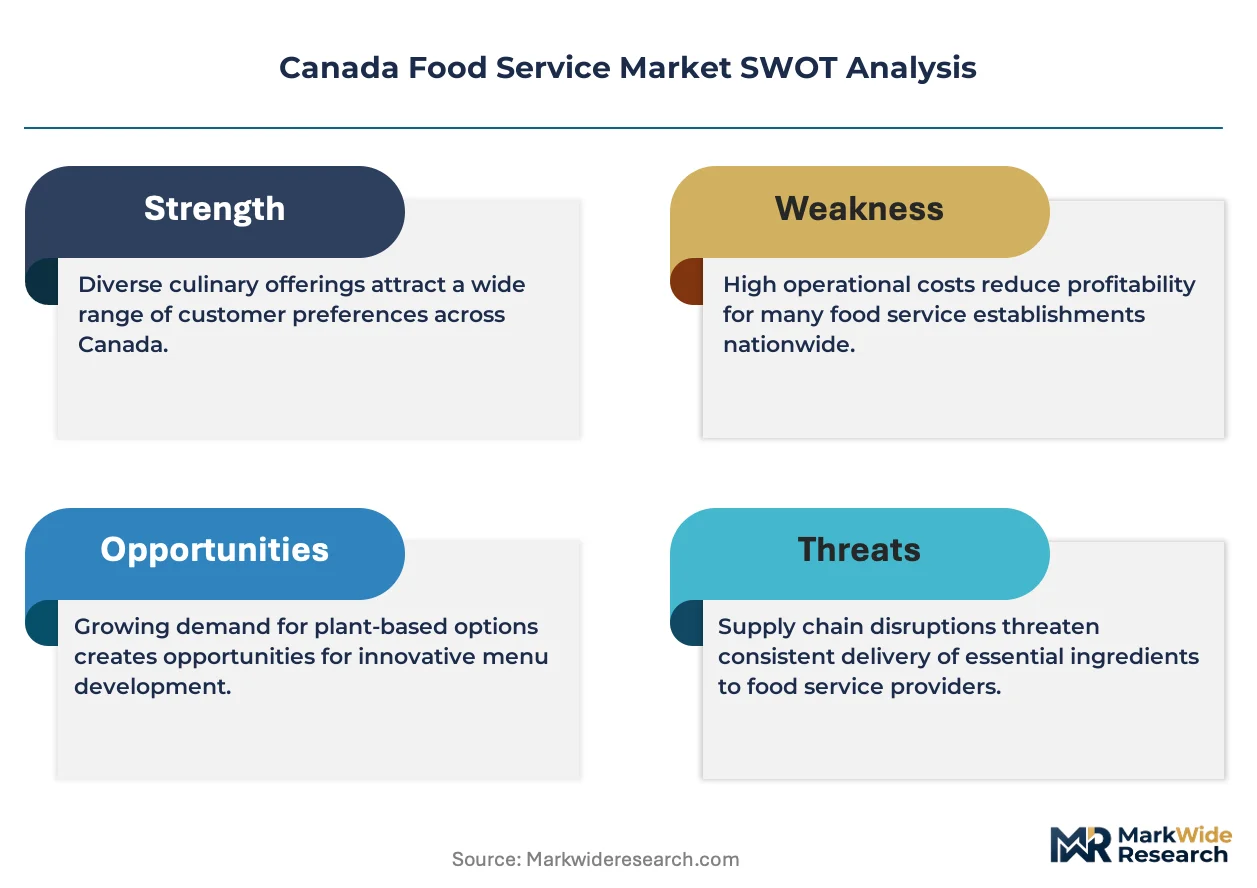
Beef and poultry commodity volatility compresses menu pricing power for full-service operators locked into quarterly contract structures, widening spreads between premium farm-to-table formats and economy quick-service tiers while forcing supply chain reconfiguration toward frozen-protein hedging and alternative-protein trials.
Pricing Analysis
Ontario and British Columbia corridors command 15-20% check premiums over Atlantic Canada markets due to urban density and tourism concentration. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by local sourcing certification and speed-of-service infrastructure. Pricing pressure stems from provincial minimum-wage escalations accelerating automation investment. Students and price-sensitive suburban families exhibit highest price sensitivity; business professionals in Toronto's Financial District show lowest.
Supply Chain Analysis
CFIA enforcement of Safe Food for Canadians Regulations acts as a domestic export-control equivalent, limiting interprovincial flow flexibility for non-compliant operators. Protein inputs draw from Alberta beef corridors, Manitoba poultry processing, and US Midwest feedlot networks. Supply chain risk centers on single-source vulnerability for certified organic produce serving Vancouver and Toronto premium segments. Distribution runs through centralized commissary networks serving multi-unit franchise systems, with ghost kitchen operators bypassing traditional foodservice distribution entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified food handler scarcity constrains new unit velocity across Canadian provinces, creating a bottleneck where operators with established training pipelines capture disproportionate expansion capacity relative to capital availability.
For Market Incumbents: Build real estate moats through drive-through format capture in Greater Toronto Area suburban corridors before municipal zoning restrictions tighten. Defend against meal-kit substitution by embedding subscription loyalty programs with direct ordering apps. Deepen backward integration into commissary production to compress protein input volatility exposure. For New Entrants and Emerging Players: Halifax and Moncton metro underpenetration offers white-space entry with lower competitive density than comparable US secondary markets. Target university-adjacent ghost kitchen formats in Waterloo and Kingston where delivery-platform dependence has not yet cemented incumbent loyalty. Launch with alcohol-forward casual dining concepts leveraging Ontario's streamlined AGCO licensing timelines. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors multi-brand portfolio operators with proven compliance infrastructure over single-concept growth stories. Long-term viability hinges on automation capex deployment and regulatory adaptation capacity. Target acquisition archetype: regional mid-scale casual chains with underutilized real estate footprints. Watch provincial minimum-wage acceleration schedules as inflection indicator for automation adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Kitchen Automation Deployment | Reduces labor hours per transaction as Ontario and BC wage floors escalate. |
| Direct Ordering Platform Launch | Reclaims customer relationships from DoorDash and Uber Eats commission structures. |
| Commissary Network Expansion | CFIA harmonized protocols enable single-node production serving multiple provinces. |
| Certified Food Handler Pipeline | Accelerates new unit openings delayed by provincial health authority training backlogs. |
| Alcohol Licensing Streamlining | AGCO modernization enables alcohol-forward formats previously stalled by approval delays. |
Research Methodology
A spread of perspectives from quick-service franchise operations directors, provincial health authority inspectors, third-party delivery platform account managers, and commercial real estate brokers converged on the working assumptions underlying this study. Primary fieldwork combined structured interviews with secondary validation through Health Canada nutrition labeling databases, CFIA enforcement bulletins, provincial liquor board licensing disclosures, and municipal zoning records. Bottom-up unit economics modeling triangulated against top-down provincial expenditure data.
Demand-supply balance framing anchored the analytical approach across the analysis window. Segmentation dimensions modeled include service type, customer demographic cohort, end-use format, and menu restriction category. CAGRs derived from trend extrapolation with cross-validation against historical provincial foodservice expenditure patterns. Forecast inputs incorporated minimum-wage escalation schedules and automation adoption curves specific to Canadian labor market conditions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by US-based cloud kitchen operators or grocery-retailer prepared-meal divisions would shift outcomes. Material shifts in CFIA enforcement intensity or interprovincial trade barrier reintroduction would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Commercial Ice Dispenser Market
Food Service
Food Trays Market
Food Service
Personal Chef Services Market
Food Service
Contract Blending Services Market
Food Service
Europe Smokeless Indoor Grills Market
Food Service
Europe Online Grocery Delivery Market
Food Service
United Kingdom Cafes & Bars Market
Food Service
Global Food Platform-To-Consumer Delivery Market
Food Service
Saudi Arabia Out of Home (OOH) Delivery Market
Food Service
Food Truck Services Market
Food Service
Pizza Oven Market
Food Service
Global Meal Kit Market
Food Service
GCC Food Service Market
Food Service
Europe Vending Machine Market
Food Service
Nigeria Food Service Market
Food Service
United Kingdom Full Service Restaurants Market