
 Oman Food Service Market | 2026-2036
Oman Food Service Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Food Service Market Insights
Market Dynamics
The divergence between premium experiential dining and commodity quick-service tiers is repositioning capital allocation across Oman's food service landscape. Americana Restaurants International PLC leverages its multi-brand portfolio to dominate fast-casual formats in Muscat's retail corridors. Jawad Business Group anchors its position through backward integration into bakery and dairy supply chains that sustain cost discipline. LuLu Group International competes aggressively on catering scale, extending its hypermarket infrastructure into institutional food contracts across northern governorates.
Segment Architecture
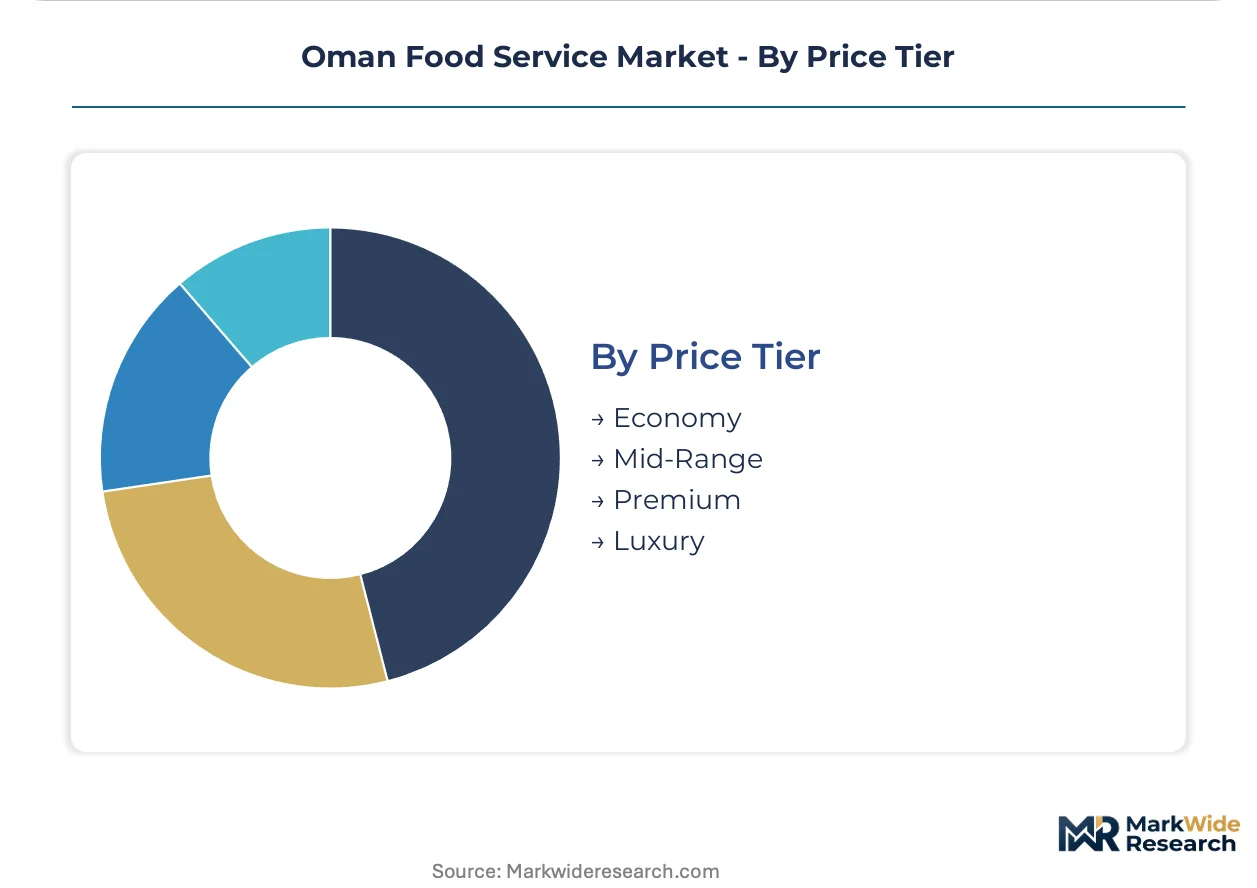
Food service encompasses the commercial preparation, assembly, and delivery of prepared meals and beverages through organized outlets ranging from full-service restaurants with table-side cooking to centralized catering kitchens serving banquets. Full-service restaurants occupy the deepest margin pools in Muscat and Salalah, where business entertainment and family celebrations sustain higher per-cover spending. Fast food and catering services represent the fastest-growing service types, driven by corporate office expansion under Oman's economic diversification program and hospital capacity additions in Seeb and Nizwa. The economy and mid-range price tiers currently absorb the bulk of transaction volume, though premium positioning is gaining traction among hotel operators targeting international visitors.
Regulatory Environment
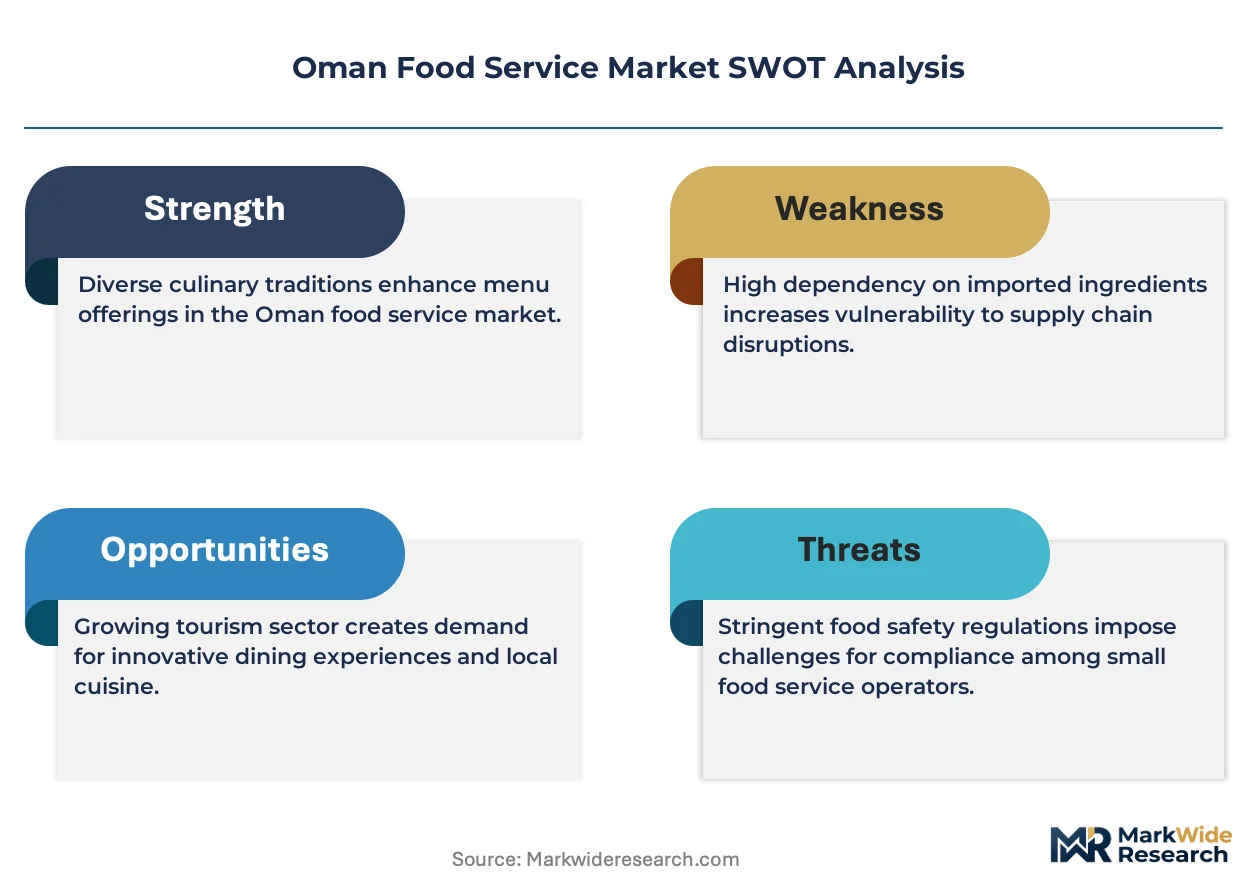
The Ministry of Commerce, Industry and Investment Promotion enforces food safety licensing and facility inspection protocols that shape market access for new entrants, while municipal authorities in Muscat and Dhofar impose additional hygiene and waste-management conditions on commercial kitchens. Compliance with these layered requirements elevates operational costs for smaller independents, creating structural advantage for organized chains with dedicated quality assurance functions. Stakeholders must monitor evolving municipal enforcement intensity and potential standardization of nutrition labeling as Oman deepens its alignment with Gulf Cooperation Council technical regulations.
Market Dynamics
Oman's hospitality sector is bifurcating around compliance capability. The Ministry of Commerce, Industry and Investment Promotion's tightened food safety licensing is compressing margins for independents while organized chains absorb certification costs as competitive moats. Capital flows toward entities with captive quality assurance infrastructure.
Growth Catalysts
- Hotel banquet expansion:Muscat and Salalah hotel operators are scaling kitchen capacity to capture international conference and wedding demand. Banquet operations now represent the fastest-growing outlet type within full-service segments.
- MOCIIP licensing harmonization:Updated hospitality sector standards are accelerating professionalization. Compliance investments by organized players are widening the performance gap against unlicensed street vendors.
- Dhofar development corridor:Salalah's port and free zone expansion is attracting labor migration. Worker canteens and institutional catering contracts are proliferating around construction and logistics hubs.
Market Restraints
- Imported protein dependency:Oman sources over 80% of red meat and poultry through Saudi and UAE re-export channels. Supply concentration exposes operators to GCC-wide price shocks and customs delays.
- Municipal hygiene layering:Muscat and Dhofar authorities impose waste-management conditions beyond national standards. Multi-jurisdictional compliance elevates facility design costs for single-location operators.
- Labor quota rigidities:The Ministry of Labor's Omanization targets restrict expatriate chef and kitchen worker visas. Talent scarcity forces wage premiums that compress full-service restaurant margins.
Strategic Opportunities
- Al Batinah coastal corridor:Sohar and Rustaq lack organized fast-casual penetration. Highway retail corridors connecting Muscat to the UAE border present greenfield site opportunities.
- Cloud kitchen infrastructure:Delivery aggregator density in Seeb and Al Khuwair is approaching saturation. Dedicated dark kitchens without dine-in overhead are capturing delivery-native demand.
- GCC technical alignment:Oman's deepening harmonization with Gulf Cooperation Council nutrition labeling standards will enable cross-border menu standardization for multi-national operators.
Industry Challenges
- Certification timeline compression:MOCIIP facility inspections now require HACCP documentation prior to license issuance. New entrants face 4-6 month delays between lease signing and operational clearance.
- Refrigeration infrastructure capex:Cold chain compliance for seafood and dairy categories demands blast chiller and temperature logging investments that strain independent capital reserves.
Report Scope
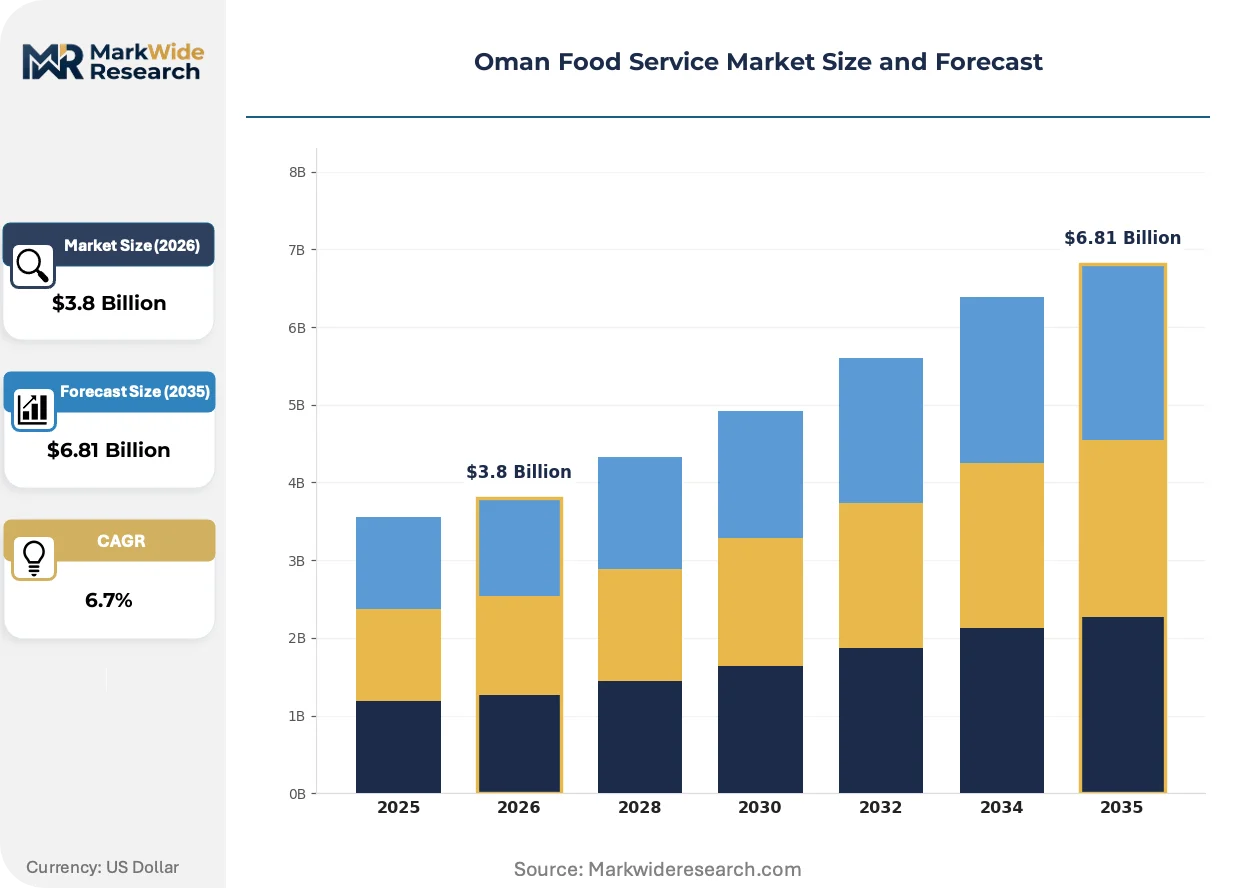
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Food Service Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Restaurants, Fast Food, Cafes, Catering Services End User: Corporate Offices, Educational Institutions, Hospitals, Hotels Product Type: Beverages, Appetizers, Main Course, Desserts Price Tier: Economy, Mid-Range, Premium, Luxury |
| Companies Covered | Al Daud Restaurants LLC, Americana Restaurants International PLC, Jawad Business Group, Khimji Ramdas, LuLu Group International, M.H. Alshaya, Apparel Group, Al Athnain, United Catering, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Food Service Market Trends and Innovations
Kitchen automation and data infrastructure are rewriting operational economics across Oman's food service landscape. Technology deployment is concentrating among organized chains with centralized procurement functions.
Automated inventory management systems are absorbing variability in perishable spoilage rates. LuLu Group International and Jawad Business Group have deployed sensor-based stock rotation across central commissaries. This technology is absorbing margin leakage that previously eroded mid-range restaurant profitability.
MOCIIP's updated hospitality sector standards now mandate digital traceability for high-risk food categories. Operators must maintain electronic supplier records accessible to municipal inspectors. Full-service restaurants in Muscat Governorate are responding by integrating procurement platforms with kitchen display systems.
Corporate procurement teams are consolidating catering contracts under annual framework agreements. Individual expense-account dining is contracting as a share of B2B food service spend. This pattern is most visible in Seeb's commercial district, where oil and gas sector clients have shifted entertainment budgets to pre-negotiated hotel banquet packages.
Oman Food Service Market Segmentation
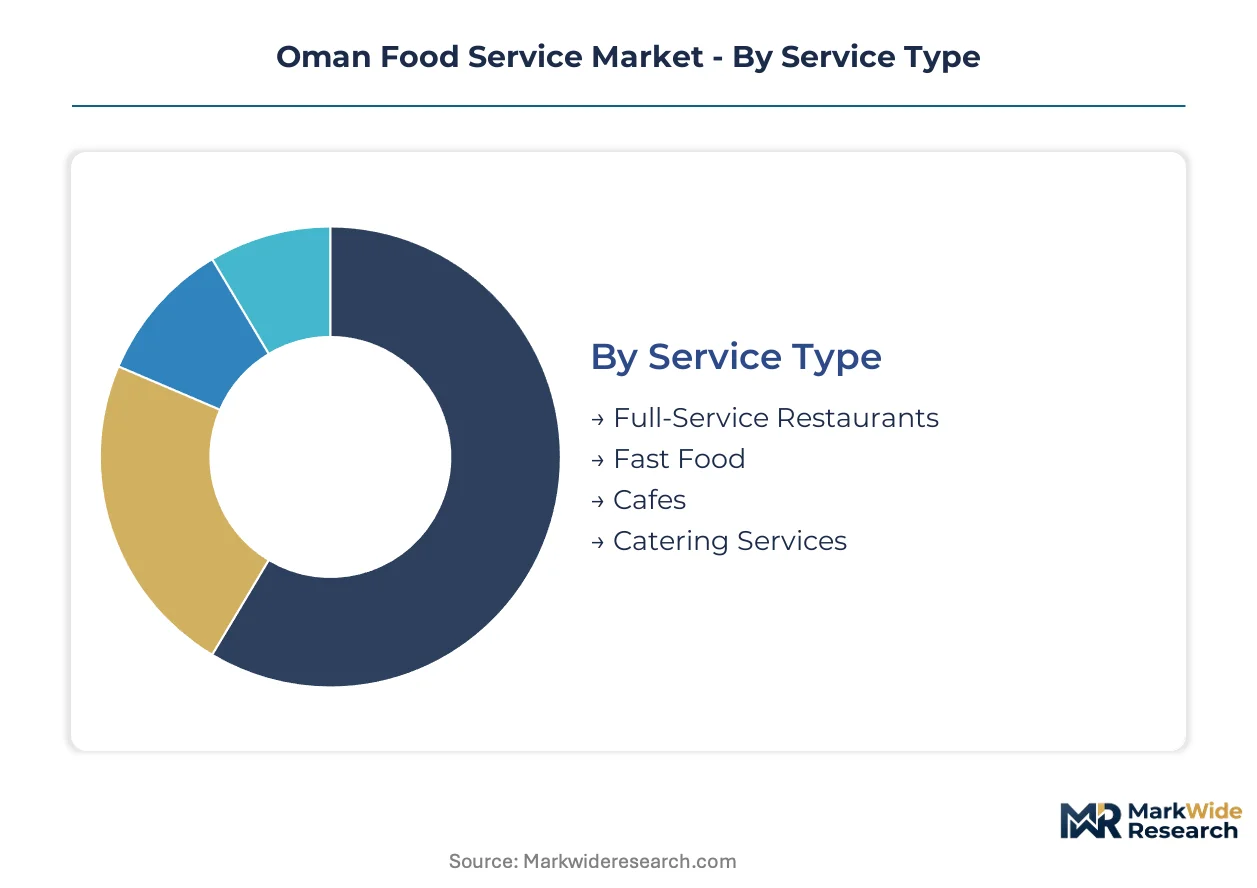
Segmentation reveals how capital and compliance burdens distribute unevenly across Oman's food service landscape. Organized chains target specific service types and price tiers where scale economies offset regulatory costs, while independents cluster in economy segments with lower facility requirements.
Service Type:
Upgrade cycles vary dramatically by service format, with kitchen equipment replacement timelines stretching from three years in fast food to eight years in full-service establishments.
- Full-Service Restaurants:Table-side preparation and banquet operations dominate revenue pools in Muscat and Salalah. Hotel operators in these cities are expanding kitchen capacity to capture international conference and wedding demand, though Omanization targets for expatriate chefs compress margins.
- Fast Food:Standardized assembly-line formats with limited menu breadth enable rapid site replication along highway retail corridors. Americana Restaurants International PLC leverages multi-brand portfolios to dominate Muscat's retail corridors where delivery aggregator density approaches saturation.
- Cafes:Beverage-forward formats with lower refrigeration capex requirements attract independent operators in Al Khuwair and Seeb commercial districts.
- Catering Services:Institutional contracts for corporate offices and hospital capacity additions in Seeb and Nizwa are proliferating around construction and logistics hubs in the Dhofar development corridor.
Fast food sits at the top of the volume ranking, with catering services climbing the fastest.
End User:
Customer procurement maturity determines contract structure, with annual framework agreements consolidating spend among sophisticated buyers.
- Corporate Offices:Oil and gas sector clients in Seeb's commercial district have shifted entertainment budgets to pre-negotiated hotel banquet packages, contracting individual expense-account dining as a share of B2B food service spend.
- Hotels:Banquet operations now absorb the fastest-growing outlet type within full-service segments as Muscat and Salalah operators scale kitchen capacity for international conference and wedding demand.
- Hospitals:Capacity additions in Seeb and Nizwa are proliferating institutional catering contracts with strict HACCP documentation requirements prior to license issuance.
- Educational Institutions:Canteen operations in Rustaq and Sohar lack organized fast-casual penetration, presenting greenfield site opportunities along highway retail corridors.
Hotels command the highest per-cover spending, with hospitals expanding most quickly on infrastructure investment.
Product Type:
Perishability gradients shape cold chain investment requirements, with seafood and dairy categories demanding blast chiller and temperature logging infrastructure.
- Main Course:Protein-centered offerings expose operators to imported red meat and poultry dependency through Saudi and UAE re-export channels, creating vulnerability to GCC-wide price shocks and customs delays.
- Beverages:Lower spoilage rates and simpler storage requirements attract independent operators with limited capital reserves, concentrating in cafe formats across Al Khuwair.
- Appetizers:Shared-plate formats dominate family celebration occasions in Muscat and Salalah where business entertainment sustains higher per-cover spending.
- Desserts:Jawad Business Group anchors position through backward integration into bakery supply chains that sustain cost discipline across central commissaries.
Main course commands the largest revenue share, with beverages gaining share fastest on format proliferation.
Price Tier:
Facility design costs stratify sharply across tiers, with premium and luxury segments absorbing compliance investments as competitive moats.
- Economy:Street vendors and unlicensed operators face widening performance gaps against organized players as MOCIIP licensing harmonization accelerates professionalization and compresses margins for independents.
- Mid-Range:Currently absorbs the bulk of transaction volume across northern governorates, with LuLu Group International competing aggressively on catering scale through hypermarket infrastructure extension.
- Premium:Hotel operators targeting international visitors are gaining traction in Muscat and Salalah, where business entertainment and family celebrations sustain higher per-cover spending.
- Luxury:Dedicated quality assurance functions and captive quality assurance infrastructure create structural advantage for organized chains with centralized procurement functions.
Economy retains the widest transaction base, with premium tiers expanding most steeply on visitor recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's food service sector outpaces Oman's in absolute scale, yet both markets share structural dependence on expatriate labor pools and GCC re-export supply chains for protein inputs.
Muscat Governorate
Hotel banquet operations and international conference demand concentrate capital deployment in the capital corridor. The Ministry of Commerce, Industry and Investment Promotion enforces tightened food safety licensing protocols that accelerate compliance investments. Seeb and Al Khuwair commercial districts absorb the densest fast-casual and cloud kitchen penetration.
Dhofar Region
Salalah's port and free zone expansion attracts labor migration, proliferating worker canteens and institutional catering contracts. Construction and logistics hubs generate demand for economy-tier meal provision. Municipal hygiene conditions exceed national standards, elevating facility design costs for new entrants.
Al Batinah Coastal Corridor
Sohar and Rustaq present greenfield opportunities where organized fast-casual penetration remains limited. Highway retail corridors connecting Muscat to the UAE border attract site development interest. Educational institution canteen operations lack structured supply chain integration.
Ad Dakhiliyah Governorate
Nizwa's hospital capacity additions drive institutional catering contract proliferation with strict HACCP documentation requirements. The region's commercial dining scene concentrates around family celebration venues. Smaller independents face margin compression from refrigeration infrastructure capex demands.
Oman Food Service Market Competitive Landscape
Top-tier vendors anchor premium hotel banquet and fast-casual retail corridors, while mid-scale independents cluster in economy street vending and unlicensed operations. Market structure tilts toward organized chains with captive quality assurance infrastructure. Three archetypes dominate: multi-brand portfolio operators, backward-integrated supply chain controllers, and hypermarket-extended caterers. Competitive moves concentrate on compliance absorption as competitive moat and cloud kitchen infrastructure deployment.
Within the multi-brand portfolio tier, Americana Restaurants International PLC and Jawad Business Group occupy positions that exemplify divergent scale strategies. LuLu Group International anchors the hypermarket-extended catering archetype, leveraging existing cold chain assets for institutional contract penetration. These three entities represent how organized capital captures share as MOCIIP licensing harmonization compresses margins for unlicensed competitors.
| Leading Market Players |
|---|
| Al Daud Restaurants LLC |
| Americana Restaurants International PLC |
| Jawad Business Group |
| Khimji Ramdas |
| LuLu Group International |
| M.H. Alshaya |
| Apparel Group |
| Al Athnain |
| United Catering |
| Others |
Pricing and Supply Chain Analysis
Automated inventory management systems are compressing spoilage losses across Oman's food service landscape, simultaneously lowering per-unit operating costs and concentrating procurement power among chains with centralized commissary infrastructure. This technology shift tightens margin pools for independents while rewarding organized players with sensor-based stock rotation capabilities.
Pricing Analysis
Bundled banquet packages and unbundled à la carte dining now split pricing models across Muscat's hospitality corridor. Three-tier pricing structure across premium, standard, and economy levels reflects quality grade and certification level under MOCIIP's tightened hospitality sector standards. Cost compression in the economy tier is intensifying because unlicensed street vendors face widening performance gaps against compliant operators. Corporate procurement teams demonstrate lowest price sensitivity, while independent consumers in worker canteens show highest elasticity.
Supply Chain Analysis
Regional distribution centers in Saudi Arabia and the UAE anchor warehouse-distribution patterns for Oman's protein inputs. The market draws from Saudi re-export channels for red meat, UAE consolidation hubs for poultry, and Indian Ocean fishing fleets for seafood. Single-source vulnerability through GCC-wide re-export concentration exposes operators to customs delays and regional price shocks. Distribution runs through hypermarket-extended catering networks and hotel central commissaries serving banquet operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oman's food service market offers margin-expansion potential through cloud kitchen infrastructure deployment that eliminates dine-in overhead while capturing delivery-native demand concentration in Seeb and Al Khuwair.
For Market Incumbents: Cement dominance in fast-casual retail corridors by deploying captive quality assurance infrastructure that absorbs MOCIIP certification costs as competitive moats against unlicensed competitors. Expand central commissary capacity to capture institutional catering contracts proliferating around Salalah's port and free zone expansion. Backward integration into bakery and dairy supply chains sustains cost discipline against protein price volatility. For New Entrants and Emerging Players: Worker canteens in the Dhofar development corridor represent the most penetrable buyer archetype for economy-tier meal provision. Highway retail corridors connecting Muscat to the UAE border present greenfield site opportunities where organized fast-casual penetration remains limited. Target educational institution canteens in Sohar and Rustaq through pre-negotiated annual framework agreements with construction and logistics hub operators. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale independents clustered in economy street vending and unlicensed operations facing margin compression from refrigeration infrastructure capex demands. Long-term viability favors organized chains with centralized procurement functions and dedicated quality assurance infrastructure. Watch MOCIIP enforcement intensity in municipal inspections as the inflection indicator for compliance-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Kitchen Infrastructure Deployment | Dark kitchens without dine-in overhead capture delivery-native demand in Seeb and Al Khuwair. |
| Backward Integration into Dairy Supply | Jawad Business Group anchors cost discipline through captive bakery and dairy production. |
| MOCIIP Compliance Certification Investment | HACCP documentation prior to license issuance creates structural advantage for organized chains. |
| Institutional Catering Contract Consolidation | LuLu Group International leverages hypermarket cold chain assets for corporate and hospital contracts. |
| Highway Retail Corridor Site Development | Al Batinah coastal corridor between Muscat and UAE border lacks organized fast-casual penetration. |
Research Methodology
Direct dialogue with procurement directors at hotel banquet operations, supply chain managers at hypermarket-extended caterers, compliance officers navigating MOCIIP licensing protocols, and facility planners in cloud kitchen development anchored qualitative foundations. Secondary validation drew from customs and trade data tracking protein re-export flows, SEC filings of listed restaurant operators, municipal inspection records in Muscat and Dhofar, and hospitality sector investment disclosures. Bottom-up outlet counts triangulated against top-down consumer expenditure estimates across the analysis window.
Bottom-up modeling aggregated individual outlet economics by service type, price tier, and regional cluster, while top-down approaches cross-referenced household food away-from-home spending patterns. Segmentation dimensions included service format, end-user procurement maturity, product perishability gradients, and facility compliance tier. CAGRs were derived from trend extrapolation adjusted for regulatory enforcement intensity and infrastructure investment pipelines. Forecast inputs incorporated Omanization target progression for expatriate labor quotas and GCC technical alignment timelines for nutrition labeling standards.
Underlying measurement precision varies by segment; full-service restaurant and fast food categories carry tighter precision than informal street vending due to licensing documentation requirements. Forecasts reflect assumptions around MOCIIP enforcement consistency, GCC re-export channel stability, and labor quota flexibility that could materially revise trajectory if disrupted. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
International Food Subscription Box Service Market
Food Service
Indonesia Foodservice Market
Food Service
US Food Service Market
Food Service
UK Smokeless Indoor Grills Market
Food Service
Food Delivery Services Market
Food Service
Asia-Pacific Cloud Kitchen Market
Food Service
Europe Barbeque Grill Market
Food Service
Asia-Pacific Online Grocery Delivery Market
Food Service
Germany Foodservice Market
Food Service
Australia Foodservice Market
Food Service
Canada Food Service Market
Food Service
South Africa Fast Food Market
Food Service
North America Online Food Delivery Market
Food Service
Snack Subscription Box Service Market
Food Service
Undercounter Ice Makers Market
Food Service
Bahrain Food Service Market