
 Global Gluten-Free Ready Meals Market | 2026-2036
Global Gluten-Free Ready Meals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gluten-Free Ready Meals Market Foresight
Rice flour is rebalancing cost structures across gluten-free ready meals as wheat-substitute formulations mature. Nestlé SA leverages its frozen distribution network to secure retail shelf space in North American supermarkets. Conagra Brands anchors its portfolio in shelf-stable formats that reduce cold-chain dependency for rural consumers. Amy's Kitchen differentiates through organic ingredient sourcing that commands premium positioning in specialty stores.
Gluten-free ready meals are pre-portioned food preparations formulated without wheat, barley, rye, or cross-contaminated oats, typically achieving less than 20 parts per million gluten content through segregated production lines and validated testing protocols. Their primary commercial purpose is to provide safe, convenient nutrition for individuals with celiac disease, gluten sensitivity, or elective dietary avoidance. Frozen meals dominate current revenue contribution due to extended shelf life and established retail infrastructure, while meal kits represent the fastest-expanding segment as subscription models reduce trial barriers for new gluten-free adopters. Online retailers capture disproportionate growth velocity among distribution channels, though supermarkets and hypermarkets retain the largest absolute transaction volume.
The FDA enforces gluten-free labeling standards that mandate ingredient verification and prevent cross-contact claims without substantiation. EFSA coordinates with national European bodies to harmonize detection thresholds and analytical methods across member states. The EU Green Deal's sustainable food system targets indirectly pressure manufacturers to reduce packaging waste in single-serve ready meal formats. Stakeholders must monitor evolving certification requirements and channel migration patterns to align production capacity with where consumer purchasing behavior stabilizes.
Market Dynamics
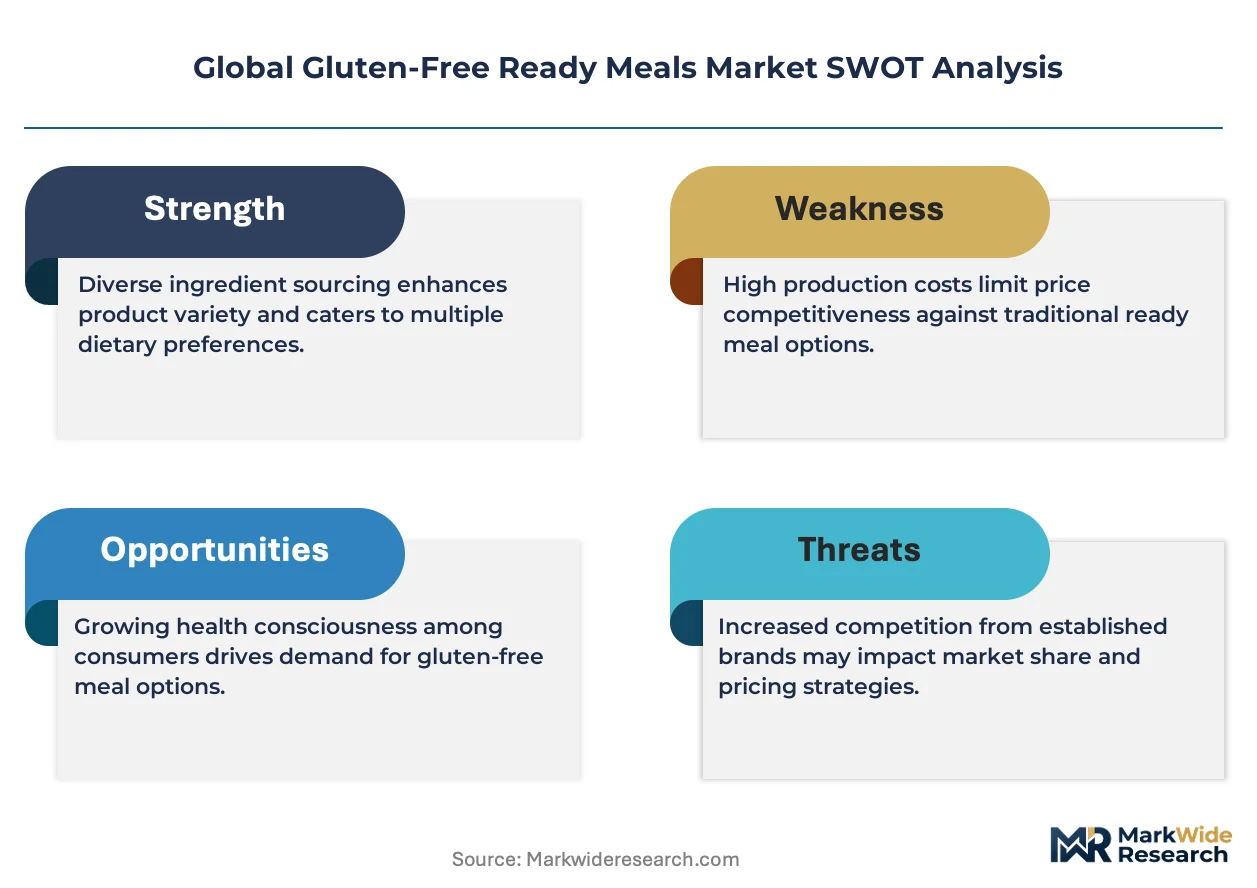
Segregated production infrastructure is compressing margins for gluten-free ready meal manufacturers as dedicated facility requirements clash with volume scalability targets. The FDA's gluten-free labeling rule mandates validated testing protocols that force capital allocation toward quality systems rather than capacity expansion.
Growth Catalysts
- Workplace Wellness Penetration:Corporate health programs in the United States are accelerating celiac disease screening, creating diagnosed demand pools that convert directly to prepared meal purchases.
- EFSA Harmonization:Coordinated detection thresholds across European member states are reducing cross-border formulation complexity for manufacturers scaling production.
- Rice Flour Maturation:Wheat-substitute supply chains in Southeast Asia are stabilizing input costs for base ingredient procurement.
Market Restraints
- Input Cost Volatility:Specialty grain prices fluctuate with climate patterns in Canadian prairie provinces, squeezing margin predictability for frozen meal producers.
- Supply Concentration Risk:Certified gluten-free oat milling concentrates in Nordic supplier networks, creating single-source vulnerability for breakfast-oriented ready meals.
- Regulatory Friction:Brazil's ANVISA maintains divergent labeling thresholds that complicate export certification for multinational manufacturers.
Strategic Opportunities
- Subscription Channel Innovation:Direct-to-consumer meal kit platforms in Germany are reducing trial barriers for newly diagnosed celiac patients through portion-controlled sampling.
- EU Green Deal Tailwinds:Sustainable packaging mandates are creating first-mover advantage for manufacturers investing in compostable single-serve formats ahead of compliance deadlines.
- Technology Convergence:Blockchain traceability systems combined with rapid gluten detection assays are enabling real-time supply chain verification for premium positioning.
Industry Challenges
- Segregated Production Capex:Dedicated facility construction requires capital intensity that mid-tier manufacturers struggle to finance without dilutive funding.
- Certification Timeline Compression:Third-party gluten-free validation from GFCO or NSF International extends product launch cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gluten-Free Ready Meals Market |
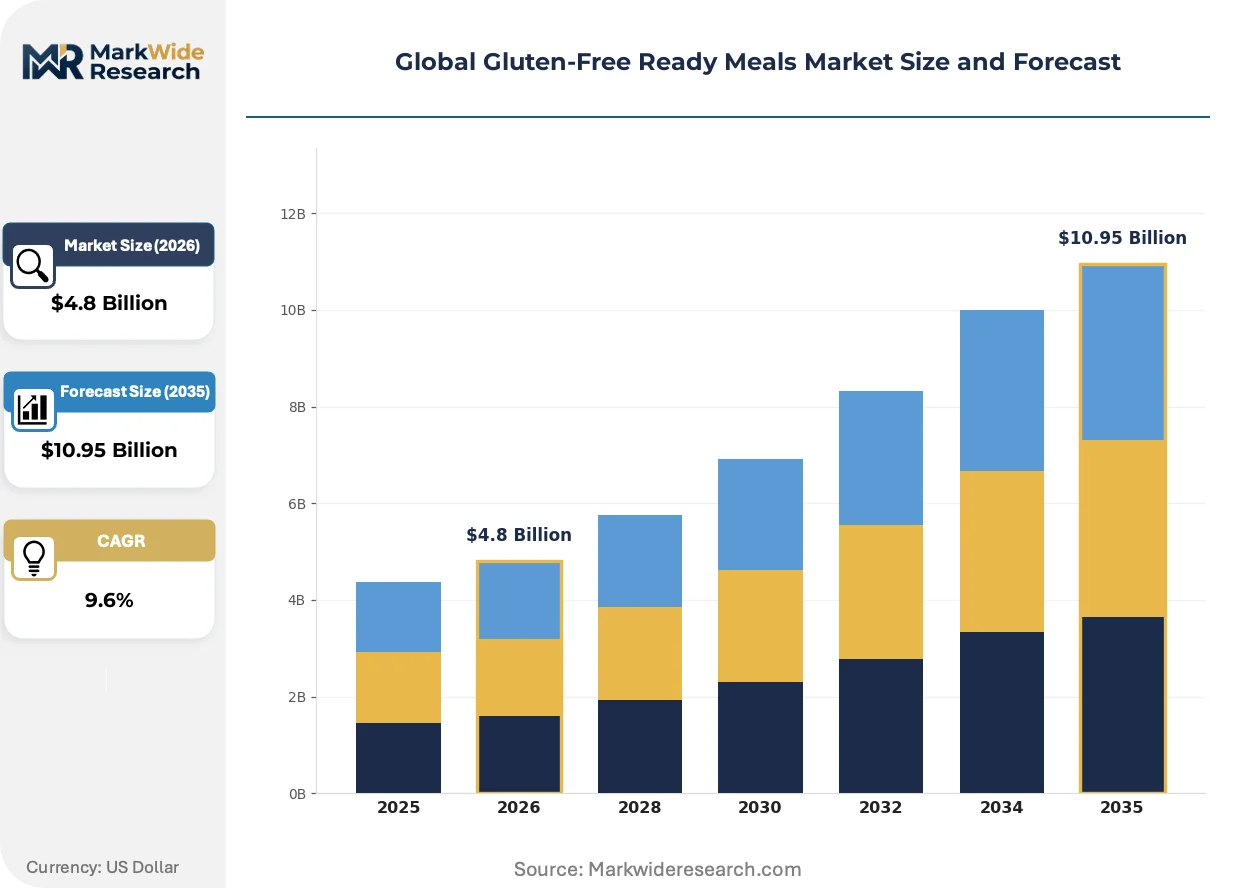
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.95 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Meals, Refrigerated Meals, Shelf-Stable Meals, Meal Kits Distribution Channel: Supermarkets & Hypermarkets, Online Retailers, Convenience Stores, Specialty Stores Consumer Age Group: Children, Adults, Young Adults, Seniors Dietary Preference: Vegan, Vegetarian, Keto, Paleo, Low-Carb |
| Companies Covered | Nestlé SA, Conagra Brands, Amy’s Kitchen, Unilever PLC, Nomad Foods Ltd, Dr. Schär AG / SPA, The Kraft Heinz Company, The Hain Celestial Group, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gluten-Free Ready Meals Market Shifts & Advancements
Digital traceability systems are reshaping how gluten-free ready meals demonstrate safety credentials to risk-averse consumer segments. Three interconnected developments are restructuring competitive positioning.
Blockchain-enabled supply chain verification is integrating with existing ERP platforms to create immutable ingredient provenance records. Large-format retailers in the United States are demanding this transparency layer for shelf placement in dedicated freezer sections. The technology is compressing audit costs while enabling premium pricing for verified-origin products.
REACH chemical safety protocols in Europe are extending scrutiny to packaging materials in contact with gluten-free formulations. Manufacturers sourcing recycled content face additional migration testing requirements that extend qualification timelines. Frozen meal producers with established European distribution are reformulating barrier layers to preempt regulatory rejection.
Young adult adopters are rotating purchases toward meal kit subscriptions that reduce the cognitive burden of ingredient verification. This channel is displacing conventional supermarket freezer browsing in urban United States markets. Digital-native brands capturing this behavioral shift are building recurring revenue models that insulate against retail slotting fee inflation.
Global Gluten-Free Ready Meals Market Segmentation
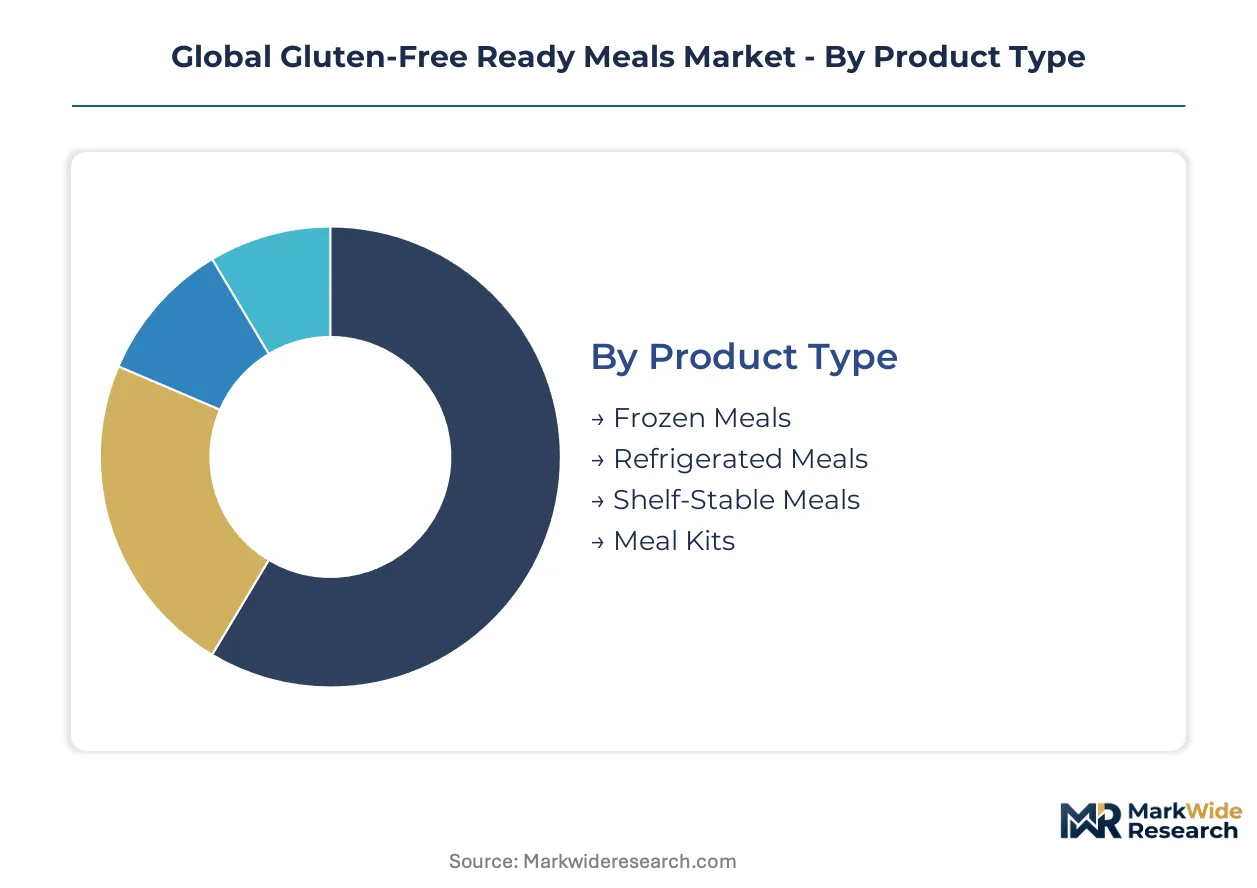
Segmentation in gluten-free ready meals reveals where capital deployment meets consumer risk tolerance. Manufacturers align production infrastructure with how distinct buyer groups navigate certification requirements and convenience trade-offs.
Product Type:
Frozen formats demand the heaviest upfront investment in segregated cold-chain facilities and dedicated production lines that prevent cross-contact.
- Frozen Meals:Extended shelf life through blast freezing enables centralized production with validated gluten testing at batch release. United States supermarket chains dedicate freezer sections to allergen-managed formats, creating shelf space scarcity that rewards early facility investors.
- Meal Kits:Portion-controlled ingredients with recipe cards reduce cognitive burden for newly diagnosed celiac patients. German direct-to-consumer platforms are expanding most quickly through subscription models that lower trial barriers.
- Refrigerated Meals:Shorter shelf life requires regional production nodes with rapid distribution networks.
- Shelf-Stable Meals:Retort processing eliminates cold-chain dependency for rural United States consumers.
Frozen meals absorb the bulk of installed capacity; meal kits are expanding most quickly.
Distribution Channel:
Channel selection determines margin structure through slotting fees, last-mile costs, and inventory risk allocation.
- Supermarkets & Hypermarkets:United States chains command slotting fees for dedicated freezer section placement. Retailers demand blockchain-enabled supply chain verification as a transparency condition for shelf access.
- Online Retailers:Digital-native brands build recurring revenue models that insulate against retail fee inflation. Urban young adults in United States markets are displacing conventional freezer browsing with subscription purchasing.
- Convenience Stores:Limited SKU depth favors single-serve formats with immediate consumption positioning.
- Specialty Stores:Premium positioning rewards organic certification and small-batch production claims.
Supermarkets and hypermarkets retain the largest absolute transaction volume; online retailers capture disproportionate growth velocity.
Consumer Age Group:
Age-based demand patterns shape marketing investment and product formulation priorities.
- Young Adults:Workplace wellness programs in the United States accelerate celiac disease screening, converting diagnosed individuals to prepared meal purchases. This cohort rotates toward digital subscription channels that eliminate ingredient verification burden.
- Adults:Established household purchasing power supports premium positioning for verified-origin products with blockchain traceability.
- Children:School lunch compliance requirements drive demand for pre-portioned formats with clear allergen labeling.
- Seniors:Texture-modified formulations address swallowing difficulties alongside gluten-free requirements.
Adults absorb the bulk of current revenue; young adults are climbing the fastest.
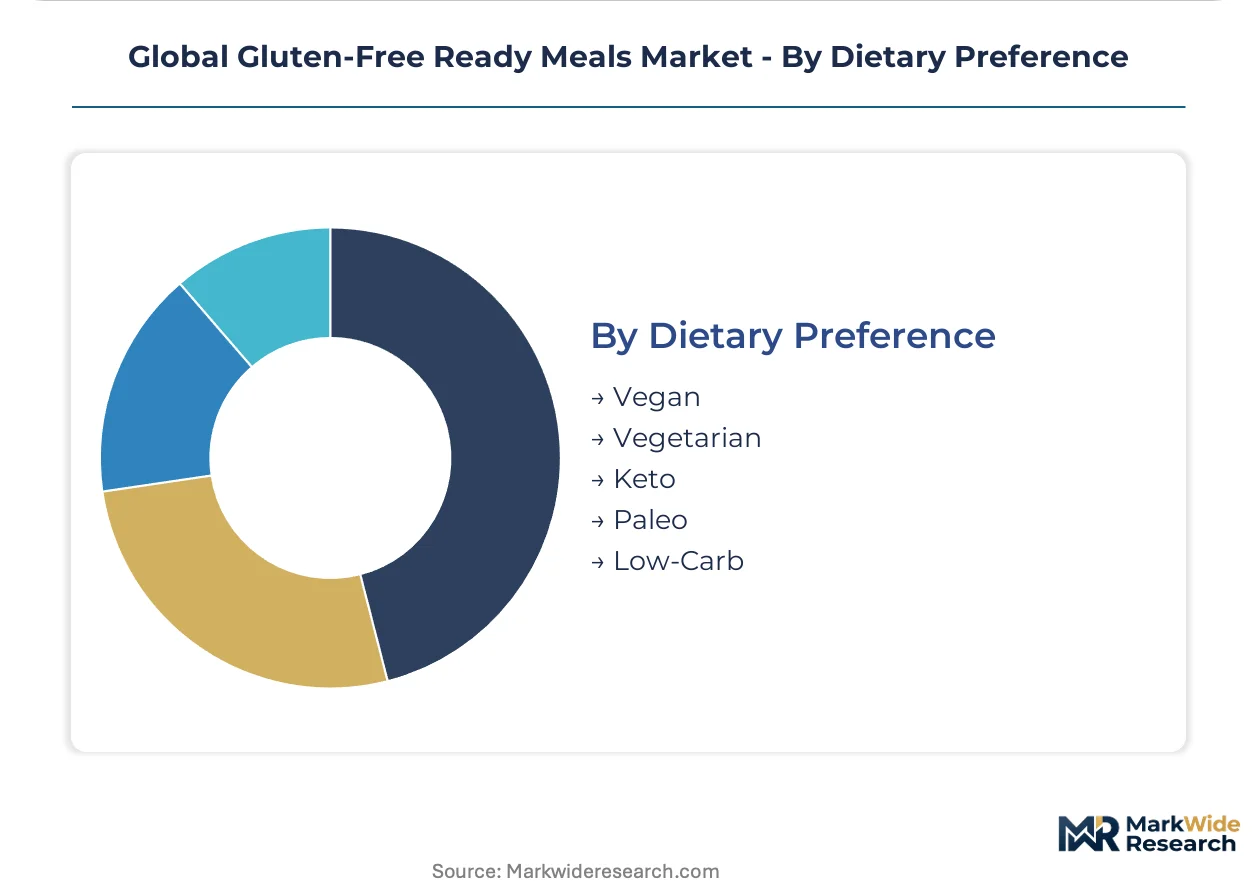
Dietary Preference:
Overlapping dietary restrictions compound formulation complexity and certification costs.
- Vegan:Plant-based protein sourcing intersects with gluten-free grain alternatives, requiring dual validation protocols for ingredient integrity.
- Vegetarian:Dairy inclusion expands texture options while maintaining segregated production lines.
- Keto:Low-carbohydrate constraints eliminate rice flour as a wheat substitute, forcing alternative binder development.
- Paleo:Grain-free positioning aligns naturally with gluten-free claims but restricts permitted carbohydrate sources.
- Low-Carb:Cauliflower and vegetable-based substitutes replace traditional gluten-free starches in reformulated classics.
Vegan-vegetarian combinations absorb the bulk of specialty product development; keto-paleo intersections are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supermarket chains in the United States command the largest absolute transaction volume for gluten-free ready meals, while German direct-to-consumer platforms and Southeast Asian rice flour supply chains anchor complementary demand nodes. Regulatory divergence across FDA, EFSA, and ANVISA jurisdictions shapes where manufacturers concentrate validated production capacity.
United States
Corporate wellness programs at Fortune 500 employers accelerate celiac disease screening, converting newly diagnosed employees into prepared meal purchasers. The FDA enforces gluten-free labeling standards that mandate validated testing protocols and prevent unsubstantiated cross-contact claims. Chicago and Minneapolis house dedicated frozen distribution centers where Nestlé SA leverages established cold-chain infrastructure to secure retail shelf space.
Germany
Subscription meal kit platforms reduce trial barriers for newly diagnosed celiac patients through portion-controlled sampling and recipe-guided preparation. EFSA coordinates detection thresholds across European member states, harmonizing analytical methods that lower cross-border formulation complexity. Berlin and Munich anchor direct-to-consumer fulfillment networks that displace conventional supermarket freezer browsing among urban young adults.
Brazil
ANVISA maintains divergent gluten-free labeling thresholds that complicate export certification for multinational manufacturers seeking Latin American market entry. São Paulo and Rio de Janeiro concentrate retail demand for shelf-stable formats that eliminate cold-chain dependency in regions with inconsistent refrigeration infrastructure. Domestic producers face margin compression from segregated facility requirements that clash with volume scalability targets.
Canada
Specialty grain price volatility in prairie provinces squeezes margin predictability for frozen meal producers dependent on Canadian oat and buckwheat sourcing. Health Canada aligns with FDA detection thresholds while maintaining distinct packaging bilingualism requirements. Toronto and Vancouver house gluten-free certification laboratories that extend product launch timelines for North American market entrants.
Australia
TGA oversight of gluten-free claims intersects with Coles and Woolworths supermarket duopoly purchasing power, concentrating retail negotiation leverage. Melbourne and Sydney host dedicated allergen-managed production facilities serving Asia-Pacific export markets. Local manufacturers exploit counter-seasonal grain harvests to stabilize input costs when Northern Hemisphere supplies face climate stress.
Global Gluten-Free Ready Meals Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers build segregated production lines to satisfy FDA and EFSA validation requirements. The vendor base clusters around three strategic archetypes: multinational conglomerates with frozen distribution networks, mid-tier specialists in organic or allergen-managed formats, and digital-native subscription platforms. M&A activity concentrates among conglomerates acquiring regional certification expertise, while strategic partnerships between meal kit platforms and third-party logistics providers accelerate last-mile coverage.
Within the multinational tier, Nestlé SA and Conagra Brands exemplify divergent format strategies—one leveraging frozen infrastructure, the other anchoring in shelf-stable distribution. Amy's Kitchen occupies a position representing the specialist archetype, with organic sourcing claims commanding premium positioning in specialty retail channels. These three entities collectively illustrate how scale, format selection, and certification positioning segment competitive maneuvering across the value chain.
| Leading Market Players |
|---|
| Nestlé SA |
| Conagra Brands |
| Amy's Kitchen |
| Unilever PLC |
| Nomad Foods Ltd |
| Dr. Schär AG / SPA |
| The Kraft Heinz Company |
| The Hain Celestial Group |
| General Mills |
| Others |
Supply & Pricing Matrix
Certified gluten-free food technologists in Chicago and Minneapolis command wage premiums that compress margin spreads between economy and premium ready meal tiers. Labor scarcity at validated production facilities forces manufacturers to absorb elevated personnel costs or automate, with either path widening price differentiation between certified-organic premium lines and conventional gluten-free economy offerings.
Pricing Analysis
Volume concentrates in frozen supermarket formats while margins accrue to subscription meal kits. Three-tier pricing structure across premium, standard, and economy levels separates blockchain-verified organic lines from conventional certified products and private-label economy tiers. Price differentiation hinges on certification grade and cold-chain investment depth. Pricing pressure stems from rice flour input volatility in Southeast Asian sourcing corridors. Rural United States consumers exhibit highest price sensitivity, while urban young adults in corporate wellness programs demonstrate lowest elasticity.
Supply Chain Analysis
Workforce availability constraints in United States and German manufacturing geographies limit expansion of validated gluten-free production lines. Supply concentrates in United States frozen distribution hubs, Canadian prairie grain belts, and Nordic certified-oat milling networks. Raw material dependencies include rice flour from Thailand and Vietnam, buckwheat from Canadian prairies, and certified gluten-free oats from Nordic suppliers. Single-source vulnerability in Nordic oat milling creates structural risk for breakfast-oriented formats. Distribution runs through supermarket dedicated freezer sections and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Segregated facility scarcity props pricing power for validated manufacturers, with FDA-mandated production line separation creating a structural capacity bottleneck that sustains margin premiums.
For Market Incumbents: Extend blockchain traceability investments to preempt retailer transparency demands and defend shelf access against digital-native entrants. Consolidate regional certification expertise through targeted capability acquisition in German and Australian laboratory networks. Capacity addition in Southeast Asian rice flour processing secures input cost stability against climate-driven volatility. For New Entrants and Emerging Players: Newly diagnosed celiac patients in Brazilian urban centers represent an underserved buyer archetype with limited local validated production. White-space targets include shelf-stable formats for refrigeration-constrained Latin American markets and texture-modified offerings for senior dietary needs. Go-to-market through ANVISA-aligned co-manufacturing partnerships accelerates regulatory compliance without dedicated facility capex. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier specialists possessing GFCO or NSF International certification infrastructure given accelerating FDA enforcement timelines. Long-term viability favors entities with dual-format capability across frozen and shelf-stable production. Watch EFSA harmonization completion as inflection indicator for European cross-border scaling opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Segregated Facility Expansion | Validated production lines secure FDA-compliant capacity for retail freezer section access. |
| Blockchain Traceability Integration | Immutable ingredient records satisfy United States supermarket transparency requirements for shelf placement. |
| Subscription Channel Development | Recurring revenue models insulate German meal kit platforms against retail slotting fee inflation. |
| Sustainable Packaging Transition | Compostable single-serve formats capture EU Green Deal compliance advantage ahead of mandates. |
| Rice Flour Supply Integration | Upstream control over Southeast Asian sourcing corridors stabilizes input costs for base formulations. |
Research Methodology
Document review covered FDA enforcement actions, EFSA guidance documents, and ANVISA regulatory filings, complemented by interviews with gluten-free certification laboratory directors, frozen food category buyers at United States supermarket chains, supply chain managers at multinational manufacturers, and regulatory affairs specialists at third-party validation bodies. Secondary sources included customs records for rice flour and specialty grain trade flows, GFCO and NSF International certification databases, and corporate disclosures from Nestlé SA and Conagra Brands. Bottom-up demand modeling and top-down supply capacity assessment enabled triangulation across independent analytical paths.
Output projections reflect segment-level modeling across product type, distribution channel, consumer age group, and dietary preference dimensions throughout the forecast period. CAGRs derive from regression analysis against validated historical capacity expansion and diagnosed patient population growth curves. Industry-specific inputs included corporate wellness program penetration rates and EFSA harmonization implementation timelines.
Revisions become necessary when FDA labeling enforcement intensity, EFSA threshold harmonization completion, or ANVISA regulatory convergence materializes differently than modeled. Forecasts reflect assumptions about certification timeline compression and channel migration velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Food Intolerance Products Market
Food Intolerance Products
Australia Gluten Free Food Market
Food Intolerance Products
Dyspepsia Market
Food Intolerance Products
Gluten Free Products Market
Food Intolerance Products
Canada Gluten-Free Foods and Beverages Market
Food Intolerance Products
Europe Gluten Free Foods and Beverages Market
Food Intolerance Products
Argentina Gluten-Free Food and Beverage Market
Food Intolerance Products
Gluten Free Tortillas Market
Food Intolerance Products
Food Allergy and Intolerance Products Market
Food Intolerance Products
Gluten-Free Soup Market
Food Intolerance Products
Gluten-Free Pasta Market
Food Intolerance Products
Asia-Pacific Gluten-Free Food and Beverages Market
Food Intolerance Products
Asia-Pacific Gluten-Free Breakfast Cereals Market
Food Intolerance Products
South America Gluten Free Foods and Beverages Market
Food Intolerance Products
Allergen Free Food Products Market
Food Intolerance Products
India Gluten-Free Food and Beverage Market