
 Contract Catering Market | 2026-2036
Contract Catering Market Size, Share, and Industry Trends Forecast 2026-2036
Contract Catering Market Intelligence
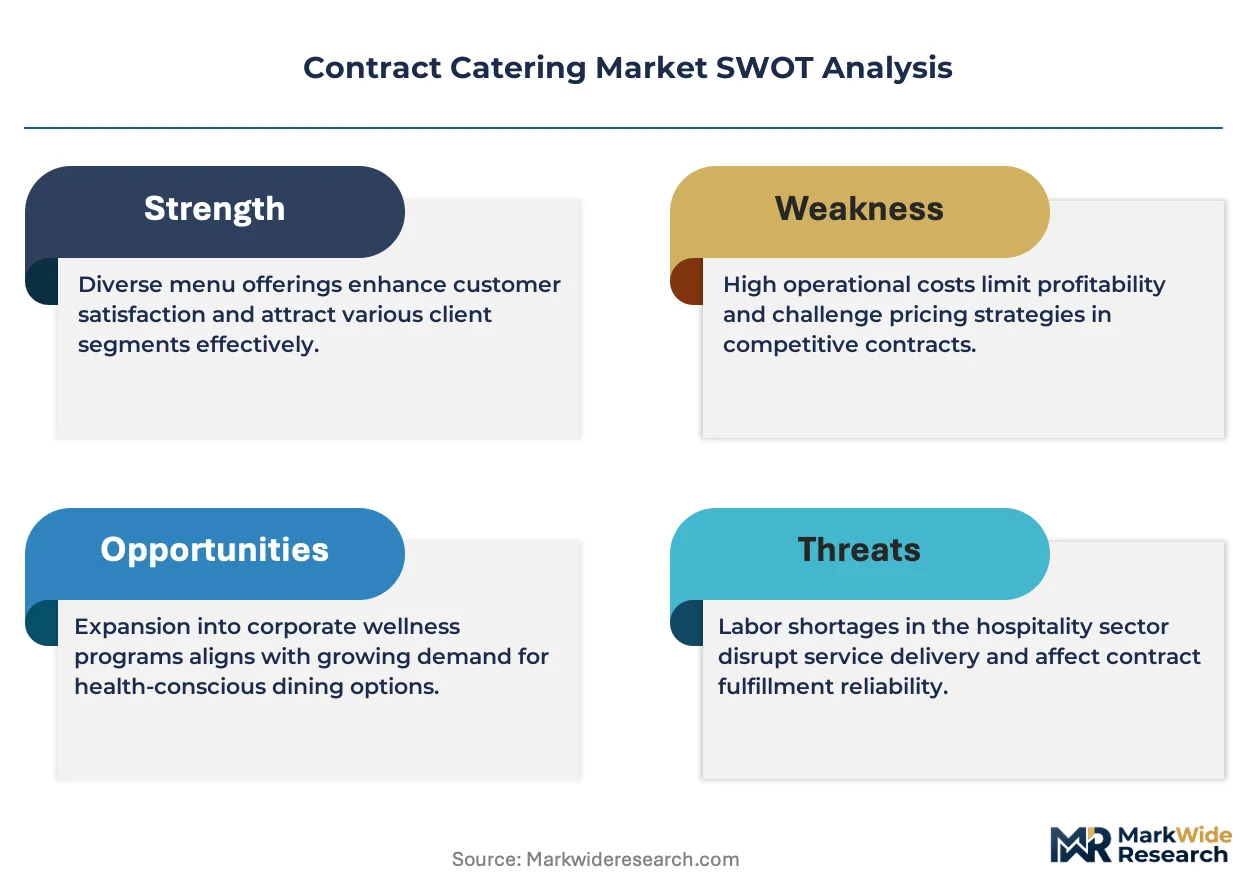
Asset-light leasing models for kitchen infrastructure and equipment are reshaping competitive entry barriers across the contract catering landscape. Compass Group leverages its global procurement network to sustain margin advantages in corporate and healthcare accounts. Sodexo anchors its position through integrated facilities management bundling that extends beyond pure foodservice. Elior Group specializes in educational and business catering across European metropolitan markets, competing on localized menu adaptation.
Contract catering encompasses the outsourced provision of prepared meals and foodservice management to institutional clients under formal agreements, typically specifying nutritional standards, volume commitments, and service-level parameters. The primary commercial purpose centers on converting fixed kitchen overhead into variable cost structures for organizations lacking culinary scale. Corporate catering dominates current revenue pools among service type segments, while healthcare catering represents the fastest-expanding channel as hospital systems outsource non-clinical operations. Business enterprises lead client type demand, though educational institutions offer longer contract tenures that stabilize cash flow visibility.
The US Food and Drug Administration governs food safety protocols, while the EU Green Deal mandates carbon disclosure across institutional supply chains, tightening vendor qualification requirements. OSHA workplace standards and EU REACH chemical frameworks further shape kitchen equipment specifications and cleaning protocol compliance. Stakeholders must monitor evolving procurement criteria that blend cost metrics with sustainability certification thresholds.
Market Dynamics
The EU Green Deal's food waste reduction mandates are compressing procurement cycles as institutional buyers requalify vendors against carbon disclosure thresholds and circular economy benchmarks.
Growth Catalysts
- Healthcare Outsourcing:Hospital systems across Germany, France, and the United Kingdom are converting fixed kitchen overhead into variable cost structures through long-term service agreements.
- REACH Chemical Frameworks:EU-wide compliance requirements for kitchen equipment specifications are locking in certified vendors and raising switching costs for institutional clients.
- Corporate Campus Density:Concentrated business parks in Munich and Frankfurt are generating volume commitments that justify dedicated on-site culinary infrastructure.
Market Restraints
- Input Cost Volatility:Wheat and dairy commodity swings compress margin predictability for operators locked into fixed-price annual contracts.
- Supply Concentration Risk:Specialized cold-chain logistics providers cluster in Northern Italy and the Netherlands, creating single-point vulnerability for pan-European contracts.
- Technical Limitation:Existing automated portioning systems fail to meet religious dietary certification standards for halal and kosher meal production.
Strategic Opportunities
- Educational Institution Expansion:Underpenetrated university foodservice in Poland and Romania offers multi-year contract tenures with stable cash flow visibility.
- AI-Driven Demand Forecasting:Machine learning convergence with IoT-enabled inventory sensors is reducing pre-consumer food waste below regulatory thresholds.
- EU Green Deal Tailwind:Mandatory carbon disclosure across institutional supply chains is disqualifying uncertified competitors and consolidating vendor pools.
Industry Challenges
- Culinary Talent Scarcity:Shortages of dietitian-trained kitchen managers delay contract ramp-up timelines for healthcare accounts.
- Legacy System Integration:ERP synchronization between client procurement platforms and caterer inventory systems requires bespoke middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contract Catering Market |
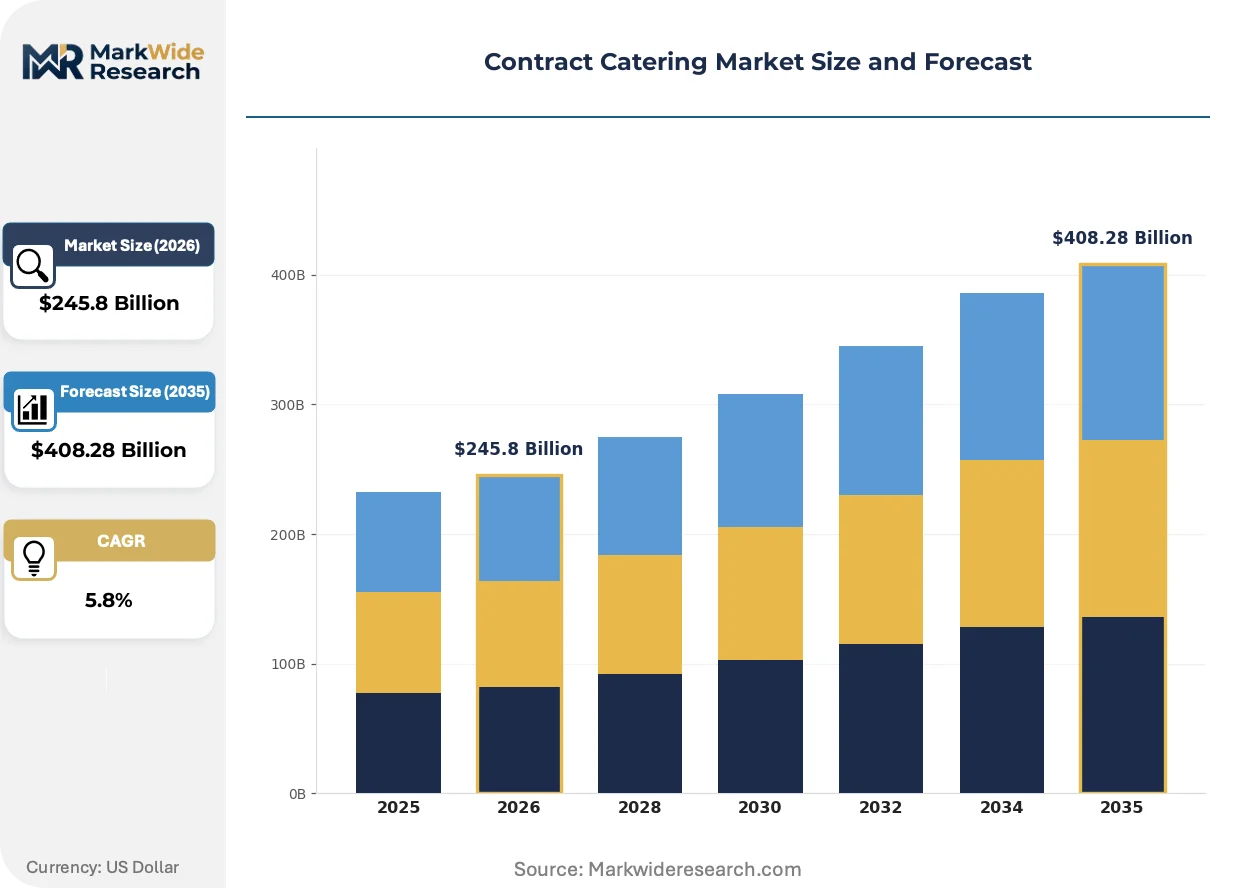
| Market Size in 2026 | $245.8 Billion |
| Market Size in 2035 | $408.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Corporate Catering, Educational Catering, Healthcare Catering, Event Catering Client Type: Business Enterprises, Educational Institutions, Healthcare Facilities, Government Agencies Delivery Model: On-Site Services, Off-Site Services, Online Ordering, Meal Delivery Cuisine Type: Italian, Asian, Vegetarian, Fast Food |
| Companies Covered | Delaware North, HMSHost, Compass Group, ISS A/S, AVI Foodsystems, Aramark, Elior Group, Healthcare Services Group, Sodexo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contract Catering Market Strategic Shifts & Innovations
Automation, regulatory disclosure mandates, and procurement model compression are restructuring how institutional foodservice contracts are priced, monitored, and renewed across European metropolitan markets.
Cloud-connected kitchen equipment is rendering obsolete manual temperature logging and paper-based HACCP documentation. Hospital systems in Denmark and Sweden are deploying these sensors at scale. The technology is rendering obsolete traditional food safety audit models and shifting liability toward real-time data verification.
CSRD corporate sustainability reporting requirements now capture Scope 3 emissions from catering supply chains. This forces contract renegotiation with explicit carbon accounting clauses. Healthcare facilities in Germany are responding by mandating supplier ESG scoring above threshold levels.
Subscription-based meal programs are displacing traditional per-meal invoicing in corporate settings. Facility managers in Amsterdam and Brussels now prefer flat-rate contracts with performance penalties for nutritional variance. This shift concentrates purchasing power with operators capable of standardizing menu cycles across multiple client sites.
Contract Catering Market Segmentation
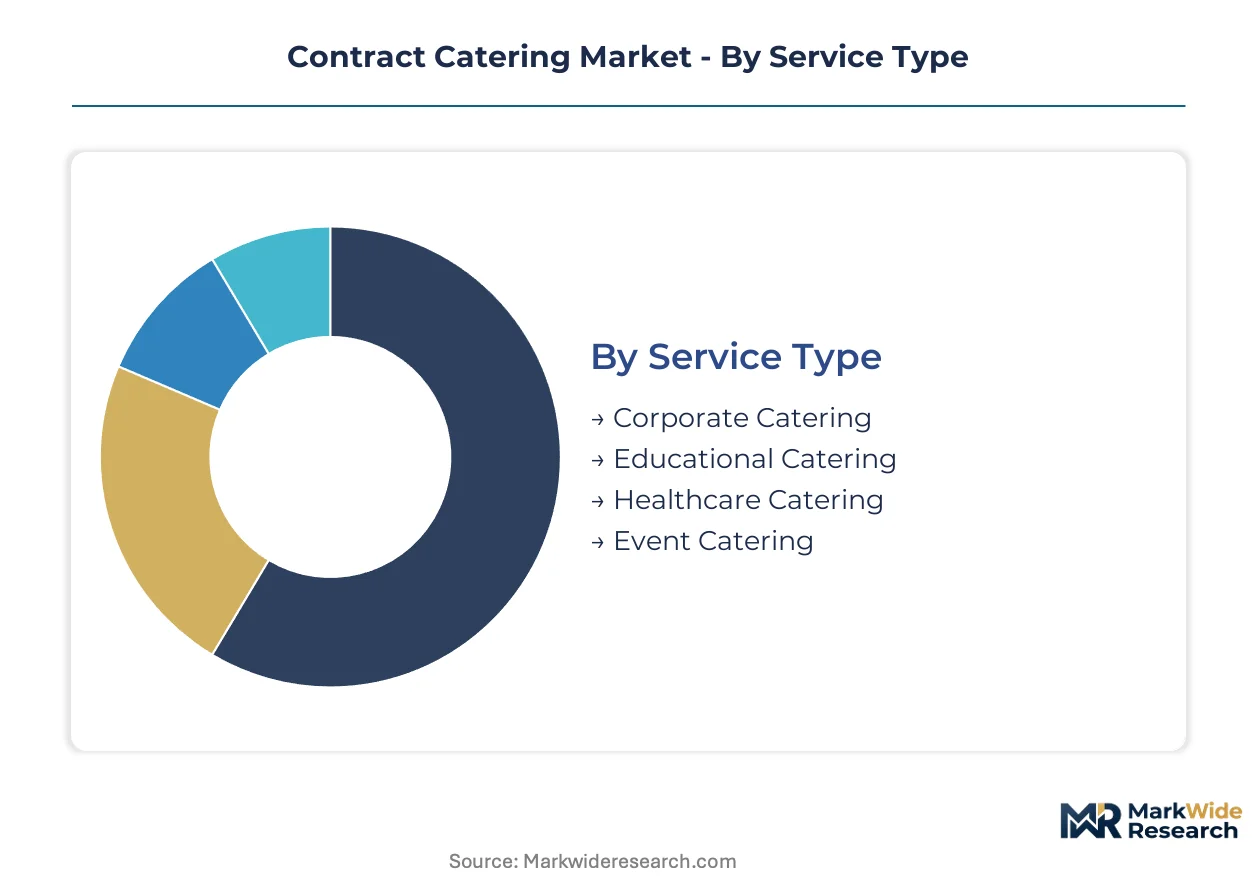
Contract catering segmentation reveals divergent contract tenures and margin profiles across service channels. Healthcare and educational agreements typically span three to five years, while corporate and event catering operate on annual or project-based cycles. Understanding these temporal patterns shapes capital allocation and kitchen infrastructure deployment strategies.
Service Type:
Corporate catering turns over fastest with annual renegotiation cycles, while healthcare contracts lock in longest tenures through decade-long facilities management bundling.
- Corporate Catering:Encompasses daily meal provision to office complexes, business parks, and headquarters under fixed-price or per-meal contracts. Demand clusters in Germany's Munich and Frankfurt corporate campuses where density justifies dedicated on-site culinary infrastructure and specialized account management teams.
- Healthcare Catering:Covers patient meal programs, staff cafeterias, and visitor foodservice within hospital systems. German hospital networks are expanding outsourced procurement fastest as they convert fixed kitchen overhead into variable cost structures under EU Green Deal compliance mandates.
- Educational Catering:Serves primary schools, secondary institutions, and universities with nutritional-standard adherence. Poland and Romania university systems offer underpenetrated expansion terrain with multi-year contract stability.
- Event Catering:Delivers temporary foodservice for conferences, exhibitions, and corporate gatherings. Peak seasonality compresses margin predictability and demands flexible labor pooling arrangements.
Corporate catering dominates installed base. Healthcare catering is where expansion concentrates.
Client Type:
Business enterprises generate highest volume throughput, while government agencies impose strictest procurement qualification barriers.
- Business Enterprises:Technology, financial services, and manufacturing firms purchasing meals for workforce sustenance. Amsterdam and Brussels facility managers now prefer subscription-based flat-rate contracts with performance penalties for nutritional variance over traditional per-meal invoicing.
- Healthcare Facilities:Hospitals, clinics, and long-term care institutions requiring dietitian-supervised meal programs. French and United Kingdom hospital systems are accelerating outsourcing of non-clinical foodservice operations.
- Educational Institutions:Schools and universities with mandated nutritional standards and extended contract durations. Cash flow visibility exceeds corporate accounts due to academic calendar predictability and public funding stability.
- Government Agencies:Public administration buildings, military installations, and correctional facilities with security-cleared staffing requirements. EU REACH chemical frameworks and ESG scoring thresholds restrict vendor pools to certified operators.
Business enterprises anchor volume concentration. Healthcare facilities are climbing the fastest as outsourcing penetration deepens.
Delivery Model:
On-site services command premium pricing through dedicated infrastructure, while off-site and digital channels expand addressable market without capital-heavy kitchen investment.
- On-Site Services:Full kitchen operations embedded within client premises with captive culinary staff and equipment. Corporate campus density in Frankfurt generates sufficient volume to justify dedicated infrastructure deployment.
- Off-Site Services:Central commissary production with transportation to multiple client locations. Specialized cold-chain logistics providers in Northern Italy and the Netherlands create supply concentration vulnerability for pan-European contract fulfillment.
- Online Ordering:Digital platforms enabling individual meal selection and payment processing. Integration with client procurement ERP systems demands bespoke middleware development.
- Meal Delivery:Direct-to-consumer or direct-to-desk distribution models. Subscription-based programs are displacing traditional invoicing in Amsterdam and Brussels corporate settings.
On-site services capture margin premium. Off-site services are gaining share fastest through asset-light scalability.
Cuisine Type:
Menu specialization drives differentiation in competitive bidding, with dietary certification requirements fragmenting supplier capabilities.
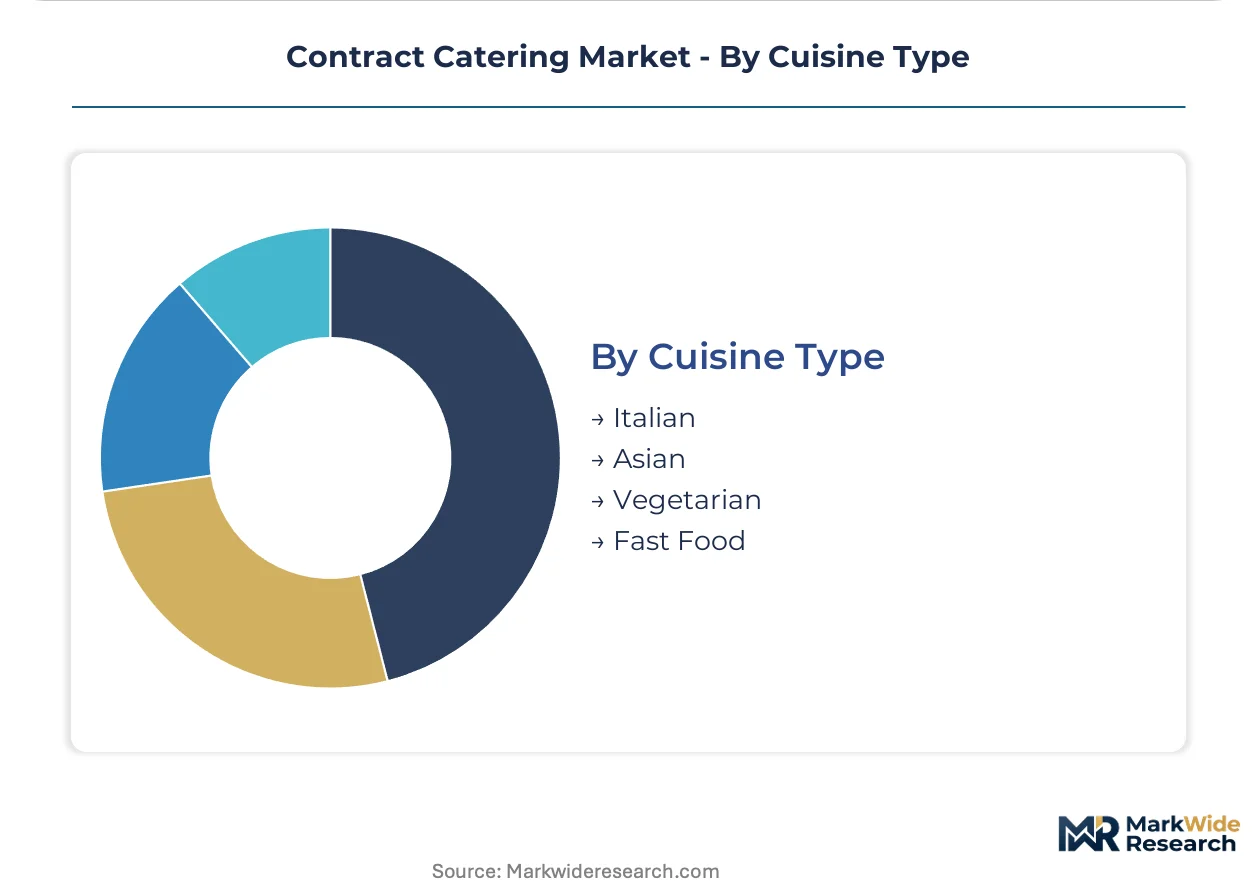
- Italian:Mediterranean diet-aligned offerings with strong acceptance across European corporate and educational accounts. Standardized recipes facilitate multi-site operational replication.
- Asian:Pan-Asian and country-specific cuisines addressing workforce diversity in metropolitan business districts. Demand concentrates in technology sector campuses with international employee bases.
- Vegetarian:Plant-forward menus responding to EU Green Deal carbon disclosure mandates and institutional ESG scoring requirements. German healthcare facilities now mandate supplier sustainability certification thresholds.
- Fast Food:Quick-service formats for high-throughput employee cafeterias and retail food courts. Limited menu complexity reduces culinary talent requirements but compresses differentiation.
Italian and fast food dominate installed base. Vegetarian is where expansion concentrates as regulatory tailwinds intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in contract catering services remain minimal given the localized nature of foodservice delivery, though cross-border procurement of specialized kitchen equipment and cold-chain logistics capabilities creates trade flows between manufacturing hubs and operational markets.
Germany
Hospital systems in Bavaria and North Rhine-Westphalia are accelerating outsourcing of non-clinical foodservice operations under EU Green Deal compliance mandates. REACH chemical frameworks restrict vendor pools to certified operators with documented carbon disclosure capabilities. Munich and Frankfurt corporate campus clusters generate sufficient volume density to justify dedicated on-site culinary infrastructure deployment.
United Kingdom
National Health Service trusts are converting fixed kitchen overhead into variable cost structures through decade-long facilities management bundling agreements. CSRD corporate sustainability reporting requirements now capture Scope 3 emissions from catering supply chains, forcing contract renegotiation with explicit carbon accounting clauses. London's concentrated financial services sector drives subscription-based flat-rate contract preferences over traditional per-meal invoicing.
France
Elior Group's home market exhibits strong educational institution penetration with mandated nutritional standards and extended contract durations. ANSM food safety protocols govern patient meal programs in hospital systems across Île-de-France and Auvergne-Rhône-Alpes. Paris metropolitan business districts demonstrate workforce diversity demand for pan-Asian cuisine offerings in technology sector campuses.
United States
FDA food safety protocols and OSHA workplace standards shape kitchen equipment specifications and cleaning protocol compliance across healthcare and corporate accounts. Delaware North and HMSHost anchor concession-heavy portfolios in transportation hubs and sports venues. Corporate headquarters clusters in Chicago and Atlanta generate annual renegotiation cycles with compressed margin predictability.
Netherlands
Specialized cold-chain logistics providers cluster in Northern Netherlands, creating supply concentration vulnerability for pan-European contract fulfillment. Amsterdam facility managers prefer subscription-based flat-rate contracts with performance penalties for nutritional variance. The country's advanced ERP integration capabilities reduce bespoke middleware development burdens for caterer-client procurement platform synchronization.
Contract Catering Market Key Industry Players
On the supply side, the industry is consolidating around integrated facilities management bundling that extends beyond pure foodservice, with three distinct strategic archetypes emerging: global procurement network operators, localized menu adaptation specialists, and concession-focused venue service providers. Competitive moves concentrate on M&A-driven geographic expansion and AI-driven demand forecasting technology licensing to reduce pre-consumer food waste below regulatory thresholds.
Within the integrated facilities management tier, Compass Group and Sodexo occupy positions as archetypal bundlers, while Elior Group exemplifies the European metropolitan specialization model. These three anchors represent divergent approaches to contract tenure optimization—global network leverage versus localized adaptation versus hybrid concession-corporate portfolios.
| Leading Market Players |
|---|
| Delaware North |
| HMSHost |
| Compass Group |
| ISS A/S |
| AVI Foodsystems |
| Aramark |
| Elior Group |
| Healthcare Services Group |
| Sodexo |
| Others |
Cost & Logistics Intelligence
Northern Italy's cold-chain logistics corridor shapes cost dynamics across European contract catering, concentrating supply-side leverage among specialized temperature-controlled distributors while downstream price differentiation splits between premium on-site operators and asset-light off-site providers.
Pricing Analysis
Business enterprise buyers anchor subscription-based pricing structures across corporate campus contracts, with flat-rate agreements displacing per-meal invoicing in Amsterdam and Brussels. Price differentiation separates certified sustainable operators from uncertified competitors under EU Green Deal mandates, while volume scale and dedicated infrastructure deployment determine margin tiers. Cost compression in healthcare catering intensifies as hospital systems renegotiate decade-long facilities management bundles. Government agencies exhibit lowest price sensitivity due to security-cleared staffing requirements and REACH compliance barriers.
Supply Chain Analysis
EU REACH chemical frameworks restrict kitchen equipment flows to certified vendors, creating regulatory gatekeeping that limits supplier pools. Geographic supply concentration centers on Germany, France, and the Netherlands for specialized cold-chain logistics and commissary production. Raw material dependencies span wheat and dairy commodities, stainless steel fabrication for equipment, and IoT-enabled temperature sensors. Single-source vulnerability runs through Northern Netherlands logistics clusters serving pan-European contracts. Distribution feeds from central commissaries to on-site kitchen operations and direct-to-desk delivery endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contract catering operates as a service-attach opportunity where AI-driven demand forecasting and facilities management bundling expand recurring revenue faster than pure foodservice provision.
For Market Incumbents: Build switching-cost moats through ERP integration middleware that locks client procurement platforms into proprietary inventory systems. Deepen certification investment under EU Green Deal carbon disclosure thresholds to disqualify uncertified competitors. Counter emerging asset-light entrants by expanding decade-long healthcare facilities management bundling that extends beyond pure foodservice into integrated operations. For New Entrants and Emerging Players: Poland and Romania university foodservice offers underpenetrated expansion terrain with multi-year contract stability and lower competitive density than Western European markets. Target educational institutions with AI-enabled waste reduction platforms that pre-qualify vendors under tightening regulatory thresholds. Penetrate through localized menu adaptation partnerships with regional culinary suppliers rather than capital-heavy kitchen infrastructure deployment. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate facilities management divisions seeking to divest non-core foodservice operations. Long-term viability hinges on operators capable of integrating carbon accounting compliance with predictive demand analytics. Watch for inflection signals in CSRD Scope 3 emissions enforcement that consolidate vendor pools toward certified sustainability leaders.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Demand Forecasting | Machine learning convergence with IoT inventory sensors reduces pre-consumer food waste below EU Green Deal regulatory thresholds. |
| Facilities Management Bundling | Integrated service agreements extend contract tenures beyond pure foodservice into decade-long healthcare operations partnerships. |
| ERP Integration Development | Bespoke middleware synchronization between client procurement platforms and caterer systems raises switching costs for institutional accounts. |
| Sustainability Certification Investment | Carbon disclosure capabilities and ESG scoring thresholds pre-qualify operators under tightening EU Green Deal procurement mandates. |
| Educational Institution Expansion | Underpenetrated university foodservice in Central and Eastern Europe offers multi-year contract stability with public funding visibility. |
Research Approach
The analysis maps corporate catering, healthcare catering, educational catering, and event catering segments, each validated through foodservice directors, hospital procurement managers, facilities management executives, and educational institution administrators. Primary interview data triangulates against EU Green Deal regulatory filings, FDA food safety protocols, SEC disclosures from listed operators, and industry association procurement surveys. Bottom-up contract value aggregation cross-references top-down market sizing across service type, client type, and delivery model dimensions.
Assumptions hold EU regulatory enforcement trajectories and healthcare outsourcing penetration rates fixed across the projection horizon, while varying commodity input costs and cold-chain logistics capacity constraints. Segmentation modeling spans service type, client type, delivery model, and cuisine type with geographic clustering across Germany, United Kingdom, France, Netherlands, and United States markets. CAGRs derive from contract tenure patterns and volume commitment densities analyzed against historical renegotiation cycles and procurement model shifts.
Practitioners should monitor REACH chemical framework enforcement intensity and CSRD Scope 3 emissions disclosure adoption for early signals of vendor pool consolidation. Forecasts reflect assumptions regarding regulatory compliance cost trajectories and healthcare system outsourcing willingness. Material shifts in EU Green Deal food waste reduction mandates or cold-chain logistics capacity constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Latin America Online Grocery Delivery Market
Food Service
Commercial Air Fryer Market
Food Service
Meal Voucher Market
Food Service
Global Digital Grocery Market
Food Service
Asia-Pacific Cloud Kitchen Market
Food Service
United States Full Service Restaurants Market
Food Service
Shaker Bottles Market
Food Service
Commercial Pizza Oven Market
Food Service
Malaysia Food Service Market
Food Service
United Kingdom Barbeque Grill Market
Food Service
Supermarkets Market
Food Service
Pizza Foodservice Market
Food Service
Russia Foodservice Market
Food Service
Turkey Retail Bubble Tea Kits Market
Food Service
A La Carte Market
Food Service
Food Service Gloves Market