
 Cambodia Foodservice Market | 2026-2036
Cambodia Foodservice Market Size, Share, and Industry Trends Forecast 2026-2036
Cambodia Foodservice Market Analysis
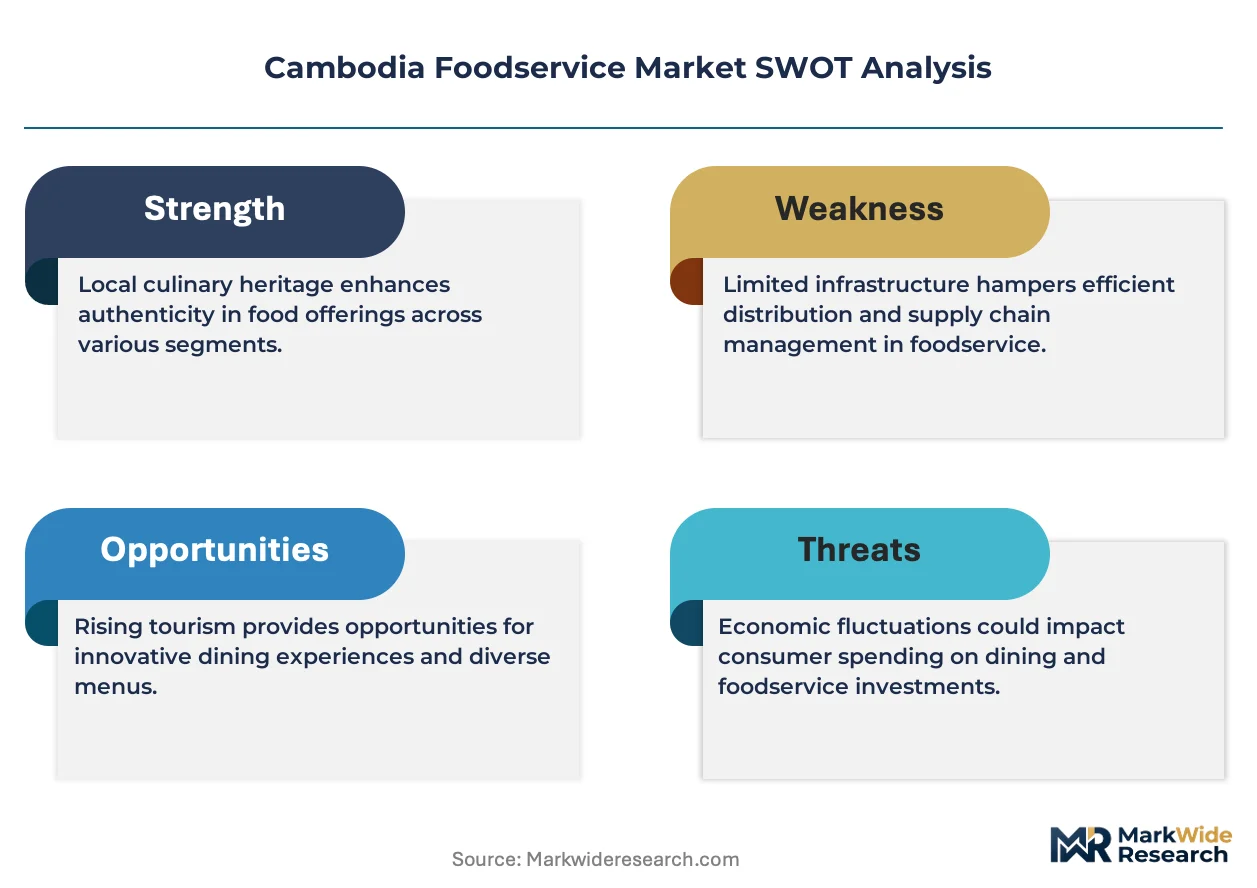
Premium casual dining is reorganizing Cambodia's foodservice competitive landscape. Minor International PLC leverages its Thai hospitality DNA to anchor luxury hotel-integrated dining across Phnom Penh and Siem Reap. Jollibee Foods Corporation sustains its Filipino fast-food playbook while competing aggressively on value meals in secondary cities. Starbucks Corporation differentiates through third-place positioning in urban coworking corridors.
Cambodia foodservice encompasses commercial food preparation and sale through organized outlets ranging from quick-service counters to full-table establishments, with operational parameters including cold-chain compliance, halal certification capability, and kitchen throughput measured in covers per hour. The sector serves domestic consumption, inbound tourism, and corporate catering demand. Fast food and casual dining product types capture the deepest margin pools due to standardized menus and scalable supply chains. Delivery service type is expanding fastest, driven by motorcycle-based logistics networks and mobile wallet penetration among urban households.
Cambodia's Ministry of Commerce and Ministry of Tourism jointly oversee foodservice licensing, while municipal health departments in Phnom Penh and Siem Reap enforce hygiene inspections aligned with ASEAN food safety protocols. Operators must navigate dual registration requirements for imported ingredients and local sourcing certifications. Stakeholders should monitor provincial tax incentive zones and emerging special economic area dining demand as manufacturing clusters attract foreign workers.
Market Dynamics
Tourism corridor densification is restructuring Cambodia's foodservice investment patterns, with capital clustering along the Siem Reap-Phnom Penh-Sihanoukville axis and operators calibrating format mix to transient versus resident demand profiles.
Growth Catalysts
- ASEAN visa facilitation:Cambodia's Ministry of Tourism streamlined entry protocols for regional travelers, expanding addressable tourist dining occasions across border provinces.
- Mobile wallet penetration:Digital payment rails in urban households enable frictionless ordering and loyalty program integration for quick-service operators.
- Manufacturing SEZ expansion:Special economic zones attracting foreign industrial workers generate captive lunch and catering demand near factory clusters.
Market Restraints
- Imported ingredient dependency:Dual registration requirements for foreign-sourced proteins and dairy create inventory lag and working capital pressure.
- Cold-chain gaps:Intermittent refrigeration coverage outside Phnom Penh and Siem Reap limits menu standardization for national chains.
- Halal certification scarcity:Few accredited certifiers service the Muslim tourism segment from Malaysia and Indonesia, constraining addressable market width.
Strategic Opportunities
- Battambang corridor development:Northwest provincial capital with emerging agricultural processing base offers first-mover positioning before saturation.
- Coworking-integrated formats:Third-place positioning combining coffee, light meals, and desk rental captures remote worker segments in urban districts.
- Kampot coastal tourism:Secondary beach destination outside Sihanoukville's casino shadow permits premium casual experimentation at lower rent structures.
Industry Challenges
- Kitchen throughput engineering:Covers-per-hour optimization for motorcycle delivery integration requires reconfigured prep lines and packaging workflows.
- Municipal hygiene inspection variance:Phnom Penh and Siem Reap health departments apply divergent ASEAN protocol interpretations, complicating multi-location compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cambodia Foodservice Market |
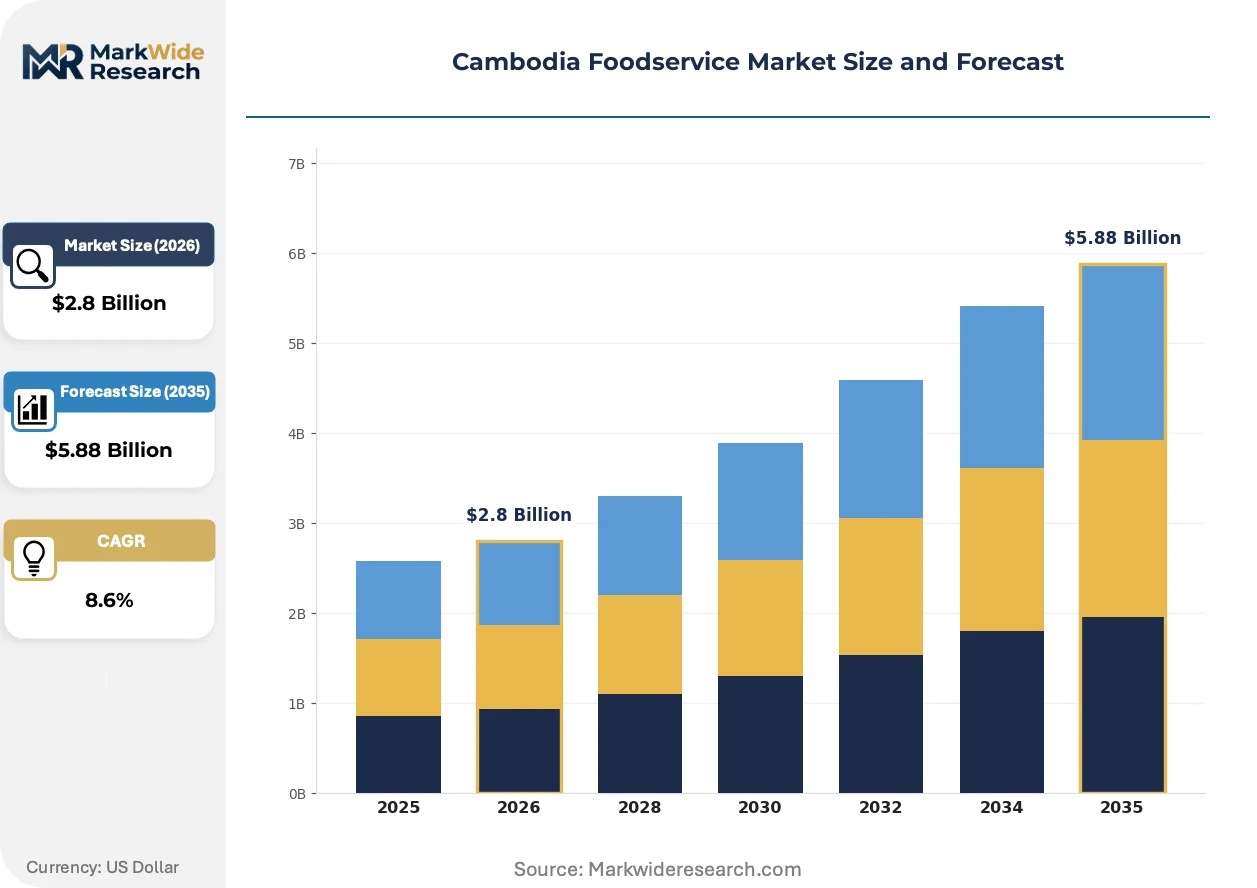
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dine-In, Delivery, Takeaway, Catering Product Type: Fast Food, Casual Dining, Fine Dining, Food Trucks Customer Type: Families, Tourists, Business Professionals, Students Application: Breakfast, Lunch, Dinner, Snacks |
| Companies Covered | Yum! Brands Inc, Restaurant Brands International Inc, Starbucks Corporation, Minor International PLC, Domino’s Pizza Inc, Papa John's International Inc, Berkshire Hathaway Inc, Jollibee Foods Corporation, Lotteria Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cambodia Foodservice Market Emerging Trajectories
Digital infrastructure deployment and format hybridization are compressing traditional dining occasion boundaries, with operators blending service models to capture fragmented consumer time budgets.
Cloud kitchen infrastructure is displacing front-of-house investment for delivery-native brands. These facilities aggregate multiple virtual concepts under single production roofs, reducing rent burden in prime Phnom Penh corridors. Young professional households order through motorcycle-logistics platforms, bypassing seated service entirely.
Cambodia's Ministry of Commerce coordinates with municipal health departments on ASEAN food safety protocol alignment. This regulatory convergence tightens cold-chain documentation requirements for cross-provincial suppliers. Full-service operators in tourism corridors absorb compliance costs through supplier consolidation.
Subscription meal programs are capturing corporate catering demand previously served by conventional cafeteria contracts. Tech-sector employers in Toul Kork district pilot monthly dining allowances integrated with mobile wallets. This procurement model shift reduces administrative overhead while expanding operator visibility into predictable revenue streams.
Cambodia Foodservice Market Segmentation
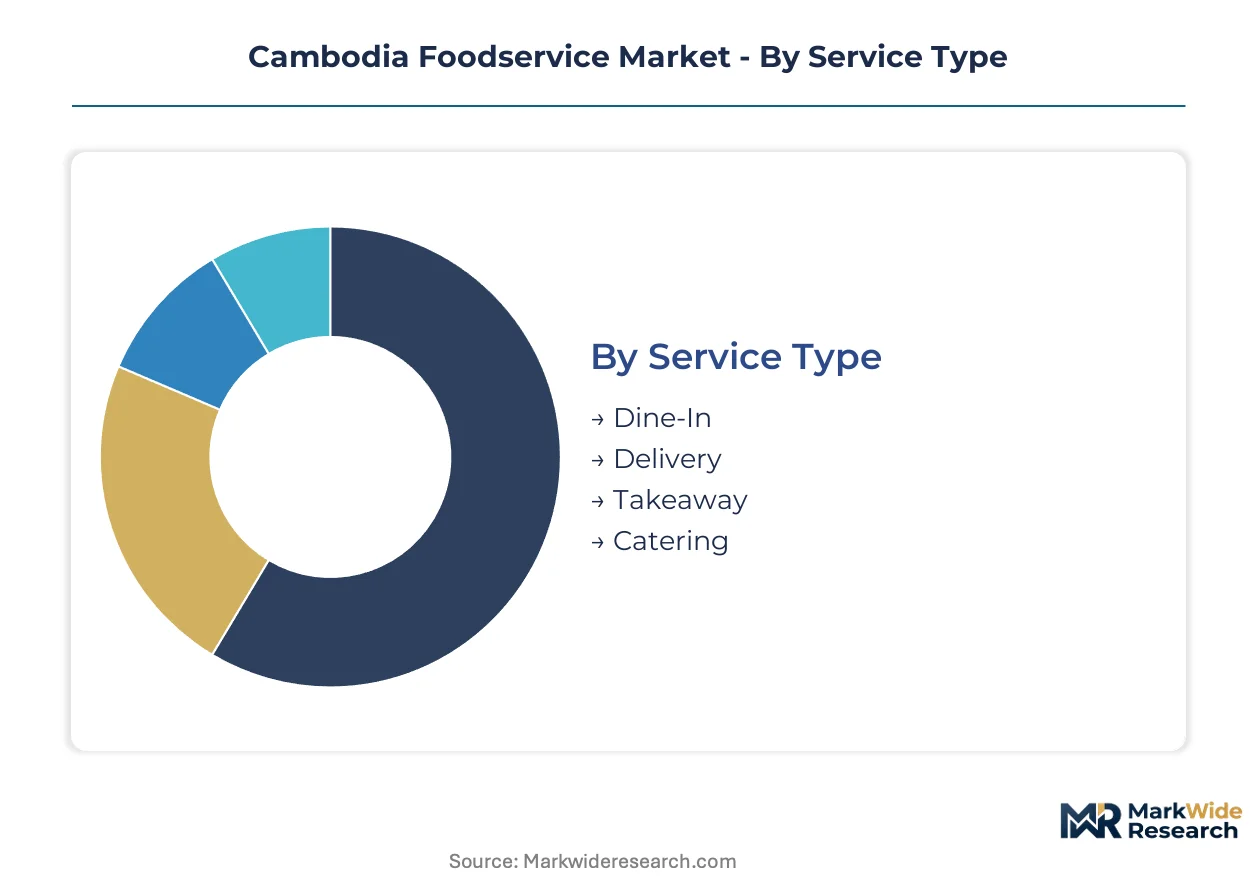
Cambodia's foodservice segmentation reveals distinct operational models competing for consumer occasions across tourism corridors and urban districts. Format choice dictates capital intensity, labor structure, and supply chain configuration for operators navigating Phnom Penh, Siem Reap, and emerging provincial markets.
Service Type:
Delivery formats face acute substitution pressure from cloud kitchens and motorcycle-logistics platforms that bypass traditional front-of-house investment entirely.
- Dine-In:Full-table service with defined seating capacity and front-of-house labor ratios. Phnom Penh's Toul Kork and Boeung Keng Kang districts concentrate upscale dine-in investment near corporate office clusters.
- Delivery:Order-fulfillment through motorcycle-based logistics networks with no customer-facing premises. Mobile wallet penetration among young professional households accelerates order frequency in urban corridors.
- Takeaway:Counter-service collection with minimal dwell time and packaging-optimized menu engineering. Secondary cities like Battambang and Kampot favor takeaway for its lower real estate burden.
- Catering:Bulk preparation for corporate events, weddings, and institutional contracts with advance-order workflows. Manufacturing SEZs generate captive lunch demand from foreign industrial workers.
Dine-In anchors the volume base while Delivery gains share at the steepest rate.
Product Type:
Margin concentration varies sharply across format tiers, with standardized menus enabling scale economies that full-table establishments cannot replicate.
- Fast Food:Limited-menu counters with sub-five-minute service cycles and frozen-protein supply chains. Jollibee Foods Corporation and regional QSR chains target value-conscious segments in secondary cities.
- Casual Dining:Full-service tables with moderate price points and flexible menu breadth. Minor International PLC anchors luxury hotel-integrated casual formats across Phnom Penh and Siem Reap tourism corridors.
- Fine Dining:Chef-driven kitchens with imported ingredient dependency and extended service durations. Cold-chain gaps outside capital cities constrain geographic expansion for premium operators.
- Food Trucks:Mobile preparation units with rotating locations and lower regulatory compliance burden. Kampot coastal tourism permits experimentation at rent structures below Sihanoukville casino districts.
Fast Food captures the deepest margin pool while Food Trucks expand most quickly into underpenetrated provincial corridors.
Customer Type:
Tourism-dependent segments exhibit higher volatility than resident demand, requiring operators to calibrate format mix to transient versus repeat customer profiles.
- Families:Multi-generational groups prioritizing portion size, value pricing, and child-friendly environments. Weekend dining occasions concentrate in mall-anchored food courts across Phnom Penh districts.
- Tourists:Inbound visitors from ASEAN markets with halal certification requirements and experience-seeking preferences. Cambodia's Ministry of Tourism visa facilitation expands addressable tourist dining occasions.
- Business Professionals:Time-constrained weekday demand for speed, convenience, and expense-account-appropriate venues. Coworking-integrated formats in Toul Kork district capture remote worker segments.
- Students:Price-sensitive volume demand concentrated near university campuses with mobile wallet payment preference. Subscription meal programs pilot monthly dining allowances integrated with digital wallets.
Business Professionals generate the highest per-cover spend while Students drive order frequency through digital platforms.
Application:
Daypart concentration shapes kitchen throughput engineering and staffing models, with lunch and dinner commanding premium labor allocation.
- Breakfast:Early-day occasions dominated by coffee-forward formats and quick-service bakery items. Starbucks Corporation targets third-place positioning in urban coworking corridors for morning routines.
- Lunch:Midday peak demand from corporate catering and quick-service counters with throughput optimization. Manufacturing SEZ expansion generates captive factory-cluster demand.
- Dinner:Extended-service occasions with higher average checks and full-table format preference. Siem Reap tourism corridors absorb dinner investment targeting inbound visitors.
- Snacks:Between-meal occasions captured by street vendors, convenience formats, and delivery-native virtual brands. Motorcycle-logistics platforms enable fragmented snacking demand across urban households.
Lunch commands the highest volume throughput while Snacks demonstrate the steepest expansion trajectory through delivery infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital deployment across Cambodia's foodservice sector clusters along three dominant urban corridors where tourism density and resident purchasing power intersect. The Ministry of Commerce tracks provincial licensing patterns that reveal this geographic concentration.
Phnom Penh Capital Region
Young professional households and corporate office clusters in Toul Kork and Boeung Keng Kang districts drive quick-service expansion. The Ministry of Tourism coordinates with municipal authorities on ASEAN business traveler facilitation. Cloud kitchen infrastructure proliferates along Russian Federation Boulevard to capture delivery-native demand.
Siem Reap Tourism Corridor
Inbound visitor volumes from Thailand and Vietnam sustain hotel-integrated dining formats near Angkor temple complexes. Cambodia's Ministry of Commerce enforces dual registration requirements for imported proteins serving premium casual establishments. Pub Street and surrounding districts absorb foreign direct investment in full-table service capacity.
Sihanoukville Coastal Zone
Casino district development and special economic zone manufacturing generate dual demand streams for institutional catering and quick-service counters. The Ministry of Tourism visa facilitation protocols expand addressable tourist dining occasions from regional markets. Cold-chain gaps constrain menu standardization for national chains beyond the city core.
Battambang Northwest Corridor
Agricultural processing expansion and emerging middle-class density create first-mover positioning opportunities before corridor saturation. Provincial health departments apply divergent hygiene inspection standards compared to capital city protocols. Riverside commercial districts attract experimental food truck and casual dining formats at lower rent structures.
Kampot Secondary Coastal Market
Premium casual experimentation flourishes outside Sihanoukville's casino-shadow rent environment. The Ministry of Commerce special economic area dining demand tracks manufacturing cluster foreign worker populations. Pepper plantation tourism and weekend visitor flows from Phnom Penh sustain seasonal revenue volatility.
Cambodia Foodservice Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across Cambodia's foodservice structure. Quick-service operators with standardized supply chains capture volume share while hotel-integrated formats command premium positioning. Three archetypes dominate: multinational QSR licensors, Thai hospitality conglomerates with regional dining portfolios, and Filipino fast-food specialists competing on value meal penetration. Competitive moves center on digital ordering infrastructure deployment and provincial corridor pre-emption before rival format saturation.
Within the multinational QSR tier, Yum! Brands Inc and Domino's Pizza Inc exemplify technology-forward licensing models emphasizing mobile wallet integration and delivery logistics. Jollibee Foods Corporation anchors the value-driven Filipino fast-food archetype with aggressive secondary city expansion. Minor International PLC represents the hospitality-integrated premium casual positioning that leverages Thai regional expertise across Phnom Penh and Siem Reap tourism corridors.
| Leading Market Players |
|---|
| Yum! Brands Inc |
| Restaurant Brands International Inc |
| Starbucks Corporation |
| Minor International PLC |
| Domino's Pizza Inc |
| Papa John's International Inc |
| Berkshire Hathaway Inc |
| Jollibee Foods Corporation |
| Lotteria Co. Ltd |
| Others |
Supply Flow & Price Mechanics
Seventy-two-day inventory cycles for imported frozen proteins compress margin buffers for quick-service operators while amplifying pricing power among cold-chain logistics consolidators in Phnom Penh. This lead-time structure rewards operators with backward integration into supplier networks and punishes those dependent on spot-market procurement.
Pricing Analysis
Cambodia's Ministry of Commerce dual registration requirements for imported ingredients dictate the pricing tier structure across the foodservice sector. Three-tier pricing structure across premium, standard, and economy levels separates hotel-integrated dining from mall food courts and street-side counters. Price differentiation rests on halal certification status and cold-chain documentation grade. Pricing pressure stems from working capital absorption for inventory lag on foreign-sourced dairy and proteins. Students and young professional households exhibit highest price sensitivity, while corporate catering contracts demonstrate lowest elasticity due to expense-account procurement.
Supply Chain Analysis
Strategic stockpiling of frozen proteins dominates inventory strategy over just-in-time approaches due to intermittent cold-chain coverage outside urban cores. Supply concentration centers on Thailand for proteins and dairy, Vietnam for fresh produce, and China for packaging materials and equipment. Raw material dependencies include imported beef and poultry, palm oil derivatives, and single-use food-grade packaging. Single-source vulnerability from Thai cold-chain logistics providers creates structural risk for national chain expansion. Distribution runs through motorcycle-based last-mile networks anchored in Phnom Penh and Siem Reap before provincial radiating spokes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among manufacturing SEZ employers and tech-sector corporates piloting subscription meal programs, shifting procurement leverage away from fragmented individual outlets. This concentration demands operator adaptation across format tiers.
For Market Incumbents: Shield margin position by securing exclusive supplier contracts with Thai cold-chain logistics consolidators before provincial corridor saturation. Invest in halal certification capability to capture Malaysian and Indonesian tourist segments. Backward integration into pepper and rice sourcing from Battambang agricultural processors reduces imported ingredient dependency.
For New Entrants and Emerging Players: Lead with cloud kitchen infrastructure in Toul Kork and Boeung Keng Kang districts where delivery-native demand outstrips seated capacity. Target Kampot coastal tourism for premium casual experimentation at rent structures below Sihanoukville casino districts. Deploy mobile wallet-integrated loyalty programs as primary customer acquisition channel.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across delivery-native virtual brands due to front-of-house displacement. Long-term viability favors operators with supplier consolidation in Thai-Vietnamese cross-border networks and municipal health department compliance track records. Acquisition targets should demonstrate kitchen throughput engineering for motorcycle delivery integration. Watch for inflection when provincial tax incentive zones attract manufacturing clusters beyond Phnom Penh-Sihanoukville axis.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Kitchen Infrastructure Deployment | Reduces rent burden in prime Phnom Penh corridors while aggregating multiple virtual concepts. |
| Halal Certification Investment | Unlocks Malaysian and Indonesian tourist segments constrained by current certifier scarcity. |
| Backward Integration into Agricultural Sourcing | Captures Battambang pepper and rice processing before corridor saturation elevates land costs. |
| Mobile Wallet Loyalty Integration | Aligns with young professional household payment preferences in urban delivery corridors. |
| Manufacturing SEZ Catering Contract | Generates predictable revenue streams from foreign industrial worker captive lunch demand. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of Ministry of Commerce licensing records, Ministry of Tourism visitor flow data, and ASEAN food safety protocol documentation. Primary interviews incorporated restaurant chain operations directors, cold-chain logistics providers, municipal health department inspectors, and manufacturing SEZ facility managers. Secondary validation drew from provincial investment promotion authority filings, customs import records for food ingredients, and mobile wallet platform transaction disclosures. Bottom-up outlet counting across Phnom Penh, Siem Reap, and Sihanoukville triangulated against top-down tourism expenditure modeling.
Segmentation dimensions modeled include service type, product type, customer type, and application across dine-in, delivery, takeaway, and catering formats. The analytical framework projects value and volume across the analysis window using CAGRs derived from historical tourism arrival patterns and urban household consumption surveys. Industry-specific forecast inputs incorporate special economic zone manufacturing employment trajectories and provincial infrastructure development timelines from Ministry of Commerce disclosures.
The analysis sits within stated boundaries; outcomes outside sustained ASEAN visa facilitation and mobile wallet penetration thresholds would require recalibration. Forecasts reflect documented assumptions on cold-chain expansion rates and halal certification capacity growth. Revision becomes warranted when manufacturing SEZ employment crosses provincial dispersion thresholds or municipal hygiene inspection variance narrows significantly.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Latin America Online Grocery Delivery Market
Food Service
Africa Foodservice Market
Food Service
China Online Food Delivery Market
Food Service
Commercial Rice Cooker Market
Food Service
Commercial Beverage Dispenser Market
Food Service
Saudi Arabia Inflight Catering Market
Food Service
Food Logistics Market
Food Service
France Foodservice Market
Food Service
Takeout Dinner Market
Food Service
Instant Grocery Market
Food Service
Gas Floor Fryers Market
Food Service
Wok Market
Food Service
Integrated Stove Market
Food Service
Indonesia Foodservice Market
Food Service
South America Free from Food Market
Food Service
North America Smokeless Indoor Grills Market