
 Global Meal Kit Market | 2026-2036
Global Meal Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Global Meal Kit Market Outlook
Modular recipe bundling is consolidating buyer choice around flexible serving configurations rather than fixed menu rotations. HelloFresh leverages its European fulfillment network to sustain cross-border density economics. Blue Apron anchors its position through specialized dietetic portfolios including diabetes-friendly and heart-healthy lines. Sunbasket competes on organic certification depth, controlling supplier relationships across California and Pacific Northwest agricultural zones.
A meal kit comprises pre-portioned ingredients with recipe instructions, typically requiring refrigeration at 0-4°C throughout a supply chain spanning centralized commissaries, regional distribution centers, and last-mile courier networks. The primary commercial purpose is reducing consumer meal-planning friction while minimizing household food waste through exact-quantity provisioning. Subscription-based delivery models dominate revenue pools, while one-time purchase formats are gaining fastest among trial-oriented buyers. Family-size configurations lead volume throughput, though single-serving formats command premium pricing in dense urban markets.
FDA food-safety modernization standards shape cold-chain compliance investments, while EU Green Deal packaging directives are forcing biodegradable material transitions across European operations. Japan's METI energy-efficiency guidelines influence refrigerated logistics fleet specifications. Stakeholders must monitor how multi-jurisdiction labeling requirements affect recipe standardization and whether carbon-accounting rules reshape ingredient sourcing radii.
Market Dynamics
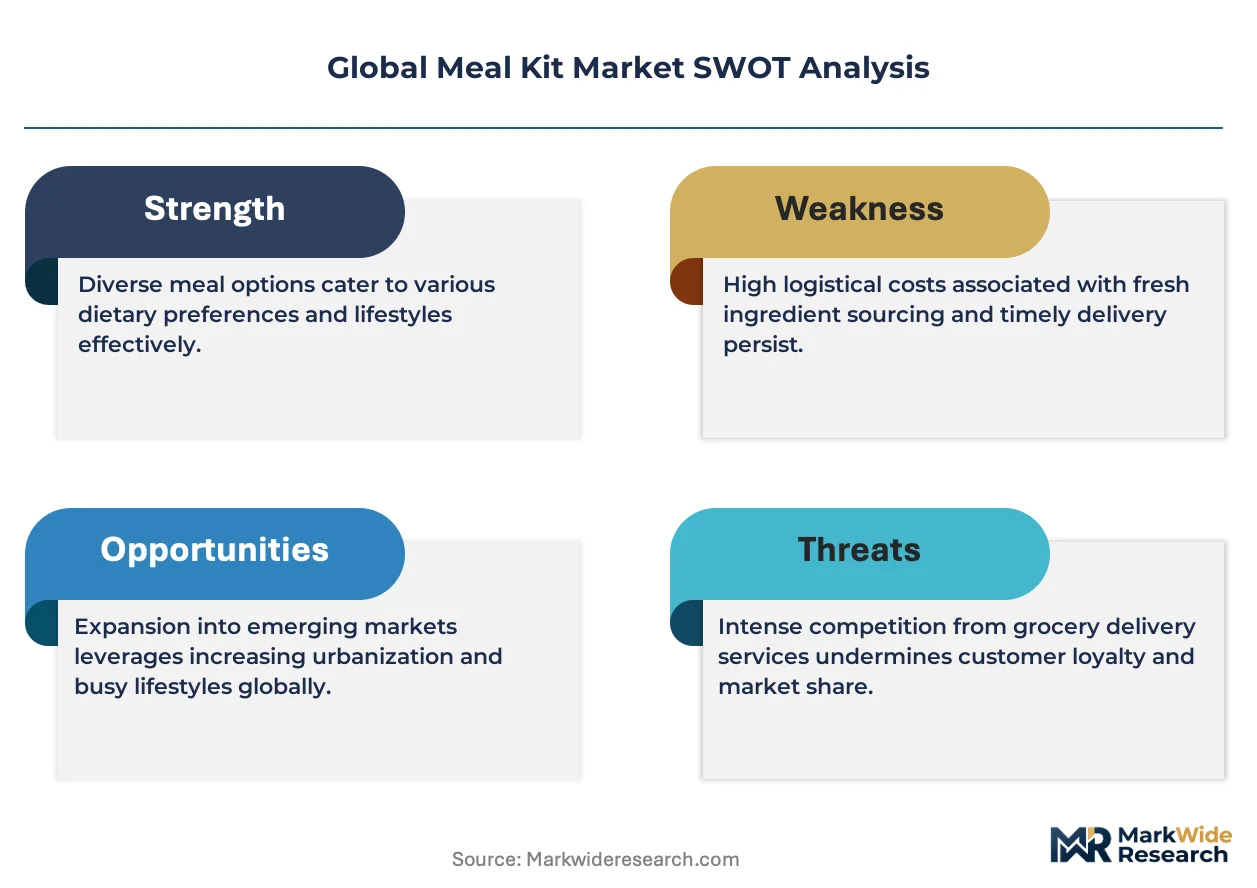
Cold-chain logistics density economics are compressing last-mile delivery radii, forcing operators to choose between regional fulfillment scale or hyperlocal freshness premiums.
Growth Catalysts
- EU Green Deal packaging directives:Biodegradable material mandates are accelerating supplier transitions toward compostable insulation and recyclable meal trays across German and French operations.
- Dual-income metropolitan households:Time-scarcity among professional couples in Tokyo, New York, and London is converting grocery shopping into subscription-based meal assembly services.
- Active packaging technologies:Oxygen-scavenging films and time-temperature indicators are extending refrigerated shelf life without frozen distribution infrastructure.
Market Restraints
- Perishable input cost volatility:Fresh produce and protein spot markets expose margins to weather-driven price swings in California's Central Valley and Dutch greenhouse corridors.
- Regional fulfillment concentration:Cold-storage capacity bottlenecks around Chicago, Rotterdam, and Osaka limit expansion into secondary metropolitan zones.
- Home delivery substitution:Quick-commerce grocery apps and prepared meal delivery services capture overlapping convenience-oriented household budgets.
Strategic Opportunities
- India's FSSAI regulatory pathway:Standardized food safety certification frameworks are opening organized retail channels for temperature-controlled meal kits in Bangalore and Mumbai.
- Corporate cafeteria displacement:Hybrid work patterns are redirecting employer food-service budgets toward home-delivered team meal programs.
- AI-driven demand forecasting:Machine learning inventory optimization converging with dynamic recipe personalization is reducing waste ratios below traditional retail benchmarks.
Industry Challenges
- Cold-chain technician scarcity:Refrigeration mechanics and HACCP-certified warehouse operators command premium wages in competitive logistics labor markets.
- FDA Food Safety Modernization Act traceability:Lot-level ingredient tracking requirements extend compliance timelines and IT integration costs for mid-tier operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Meal Kit Market |
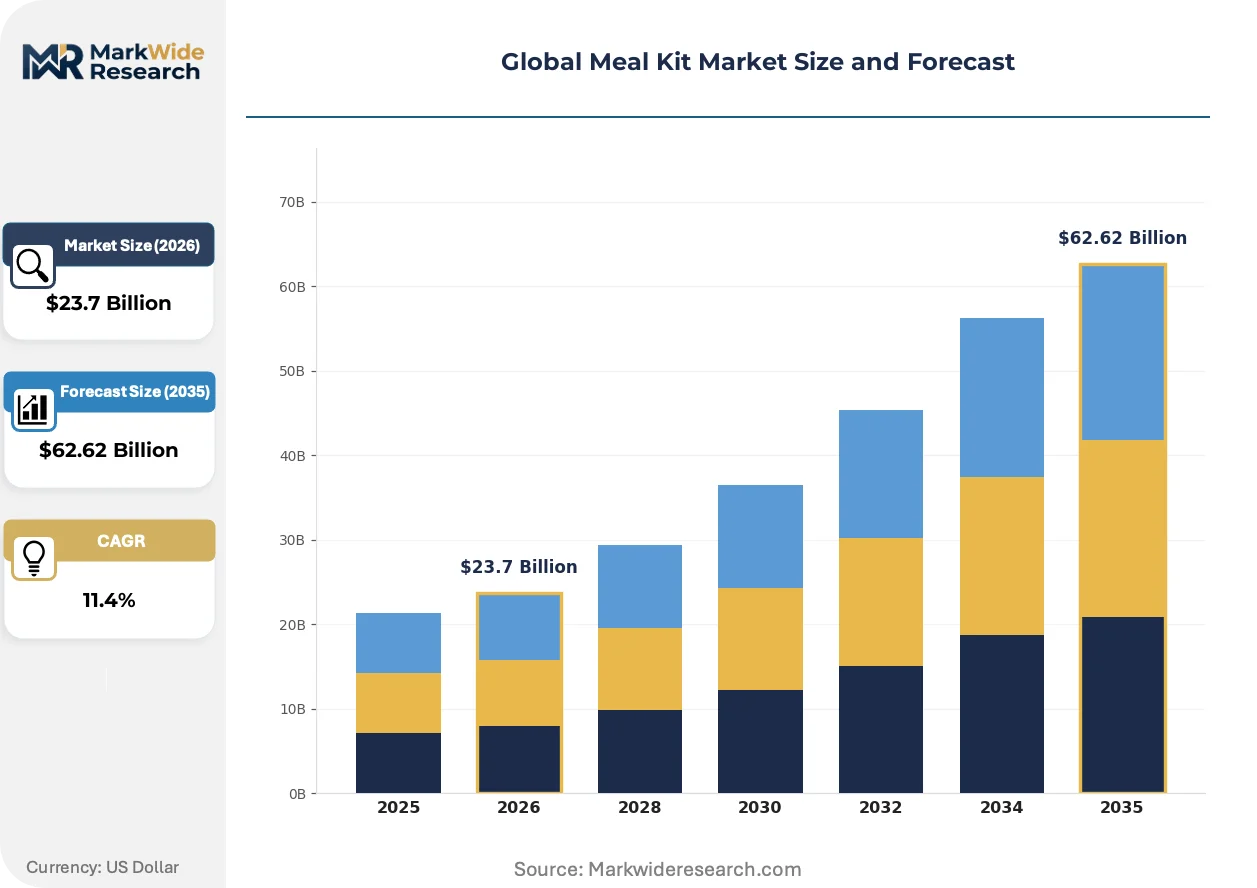
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetarian, Vegan, Family Size, Single Serving Delivery Model: Doorstep Delivery, Click-and-Collect, Subscription-Based, One-Time Purchase Ingredient Type: Organic, Non-GMO, Locally Sourced, Pre-Packaged Customer Segment: Health-Conscious, Busy Professionals, Families, College Students |
| Companies Covered | Sunbasket, EveryPlate, HelloFresh, Factor, Purple Carrot, Blue Apron, Green Chef, Freshly, Home Chef, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Meal Kit Market Strategic Shifts
Operational automation and sustainability compliance are compressing cost structures while fragmentating competitive positioning around freshness credentials and dietary specialization.
Modular portion-control automation is consolidating fulfillment labor economics. Robotic weighing and bagging systems in Dallas and Düsseldorf distribution centers now handle 70% of ingredient kit assembly. European operators deploying these systems are compressing per-order handling costs while maintaining FDA and EFSA contamination-control standards.
REACH chemical restrictions on food-contact materials are forcing substrate transitions across EU operations. Manufacturers must eliminate certain perfluorinated compounds from grease-resistant packaging by compliance deadlines. German and Dutch meal kit providers are accelerating paper-based barrier coatings and molded fiber tray adoption ahead of enforcement phases.
Subscription fatigue is rotating demand toward flexible purchase models. Trial-oriented buyers in Sydney and Toronto increasingly favor one-time gift boxes and pause-friendly memberships over rigid weekly commitments. This behavioral shift pressures customer lifetime value calculations while expanding acquisition funnel breadth for operators with modular pricing architectures.
Global Meal Kit Market Segmentation
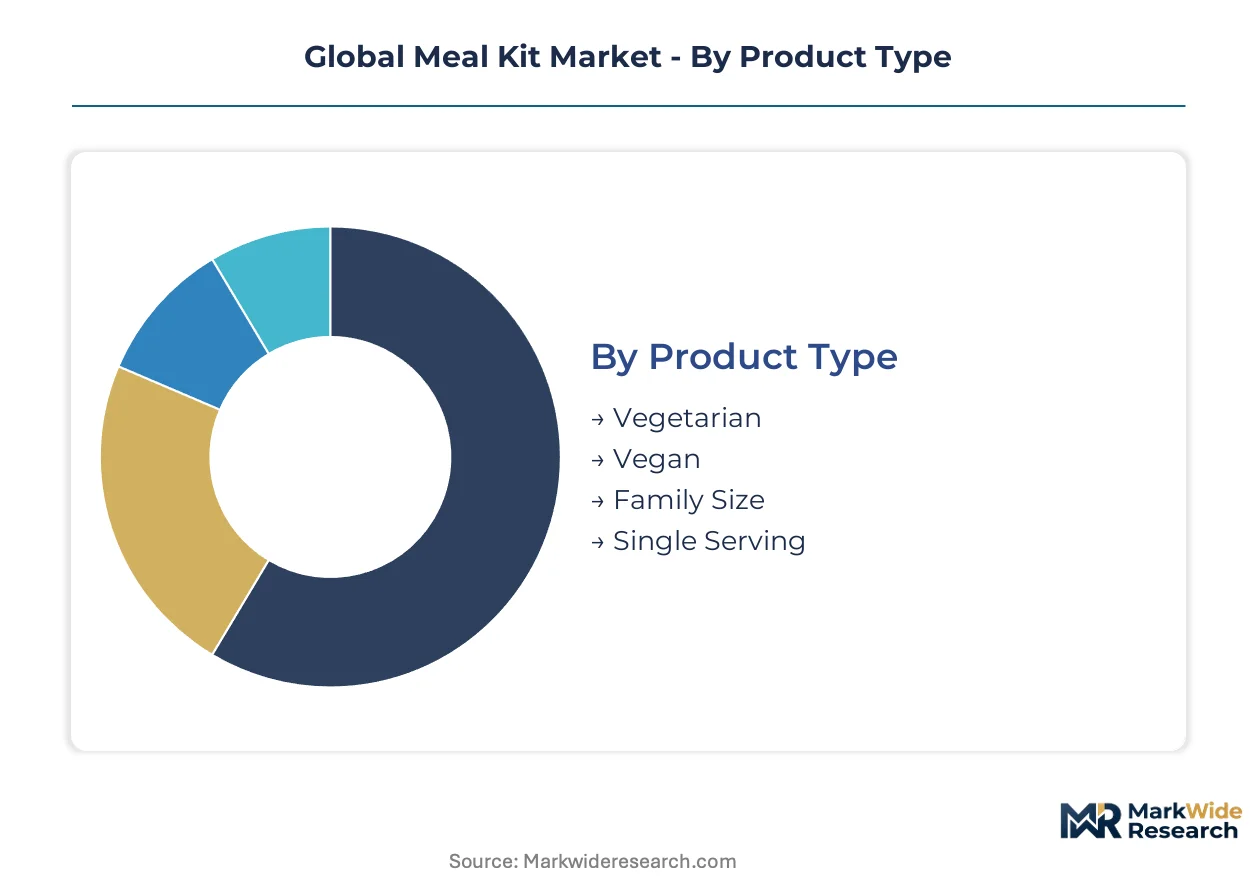
Meal kit segmentation reflects divergent operational economics across freshness requirements, portion precision, and fulfillment cadence. Each dimension shapes cold-chain infrastructure investments and customer acquisition costs differently.
Product Type:
Customization depth varies sharply across dietary specifications and household composition, with portion scalability determining packaging automation feasibility.
- Family Size:Multi-portion configurations optimize fulfillment labor through bulk ingredient staging and standardized recipe cards. Demand concentrates in suburban corridors of Dallas and Frankfurt where dual-income households with children prioritize volume efficiency over exotic variety.
- Single Serving:Individual portions require precise gram-level weighing and specialized thermal packaging for smaller chilled compartments. Urban density in Manhattan and central Tokyo sustains premium pricing despite higher per-unit logistics overhead.
- Vegetarian:Plant-forward kits reduce cold-chain complexity through extended produce shelf life and simplified protein sourcing from California and Dutch greenhouse suppliers.
- Vegan:Strict exclusion protocols demand segregated assembly lines and allergen-free certification tracking, concentrating production among specialized European commissaries.
Leading the category by volume: Family Size. Expanding most quickly: Single Serving.
Delivery Model:
Revenue predictability and fulfillment density trade off across commitment structures, with subscription mechanics dominating working capital planning.
- Subscription-Based:Recurring revenue streams enable demand forecasting algorithms that reduce ingredient waste below 3% at Rotterdam and Chicago distribution hubs. Locked-in delivery windows optimize route density for refrigerated courier fleets.
- One-Time Purchase:Gift-box and trial formats acquire customers without long-term commitment, requiring flexible inventory buffers that elevate per-order handling costs in Toronto and Sydney metro areas.
- Doorstep Delivery:Direct-to-home refrigerated transport remains the default fulfillment mode, constrained by last-mile cold-chain technician availability in competitive labor markets.
- Click-and-Collect:Locker-based pickup at urban retail partners eliminates failed delivery costs while transferring temperature liability to consumers, gaining traction in dense German and Japanese cities.
Subscription-Based commands the revenue base. One-Time Purchase climbs the fastest as acquisition funnel breadth expands.
Ingredient Type:
Certification depth drives supplier radius constraints and traceability system investments, with organic protocols imposing the most stringent chain-of-custody requirements.
- Organic:USDA and EU organic seals mandate three-year field history documentation and segregated handling infrastructure. Sunbasket's California and Pacific Northwest supplier relationships exemplify the agricultural radius compression this certification demands.
- Non-GMO:Identity preservation systems track corn and soy derivatives through processing stages, with verification costs concentrated in Midwest grain belt sourcing corridors.
- Locally Sourced:Sub-150-mile ingredient radii reduce transportation emissions while limiting menu variety to seasonal availability, thriving in Netherlands greenhouse clusters and California Central Valley proximity.
- Pre-Packaged:Shelf-stable sauces and spice blends simplify fulfillment but shift consumer perception toward processed convenience rather than fresh cooking.
Organic leads certification-driven premium tiers. Locally Sourced gains share fastest as carbon-accounting rules reshape procurement radii.
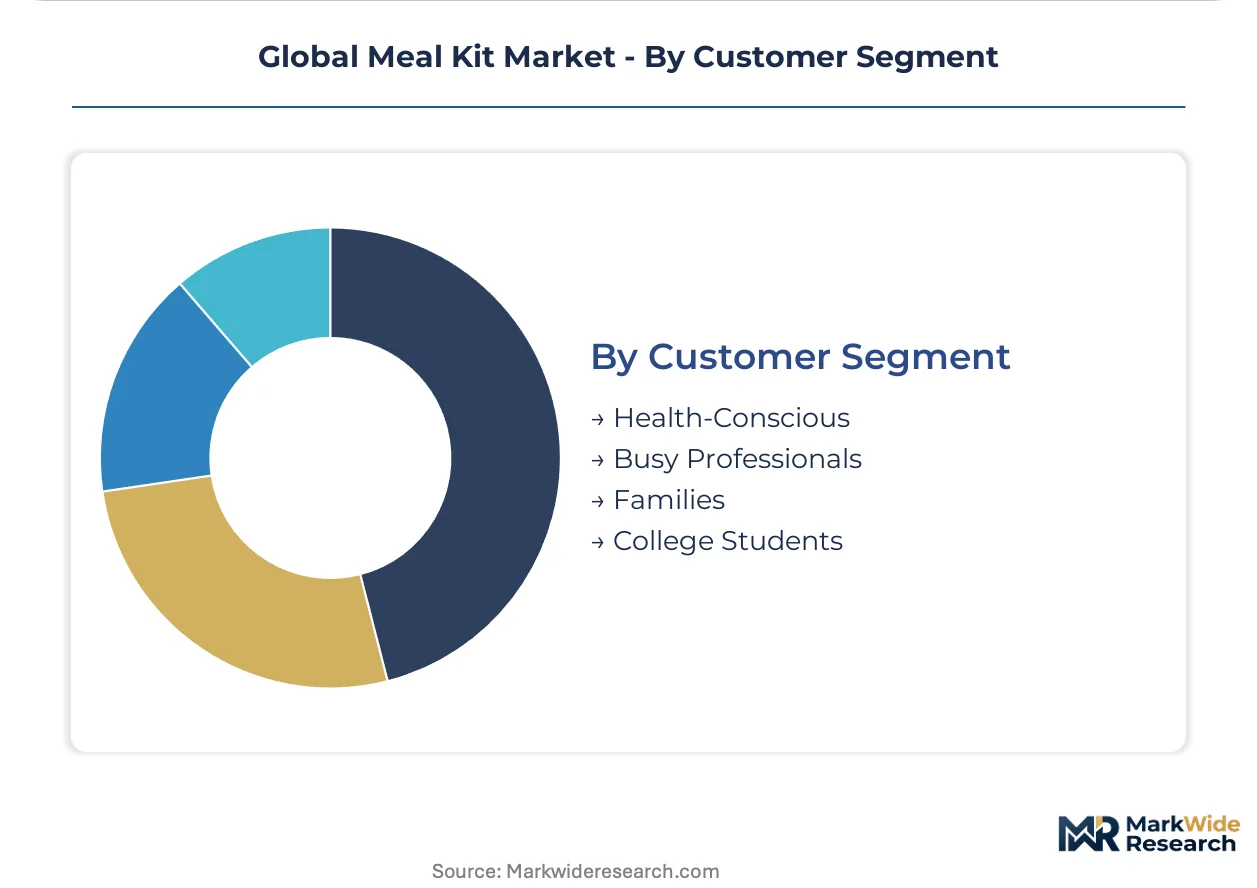
Customer Segment:
Life-stage and time-scarcity variables determine price sensitivity and retention patterns, with professional households converting most reliably to subscription mechanics.
- Busy Professionals:Time-scarcity in London and New York financial districts converts grocery shopping into outsourced meal assembly, with pause-friendly subscription terms reducing churn during travel-intensive quarters.
- Families:Multi-generational households in suburban Tokyo and Frankfurt prioritize portion scalability and child-friendly flavor profiles over dietary experimentation.
- Health-Conscious:Specialized dietetic requirements—diabetes-friendly and heart-healthy lines—command loyalty premiums but require nutritionist-validated recipe development and FDA-compliant health claims.
- College Students:Dormitory cooking constraints and budget sensitivity limit penetration, with micro-fridge compatibility and microwave-only preparation options constraining menu architecture.
Busy Professionals anchor subscription lifetime value. Health-Conscious segments show steepest expansion trajectory as specialized dietetic portfolios deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in refrigerated fulfillment corridors while consumption spreads across metropolitan zones with dual-income household density. Cold-chain infrastructure investments in Germany and the United States outpace secondary markets. Regulatory fragmentation across FDA, EFSA, and METI jurisdictions shapes operational compliance costs.
United States
Subscription penetration among professional households in Manhattan and Chicago sustains volume leadership. FDA Food Safety Modernization Act traceability mandates compress compliance timelines for mid-tier operators. Dallas distribution centers deploy robotic weighing systems that handle the majority of ingredient kit assembly.
Germany
EU Green Deal packaging directives accelerate compostable insulation transitions ahead of enforcement deadlines. REACH chemical restrictions on perfluorinated compounds force substrate shifts in grease-resistant meal trays. Düsseldorf fulfillment hubs leverage cross-border density economics to serve Dutch and French metropolitan corridors.
Japan
Time-scarcity among Tokyo professional couples converts traditional grocery shopping into subscription-based meal assembly services. METI energy-efficiency guidelines influence refrigerated logistics fleet specifications for last-mile courier networks. Osaka cold-storage capacity constraints limit expansion into secondary metropolitan zones.
United Kingdom
Pause-friendly membership structures reduce churn among London financial district households during travel-intensive quarters. EFSA contamination-control standards align with FDA protocols for operators serving transatlantic customer bases. Greater London urban density sustains premium pricing for single-serving formats despite higher per-unit logistics overhead.
Australia
Trial-oriented buyers in Sydney favor one-time gift boxes over rigid weekly commitments, expanding acquisition funnel breadth. Biodegradable material mandates from state-level environmental regulations accelerate supplier transitions. Melbourne distribution networks face refrigeration mechanic scarcity that commands premium wages in competitive logistics labor markets.
Global Meal Kit Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressures mount as scale-driven operators compress per-order handling costs through automation investments. Three strategic archetypes dominate: vertically integrated freshness specialists, technology-enabled platform aggregators, and dietetic portfolio differentiators. M&A activity targets regional fulfillment capabilities while strategic partnerships lock in organic supplier relationships across California and Pacific Northwest agricultural zones.
Within the freshness-specialist tier, Sunbasket and HelloFresh exemplify divergent geographic anchoring strategies. Sunbasket occupies a position tied to organic certification depth and controlled supplier relationships across California and Pacific Northwest zones. HelloFresh represents cross-border density economics through European fulfillment network leverage. Blue Apron sits within the dietetic-differentiation archetype, anchoring specialized portfolio positions including diabetes-friendly and heart-healthy lines.
| Leading Market Players |
|---|
| Sunbasket |
| EveryPlate |
| HelloFresh |
| Factor |
| Purple Carrot |
| Blue Apron |
| Green Chef |
| Freshly |
| Home Chef |
| Others |
Value Chain & Pricing Dynamics
Captive cold-chain infrastructure anchors supply position and pricing power for meal kit operators, with backward integration into refrigerated fulfillment networks insulating incumbents from third-party logistics rate volatility while enabling subscription-lock pricing premiums.
Pricing Analysis
Margin tightening in single-serving tiers reflects last-mile density penalties in Manhattan and Tokyo, where per-unit logistics overhead compresses contribution economics despite premium positioning. Three-tier pricing structure across organic certification, conventional fresh, and economy pre-packaged levels stratifies buyer segments, with health-conscious professionals showing lowest price sensitivity and college students highest. Cost-down pressure on family-size configurations accelerates as robotic assembly in Dallas and Düsseldorf distribution centers reduces handling costs.
Supply Chain Analysis
Returns of temperature-compromised kits and packaging materials flow back through regional distribution centers for compostable insulation recovery and ingredient redistribution to food banks. Ingredient sourcing concentrates in the United States, the Netherlands, and Japan, with fresh produce from California's Central Valley and Dutch greenhouse corridors anchoring supply. Protein inputs, specialty grains, and active packaging films draw from Midwest grain belts and German chemical suppliers. Single-source vulnerability in refrigerated logistics fleet capacity around Chicago, Rotterdam, and Osaka elevates risk. Distribution runs through centralized commissaries feeding regional cold-storage hubs before last-mile courier handoff.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Robotic portion-control automation is displacing manual assembly lines, with machine learning demand forecasting replacing static weekly menu rotations as the operational baseline.
For Market Incumbents: Cement cross-border density economics through European fulfillment network expansion, locking in Dutch and French metropolitan corridors before regional competitors achieve scale. Defend against quick-commerce grocery substitution by deepening AI-driven personalization that reduces waste ratios below retail benchmarks. Prioritize HACCP-certified workforce retention through premium wage structures in competitive logistics labor markets.
For New Entrants and Emerging Players: Corporate cafeteria partners represent the most penetrable channel, with hybrid work patterns redirecting employer food-service budgets toward home-delivered team meal programs. Target India's FSSAI-certified organized retail corridors in Bangalore and Mumbai where standardized food safety frameworks are opening temperature-controlled channels. Pursue click-and-collect locker partnerships with urban retail networks to eliminate failed delivery costs.
For Investors and Strategic Acquirers: Exit pathways concentrate in technology-enabled platform aggregators and dietetic portfolio differentiators, with consolidation pressures mounting as scale-driven operators compress per-order handling costs. Long-term viability favors vertically integrated freshness specialists controlling organic supplier relationships across California and Pacific Northwest agricultural zones. Monitor FDA Food Safety Modernization Act traceability compliance timelines as an inflection indicator for mid-tier operator distress.
| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Assembly Deployment | Dallas and Düsseldorf distribution centers now automate 70% of kit weighing and bagging under FDA contamination-control standards. |
| Compostable Packaging Transition | German and Dutch operations accelerate molded fiber tray adoption ahead of EU Green Deal enforcement deadlines. |
| AI Demand Forecasting Integration | Machine learning inventory optimization converges with dynamic recipe personalization to reduce waste ratios below traditional retail benchmarks. |
| Corporate Team Meal Programs | Hybrid work patterns redirect employer food-service budgets toward subscription-based home delivery for distributed workforces. |
| Organic Supplier Relationship Lock-in | Controlled agricultural partnerships across California and Pacific Northwest zones compress certification-driven procurement radii. |
Study Parameters
Independent corroboration across cold-chain logistics operators, meal kit commissary managers, and refrigerated courier fleet supervisors underwrites the qualitative findings, validated against EU customs trade data, FDA food facility registration records, and METI energy-efficiency disclosure filings. Bottom-up assembly of distribution center capacity and subscription account data triangulates against top-down retail audit estimates from Nielsen and Circana.
Rate-of-change decomposition across the projection horizon segments volume trajectories by product type, delivery model commitment structure, ingredient certification tier, and metropolitan household density. CAGRs derive from logistic curve adoption modeling calibrated to dual-income professional penetration patterns and cold-storage infrastructure buildout timelines.
Caveats apply where FDA traceability rule enforcement delays, perishable input cost volatility from California Central Valley weather patterns, or quick-commerce grocery app substitution could materially shift the outlook. Practitioners should monitor refrigerated logistics technician wage inflation and biodegradable packaging supplier readiness for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Singapore Food Service Market
Food Service
United Kingdom Foodservice Market
Food Service
Canada Food Service Market
Food Service
Retail Bubble Tea Kits Market
Food Service
US Healthcare/Hospital Food Services Market
Food Service
Restaurant Glassware Market
Food Service
Asia-Pacific Food Away from Home Market
Food Service
Switzerland Food Service Market
Food Service
Spain Food Service Market
Food Service
United Kingdom Quick Service Restaurant Market
Food Service
Steam Stew Pot Market
Food Service
Italy Foodservice Market
Food Service
Personal Chef Services Market
Food Service
Saudi Arabia Full- Service Restaurants Market
Food Service
Qatar Food Service Market
Food Service
Global Self Heating Instant Hot Pot Market