
 Food Service Market | 2026-2036
Food Service Market Size, Share, and Industry Trends Forecast 2026-2036
Food Service Market Intelligence
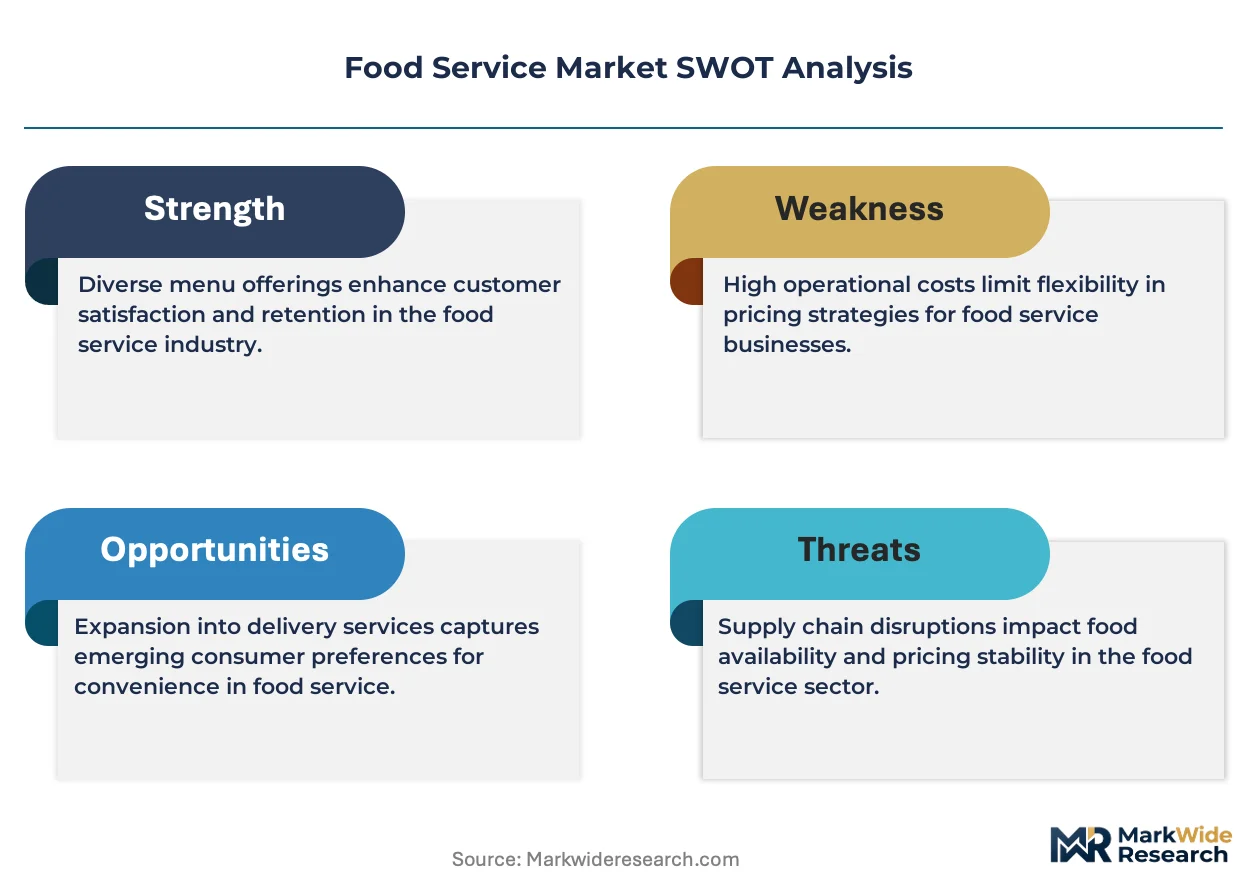
Corporate catering clients are unwinding traditional contract structures as institutional buyers shift spend toward flexible, on-demand formats. Sodexo anchors large-scale managed services across North American and European education and healthcare campuses. Compass Group leverages its geographic breadth to sustain volume across British, Australian, and French institutional kitchens. Sysco Corporation dominates wholesale distribution through its captive trucking network and direct sales force covering independent restaurants.
Food service encompasses the commercial preparation, delivery, and sale of ready-to-consume meals and beverages through organized outlets, with operational parameters governed by HACCP temperature controls, allergen labeling protocols, and real-time inventory management systems. Its primary commercial purpose is to externalize meal production for away-from-home consumption across institutional, hospitality, and individual buyer contexts. Quick Service Restaurants lead transaction volume globally, while Catering Services command premium margins through event-based pricing and bespoke menu development. Third-Party Delivery platforms are displacing direct sales as the fastest-growing distribution channel, though Franchise Operations retain superior unit economics and brand consistency control.
The FDA enforces Hazard Analysis and Critical Control Points standards across US commercial kitchens, while the EU Green Deal's packaging waste directives are forcing European operators toward reusable container systems and carbon-labeled menus. India's FSSAI mandates licensing and hygiene ratings for all food business operators, tightening market access for unorganized street vendors. Stakeholders must monitor how AI-driven dynamic pricing and ghost kitchen consolidation reshape capital allocation between physical dining footprints and delivery-only production nodes.
Market Dynamics
Third-party delivery platforms are decomposing the traditional restaurant value chain by inserting algorithmic intermediaries between production and consumption, forcing operators to surrender margin control and customer data access to aggregator networks.
Growth Catalysts
- Urban Food Delivery Corridors:Dense metropolitan zones in India concentrate demand through hyperlocal logistics networks, compressing delivery windows and expanding addressable meal occasions beyond traditional dining hours.
- FSMA Traceability Mandates:The FDA's updated Food Safety Modernization Act rules mandate granular lot-tracking across supply chains, accelerating technology adoption among mid-scale operators seeking compliance automation.
- Ghost Kitchen Consolidation:Delivery-only production nodes reduce real estate costs and enable rapid menu iteration, attracting capital from operators exiting high-street dining footprints.
Market Restraints
- Input Cost Volatility:Proteins and cooking oils face commodity price swings that compress menu margin flexibility, particularly for fixed-price contract catering agreements.
- Regulatory Friction:India's FSSAI licensing requirements and hygiene rating systems impose compliance timelines that exclude unorganized street vendors from formal market participation.
- Supply Concentration Risk:Wholesale distribution networks concentrate in captive trucking territories, limiting independent restaurant access to competitive sourcing alternatives.
Strategic Opportunities
- Corporate Catering Pivot:Institutional buyers in North America unwind rigid contract structures in favor of flexible, on-demand formats that accommodate hybrid workforce scheduling.
- EU Green Deal Tailwind:Packaging waste directives accelerate reusable container system deployment and carbon-labeled menu development, creating differentiation for early adopters.
- AI-Driven Dynamic Pricing:Machine learning algorithms optimize revenue per available seat-hour by adjusting menu prices in real-time based on demand signals and inventory positions.
Industry Challenges
- HACCP Certification Timelines:Hazard Analysis and Critical Control Points implementation requires specialized personnel and documentation systems that strain smaller operator resource bases.
- Legacy System Integration:Real-time inventory management platforms face friction when interfacing with established point-of-sale and accounting architectures.
- Temperature Control Compliance:Cold chain maintenance across distributed delivery networks demands capital investment in sensor infrastructure and monitoring protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Service Market |
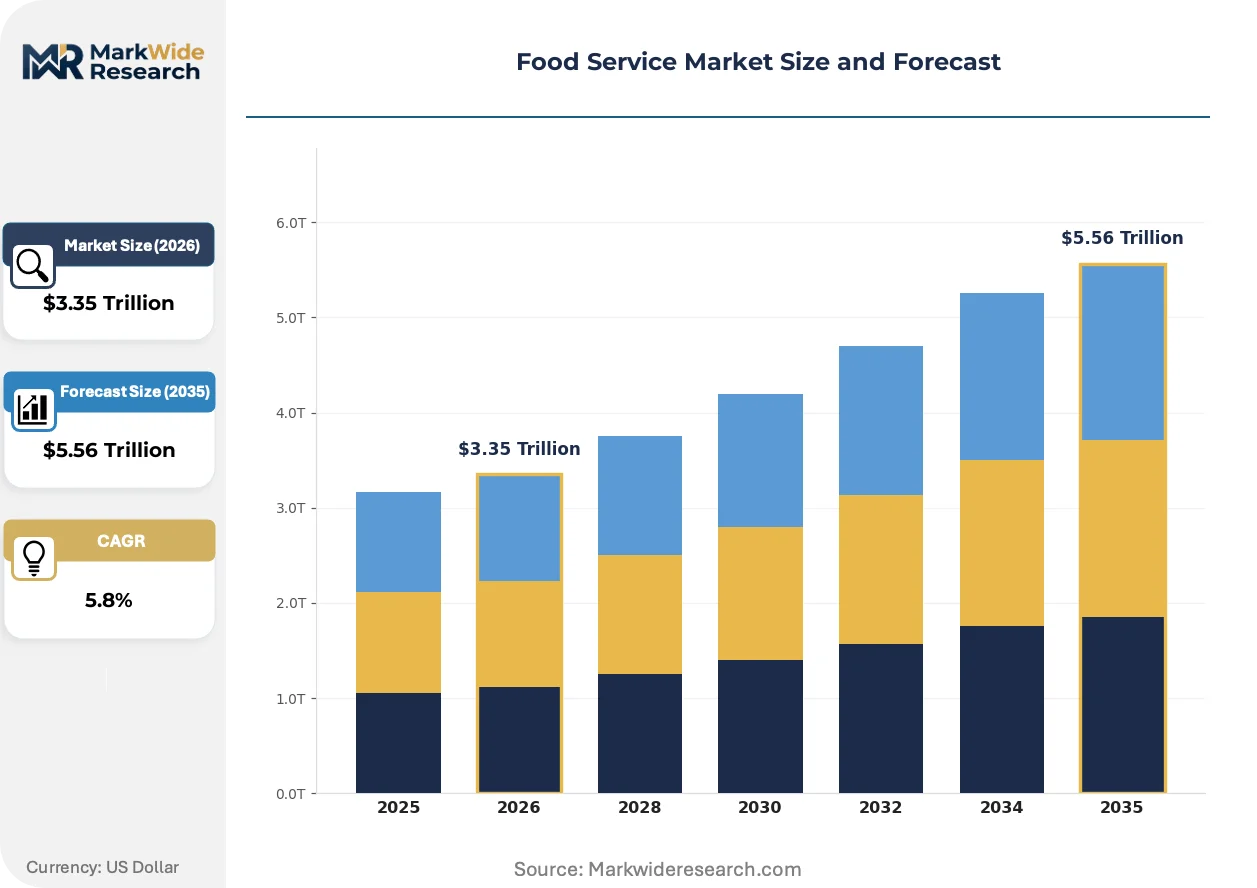
| Market Size in 2026 | $3.35 Trillion |
| Market Size in 2035 | $5.56 Trillion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Restaurants, Quick Service Restaurants, Cafeterias, Catering Services, Food Trucks, Vending Services Customer Type: Individuals, Corporate Clients, Institutions, Hospitality Providers, Educational Facilities, Event Organizers Distribution Channel: Direct Sales, Online Ordering Platforms, Third-Party Delivery, Wholesale Suppliers, Franchise Operations, Mobile Apps Product Offering: Ready-to-Eat Meals, Beverage Services, Bakery Items, Frozen Foods, Health-Oriented Products, Ethnic Cuisine |
| Companies Covered | McDonald's, Subway, Aramark, LSG Sky Chefs, Sodexo, Compass Group, Starbucks, Dunkin', Sysco Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Service Market Strategic Shifts & Innovations
Operational technology is fragmenting production from service location, enabling capital-light market entry while eroding traditional location-based competitive moats. This structural separation demands new competency development around logistics orchestration and digital customer acquisition.
Cloud-based kitchen management software is decomposing the integrated restaurant model by enabling independent operators to share production infrastructure, reduce equipment capex, and access aggregated purchasing power. Mid-scale restaurant groups deploy these platforms to test market expansion without property commitments. The technology is compressing the minimum viable scale for multi-unit operations and accelerating format experimentation cycles.
The EU Green Deal's packaging waste directives are mandating reusable container systems and carbon-labeled menus across European commercial kitchens. Operators face retrofit costs for inventory tracking and supplier certification documentation. Full-service restaurants in France and Germany respond by redesigning takeout offerings around returnable packaging partnerships and localized sourcing verification.
Corporate procurement departments are fragmenting food service spend across multiple on-demand platforms rather than consolidating under single managed service contracts. This pattern compresses vendor switching costs and elevates price transparency, particularly visible in North American technology sector campuses where employees select individual meal allowances through mobile applications. Catering providers respond with modular menu components and event-based pricing structures.
Food Service Market Segmentation
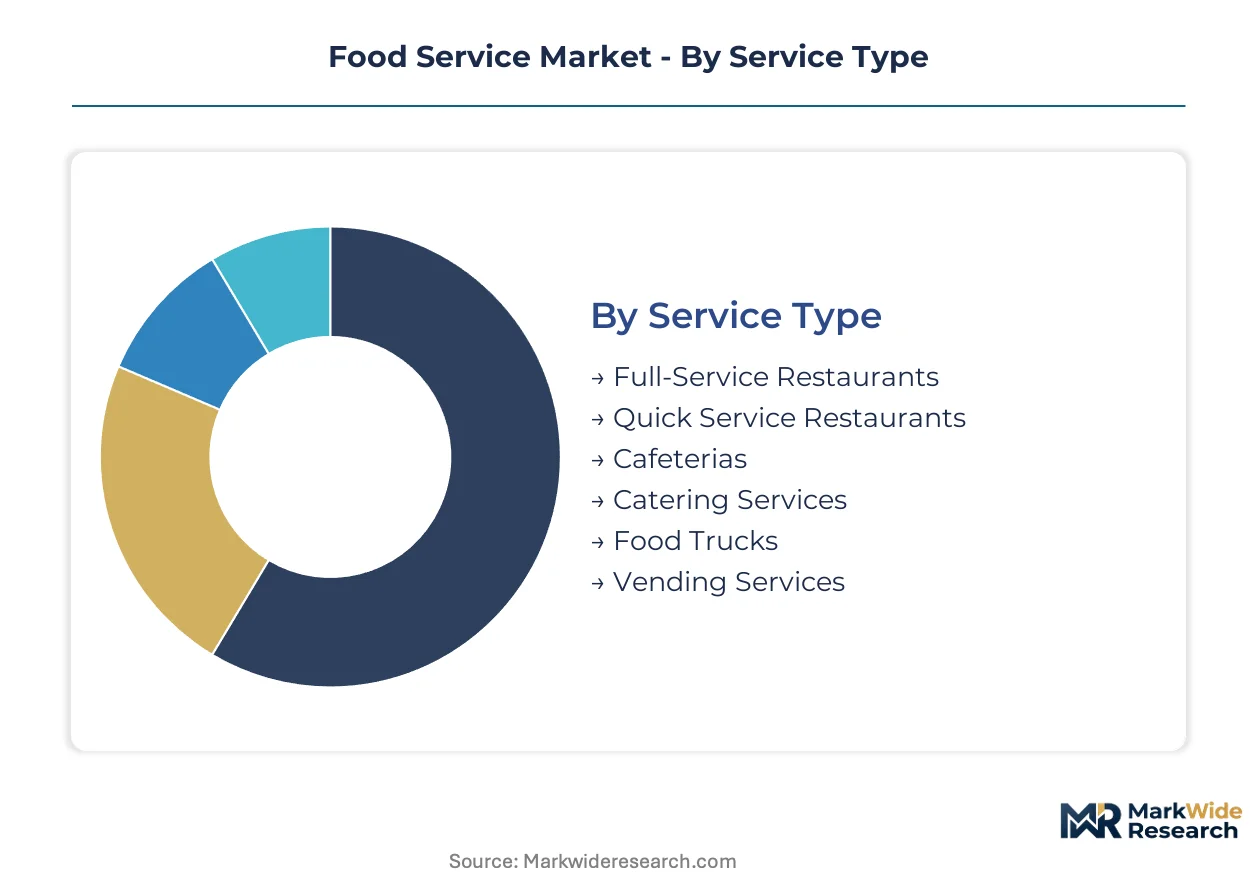
Food service segmentation reveals how production formats, buyer archetypes, and distribution pathways allocate margin and risk across the value chain. Channel-mix decisions determine whether operators capture direct customer relationships or surrender data access to platform intermediaries.
Service Type:
Channel-mix dynamics vary sharply across service formats, with table-service models retaining direct customer data while limited-service formats optimize throughput velocity.
- Full-Service Restaurants:Table-service formats with extended dwell times and higher per-cover spending concentrate in urban hospitality corridors and premium suburban clusters. US operators face FDA HACCP documentation burdens that favor multi-unit groups with dedicated compliance personnel.
- Quick Service Restaurants:Limited-service formats optimize throughput velocity through standardized menu architectures and drive-through infrastructure. India's urban food delivery corridors concentrate demand for these formats, with franchise operations expanding through cloud kitchen partnerships to reduce real estate exposure.
- Cafeterias:Self-service institutional formats serving captive populations in workplace and educational settings.
- Catering Services:Event-based production with bespoke menu development and premium pricing structures.
- Food Trucks:Mobile production units leveraging lower capital entry thresholds and location flexibility.
- Vending Services:Automated retail formats for constrained-access environments with extended operating hours.
By volume, Quick Service Restaurants lead. By growth pace, Catering Services is expanding most quickly through corporate on-demand procurement shifts.
Customer Type:
Margin profiles diverge sharply across buyer archetypes, with institutional contracts offering volume certainty at compressed yields while individual transactions command premium pricing with higher churn.
- Corporate Clients:Institutional buyers unwinding rigid managed service contracts in favor of flexible, platform-mediated meal allowances. North American technology sector campuses drive demand for modular menu components and event-based pricing structures.
- Individuals:Fragmented consumer demand channeled through mobile applications and third-party delivery platforms. India's hyperlocal logistics networks compress delivery windows and expand addressable meal occasions beyond traditional dining hours.
- Institutions:Healthcare and government facilities with extended contract horizons and stringent compliance requirements.
- Hospitality Providers:Hotels and resorts outsourcing food production to specialized operators.
- Educational Facilities:K-12 and university dining programs with seasonal demand volatility and nutritional mandate constraints.
- Event Organizers:One-time buyers with high service expectations and compressed planning timelines.
Corporate Clients anchor revenue stability. Individuals are gaining share fastest as platform penetration deepens.
Distribution Channel:
Control over customer relationships and transaction data separates channels that preserve operator autonomy from those that commoditize production.
- Third-Party Delivery:Algorithmic intermediaries inserting between production and consumption, forcing margin surrender and data access loss. EU operators face additional packaging waste directive compliance costs for container standardization across aggregator networks.
- Direct Sales:Operator-controlled channels preserving full margin capture and customer relationship ownership. Full-service restaurants in France and Germany leverage direct channels to deploy reusable container systems and carbon-labeled menus.
- Online Ordering Platforms:Operator-owned digital interfaces with lower commission structures than aggregator alternatives.
- Wholesale Suppliers:B2B procurement channels for institutional and multi-unit operators.
- Franchise Operations:Brand-licensed expansion with standardized operating procedures and supply chain integration.
- Mobile Apps:Proprietary customer interfaces enabling loyalty program deployment and direct marketing.
Direct Sales still dominates transaction value. Third-Party Delivery shows the steepest expansion trajectory as urban density increases.
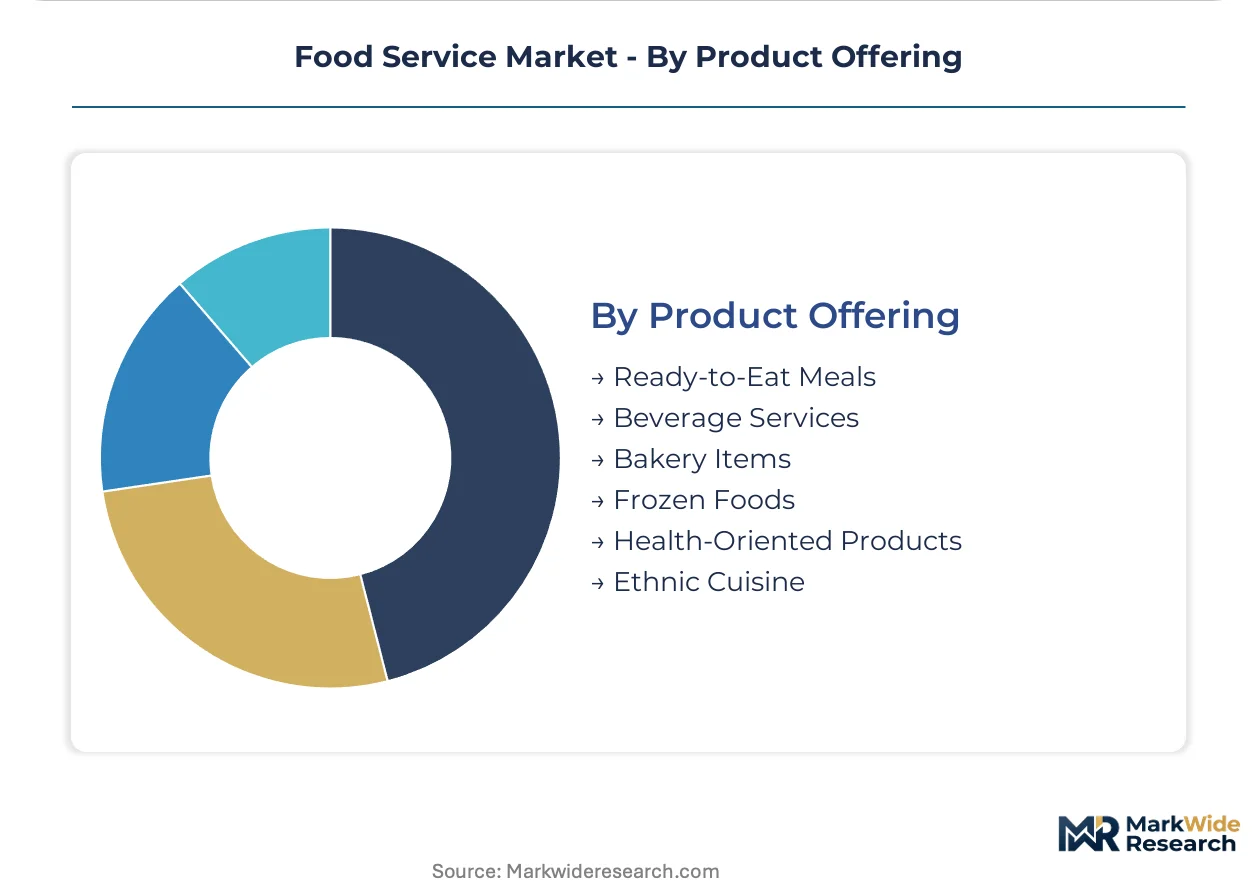
Product Offering:
Production complexity and perishability constraints shape which product categories flow through which service and channel combinations.
- Ready-to-Eat Meals:Fresh-prepared items with compressed shelf life demanding temperature-controlled logistics. Ghost kitchen consolidation accelerates format experimentation for these products, reducing real estate costs and enabling rapid menu iteration.
- Health-Oriented Products:Nutritionally positioned offerings with ingredient transparency requirements and premium pricing. EU Green Deal carbon labeling mandates create differentiation opportunities for verified sourcing claims.
- Beverage Services:High-margin add-on sales with lower preparation complexity.
- Bakery Items:Production-forward categories with equipment specialization requirements.
- Frozen Foods:Extended-shelf-life products with distribution flexibility and lower waste rates.
- Ethnic Cuisine:Differentiated menu architectures requiring specialized ingredient sourcing and culinary expertise.
Ready-to-Eat Meals command the largest revenue pool. Health-Oriented Products are climbing the fastest as regulatory disclosure requirements expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European food service supply chains, handling containerized food imports that feed distribution networks across Germany and neighboring markets. Rail corridors connect this hub to cold storage facilities in the Ruhr industrial belt.
United States
Corporate catering demand from technology sector campuses drives format experimentation, with hybrid workforce patterns fragmenting traditional contract structures. The FDA enforces updated Food Safety Modernization Act traceability mandates that accelerate technology adoption among mid-scale operators. New York City's dense urban corridors concentrate ghost kitchen consolidation as operators exit high-street dining footprints.
Germany
Institutional kitchen outsourcing across healthcare and education facilities sustains volume for managed service operators. The EU Green Deal's packaging waste directives mandate reusable container systems and carbon-labeled menus, imposing retrofit costs for inventory tracking. Berlin-Brandenburg's metropolitan zone hosts early adopters redesigning takeout offerings around returnable packaging partnerships.
India
Urban food delivery corridors in Mumbai, Bangalore, and Delhi compress delivery windows through hyperlocal logistics networks. The FSSAI mandates licensing and hygiene ratings that exclude unorganized street vendors from formal market participation. Maharashtra's Mumbai-Pune corridor anchors franchise expansion through cloud kitchen partnerships reducing real estate exposure.
France
Full-service restaurants command premium positioning through extended dwell times and higher per-cover spending in urban hospitality corridors. EU Green Deal carbon labeling requirements create differentiation opportunities for verified sourcing claims. Paris and Lyon concentrate operator investment in localized supply chain verification and reusable container system deployment.
United Kingdom
Compass Group leverages geographic breadth to sustain institutional kitchen volume across British education and healthcare campuses. Post-Brexit regulatory divergence complicates cross-border supplier certification documentation for multi-national operators. London's metropolitan zone leads third-party delivery platform penetration, forcing margin surrender to algorithmic intermediaries.
Food Service Market Key Industry Players
Listed leaders compete with private specialists across contract structures, with publicly traded giants facing pressure from agile platform-native entrants. The market structure concentrates around three archetypes: multi-national managed service operators with captive institutional relationships, wholesale distributors controlling captive trucking networks, and platform-dependent restaurant brands surrendering customer data access to aggregators. Dominant competitive moves include ghost kitchen consolidation to reduce real estate exposure and AI-driven dynamic pricing deployment to optimize revenue per available seat-hour.
Within the managed services tier, Sodexo and Compass Group exemplify institutional-scale operators anchoring large-scale contracts across education and healthcare campuses. Among wholesale distributors, Sysco Corporation occupies a position representing captive logistics control through direct sales force coverage of independent restaurants. These three entities collectively represent the spectrum from relationship-heavy contract catering to infrastructure-dominated supply chain intermediation.
| Leading Market Players |
|---|
| McDonald's |
| Subway |
| Aramark |
| LSG Sky Chefs |
| Sodexo |
| Compass Group |
| Starbucks |
| Dunkin' |
| Sysco Corporation |
| Others |
Cost & Logistics Intelligence
Long-term fixed-price catering contracts lock in supply access for institutional buyers while constraining operator margin flexibility when commodity inputs swing. These agreements concentrate pricing power with wholesale distributors controlling captive logistics networks across North America and Europe.
Pricing Analysis
Volume-discount tiering structures separate enterprise contract catering from individual transaction pricing, with corporate accounts commanding steep rebates for committed volume. Price differentiation rests on HACCP certification grade and geographic delivery density, with urban corridor operators capturing premium positioning. Cost compression in mid-scale contract catering intensifies as protein and cooking oil volatility strains fixed-price commitments. Quick Service Restaurants exhibit highest price sensitivity due to thin per-transaction margins, while bespoke catering services maintain lowest sensitivity through event-based premium positioning.
Supply Chain Analysis
Cold storage chokepoints at the Port of Hamburg and Rotterdam anchor European food service distribution, with rail corridors feeding inland consolidation centers. Supply concentration centers on the United States, Brazil, and Argentina for proteins; Indonesia and Malaysia for cooking oils; and the Netherlands for specialized dairy inputs. Single-source vulnerability runs through Sysco Corporation's captive trucking territories limiting independent restaurant sourcing alternatives. Distribution runs through wholesale distributors with direct sales force coverage dominating institutional procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corporate procurement fragmentation creates white-space opportunities across on-demand platform niches as institutional buyers abandon rigid managed service contracts. This demand-side shift rewards agile operators capable of modular menu assembly and rapid format pivoting.
For Market Incumbents: Secure HACCP-certified ghost kitchen infrastructure in India's Mumbai-Pune corridor to defend against cloud kitchen entrants eroding franchise unit economics. Consolidate backward integration into protein sourcing to offset commodity volatility compressing contract catering margins.
For New Entrants and Emerging Players: AI-driven dynamic pricing services for mid-scale restaurant groups represent an underserved layer where legacy POS systems create integration friction. India's urban food delivery corridors offer the most penetrable geography given FSSAI licensing barriers excluding unorganized vendors. Pursue white-label kitchen management software partnerships with franchise operators seeking rapid menu iteration capabilities.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform-native entrants with algorithmic pricing capabilities over relationship-heavy contract caterers. Long-term viability favors operators controlling direct customer data channels rather than aggregator-dependent brands. Watch EU Green Deal packaging compliance cost trajectories as the inflection signal separating early adopter margins from laggard retrofit burdens.
| Strategic Initiative | Industry Significance |
|---|---|
| Ghost Kitchen Consolidation | Reduces real estate exposure while enabling rapid menu testing for delivery-only formats. |
| AI-Driven Dynamic Pricing | Optimizes revenue per available seat-hour using demand signals from POS systems. |
| Reusable Container System Deployment | EU Green Deal compliance creates differentiation for French and German early adopters. |
| Backward Integration into Proteins | Captive sourcing mitigates commodity volatility threatening fixed-price contract margins. |
| Cloud Kitchen Partnership Expansion | Franchise operators in India leverage shared production infrastructure to reduce capex. |
Research Approach
Operator-level perspectives from contract catering procurement directors, ghost kitchen facility managers, third-party delivery platform strategists, and FSSAI compliance officers anchored the qualitative base. Secondary validation drew from FDA FSMA traceability guidance documents, EU Green Deal packaging directive filings, FSSAI licensing databases, and SEC 10-K disclosures from listed food service distributors. Bottom-up unit economics modeling triangulated against top-down market sizing from customs trade data and institutional procurement contract registries.
Sensitivity analysis tested volume assumptions across service type, customer archetype, and distribution channel dimensions throughout the forecast period. The analytical framework modeled Quick Service Restaurant throughput velocity, Catering Services event-based pricing structures, and Third-Party Delivery commission structures as core segmentation drivers. CAGRs were derived from trend extrapolation of urban delivery corridor density metrics and ghost kitchen capacity expansion rates, cross-referenced against FSSAI licensing growth trajectories.
Forecasts assume regulatory continuity in FDA FSMA traceability enforcement and EU Green Deal packaging mandates; material policy shifts would require re-modeling compliance cost trajectories. Specific risks include FSSAI licensing timeline extensions excluding vendor categories, and commodity price spikes breaching fixed-price contract buffers. Practitioners should keep alternative scenarios live as hybrid workforce attendance patterns and aggregator commission structures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Self-Heating Hot Pot Market
Food Service
Malaysia Food Service Market
Food Service
Latin America Airport Quick Service Restaurant Market
Food Service
France Foodservice Market
Food Service
United States Foodservice Market
Food Service
Galley Equipment Market
Food Service
India Retail Bubble Tea Kits Market
Food Service
Pasteurized Eggs Market
Food Service
GCC Biodegradable Food Service Disposables Market
Food Service
United States Food Truck Market
Food Service
Ice Cream Carts Market
Food Service
Global Cafe and Bars Market
Food Service
Bottled Water Cooler Market
Food Service
Commercial Tandoor Oven Market
Food Service
China Inflight Catering Market
Food Service
Stirrers Market