
 Global Vending Machine Market | 2026-2036
Global Vending Machine Market Size, Share, and Industry Trends Forecast 2026-2036
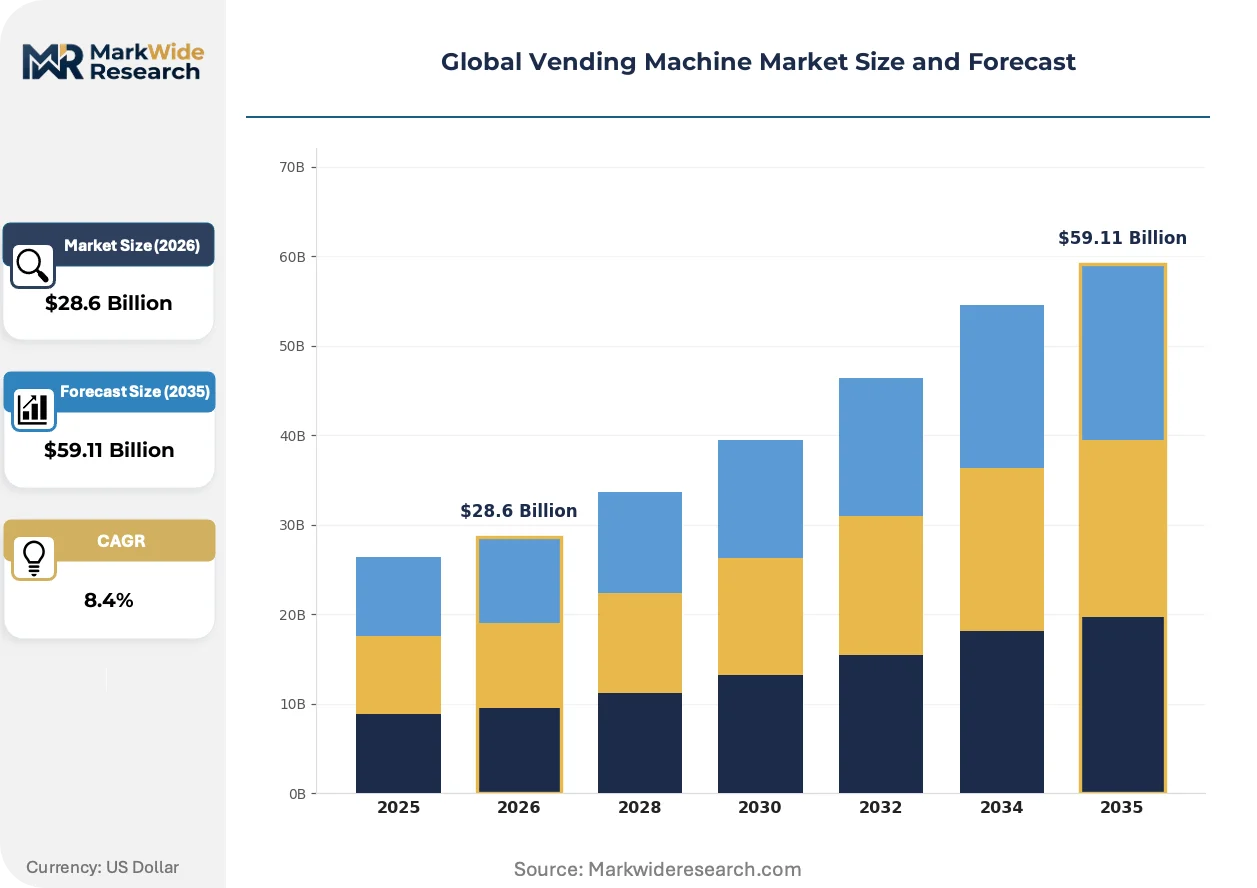
Global Vending Machine Market Outlook
ISO 9001 quality management certification is redrawing competitive boundaries for vending equipment suppliers. Fuji Electric Co., Ltd. leverages its refrigeration heritage to dominate temperature-controlled fresh food dispensers. Crane Merchandising Systems anchors North American market presence through extensive distributor networks and in-house manufacturing depth.
Vending machines are self-service automated retail units that dispense products through mechanical or electronic selection systems, typically incorporating refrigeration units maintaining temperatures between 2°C and 8°C for perishable goods. These machines serve commercial and institutional buyers seeking labor-minimized point-of-sale distribution. Beverage and snack configurations still occupy the largest installed base, though healthy options and fresh food segments are attracting premium positioning as workplace wellness programs expand. Smart vending technology with real-time inventory telemetry is capturing disproportionate R&D investment as operators seek to reduce stockout-driven revenue loss.
FDA food safety standards, EU Ecodesign Directive efficiency mandates, and Japan's METI appliance quality regulations collectively determine which manufacturers gain market access and which product configurations justify capital deployment. China's GB standards for electronic payment security and India's BIS certification for electrical safety add further compliance layers for cross-border suppliers. Stakeholders must weigh energy efficiency upgrade cycles against cashless payment integration timelines when prioritizing capital allocation across geographic portfolios.
Market Dynamics
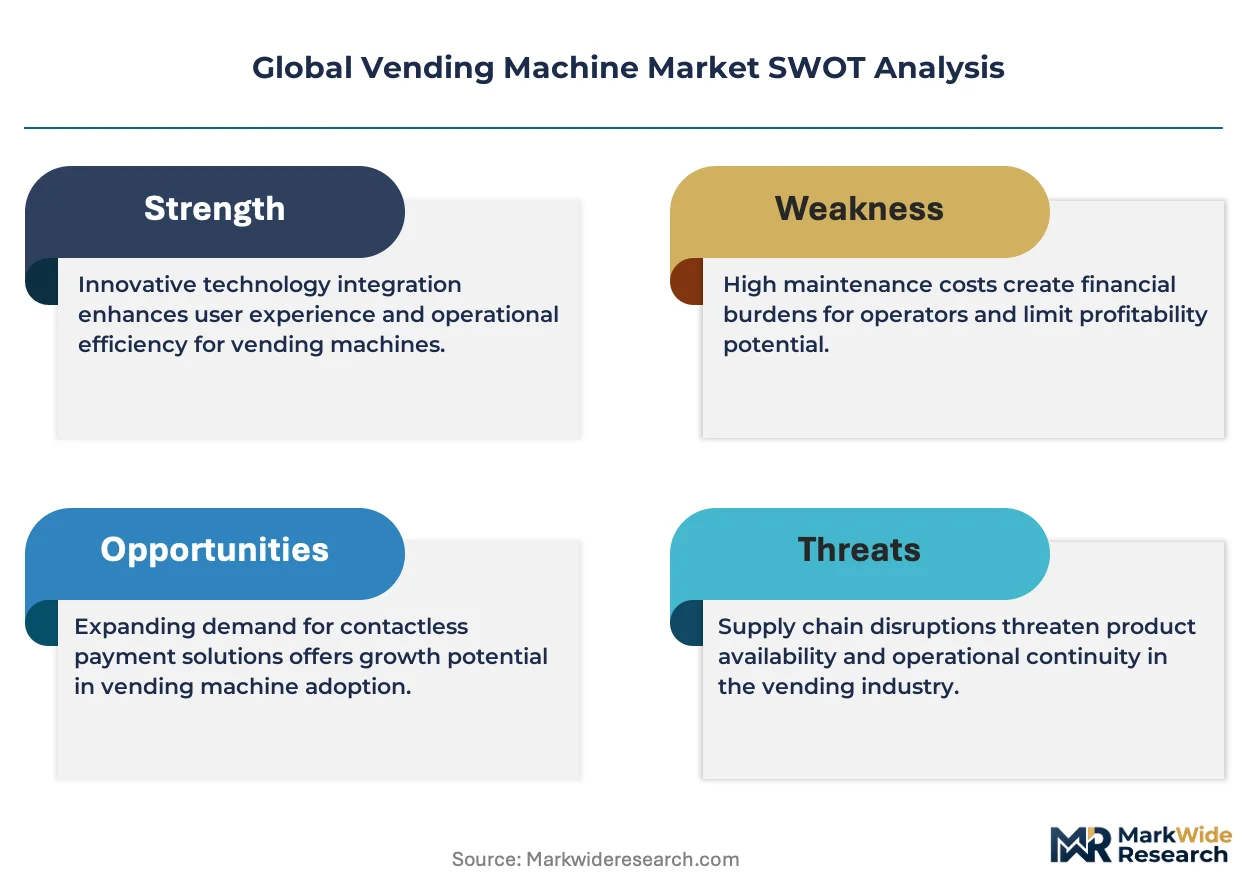
Cashless payment integration is compressing equipment replacement cycles as operators face simultaneous pressure from EU energy efficiency mandates and telemetry hardware upgrade requirements. This dual-technology squeeze favors suppliers with modular retrofit architectures over full-system replacement vendors.
Growth Catalysts
- Japan's METI appliance quality regulations:Stringent reliability standards are filtering out low-tier manufacturers and concentrating procurement among certified suppliers with proven field performance.
- High-speed rail station networks:China's expanding intercity rail infrastructure is creating captive foot-traffic environments where fresh-food vending achieves premium throughput.
- Computer vision checkout:Camera-based product recognition is eliminating mechanical dispensing complexity and expanding viable product categories beyond traditional packaging constraints.
Market Restraints
- Refrigeration compressor supply:European and Japanese compressor manufacturers command 70%+ of global capacity, creating input bottleneck vulnerability for mid-tier equipment assemblers.
- EU F-Gas Regulation phase-down:Hydrofluorocarbon refrigerant restrictions are forcing costly cooling system redesigns and compressing margin structures for existing product lines.
- Fresh food spoilage risk:Temperature excursion liability and shortened shelf-life logistics impose operational complexity that snack-and-beverage configurations avoid entirely.
Strategic Opportunities
- India's railway station modernization:The Dedicated Freight Corridor and station redevelopment programs are opening institutional procurement channels with 10-year concession frameworks.
- Workplace wellness program integration:Corporate facilities managers are specifying healthy-option vending as employee benefit infrastructure, creating specification pull-through distinct from traditional retail.
- IoT telemetry and predictive restocking convergence:Real-time inventory data married to route optimization software is enabling vending-as-a-service business models that transfer capital burden from operators to equipment suppliers.
Industry Challenges
- Multi-certification sequencing:ISO 9001 quality management, electrical safety, and food contact material approvals require 14-18 month parallel tracks that delay market entry.
- Legacy mechanical estate retrofit:Installed base of 1990s-era machines lacks connectivity architecture, forcing operators into binary capex decisions between upgrade modules and full replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vending Machine Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Beverages, Fresh Food, Healthy Options End User: Offices, Schools, Hospitals, Public Places Technology: Smart Vending, Cashless Payment, Traditional, Hybrid Sales Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | SandenVendo, Seaga Manufacturing, Inc., Fuji Electric Co., Ltd., Westomatic Vending Services Ltd., Glory Ltd., Crane Merchandising Systems, Royal Vendors, Inc., Cantaloupe Inc., Azkoyen Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vending Machine Market Strategic Shifts
Payment architecture, refrigeration chemistry, and inventory intelligence are converging to redefine equipment specifications. Operators now prioritize retrofit-friendly platforms over purpose-built systems.
Dynamic pricing algorithms are fragmenting traditional fixed-price vending economics. Cloud-connected machines adjust SKU pricing by hour, weather, and inventory age. Airport operators in Singapore and Dubai are piloting surge pricing for premium beverages during flight-delay windows. This capability is compressing margin recovery timelines for slow-moving products while demanding real-time connectivity infrastructure.
The EU Ecodesign Directive is mandating minimum energy performance standards for refrigerated vending equipment. Manufacturers must demonstrate coefficient of performance thresholds or face market exclusion. German and Italian suppliers are accelerating natural refrigerant adoption to preempt 2027 enforcement deadlines, while Asian exporters face certification lag risks.
Corporate procurement teams are consolidating vending contracts under integrated facilities management umbrellas. Single-source agreements covering cleaning, security, and refreshment services are displacing standalone vending operators. This bundling is most advanced in London and New York financial districts, where building management companies specify equipment-as-a-service terms with uptime guarantees rather than capital purchase models.
Global Vending Machine Market Segmentation
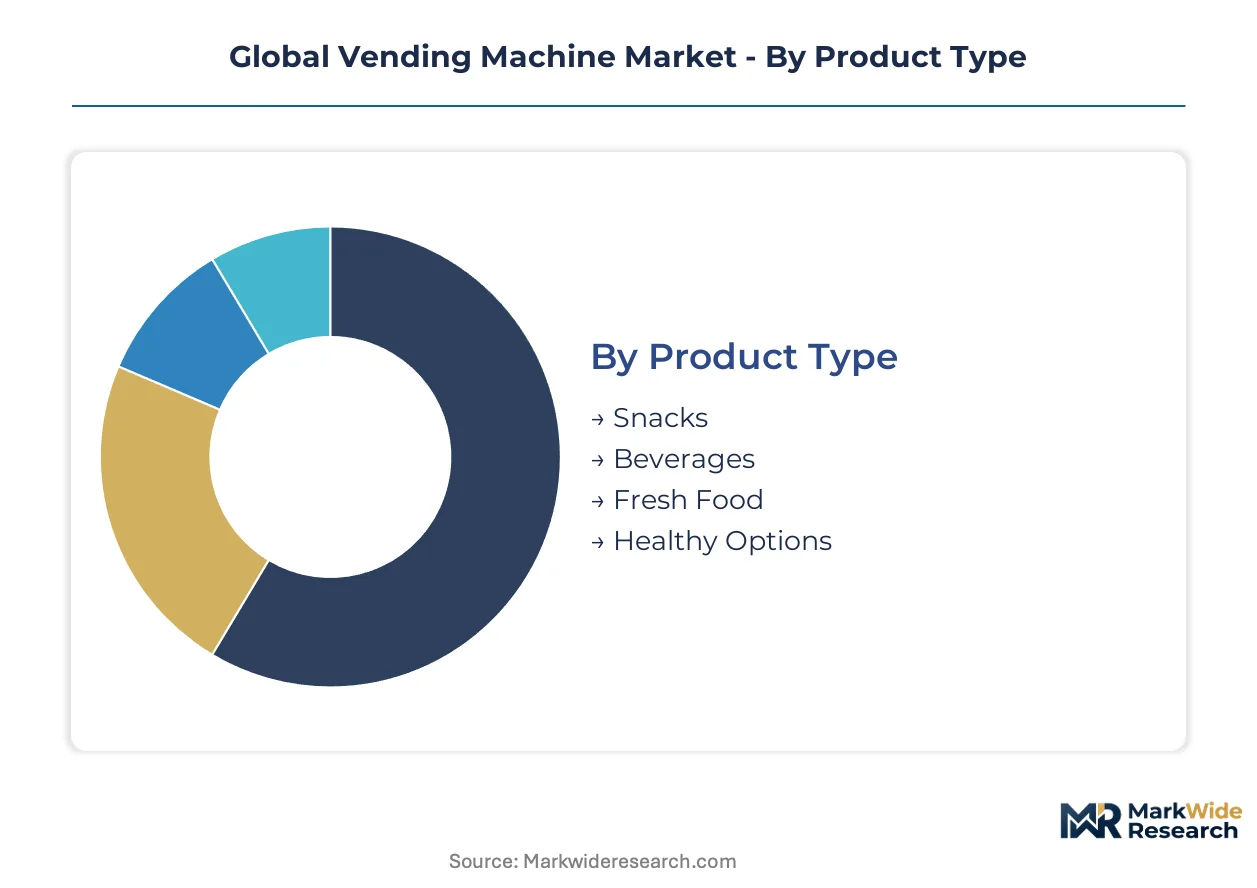
Vending machine procurement specifications diverge sharply across deployment environments, with refrigeration requirements, payment architecture, and inventory telemetry driving category-specific equipment selection. Regulatory mandates on food safety and energy efficiency further fragment supplier qualification pathways by segment.
Product Type:
FDA food safety standards and EU Ecodesign Directive efficiency thresholds apply differentially across temperature-controlled versus ambient configurations, reshaping manufacturer competitive access.
- Beverages:Refrigerated units maintaining 2°C to 8°C dominate installed base economics. China's high-speed rail stations and Japan's dense urban corridors concentrate demand for premium chilled configurations with rapid restock cycles.
- Snacks:Ambient-temperature mechanical dispensing requires minimal regulatory compliance beyond electrical safety certification. Workplace wellness program expansion in US corporate campuses is pulling specification toward nutritional labeling transparency and healthier SKU portfolios.
- Fresh Food:Temperature excursion liability and shortened shelf-life logistics impose operational complexity that limits deployment to captive foot-traffic environments with guaranteed throughput.
- Healthy Options:Corporate facilities managers specify these configurations as employee benefit infrastructure, creating procurement pull-through distinct from traditional retail channel economics.
Established volume favors beverages; emerging adoption favors healthy options.
End User:
Capital deployment cycles and concession frameworks vary dramatically by institutional buyer type, with public infrastructure tenders demanding longer warranty terms than private commercial contracts.
- Public Places:India's railway station modernization programs and China's intercity rail expansion create institutional procurement channels with decade-long concession frameworks. High foot traffic justifies premium equipment with real-time inventory telemetry.
- Offices:Integrated facilities management consolidation in London and New York financial districts specifies equipment-as-a-service terms with uptime guarantees rather than capital purchase models.
- Hospitals:FDA food safety standards and EU Ecodesign Directive mandates impose dual compliance layers that filter supplier pools toward certified manufacturers with proven field performance.
- Schools:Nutritional content regulations and restricted operating hours compress margin recovery timelines, favoring lower-cost hybrid technology configurations over full smart vending deployments.
Public places command the steepest expansion trajectory; offices concentrate the highest contract value per deployment.
Technology:
Equipment replacement cycles compress when cashless payment integration timelines collide with telemetry hardware upgrade requirements, favoring modular retrofit architectures.
- Smart Vending:Real-time inventory data married to route optimization software enables vending-as-a-service business models. Cloud-connected machines with dynamic pricing algorithms adjust SKU pricing by hour, weather, and inventory age.
- Cashless Payment:China's GB standards for electronic payment security and India's BIS certification for electrical safety add compliance layers for cross-border suppliers deploying NFC and mobile wallet architectures.
- Hybrid:Legacy mechanical estate retrofit with connectivity modules offers intermediate capex path for operators facing binary upgrade decisions.
- Traditional:Mechanical coin-and-bill acceptance persists in cost-sensitive deployments where connectivity infrastructure remains unavailable or uneconomical.
Smart vending captures disproportionate R&D investment; hybrid configurations bridge the installed base transition.
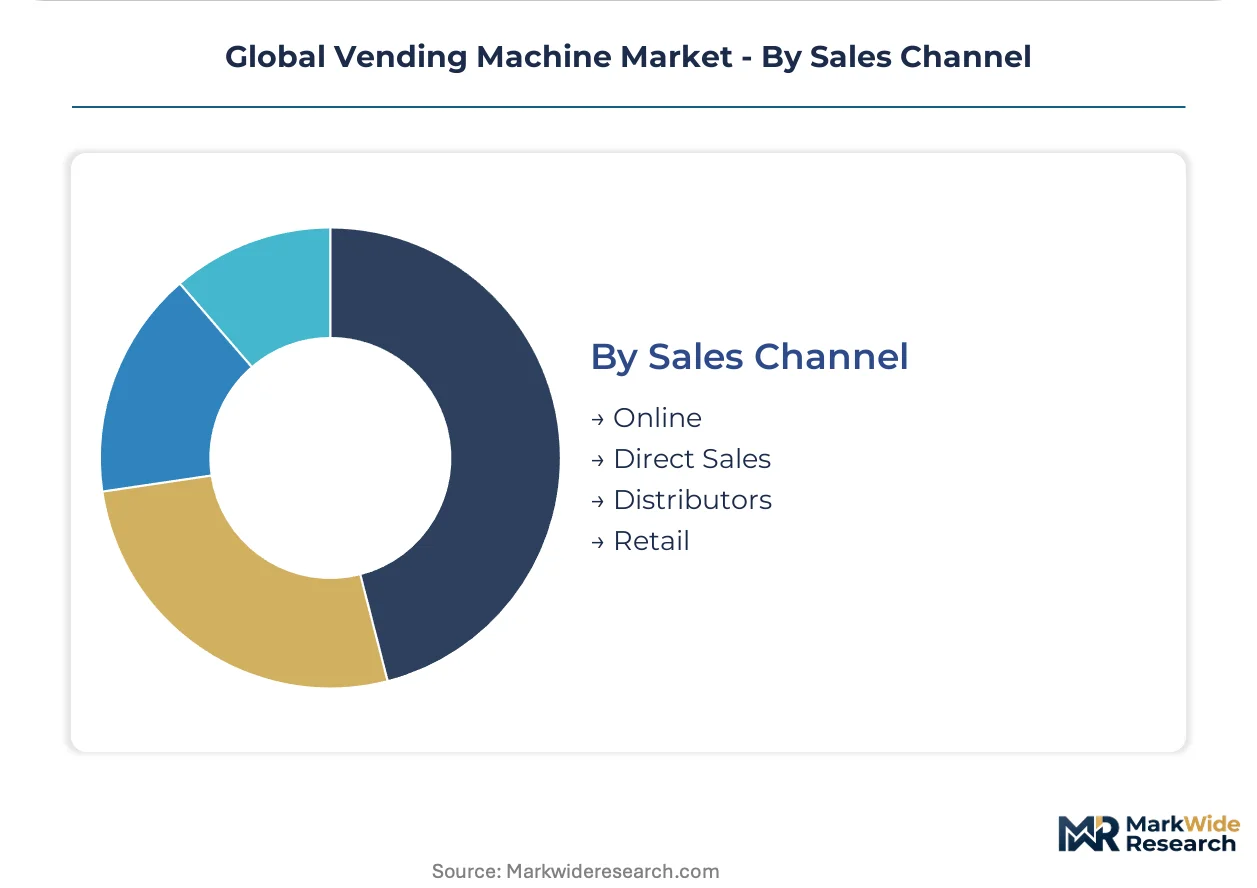
Sales Channel:
Route-to-market economics shift with contract scale, with direct sales anchoring enterprise accounts and distributor networks penetrating fragmented geographic markets.
- Distributors:Extensive networks dominate mid-tier equipment penetration across fragmented regional markets where direct sales force coverage proves uneconomical.
- Direct Sales:Large-scale institutional tenders and integrated facilities management contracts require manufacturer-direct negotiation of equipment-as-a-service terms.
- Online:Digital procurement platforms aggregate specification comparisons for smaller operators seeking standardized configurations with rapid fulfillment.
- Retail:Point-of-sale equipment purchases serve replacement cycles and capacity expansions for established operators with internal technical capabilities.
Distributors anchor geographic reach; direct sales secure the highest-margin contract structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI appliance quality regulations and China's dual carbon goals are redirecting procurement toward certified suppliers with energy-efficient refrigeration architectures. Airport operators in Singapore and Dubai are deploying surge pricing pilots for premium beverages during flight-delay windows. India's Dedicated Freight Corridor is opening decade-long concession frameworks for station-based automated retail.
United States
Workplace wellness program expansion across corporate campuses is pulling specification toward healthy-option configurations with nutritional labeling transparency. FDA food safety standards filter supplier pools toward certified manufacturers with proven field performance. New York and London financial districts concentrate integrated facilities management contracts bundling vending under equipment-as-a-service terms.
China
Expanding high-speed rail station networks create captive foot-traffic environments where fresh-food vending achieves premium throughput. GB standards for electronic payment security add compliance layers for cross-border suppliers deploying mobile wallet architectures. Yangtze River Delta and Pearl River Delta clusters anchor manufacturing depth for temperature-controlled equipment.
Japan
Dense urban corridors concentrate demand for premium chilled configurations with rapid restock cycles. METI appliance quality regulations filter out low-tier manufacturers and concentrate procurement among ISO 9001 certified suppliers. Tokyo and Osaka metropolitan areas drive smart vending adoption with real-time inventory telemetry requirements.
Germany
EU Ecodesign Directive efficiency mandates are forcing costly cooling system redesigns ahead of 2027 enforcement deadlines. F-Gas Regulation phase-down restrictions compress margin structures for existing hydrofluorocarbon-dependent product lines. Bavaria and Baden-Württemberg industrial clusters accelerate natural refrigerant adoption to preempt regulatory exclusion.
India
Railway station modernization programs under the Dedicated Freight Corridor open institutional procurement channels with 10-year concession frameworks. BIS certification for electrical safety adds compliance layers for equipment assemblers. Maharashtra and Gujarat anchor distributor networks penetrating fragmented regional markets where direct sales force coverage proves uneconomical.
Global Vending Machine Market Competitive Environment
Player mix skews toward diversified industrial conglomerates with refrigeration heritage alongside specialized vending equipment fabricators. Market structure concentrates procurement authority among certified suppliers capable of navigating multi-certification sequencing across ISO 9001, electrical safety, and food contact material approvals. Three strategic archetypes dominate: temperature-controlled fresh food specialists, modular retrofit platform providers, and scale-driven beverage-snack configurators. Competitive dynamics center on M&A activity consolidating distributor networks and strategic partnerships securing compressor supply agreements.
Within the diversified industrial tier, Fuji Electric Co., Ltd. and SandenVendo exemplify manufacturers leveraging refrigeration heritage to dominate temperature-controlled segments. Crane Merchandising Systems occupies a position anchoring North American market presence through extensive distributor networks. Among specialized fabricators, Azkoyen Group and Westomatic Vending Services Ltd. represent European suppliers accelerating natural refrigerant adoption to preempt EU enforcement deadlines. Seaga Manufacturing, Inc. sits within the mid-tier equipment segment serving cost-sensitive deployments where connectivity infrastructure remains uneconomical.
| Leading Market Players |
|---|
| SandenVendo |
| Seaga Manufacturing, Inc. |
| Fuji Electric Co., Ltd. |
| Westomatic Vending Services Ltd. |
| Glory Ltd. |
| Crane Merchandising Systems |
| Royal Vendors, Inc. |
| Cantaloupe Inc. |
| Azkoyen Group |
| Others |
Value Chain & Pricing Dynamics
Long-term equipment-as-a-service contracts with 10-year concession frameworks lock in both compressor supply access and price visibility for institutional buyers across India's railway modernization and China's high-speed rail expansion. These structures transfer capital burden from operators to suppliers while embedding maintenance and telemetry obligations that reshape lifetime cost calculations.
Pricing Analysis
Certification level creates the primary spread between ISO 9001-certified premium tier and uncertified economy configurations. Three-tier pricing structure across premium, standard, and economy levels reflects differential compliance burdens with FDA food safety standards and EU Ecodesign Directive mandates. Cost compression in the economy tier is intensifying because F-Gas Regulation phase-down forces cooling system redesigns. Corporate facilities managers in integrated facilities management contracts show lowest price sensitivity; cost-sensitive operators in fragmented regional markets exhibit highest.
Supply Chain Analysis
European and Japanese compressor manufacturers command dominant global capacity, creating input bottleneck vulnerability for mid-tier equipment assemblers sourcing refrigeration systems. Manufacturing draws from Germany, Italy, and China's Yangtze River Delta industrial clusters for temperature-controlled equipment. Natural refrigerant supply constraints and hydrofluorocarbon phase-down timelines present single-source vulnerability. Distribution runs through extensive distributor networks across fragmented regional markets where direct sales force coverage proves uneconomical.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated facilities management consolidation concentrates procurement authority among fewer corporate buyers with specification power over equipment-as-a-service terms. This buyer-power shift compresses margin recovery timelines for standalone vending operators unable to bundle under facilities contracts.
For Market Incumbents: Secure compressor supply agreements with European and Japanese manufacturers to preempt input bottlenecks as F-Gas Regulation phase-down accelerates. Deepen backward integration into natural refrigerant cooling system production to defend margin position against compliance-driven cost inflation. Anchor distributor network control in North American and Asia-Pacific markets where route-to-market economics favor scale. For New Entrants and Emerging Players: Differentiate on modular retrofit platform architecture that bridges legacy mechanical estate transitions without full-system replacement capex. Target India's railway station modernization and China's high-speed rail expansion as most penetrable geographies with decade-long concession frameworks. Pursue direct sales to institutional buyers seeking equipment-as-a-service terms rather than competing through distributor channels. For Investors and Strategic Acquirers: Capital is best deployed toward certified suppliers with proven field performance navigating multi-certification sequencing across ISO 9001, electrical safety, and food contact material approvals. Long-term viability over the analysis window rests on refrigeration heritage and telemetry integration capabilities rather than pure manufacturing scale. Watch smart vending R&D intensity as inflection indicator for which suppliers capture disproportionate operator investment.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Adoption | Preempts EU F-Gas Regulation exclusion ahead of enforcement deadlines in Germany and Italy. |
| Cashless Payment Integration | Compresses replacement cycles as China's GB standards and India's BIS certification add compliance layers. |
| IoT Telemetry Deployment | Enables vending-as-a-service models transferring capital burden from operators to equipment suppliers. |
| Modular Retrofit Architecture | Bridges legacy mechanical estate transitions without forcing binary capex decisions on operators. |
| Integrated Facilities Management Partnership | Captures specification pull-through in London and New York financial districts bundling services. |
Study Parameters
The analysis maps beverage, snack, fresh food, and healthy option configurations, each validated through equipment procurement managers, facilities directors, distributor network heads, and railway station concession operators. Primary interviews with these stakeholders combined with secondary validation against SEC filings, customs trade records, EU Ecodesign Directive compliance databases, and METI appliance quality registration data. Bottom-up installation base enumeration triangulates against top-down market sizing across geographic clusters.
Consistency checks validated volume and value outputs against external benchmarks including refrigeration equipment production data and automated retail telemetry deployment statistics. The analytical framework models product type, end user environment, technology tier, and sales channel dimensions across the projection horizon. CAGRs were derived from equipment replacement cycle compression analysis and concession framework expansion trajectories, incorporating cashless payment penetration curves and energy efficiency upgrade timelines as industry-specific inputs.
Material uncertainties — regulatory enforcement timing on F-Gas phase-down, compressor supply allocation during natural refrigerant transitions, and concession award delays in public infrastructure tenders — sit outside the modeled envelope. Forecasts reflect assumptions on technology adoption curves and certification pathway durations. Practitioners should keep alternative scenarios live as EU Ecodesign Directive enforcement deadlines and China's dual carbon goal implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
United States Smokeless Indoor Grills Market
Food Service
United Arab Emirates Quick Service Restaurant Market
Food Service
Plates Market
Food Service
Asia-Pacific Cloud Kitchen Market
Food Service
Beverage Vending Machine Market
Food Service
Smokeless Grill Market
Food Service
Restaurants in Belgium Market
Food Service
Instant Grocery Market
Food Service
US Food Trucks Services Market
Food Service
United Arab Emirates Foodservice Market
Food Service
Food Service Gloves Market
Food Service
North America Online Food Delivery Market
Food Service
Oman Food Service Market
Food Service
Netherlands Food Service Market
Food Service
Chile Food Delivery Market
Food Service
Hyperlocal Grocery Delivery Market