
 Bahrain Food Service Market | 2026-2036
Bahrain Food Service Market Size, Share, and Industry Trends Forecast 2026-2036
Bahrain Food Service Market Insights
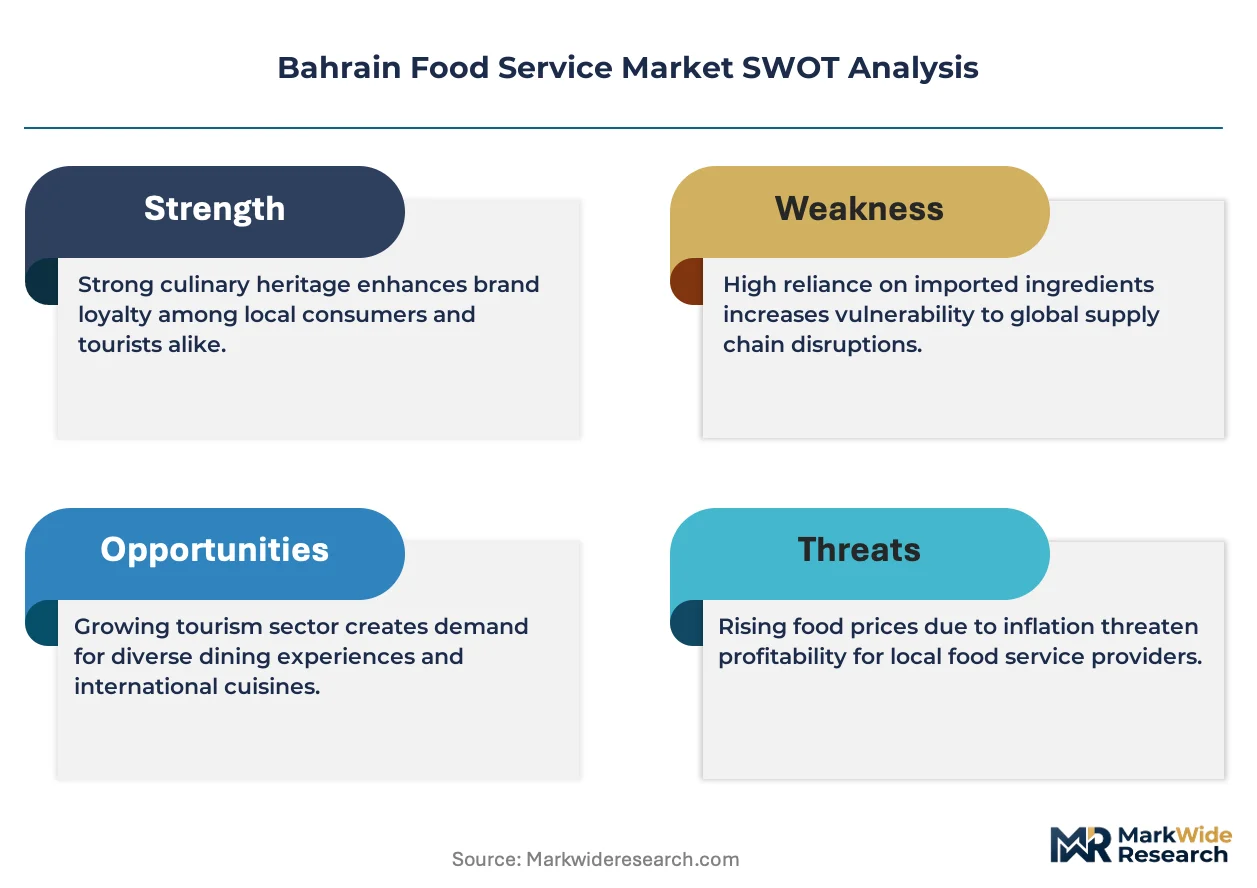
The Bahrain food service sector is restructuring around a sharp divergence between premium dining experiences and commodity-grade fast food, with full-service restaurants investing in chef-driven concepts while fast-food chains compete on delivery speed. Alamar Foods Company leverages its multi-brand portfolio to dominate quick-service positioning across the kingdom. Americana Restaurants International PLC sustains operational scale through centralized supply chains that anchor cost discipline. Jawad Business Group differentiates via localized menu adaptation that competes effectively against standardized global offerings.
Food service encompasses the commercial preparation, delivery, and sale of ready-to-consume meals through institutional and retail channels, requiring cold-chain integrity above four degrees Celsius and HACCP-compliant preparation surfaces to prevent contamination. The sector serves hospitality, corporate, healthcare, and educational end users with standardized portion control and traceable ingredient sourcing. Full-service restaurants capture premium margin pools through experiential dining, while fast food leads volume throughput. Catering services to corporations and hospitals represent the fastest-growing channel as institutional outsourcing accelerates. Online delivery is displacing direct sales as the dominant distribution pathway, particularly among younger demographics in urban centers.
Bahrain's national food safety regulator enforces Hazard Analysis Critical Control Point standards across all commercial kitchens, with mandatory inspection frequencies rising for high-volume operators. The Ministry of Municipalities Affairs and Agriculture oversees halal certification integrity, which shapes market access for international chains entering the kingdom. Stakeholders must monitor how evolving labor quota policies affect staffing costs, while digital payment integration and ghost kitchen proliferation demand capital allocation decisions that separate scalable platforms from location-dependent legacy models.
Market Dynamics
Bahrain's food service sector is restructuring around ghost kitchen proliferation and third-party platform dependency, compressing traditional dine-in economics while redistributing capital toward delivery-native infrastructure and cloud-based kitchen operations.
Growth Catalysts
- Corporate Catering Outsourcing:Bahrain's hospitality sector diversification beyond oil revenue is accelerating institutional food service procurement. High-rise office clusters in Manama's central business district generate concentrated demand for contracted meal programs.
- MOH Food Safety Certification:The Ministry of Health's tightening inspection protocols for high-volume operators is professionalizing kitchen standards. Compliance investments are separating scalable platforms from informal competitors.
- Digital Payment Integration:Mobile wallet penetration across Bahrain's urban consumer base is unifying ordering, payment, and loyalty functions. Younger demographics in Manama and Riffa are driving platform-native consumption patterns.
Market Restraints
- Halal Certification Integrity Costs:The Ministry of Municipalities Affairs and Agriculture's enforcement standards create compliance friction for international chains entering the kingdom. Certification timelines extend market entry cycles.
- Labor Quota Policy Volatility:Evolving expatriate staffing regulations affect wage structures across commercial kitchens. Dependence on foreign kitchen staff exposes operators to permit renewal uncertainty.
- Last-Mile Cold-Chain Fragility:Temperature excursions above four degrees Celsius during Bahrain's summer months compromise food safety. Delivery radius constraints limit ghost kitchen location flexibility.
Strategic Opportunities
- Healthcare Catering Expansion:Hospital and clinic outsourcing of patient and staff meal programs represents underpenetrated institutional demand. MOH facility privatization is creating tender opportunities for specialized operators.
- Educational Institution Contracts:Private school and university campus dining remains fragmented. Standardized portion control and traceable sourcing capabilities position organized caterers for multi-year agreements.
- Ghost Kitchen Platform Convergence:Cloud kitchen infrastructure combined with aggregator app integration is compressing real estate requirements. Capital-light entry models enable rapid menu testing across Bahrain's dense urban corridors.
Industry Challenges
- HACCP-Trained Kitchen Staff Scarcity:Hazard Analysis Critical Control Point certification requirements exceed available trained personnel supply. Commercial kitchens face recruitment bottlenecks for compliant food handlers.
- Aggregator Commission Compression:Third-party delivery platform fees are eroding quick-service margins. Operators must balance volume access against per-order profitability in Bahrain's price-sensitive segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bahrain Food Service Market |
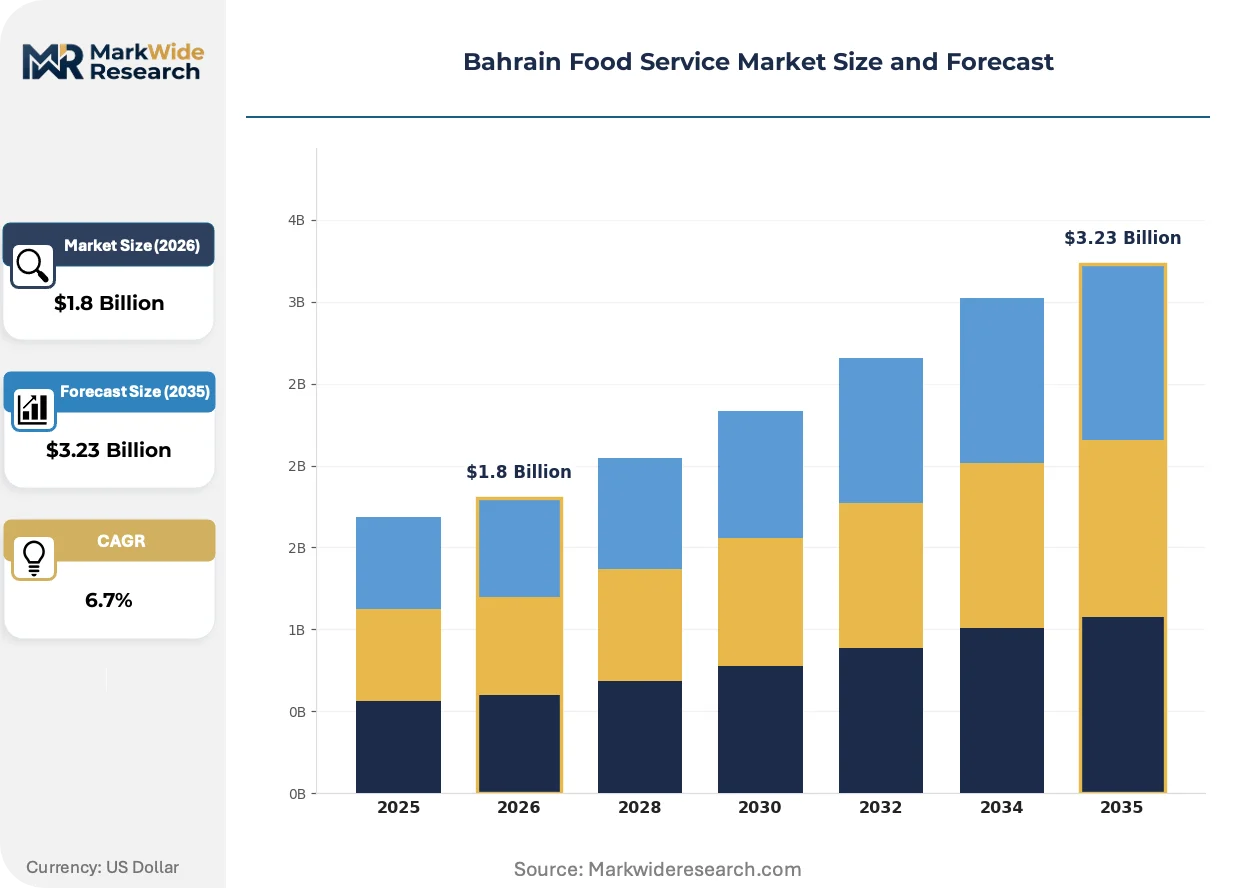
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Restaurants, Fast Food, Cafes, Catering Services End User: Individuals, Corporations, Educational Institutions, Hospitals Distribution Channel: Online Delivery, Direct Sales, Wholesale, Retail Outlets Cuisine Type: Arabic, Indian, Asian, International |
| Companies Covered | Alamar Foods Company, Fakhro Restaurants Company WLL, Americana Restaurants International PLC, Jawad Business Group, Gastronomica General Trading Company WLL, M.H. Alshaya Co. WLL, ALBAIK Food Systems Company SA, LuLu Group International, Alabraaj Restaurants Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bahrain Food Service Market Trends and Innovations
Delivery-native business models are compressing traditional restaurant economics across Bahrain's urban centers, redistributing competitive advantage toward platform-integrated operators with centralized production infrastructure.
Cloud kitchen technology is unifying order aggregation, kitchen display systems, and delivery dispatch into single-stack platforms. Full-service restaurant groups in Manama are adopting these systems to test virtual brands without location-dependent capex. The technology is unifying previously fragmented production and distribution workflows, enabling multi-concept operations from single licensed facilities.
MOHAP-aligned food safety frameworks are tightening operational standards across Bahrain's commercial kitchen landscape. Mandatory HACCP documentation and rising inspection frequencies for high-volume operators are forcing legacy establishments into compliance investments. Full-service restaurants with chef-driven concepts face the steepest adaptation costs as they retrofit open-kitchen designs for controlled preparation surfaces.
Younger urban consumers are consolidating meal decisions around aggregator app interfaces rather than direct brand relationships. Quick-service chains dependent on walk-in traffic in Bahrain's traditional souk-adjacent locations are experiencing demand rotation toward platform-discoverable options. This behavioral shift concentrates most visibly in Manama's diplomatic and financial districts where office workers execute majority of lunch procurement through mobile ordering.
Bahrain Food Service Market Segmentation
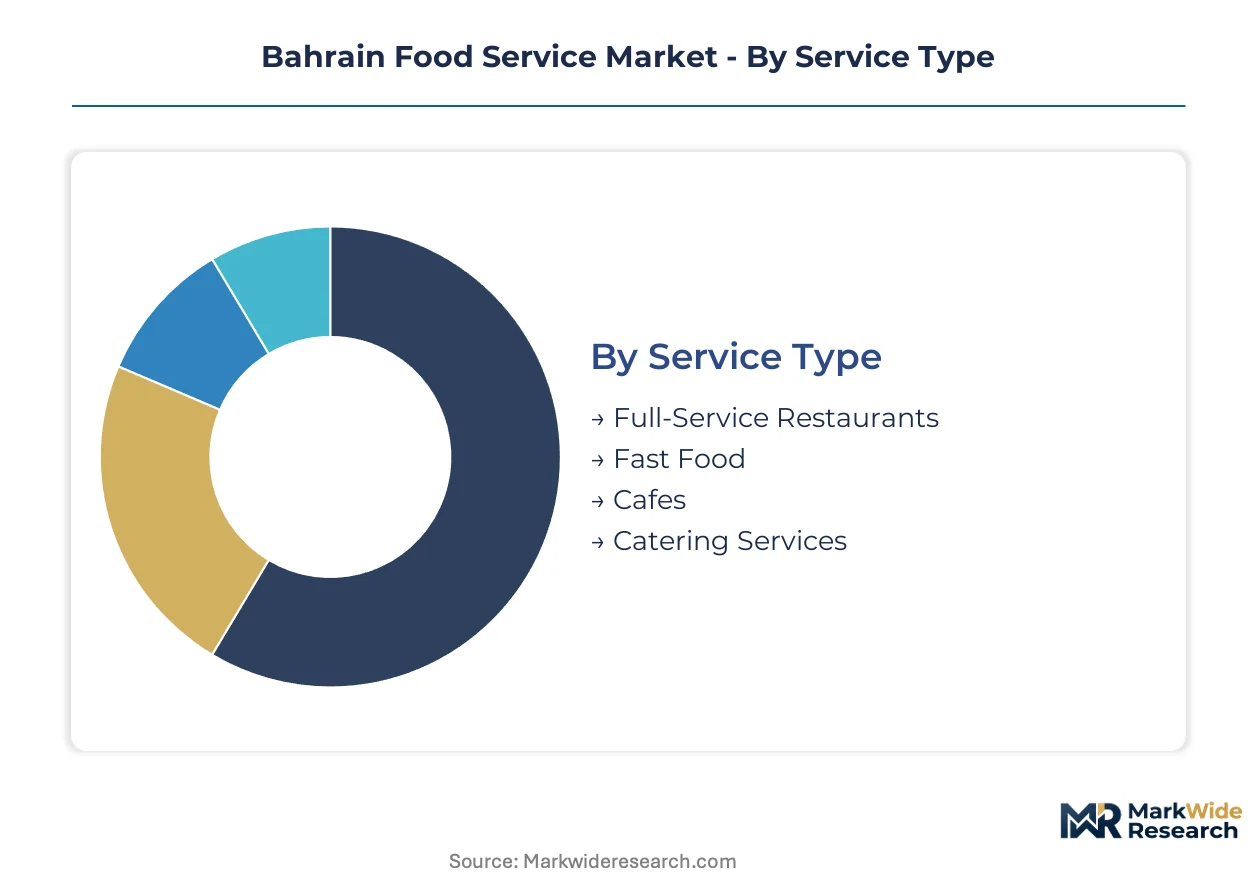
Bahrain's food service segmentation reveals divergent margin profiles across service models, with premium full-service concepts commanding distinct pricing power while fast-food and catering channels compete on operational throughput and contract scale.
Service Type:
Volume throughput concentrates in standardized formats, while premium positioning requires experiential differentiation and chef-driven menu architecture.
- Full-Service Restaurants:Table-service operations with open-kitchen designs and controlled preparation surfaces command premium pricing through experiential dining. Manama's diplomatic and financial districts concentrate demand for chef-driven concepts where Bahrain's Ministry of Health HACCP standards enforce rigorous documentation.
- Fast Food:Standardized quick-service formats prioritize delivery speed and menu consistency across multi-brand portfolios. Aggregator platform dependency is compressing per-order margins in Bahrain's price-sensitive segments while expanding geographic reach beyond traditional souk-adjacent locations.
- Cafes:Beverage-forward formats with limited food menus target daytime consumption occasions in office clusters.
- Catering Services:Institutional meal programs for corporations and healthcare facilities represent contract-based revenue with standardized portion control requirements.
Mature deployment sits with Full-Service Restaurants. Newer deployment is concentrated in Catering Services.
End User:
Procurement patterns split between discretionary individual spending and institutional contract volume with traceable sourcing mandates.
- Corporations:High-rise office towers in Manama's central business district generate concentrated demand for contracted meal programs with digital payment integration. Hospitality sector diversification beyond oil-dependent revenue streams is accelerating procurement formalization.
- Hospitals:Patient and staff meal outsourcing under Ministry of Health facility privatization creates tender opportunities for HACCP-certified operators with cold-chain integrity capabilities.
- Individuals:Mobile wallet penetration drives platform-native consumption patterns among younger demographics in urban centers.
- Educational Institutions:Private school and university campus dining remains fragmented with multi-year agreement potential for organized caterers.
Contracted volume anchors with Corporations. Volume expansion is climbing fastest in Hospitals.
Distribution Channel:
Channel economics redistribute capital toward delivery-native infrastructure as direct walk-in traffic declines in traditional locations.
- Online Delivery:Aggregator app interfaces consolidate meal decisions among younger urban consumers, displacing direct brand relationships. Ghost kitchen proliferation enables cloud-based production without location-dependent capex in Bahrain's dense urban corridors.
- Direct Sales:Traditional dine-in and counter-service formats face demand rotation toward platform-discoverable options, particularly in Manama's central business district where office workers execute majority of lunch procurement through mobile ordering.
- Wholesale:Bulk supply to institutional kitchens and secondary food service operators.
- Retail Outlets:Grab-and-go formats in high-traffic commercial zones with limited preparation capabilities.
Legacy infrastructure remains with Direct Sales. Capital allocation is shifting most aggressively toward Online Delivery.
Cuisine Type:
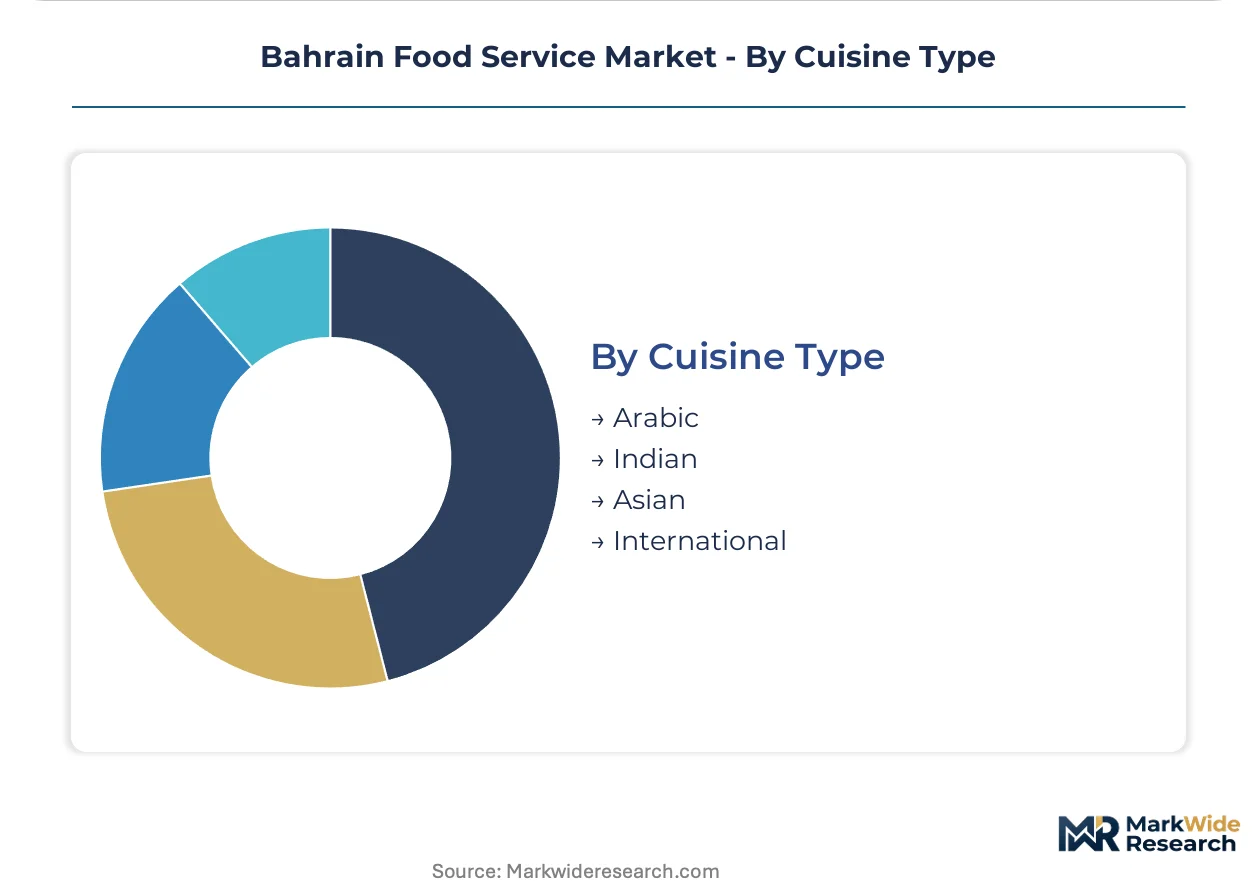
Menu positioning balances localization requirements against international brand recognition in a market with halal certification integrity mandates.
- Arabic:Traditional Gulf and Levantine preparations dominate local taste preferences with Ministry of Municipalities Affairs and Agriculture halal certification as market access prerequisite.
- Indian:South Asian flavor profiles capture significant share through established expatriate communities and localized menu adaptation strategies.
- Asian:East and Southeast Asian concepts test virtual brands through cloud kitchen infrastructure without dedicated real estate investment.
- International:Standardized global offerings compete against adapted menus that modify portion sizes and spice levels for Bahraini consumer preferences.
Established penetration rests with Arabic cuisine. Steepest expansion trajectory is appearing in Asian formats through ghost kitchen testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manama's central business district concentrates Bahrain's food service procurement, with high-rise office towers and luxury hotel clusters generating dense institutional demand. The capital's diplomatic and financial districts anchor contract catering volume. Riffa and Muharraq extend demand into residential and airport-adjacent corridors.
Manama Capital District
Corporate catering contracts dominate procurement as hospitality sector diversification accelerates beyond oil-dependent revenue streams. The Ministry of Health enforces HACCP standards across commercial kitchens with mandatory inspection frequencies rising for high-volume operators. Seef and Diplomatic Area clusters generate concentrated lunch demand from office workers executing majority of procurement through mobile ordering platforms.
Muharraq Governorate
Bahrain International Airport traffic sustains grab-and-go and fast-casual formats targeting transit passengers and aircrew. The Ministry of Municipalities Affairs and Agriculture oversees halal certification integrity for airport concessionaires. City Centre Muharraq and surrounding retail zones concentrate quick-service deployment with delivery-native operators testing ghost kitchen configurations.
Northern Governorate
Expatriate residential communities in Budaiya and Jidd Hafs drive family-oriented dining demand with preference for standardized global brands. Labor quota policies affect staffing costs across commercial kitchens dependent on foreign food handlers. Diyar Al Muharraq and Marassi Al Bahrain developments are attracting waterfront dining investments with experiential positioning.
Southern Governorate
Industrial zones around Askar and Riffa house manufacturing and logistics workforces with price-sensitive meal requirements. Educational institution contracts remain fragmented across private school campuses with multi-year agreement potential for organized caterers. University of Bahrain Sakhir campus and Bahrain Polytechnic generate captive daytime consumption with limited on-site dining infrastructure.
Bahrain Food Service Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service-model differentiation, with full-service restaurants capturing experiential pricing power while fast-food chains compete on delivery speed and volume throughput. The vendor base organizes around three strategic archetypes: multi-brand portfolio operators dominating quick-service positioning, centralized supply-chain players anchoring cost discipline, and localized menu adapters competing against standardized global offerings. Consolidation pressure is accelerating through aggregator platform dependency and ghost kitchen proliferation, while portfolio diversification and geographic expansion within Gulf Cooperation Council markets represent dominant competitive moves.
Within the multi-brand portfolio tier, Alamar Foods Company and Americana Restaurants International PLC exemplify scale-driven positioning across quick-service formats. Jawad Business Group occupies a differentiated position through localized adaptation strategies. These three anchors represent divergent approaches to Bahrain's market: portfolio breadth, supply-chain centralization, and menu localization respectively.
| Leading Market Players |
|---|
| Alamar Foods Company |
| Fakhro Restaurants Company WLL |
| Americana Restaurants International PLC |
| Jawad Business Group |
| Gastronomica General Trading Company WLL |
| M.H. Alshaya Co. WLL |
| ALBAIK Food Systems Company SA |
| LuLu Group International |
| Alabraaj Restaurants Group |
| Others |
Pricing and Supply Chain Analysis
Family-owned hospitality groups and private-equity-rolled-up multi-brand operators dominate Bahrain's food service supply base, translating procurement scale into pricing discipline across institutional catering contracts while compressing margins for independent single-location competitors.
Pricing Analysis
Throughput-based pricing anchors Bahrain's food service economics, with per-meal contract rates tied to volume commitments rather than ingredient cost-plus structures. Three-tier pricing structure across premium experiential dining, standardized fast-casual, and commodity-grade institutional catering separates margin pools. Pricing pressure stems from third-party aggregator commission compression, which erodes quick-service profitability. Corporate catering clients exhibit lowest price sensitivity due to bundled service requirements, while individual delivery consumers drive hardest bargain-hunting through platform comparison.
Supply Chain Analysis
Direct-to-institutional channels handle high-volume corporate and healthcare catering demand, while aggregator-integrated ghost kitchens serve fragmented individual consumption. Geographic supply concentration draws from Saudi Arabia for protein inputs, UAE for processed ingredients, and India for rice and spice commodities. Cold-chain equipment, halal-certified packaging, and HACCP-compliant preparation surfaces constitute critical component dependencies. Single-source vulnerability sits with summer cold-chain integrity during Bahrain's extreme heat periods. Distribution runs through centralized commissary kitchens feeding multiple virtual brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bahrain's food service sector is becoming a vertical-integration race as operators pursue captive supply of HACCP-certified kitchen labor and in-house cold-chain logistics to escape margin compression from third-party platform dependency.
For Market Incumbents: Hedge against aggregator commission erosion by developing direct-ordering mobile infrastructure with integrated payment and loyalty systems. Backward integration into commissary production for multiple virtual brands reduces per-unit real estate costs. Threat substitution from Saudi-based cloud kitchen operators entering via causeway logistics demands preemptive geographic coverage in Northern Governorate residential clusters. For New Entrants and Emerging Players: Ghost kitchen technology platforms offer the most penetrable entry vector, enabling rapid menu testing without location-dependent capital expenditure. Healthcare catering tenders under Ministry of Health facility privatization represent undercontracted institutional volume with compliance barriers that filter out informal competitors. Go-to-market execution should anchor on HACCP certification acquisition as table stakes for hospital procurement eligibility. For Investors and Strategic Acquirers: Consolidation of multi-brand portfolio operators into three-to-five player market structure is the leading indicator that scale economics are becoming decisive. Long-term viability favors platforms with integrated supply chain control spanning procurement, production, and last-mile delivery capability. Acquisition target archetype: regional cloud kitchen operators with existing aggregator relationships and unused capacity for brand expansion. Signal to monitor: Ministry of Health inspection frequency increases that accelerate compliance-driven exit of subscale independents.| Strategic Initiative | Industry Significance |
|---|---|
| Ghost Kitchen Infrastructure Expansion | Compresses real estate requirements while enabling multi-brand production from single licensed facilities. |
| HACCP Certification Investment | Separates scalable platforms from informal competitors under tightening Ministry of Health protocols. |
| Direct-to-Consumer Platform Launch | Reduces aggregator commission burden and captures customer data for personalized loyalty programs. |
| Healthcare Catering Contract Pursuit | Captures multi-year institutional revenue streams with standardized portion control requirements. |
| Cold-Chain Logistics Integration | Ensures temperature integrity during Bahrain's summer months while expanding delivery radius flexibility. |
Research Methodology
Ministry of Health regulatory filings, hospitality sector procurement databases, and customs import records for food service equipment formed the secondary backbone of this analysis. Primary interviews with commercial kitchen operators, corporate catering procurement managers, third-party delivery platform executives, and restaurant group supply chain directors were combined with secondary validation. Bottom-up triangulation across outlet-level operational metrics and top-down reconciliation against national food service expenditure estimates anchored the analytical framework.
Historical trendline analysis of outlet expansion, contract catering procurement volumes, and aggregator platform transaction growth informed the projection methodology across the analysis window. Segmentation dimensions modeled include service type, end-user category, distribution channel, and cuisine format. CAGRs were derived from regression analysis of volume and value trajectories. Industry-specific forecast inputs incorporated labor quota policy evolution scenarios and digital payment penetration curves.
Several conditions sit outside the modeled scope, including geopolitical disruptions to Gulf Cooperation Council supply corridors and abrupt regulatory shifts in expatriate staffing permissions. Forecasts reflect assumptions about sustained hospitality sector diversification beyond oil-dependent revenue streams. Periodic stress-testing of base assumptions is recommended given labor policy volatility and aggregator platform fee structure uncertainty.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Latin America Online Grocery Market
Food Service
India Quick Service Restaurant Market
Food Service
Europe Inflight Catering Market
Food Service
Egypt Food Service Market
Food Service
Europe Out of Home (OOH) Delivery Market
Food Service
Galley Equipment Market
Food Service
Latin America Online Grocery Delivery Market
Food Service
Asia-Pacific and Middle-East Inflight Catering Market
Food Service
Nigeria Food Service Market
Food Service
United States Quick Service Restaurants Market
Food Service
US Food Trucks Services Market
Food Service
Spain Food Service Market
Food Service
Commercial Rice Cooker Market
Food Service
Snack Subscription Box Service Market
Food Service
Instant Noodle Vending Machine Market
Food Service
Bar Refrigeration Market