
 Fermented Mediterranean Pepper and Tomato Complexes Market | 2026-2036
Fermented Mediterranean Pepper and Tomato Complexes Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Mediterranean Pepper and Tomato Complexes Market Insights
Modular paste-and-powder bundling is realigning how food manufacturers configure their ingredient procurement. Belazu Ingredient Company leverages its Mediterranean sourcing network to sustain premium positioning across European retail channels. Kerry Group plc anchors its fermentation capabilities in controlled-culture systems that supply standardized flavor bases to multinational food manufacturers. FerMato Sauce s.r.o. competes through geographic dominance in Central European private-label supply.
Fermented Mediterranean pepper and tomato complexes comprise lactic acid-fermented matrices of Capsicum annuum and Solanum lycopersicum cultivars, typically achieving pH levels of 3.8–4.2 and developing elevated glutamate and ribonucleotide concentrations that function as clean-label umami enhancers. These complexes serve primarily as natural flavor modulators in reduced-sodium and additive-free food systems. Paste and concentrate forms command the deepest margin pools due to their concentration of bioactive compounds and suitability for industrial-scale dosing, while powder forms represent the fastest-expanding configuration as dietary supplement producers seek shelf-stable, free-flowing inputs for capsule and sachet applications. Lactic acid fermentation technology leads in installed capacity, though mixed culture fermentation is gaining traction among nutraceutical-oriented suppliers targeting specific metabolite profiles.
EFSA's novel food evaluation pathways and the EU's Clean Labeling guidelines shape product development timelines and substantiation requirements for fermented botanical ingredients in Europe. REACH compliance for fermentation-derived extracts governs market access for non-EU suppliers seeking to serve continental food manufacturers. Stakeholders must monitor how evolving microbiome health claims regulation affects the permissible positioning of fermented pepper-tomato complexes across food and supplement categories.
Market Dynamics
The EU Farm to Fork Strategy's additive reduction mandates are compressing reformulation timelines for food manufacturers sourcing clean-label umami systems, forcing procurement teams to lock multi-year supply contracts for fermented pepper-tomato bases ahead of competitor bidding.
Growth Catalysts
- Clean-label mandates:EFSA's evolving guidance on natural flavor substantiation creates procurement urgency among reduced-sodium sauce manufacturers seeking compliant umami alternatives.
- Heritage cultivar concentration:Spain's Extremadura and Murcia processing corridors anchor supply of authenticated Capsicum annuum varieties with documented metabolite profiles.
- Nutraceutical pivot:Dietary supplement producers are expanding capsule and sachet applications using shelf-stable fermented complexes as microbiome-targeted inputs.
Market Restraints
- Input cost volatility:Heritage pepper harvest yields fluctuate with Mediterranean drought cycles, compressing margin predictability for paste and concentrate suppliers.
- Supply concentration risk:Lactic acid fermentation capacity clusters in Central European controlled-culture facilities, creating single-source vulnerability for multinational food manufacturers.
- Regulatory friction:REACH compliance documentation requirements for fermentation-derived extracts delay market access for non-EU suppliers by 18-24 months.
Strategic Opportunities
- Underpenetrated geographies:German and French specialty condiment makers are expanding premium retail lines, creating first-mover advantage for suppliers with authenticated Mediterranean sourcing networks.
- Technology convergence:Mixed culture fermentation systems combined with metabolite profiling analytics enable custom ribonucleotide concentrations for targeted nutraceutical applications.
- Channel innovation:Direct-to-manufacturer digital procurement platforms are disintermediating traditional ingredient distributors in Central European private-label supply.
Industry Challenges
- Skill scarcity:Fermentation microbiologists with expertise in controlled-culture Capsicum matrices command premium compensation, constraining facility expansion timelines.
- Certification complexity:Novel food evaluation pathways under EFSA require 24-36 month substantiation timelines for new fermented botanical ingredient formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Mediterranean Pepper and Tomato Complexes Market |
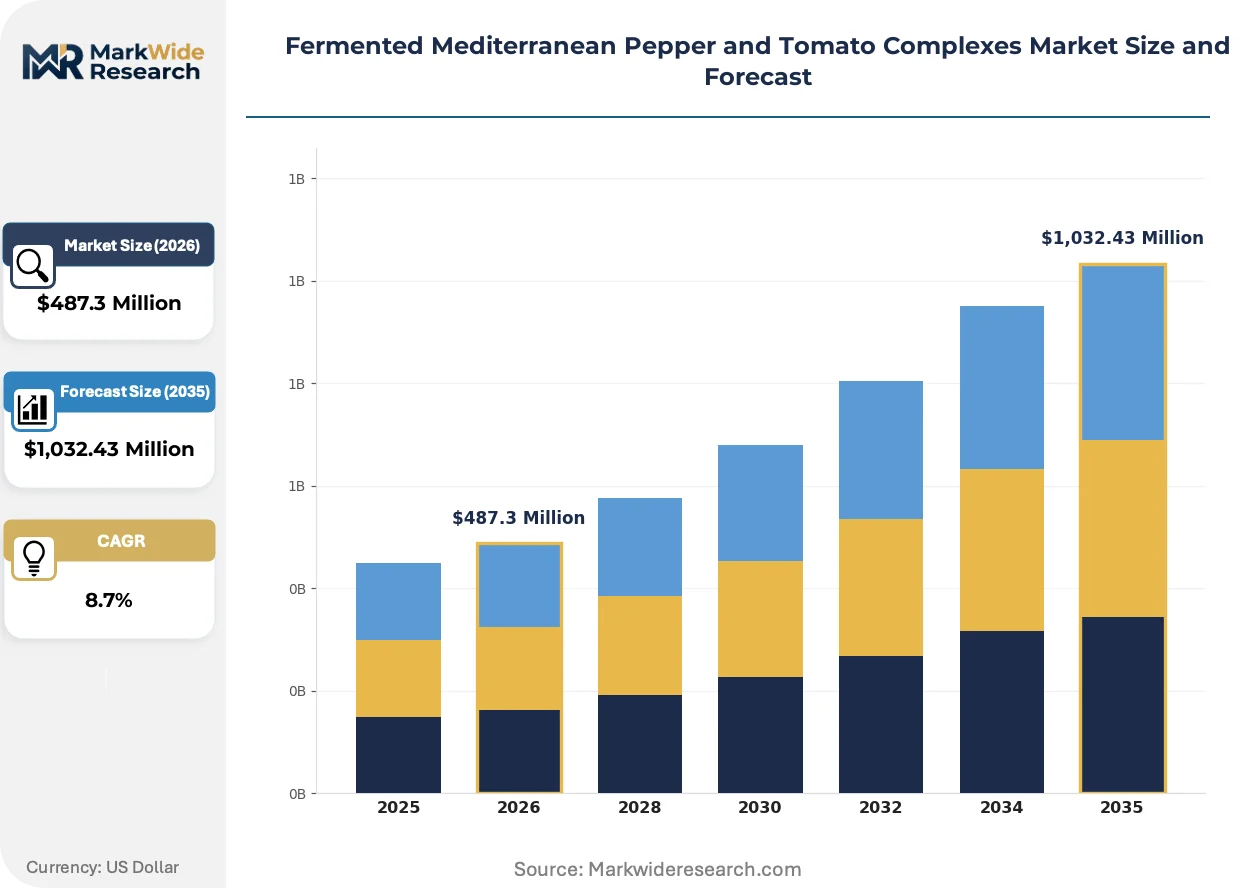
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Form: Powder, Liquid Extract, Paste, Concentrate, Oil Infusion Application: Food Flavoring, Nutraceuticals, Cosmetic Ingredients, Functional Beverages, Pet Nutrition Processing Technology: Lactic Acid Fermentation, Enzymatic Fermentation, Spontaneous Fermentation, Controlled Fermentation, Mixed Culture Fermentation End User: Food Manufacturers, Dietary Supplement Producers, Cosmetic Companies, Beverage Organizations, Animal Feed Producers |
| Companies Covered | FerMato Sauce s.r.o., Belazu Ingredient Company, Eaten Alive, Sauce Shop, Ajinomoto Co., Danone, Kerry Group plc, Cargill, Chr. Hansen Holding A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Mediterranean Pepper and Tomato Complexes Market Trends and Innovations
Automation of fermentation monitoring systems is compressing batch-to-batch variability while regulatory pressure on additive claims intensifies documentation requirements across European food manufacturing.
Sensor-integrated bioreactor technology is automating real-time pH and metabolite tracking during lactic acid fermentation of pepper-tomato matrices. Mid-sized sauce producers in France and Germany are adopting these systems at accelerating rates to reduce quality control labor. This automation is compressing the competitive gap between artisan heritage suppliers and industrial-scale manufacturers.
REACH registration requirements for fermentation-derived botanical extracts are tightening documentation standards for importers serving EU food manufacturers. The industrial consequence is a bifurcation between established European suppliers with existing dossiers and non-EU competitors facing 18-24 month entry delays. Powder and concentrate formats face the most acute compliance scrutiny due to their concentration of bioactive compounds.
Consolidation of buyer procurement functions among multinational food manufacturers is compressing supplier negotiation cycles and demanding outcome-based flavor performance guarantees. Traditional ingredient distributors in Central Europe are losing share to direct manufacturer relationships. This pattern is most visible in Germany, where clean-label sauce producers now contract directly with Spanish processing corridors for heritage cultivar authentication.
Fermented Mediterranean Pepper and Tomato Complexes Market Segmentation
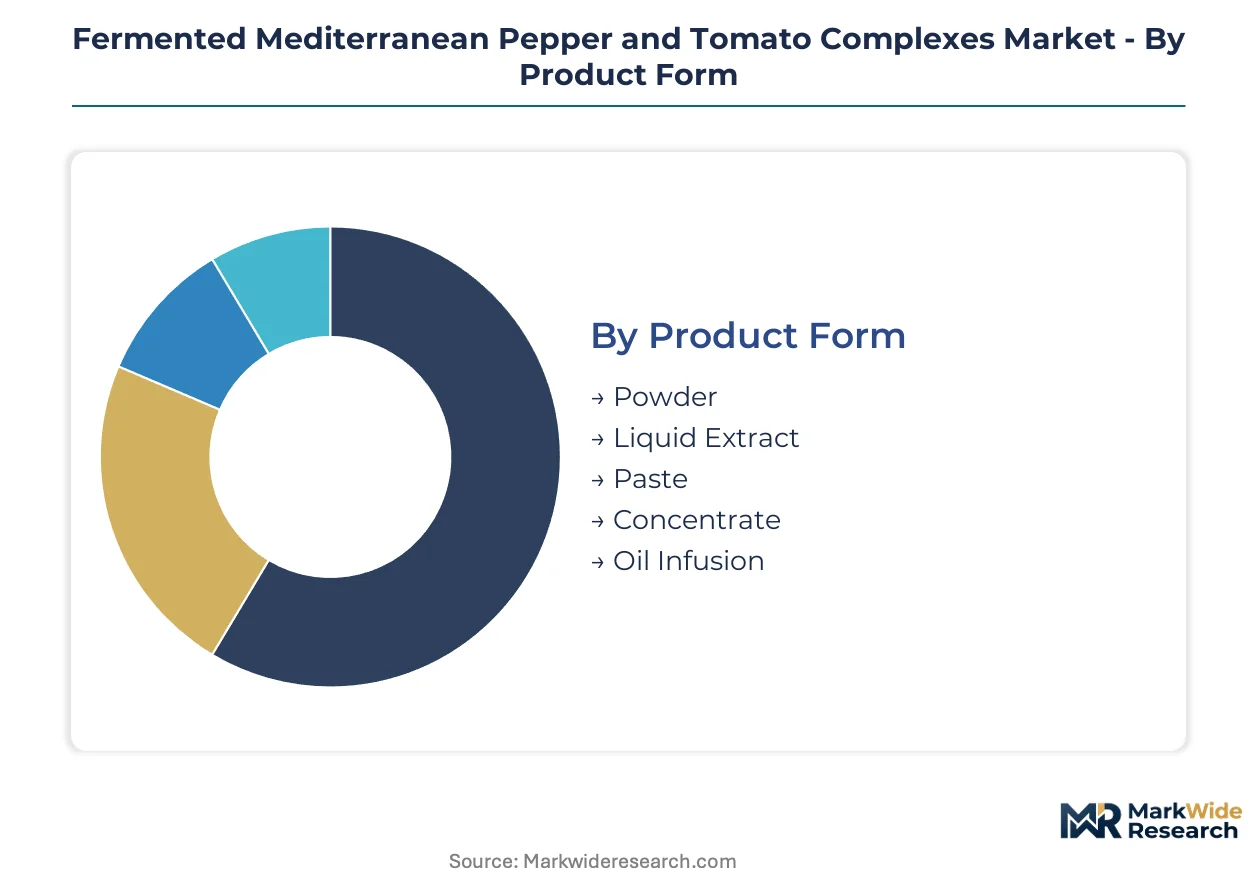
Segmentation in fermented Mediterranean pepper and tomato complexes determines which regulatory pathways apply and where margin pools concentrate. Product form dictates REACH documentation burden, while processing technology separates artisan heritage suppliers from industrial-scale competitors.
Product Form:
Certification intensity varies sharply across physical states, with concentrates and powders facing the deepest EFSA novel food scrutiny due to bioactive compound density.
- Paste:Semi-solid matrices with 25-40% dry matter content serve as the workhorse input for sauce manufacturers. German clean-label condiment makers in Baden-Württemberg and Bavaria lock multi-year contracts for heritage cultivar pastes to secure supply ahead of EU Farm to Fork additive reduction deadlines. Leading the category by volume: Paste. Growing fastest: Powder.
- Powder:Spray-dried or freeze-dried free-flowing formats achieve shelf stability exceeding 24 months at ambient conditions. Dietary supplement producers in France's Occitanie region expand capsule and sachet applications using authenticated Extremadura-sourced powders with documented metabolite profiles.
- Liquid Extract:Aqueous or hydro-alcoholic solutions standardized for ribonucleotide content enable precise dosing in functional beverage formulations.
- Concentrate:Reduced-moisture formats with elevated glutamate density command premium positioning in reduced-sodium food systems requiring intense umami impact.
- Oil Infusion:Lipid-based carriers suspend fat-soluble fermentation metabolites for cosmetic and specialty culinary applications.
Paste dominates procurement tonnage. Powder climbs fastest as nutraceutical channels absorb capacity.
Application:
End-use segmentation tracks where EFSA natural flavor substantiation requirements intersect with microbiome health claim restrictions.
- Food Flavoring:Clean-label umami modulation in reduced-sodium sauces, soups, and ready meals represents the foundational demand pillar. France's specialty condiment sector in Provence-Alpes-Côte d'Azur drives premium positioning for authenticated Mediterranean sourcing.
- Nutraceuticals:Capsule, tablet, and sachet formats targeting gut microbiome support face the steepest regulatory climb under evolving EFSA health claims guidance. Spanish processors in Murcia develop custom ribonucleotide profiles for French and German supplement contract manufacturers.
- Cosmetic Ingredients:Fermentation-derived antioxidants and bioactive peptides enter skincare formulations through oil infusion and extract formats.
- Functional Beverages:Liquid extracts enable clean-label flavor enhancement in reduced-sugar drink systems without artificial additive declarations.
- Pet Nutrition:Palatability enhancers for premium companion animal feeds utilize paste and powder formats with documented safety dossiers.
Food flavoring absorbs the greatest volume. Nutraceuticals expand most quickly amid microbiome positioning interest.
Processing Technology:
Technology choice determines which suppliers can meet multinational food manufacturer specifications for batch-to-batch consistency.
- Lactic Acid Fermentation:Dominant installed capacity using defined Lactobacillus strains achieves pH 3.8-4.2 with predictable metabolite accumulation. Kerry Group plc anchors industrial supply through controlled-culture facilities serving pan-European sauce manufacturers with standardized flavor bases.
- Mixed Culture Fermentation:Combinations of lactic acid bacteria and yeasts enable targeted ribonucleotide ratios for specific nutraceutical applications. Central European specialists in Czechia deploy metabolite profiling analytics to customize outputs for French dietary supplement producers.
- Enzymatic Fermentation:Exogenous enzyme supplementation accelerates matrix breakdown for specific texture and flavor targets in premium paste applications.
- Controlled Fermentation:Sensor-integrated bioreactor systems with real-time pH and metabolite monitoring compress quality control labor for mid-sized French and German producers.
- Spontaneous Fermentation:Heritage Extremadura processors maintain traditional ambient-culture methods for authenticated provenance positioning in premium retail channels.
Lactic acid fermentation commands installed capacity. Mixed culture systems gain share fastest in nutraceutical-directed supply.
End User:
Buyer type shapes procurement modality, with multinational food manufacturers consolidating direct relationships while smaller players rely on distributor intermediation.
- Food Manufacturers:Multinational sauce and ready meal producers in Germany and France compress supplier negotiation cycles and demand outcome-based flavor performance guarantees. Direct contracting with Spanish processing corridors displaces traditional Central European distributors.
- Dietary Supplement Producers:French and German capsule and sachet specialists seek shelf-stable powder inputs with REACH-registered dossiers and novel food evaluation documentation.
- Cosmetic Companies:Formulators prioritize oil infusion and extract formats with cosmetic ingredient safety assessments under EU Cosmetics Regulation.
- Beverage Organizations:Functional drink manufacturers specify liquid extracts for clean-label flavor modulation in reduced-sugar systems.
- Animal Feed Producers:Premium pet nutrition compounders utilize paste and powder palatability enhancers with feed-grade safety certifications.
Food manufacturers represent the largest procurement volume. Dietary supplement producers drive the steepest growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain concentrates production of heritage Capsicum cultivars while Germany and France absorb the majority of processed volume for clean-label condiment manufacturing. This production-consumption divide shapes procurement logistics and contract structures across the continent.
Spain
Extremadura and Murcia processing corridors anchor supply of authenticated pepper-tomato bases with documented metabolite profiles. EFSA's novel food evaluation pathways govern export documentation for Spanish processors serving French and German buyers. Heritage cultivar fermentation facilities in Cáceres and Albacete expand capacity to meet multi-year supply contracts locked ahead of EU Farm to Fork deadlines.
Germany
Specialty condiment makers in Baden-Württemberg and Bavaria drive premium retail line expansion using Mediterranean-sourced fermented bases. REACH compliance requirements for fermentation-derived extracts filter supplier qualification to established European dossier holders. Clean-label sauce producers in Stuttgart and Munich consolidate direct procurement relationships with Spanish processing corridors.
France
Provence-Alpes-Côte d'Azur specialty condiment sector commands premium positioning for authenticated Mediterranean sourcing claims. EU Clean Labeling guidelines shape reformulation timelines for reduced-sodium sauce manufacturers in Marseille and Nice. Occitanie dietary supplement producers expand capsule applications using Extremadura-sourced powders with REACH-registered documentation.
Italy
Artisan heritage processors in Emilia-Romagna maintain traditional ambient-culture methods for premium retail channel supply. EFSA guidance on natural flavor substantiation creates procurement urgency among Emilian sauce producers seeking compliant umami alternatives. Controlled-culture fermentation facilities in Modena and Parma adopt sensor-integrated bioreactor technology to reduce batch-to-batch variability.
Czechia
Central European private-label supply concentrates in Prague and Brno corridor fermentation facilities serving pan-European distributors. Mixed culture fermentation specialists deploy metabolite profiling analytics to customize ribonucleotide outputs for French and German supplement contract manufacturers. FerMato Sauce s.r.o. anchors geographic dominance in regional private-label channels.
Fermented Mediterranean Pepper and Tomato Complexes Market Competitive Landscape
The competitive structure tilts toward heritage-provenance specialists and controlled-culture industrial suppliers. Three archetypes occupy distinct positions: Mediterranean-sourced heritage authenticators, Central European private-label scale players, and multinational fermentation technology providers. Consolidation pressure intensifies as multinational food manufacturers compress supplier negotiation cycles and demand outcome-based performance guarantees. Capacity expansion and direct-to-manufacturer digital procurement platforms represent the dominant competitive moves reshaping distributor relationships.
Among heritage-provenance specialists, Belazu Ingredient Company leverages its Mediterranean sourcing network to sustain premium positioning across European retail channels. Kerry Group plc anchors industrial supply through controlled-culture fermentation capabilities serving standardized flavor base demand from multinational food manufacturers. FerMato Sauce s.r.o. occupies a position within the Central European private-label tier, competing through geographic proximity to Czech and German processing corridors.
| Leading Market Players |
|---|
| FerMato Sauce s.r.o. |
| Belazu Ingredient Company |
| Eaten Alive |
| Sauce Shop |
| Ajinomoto Co. |
| Danone |
| Kerry Group plc |
| Cargill |
| Chr. Hansen Holding A/S |
| Others |
Pricing and Supply Chain Analysis
Sensor-integrated bioreactor automation in Central European controlled-culture facilities compresses batch-to-batch variability while simultaneously concentrating production economics among capitalized suppliers. This technological shift tightens margin pools for artisan heritage processors in Spain's Extremadura corridor while elevating pricing power for industrial-scale fermentation operators serving multinational food manufacturers.
Pricing Analysis
Margin tightening in paste and concentrate tiers reflects drought-driven volatility in heritage Capsicum harvest yields across Murcia and Extremadura. Three-tier pricing structure across premium authenticated-provenance, standard industrial-grade, and economy private-label levels separates suppliers by metabolite documentation depth and REACH registration status. Cost-down pressure on powder formats accelerates because dietary supplement producers demand shelf-stable inputs with novel food evaluation dossiers. Multinational sauce manufacturers exhibit lowest price sensitivity due to locked multi-year contracts, while mid-sized French condiment makers face acute procurement urgency.
Supply Chain Analysis
EU Farm to Fork Strategy's domestic-content mandates for additive-free reformulation reshape sourcing patterns toward authenticated Mediterranean pepper-tomato bases. Supply concentrates in Spain's heritage cultivar corridors, Germany's clean-label sauce manufacturing clusters, and Czechia's Central European private-label fermentation facilities. Raw material dependencies rest on Extremadura Capsicum annuum harvests, Murcia Solanum lycopersicum supply, and defined Lactobacillus culture stocks. Single-source vulnerability clusters in lactic acid fermentation capacity. Distribution runs through direct-to-manufacturer digital procurement platforms disintermediating traditional Central European ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
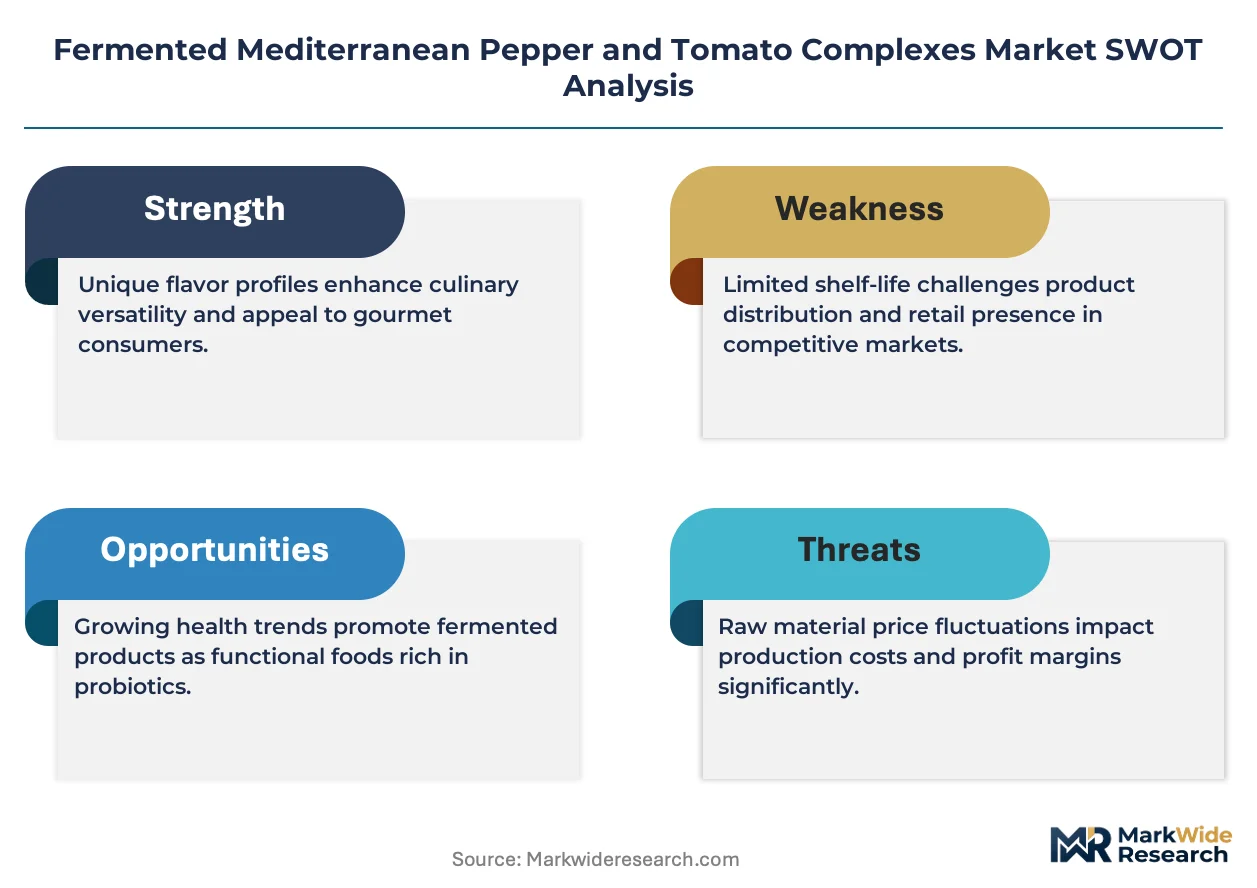
Fermented Mediterranean pepper and tomato complexes operate as a supply-constrained market where heritage cultivar fermentation capacity anchors pricing. EFSA's novel food evaluation timelines and REACH registration bottlenecks prop valuations for established dossier holders.
For Market Incumbents: To counter disintermediation by direct-procurement platforms, anchor defensive positioning through backward integration into Spanish heritage cultivar sourcing corridors and sensor-automated bioreactor capacity expansion in Baden-Württemberg. Lock multi-year supply contracts with Extremadura processors ahead of competitor bidding cycles. Invest in REACH-registered novel food documentation for powder formats to capture nutraceutical channel growth.
For New Entrants and Emerging Players: French dietary supplement contract manufacturers represent the most penetrable buyer archetype seeking authenticated Extremadura-sourced powders with microbiome-targeted metabolite profiles. White-space exists in mixed-culture fermentation customization for specific ribonucleotide ratios. Enter through metabolite profiling analytics partnerships with Czechia-based specialists serving Occitanie capsule producers.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of heritage-provenance specialists with documented Capsicum cultivar authentication and existing EFSA novel food dossiers. Long-term viability frames around 5-10 year windows where clean-label mandate compliance creates durable demand. Watch EFSA microbiome health claims guidance evolution as the critical inflection signal for permissible nutraceutical positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Cultivar Sourcing Integration | Secures authenticated Extremadura and Murcia supply corridors ahead of EU Farm to Fork deadlines. |
| Sensor-Automated Bioreactor Deployment | Compresses quality control labor for mid-sized French and German sauce producers. |
| REACH Registration Investment | Accelerates market access for powder and concentrate formats facing EFSA novel food scrutiny. |
| Direct-to-Manufacturer Digital Platform | Disintermediates traditional Central European distributors in private-label supply channels. |
| Mixed Culture Fermentation Customization | Enables targeted ribonucleotide profiles for French and German dietary supplement contract manufacturers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this fermented Mediterranean pepper and tomato complexes analysis. Primary interviews with fermentation microbiologists, clean-label sauce procurement leads, dietary supplement contract manufacturers, and EFSA regulatory affairs specialists combined with EFSA novel food evaluation databases, REACH registration dossiers, and EU Farm to Fork Strategy implementation reports. Bottom-up volume modeling across paste, powder, liquid extract, concentrate, and oil infusion formats triangulated against top-down value estimates from Spanish processing corridor capacity disclosures.
Granularity-level modeling operated at product form, application, processing technology, and end user dimensions across the projection horizon. Lactic acid fermentation and mixed culture system splits were modeled separately. CAGRs derived from historical volume trajectories in Spanish export statistics and forward procurement contract visibility from German and French food manufacturers. Industry-specific inputs incorporated heritage cultivar harvest yield volatility patterns and EFSA substantiation timeline distributions.
Revisions become necessary when EFSA microbiome health claims guidance shifts, REACH documentation requirements tighten for fermentation-derived extracts, or drought cycles compress Extremadura Capsicum yields beyond historical variance bands. Forecasts reflect documented assumptions about regulatory pathway durations and buyer procurement consolidation patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Condiments
Geranium Oil Market
Spices and Condiments
Peeled Garlic Market
Spices and Condiments
Middle East and Mediterranean Tahini Market
Spices and Condiments
Middle East and Africa Vanilla Beans and Extract Market
Spices and Condiments
Acacia Concinna Extracts Market
Spices and Condiments
Frangipani Extract Market
Spices and Condiments
Mustard Brown Extract Market
Spices and Condiments
Europe Dehydrated Onion Market
Spices and Condiments
Savory Flavor Blends Market
Spices and Condiments
Culinary Powder Market
Spices and Condiments
Asia-Pacific Dehydrated Onion Market
Spices and Condiments
Middle East and Africa Dehydrated Onion Market
Spices and Condiments
Global Pickles and Pickle Products Market
Spices and Condiments
Japanese Curry Market
Spices and Condiments
Global Dehydrated Onion Market
Spices and Condiments
Dehydrated Garlic Market