
 Food Processing and Handling Equipment Market | 2026-2036
Food Processing and Handling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Food Processing and Handling Equipment Market Intelligence
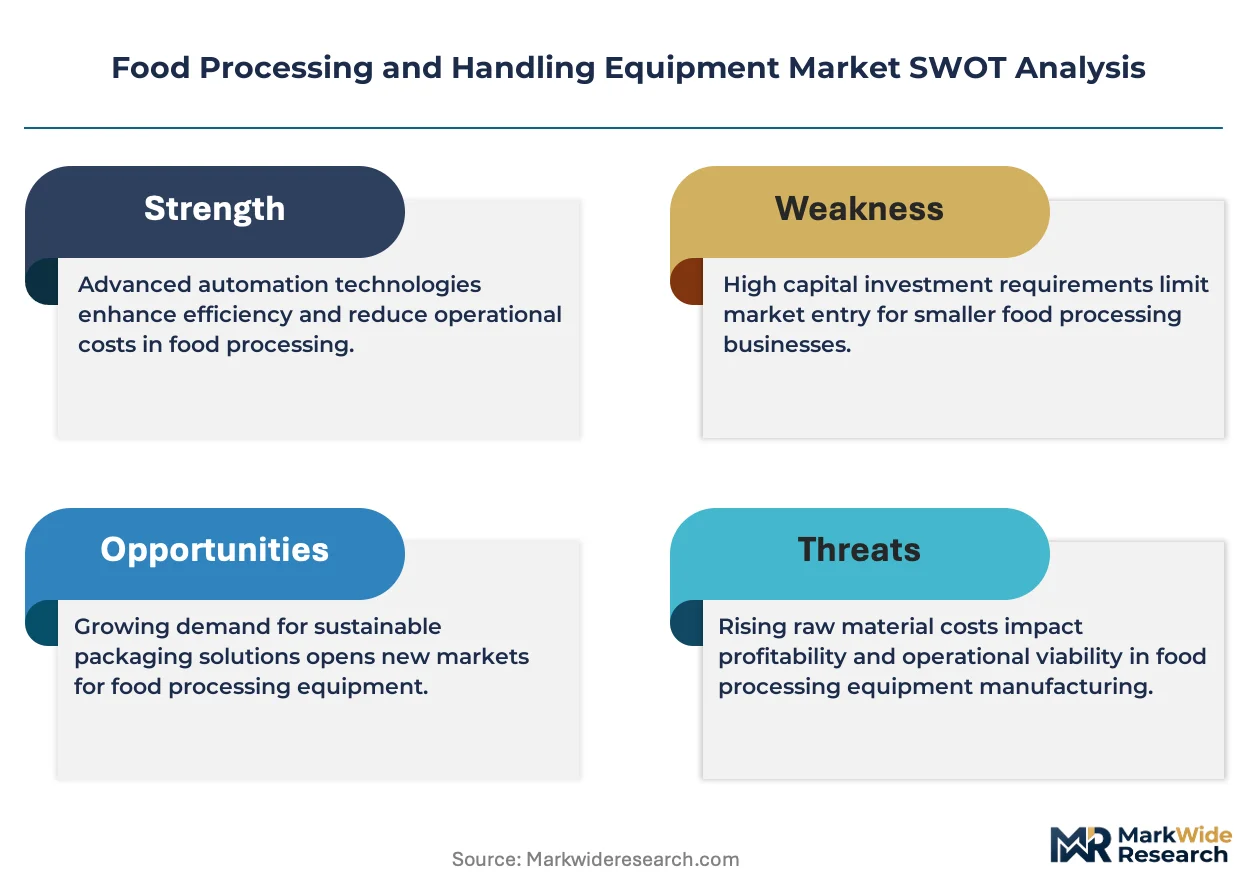
Grade-A sanitary specification upgrades is unwinding legacy equipment replacement cycles across developed manufacturing bases. GEA Group leverages captive engineering networks to dominate thermal processing sub-systems. Bühler AG anchors its position through integrated grain-to-final-product workflows. Alfa Laval competes via membrane and heat transfer specialization in dairy and beverage lines.
Food processing and handling equipment encompasses mechanical systems engineered to stainless steel 304/316 grades with surface finishes below 0.8 micrometers Ra, designed to transform raw agricultural inputs into packaged consumables while maintaining cold chain integrity and pathogen control. Automated technology leads capital deployment as labor costs escalate and throughput precision becomes non-negotiable for food manufacturers. Smart technology represents the fastest-expanding segment, though semi-automated lines retain volume dominance in emerging manufacturing clusters where capital intensity faces budget constraints.
FDA sanitary design standards, EU MDR framework adaptations for food-contact materials, and China's SAMR GB standards collectively elevate compliance costs while filtering sub-scale suppliers from tender pools. EFSA hazard analysis protocols now extend to equipment surface validation, forcing redesign cycles among European vendors. Stakeholders must monitor regulatory divergence between hygiene certification regimes as export-oriented manufacturers face multi-jurisdiction compliance stacking.
Market Dynamics
Smart automation is compressing equipment replacement cycles as food manufacturers face simultaneous pressure from FDA sanitary mandates and labor cost escalation across developed manufacturing bases.
Growth Catalysts
- EFSA hazard analysis protocols:Extended surface validation requirements are forcing equipment redesigns that favor stainless steel 316L specifications with sub-0.8 Ra finishes, benefiting suppliers with captive metallurgy capabilities.
- Ready-to-eat meal manufacturers:Cold chain integrity demands from this segment are pulling investment into integrated thermal processing and packaging lines that maintain pathogen control across continuous operations.
- Membrane filtration specialization:Dairy and beverage processors are upgrading to automated clean-in-place systems that reduce downtime between product changeovers while meeting SAMR GB standards for export qualification.
Market Restraints
- Nickel alloy price volatility:Stainless steel 304/316 input costs swing with LME nickel futures, compressing margin stability for fabricators without long-term supply contracts.
- Captive engineering concentration:Thermal processing subsystem expertise clusters in German industrial zones, creating single-source vulnerability for buyers seeking rapid commissioning support.
- Multi-jurisdiction compliance stacking:Export-oriented manufacturers face simultaneous FDA, EFSA, and SAMR GB certification requirements that extend tender qualification timelines.
Strategic Opportunities
- India FSSAI modernization:Food safety infrastructure upgrades across processing cooperatives create first-mover advantage for equipment vendors offering semi-automated lines at capital intensity levels matching budget-constrained buyers.
- IoT-enabled predictive maintenance:Convergence of sensor networks and cloud analytics allows equipment suppliers to unbundle after-sales service into subscription revenue streams.
- EU Green Deal adaptation:Energy efficiency mandates for thermal processing equipment are accelerating demand for heat recovery integration in retrofit installations.
Industry Challenges
- Sanitary welding certification scarcity:Qualified orbital welders for 316L pharmaceutical-grade joints command premium wages, constraining production capacity expansion at fabricators.
- Legacy PLC integration complexity:Brownfield facilities running proprietary control architectures face disruptive downtime when retrofitting smart automation overlays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Processing and Handling Equipment Market |
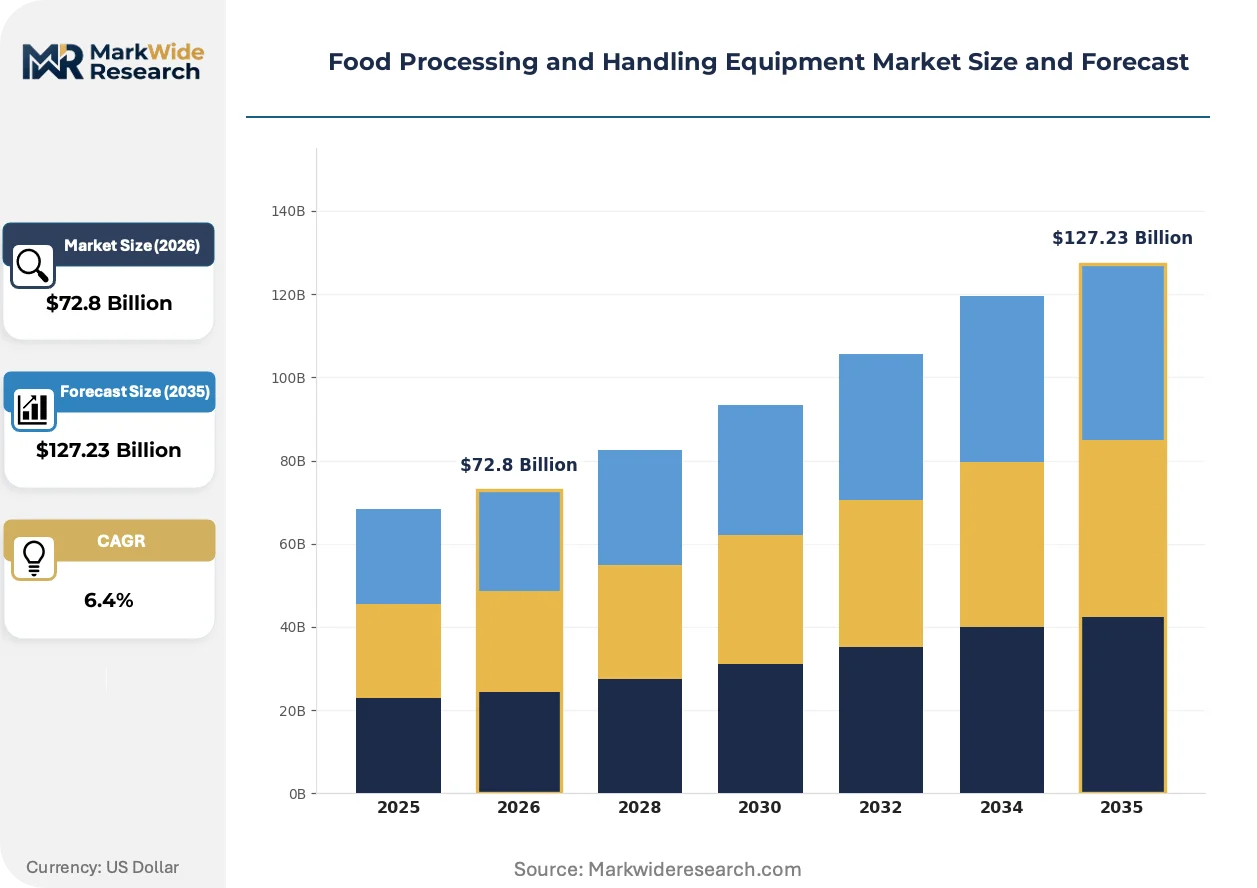
| Market Size in 2026 | $72.8 Billion |
| Market Size in 2035 | $127.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Mixers, Conveyors, Refrigerators, Processors Application: Baking, Freezing, Packaging, Mixing End User: Restaurants, Supermarkets, Food Manufacturers, Cafes Technology: Automated, Manual, Semi-Automated, Smart |
| Companies Covered | GEA Group, Bühler AG, Alfa Laval, SPX Flow, JBT Corporation, Marel, Tetra Pak International S.A., The Middleby Corporation, IMA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Processing and Handling Equipment Market Strategic Shifts & Innovations
Equipment intelligence is migrating from bolt-on sensors to native machine architecture, redefining competitive advantage around data architecture rather than mechanical reliability alone.
Electropolished 316L stainless steel with electrochemical surface passivation is displacing mechanically polished 304 grades in high-acid processing environments. Beverage manufacturers in Germany and the United States are specifying these surfaces for extended run times between cleaning cycles. This material shift is displacing legacy fabricators without in-house electrochemical finishing capabilities from premium tender pools.
EFSA's extension of hazard analysis protocols to equipment surface validation is forcing redesign cycles among European vendors. Manufacturers must now document Ra surface measurements and material traceability through entire supply chains. Dairy processing lines face the steepest compliance burden, with Swiss and Dutch fabricators investing in laser profilometry certification to maintain tender eligibility.
Service unbundling is fragmenting traditional equipment procurement into capital and operating expenditure components. Food manufacturers in China are piloting performance-based contracts where suppliers retain equipment ownership and charge per unit processed. This model is most visible in ready-to-eat meal facilities around Shanghai and Shenzhen, where balance sheet constraints favor operational flexibility over asset ownership.
Food Processing and Handling Equipment Market Segmentation
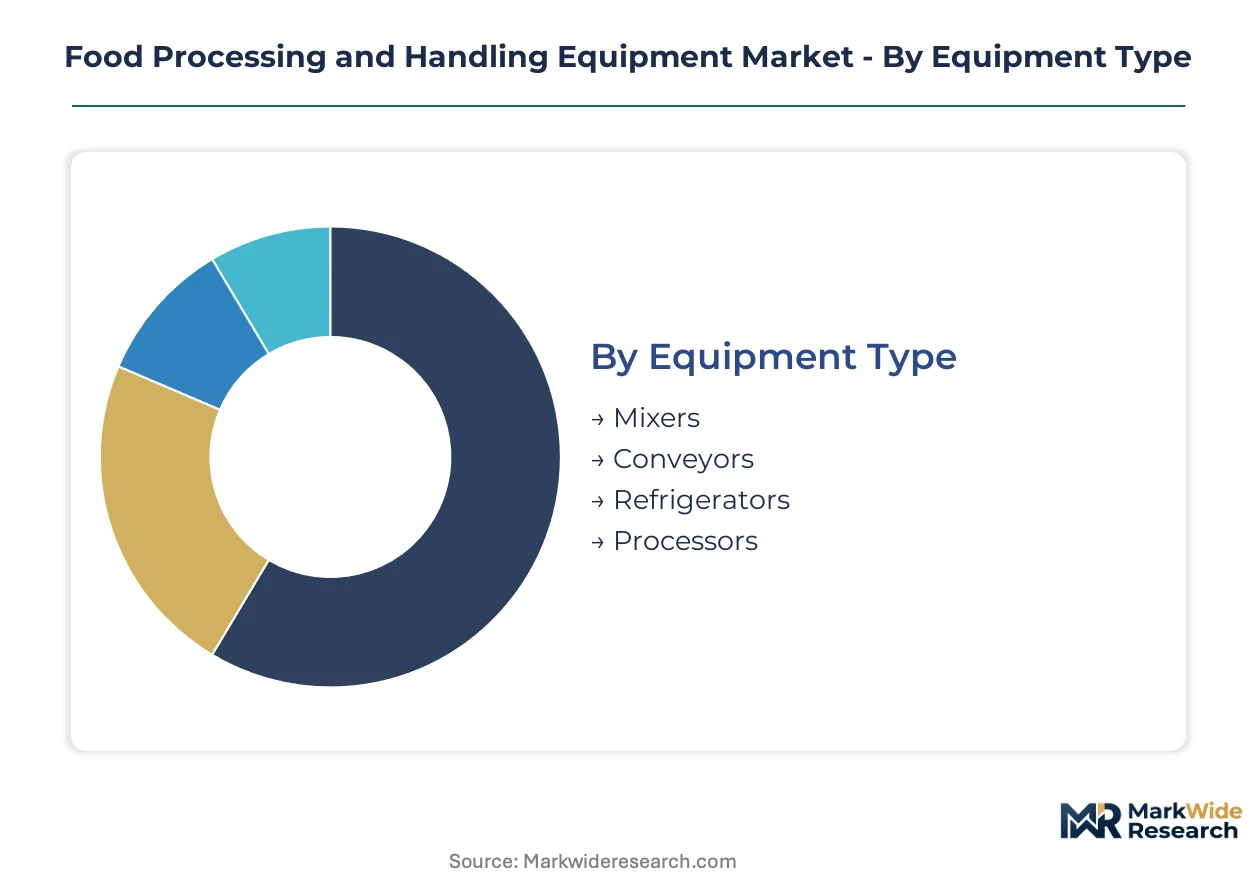
Segmentation in food processing equipment reveals distinct procurement patterns between domestic food service operators and export-oriented manufacturers facing multi-jurisdiction compliance. Equipment specifications diverge sharply across these channels, with sanitary grades and automation levels serving as the primary sorting mechanism.
Equipment Type:
Domestic restaurant and cafe procurement concentrates on compact, standardized units, while export-facing food manufacturers demand custom thermal processing subsystems with full material traceability.
- Mixers:Planetary and spiral configurations dominate high-viscosity dough and batter applications. Demand clusters in German baking cooperatives upgrading to 316L contact surfaces under EFSA surface validation protocols. Stainless steel fabrication with sub-0.8 Ra finishes commands tender priority in EU-qualified installations.
- Conveyors:Modular belt and screw configurations handle bulk solids and packaged goods across continuous processing lines. Cold chain integrity requirements from ready-to-eal meal manufacturers in the United States are pulling investment into sanitary washdown-rated systems with integrated metal detection.
- Refrigerators:Blast chillers and walk-in cold storage units maintain HACCP-critical temperature bands. China's SAMR GB standards for export qualification are accelerating clean-in-place integration in domestic manufacturing clusters around Shanghai.
- Processors:Thermal processing equipment including retorts, extruders, and homogenizers transform raw agricultural inputs. Nickel alloy price volatility constrains margin stability for fabricators without long-term supply contracts.
Processors hold the largest share; momentum sits with conveyors as continuous line integration accelerates.
Application:
Cost tier stratification separates premium sanitary-grade installations from economy food service equipment, with mid-tier systems capturing volume in emerging manufacturing bases.
- Baking:Ovens, proofers, and depositors handle fermentation and thermal transformation of cereal grains. Swiss and Dutch fabricators are investing in laser profilometry certification to maintain EFSA tender eligibility for high-acid processing environments.
- Freezing:IQF tunnels and cryogenic systems preserve cellular structure in prepared foods. Cold chain integrity mandates from FDA sanitary design standards are compressing replacement cycles in United States ready-to-eat facilities.
- Packaging:Form-fill-seal and aseptic filling lines complete product containment. German manufacturers specify electropolished 316L surfaces for extended run times between cleaning cycles.
- Mixing:Batch and continuous blending systems achieve ingredient homogeneity. Semi-automated lines retain volume dominance in India's budget-constrained processing cooperatives under FSSAI modernization programs.
Packaging commands the largest installed base; freezing is expanding most quickly as prepared meal segments scale.
End User:
Customer type determines automation intensity, with food manufacturers deploying full smart automation while food service operators prioritize operational flexibility over capital intensity.
- Restaurants:Compact countertop and floor-standing equipment serves batch production with rapid changeover. United States independent operators favor lease-based procurement models to preserve balance sheet capacity.
- Supermarkets:In-store preparation and deli equipment supports fresh food retailing. EU Green Deal energy efficiency mandates are accelerating heat recovery integration in retrofit installations across German retail chains.
- Food Manufacturers:Industrial-scale continuous processing lines demand 99.9% uptime with automated clean-in-place validation. Performance-based contracts where suppliers retain equipment ownership are piloting around Shanghai and Shenzhen.
- Cafes:Espresso grinders, blenders, and refrigerated display cases serve beverage-focused operations. Capital constraints favor semi-automated equipment with modular upgrade paths.
Food manufacturers represent the dominant revenue pool; supermarkets are gaining share fastest through in-store fresh preparation expansion.
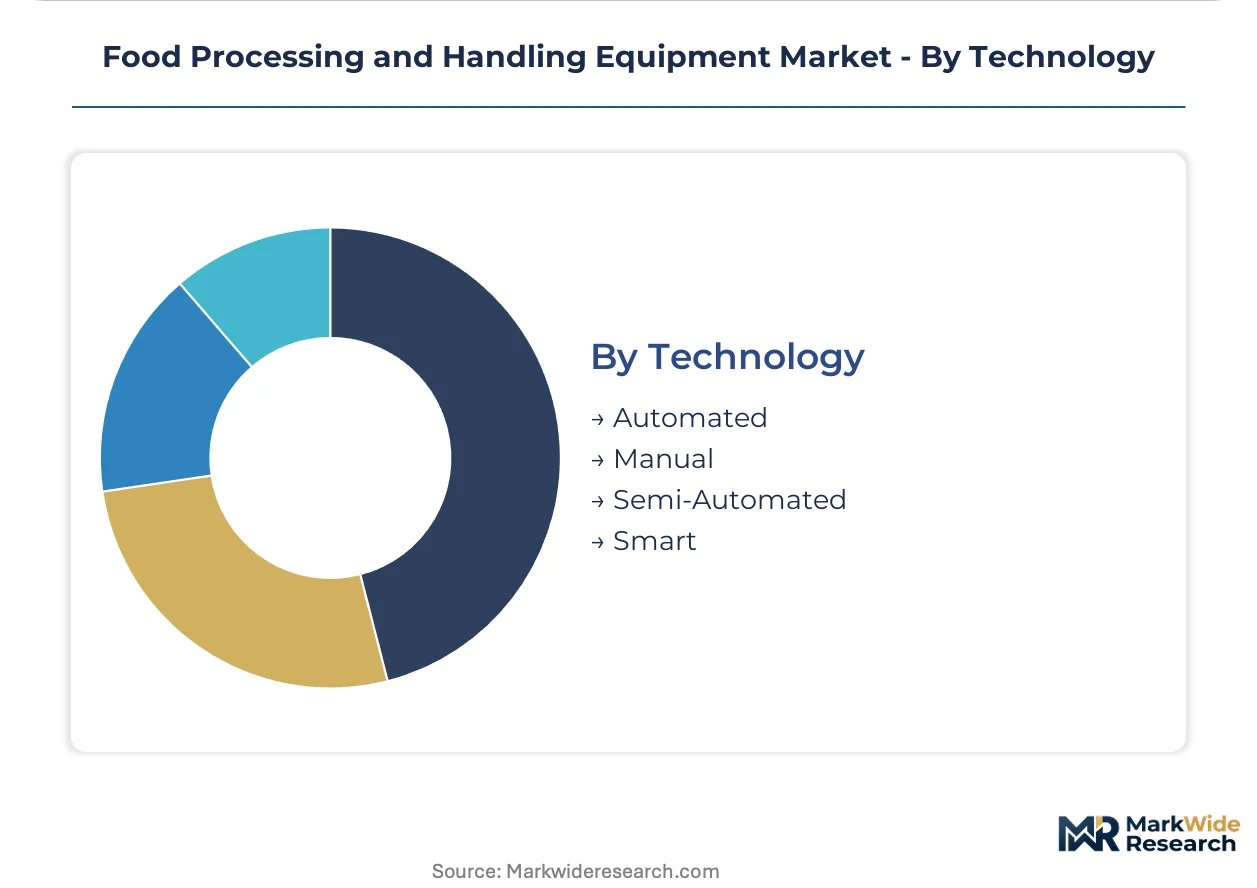
Technology:
Maturity curves diverge across automation levels, with smart technology climbing the fastest while manual equipment retains residual demand in artisanal and small-batch segments.
- Automated:PLC-controlled systems with servo-driven actuation achieve throughput precision non-negotiable for large-scale manufacturers. Legacy PLC integration complexity creates disruptive downtime risks in brownfield United States facilities retrofitting smart overlays.
- Manual:Operator-dependent equipment serves specialty and craft production with low capital barriers. Residual demand concentrates in European artisanal cheese and charcuterie operations prioritizing traditional methods.
- Semi-Automated:Hybrid systems combine operator oversight with mechanized material handling. India's FSSAI modernization creates first-mover advantage for vendors offering capital intensity levels matching budget-constrained buyers.
- Smart:Native machine architecture with embedded sensor networks and cloud analytics enables predictive maintenance unbundling. IoT-enabled service subscriptions are fragmenting traditional procurement into capital and operating expenditure components.
Semi-automated lines retain volume leadership; smart technology shows the steepest expansion trajectory as sensor costs decline and cloud infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across manufacturing bases. United States buyers absorb premium sanitary specifications without volume contraction, while Indian processing cooperatives prioritize capital efficiency over automation intensity.
United States
Ready-to-eat meal manufacturers drive equipment replacement cycles under tightening FDA sanitary design standards. Cold chain integrity mandates compress replacement timelines for thermal processing lines. Chicago and Dallas-Fort Worth industrial corridors concentrate demand for automated clean-in-place systems.
Germany
Baking cooperatives upgrade planetary mixers to 316L contact surfaces under EFSA surface validation protocols. EU Green Deal energy efficiency mandates accelerate heat recovery integration in retrofit installations. Stuttgart and Munich engineering clusters dominate thermal processing subsystem supply.
China
Performance-based contracts pilot around Shanghai and Shenzhen where suppliers retain equipment ownership. SAMR GB standards for export qualification pull investment into integrated thermal processing lines. Yangtze River Delta manufacturing bases prioritize smart automation despite capital intensity constraints.
India
FSSAI modernization programs create procurement windows for semi-automated lines across processing cooperatives. Budget constraints favor hybrid systems with modular upgrade paths over full automation. Maharashtra and Gujarat dairy clusters drive membrane filtration specialization demand.
Japan
Artisanal cheese and charcuterie operations sustain residual demand for manual equipment prioritizing traditional methods. METI industrial standards elevate surface finish specifications for high-acid processing environments. Osaka-Kobe manufacturing zones concentrate precision fabrication for beverage line components.
Food Processing and Handling Equipment Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the equipment spectrum. Premium-tier vendors with captive metallurgy capabilities command tender priority for 316L pharmaceutical-grade specifications. Mid-scale fabricators compete on delivery velocity for standardized stainless steel 304 units. The two dominant competitive moves are strategic partnerships for regional commissioning support and portfolio diversification into IoT-enabled predictive maintenance subscriptions.
Within the integrated engineering tier, GEA Group and Bühler AG exemplify divergent specialization strategies. GEA Group occupies a position concentrated in thermal processing subsystems with German engineering network density. Bühler AG anchors grain-to-final-product workflow integration. Alfa Laval sits within the membrane and heat transfer specialist archetype serving dairy and beverage line requirements. These three represent distinct competitive positioning vectors rather than overlapping market contests.
| Leading Market Players |
|---|
| GEA Group |
| Bühler AG |
| Alfa Laval |
| SPX Flow |
| JBT Corporation |
| Marel |
| Tetra Pak International S.A. |
| The Middleby Corporation |
| IMA Group |
| Others |
Cost & Logistics Intelligence
Capital intensity at stainless steel fabrication facilities in Germany and China establishes minimum viable scale thresholds that compress margin structures for sub-scale competitors across all pricing tiers. These scale thresholds propagate through tender pools as EFSA surface validation protocols and FDA sanitary mandates filter out fabricators lacking captive metallurgy capabilities.
Pricing Analysis
FDA sanitary design standards dictate the pricing tier structure across equipment procurement, with three-tier pricing stratification separating electropolished 316L pharmaceutical-grade systems from mechanically polished 304 standard units and economy-grade food service equipment. Certification level under EFSA hazard analysis protocols and SAMR GB export qualification standards drives price differentiation of fifteen to twenty-five percent between adjacent tiers. Pricing pressure stems from nickel alloy price volatility on LME futures, which compresses fabricator margins without long-term supply contracts. Ready-to-eat meal manufacturers in the United States show lowest price sensitivity due to cold chain liability exposure, while Indian processing cooperatives under FSSAI modernization programs prioritize capital efficiency over specification grade.
Supply Chain Analysis
Strait of Malacca transit routes for nickel ore concentrate from Indonesian mining operations to Chinese stainless steel mills create logistical chokepoints that propagate through equipment fabrication costs. Supply concentration clusters in Germany for thermal processing subsystems, China for integrated line manufacturing, and Italy for specialized conveying equipment. Raw material dependencies center on nickel ore, chromium alloys, and high-purity argon for orbital welding. Single-source vulnerability concentrates in German engineering networks for retort and extruder commissioning support. Distribution runs through regional equipment distributors with captive service capabilities, though performance-based contracting in Shanghai and Shenzhen is fragmenting traditional capital expenditure procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart automation convergence with tightening EFSA and FDA surface validation mandates is compressing replacement cycles and redrawing competitive boundaries across equipment tiers. This regulatory-technology inflection favors vendors with captive metallurgy and native machine architecture capabilities over legacy mechanical specialists.
For Market Incumbents: Consolidate thermal processing subsystem expertise through selective acquisition of German engineering networks with orbital welding certification capacity. Deepen backward integration into electrochemical finishing capabilities to defend margin position against nickel price volatility. Priority investment targets laser profilometry certification infrastructure to maintain EFSA tender eligibility as surface validation protocols extend to dairy and beverage lines. For New Entrants and Emerging Players: Aftermarket predictive maintenance service gaps where incumbents under-serve present white-space entry points around IoT-enabled subscription models. Target India's FSSAI modernization programs with semi-automated lines engineered for modular upgrade paths. Penetrate China's Yangtze River Delta through performance-based contracting structures that transfer balance sheet risk from capital-constrained food manufacturers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors membrane filtration specialists with clean-in-place automation capabilities as dairy and beverage processors upgrade under multi-jurisdiction compliance stacking. Long-term viability hinges on data architecture differentiation rather than mechanical reliability alone. Acquisition target archetype: mid-scale fabricators with SAMR GB certification and captive electropolishing capacity. Signal to watch: tender pool consolidation around equipment-as-a-service contract structures in Chinese ready-to-eat facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrochemical Finishing | Captive 316L surface passivation capability secures EFSA tender eligibility against filtration protocols. |
| IoT-Enabled Predictive Maintenance Launch | Sensor-native architecture unbundles after-sales service into recurring subscription revenue streams. |
| SAMR GB Certification Investment | Export qualification for Chinese food manufacturers opens tender access across Asia-Pacific procurement pools. |
| Performance-Based Contracting Pilot | Equipment ownership retention transfers capital intensity risk from Shanghai ready-to-eat facilities. |
| Orbital Welding Certification Expansion | Pharmaceutical-grade 316L joint capability commands premium positioning as sanitary welding scarcity intensifies. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 483 inspection observations, EFSA scientific opinions on food-contact materials, and SAMR GB standard disclosure documents. Primary interviews engaged equipment procurement directors at ready-to-eat manufacturers, plant engineers at dairy processing cooperatives, aftermarket service heads at regional distributors, and regulatory affairs leads at stainless steel fabricators. Secondary validation drew from customs trade data on nickel alloy imports, SEC 10-K filings of listed equipment vendors, and EFSA hazard analysis protocol amendments. Bottom-up equipment shipment tracking triangulates against top-down manufacturing value-add estimates.
Segmentation dimensions modeled span equipment type, automation technology tier, end-user category, and application vertical across the projection horizon. Analytical framework derives CAGRs from replacement cycle compression rates under sanitary mandate tightening and smart automation penetration curves. Industry-specific forecast inputs incorporate nickel price volatility bands and orbital welder wage inflation trajectories.
Forecasts assume regulatory continuity in FDA sanitary design standards, EFSA surface validation protocols, and SAMR GB export qualification regimes; material policy shifts would require re-modeling of tender pool eligibility and replacement cycle timelines. Practitioners should keep alternative scenarios live as EFSA hazard analysis extension timelines and FSSAI infrastructure commitment levels evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Deaeration Machine Market
Food Processing Equipment
Global Meat Mixer Market
Food Processing Equipment
Granular Ice Machine Market
Food Processing Equipment
Industrial Graters Market
Food Processing Equipment
Commercial Food Refrigeration Equipment Market
Food Processing Equipment
Global Wine Tanks Market
Food Processing Equipment
Global Carbonated Beverage Processing Equipment Market
Food Processing Equipment
Water Cooled Cube Ice Machines Market
Food Processing Equipment
Walk-In Refrigerators & Freezers Market
Food Processing Equipment
Bakery Processing Equipment Market
Food Processing Equipment
Global Industrial Food Blanchers Market
Food Processing Equipment
Nut Processing Machine Market
Food Processing Equipment
Global Snack Pellet Equipment Market
Food Processing Equipment
Crossflow Wine Filters Market
Food Processing Equipment
Magnetic Grill Market
Food Processing Equipment
Defrosting & Thawing Equipment for Food Market