
 Global Meal Replacement Shakes Market | 2026-2036
Global Meal Replacement Shakes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Meal Replacement Shakes Market Foresight
Young professionals seeking convenient nutrition is unwinding the historical dominance of weight-loss-focused buyers in the meal replacement shakes category. Abbott Nutrition leverages its clinical nutrition heritage to anchor hospital and dietitian channels. Herbalife Nutrition sustains its direct-selling infrastructure across emerging markets. Huel differentiates through complete-nutrition positioning and subscription-based distribution.
Meal replacement shakes are formulated beverages delivering controlled macronutrient profiles, typically containing 15-30 grams of protein per serving alongside vitamins, minerals, and fiber, manufactured via spray-drying or liquid blending processes to serve as partial or total food substitutes. Protein-based formulations occupy the largest volume share as sports nutrition applications expand. The clinical nutrition segment leads value generation through higher price realization in hospital and elderly care settings. Online retailers represent the fastest-growing distribution channel as subscription models reduce customer acquisition costs.
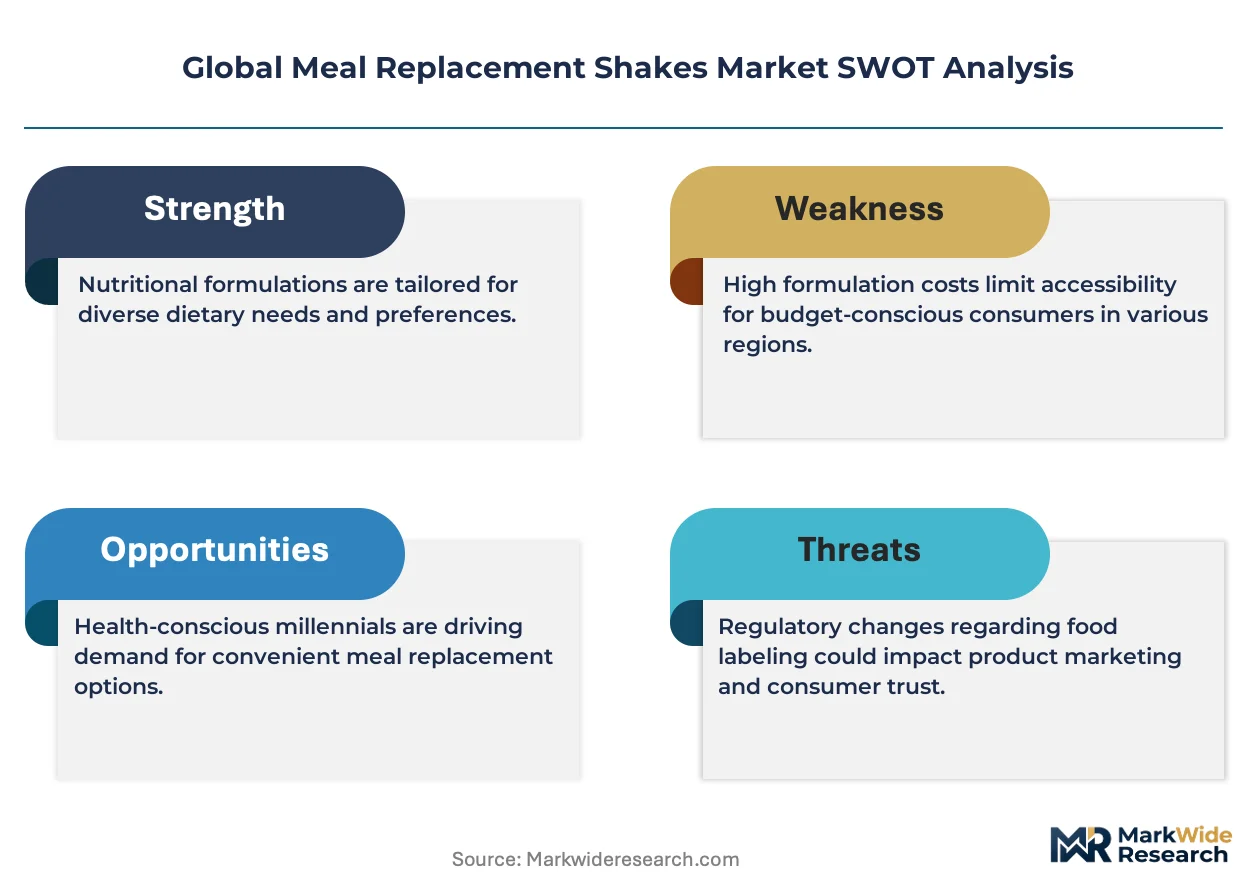
The FDA exercises oversight through nutrition labeling requirements and health claim substantiation, while EFSA in Europe mandates strict scientific evidence for functional claims on packaging. China's SAMR implements GB standards for prepackaged food labeling that constrain import flexibility. Stakeholders must monitor evolving protein source regulations and sugar taxation proposals as these frameworks increasingly determine permissible formulation ranges and market access conditions.
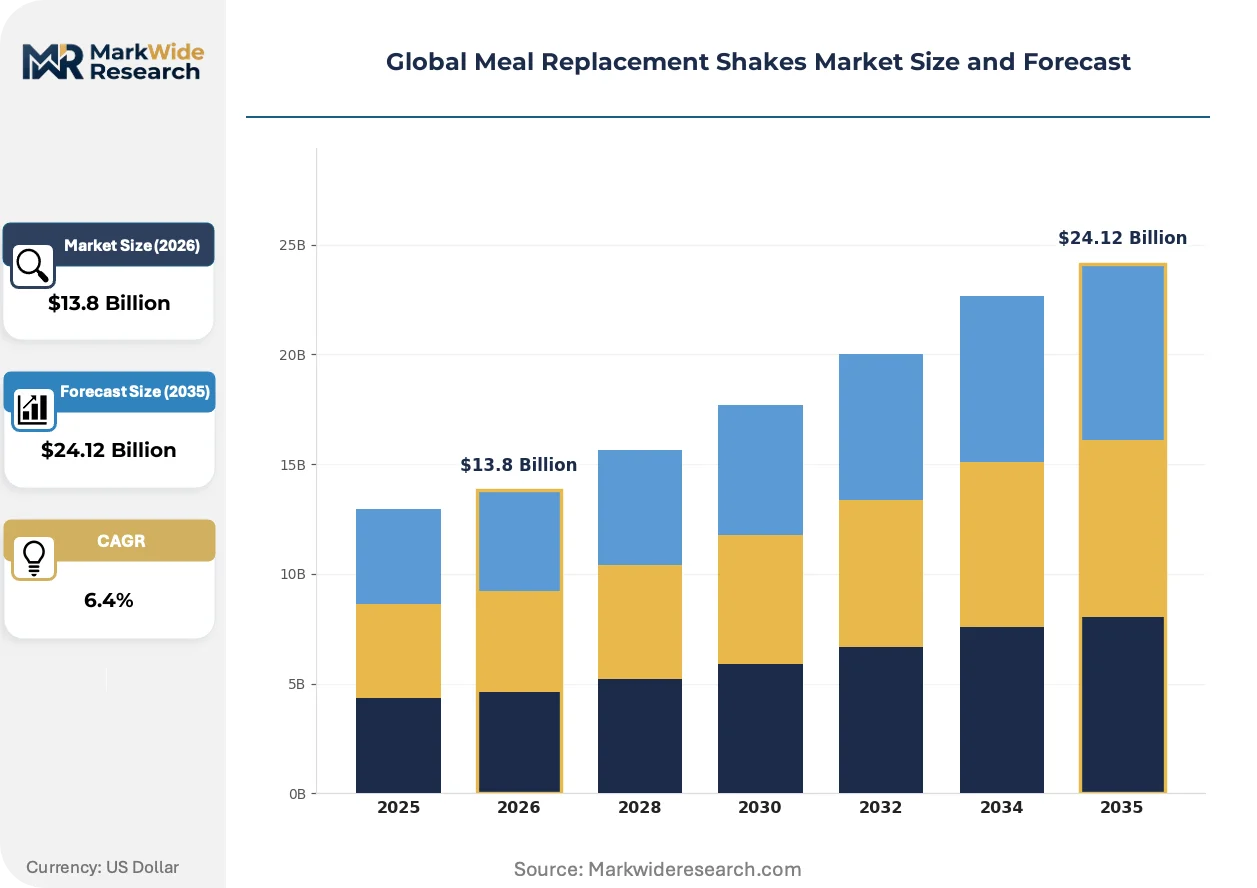
Market Dynamics
The meal replacement shakes market is being fundamentally restructured by the convergence of protein diversification mandates and clean-label enforcement across major regulatory jurisdictions, forcing manufacturers to reformulate around novel inputs while maintaining nutritional density.
Growth Catalysts
- Fitness Industry Expansion:Sports nutrition applications now command substantial volume as gym chains and athletic programs integrate meal replacements into structured dietary protocols.
- EFSA Health Claims Framework:Verified scientific substantiation for protein and micronutrient claims enables premium positioning and hospital channel access across European markets.
- China's Aging Demographics:Elderly care facilities in Shanghai and Beijing are adopting clinical-grade formulations to address malnutrition in institutional settings.
Market Restraints
- Whey Protein Price Volatility:Dairy commodity fluctuations create margin compression for manufacturers dependent on traditional animal-based inputs.
- Supply Concentration Risk:Pea protein isolate production clusters in limited Canadian and French processing facilities, creating geographic vulnerability.
- GB Standards Compliance:China's SAMR labeling requirements constrain import flexibility and extend product registration timelines.
Strategic Opportunities
- India's Urban Professional Class:Metro areas Mumbai and Bangalore show nascent demand for convenient nutrition among tech sector workers.
- Cellular Agriculture Integration:Precision fermentation for dairy-identical proteins offers pathway to decouple from agricultural commodity cycles.
- Subscription Direct-to-Consumer Models:Recurring revenue platforms reduce customer acquisition costs and build consumption habit formation.
Industry Challenges
- Formulation Science Talent Scarcity:Food technologists with dual expertise in clinical nutrition and sensory science command premium compensation.
- Cross-Border Certification Complexity:Divergent FDA, EFSA, and SAMR evidentiary standards require parallel dossier development for multi-territory launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Meal Replacement Shakes Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein-Based, Fiber-Enriched, Vitamin-Fortified, Low-Calorie, Organic Application: Weight Management, Sport Nutrition, Clinical Nutrition, Busy Professionals, Elderly Care Distribution Channel: Online Retailers, Pharmacies, Specialty Stores, Supermarkets, Fitness Centers End User: Dietitians, Athletes, Hospitals, Fitness Enthusiasts, Wellness Clinics |
| Companies Covered | Abbott Nutrition, Nestlé Health Science, Herbalife Nutrition, Glanbia, Huel, Soylent, SlimFast, Amway, Danone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Meal Replacement Shakes Market Shifts & Advancements
Formulation science and distribution architecture are undergoing simultaneous transformation as manufacturers respond to protein source diversification pressures and direct-channel consumer acquisition economics.
Precision fermentation for dairy-identical proteins is decomposing the historical link between whey supply and product availability. Clean-label startups in California and the Netherlands are scaling production of lactoferrin and casein without cow agriculture. This biotechnology is compressing input cost structures for premium positioning while eliminating allergen labeling requirements.
EFSA's updated guidance on protein quality scoring is reshaping European formulation standards. Manufacturers must now demonstrate PDCAAS or DIAAS equivalence for novel plant inputs to retain muscle-maintenance claims. Sports nutrition SKUs targeting German and French athletes are reformulating around fava bean and potato protein concentrates to meet these evidentiary thresholds.
Hospital procurement departments are consolidating vendor relationships around single-source clinical nutrition contracts. Abbott Nutrition and Nestlé Health Science are displacing fragmented regional suppliers through comprehensive enteral and oral nutrition portfolios. This concentration is most visible in United States health systems where GPOs negotiate enterprise-wide agreements spanning acute and post-acute settings.
Global Meal Replacement Shakes Market Segmentation
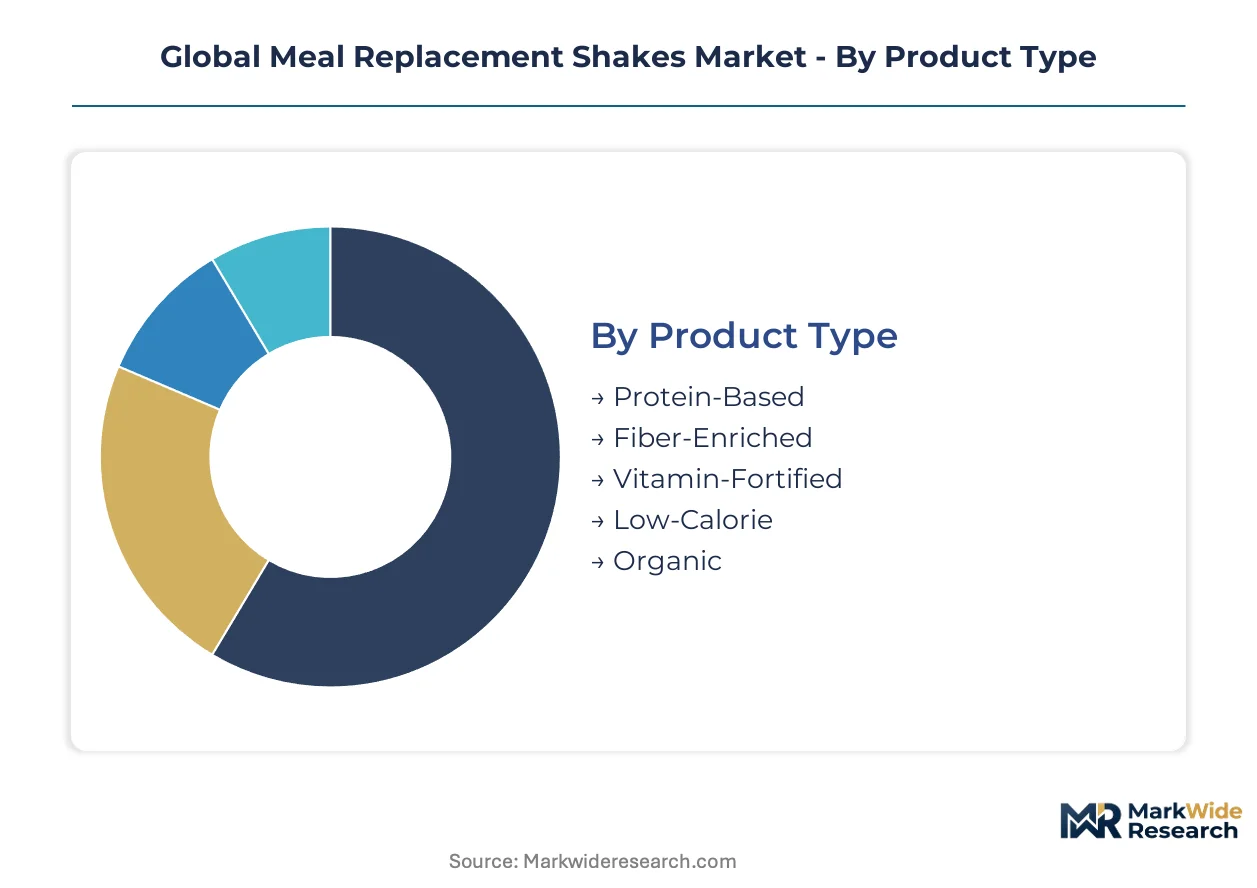
Segmentation in meal replacement shakes determines formulation priorities, regulatory pathways, and channel economics. Manufacturers align R&D investments with end-user nutritional requirements while navigating divergent certification standards across clinical and consumer applications.
Product Type:
Channel mix varies sharply by formulation—protein-based SKUs concentrate in fitness centers and sports specialty retail, while clinical-grade variants flow through hospital procurement and pharmacy networks.
- Protein-Based:Formulations delivering 15-30 grams per serving via whey, casein, or novel plant isolates. Demand concentrates among German and US athletes seeking muscle maintenance claims validated under EFSA protein quality scoring protocols.
- Fiber-Enriched:SKUs incorporating 5-10 grams of soluble and insoluble fiber for glycemic control and satiety. Chinese elderly care facilities in Shanghai are adopting these for diabetes management protocols, constrained by SAMR GB standards on prepackaged food labeling.
- Vitamin-Fortified:Complete micronutrient profiles targeting nutritional adequacy for total meal replacement.
- Low-Calorie:Sub-200 calorie formulations for controlled energy deficit protocols.
- Organic:Certified inputs excluding synthetic pesticides and GMOs, commanding shelf space in premium supermarket channels.
Protein-Based dominates installed base. Fiber-Enriched is where expansion concentrates.
Application:
Margin structures diverge across applications—clinical nutrition commands price premiums through hospital GPO contracts, while sports nutrition scales through volume in gym and direct-to-consumer channels.
- Weight Management:Calorie-controlled formulations with controlled macronutrient ratios for structured dietary protocols. US dietitians prescribe these for obesity intervention programs, though FDA health claim substantiation requirements constrain marketing language.
- Sport Nutrition:High-protein formulations optimized for recovery windows and training adaptation. German athletic programs and French fitness chains integrate these into structured dietary protocols, driving volume through specialty retail.
- Clinical Nutrition:Enteral and oral formulations meeting medical-grade purity standards for hospital and post-acute settings.
- Busy Professionals:Convenience-focused SKUs emphasizing preparation speed and portability for urban commuters.
- Elderly Care:Texture-modified and nutrient-dense formulations addressing malnutrition in institutional settings.
Clinical Nutrition captures value concentration. Sport Nutrition is climbing the fastest.
Distribution Channel:
Customer acquisition economics favor direct channels—subscription models reduce CAC while building consumption habits, though pharmacy and hospital procurement retain gatekeeper status for clinical-grade products.
- Online Retailers:E-commerce platforms and brand-direct subscription services. Huel and comparable direct-to-consumer operators leverage recurring revenue models to reduce customer acquisition costs and lock in consumption patterns.
- Pharmacies:Retail and hospital pharmacy networks requiring OTC or prescription-aligned positioning. China's SAMR registration timelines extend product launch cycles for imported formulations.
- Specialty Stores:Sports nutrition and health food retailers with educated staff and sampling infrastructure.
- Supermarkets:Mass-market retail with placement dependent on slotting fees and velocity metrics.
- Fitness Centers:Gym-based retail integrating with personal training and nutrition coaching services.
Pharmacies dominate installed base. Online Retailers is where expansion concentrates.
End User:
Prescription authority and procurement concentration determine access—hospitals and dietitians function as gatekeepers for clinical applications, while fitness enthusiasts and athletes drive self-directed purchasing.
- Dietitians:Licensed nutrition professionals prescribing formulations for medical nutrition therapy. US hospital systems and German outpatient clinics route patients toward specific SKUs through formal care protocols.
- Athletes:Competitive and recreational athletes with performance-oriented nutritional requirements. EFSA-verified protein quality claims enable premium positioning for this segment across European markets.
- Hospitals:Acute and post-acute care facilities with enterprise procurement contracts.
- Fitness Enthusiasts:Gym members and home exercisers seeking convenient nutrition aligned with training goals.
- Wellness Clinics:Preventive health and functional medicine practices integrating nutrition into holistic protocols.
Hospitals dominate installed base. Fitness Enthusiasts is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites Europe's position as the primary import gateway for novel protein isolates. Union Pacific's refrigerated rail network connects West Coast processing facilities to Midwest distribution hubs. Shanghai Yangshan Port's automated container terminals handle the bulk of clinical-grade formulation imports into China.
United States
Fitness enthusiasts in Texas and Florida drive volume through gym-based retail channels. FDA nutrition labeling requirements constrain health claim language for weight management SKUs. Chicago's distribution corridor anchors national fulfillment networks for subscription-based operators.
Germany
EFSA protein quality scoring protocols enable premium positioning for sports nutrition applications. German athletic programs in Bavaria integrate meal replacements into structured dietary protocols. Cologne's food technology cluster houses formulation labs serving Central European markets.
China
Elderly care facilities in Shanghai and Beijing adopt clinical-grade formulations for malnutrition management. SAMR GB standards on prepackaged food labeling extend product registration timelines for imports. Yangtze River Delta manufacturing bases produce fiber-enriched variants for diabetes protocols.
United Kingdom
Urban professionals in London and Manchester fuel direct-to-consumer subscription growth. EFSA health claims verification applies post-Brexit through retained EU law frameworks. Cambridge's biotechnology corridor hosts precision fermentation startups developing dairy-identical proteins.
India
Tech sector workers in Mumbai and Bangalore generate nascent demand for convenient nutrition solutions. FSSAI labeling requirements for prepackaged foods constrain import flexibility. Hyderabad's pharmaceutical manufacturing belt supplies excipients and micronutrient premixes to regional formulators.
Global Meal Replacement Shakes Market Competitive Landscape
Concentration sits with diversified nutrition conglomerates commanding hospital procurement channels and direct-selling infrastructure. The vendor base spans clinical nutrition specialists, sports nutrition pure-plays, and subscription-native digital brands. Three archetypes dominate: legacy healthcare nutrition houses with GPO relationships, direct-selling networks with emerging market penetration, and direct-to-consumer operators leveraging recurring revenue models. Competitive moves center on portfolio diversification into novel protein sources and geographic expansion through localized formulation facilities.
Within the clinical nutrition tier, Abbott Nutrition and Nestlé Health Science exemplify diversified healthcare portfolios with established hospital channel access. Huel occupies a position as the archetypal subscription-native operator, representing the direct-to-consumer model's challenge to traditional retail economics. Herbalife Nutrition anchors the direct-selling infrastructure archetype, with network distribution capabilities concentrated across emerging markets.
| Leading Market Players |
|---|
| Abbott Nutrition |
| Nestlé Health Science |
| Herbalife Nutrition |
| Glanbia |
| Huel |
| Soylent |
| SlimFast |
| Amway |
| Danone |
| Others |
Supply & Pricing Matrix
Pea protein isolate's displacement of whey concentrate in European formulations simultaneously redistributes sourcing geography toward Canadian and French processing clusters while compressing input cost structures for mid-tier SKUs. This substitution dynamic is reshaping procurement strategies as manufacturers seek insulation from dairy commodity cycles.
Pricing Analysis
Volume-discount tiering structures separate clinical-grade hospital contracts from subscription direct-to-consumer plans and mass-market retail SKUs. Price differentiation hinges on EFSA protein quality certification tiers and brand heritage in clinical channels. Cost compression in standard-tier formulations is intensifying because of pea protein spot price volatility. Hospital procurement departments show lowest price sensitivity while fitness enthusiasts in direct channels exhibit highest elasticity.
Supply Chain Analysis
Inbound logistics costs from Yangshan Port congestion and trans-Pacific container availability constraints are elevating landed costs for clinical-grade imports into China. Pea protein isolate production concentrates in Canada and France, while precision fermentation capacity clusters in California and the Netherlands. Raw material dependencies include dairy-derived proteins, plant isolates, and micronutrient premixes. Single-source vulnerability around Canadian pea protein processing creates geographic concentration risk. Distribution runs through cold-chain rail networks connecting West Coast ports to Midwest fulfillment hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as young professionals seeking convenient nutrition fragment the historical weight-loss buyer concentration, creating white-space for differentiated positioning across multiple price tiers.
For Market Incumbents: Compound channel control through exclusive hospital GPO contracts and subscription platform acquisitions to lock in recurring revenue. Precision fermentation startups threaten traditional dairy-input supply chains. Backward integration into novel protein production secures formulation flexibility. For New Entrants and Emerging Players: Anchor in India's urban professional segment where FSSAI labeling requirements create barriers for imports but demand from Mumbai tech workers remains underserved. Direct-to-consumer subscription models with localized formulation facilities offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward precision fermentation specialists with demonstrated PDCAAS equivalence for novel plant inputs and established EFSA dossier capabilities. Long-term viability across the analysis window rests on regulatory navigation expertise rather than brand equity alone. Watch for SAMR registration timeline acceleration as inflection indicator for China market access.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Dairy-identical protein production decouples from agricultural commodity cycles and eliminates allergen labeling. |
| EFSA Dossier Investment | Verified protein quality claims unlock hospital channel access and premium positioning across German markets. |
| SAMR Registration Acceleration | GB standards compliance reduces import friction and compresses product launch timelines for Shanghai elderly care facilities. |
| Subscription Platform Acquisition | Recurring revenue models reduce customer acquisition costs and build consumption habit formation among urban professionals. |
| Localized Formulation Facilities | Regional production hubs navigate FSSAI labeling requirements and serve nascent demand from Bangalore tech sector workers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement managers, sports nutrition formulators, regulatory affairs specialists at multinational nutrition houses, and direct-to-consumer brand operators. Secondary validation drew from FDA nutrition labeling guidance, EFSA health claims registers, SAMR GB standards documentation, and customs trade records for protein isolate shipments. Bottom-up demand modeling and top-down market sizing were triangulated to ensure consistency.
Across the analysis window, forecasts incorporate product type segmentation by protein source and application tier, distribution channel economics, and end-user prescription authority patterns. CAGRs were derived from regression analysis of historical volume trajectories and elasticity-adjusted demand projections. Forecast inputs include EFSA protein quality scoring adoption rates and precision fermentation capacity buildout timelines.
Material uncertainties — regulatory timeline shifts, commodity price spikes, and biotechnology scale-up delays — sit outside the modeled envelope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Seaweed Protein Market
Alternative Food Sources
Artificial Meat Market
Alternative Food Sources
Mock Meat Market
Alternative Food Sources
Middle East and Africa Meal Replacement Products Market
Alternative Food Sources
Plant-Based Compound Feed Market
Alternative Food Sources
Vegan Egg Substitute Market
Alternative Food Sources
Upcycled Food Products Market
Alternative Food Sources
Gluten-Free Meat Substitutes Market
Alternative Food Sources
Algae Products Market
Alternative Food Sources
Asia-Pacific Algae Protein Market
Alternative Food Sources
Products from Food Waste Market
Alternative Food Sources
Feather Meal Market
Alternative Food Sources
Vegan Casing Market
Alternative Food Sources
Spirulina Beverages Market
Alternative Food Sources
North America Edible Insects Market
Alternative Food Sources
Organic Gluten Substitutes Market