
 Commercial Food Refrigeration Equipment Market | 2026-2036
Commercial Food Refrigeration Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Food Refrigeration Equipment Market Analysis
Natural refrigerant adoption is fragmenting the commercial food refrigeration equipment technology stack as CO2 transcritical and hydrocarbon systems displace legacy HFC architectures. Carrier Global Corporation leverages its compressor manufacturing depth to anchor North American distribution of low-GWP rack systems. Danfoss competes through its valve and control component specialization that sustains European market positioning in energy-optimized installations.
Commercial food refrigeration equipment encompasses insulated cabinet assemblies, compression-based cooling circuits, and environmental control systems engineered to maintain prescribed temperature bands between minus twenty-five and positive ten degrees Celsius for perishable inventory preservation. Walk-in systems dominate capital allocation across supermarket back-of-house operations while display cases capture front-of-store retrofit cycles driven by merchandising refresh programs. Hydrocarbon technology leads new European installations under F-Gas phase-down schedules as CO2 transcritical configurations extend into warmer climate zones previously considered technically marginal.
The EPA SNAP program, EU F-Gas Regulation, and Japan METI refrigerant guidelines collectively restrict high-GWP substance deployment and mandate leak detection protocols that reshape equipment design specifications. Compliance timelines compress product development cycles and elevate certification costs for manufacturers serving multiple regulatory jurisdictions. Stakeholders must monitor refrigerant quota auction outcomes and energy labeling revisions to anticipate equipment replacement waves and regional competitive repositioning.
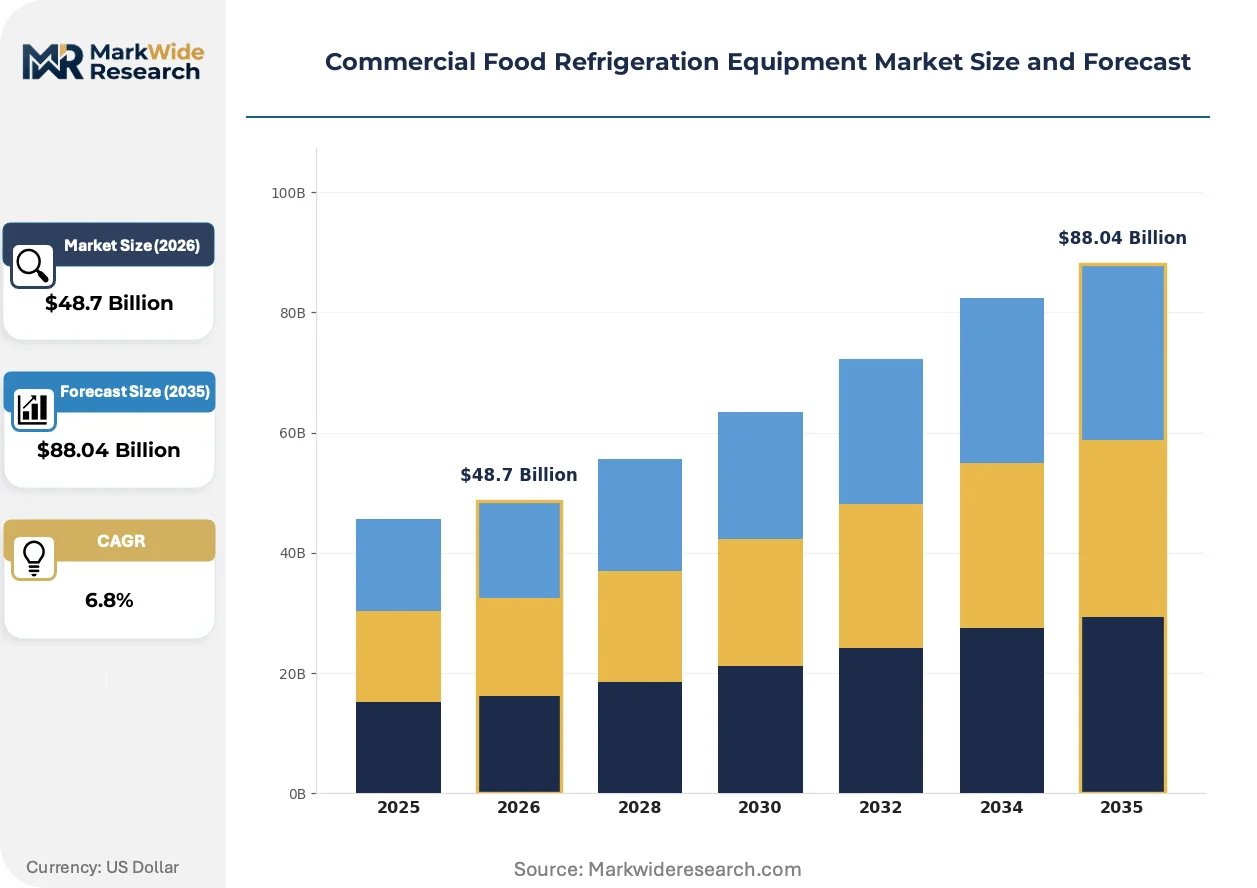
Market Dynamics
Natural refrigerant mandates under the EPA SNAP program and EU F-Gas Regulation are compressing equipment replacement cycles while fragmenting supplier capabilities across CO2 transcritical and hydrocarbon technology stacks.
Growth Catalysts
- EU F-Gas Regulation phase-down:Quota restrictions on high-GWP refrigerants are accelerating supermarket retrofit programs across Germany, France, and Italy.
- Supermarket cold chain expansion:Hypermarket network consolidation in the United States and China is driving procurement of centralized rack systems with remote monitoring.
- CO2 transcritical technology maturation:Compressor efficiency gains in warm climate operation are opening previously marginal markets in the southern United States and Australia.
Market Restraints
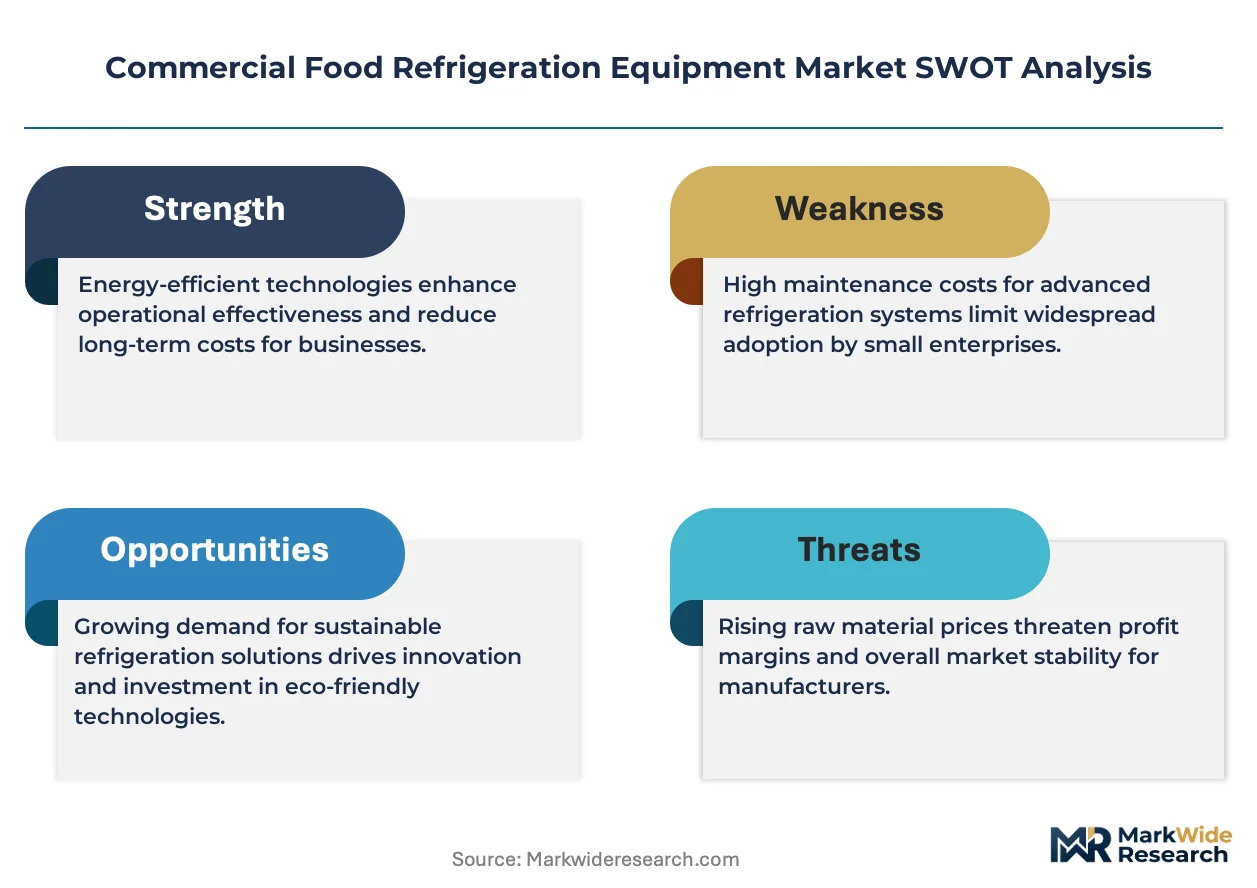
- Copper and aluminum input volatility:Heat exchanger and piping material costs fluctuate with commodity markets, compressing OEM margins on fixed-price contracts.
- Compressor supply concentration:European and Japanese manufacturers control critical CO2 compressor capacity, creating allocation risk during demand surges.
- Technician certification bottlenecks:Hydrocarbon and high-pressure CO2 systems require specialized handling credentials that remain scarce in North American service networks.
Strategic Opportunities
- India cold chain infrastructure:FSSAI food safety mandates and PLI scheme incentives are opening commercial refrigeration deployment in organized retail and food processing.
- Remote diagnostics convergence:Integration of IoT sensors with predictive maintenance platforms enables service revenue unbundling from equipment sales.
- Japan METI refrigerant guidelines:Early adoption timelines for low-GWP alternatives create premium positioning for manufacturers with proven hydrocarbon systems.
Industry Challenges
- Multijurisdictional certification complexity:EPA SNAP, EU CE marking, and Japan JIS standards impose overlapping test protocols that extend product launch timelines.
- Legacy HFC service base obsolescence:Technician retraining costs and parts inventory write-downs strain distributor networks during technology transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Food Refrigeration Equipment Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reach-In, Walk-In, Undercounter, Display Cases End User: Restaurants, Supermarkets, Convenience Stores, Hotels Technology: Hydrocarbon, Ammonia, CO2, HFCs Installation Type: On-site, Modular, Built-in, Portable |
| Companies Covered | Daikin Industries Ltd., Johnson Controls, Dover Corporation, Hussmann Corporation, GEA Group, Carrier Global Corporation, Danfoss, AB Electrolux, Ali Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Food Refrigeration Equipment Market Emerging Trajectories
Equipment intelligence and refrigerant chemistry are converging to redefine performance benchmarks, with connected systems and natural working fluids displacing conventional architectures across installation and retrofit channels.
CO2 transcritical booster systems with parallel compression and ejector technology are extending operating envelopes into ambient temperatures above thirty-five degrees Celsius. Supermarket operators in Australia and the southern United States are specifying these configurations for new construction and full-store renovations. The technology is rendering obsolete the geographic climate limitations that previously restricted CO2 adoption to northern European markets.
The EU F-Gas Regulation's stepped quota reductions are forcing refrigerant cost accounting into total cost of ownership calculations for equipment procurement. Leak detection mandates and maintenance record requirements are reshaping service contract structures and facility management priorities. Cold storage and supermarket segments across Germany, France, and the Netherlands are responding with accelerated replacement schedules and centralized refrigerant management systems.
Food retailers are consolidating vendor relationships and demanding outcome-based performance guarantees that bundle energy efficiency, uptime, and regulatory compliance. Equipment suppliers are repositioning from component sellers to integrated service providers with captive installation and maintenance capabilities. This pattern is most pronounced in the United States, where supermarket chain consolidation has concentrated procurement authority among fewer buyers with standardized specification protocols.
Commercial Food Refrigeration Equipment Market Segmentation
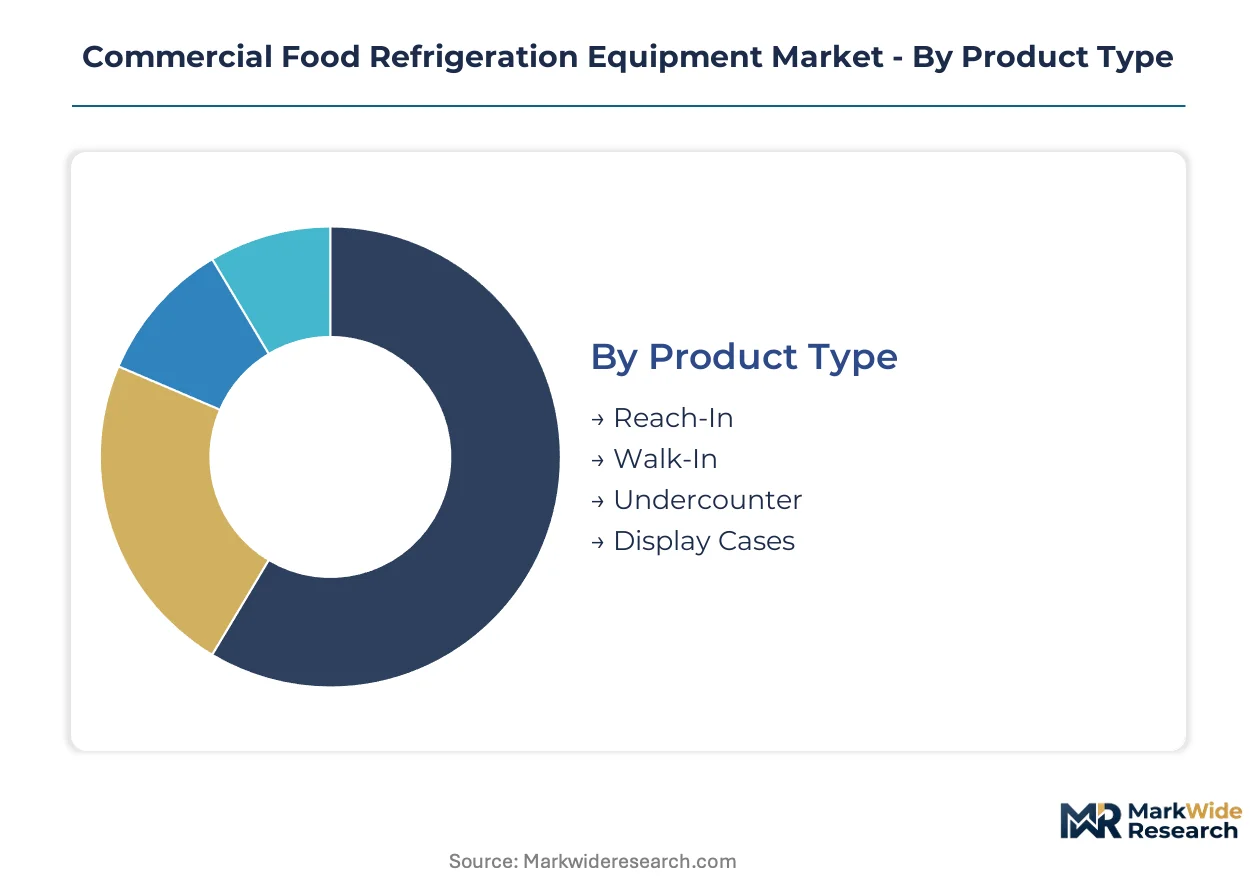
Equipment segmentation in commercial food refrigeration tracks divergent capital deployment patterns across food service formats and regulatory compliance tiers. Product architecture, refrigerant chemistry, and installation modality each command distinct procurement workflows and margin structures.
Product Type:
Volume scale and capital intensity separate equipment categories, with back-of-house systems absorbing the bulk of replacement spending while front-of-store units drive merchandising-led refresh cycles.
- Walk-In:These engineered envelope systems with integrated refrigeration machinery dominate supermarket and food processing back-of-house infrastructure. German hypermarket chains and US cold storage operators are consolidating procurement around centralized rack-fed walk-in complexes with remote monitoring.
- Display Cases:Glass-fronted merchandising units with precise temperature uniformity specifications capture front-of-store retrofit demand. Convenience store chains across Japan and France are accelerating replacement schedules to meet energy labeling and leak detection mandates.
- Reach-In:Self-contained cabinet systems serve mid-scale food service operations with standardized capacity tiers.
- Undercounter:Compact units integrate beneath preparation surfaces for space-constrained kitchen layouts.
Walk-In commands the established base. The steepest expansion runs through Display Cases.
End User:
Customer scale and cold chain sophistication create tiered demand profiles, with consolidated retail networks driving standardization while fragmented food service sustains customization.
- Supermarkets:These multi-zone operators with centralized refrigeration plants represent the highest equipment spend per square meter. US and Chinese hypermarket consolidation is concentrating procurement authority among fewer buyers demanding outcome-based performance guarantees.
- Restaurants:Full-service and quick-service operators deploy distributed equipment portfolios with varied capacity requirements. Independent restaurant clusters in India and Southeast Asia are emerging as volume opportunities under food safety modernization programs.
- Convenience Stores:Small-format retailers with limited back-of-house space prioritize compact self-contained units.
- Hotels:Hospitality operators balance kitchen production needs with in-room minibar and banquet service requirements.
Supermarkets anchor the revenue base. Restaurants are climbing the fastest.
Technology:
Refrigerant chemistry selection now hinges on regulatory jurisdiction rather than climate zone alone, fragmenting supplier capabilities across compliance regimes.
- CO2:Transcritical booster systems with parallel compression extend operating envelopes into ambient temperatures above thirty-five degrees Celsius. Australian and southern US supermarket operators are specifying these configurations as compressor efficiency gains eliminate previous climate limitations.
- Hydrocarbon:Propane and isobutane systems with reduced charge limits lead new European installations. Germany, France, and the Netherlands are deploying hydrocarbon display cases and plug-in units under F-Gas quota pressure.
- HFCs:Legacy hydrofluorocarbon systems face phasedown constraints under EPA SNAP and EU regulations.
- Ammonia:Industrial-scale systems dominate cold storage and food processing applications with strict safety protocols.
CO2 holds the technology leadership position. Hydrocarbon systems are gaining share fastest.
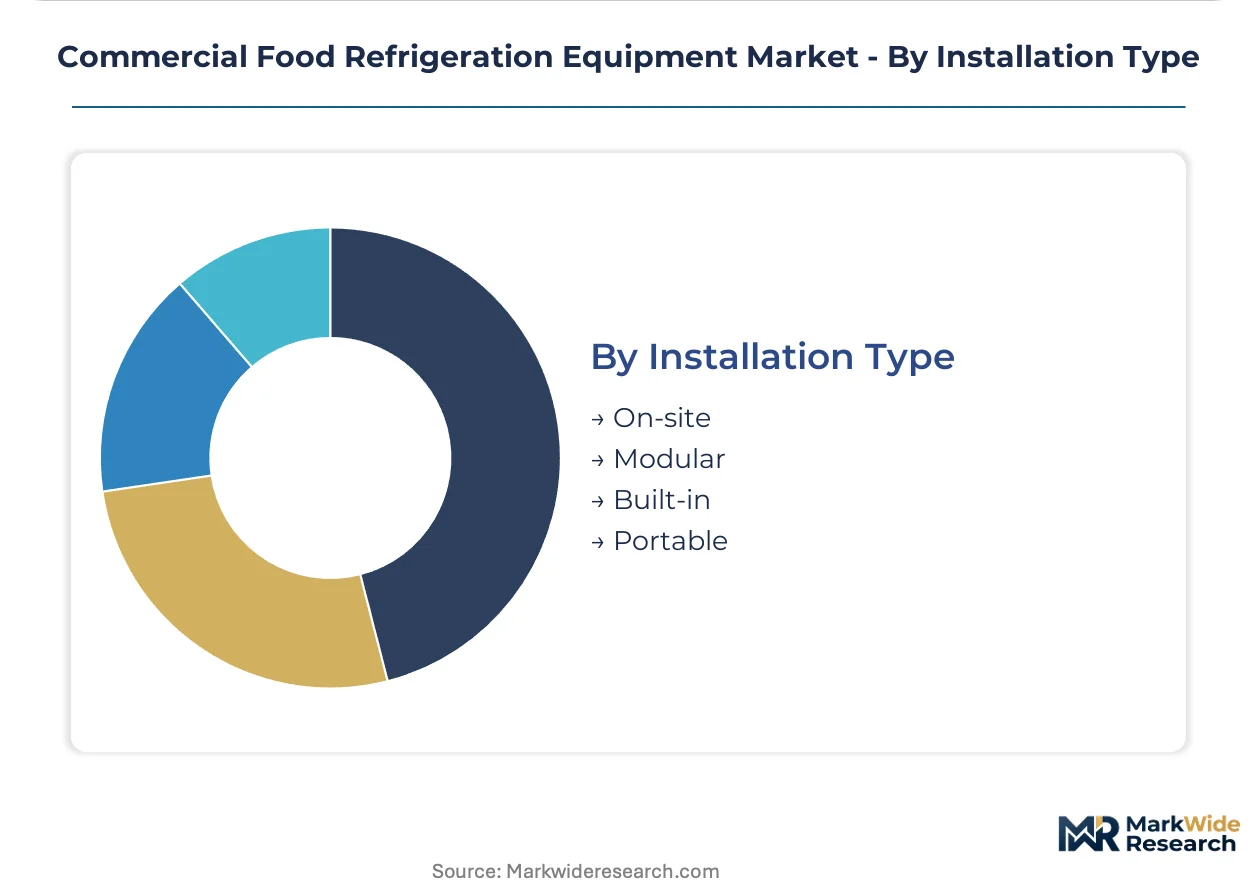
Installation Type:
Deployment methodology shapes total cost of ownership calculations and service contract structures across equipment lifecycles.
- On-site:Custom-fabricated systems assembled at location serve permanent supermarket and cold storage infrastructure. US and German operators favor on-site walk-in construction for facility-specific thermal load optimization.
- Modular:Pre-engineered skid-mounted units with plug-and-connect refrigeration circuits accelerate deployment timelines. China's organized retail expansion is absorbing modular rack systems for rapid store rollout programs.
- Built-in:Integrated cabinet-refrigeration combinations serve space-constrained formats.
- Portable:Mobile units address temporary capacity needs and emergency replacement scenarios.
On-site installation retains the volume base. Modular systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supermarket procurement departments in the United States, Germany, and China concentrate equipment purchasing authority, driving standardization across cold chain infrastructure investments. These three markets absorb the majority of centralized rack system deployments and display case retrofit cycles.
United States
Hypermarket consolidation among Kroger, Albertsons, and Walmart concentrates procurement of CO2 transcritical rack systems with remote monitoring capabilities. EPA SNAP program phase-down schedules for high-GWP refrigerants accelerate replacement timelines in California and Texas. Cold storage clusters in the Chicago metropolitan area and California Central Valley anchor walk-in system demand for food processing and distribution.
Germany
Discounter chains Aldi and Lidl standardize hydrocarbon display case specifications across store renovation programs. EU F-Gas Regulation quota auctions elevate refrigerant cost visibility in total cost of ownership calculations. Industrial refrigeration corridors in North Rhine-Westphalia and Bavaria concentrate manufacturing and cold storage infrastructure serving pan-European food distribution.
China
Organized retail expansion by Sun Art Retail and Yonghui Superstores drives modular rack system procurement for rapid store rollout schedules. National carbon neutrality targets under dual carbon goals pressure state-owned supermarket operators toward energy-efficient equipment. Yangtze River Delta and Pearl River Delta manufacturing clusters produce compressors and heat exchangers for domestic installation and regional export.
Japan
Convenience store operators Lawson and Seven-Eleven Japan accelerate display case replacement under METI refrigerant guidelines favoring low-GWP alternatives. Early adoption timelines for hydrocarbon systems create certification requirements that filter supplier participation. Kanto and Kansai metropolitan areas concentrate supermarket and food service equipment demand with stringent energy labeling compliance.
Australia
Supermarket operators Coles and Woolworths specify CO2 transcritical booster systems as compressor efficiency gains eliminate previous warm-climate limitations. National refrigerant phase-down regulations align with state-level energy efficiency disclosure requirements. Sydney and Melbourne metropolitan corridors anchor commercial refrigeration demand for food retail and hospitality sectors.
Commercial Food Refrigeration Equipment Market Vendor Landscape
Channel-controlling players compete with product-specialist players across divergent capability requirements for refrigerant chemistry and system integration. The market structures around three tiers: full-stack system integrators with captive installation networks, component specialists supplying valves and controls to third-party assemblers, and regional fabricators serving localized retrofit demand. Consolidation pressures concentrate among supermarket-facing suppliers as procurement authority narrows to fewer buyers. Competitive moves center on backward integration into compressor manufacturing and service revenue unbundling through predictive maintenance platforms.
Among diversified industrial conglomerates, Daikin Industries Ltd. and Johnson Controls occupy positions spanning HVAC and refrigeration equipment portfolios. Carrier Global Corporation exemplifies the full-system archetype with integrated manufacturing and service capabilities. Component specialists including Danfoss and GEA Group anchor supply relationships with third-party equipment assemblers seeking energy-optimized control systems. These named entities represent the competitive topology without exhausting the participant base.
| Leading Market Players |
|---|
| Daikin Industries Ltd. |
| Johnson Controls |
| Dover Corporation |
| Hussmann Corporation |
| GEA Group |
| Carrier Global Corporation |
| Danfoss |
| AB Electrolux |
| Ali Group |
| Others |
Supply Flow & Price Mechanics
European compressor manufacturers in Germany and Italy anchor CO2 transcritical capacity, concentrating margin pools with OEMs commanding rack system integration rather than component supply. Copper and aluminum commodity indexation in heat exchanger contracts passes raw material volatility through to supermarket procurement departments via quarterly price adjustment clauses.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate heat exchanger and piping procurement, transferring commodity risk downstream to equipment assemblers. Price differentiation rests on energy efficiency certification tier and remote monitoring capability bundling. Cost compression in standard HFC replacement equipment is intensifying as F-Gas quota auctions elevate refrigerant costs in total cost of ownership calculations. Independent restaurant operators exhibit highest price sensitivity, while consolidated US hypermarket chains prioritize performance guarantees over unit economics.
Supply Chain Analysis
Extended payment terms from 60 to 90 days and supply-chain finance facilities have become standard among European component suppliers serving rack system integrators. Manufacturing concentrates in China, Germany, and the United States for compressors, heat exchangers, and control systems respectively. The supply chain draws from copper rod mills in Chile, aluminum smelters in Russia, and rare earth processors in China for permanent magnet compressor motors. Single-source vulnerability in European CO2 compressor capacity creates allocation risk during demand surges. Distribution runs through captive installation networks for supermarket chains and third-party HVAC contractors for food service accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected refrigeration platforms are redefining competitive boundaries as IoT sensor networks enable predictive maintenance revenue unbundling from equipment sales. Interoperability between supermarket energy management systems and utility demand-response programs is creating new ecosystem control points.
For Market Incumbents: Harden service revenue capture through captive predictive maintenance platforms before third-party software vendors disintermediate equipment relationships. Deepen backward integration into CO2 compressor manufacturing to secure allocation during demand surges. Invest in technician certification programs to alleviate North American service network bottlenecks.
For New Entrants and Emerging Players: Mid-scale food processing facilities in India's organized retail corridor represent the most penetrable entry point under FSSAI modernization mandates. Hydrocarbon display case retrofits in Japan's convenience store sector offer premium positioning before METI guidelines fully mature. Partner with regional fabricators possessing existing installation relationships rather than building captive service networks.
For Investors and Strategic Acquirers: Capital is best deployed toward component specialists with valve and control system expertise that sustains positioning across refrigerant chemistry transitions. Long-term viability hinges on energy efficiency regulatory tightening rather than commodity cycle timing. Monitor EU F-Gas quota auction clearing prices as an inflection indicator for equipment replacement wave acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Secures CO2 transcritical capacity allocation during demand surges from supermarket retrofit programs. |
| Predictive Maintenance Platform Development | Enables service revenue unbunding from equipment sales through IoT sensor network deployment. |
| Hydrocarbon System Certification Investment | Positions suppliers for EU F-Gas Regulation compliance ahead of quota phase-down deadlines. |
| Technician Training Network Expansion | Alleviates North American service bottlenecks for high-pressure CO2 and hydrocarbon systems. |
| Modular Rack System Standardization | Accelerates deployment timelines for China's organized retail store rollout programs. |
Methodological Framework
The analysis maps walk-in systems, display cases, and reach-in equipment segments, each validated through supermarket procurement directors, food service equipment distributors, and compressor manufacturing executives. Primary interviews with refrigeration rack system integrators, aftermarket service technicians, and regulatory compliance officers combined with secondary validation from EPA SNAP filings, EU F-Gas Regulation quota auction records, and METI refrigerant guideline publications. Bottom-up equipment shipment data triangulates against top-down cold chain infrastructure investment tracking.
Assumptions held fixed include current EPA SNAP and EU F-Gas Regulation phase-down schedules, while refrigerant cost trajectories and compressor efficiency improvement curves were varied across sensitivity scenarios. The projection framework models product type, refrigerant chemistry, installation modality, and end-user format segmentation dimensions. CAGRs derive from equipment replacement cycle compression analysis and cold chain expansion intensity metrics. Forecast inputs incorporate supermarket square footage growth patterns and energy labeling revision timelines.
Practitioners should monitor refrigerant quota auction outcomes, copper futures volatility, and technician certification program graduation rates for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
China Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Small Continuous Fryer Market
Food Processing Equipment
Pasty Products Filling Machine Market
Food Processing Equipment
Non-Thermal Food Processing Market
Food Processing Equipment
Air Cooled Cube Ice Machines Market
Food Processing Equipment
Gas Convection Oven Market
Food Processing Equipment
Deep Fryer Oil Filtration Market
Food Processing Equipment
UHT Systems Market
Food Processing Equipment
Industrial Fryers Market
Food Processing Equipment
Industrial Planetary Mixers Market
Food Processing Equipment
Shawarma Grill Machine Market
Food Processing Equipment
Tangyuan Machine Market
Food Processing Equipment
Fish Feed Pellet Making Machine Market
Food Processing Equipment
Bottled Water Processing Equipment Market
Food Processing Equipment
Contact and Convective Dryers Market
Food Processing Equipment
Global Shawarma Machines Market