
 Industrial Graters Market | 2026-2036
Industrial Graters Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Graters Market Foresight
Aftermarket blade sharpening and replacement drum services is rewriting margin capture for original equipment suppliers. Hobart Corporation leverages its North American service network to sustain recurring revenue streams beyond initial equipment sales. Sirman Spa anchors its competitive position through Italian manufacturing scale and specialized distribution across European foodservice channels. Deville Technologies differentiates via precision-engineered cutting assemblies that extend operational lifespan in high-volume cheese processing facilities.
Industrial graters are electromechanical or manually operated machines designed to reduce solid foodstuffs into uniform particles through rotary drum or planar blade mechanisms, typically constructed with 304-grade stainless steel contact surfaces and motors rated between 0.5 and 3 horsepower for continuous duty cycles. These systems serve commercial kitchens and food production lines where consistency, throughput, and sanitation compliance replace manual preparation methods. Electric graters command the largest installed base due to labor cost arbitrage in centralized food production, while heavy-duty configurations with carbon steel cutting heads capture premium pricing in agricultural product processing where abrasive raw materials accelerate wear. Multi-functional graters integrating slicing and dicing modules represent the fastest expansion category as food manufacturers consolidate prep-line footprints.
Food contact material regulations from EFSA and CE machinery safety directives govern European market access, while FDA 21 CFR food equipment standards shape product specifications for US-bound exports. NSF International sanitation certification functions as a de facto gatekeeper for institutional procurement in North American school and hospital foodservice. Stakeholders must monitor evolving EU Green Deal requirements for repairability and energy efficiency labeling that will reshape equipment design priorities and aftermarket service obligations.
Market Dynamics
EU Green Deal repairability mandates are forcing equipment redesign cycles toward modular, serviceable architectures that extend asset lifecycles and lock in aftermarket revenue for original manufacturers.
Growth Catalysts
- EFSA food contact material standards:Stainless steel drum specifications are tightening across European commercial bakeries, mandating equipment upgrades that favor certified suppliers.
- Agricultural processing clusters:Abrasive root vegetable handling in Benelux and Eastern European facilities is driving replacement demand for carbon steel cutting head configurations.
- Multi-functional consolidation:Slicing-dicing module integration is compressing prep-line footprints in centralized food production facilities.
Market Restraints
- Nickel price volatility:304-grade stainless steel input costs fluctuate with commodity markets, squeezing margin stability for drum fabricators.
- Single-source motor supply:Continuous-duty 0.5-3 horsepower electromechanical drives concentrate among German and Italian component suppliers.
- Manual grater substitution:Low-volume artisan producers in Mediterranean markets retain hand-operated equipment for specialty cheese grades.
Strategic Opportunities
- CE marking plus energy efficiency labeling:Dual compliance positioning opens institutional procurement channels in Nordic public foodservice.
- Blade sharpening subscription models:Predictive maintenance contracts are penetrating North American hospital and school kitchen networks.
- Precision cutting assembly convergence:Integration of optical sorting with rotary drum mechanisms targets high-volume cheese processing lines.
Industry Challenges
- NSF sanitation certification timelines:Third-party validation cycles for institutional buyers create 12-18 month sales friction.
- Retrofit integration complexity:Legacy planar blade systems in aging French and Italian facilities resist electromechanical upgrades without full line reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Graters Market |
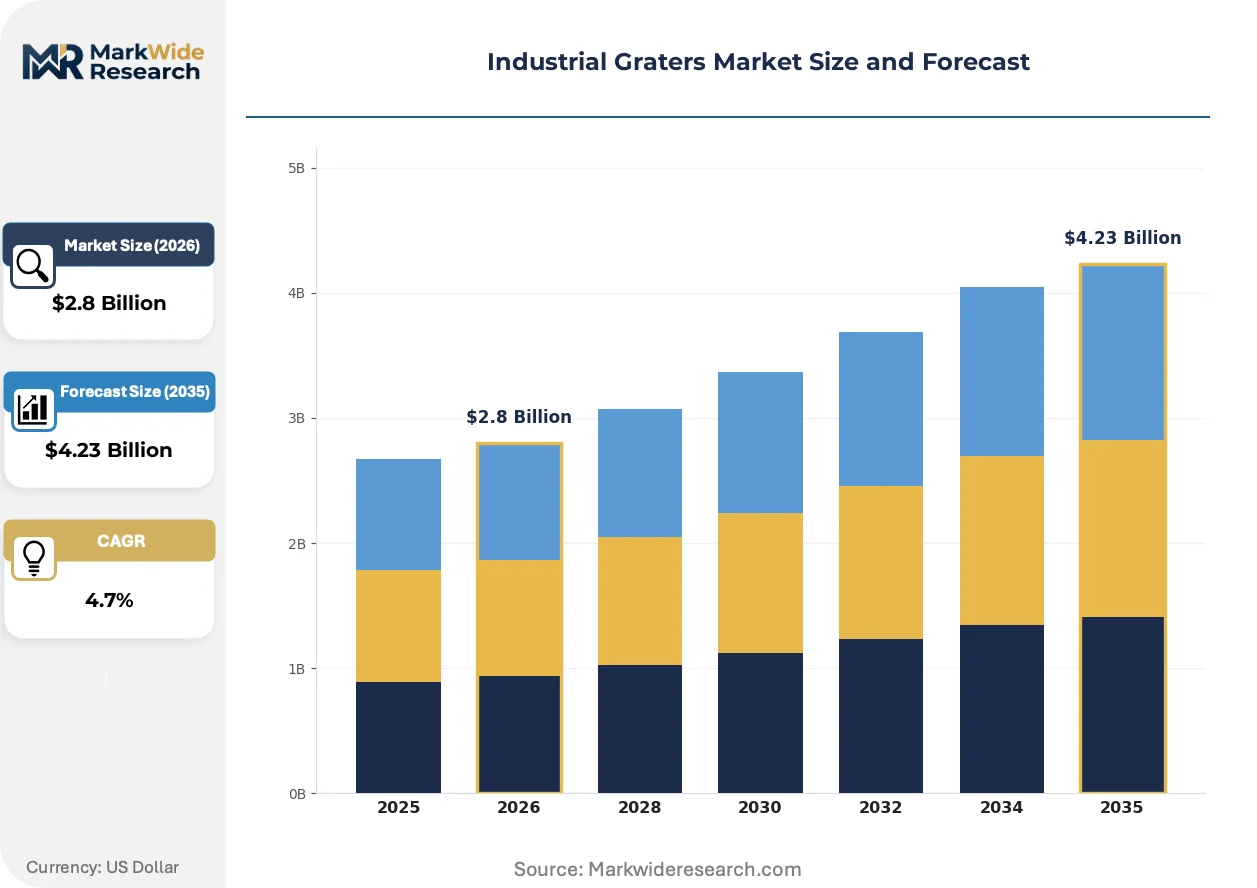
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Graters, Electric Graters, Heavy-Duty Graters, Multi-Functional Graters Material: Stainless Steel, Plastic, Aluminum, Carbon Steel Application: Food Processing, Agricultural Products, Industrial Cooking, Bakeries End User: Food Manufacturers, Restaurants, Catering Services, Home Users |
| Companies Covered | Robot Coupe, Hobart Corporation, The Vollrath Company, Sirman Spa, Deville Technologies, Travaglini S.p.A., Arsopi, Hajek Maschinenbau, Fam Stumabo USA Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Graters Market Shifts & Advancements
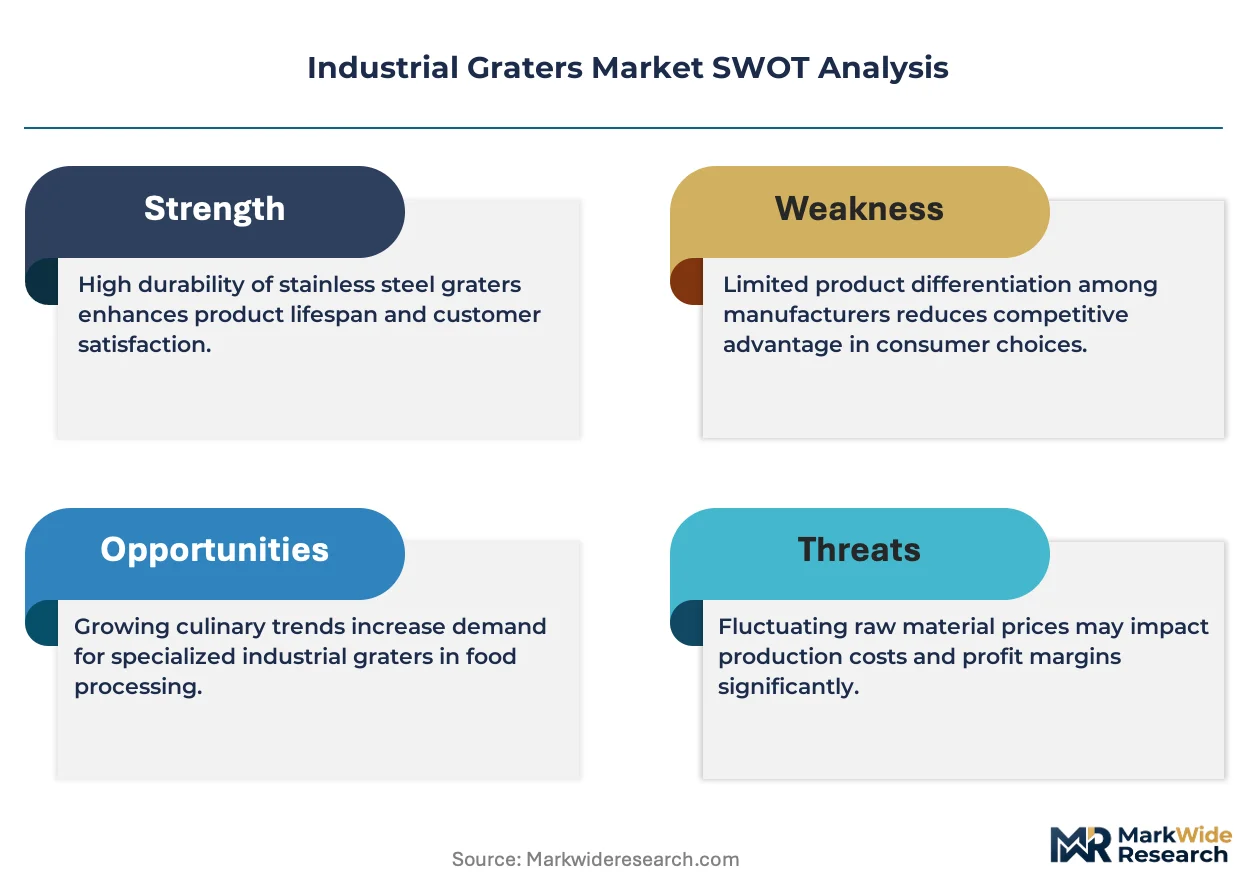
Equipment architecture is pivoting toward predictive maintenance integration and modular component standardization, compressing total cost of ownership calculations for capital-constrained buyers.
Sensor-embedded drum assemblies are virtualizing condition monitoring for cutting surface wear. High-volume cheese processors in Wisconsin and Lombardy are piloting these systems to eliminate unplanned downtime. Real-time data feedback is virtualizing traditional scheduled maintenance intervals into usage-triggered service events.
EU Green Deal repairability requirements are mandating disassembly documentation and spare parts availability timelines. Equipment manufacturers must now design for component-level replacement rather than full-unit disposal. German and Dutch food manufacturers are prioritizing suppliers with modular architectures that satisfy these emerging obligations.
Buyer concentration among contract foodservice management companies is consolidating procurement authority. Aramark, Compass, and Sodexo equivalents are standardizing equipment specifications across multi-site operations, displacing fragmented local purchasing. This concentration is most visible in UK and US institutional foodservice channels where national account pricing now dominates regional distributor relationships.
Industrial Graters Market Segmentation
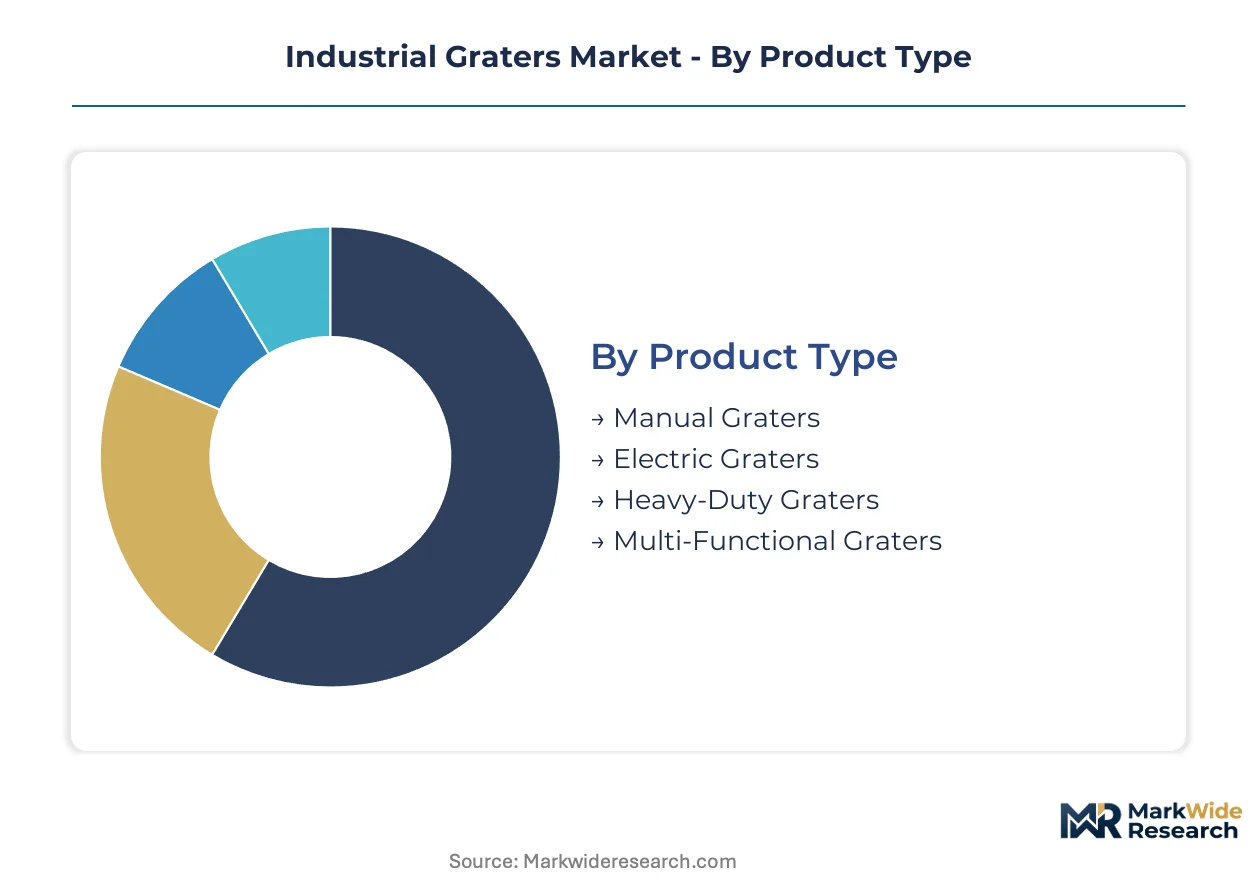
Segmentation in the industrial graters market determines service lifecycle economics and aftermarket revenue capture. Equipment configuration directly shapes blade replacement frequency, sharpening service intervals, and spare parts attach rates that manufacturers rely on for margin sustainability.
Product Type:
After-sales service intensity varies dramatically across product configurations, with electromechanical systems generating recurring maintenance contracts while manual units produce minimal follow-on revenue.
- Manual Graters:Hand-cranked rotary drum mechanisms with cast iron or carbon steel cutting heads require no electrical infrastructure and suit low-volume artisan cheese producers in Mediterranean markets. Demand concentrates among specialty food manufacturers in rural France and Italy where traditional production methods command premium positioning.
- Electric Graters:Continuous-duty motors rated 0.5-3 horsepower drive rotary drum assemblies, dominating commercial bakery procurement across Germany, France, and Spain due to labor cost arbitrage in centralized production. Service networks capture recurring revenue through scheduled maintenance and motor replacement programs.
- Heavy-Duty Graters:Reinforced carbon steel cutting heads withstand abrasive root vegetable processing in Benelux agricultural facilities.
- Multi-Functional Graters:Modular slicing-dicing integration compresses prep-line footprints in contract foodservice operations.
By volume, Electric Graters leads. By growth pace, Multi-Functional Graters is ahead.
Material:
Raw material cost tiers stratify procurement decisions, with commodity price volatility directly impacting drum fabricator margin stability and buyer total cost of ownership calculations.
- Stainless Steel:304-grade contact surfaces meet EFSA food contact material standards and NSF sanitation certification requirements, commanding premium positioning in institutional foodservice. German food manufacturers prioritize this specification for EU hygiene compliance.
- Carbon Steel:Hardened cutting edges excel in abrasive agricultural applications where wear resistance outweighs corrosion concerns, capturing replacement demand in Eastern European vegetable processing clusters.
- Plastic:Polymer housings reduce unit weight for mobile catering applications.
- Aluminum:Lightweight drum substrates serve cost-sensitive commercial kitchen segments.
By installed base, Stainless Steel dominates. By replacement velocity, Carbon Steel generates higher service revenue.
Application:
End-use environment dictates equipment specification intensity, with regulatory compliance requirements escalating from agricultural processing through institutional foodservice channels.
- Food Processing:High-throughput rotary drum configurations serve centralized production facilities where consistency and sanitation compliance replace manual preparation, particularly in Wisconsin and Lombardy cheese processing corridors.
- Bakeries:Automated shredding modules reduce labor costs across French, Italian, and Spanish commercial bakery networks.
- Agricultural Products:Abrasive root vegetable handling accelerates cutting head wear in Benelux facilities.
- Industrial Cooking:Large-batch preparation systems integrate into contract foodservice management company specifications.
By equipment value, Food Processing commands highest unit pricing. By contract consolidation, Bakeries is standardizing fastest.
End User:
Customer scale and procurement sophistication determine pricing architecture, with national account concentration displacing fragmented local purchasing in institutional channels.
- Food Manufacturers:Centralized production facilities in Germany and the Netherlands prioritize modular, repairable architectures satisfying EU Green Deal requirements, generating predictable aftermarket service revenue for original equipment suppliers.
- Catering Services:Mobile and contract operators standardize equipment specifications across multi-site operations.
- Restaurants:Independent operators retain fragmented purchasing through regional distributors.
- Home Users:Minimal penetration in industrial-grade equipment categories.
By service contract penetration, Food Manufacturers leads. By procurement consolidation velocity, Catering Services is restructuring fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Mediterranean artisan markets retain hand-cranked equipment despite labor inefficiencies, while German and Dutch food manufacturers absorb premium pricing for modular electric systems that satisfy repairability mandates. Price elasticity diverges sharply between cost-sensitive agricultural processors in Eastern Europe and institutional buyers in Nordic public foodservice channels.
Germany
Commercial bakeries in Bavaria and North Rhine-Westphalia are standardizing procurement of electric graters with 304-grade stainless steel drums to meet EFSA food contact material standards. CE marking plus emerging EU Green Deal energy efficiency labeling requirements are reshaping equipment specifications for institutional buyers. The Stuttgart industrial corridor hosts concentrated demand from centralized food production facilities prioritizing modular, serviceable architectures.
France
Artisan cheese producers in rural Auvergne and Provence retain manual graters for specialty grade positioning, while Paris-region contract foodservice operators consolidate toward multi-functional electric systems. EFSA hygiene compliance mandates are accelerating replacement cycles in commercial bakery networks across Île-de-France. The Lyon food processing cluster is piloting sensor-embedded drum assemblies for predictive maintenance integration.
Italy
Lombardy cheese processing corridors in Milan and Bergamo are driving demand for precision-engineered cutting assemblies that extend operational lifespan in high-volume environments. Sirman Spa anchors specialized distribution across domestic foodservice channels. Emilia-Romagna's agricultural processing facilities are adopting heavy-duty carbon steel configurations for abrasive root vegetable handling.
United States
Wisconsin cheese processors are piloting optical sorting integration with rotary drum mechanisms, while institutional foodservice networks in Chicago and New York Metro standardize around NSF sanitation certification requirements. FDA 21 CFR food equipment standards shape product specifications for domestic procurement. Hobart Corporation leverages its North American service network to sustain recurring revenue through blade sharpening subscription models in hospital and school kitchen networks.
Netherlands
Benelux agricultural processing clusters in Rotterdam and Eindhoven are generating replacement demand for carbon steel cutting heads in abrasive vegetable handling applications. Dutch food manufacturers are prioritizing suppliers with modular architectures that satisfy EU Green Deal repairability and spare parts availability timelines. Randstad contract foodservice operators are compressing prep-line footprints through multi-functional grater adoption.
Industrial Graters Market Competitive Landscape
Full-line industrial equipment conglomerates and specialized foodservice fabricators split the market into distinct competitive spheres with divergent service model economics. Conglomerates leverage integrated distribution and aftermarket networks to capture recurring maintenance revenue, while specialists compete on cutting assembly precision and regional customization. Three archetypes dominate: scale-driven multi-product manufacturers, precision-engineering specialists, and regional service-integrated fabricators. Competitive dynamics center on M&A consolidation of distribution channels and vertical integration into blade sharpening and replacement drum services.
Within the precision-engineering specialist tier, Deville Technologies and Sirman Spa occupy positions defined by cutting assembly specialization and Italian manufacturing scale respectively. Robot Coupe exemplifies the European full-line conglomerate archetype with integrated foodservice equipment portfolios. Hobart Corporation anchors the North American service-integrated segment through captive aftermarket networks. These three entities collectively represent the strategic positioning spectrum: precision differentiation, manufacturing scale, and service infrastructure capture.
| Leading Market Players |
|---|
| Robot Coupe |
| Hobart Corporation |
| The Vollrath Company |
| Sirman Spa |
| Deville Technologies |
| Travaglini S.p.A. |
| Arsopi |
| Hajek Maschinenbau |
| Fam Stumabo USA Inc. |
| Others |
Supply & Pricing Matrix
Nickel price volatility in 304-grade stainless steel markets compresses margin stability for drum fabricators while simultaneously widening pricing spreads between certified institutional-grade equipment and cost-sensitive commercial kitchen alternatives. This commodity exposure cascades through procurement decisions, forcing buyers to choose between premium EFSA-compliant configurations and lower-tier carbon steel substitutes that accelerate replacement cycles.
Pricing Analysis
Aftermarket blade sharpening and replacement drum services generate the dominant lifetime value capture for original equipment suppliers. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified institutional systems from CE-marked commercial units and unbranded import alternatives. Cost compression in economy tiers is intensifying because Eastern European agricultural processors prioritize upfront capital savings over total cost of ownership calculations. Contract foodservice management companies exhibit lowest price sensitivity due to national account standardization, while independent Mediterranean bakeries retain highest elasticity.
Supply Chain Analysis
Extended payment terms from Italian and German component suppliers are tightening working capital requirements for downstream fabricators. Motor and drive assemblies concentrate in Germany, Italy, and Japan, while 304-grade stainless steel sheet draws from Finnish and Belgian mills. Single-source dependency on continuous-duty electromechanical drives creates vulnerability to component allocation disruptions. Distribution runs through specialized foodservice equipment distributors with captive service networks in North America and regional multi-brand dealers across European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among contract foodservice management companies that displace fragmented local purchasing through national account standardization across multi-site operations.
For Market Incumbents: Build captive aftermarket service moats through predictive maintenance platform integration and blade sharpening subscription contracts. Consolidate distribution relationships with Aramark, Compass, and Sodexo equivalents before emerging Asian fabricators establish institutional credibility. Invest in modular architecture R&D to satisfy EU Green Deal repairability mandates ahead of compliance deadlines. For New Entrants and Emerging Players: Establish a beachhead in Mediterranean artisan cheese segments where manual grater substitution creates white-space demand for precision-engineered electric alternatives. Target Benelux agricultural processing clusters seeking carbon steel cutting head replacements without premium stainless steel pricing. Pursue private-label partnerships with regional distributors lacking in-house manufacturing capabilities. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors service-integrated manufacturers with captive aftermarket networks over pure-play equipment fabricators. Long-term viability hinges on recurring revenue attach rates rather than unit shipment volumes. Watch blade replacement velocity and service contract renewal rates as inflection indicators for margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Sensor-embedded drum assemblies from Deville Technologies virtualize condition monitoring for Wisconsin cheese processors. |
| Modular Architecture Redesign | EU Green Deal repairability mandates force component-level replacement designs across German food manufacturing supply chains. |
| Blade Sharpening Subscription Rollout | Hobart Corporation sustains recurring revenue through hospital and school kitchen network penetration in Chicago and New York Metro. |
| CE Plus Energy Efficiency Dual Certification | Nordic public foodservice procurement channels open to compliant suppliers meeting emerging EU labeling requirements. |
| Optical Sorting Integration Partnership | Precision cutting assembly convergence targets high-volume Lombardy cheese processing lines for automated quality control. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads across commercial bakery and cheese processing facilities; and secondary validation through customs trade databases, EFSA food contact material filings, NSF certification registries, and SEC equipment manufacturer disclosures. Bottom-up equipment shipment estimates triangulated against top-down food production capacity expansion projections.
Forecast inputs considered motor horsepower tier, drum material specification, end-use application intensity, and regional regulatory compliance cluster across the analysis window. CAGRs derived from segmented growth rate blending weighted by installed base evolution and replacement cycle compression. Industry-specific variables incorporated EU Green Deal implementation timelines and contract foodservice procurement consolidation velocity.
Sensitivities concentrate around nickel commodity price trajectories, motor supplier allocation disruptions, and EFSA hygiene standard revision schedules. Forecasts reflect documented assumptions regarding repairability mandate enforcement intensity and aftermarket service attach rate stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Brewery Heat Exchanger Market
Food Processing Equipment
Global Shawarma Machines Market
Food Processing Equipment
Global Industrial Bakery Processing Equipment Market
Food Processing Equipment
US Cold Storage Market
Food Processing Equipment
Commercial Food Processors Market
Food Processing Equipment
Wine Processing Equipment Market
Food Processing Equipment
Global Snack Pellet Equipment Market
Food Processing Equipment
Automatic Grilling Machine Market
Food Processing Equipment
Global Electrodialysis Equipment Market
Food Processing Equipment
Countertop Convection Oven Market
Food Processing Equipment
Global Wine Tanks Market
Food Processing Equipment
Bakery Processing Equipment Market
Food Processing Equipment
Food-Grade Mixing Tank Market
Food Processing Equipment
India Household Flour Milling Machines Market
Food Processing Equipment
North America Beverage Filling and Capping Machine Market
Food Processing Equipment
Chewing Gum Machine Market