
 Crossflow Wine Filters Market | 2026-2036
Crossflow Wine Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Crossflow Wine Filters Market Analytics
After-sales membrane replacement and remote monitoring subscriptions are broadening vendor revenue models beyond hardware sales. Pall Corporation leverages its hollow-fiber membrane expertise to anchor service contracts across North American wineries. GEA Group sustains engineering-intensive positions through turnkey filtration skids with integrated CIP systems. Bucher Unipektin specializes in gentle processing configurations that protect aromatic compounds during white wine clarification.
Crossflow wine filters employ tangential-flow membrane separation to remove yeast, bacteria, and colloidal haze without filter aid consumption, typically operating at transmembrane pressures of 0.5–2.0 bar with pore ratings from 0.1–0.65 microns. Membrane filter types command the dominant installed base due to reproducible pore geometry and steam-in-place validation protocols. Ultrafiltration technology segments attract accelerated replacement demand as wineries pursue protein and polyphenol stabilization in single-pass configurations.
The FDA's Food Safety Modernization Act and EPA effluent guidelines for winery wastewater shape membrane selection and cleaning chemistry requirements. ISO 9001 quality system certification and 3-A sanitary standards govern equipment fabrication for North American food-contact applications. Stakeholders must weigh membrane material compatibility against emerging cold stabilization and dealcoholization process integration demands.
Market Dynamics
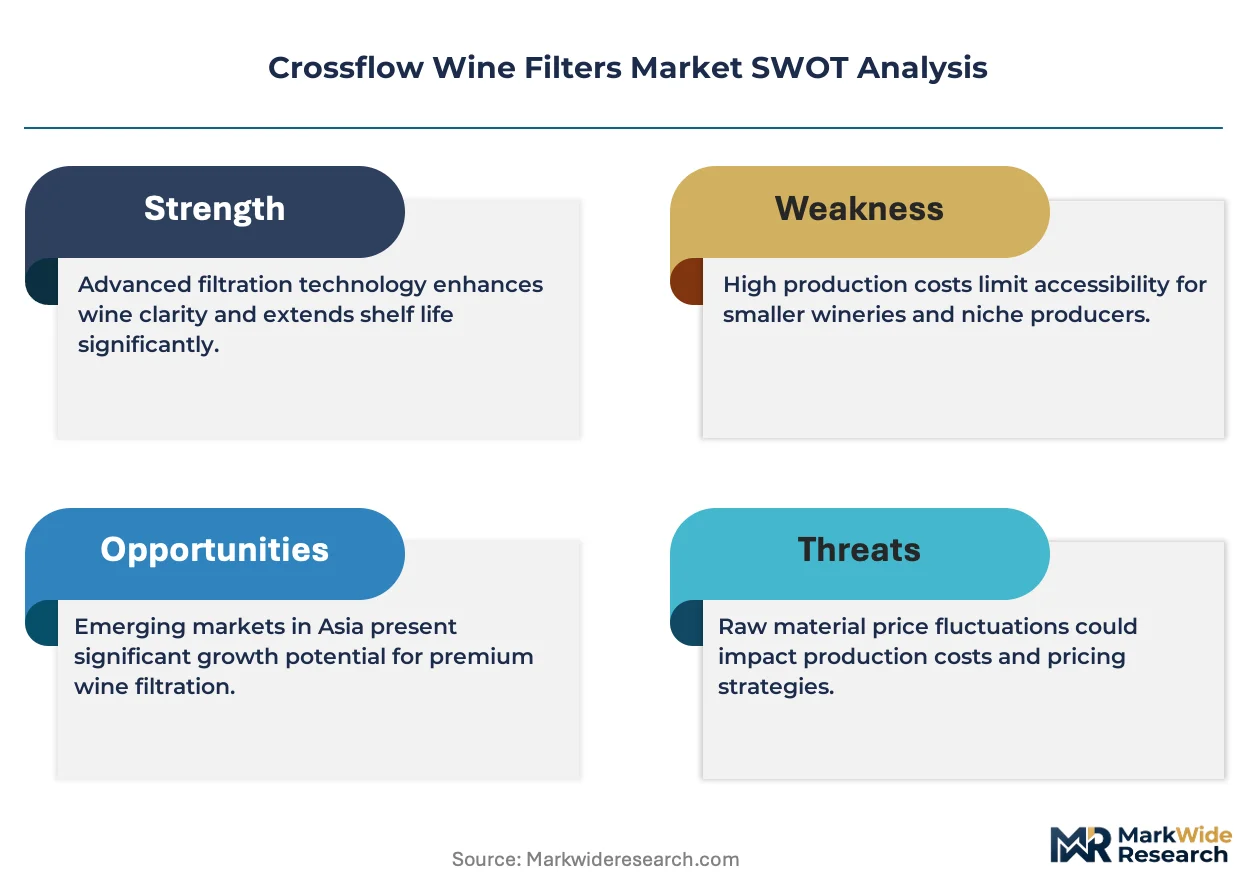
Wineries in premium appellations are dismantling diatomaceous earth filtration halls and retrofitting crossflow membrane skids to meet tightening microbial standards and eliminate filter aid disposal liabilities.
Growth Catalysts
- FSMA microbial limits:The FDA's Food Safety Modernization Act mandates stricter yeast and bacteria thresholds in finished wine, forcing estate bottlers to abandon depth filtration for validated membrane systems.
- Dealcoholization integration:Reverse osmosis and spinning cone technologies require upstream crossflow clarification to protect delicate membranes from colloidal fouling during alcohol removal.
- Napa Valley infrastructure buildout:Estate wineries across Rutherford and Oakville are scaling filtration capacity to handle estate-grown fruit volumes without contract processing.
Market Restraints
- PVDF membrane cost volatility:Polyvinylidene fluoride resin prices fluctuate with fluorochemical feedstock markets, squeezing gross margins on replacement element sales.
- Technical service scarcity:Qualified membrane technicians concentrate in California's Central Coast and Finger Lakes corridors, leaving interior regions underserved for emergency rebuilds.
- CIP chemistry restrictions:EPA effluent guidelines for winery wastewater limit caustic and acid discharge concentrations, extending cleaning cycle times and water consumption.
Strategic Opportunities
- Willamette Valley white wine expansion:Oregon's Pinot Gris and Chardonnay producers are underpenetrated for crossflow adoption, presenting first-mover equipment placement potential.
- Cold stabilization convergence:Electrodialysis and tartrate stabilization systems are pairing with crossflow skids in single-pass process trains, reducing tank farm requirements.
- Remote monitoring subscriptions:IoT-enabled transmembrane pressure and flux sensors allow vendors to sell predictive maintenance contracts separate from hardware.
Industry Challenges
- Sanitary welding certification delays:ASME BPE and 3-A symbol compliance for stainless steel skids extends fabrication timelines by eight to fourteen weeks during peak order seasons.
- Legacy diatomaceous earth workforce retraining:Cellar operators accustomed to powder handling and precoat procedures require structured programs to operate automated CIP sequences.
Report Scope
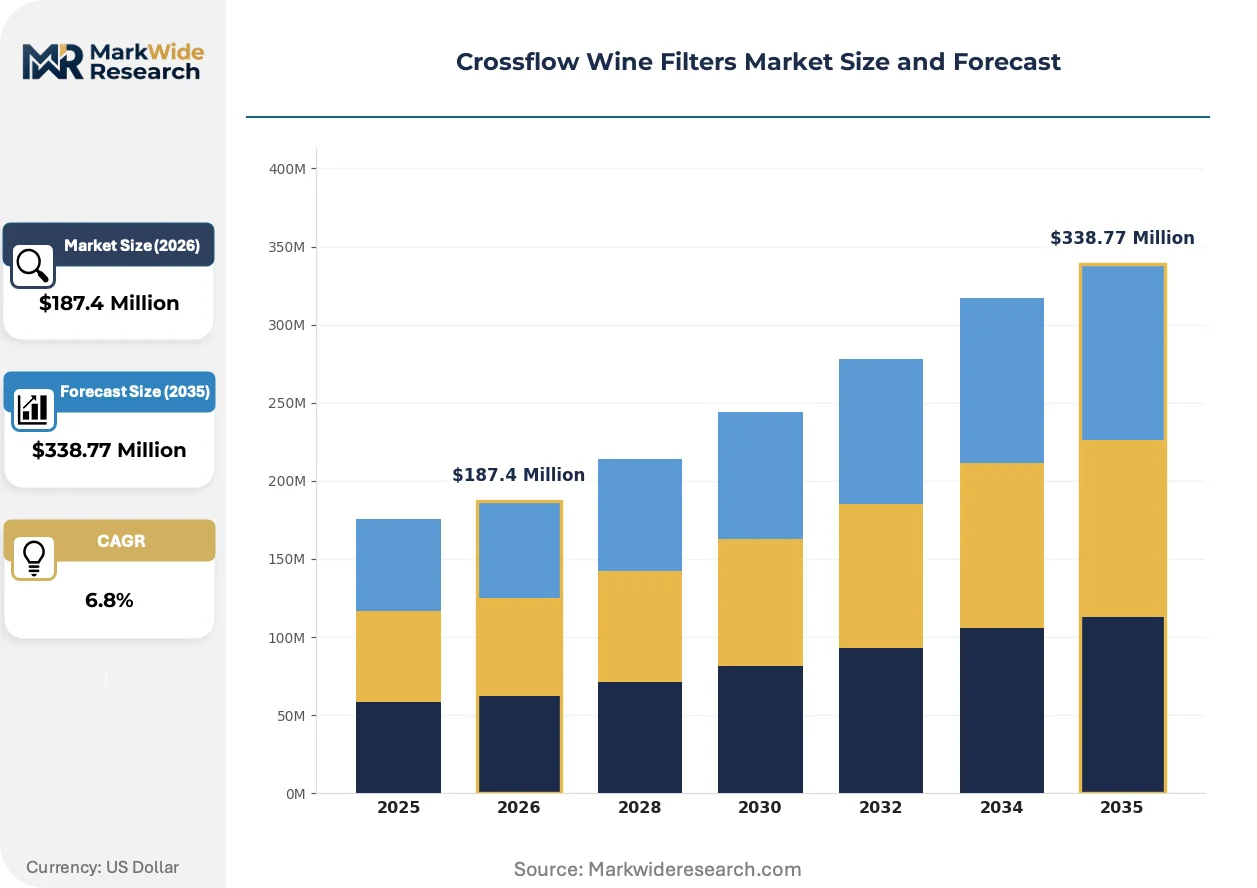
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crossflow Wine Filters Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Filter Type: Membrane, Depth, Cartridge, Plate Application: Red Wine, White Wine, Sparkling Wine, Fortified Wine End User: Wineries, Breweries, Distilleries, Research Labs Technology: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis |
| Companies Covered | Pall Corporation, GEA Group, Parker Hannifin, Della Toffola Group, Andritz, Bucher Unipektin, Sartorius AG, Enoveneta, VLS Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crossflow Wine Filters Market Evolving Landscape
Membrane material science and digital process control are compressing the functional gap between laboratory validation and production-scale wine clarification. Equipment vendors are embedding sensors that transform filtration from batch judgment into continuous data streams.
Ceramic membrane modules with titanium dioxide-zirconia composite layers are unifying thermal stability and chemical resistance for aggressive cleaning protocols. Willamette Valley and Sta. Rita Hills producers are piloting these systems for high-temperature CIP sequences that degrade polymeric elements. This unifying architecture enables wineries to process both red must lees and finished white wines on identical skids without cross-contamination protocols.
The EPA's forthcoming effluent guidelines for winery wastewater will tighten total suspended solids and biochemical oxygen demand limits for direct discharge permits. Membrane bioreactor compatibility is becoming a procurement criterion for new filtration installations. Central Coast processors with existing wastewater lagoons face retrofit decisions that favor crossflow systems with segregated CIP effluent streams.
Winery procurement departments are bundling membrane replacement schedules into multi-year service agreements rather than spot-buying elements. Equipment vendors are responding with guaranteed flux-rate contracts that shift technical risk from cellar staff to suppliers. This reconfiguration concentrates in Napa Valley and Sonoma County where estate legal departments prefer fixed-cost operational budgets over capital expenditure cycles.
Crossflow Wine Filters Market Segmentation
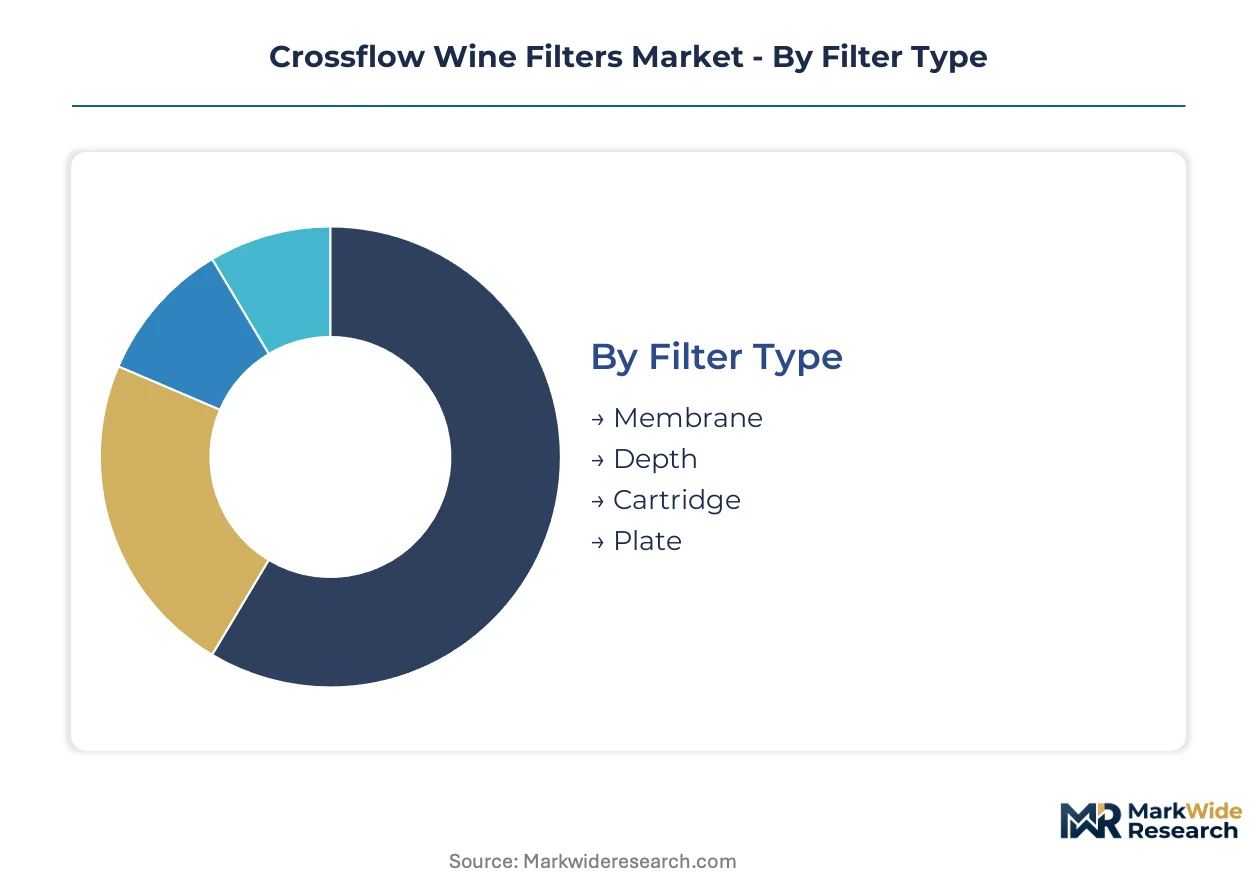
Crossflow wine filter procurement varies sharply by production scale, wine style, and regulatory exposure. Buyers prioritize validated pore geometry for estate bottling, while contract processors emphasize throughput flexibility across multiple wine types.
Filter Type:
Cost tier differentiation separates premium estate wineries from high-volume contract processors in membrane selection.
- Membrane:Polymeric hollow-fiber configurations deliver reproducible 0.1–0.65 micron ratings with steam-in-place validation protocols. Napa Valley estate bottlers specify these for FSMA microbial compliance, accepting higher capital outlay to eliminate diatomaceous earth disposal liabilities and precoat labor.
- Depth:Traditional cellulose and diatomaceous earth stacks persist in older Central Coast facilities with legacy infrastructure. Operators face rising EPA effluent penalties for filter aid discharge, accelerating retrofit timelines toward membrane replacement.
- Cartridge:Disposable pleated polypropylene suits small-batch experimental programs and research laboratories requiring rapid changeover without CIP investment.
- Plate:Stainless steel frame-and-plate assemblies serve high-turbidity red must lees with cleanable support screens, common in Rutherford Cabernet producers processing estate-grown fruit volumes.
Volume sits with Membrane; growth tilts toward Depth-to-membrane conversions.
Application:
Processing chemistry and aromatic sensitivity dictate equipment specification across wine styles.
- Red Wine:Tannin-protein complex stabilization demands gentle transmembrane pressure control to avoid astringency stripping. Oakville Cabernet Sauvignon producers pair crossflow clarification with oak chip integration, requiring skid configurations that handle high-solids lees without membrane compaction.
- White Wine:Pinot Gris and Chardonnay clarification prioritizes aromatic compound preservation through low-temperature operation. Willamette Valley producers pilot ceramic membrane modules for aggressive CIP protocols that would degrade polymeric elements.
- Sparkling Wine:Secondary fermentation pressure vessels require sterile filtration at 0.45 micron or tighter to prevent yeast refermentation in bottle, with Pall Corporation hollow-fiber systems dominating methode champenoise installations.
- Fortified Wine:High-alcohol Port and Sherry styles stress membrane material compatibility, with PVDF and PES polymers selected for solvent resistance in Lodi and Paso Robles fortified programs.
Red Wine commands current installed base; White Wine claims steepest expansion trajectory.
End User:
Customer type determines service intensity and contract structure preferences.
- Wineries:Estate and custom crush operations across Napa, Sonoma, and Central Coast sub-regions drive membrane replacement subscription models and remote monitoring adoption for predictive maintenance.
- Breweries:Craft beer clarification applications favor compact skid footprints with shorter membrane life cycles due to high-protein wort loading, concentrated in San Diego and Portland metropolitan clusters.
- Distilleries:Whiskey and vodka producers employ crossflow for mash clarification prior to distillation, with Kentucky bourbon distillers specifying high-temperature CIP compatibility for starch and protein removal.
- Research Labs:University enology programs and contract analytical services purchase small-format systems for pilot-scale validation, prioritizing data logging and experimental flexibility over production throughput.
Wineries anchor revenue concentration; Research Labs expand most quickly for technology demonstration.
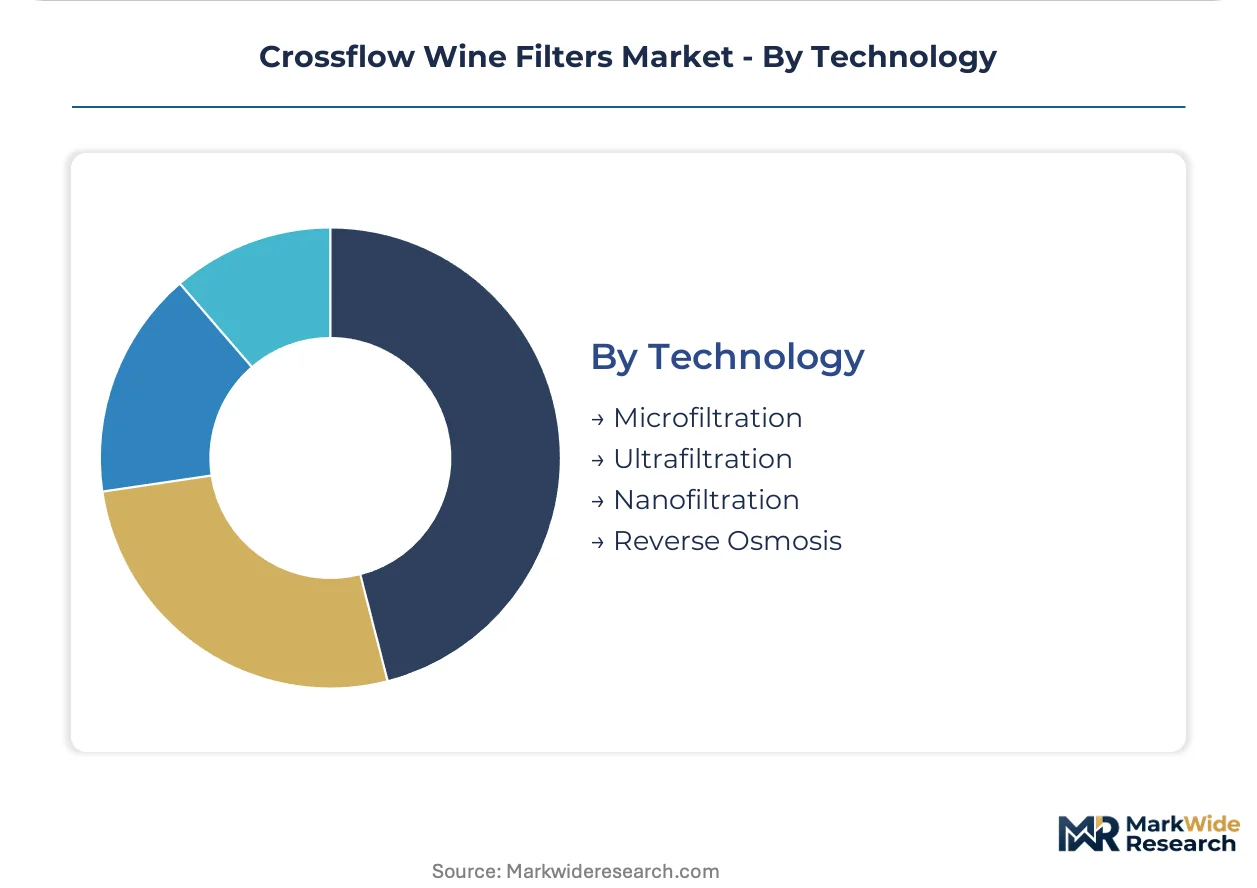
Technology:
Pore size specification aligns with specific stabilization objectives beyond basic clarification.
- Microfiltration:0.1–0.45 micron ratings remove yeast, bacteria, and colloidal haze for finished wine stabilization. FDA FSMA microbial limits mandate validated microfiltration for interstate commerce, forcing estate bottler adoption.
- Ultrafiltration:10–100 kDa molecular weight cutoffs enable protein and polyphenol stabilization in single-pass configurations. Dealcoholization process integration requires upstream ultrafiltration to protect reverse osmosis membranes from colloidal fouling.
- Nanofiltration:Divalent ion selectivity supports tartrate stabilization and partial dealcoholization without heat damage, emerging in premium Chardonnay programs targeting cold stability without energy-intensive refrigeration.
- Reverse Osmosis:Alcohol and water separation for dealcoholized wine production demands rigorous prefiltration; spinning cone technology users specify crossflow clarification to extend delicate membrane life.
Microfiltration holds dominant share; Ultrafiltration gains share fastest for process integration demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in established viticultural zones with estate bottling infrastructure, while demand expands fastest in emerging premium appellations retrofitting legacy filtration halls. Consumption patterns track regulatory enforcement intensity and water discharge permit conditions.
United States
Napa Valley and Sonoma County estate wineries drive membrane replacement subscriptions and remote monitoring adoption. The FDA's Food Safety Modernization Act mandates validated microbial filtration for interstate wine commerce, forcing Central Coast processors to abandon diatomaceous earth systems. Rutherford and Oakville sub-regions scale crossflow capacity to handle estate-grown Cabernet Sauvignon volumes without contract processing.
France
Bordeaux châteaux and Burgundy domaines prioritize aromatic preservation in white wine clarification, accelerating ceramic membrane trials. EFSA guidance on food contact materials shapes PVDF and PES polymer selection for high-alcohol fortified wine production. Champagne houses in Épernay and Reims specify sterile filtration at 0.45 micron for méthode champenoise secondary fermentation protection.
Italy
Tuscan estates in Chianti Classico and Montalcino retrofit filtration infrastructure to meet export market microbial standards. REACH compliance costs for fluorochemical feedstocks squeeze membrane replacement margins. Prosecco producers in Veneto's Conegliano-Valdobbiadene zone expand crossflow capacity for sparkling wine clarification ahead of DOCG volume growth.
Australia
Barossa Valley and McLaren Vale Shiraz producers adopt high-solids crossflow configurations for red must lees processing. The country's national environmental regulator tightens winery wastewater discharge limits for total suspended solids, favoring membrane systems with segregated CIP effluent streams. Yarra Valley Pinot Noir and Chardonnay specialists pilot low-temperature ultrafiltration for protein stabilization.
Spain
Rioja and Ribera del Duero bodegas dismantle traditional filtration halls under tightening EU effluent directives. Jerez sherry producers stress-test membrane material compatibility for high-alcohol fortified wine matrices. Catalonian cava houses in Penedès scale sterile filtration capacity to protect against yeast refermentation in bottle-conditioned sparkling wines.
Crossflow Wine Filters Market Competitive Landscape
Top-tier vendors anchor premium estate winery segments with validated membrane systems and service contracts, while mid-tier fabricators compete on turnkey skid delivery and CIP integration. The competitive landscape stratifies across three archetypes: membrane material specialists, engineering-intensive system integrators, and gentle-processing configuration experts. Consolidation pressures concentrate among hollow-fiber technology holders and ceramic module developers. Geographic expansion into underpenetrated white wine appellations and backward integration into membrane resin supply represent dominant competitive vectors.
Within the premium service tier, Pall Corporation and GEA Group exemplify divergent strategic positions. Pall Corporation occupies a membrane technology anchor role through hollow-fiber expertise and service contract penetration across North American wineries. GEA Group represents the engineering-intensive system integrator archetype with turnkey filtration skids featuring integrated CIP sequences. Bucher Unipektin sits within the gentle-processing specialist category, configuring equipment to protect aromatic compounds during white wine clarification.
| Leading Market Players |
|---|
| Pall Corporation |
| GEA Group |
| Parker Hannifin |
| Della Toffola Group |
| Andritz |
| Bucher Unipektin |
| Sartorius AG |
| Enoveneta |
| VLS Technologies |
| Others |
Value Network & Pricing Analysis
Estate-membrane versus contract-processor divergence separates validated hollow-fiber systems from commodity skid configurations, with Napa Valley bottlers absorbing premium outlays for FSMA compliance while Central Coast operators trade price for throughput flexibility. This bifurcation concentrates margin capture among membrane material specialists who bundle replacement schedules into multi-year service agreements, compressing spot-market pricing power for standalone hardware vendors.
Pricing Analysis
Margin tightening in polymeric membrane tiers reflects fluorochemical feedstock volatility and REACH compliance costs for PVDF resin sourcing. Three-tier pricing structure across premium, standard, and economy levels aligns with validation protocol intensity—steam-in-place certified hollow-fiber commands substantial premiums over cleanable plate assemblies. Cost-down pressure on standard-tier skids accelerates because contract processors prioritize capital efficiency over microbial validation documentation. Estate wineries exhibit lowest price sensitivity due to legal department preference for fixed operational budgets.
Supply Chain Analysis
PVDF and PES polymer supply rests on German and Japanese specialty chemical producers with captive fluorochemical feedstock integration. Hollow-fiber membrane fabrication draws from North Carolina and Bavaria production clusters, while stainless steel skid assembly concentrates in Northern Italy and Wisconsin fabrication facilities. Single-source vulnerability in zirconia-titania ceramic substrate sourcing exposes ceramic membrane developers to mining concentration in Australian and South African mineral corridors. Distribution runs through enology equipment distributors with cellar technical service capabilities rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market is becoming a vertical-integration race, with membrane resin sourcing and remote monitoring software development representing the critical upstream and downstream levers players are pursuing to escape commodity hardware margins.
For Market Incumbents: Extend service contract penetration by embedding IoT flux sensors that shift technical risk from cellar staff to vendors, locking in multi-year membrane replacement revenue streams. Consolidate position through backward integration into hollow-fiber spinning capacity to offset fluorochemical price volatility. Ceramic membrane technology represents the primary substitute threat requiring defensive R&D allocation. For New Entrants and Emerging Players: The EPA's forthcoming effluent guidelines for winery wastewater in the United States opens a window for membrane bioreactor-compatible skid configurations targeting Central Coast processors with lagoon retrofit requirements. Willamette Valley white wine appellations present the most penetrable geography, with Pinot Gris and Chardonnay producers underindexed for crossflow adoption. A technical service partnership model with established cellar contractors offers the lowest-friction go-to-market path. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to industrial filtration conglomerates seeking wine-specific application expertise rather than IPO candidates. Long-term viability hinges on recurring revenue attachment rates from membrane replacement subscriptions exceeding hardware depreciation cycles. Watch ceramic membrane pilot adoption rates in Willamette Valley and Sta. Rita Hills as the inflection signal for material substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Resin | Captive PVDF supply insulates margin structures from ECHA fluorochemical feedstock restrictions. |
| Remote Monitoring Platform Launch | IoT-enabled predictive maintenance contracts separate recurring software revenue from capital equipment cycles. |
| Ceramic Module Manufacturing Scale-Up | Titanium dioxide-zirconia composites enable aggressive CIP protocols that degrade polymeric alternatives. |
| Willamette Valley Sales Office Establishment | Oregon white wine expansion creates first-mover equipment placement ahead of competitor saturation. |
| Membrane Bioreactor Compatibility Certification | EPA effluent guideline alignment opens wastewater treatment procurement criteria for integrated skid sales. |
Research Methodology
Independent corroboration across winery engineering directors, membrane technician labor pools, and enology equipment distributors underwrites the qualitative findings in this analysis. Primary interviews with cellar operations managers, OEM aftermarket service heads, and contract processing procurement leads combined with secondary validation from FDA FSMA guidance documents, EPA effluent regulation dockets, and stainless steel fabrication trade association data. Bottom-up triangulation against top-down membrane replacement volume estimates anchored the segmentation outputs.
Rate-of-change decomposition across filter type, application, end user, and technology dimensions structured the analytical framework over the projection horizon. CAGRs derived from installed base growth modeling and replacement cycle velocity analysis, with wine production volume forecasts and regulatory compliance timeline assumptions as industry-specific inputs. Dealcoholization process integration demand and cold stabilization convergence trends informed the ultrafiltration segment trajectory.
Caveats apply where EPA effluent guideline finalization timelines or fluorochemical feedstock restriction implementations could materially shift the outlook. Forecasts reflect assumptions regarding estate bottling infrastructure buildout rates and membrane material substitution elasticities. A small set of named triggers—ceramic membrane cost curves, remote monitoring adoption rates, and technical service labor availability—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Freeze Thaw Chambers Market
Food Processing Equipment
Global Food Sterilization Machines Market
Food Processing Equipment
High-Pressure Processing Equipment Market
Food Processing Equipment
Magnetic Grill Market
Food Processing Equipment
Bread Processing Equipment Market
Food Processing Equipment
Shrimp Peeling Machine Market
Food Processing Equipment
Water Pod Soluble Machines Market
Food Processing Equipment
Mooncake Production Line Market
Food Processing Equipment
Spray Drying Equipment Market
Food Processing Equipment
Industrial Food Slicers Market
Food Processing Equipment
Canning Equipment Market
Food Processing Equipment
Smart Food Machine Market
Food Processing Equipment
Bakery Processing Equipment Market
Food Processing Equipment
Commercial Food Processors Market
Food Processing Equipment
Commercial Beverage Blender Market
Food Processing Equipment
High Speed Oven Market