
 Coffee Roaster Machine Market | 2026-2036
Coffee Roaster Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Roaster Machine Market Outlook
Equipment leasing and roaster-as-a-service arrangements are narrowing the capital barrier for new entrants across the value chain. PROBAT-Werke von Gimborn Maschinenfabrik GmbH leverages its century-long manufacturing heritage to dominate industrial-scale drum roasting installations. Bühler AG sustains engineering intensity through integrated process control platforms that extend from green coffee intake to packaging. Loring Smart Roast Inc. differentiates through combustion-free electric roasting architecture that eliminates afterburner infrastructure.
A coffee roaster machine thermochemically transforms green coffee beans through controlled convective and conductive heat transfer, typically operating between 180°C and 240°C with precise airflow modulation to develop volatile aromatic compounds and achieve target roast profiles. Drum roasters occupy the largest installed base due to proven scalability across small batch through commercial batch capacities, while hybrid roasters represent the fastest-growing technology segment as operators seek fuel-flexibility between gas and electric heat sources. Air roasters command premium positioning in sample roasting applications where rapid batch turnaround and minimal heat retention enable precise quality control protocols.
EPA emissions standards and EU Green Deal carbon reduction frameworks are reshaping equipment specifications, compelling manufacturers to certify thermal efficiency and particulate capture performance. CE marking and UL electrical safety requirements govern market access across European and North American jurisdictions, with ISO 9001 quality management systems serving as baseline procurement filters for institutional buyers. Stakeholders must weigh total cost of ownership against regulatory compliance horizons when selecting between gas-fired legacy platforms and emerging electric roasting architectures.
Market Dynamics
Electric roasting architectures are displacing gas-fired drum systems as EPA emissions standards and EU Green Deal carbon reduction frameworks tighten thermal efficiency mandates across commercial installations.
Growth Catalysts
- EU Green Deal carbon reduction frameworks:Mandatory decarbonization timelines in Germany and Italy are compelling café chains to retrofit gas-fired equipment with electric or hybrid roasting platforms.
- Pacific Northwest micro-roastery cluster:Seattle and Portland-based specialty operators are scaling automated batch systems to supply direct-trade subscription channels and third-wave café networks.
- Infrared radiant heating technology:Combustion-free thermal transfer systems eliminate afterburner infrastructure while reducing particulate emissions below EPA thresholds for urban roasting facilities.
Market Restraints
- Stainless steel and copper input volatility:Drum fabrication costs fluctuate with base metal commodity markets, compressing margin visibility for equipment manufacturers.
- Proprietary control system lock-in:Integrated process platforms from dominant vendors create switching friction for operators seeking component-level upgrades.
- Afterburner retrofit mandates:EPA emissions standards impose capital-intensive exhaust treatment requirements on legacy gas-fired installations in urban air quality non-attainment zones.
Strategic Opportunities
- São Paulo commercial processing corridor:Brazil's largest metropolitan roasting hub remains underpenetrated by automated hybrid systems, presenting first-mover positioning for flexible-fuel equipment.
- Roaster-as-a-service leasing models:Equipment financing arrangements are lowering capital barriers for independent café operators entering in-house roasting.
- CE marking and UL electrical safety convergence:Harmonized certification pathways are streamlining market access for electric roasting architectures across European and North American jurisdictions.
Industry Challenges
- Roast profile engineering talent scarcity:Operators struggle to recruit technicians capable of optimizing thermochemical transformations across convective-conductive heat transfer regimes.
- ISO 9001 quality management certification timelines:Institutional procurement filters require 12-18 month compliance documentation cycles that delay equipment qualification.
- Legacy drum system integration complexity:Retrofitting existing installations with digital airflow modulation and emissions monitoring creates operational downtime risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Roaster Machine Market |
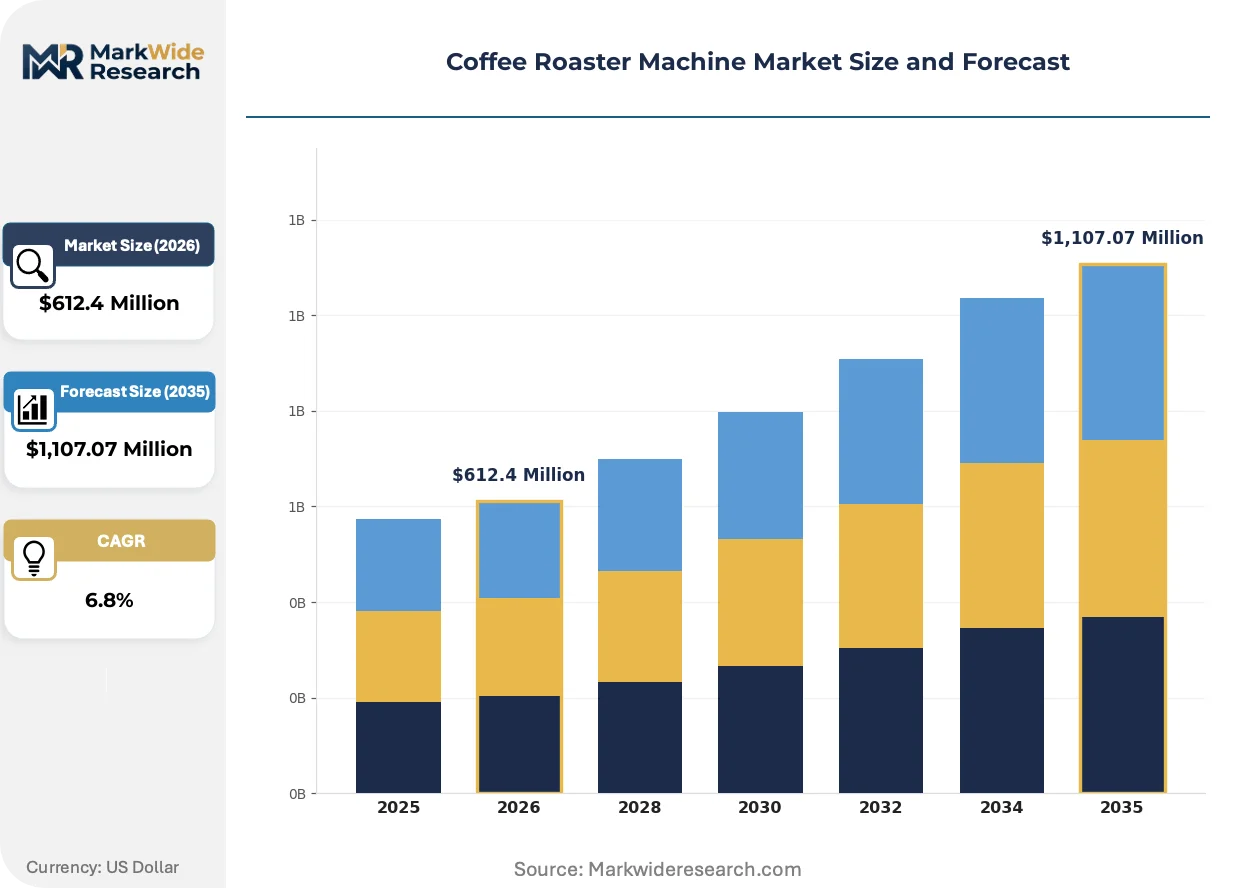
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drum Roasters, Air Roasters, Hybrid Roasters, Sample Roasters Capacity: Small Batch, Medium Batch, Large Batch, Commercial Batch Technology: Electric Roasters, Gas Roasters, Infrared Roasters, Wood-Fired Roasters End User: Home Users, Cafés, Roasteries, Foodservice Chains |
| Companies Covered | PROBAT-Werke von Gimborn Maschinenfabrik GmbH, Bühler AG, Giesen Coffee Roasters, Loring Smart Roast Inc., Diedrich Roasters, Mill City Roasters, San Franciscan Roaster Company, Toper Roaster, US Roaster Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Roaster Machine Market Strategic Shifts
Equipment architectures are converging around fuel-flexible thermal systems as regulatory pressure and buyer preference simultaneously pivot away from conventional gas-fired platforms.
Hybrid roasting technology is hybridizing convective and conductive heat transfer mechanisms within single-drum configurations, enabling real-time fuel switching between gas and electric sources. Mid-scale commercial operators in Germany and Italy are adopting these platforms fastest to hedge against carbon pricing volatility. The technology is hybridizing equipment procurement decisions by collapsing the traditional gas-versus-electric choice into a single capital commitment.
EPA emissions standards for particulate matter and volatile organic compounds are mandating thermal oxidizer integration or combustion-free alternatives for all new commercial roasting installations. This regulatory pressure is accelerating electric and infrared system development while rendering conventional gas-fired architectures non-compliant in urban air quality zones. Pacific Northwest micro-roasteries are responding fastest, with Seattle operators leading retrofit adoption to maintain operating permits.
Café chains are unbundling roasting equipment ownership from operational capability through managed service contracts that bundle maintenance, profile optimization, and emissions compliance. This procurement model shift displaces traditional capital purchase arrangements among foodservice chains entering in-house roasting. The transformation is most visible across United States multi-location operators seeking to differentiate through origin-specific roast profiles without building internal engineering teams.
Coffee Roaster Machine Market Segmentation
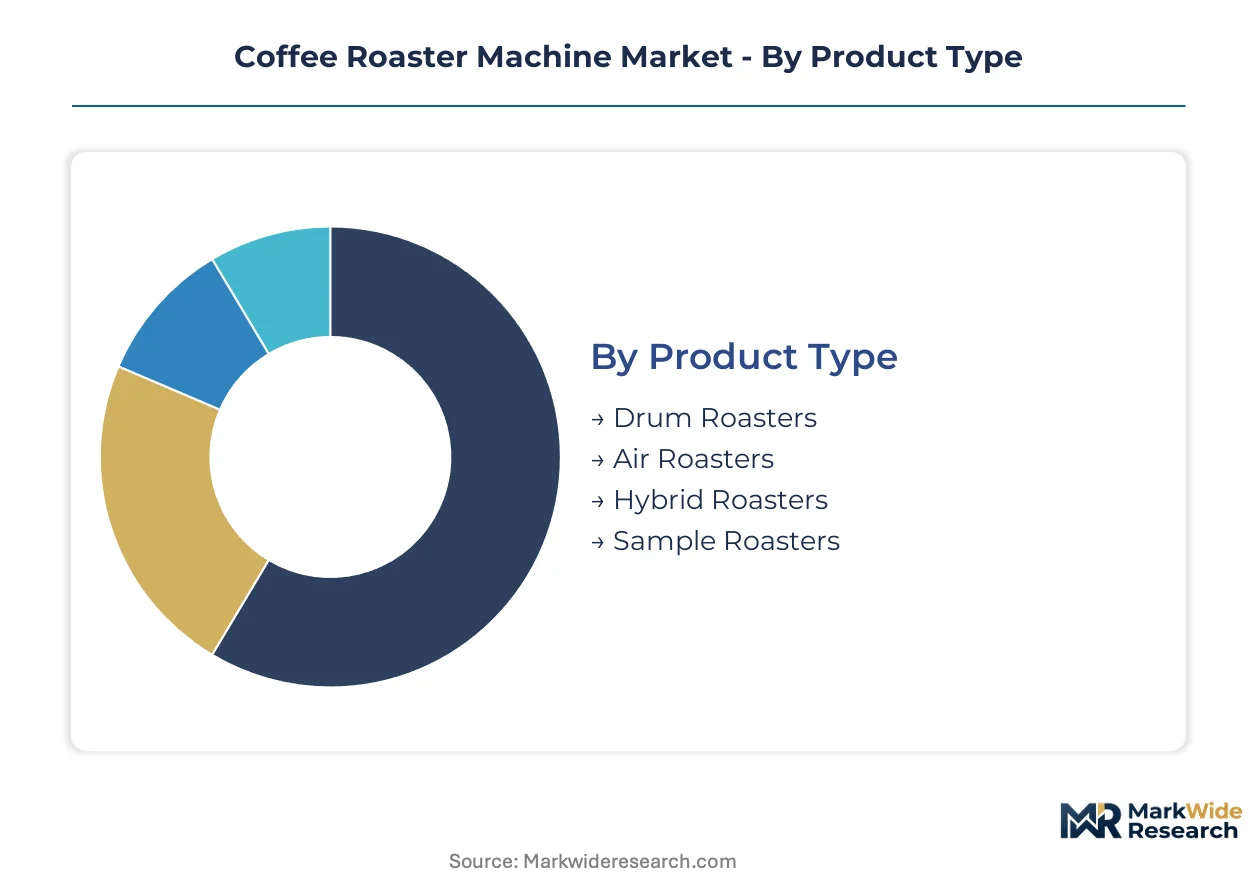
Segmentation in coffee roasting equipment reveals divergent service intensity requirements across thermal architectures and operational scales. Maintenance contracts, spare parts logistics, and technician dispatch frequencies vary substantially between high-throughput commercial installations and precision sample roasting systems.
Product Type:
After-sales-service intensity escalates with thermal system complexity and drum fabrication tolerances, creating tiered support obligations across equipment categories.
- Drum Roasters:Cast iron or stainless steel drum assemblies with direct flame or indirect heat transfer mechanisms require scheduled bearing replacement and surface reconditioning every 2,000-3,000 operating hours. Demand concentrates among German and Italian specialty roasteries scaling automated batch systems to supply café chain procurement networks, with EPA emissions compliance driving thermal oxidizer retrofit demand in urban installations.
- Hybrid Roasters:Dual-fuel architectures integrating gas burners with electric heating elements enable real-time fuel switching but demand specialized technician training for control system calibration. Pacific Northwest micro-roasteries in Seattle and Portland are adopting these platforms fastest to hedge against carbon pricing volatility while maintaining operating permits under tightening air quality regulations.
- Air Roasters:Fluidized-bed configurations with forced convection through perforated plates serve laboratory and quality control applications requiring rapid batch turnaround.
- Sample Roasters:Compact 100-500 gram capacity units with precise thermocouple arrays enable origin evaluation and profile development for green coffee buyers.
By volume, Drum Roasters leads. By growth pace, Hybrid Roasters is ahead.
Capacity:
Equipment footprint and utility infrastructure requirements scale non-linearly across batch size thresholds, reshaping facility layout economics and permitting complexity.
- Small Batch:1-5 kg per batch configurations dominate independent café roasting operations and training facilities.
- Medium Batch:15-30 kg systems balance throughput flexibility with manageable exhaust treatment requirements.
- Large Batch:60-120 kg drums serve regional roasting operations supplying multi-location foodservice accounts.
- Commercial Batch:240+ kg continuous or batch configurations integrate with automated green coffee handling and packaging lines for industrial-scale processing corridors.
Commercial Batch installations command highest absolute revenue per unit. Small Batch systems are expanding most quickly among independent operators entering direct-to-consumer subscription channels.
Technology:
Regulatory pressure from EPA and EU Green Deal frameworks is fragmenting technology adoption patterns across geographic jurisdictions with divergent decarbonization timelines.
- Electric Roasters:Resistance or induction heating elements eliminate combustion emissions and afterburner infrastructure, though power density requirements strain electrical service capacity in older facilities. São Paulo's commercial processing corridor is seeing accelerated adoption as Brazilian operators anticipate future carbon pricing mechanisms.
- Gas Roasters:Direct-fire or indirect radiant tube configurations retain installed base dominance but face compliance cost escalation in urban air quality non-attainment zones.
- Infrared Roasters:Ceramic or quartz radiant panels enable precise thermal profiling with minimal thermal mass and rapid temperature response.
- Wood-Fired Roasters:Hardwood combustion systems serve niche positioning for origin-story marketing in craft roasting segments.
Gas Roasters retains largest installed base. Electric Roasters is gaining share fastest where grid decarbonization and emissions regulations converge.
End User:
Procurement authority and technical staffing depth vary dramatically across buyer categories, driving divergent sales channel and support model requirements.
- Home Users:Countertop 100-500 gram electric units with simplified profile automation serve enthusiast segments.
- Cafés:5-15 kg systems enable on-site roasting for aroma marketing and origin differentiation, with roaster-as-a-service leasing lowering capital barriers.
- Roasteries:Dedicated production facilities with 30-120 kg equipment supply wholesale and retail channels, requiring ISO 9001 quality management certification for institutional procurement qualification.
- Foodservice Chains:Multi-location operators are unbundling equipment ownership from operational capability through managed service contracts bundling maintenance, profile optimization, and emissions compliance.
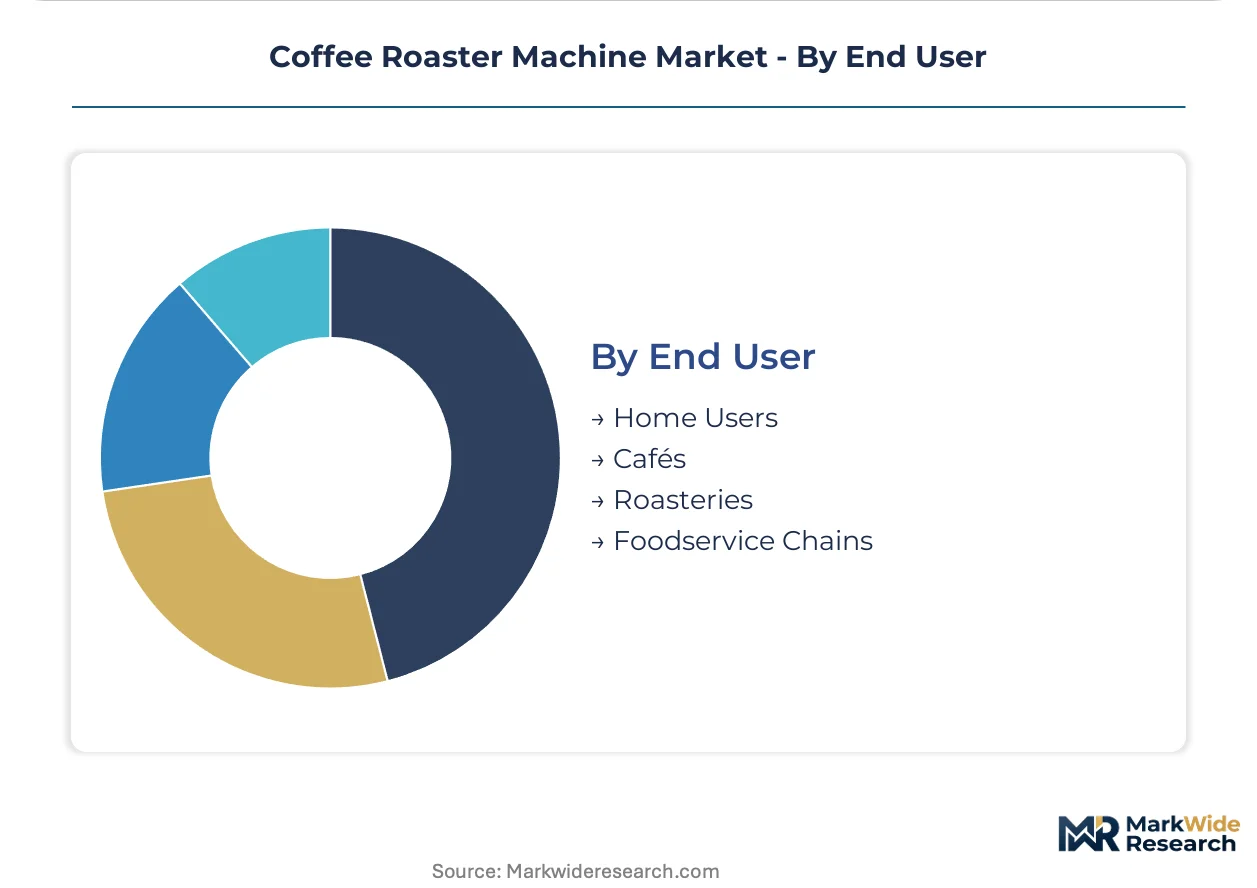
Roasteries represent highest equipment revenue concentration. Foodservice Chains are expanding most quickly as chains enter in-house roasting to differentiate through origin-specific profiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented coffee processing clusters in Brazil and Vietnam supply green beans to roasting equipment markets in Germany, Italy, and the United States, creating asymmetric trade flows where machinery demand concentrates in consuming nations while bean supply originates in producing regions.
United States
EPA emissions standards for particulate matter drive retrofit demand across urban roasting facilities. The Pacific Northwest micro-roastery cluster in Seattle and Portland scales automated batch systems to serve direct-trade subscription channels. Foodservice chains deploy roaster-as-a-service models to enter in-house roasting without capital commitment.
Germany
EU Green Deal carbon reduction frameworks mandate decarbonization timelines for commercial roasting operations. CE marking requirements govern equipment certification for cross-border European sales. Specialty roasteries in Hamburg and Berlin retrofit gas-fired drums with electric or hybrid platforms to maintain operating permits.
Italy
Traditional espresso culture sustains demand for precision roasting equipment across café supply chains. National air quality regulations in Milan and Turin accelerate electric roasting adoption. Equipment manufacturers in Bologna and Florence export drum systems to Middle Eastern and Asian markets.
Brazil
São Paulo's commercial processing corridor remains underpenetrated by automated hybrid systems despite its status as the largest metropolitan roasting hub. Brazilian operators anticipate future carbon pricing mechanisms and pilot electric installations. Domestic equipment fabricators serve regional coffee cooperatives with mid-scale batch configurations.
China
Specialty coffee consumption growth in Shanghai and Beijing generates demand for small-batch roasting equipment among independent café operators. National dual carbon goals pressure commercial processors to evaluate electric alternatives. Zhengzhou and Guangzhou equipment fabricators supply domestic roasteries with cost-competitive drum systems.
Coffee Roaster Machine Market Competitive Environment
On the supply side, the industry is tiered between century-established European fabricators, North American technology specialists, and emerging Asian cost competitors. Three strategic archetypes dominate: heritage drum manufacturers with installed base lock-in, combustion-free technology pioneers, and regional value fabricators serving price-sensitive markets. Capacity expansion and technology licensing represent the primary competitive vectors as emissions regulations fragment equipment specifications across jurisdictions.
Among heritage European manufacturers, PROBAT-Werke von Gimborn Maschinenfabrik GmbH and Bühler AG exemplify the industrial-scale drum roasting archetype, while Loring Smart Roast Inc. occupies a position within the combustion-free technology tier. These three anchors illustrate how competitive positioning diverges between legacy thermal architectures and emerging electric platforms.
| Leading Market Players |
|---|
| PROBAT-Werke von Gimborn Maschinenfabrik GmbH |
| Bühler AG |
| Giesen Coffee Roasters |
| Loring Smart Roast Inc. |
| Diedrich Roasters |
| Mill City Roasters |
| San Franciscan Roaster Company |
| Toper Roaster |
| US Roaster Corporation |
| Others |
Value Chain & Pricing Dynamics
São Paulo's commercial processing corridor concentrates Latin American roasting equipment demand, creating asymmetric pricing power for German and Italian manufacturers who anchor premium tier positioning through CE-marked certification heritage.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on CE/UL certification tier and after-sales service bundling intensity. Cost compression in economy tiers is intensifying because Chinese fabricators are penetrating small-batch segments. Independent café operators exhibit highest price sensitivity, while foodservice chains prioritize emissions compliance over unit cost.
Supply Chain Analysis
Stainless steel feedstock draws from German, Italian, and Chinese metallurgical suppliers, with drum fabrication tolerances resting on precision machining capabilities concentrated in Baden-Württemberg and Lombardy. Copper heating elements and ceramic infrared panels feed from South Korean and Japanese component specialists. Single-source vulnerability in precision bearing assemblies creates supply chain risk. Distribution runs through authorized dealer networks with factory-direct service contracts for commercial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment around EPA and EU Green Deal emissions certification creates high switching costs for installed base operators.
For Market Incumbents: Harden installed base lock-in through backward integration into precision drum fabrication and predictive maintenance software platforms. Expand certified service technician networks in Pacific Northwest micro-roastery clusters to preempt emerging electric roasting specialists. Prioritize hybrid system R&D to capture carbon pricing volatility hedging demand from German and Italian café chains.
For New Entrants and Emerging Players: Pursue São Paulo's underpenetrated commercial processing corridor with cost-optimized electric batch systems tailored to Brazilian grid infrastructure. Target roaster-as-a-service leasing arrangements for United States foodservice chains seeking in-house capability without capital commitment. Anchor go-to-market strategy through emissions compliance guarantees rather than equipment specifications.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory capture play because EPA and EU Green Deal frameworks are rendering legacy gas-fired architectures non-compliant, concentrating value in electric and hybrid technology platforms. Acquisition targets should exhibit combustion-free thermal engineering depth and ISO 9001 quality management certification. Monitor carbon pricing implementation timelines in Brazil and China as inflection indicators for electric roasting adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Drum Fabrication | Captures margin from stainless steel volatility while tightening quality control for CE marking compliance. |
| Roaster-as-a-Service Leasing Model Expansion | Lowers capital barriers for United States foodservice chains entering origin-specific profile differentiation. |
| Electric Roasting Architecture Certification | Secures EPA emissions compliance in urban air quality non-attainment zones ahead of retrofit mandates. |
| Hybrid System Platform Development | Enables real-time fuel switching for German and Italian operators hedging carbon pricing volatility. |
| Predictive Maintenance Software Deployment | Extends service revenue streams while reducing operational downtime risks for commercial batch installations. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA emissions filings, EU Green Deal implementation documents, and equipment manufacturer technical specifications. Primary interviews engaged roasting equipment procurement managers at foodservice chains, maintenance directors at regional roasteries, and aftermarket service heads at German and Italian manufacturers. Secondary validation drew from CE marking databases, UL certification registries, and customs trade data on stainless steel and copper component flows. Bottom-up equipment shipment analysis triangulates against top-down market sizing across thermal architecture segments.
Forecast inputs incorporate batch capacity tier, thermal technology type, and end-user procurement authority across the projection horizon. Segmentation modeling spans product type, capacity threshold, fuel source, and buyer category. CAGRs derive from equipment replacement cycle analysis and regulatory compliance timeline convergence. Industry-specific inputs include EPA emissions standard phase-in schedules and EU Green Deal carbon reduction framework milestones.
Sensitivities concentrate around carbon pricing implementation velocity, base metal commodity volatility, and grid decarbonization progress in key manufacturing jurisdictions. Forecasts reflect assumptions regarding regulatory enforcement consistency and technology substitution rates. Cross-checking against customs trade data on green coffee processing equipment imports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Coffee Capsules Market
Coffee
Global Coffee Shop Market
Coffee
Espresso Powder Market
Coffee
Bioactive Proteins in Coffee Market
Coffee
Caffeine Market
Coffee
Asia-Pacific Coffee Franchise Market
Coffee
Japan Coffee and Tea Capsules Market
Coffee
India Ready-To-Drink (RTD) Coffee Market
Coffee
Asia-Pacific Espresso Coffee Market
Coffee
Butter Coffee Market
Coffee
China Ready-To-Drink (RTD) Coffee Market
Coffee
High Protein Coffee Market
Coffee
Coffee Pods and Capsules Market
Coffee
Green Coffee Market
Coffee
United Arab Emirates Coffee Roaster Market
Coffee
United Kingdom Ready-To-Drink (RTD) Coffee Market