
 Dairy Processing Equipment Market | 2026-2036
Dairy Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Processing Equipment Market Analysis
Modular skid-mounted pasteurizer configurations is broadening buyer choice among mid-size dairy cooperatives seeking phased capital deployment. GEA Group AG leverages its centrifugal separation expertise to anchor premium contracts in European cheese manufacturing. Tetra Laval sustains technology leadership through integrated aseptic filling and packaging systems. SPX FLOW specializes in custom pump and valve solutions that navigate stringent hygienic design standards.
Dairy processing equipment encompasses mechanical and thermal systems engineered to transform raw milk into finished products through controlled temperature regimes, pressure differentials, and microbial reduction protocols. Stainless steel construction with surface finishes below 0.8 micrometers Ra ensures compliance with 3-A Sanitary Standards while preventing bacterial adhesion in CIP cycles. Pasteurizers and homogenizers command established margin pools in fluid milk treatment, whereas automated continuous processing systems represent the fastest-expanding technology segment as processors eliminate batch-to-batch variability. Separators retain structural importance in butterfat standardization for yogurt and ice cream applications.
The FDA enforces Grade A Pasteurized Milk Ordinance standards that dictate equipment design and thermal validation protocols across US fluid milk operations. EFSA and national regulators within the EU enforce hygiene requirements under EC 853/2004, while the F-Gas Regulation constrains refrigerant selections in cooling-dependent equipment. Stakeholders must monitor evolving energy efficiency mandates and carbon accounting rules that will reshape equipment specification criteria and retrofit priorities.
Market Dynamics
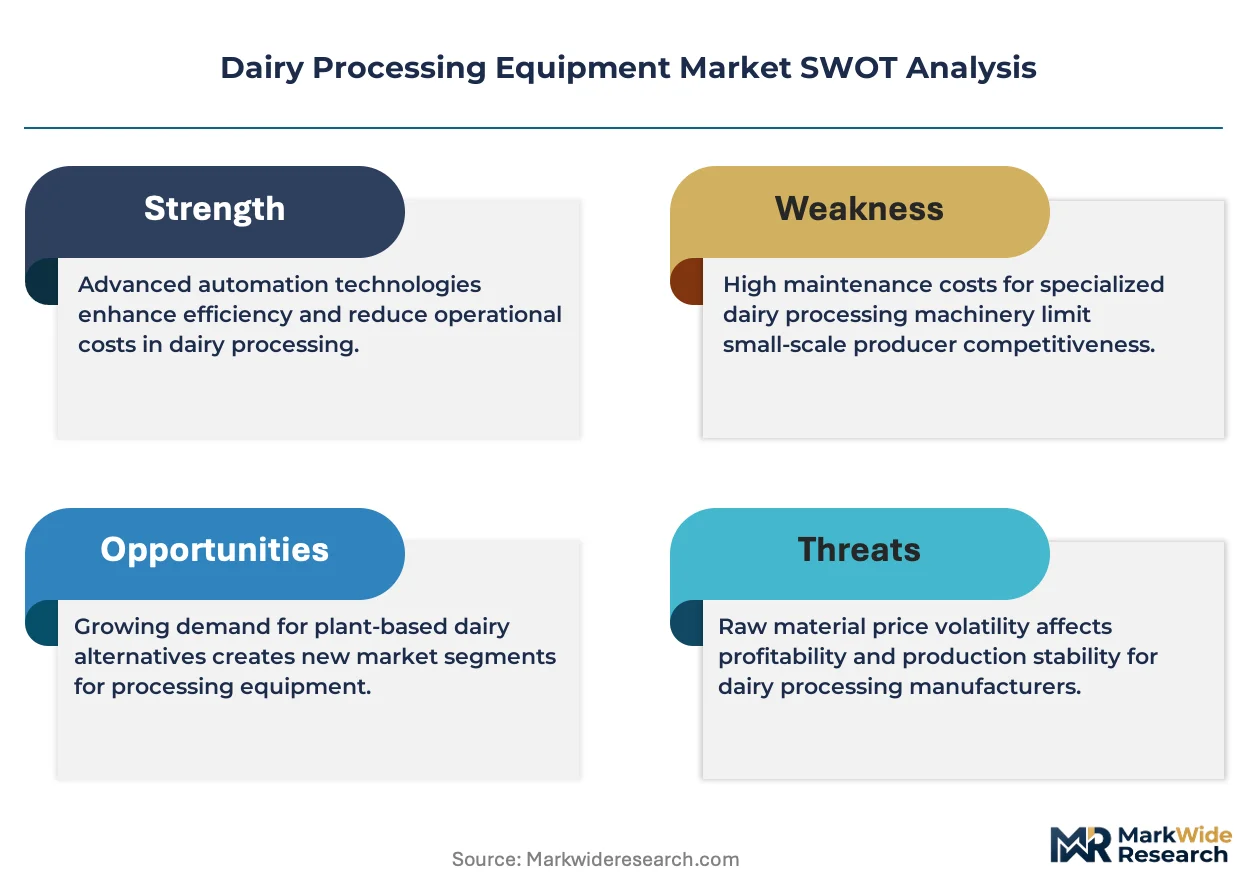
The EU F-Gas Regulation is compressing refrigerant choices for cooling-dependent equipment while artisan cheese producers in France and Wisconsin simultaneously expand capacity for aged varieties, creating divergent equipment specification pressures across fluid milk and specialty dairy segments.
Growth Catalysts
- Automated Continuous Processing:Extended shelf-life fluid milk processors are eliminating batch-to-batch variability through integrated pasteurization and aseptic filling lines.
- 3-A Sanitary Standards Compliance:Stainless steel surface finishes below 0.8 micrometers Ra are becoming mandatory specification criteria for CIP cycle validation.
- Artisan Cheese Capacity Expansion:Small-batch producers in Wisconsin and France are retrofitting aging rooms with precision humidity control systems.
Market Restraints
- F-Gas Phase-Down Timeline:Hydrofluorocarbon refrigerant restrictions under EU regulation are forcing premature equipment obsolescence for cooling systems.
- Stainless Steel Input Volatility:Grade 316L and 304 alloy price swings are compressing margin pools for fabricators of hygienic vessels and piping.
- Skilled Technician Scarcity:Certified welding specialists for orbital TIG applications on dairy-grade surfaces are concentrating in Western European supply bases.
Strategic Opportunities
- Modular Skid Configurations:Mid-size dairy cooperatives are adopting phased capital deployment models for pasteurizer installations.
- Energy Efficiency Retrofit Mandates:Carbon accounting rules in the EU are creating specification pull for heat recovery systems and regenerative pasteurization.
- Plant-Based Dairy Adjacencies:Oat and almond milk processors are adapting existing homogenizer and separator infrastructure for alternative protein applications.
Industry Challenges
- Legacy System Integration:Batch pasteurizers from prior decades require custom control architecture to interface with continuous processing lines.
- Thermal Validation Documentation:FDA Grade A Pasteurized Milk Ordinance compliance demands extensive protocol documentation for each equipment modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Processing Equipment Market |
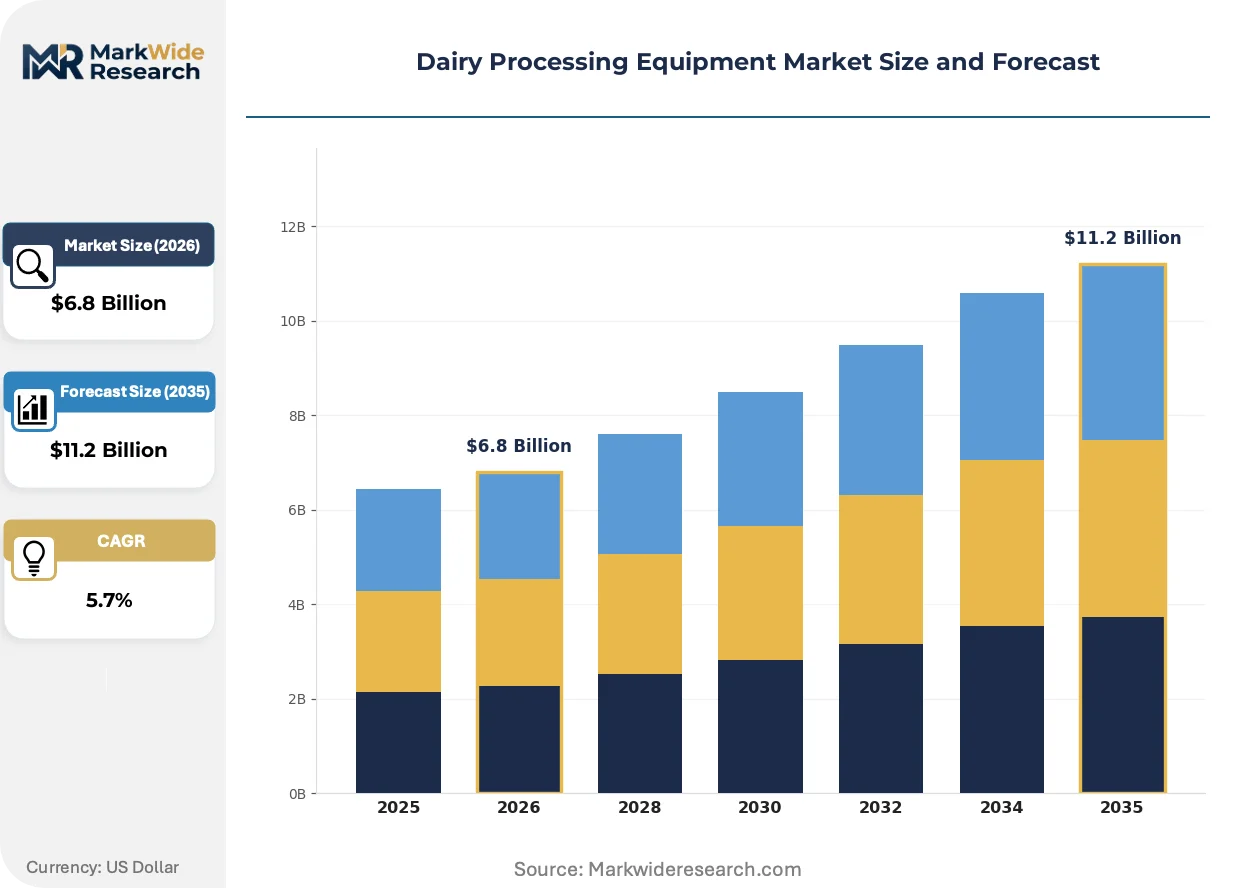
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Pasteurizers, Homogenizers, Separators, Pumps Processing Stage: Milk Treatment, Fermentation, Packaging, Bottling End User: Cheese Manufacturers, Yogurt Producers, Fluid Milk Processors, Ice Cream Makers Technology: Batch Processing, Continuous Processing, Automated Systems, Manual Systems |
| Companies Covered | Alfa Laval, Bucher Industries AG, GEA Group AG, Krones AG, The Middleby Corporation, SPX FLOW, JBT Corporation, IDMC Limited, Tetra Laval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Processing Equipment Market Emerging Trajectories
Equipment architecture is converging around closed-loop thermal management and unified control platforms that bridge previously siloed processing stages.
Integrated aseptic filling and packaging systems are unifying what were historically separate pasteurization and packaging procurement decisions. Large fluid milk processors in Germany and the Netherlands are consolidating vendor relationships around single-source responsibility for contamination control. This unification is compressing the traditional equipment specification timeline from eighteen months to under ten months for greenfield installations.
The EU F-Gas Regulation is mandating refrigerant transitions that cascade through cooling system redesigns. Equipment manufacturers must now validate alternative chemistries such as CO2 transcritical systems and ammonia-based circuits for dairy applications. French and Italian ice cream producers are absorbing the highest compliance costs due to their reliance on low-temperature hardening tunnels.
Service contract unbundling is fragmenting the traditional full-service equipment procurement model. Mid-size cooperatives in Denmark and Ireland are separating hardware acquisition from maintenance agreements, instead sourcing predictive maintenance through third-party industrial IoT platforms. This pattern is most pronounced among processors with in-house engineering capabilities who can self-perform CIP validation and thermal calibration.
Dairy Processing Equipment Market Segmentation
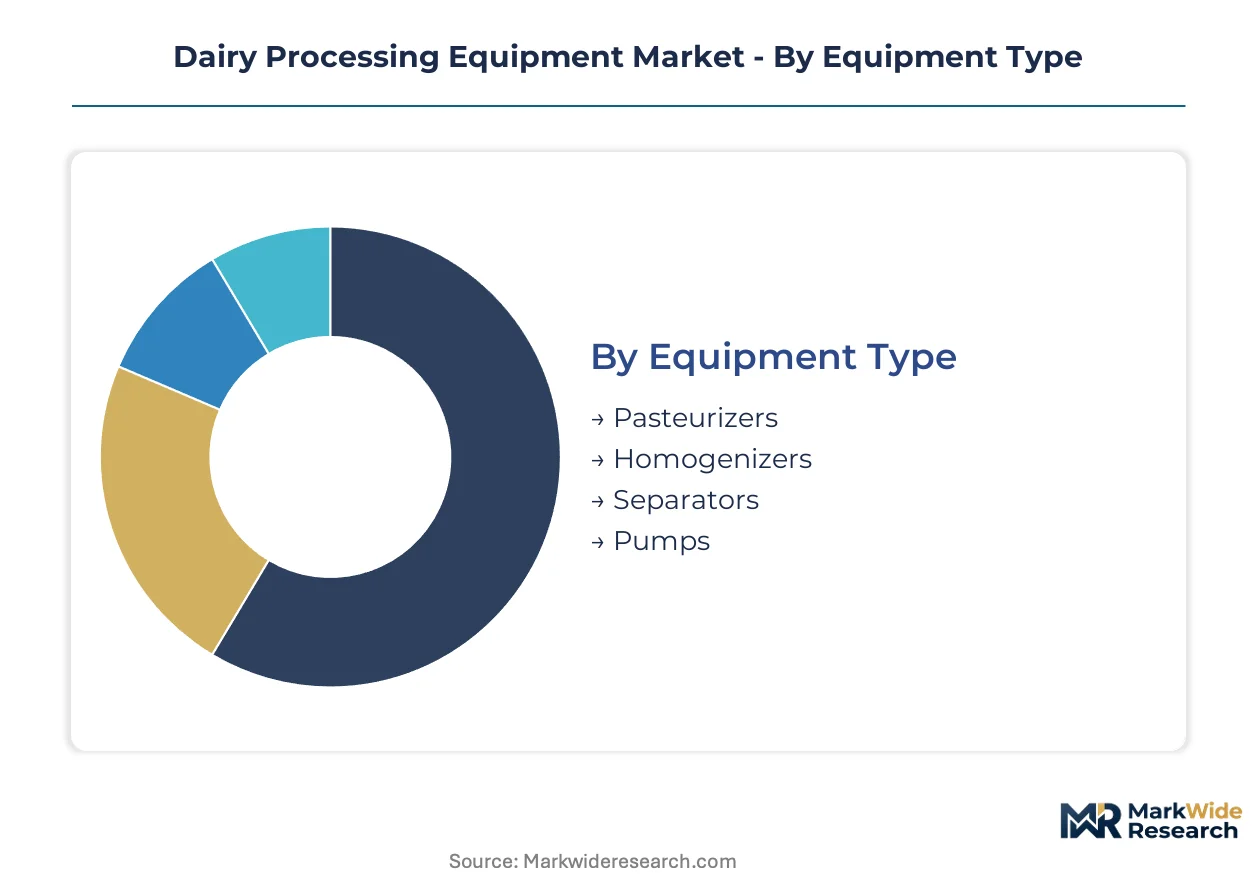
Equipment specification in dairy processing diverges sharply between commodity fluid milk operations and specialty fermented product lines. Segmentation reveals where capital deployment concentrates and which technology configurations command premium positioning.
Equipment Type:
Standalone thermal units operate independently at line entry points, while separation and pumping systems embed deeply into continuous processing architectures with unified control platforms.
- Pasteurizers:Thermal validation systems apply controlled temperature regimes to achieve microbial reduction protocols mandated by FDA Grade A Pasteurized Milk Ordinance. Demand concentrates among fluid milk processors in Germany and the Netherlands eliminating batch-to-batch variability through integrated lines. The EU F-Gas Regulation is compressing refrigerant choices for cooling-dependent thermal recovery systems.
- Homogenizers:High-pressure valve configurations force milk through narrow apertures to disrupt fat globule membranes and prevent cream separation. Extended shelf-life fluid milk processors in North America anchor procurement volumes here. Stainless steel surface finishes below 0.8 micrometers Ra are becoming mandatory specification criteria for CIP cycle validation.
- Separators:Centrifugal force systems standardize butterfat content for yogurt and ice cream applications.
- Pumps:Positive displacement and centrifugal configurations navigate stringent hygienic design standards for viscous and fluid dairy streams.
Volume placements concentrate in pasteurizers; the faster expansion belongs to homogenizers as shelf-life extension drives specification upgrades.
Processing Stage:
Capital intensity escalates downstream from raw milk intake toward aseptic filling, with packaging integration now compressing traditional eighteen-month specification timelines to under ten months.
- Milk Treatment:Raw reception, standardization, and thermal processing stages employ pasteurizers, separators, and homogenizers in sequence. Fluid milk processors in Germany and the Netherlands are consolidating vendor relationships around single-source responsibility for contamination control. Automated continuous processing systems are displacing batch configurations as processors eliminate variability.
- Fermentation:Controlled culture propagation for cheese and yogurt requires precision temperature and pH management across aging rooms and incubation vessels. Artisan cheese producers in France and Wisconsin are retrofitting aging rooms with precision humidity control systems. Small-batch capacity expansion is creating specification pull for modular skid-mounted configurations.
- Packaging:Aseptic filling systems unify previously separate pasteurization and packaging procurement decisions.
- Bottling:Container formation, filling, and sealing operations complete the processing chain.
Procurement volume clusters in milk treatment; packaging is climbing the fastest as integrated aseptic systems consolidate vendor relationships.
End User:
Customer scale determines equipment architecture, with large fluid milk operations demanding continuous processing while artisan producers prioritize batch flexibility and phased capital deployment.
- Cheese Manufacturers:Aging room infrastructure, curd handling systems, and whey separation equipment dominate capital allocation. Artisan producers in France and Wisconsin are expanding capacity for aged varieties. Precision humidity control systems are becoming specification priorities for small-batch operations.
- Fluid Milk Processors:Extended shelf-life production lines command the highest automation intensity and thermal validation documentation. Large processors in Germany and the Netherlands are driving adoption of integrated pasteurization and aseptic filling lines. The FDA enforces Grade A Pasteurized Milk Ordinance standards that dictate equipment design across US operations.
- Yogurt Producers:Incubation vessels and fruit incorporation systems serve stirred and set product formats.
- Ice Cream Makers:Low-temperature hardening tunnels and continuous freezers face elevated compliance costs under EU F-Gas Regulation refrigerant transitions.
Equipment shipments concentrate with fluid milk processors; cheese manufacturing is gaining share fastest as artisan capacity expansion accelerates.
Technology:
Automation depth separates premium system integrators from commodity fabricators, with unified control platforms now bridging previously siloed processing stages.
- Continuous Processing:Uninterrupted product flow through integrated thermal, separation, and filling stages eliminates batch-to-batch variability. Extended shelf-life fluid milk processors in Germany and the Netherlands are the primary demand anchors. Large operations are consolidating vendor relationships around single-source responsibility for contamination control.
- Automated Systems:Programmable logic controllers and unified HMI platforms enable remote monitoring and predictive maintenance integration. Mid-size cooperatives in Denmark and Ireland are separating hardware acquisition from maintenance agreements, sourcing predictive maintenance through third-party industrial IoT platforms. Service contract unbundling is fragmenting traditional full-service procurement models.
- Batch Processing:Discrete vessel operations retain relevance for specialty and artisan production formats.
- Manual Systems:Limited automation configurations serve small-scale operations and developing market entry points.
Installed base concentrates in batch processing; continuous systems show the steepest expansion trajectory as variability elimination drives replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bavaria and the Randstad cluster drive equipment concentration. Tax incentives for food technology investment pull capital toward dairy processing corridors. Industrial policy in France and Wisconsin accelerates artisan capacity expansion.
Germany
Extended shelf-life fluid milk processors in Lower Saxony and Bavaria anchor procurement volumes for continuous pasteurization lines. The EU F-Gas Regulation compresses refrigerant choices for cooling-dependent thermal systems. Equipment vendors concentrate around Munich and Stuttgart engineering clusters serving dairy cooperatives.
United States
Artisan cheese producers in Wisconsin and California expand aging room capacity for specialty varieties. FDA Grade A Pasteurized Milk Ordinance dictates equipment design standards across fluid milk operations. Dairy processing equipment fabricators cluster in the Upper Midwest near Chicago and Milwaukee industrial corridors.
France
Small-batch cheese manufacturers in Auvergne-Rhône-Alpes and Normandy retrofit facilities with precision humidity control systems. The EU F-Gas Regulation mandates refrigerant transitions for ice cream hardening tunnels. Equipment specification activity concentrates in Lyon and Rennes food technology zones.
Netherlands
Large fluid milk processors in Friesland and Gelderland consolidate vendor relationships around integrated aseptic filling systems. National energy efficiency mandates create specification pull for heat recovery pasteurization. Dairy technology suppliers cluster in the Eindhoven region and Randstad logistics corridor.
India
Cooperative dairy federations in Gujarat and Maharashtra deploy modular skid-mounted pasteurizers for phased capital deployment. FSSAI hygiene requirements under Food Safety and Standards Act shape equipment specification criteria. Dairy processing equipment demand concentrates in Anand and Pune industrial zones.
Dairy Processing Equipment Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment categories. The vendor base organizes into three tiers: integrated system integrators commanding premium contracts, mid-scale fabricators serving regional cooperatives, and specialized component suppliers. Market structure rewards single-source responsibility for contamination control and unified thermal validation documentation. Dominant competitive moves include service contract unbundling and predictive maintenance platform partnerships.
Within the integrated system integrator tier, GEA Group AG and Tetra Laval exemplify archetypes anchoring premium positioning through centrifugal separation expertise and aseptic filling integration respectively. SPX FLOW occupies a specialist position among pump and valve fabricators navigating hygienic design standards. Alfa Laval represents the Scandinavian engineering tradition in thermal and separation systems. These three named entities collectively illustrate how geographic origin and corporate structure correlate with strategic positioning across fluid milk and specialty dairy segments.
| Leading Market Players |
|---|
| Alfa Laval |
| Bucher Industries AG |
| GEA Group AG |
| Krones AG |
| The Middleby Corporation |
| SPX FLOW |
| JBT Corporation |
| IDMC Limited |
| Tetra Laval |
| Others |
Supply Flow & Price Mechanics
Grade 316L stainless steel alloy volatility transmits from European foundries through three-tier pricing structures separating premium European fabricators from mid-tier Asian suppliers and economy-grade regional metalworkers serving dairy cooperatives in India and Wisconsin.
Pricing Analysis
Margin tightening in mid-tier equipment reflects F-Gas Regulation compliance costs cascading through cooling system redesigns. Three-tier pricing structure across premium, standard, and economy levels separates GEA and Tetra Laval's integrated thermal validation packages from regional fabricators in Bavaria and Pune. Pricing pressure stems from artisan cheese producers demanding modular skid configurations with phased payment terms. Mid-size dairy cooperatives in Denmark and Ireland exhibit highest price sensitivity; large fluid milk processors in Germany accept premium positioning for single-source contamination control.
Supply Chain Analysis
Regional distribution centers in Munich, Stuttgart, and Eindhoven anchor hub-and-spoke patterns serving dairy technology corridors. Manufacturing concentrates in Germany, Denmark, and India. Supply chains draw from Swedish stainless steel mills, Italian precision valve specialists, and Indian fabrication clusters. Single-source vulnerability sits with certified orbital TIG welders concentrating in Western European supply bases. Distribution runs through OEM-direct channels for large processors and equipment dealer networks for artisan producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dairy processing equipment represents a consolidation play as F-Gas Regulation compliance costs force sub-scale fabricators toward exit or acquisition.
For Market Incumbents: Deploy predictive maintenance platform partnerships to capture service contract unbundling revenue from mid-size cooperatives with in-house engineering capabilities. Deepen backward integration into stainless steel surface finishing to defend margin position against Grade 316L input volatility. Anchor premium positioning through unified thermal validation documentation that satisfies FDA Grade A Pasteurized Milk Ordinance requirements. For New Entrants and Emerging Players: Artisan cheese producers in Auvergne-Rhône-Alpes and Normandy represent the most penetrable buyer archetype. These small-batch operations seek precision humidity control retrofit packages absent from incumbent portfolios. Enter through modular skid-mounted configurations with phased capital deployment terms that match cooperative financing constraints. For Investors and Strategic Acquirers: Service contract unbundling announcements from Danish and Irish cooperatives are the leading indicator that predictive maintenance platforms will consolidate fragmented aftermarket revenue pools. Five-to-ten year viability favors specialists with captive orbital TIG welding capability and F-Gas-validated alternative refrigerant portfolios. Watch for EU energy efficiency retrofit mandate acceleration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Finishing | Captures margin from surface treatment specialists while ensuring 0.8 micrometer Ra compliance for CIP validation. |
| Predictive Maintenance Platform Partnership | Converts unbundled service contracts into recurring revenue from Denmark and Ireland cooperative networks. |
| F-Gas Alternative Refrigerant Validation | Positions cooling systems for EU regulatory compliance ahead of hydrofluorocarbon phase-down deadlines. |
| Modular Skid Configuration Development | Matches phased capital deployment needs of mid-size cooperatives in India and Wisconsin. |
| Single-Source Contamination Control Packaging | Compresses eighteen-month specification timelines to under ten months for German and Dutch fluid milk processors. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this dairy processing equipment analysis. Primary interviews with plant engineers at fluid milk processors, procurement leads at dairy cooperatives, aftermarket service heads at OEMs, and regulatory affairs specialists at equipment fabricators validated demand patterns. FDA Grade A Pasteurized Milk Ordinance documentation, EU F-Gas Regulation implementation guidance, and FSSAI Food Safety and Standards Act compliance frameworks supplemented bottom-up installation tracking with top-down market sizing triangulation.
Data-stream reconciliation across equipment shipment records, capital expenditure disclosures, and thermal system validation databases shaped the analytical framework. Segmentation dimensions modeled include equipment type, processing stage, automation depth, and end-user scale across the projection horizon. CAGRs derived from regression analysis against dairy production volume forecasts and regulatory compliance cost trajectories. Industry-specific inputs incorporated stainless steel price indices and refrigerant transition timelines.
Revisions become necessary when EU energy efficiency mandates accelerate, F-Gas Regulation enforcement tightens, or stainless steel alloy markets experience sustained dislocation. Forecasts reflect documented assumptions regarding cooperative capital availability and artisan producer expansion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Processing Machinery
Milk Powder Analyzing Device Market
Dairy Processing Machinery
Global Milk Tank Cooling System Market
Dairy Processing Machinery
Milk Processing Systems Market
Dairy Processing Machinery
Milk Pasteurization Machines Market
Dairy Processing Machinery
Cream Separator Market
Dairy Processing Machinery
Electric Milkshake Machine Market
Dairy Processing Machinery
Commercial Milkshake Machine Market
Dairy Processing Machinery
Milk Clarifier Market
Dairy Processing Machinery
Cheese Liners Market
Dairy Processing Machinery
Concentrated Whey Market
Dairy Processing Machinery
Milk Homogenizer Machine Market
Dairy Processing Machinery
Yogurt Cup Market
Dairy Processing Machinery
Modified Milk Powder Market
Dairy Processing Machinery
Cheese Cutting Machine Market
Dairy Processing Machinery
Dairy Filtration Systems Market
Dairy Processing Machinery
Commercial Cheese Shredder Market