
 Global Wine Tanks Market | 2026-2036
Global Wine Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wine Tanks Market Foresight
Premium-grade stainless steel specifications with enhanced temperature control precision is unwinding traditional equipment replacement cycles across established wine regions. Paul Mueller Company leverages its vertical integration in stainless steel fabrication to dominate North American vineyard supply chains. Della Toffola Group anchors its competitive position through specialized fermentation engineering for mid-to-large European wineries. Bucher Vaslin differentiates via precision welding protocols that sustain extended barrel-aging simulations in tank environments.
Wine tanks are sealed vessels engineered from food-grade stainless steel, concrete, or oak, designed with wall thicknesses ranging from 2 to 5 millimeters and integrated cooling jackets to regulate fermentation temperatures between 10°C and 30°C; their primary commercial purpose is to contain grape must and wine through controlled biochemical transformation and maturation. Stainless steel tanks command the largest installed base due to sanitation advantages and decades-long service life, while concrete vessels represent the fastest-growing material segment as natural wineries pursue thermal mass stability without oak influence. Oak tanks concentrate margin pools among artisanal producers seeking flavor compound integration without barrel logistics, and fiberglass occupies niche positions in mobile or temporary storage applications.
FDA food-contact material standards and EU CE marking requirements shape tank surface finish specifications and welding certification protocols, while REACH compliance governs coating and sealant chemistry for European exports. France's national food safety regulator enforces additional hygiene auditing for tanks deployed in AOC-designated zones, creating segmented compliance obligations. Stakeholders must monitor evolving EU Green Deal manufacturing standards and California Air Resources Board emissions rules for on-site welding operations as these frameworks tighten material traceability and fabrication energy disclosure requirements.
Market Dynamics
Premium wineries in Napa Valley, Bordeaux, and Barossa Valley are compressing equipment replacement cycles as temperature-controlled fermentation systems displace traditional passive vessels. This technology pull is restructuring supplier relationships and fabrication capacity allocation across stainless steel supply chains.
Growth Catalysts
- EU CE marking alignment:Stainless steel tank specifications meeting CE and FDA food-contact standards unlock cross-border procurement for French Champagne houses modernizing aging infrastructure.
- Concrete thermal mass adoption:Natural wineries pursuing fermentation stability without oak influence are expanding concrete vessel specifications across premium and super-premium tiers.
- Barossa Valley cluster concentration:Australian producers are consolidating tank procurement around regional fabrication hubs to reduce lead times and logistics costs.
Market Restraints
- Nickel alloy price volatility:Stainless steel 304 and 316 input costs fluctuate with LME nickel pricing, compressing fabrication margins and triggering indexed contract clauses.
- EU Green Deal manufacturing standards:Tightening material traceability and fabrication energy disclosure requirements are extending compliance timelines for European exporters.
- Welding certification scarcity:Precision orbital welding protocols for cooling jacket integration face qualified technician shortages in emerging wine regions.
Strategic Opportunities
- India wine market emergence:Nascent vineyard development in Maharashtra and Karnataka creates first-mover positioning for tank suppliers offering turnkey fermentation infrastructure.
- California Air Resources Board emissions rules:On-site welding operation compliance is driving demand for centralized fabrication with pre-certified modular tank systems.
- IoT sensor convergence:Integration of wireless fermentation monitoring with existing tank infrastructure enables retrofit service revenue streams without full vessel replacement.
Industry Challenges
- REACH compliance timeline complexity:Coating and sealant chemistry validation for European exports extends product development cycles by 8-14 months.
- Legacy oak tank integration:Hybrid wineries face operational friction combining traditional barrel-aging protocols with new stainless steel fermentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wine Tanks Market |
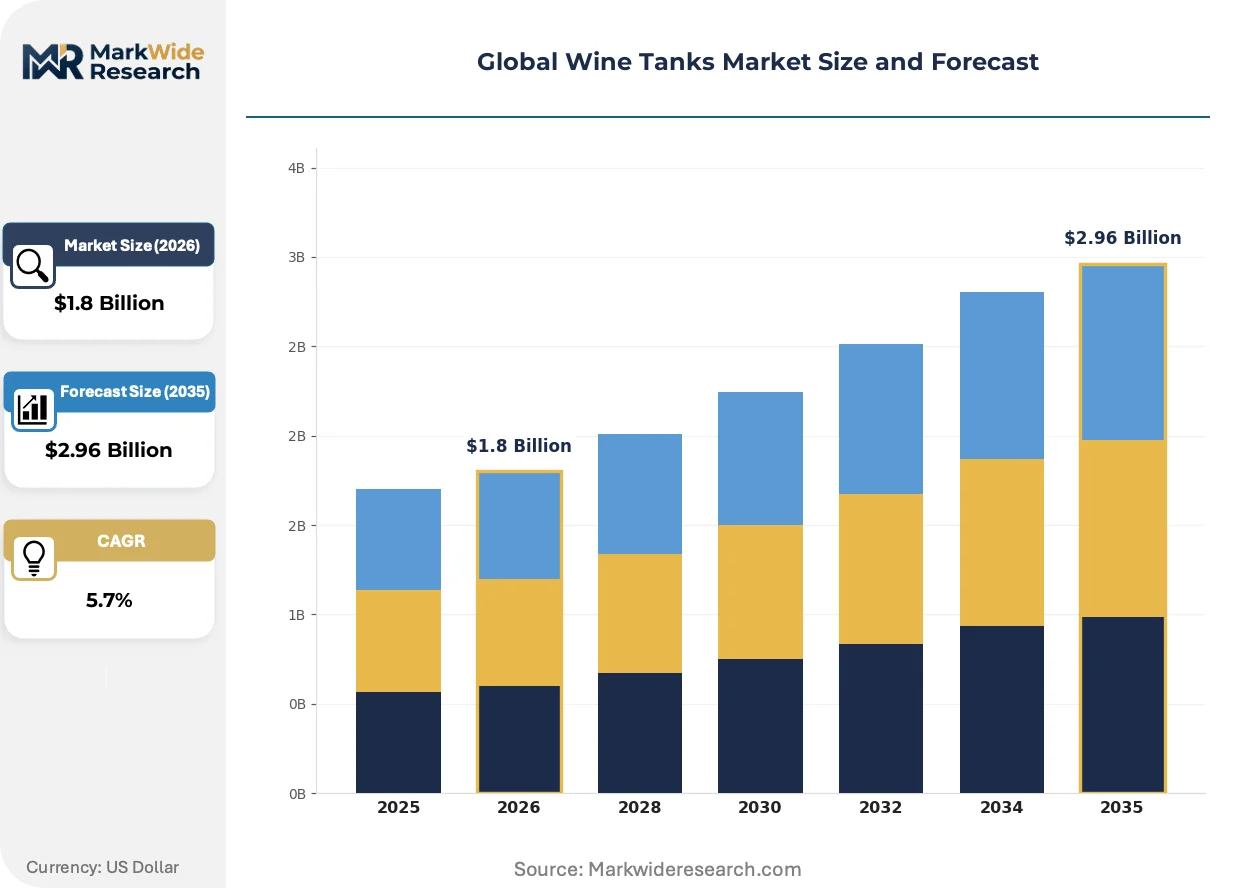
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Stainless Steel, Concrete, Fiberglass, Oak, Plastic Capacity: 500 Liters, 1000 Liters, 5000 Liters, 10000 Liters Application: Fermentation, Aging, Storage, Blending End User: Vineyards, Wineries, Wine Distributors, Research Labs |
| Companies Covered | Paul Mueller Company, Della Toffola Group, Cedarstone Industry, Bucher Vaslin, Speidel Tank- und Behälterbau GmbH, Zottel d.o.o., Letina Inox, Gortani Srl, Tanks and Vessels Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wine Tanks Market Shifts & Advancements
Active fermentation monitoring and modular fabrication methods are compressing project timelines while expanding precision control capabilities. Equipment suppliers are repositioning around data-enabled service models rather than pure hardware transactions.
Wireless temperature and density sensor arrays are miniaturizing to fit existing tank ports without structural modification. Mid-sized wineries in Spain's Ribera del Duero are adopting these retrofit systems at 18-month replacement cycles. The technology is miniaturizing the barrier between capital equipment and consumable monitoring services, enabling subscription-based fermentation analytics.
France's ANSM hygiene auditing requirements for AOC-designated zones are mandating surface finish documentation down to Ra 0.8 micrometers. Tank fabricators must now maintain batch-level material certificates and welding operator logs for decade-long traceability. Champagne producers are responding by consolidating procurement around vertically integrated suppliers with captive metallurgy labs.
Direct-to-winery fabrication partnerships are displacing distributor-mediated equipment sales in established regions. Australian producers in Margaret River and Coonawarra now specify tanks through engineering consultants rather than agricultural equipment dealers. This channel shift concentrates margin capture with technical specialists and compresses price transparency for standardized vessel configurations.
Global Wine Tanks Market Segmentation
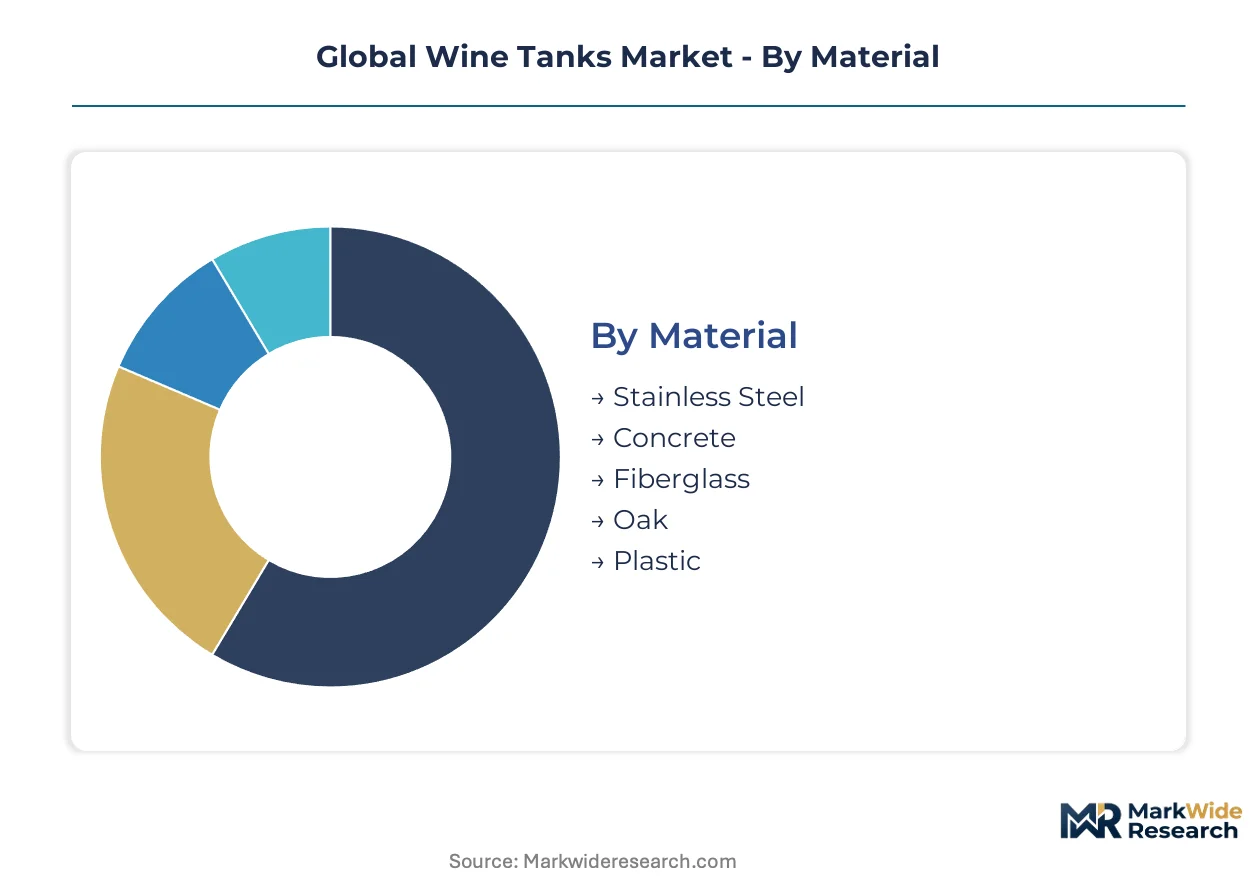
Wine tank segmentation reveals how material science, scale economics, and process specificity fragment procurement decisions across the value chain. Each dimension carries distinct margin architectures and supplier qualification barriers that reshape competitive positioning.
Material:
Margin pools concentrate in surface finish precision and alloy traceability documentation rather than raw tonnage.
- Stainless Steel:Food-grade 304 and 316 alloys with 2-5 millimeter wall thicknesses and integrated cooling jackets dominate installed base. Demand clusters in Napa Valley and Champagne as AOC-designated zones mandate Ra 0.8 micrometer surface documentation and decade-long welding operator logs.
- Concrete:Thermal mass vessels with passive fermentation stability are climbing fastest among natural wineries in Barossa Valley and Ribera del Duero seeking oak-influence-free alternatives. Specifications emphasize wall porosity control and mineral leaching prevention.
- Fiberglass:Mobile and temporary storage applications occupy niche positions where weight reduction overrides thermal precision requirements.
- Oak:Artisanal producers in Bordeaux and Margaret River specify these for flavor compound integration without barrel logistics complexity.
- Plastic:Entry-tier fermentation for research labs and experimental batches where capital constraints override longevity concerns.
Stainless steel holds installed capacity. Concrete is rotating up the share rankings.
Capacity:
Cost tier stratification separates premium precision engineering from standardized volume fabrication.
- 500 Liters:Experimental and small-batch fermentation vessels with precision temperature control for research labs and boutique wineries. Demand concentrates in emerging wine regions where pilot-scale validation precedes commercial expansion.
- 1000 Liters:Mid-tier workhorse specification balancing flexibility with throughput, dominating procurement volumes across European family-owned wineries upgrading from barrel-based workflows.
- 5000 Liters:Commercial-scale fermentation and aging infrastructure for established vineyards in Coonawarra and Margaret River consolidating tank procurement around regional fabrication hubs.
- 10000 Liters:Maximum-scale storage and blending operations where logistics optimization and energy efficiency per hectoliter drive specification decisions.
1000 Liter specifications anchor current procurement volumes. 5000 Liter configurations are expanding most quickly as mid-sized wineries achieve scale thresholds.
Application:
Process specificity determines cooling jacket complexity and sensor integration requirements.
- Fermentation:Active temperature regulation between 10°C and 30°C with wireless monitoring arrays. Precision demands peak in Champagne houses modernizing infrastructure with EU CE marking alignment.
- Aging:Extended maturation protocols requiring surface chemistry stability and minimal oxygen transfer rates. Concrete vessels are gaining traction here for thermal mass without oak influence.
- Storage:Capacity optimization with reduced control precision, concentrating margin competition on logistics integration and lead time compression.
- Blending:Homogenization-focused specifications emphasizing clean-in-place efficiency and rapid turnover capability for high-throughput distributors.
Fermentation commands technology premiums. Aging is rotating up the share rankings as natural winery protocols expand.
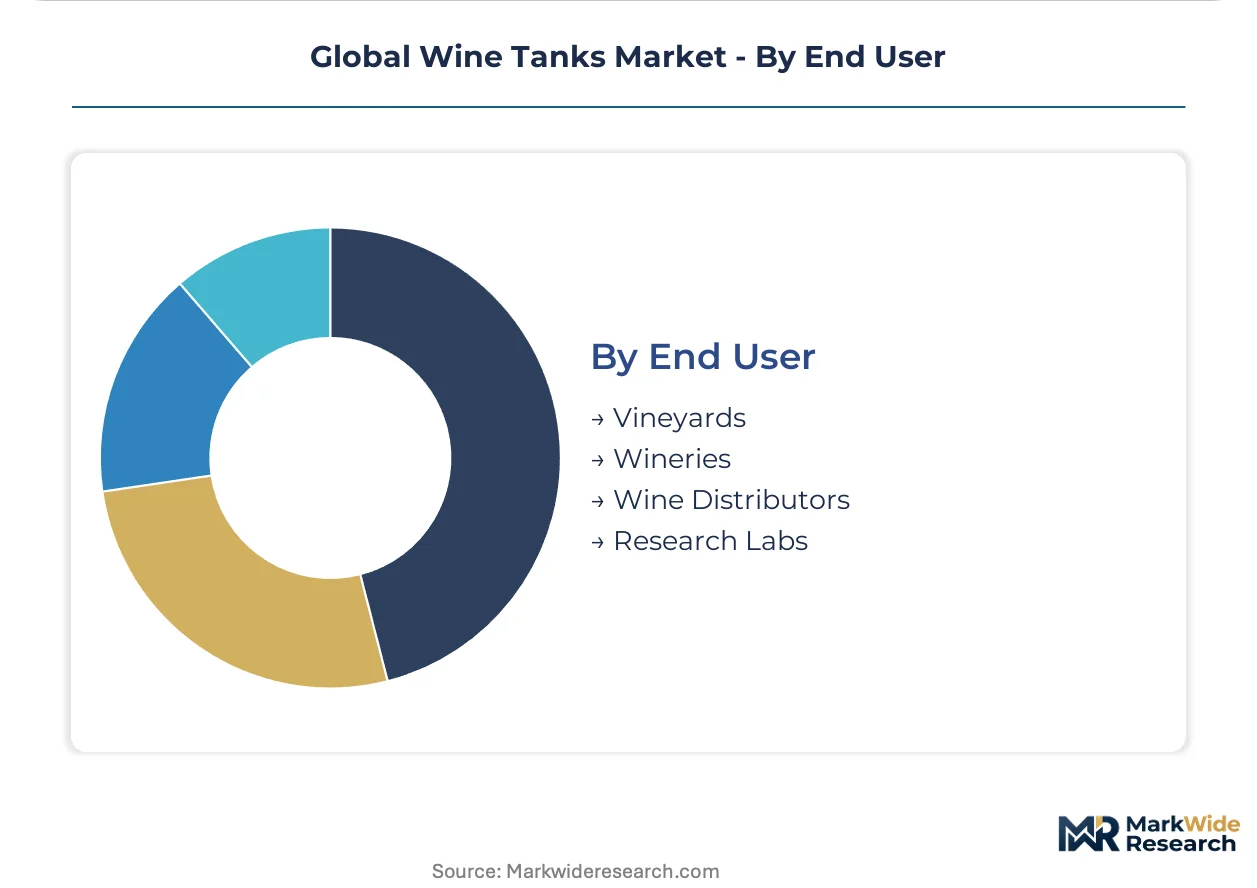
End User:
Customer type dictates procurement channel structure and service bundling expectations.
- Vineyards:Integrated growing and fermentation operations specifying tanks through engineering consultants rather than equipment dealers, concentrating in Australian clusters.
- Wineries:Primary demand anchor with fragmented scale from artisanal to industrial, driving tiered specification diversity across all material categories.
- Wine Distributors:Blending and storage infrastructure with logistics-centric procurement emphasizing modularity and rapid deployment.
- Research Labs:Experimental-scale vessels with maximum sensor integration and documentation requirements for protocol validation.
Wineries hold installed capacity. Vineyards are rotating up the share rankings as direct-to-winery fabrication partnerships displace distributor mediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in wine tank fabrication favor established manufacturing clusters with integrated stainless steel supply chains. France and Italy maintain trade surpluses in precision-engineered fermentation vessels, while Australia and the United States rely on regional fabrication hubs to compress lead times for domestic vineyard modernization.
France
Champagne houses are modernizing aging infrastructure with EU CE marking alignment for cross-border procurement. ANSM hygiene auditing mandates Ra 0.8 micrometer surface documentation and decade-long welding operator logs for AOC-designated zones. Producers in Reims and Épernay are consolidating procurement around vertically integrated suppliers with captive metallurgy labs.
United States
Napa Valley premium wineries are compressing equipment replacement cycles as temperature-controlled fermentation systems displace passive vessels. California Air Resources Board emissions rules for on-site welding operations are driving demand for centralized fabrication with pre-certified modular tank systems. Sonoma County clusters are specifying tanks through engineering consultants rather than agricultural equipment dealers.
Australia
Barossa Valley producers are consolidating tank procurement around regional fabrication hubs to reduce lead times and logistics costs. TGA-equivalent state-level food safety protocols govern surface finish specifications for wine-contact equipment. Margaret River and Coonawarra clusters are shifting procurement channels toward technical specialists, compressing price transparency for standardized vessel configurations.
Italy
Mid-sized wineries in Tuscany and Piedmont are upgrading from barrel-based workflows to 1000-liter stainless steel workhorse specifications. EU Green Deal manufacturing standards are tightening material traceability and fabrication energy disclosure requirements for European exporters. Prosecco producers in Veneto are adopting concrete thermal mass vessels for fermentation stability without oak influence.
Spain
Ribera del Duero mid-sized wineries are adopting wireless temperature and density sensor arrays at 18-month replacement cycles. REACH compliance governs coating and sealant chemistry validation for tank exports to broader European markets. Natural wineries in Priorat are expanding concrete vessel specifications across premium tiers, emphasizing wall porosity control and mineral leaching prevention.
Global Wine Tanks Market Competitive Landscape
Listed leaders compete with private specialists across fabrication scale and geographic coverage, producing a tiered structure where capital access separates volume players from precision engineering boutiques. The vendor base spans multinational stainless steel conglomerates, regional fabrication cooperatives, and artisanal oak cooperage specialists. Three archetypes dominate: vertically integrated metallurgy-to-fabrication operators, regional hub-and-spoke fabrication networks, and specialized fermentation engineering consultancies. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with modular pre-certification displacing on-site welding compliance.
Within the precision-engineering tier, Paul Mueller Company exemplifies North American vertical integration from raw alloy to finished vessel, while Della Toffola Group anchors Italian specialization in mid-to-large winery fermentation systems. Bucher Vaslin occupies a position among European precision-welding specialists serving extended barrel-aging simulation protocols. These three represent distinct geographic anchoring strategies—American captive supply chains, Italian regional hub concentration, and French welding-certification expertise—rather than direct product competition.
| Leading Market Players |
|---|
| Paul Mueller Company |
| Della Toffola Group |
| Cedarstone Industry |
| Bucher Vaslin |
| Speidel Tank- und Behälterbau GmbH |
| Zottel d.o.o. |
| Letina Inox |
| Gortani Srl |
| Tanks and Vessels Industries Ltd |
| Others |
Supply & Pricing Matrix
EU CE marking and FDA food-contact standards gate both supplier qualification and price differentiation simultaneously, forcing fabricators to absorb certification costs into tiered offerings while buyers consolidate procurement around pre-qualified vendors. Nickel alloy volatility on the London Metal Exchange feeds directly into contract indexing clauses, compressing margins for non-integrated suppliers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on surface finish precision to Ra 0.8 micrometers and decade-long welding operator traceability documentation. Pricing pressure stems from LME nickel volatility, with 304 and 316 alloy input costs triggering indexed contract renegotiations. Boutique wineries in emerging regions exhibit highest price sensitivity, while Champagne houses modernizing AOC-designated infrastructure show lowest.
Supply Chain Analysis
LME nickel futures trading in London underwrites raw material cost predictability for stainless steel fabricators. Supply concentrates in Italy, France, and the United States, with captive metallurgy labs in Reims and Épernay feeding specialized Champagne house demand. Raw material dependencies center on nickel ore from Indonesia and the Philippines, ferrochrome from South Africa, and scrap stainless from domestic recycling streams. Single-source vulnerability runs through Indonesian nickel processing capacity. Distribution runs through engineering consultants displacing agricultural equipment dealers in established wine regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement through direct-to-winery fabrication partnerships, as Australian and Californian clusters disintermediate distributor networks. This channel compression fragments price transparency and concentrates margin capture with technical specialists.
For Market Incumbents: Compound defensive positioning by deepening captive metallurgy lab capabilities to meet ANSM decade-long traceability mandates, and anchor capacity expansion in Barossa Valley regional hubs to compress lead times for Australian vineyard consolidation. Threat substitution from concrete thermal mass vessels in natural winery segments demands accelerated stainless steel IoT sensor integration to sustain technology premiums.
For New Entrants and Emerging Players: CE marking fast-track services for Maharashtra and Karnataka vineyard development unlock first-mover positioning in India's nascent wine market. White-space targets concentrate in turnkey fermentation infrastructure for emerging regions and modular pre-certified tank systems compliant with California Air Resources Board emissions rules. A go-to-market angle through engineering consultants rather than equipment dealers bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional fabrication cooperatives in Italy and Spain lacking captive metallurgy capabilities. Long-term viability over a 5-10 year window favors targets with backward integration into stainless steel supply chains and established welding certification protocols. The signal to watch is REACH compliance timeline acceleration for coating and sealant chemistry validation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Supply | Captive ferrochrome sourcing from South Africa insulates margins from LME volatility. |
| Modular Pre-Certification Program | California Air Resources Board compliance enables centralized fabrication with reduced on-site welding. |
| IoT Sensor Platform Launch | Wireless fermentation monitoring retrofit at Ribera del Duero wineries creates subscription revenue streams. |
| CE Marking Fast-Track Service | Expedited EU compliance unlocks cross-border procurement for Champagne house modernization. |
| Regional Fabrication Hub Expansion | Barossa Valley concentration reduces logistics costs for Australian vineyard procurement consolidation. |
Research Methodology
A spread of perspectives from tank fabrication engineers, vineyard procurement directors, welding certification auditors, and aftermarket service heads converged on the working assumptions. Primary fieldwork combined with secondary validation from EU CE marking documentation, FDA food-contact material filings, ANSM hygiene audit protocols, and LME nickel pricing archives. Customs data from French, Italian, and Australian trade authorities anchored volume triangulation. Bottom-up tank shipment analysis and top-down winery capital expenditure surveys were cross-referenced for convergence.
Segmentation dimensions modeled include material category, capacity tier, application process, and end-user type across the projection horizon. CAGRs were derived from installed base replacement cycle compression and premium tier adoption curves. Industry-specific forecast inputs incorporated REACH compliance timeline extensions and California Air Resources Board emissions rule implementation schedules.
Decision-makers should treat outputs as directional under stable nickel pricing and regulatory enforcement continuity; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EU Green Deal manufacturing standards and Indian vineyard development trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Tea Processing Machine Market
Food Processing Equipment
Air Cooled Cube Ice Machines Market
Food Processing Equipment
Reach-In Freezers Market
Food Processing Equipment
Reflow Oven Market
Food Processing Equipment
Water Cooled Cube Ice Machines Market
Food Processing Equipment
Portable Clean-In-Place Market
Food Processing Equipment
Deep Fryer Oil Filtration Market
Food Processing Equipment
Wine Processing Equipment Market
Food Processing Equipment
Fish Feed Pellet Making Machine Market
Food Processing Equipment
Sous Vide Cooking Appliances Market
Food Processing Equipment
Food-Grade Mixing Tank Market
Food Processing Equipment
Freeze-Drying Market
Food Processing Equipment
Conveyor Ovens and Impinger Ovens Market
Food Processing Equipment
Global Food Dehydrators Market
Food Processing Equipment
Food Ultrasound Market
Food Processing Equipment
Fish Filleting Machine Market