
 Bakery Processing Equipment Market | 2026-2036
Bakery Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Bakery Processing Equipment Market Analysis
China is tilting its bakery equipment manufacturing base toward automated lines serving domestic and export markets. Bühler leverages its Swiss engineering heritage to sustain premium positioning in industrial-scale mixing systems. GEA Group anchors European demand through integrated thermal processing solutions for high-volume bread plants.
Bakery processing equipment encompasses mechanical and thermal systems engineered to transform raw dough and batter into finished baked goods, typically operating at temperatures between 150°C and 300°C depending on product chemistry. These systems automate mixing, fermentation, dividing, forming, baking, cooling, and packaging to achieve batch consistency and throughput targets in commercial settings. Ovens and mixers command the largest installed base, though proofers generate disproportionate margin pools due to precision humidity control requirements. Convection technology leads in new installations across artisan and commercial bakeries, while industrial-scale rotary systems dominate frozen dough operations where throughput economics override capital intensity concerns.
FDA food safety mandates and EU MDR framework for food-contact materials shape equipment design standards and market access protocols across North American and European supply chains. China's SAMR enforces GB standards for electrical safety and hygiene that govern import eligibility for foreign oven manufacturers. Stakeholders must monitor evolving refrigerant phase-down schedules and energy efficiency benchmarks that will determine retrofit cycles and replacement demand trajectories.
Market Dynamics
The EU F-Gas Regulation is compressing replacement cycles for thermal processing equipment as bakeries face mandatory refrigerant phase-downs and efficiency benchmarks that render legacy ovens economically unviable.
Growth Catalysts
- Artisan bakery expansion:Western European craft bakeries are procuring precision fermentation systems to achieve consistent dough development at smaller batch scales.
- EU F-Gas Regulation:Mandatory hydrofluorocarbon phase-downs are forcing retrofit demand for low-emission oven technologies across member states.
- Industrial cluster concentration:German baking hubs anchor equipment procurement volumes through centralized purchasing agreements with processing line integrators.
Market Restraints
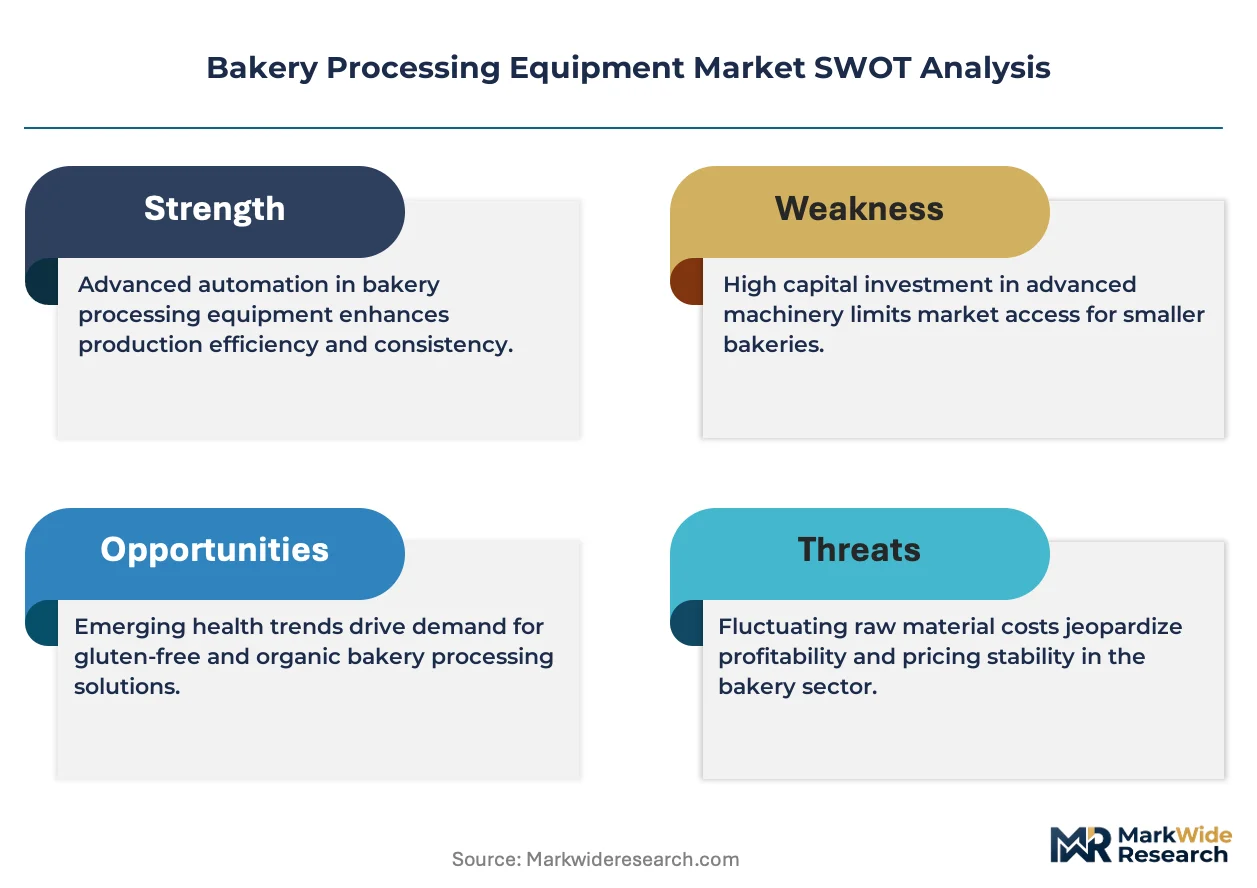
- Stainless steel price volatility:Input cost swings for food-grade alloys compress margin buffers for oven and mixer fabricators.
- Precision component supply concentration:Humidity sensor and thermal control module production concentrates in East Asian electronics manufacturing zones.
- Technical limitation in thermal uniformity:Rotary oven designs struggle to maintain consistent heat distribution across wide product portfolios without extended calibration cycles.
Strategic Opportunities
- Underpenetrated frozen dough segment:Automated proofing-to-baking lines for par-baked products remain undersupplied in North American commercial bakery chains.
- China's domestic equipment upgrade cycle:SAMR enforcement of GB electrical safety standards is disqualifying legacy imports and opening procurement windows for compliant system integrators.
- Technology convergence:IoT-enabled predictive maintenance modules are hybridizing with conventional thermal processing equipment to reduce unplanned downtime.
Industry Challenges
- Certification timeline compression:FDA food-contact material validations and EU MDR conformity assessments now extend equipment commercialization schedules by 8-14 months.
- Integration complexity:Legacy PLC architectures in installed bakery lines resist seamless connectivity with cloud-based production monitoring platforms.
- Specialized technician scarcity:Qualified field service engineers for thermal system diagnostics remain concentrated with original equipment manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bakery Processing Equipment Market |
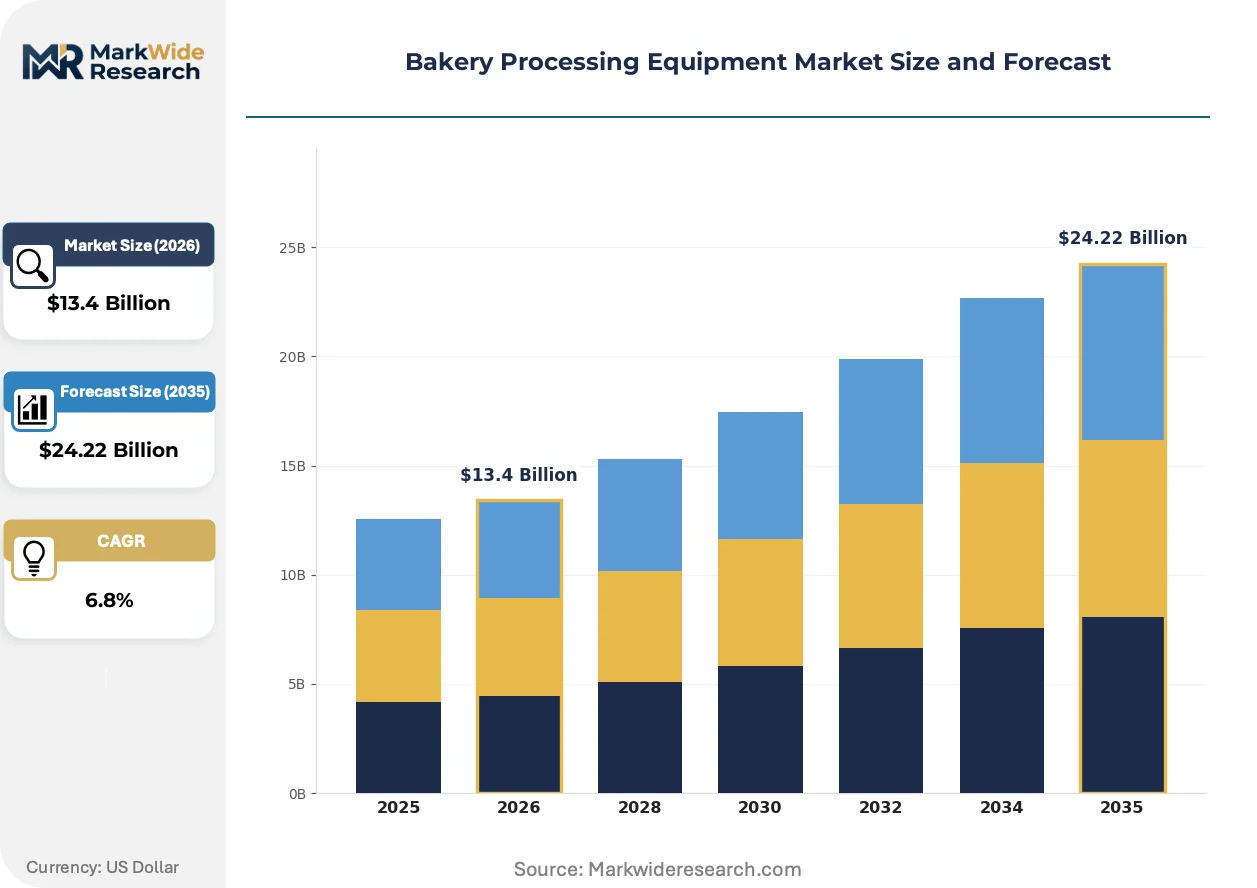
| Market Size in 2026 | $13.4 Billion |
| Market Size in 2035 | $24.22 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mixers, Ovens, Proofers, Dividers Application: Bread, Pastry, Cookies, Puff Pastry End User: Commercial Bakeries, Artisan Bakeries, Supermarkets, Foodservice Technology: Convection, Rotary, Microwave, Industrial |
| Companies Covered | GEA Group, Bühler, The Middleby Corporation, Ali Group, John Bean Technologies Corporation, Baker Perkins, Heat and Control, Rheon Automatic Machinery, Markel Food Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bakery Processing Equipment Market Emerging Trajectories
Active thermal management and digital thread technologies are restructuring how bakeries configure production lines, compressing the gap between artisan precision and industrial throughput.
Electrification of thermal processing is hybridizing conventional gas-fired oven architectures with induction heating elements and thermal storage systems. Mid-scale commercial bakeries in France and Italy are piloting these configurations to circumvent natural gas price volatility. The technology is hybridizing equipment procurement criteria, forcing buyers to evaluate total cost of ownership across mixed energy portfolios rather than capital expenditure alone.
The EU F-Gas Regulation and its national implementing measures are mandating refrigerant containment and leak detection systems in proofing and cooling equipment. Industrial bakeries must retrofit or replace climate-controlled fermentation chambers by fixed compliance deadlines. Frozen dough operations face the steepest capital requirements, with many German and Dutch facilities accelerating depreciation schedules to absorb replacement costs.
Buyer consolidation among supermarket private-label suppliers is compressing vendor negotiation cycles and unbundling after-sales service contracts from equipment purchases. Large French and British retail bakery suppliers now procure maintenance separately through third-party industrial service platforms. This pattern is most visible in high-volume bread and pastry segments where asset utilization rates dictate total cost sensitivity.
Bakery Processing Equipment Market Segmentation
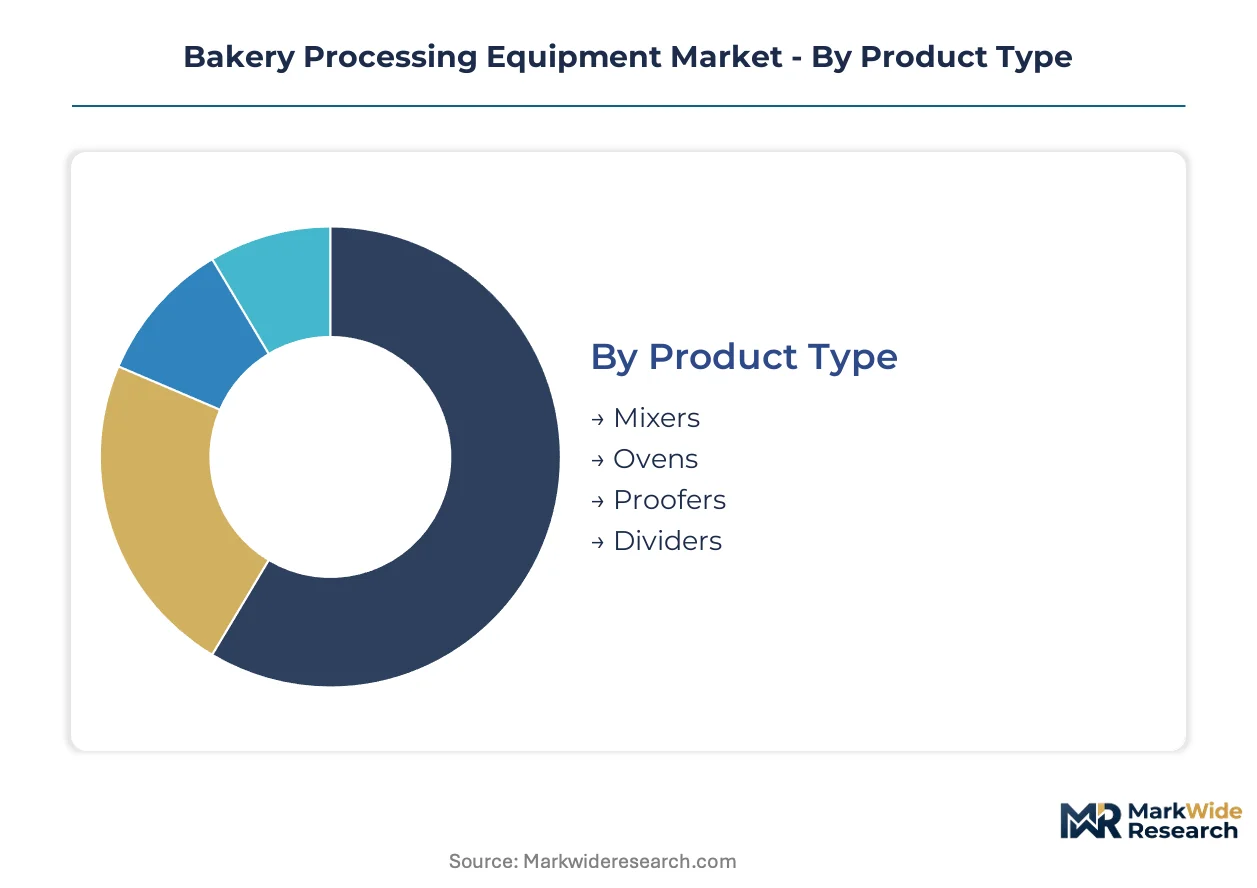
Equipment segmentation in bakery processing reveals divergent technology requirements across production scales. Product type and application dimensions drive fundamentally different thermal and mechanical specifications. End-user concentration and technology choices determine margin capture and replacement cycle timing.
Product Type:
Cost tier separates precision fermentation systems from high-throughput thermal processing assets. Capital intensity and operating expense profiles vary substantially across mixing, baking, and conditioning equipment categories.
- Mixers:Planetary and spiral configurations dominate commercial installations. Artisan bakeries in Germany specify variable-speed drives for dough development control. Stainless steel contact surfaces command premium pricing over coated alternatives.
- Ovens:Thermal processing cores operate between 150°C and 300°C with energy recovery systems. French industrial baking clusters anchor convection oven procurement volumes. EU F-Gas Regulation retrofit deadlines compress replacement cycles for legacy gas-fired units.
- Proofers:Climate-controlled fermentation chambers with humidity sensors. Precision component supply concentrates in East Asian manufacturing zones.
- Dividers:Automated dough portioning systems for high-volume lines. Commercial bakery chains in North America drive demand for integrated forming-dividing combinations.
Ovens hold installed capacity. Proofers are rotating up the share rankings.
Application:
Volume requirements and product chemistry dictate divergent equipment specifications across baked goods categories. Thermal uniformity demands vary with moisture content and crust development targets.
- Bread:High-throughput lines require continuous mixing and tunnel oven configurations. German baking hubs concentrate industrial bread equipment procurement through centralized purchasing agreements.
- Pastry:Lamination and precision forming systems for layered products. Artisan bakeries in Western Europe specify sheeting equipment with adjustable roller gaps.
- Cookies:Rotary moulders and wire-cut depositors for consistent portion control. Frozen dough operations drive automated line integration for par-baked cookie production.
- Puff Pastry:Specialized laminating systems with controlled temperature conditioning. Italian commercial bakeries pilot hybrid gas-induction thermal configurations for energy cost management.
Bread commands the largest installed base. Puff pastry is climbing the fastest on margin contribution.
End User:
Customer type determines batch scale, automation level, and service contract structure. Procurement authority concentrates differently across centralized industrial facilities versus distributed retail operations.
- Commercial Bakeries:High-volume production lines with integrated thermal processing and packaging. Supermarket private-label supplier consolidation in France and Britain unbundles equipment purchases from maintenance contracts.
- Artisan Bakeries:Smaller-batch precision equipment with fermentation control systems. Western European craft bakeries drive adoption of proofing technology with humidity regulation.
- Supermarkets:In-store baking operations with compact footprint requirements. Asset utilization rates dictate total cost sensitivity for high-volume bread and pastry segments.
- Foodservice:Rapid-cooking and compact oven configurations for institutional kitchens. Convection technology leads new installations across hotel and restaurant chains.
Commercial bakeries hold installed capacity. Artisan bakeries are gaining share fastest on precision equipment demand.
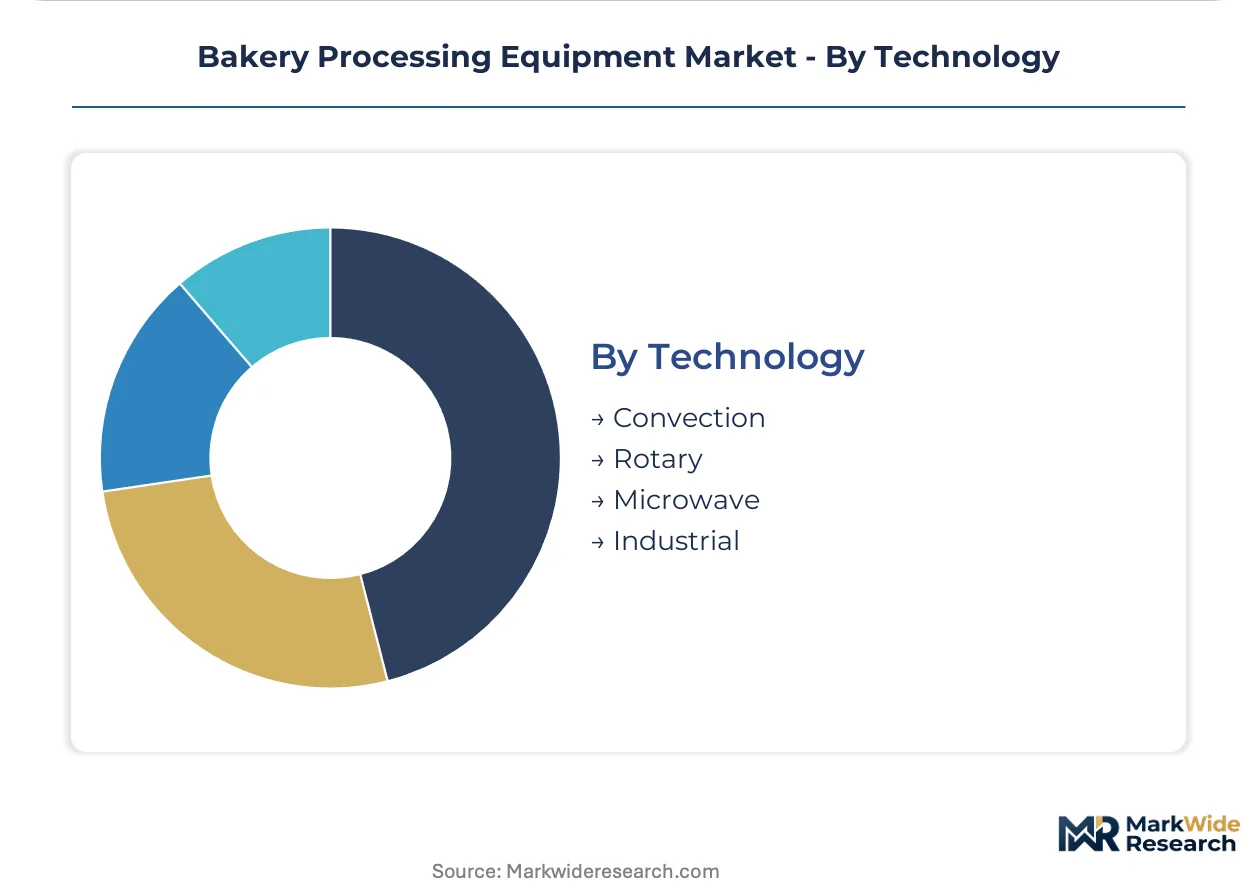
Technology:
Maturity and performance differentiation separate established thermal transfer methods from emerging energy configurations. Energy portfolio diversification is reshaping equipment evaluation criteria.
- Convection:Forced-air circulation systems for uniform heat distribution. Mid-scale commercial bakeries in France and Italy deploy these configurations for product consistency.
- Rotary:Continuous baking racks for high-throughput frozen dough operations. German and Dutch facilities face steepest capital requirements from F-Gas compliance deadlines.
- Microwave:Rapid heating applications for specific product categories. Limited penetration due to crust quality constraints in traditional bread production.
- Industrial:Integrated production lines with automated material handling. China tilts manufacturing capacity toward automated lines serving domestic and export markets.
Convection holds installed capacity. Industrial is rotating up the share rankings on automation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation anchors equipment procurement decisions across German industrial baking clusters, compressing replacement cycles for thermal processing assets. Specific country dynamics reveal divergent regulatory pressures and demand concentrations.
Germany
Industrial bread equipment procurement concentrates in North Rhine-Westphalia and Bavaria baking hubs through centralized purchasing agreements. The EU F-Gas Regulation mandates refrigerant phase-downs that accelerate depreciation schedules for legacy rotary ovens. Munich-based facilities pilot hybrid gas-induction thermal configurations for energy cost management.
United States
Frozen dough operations drive automated proofing-to-baking line demand among North American commercial bakery chains. FDA food safety mandates extend equipment commercialization schedules through food-contact material validation requirements. Chicago and Minneapolis industrial baking clusters anchor procurement volumes for high-throughput tunnel oven configurations.
China
Domestic equipment upgrade cycles accelerate as SAMR enforces GB electrical safety and hygiene standards that disqualify non-compliant imports. Automated line manufacturing tilts toward serving export markets alongside domestic bakery chain expansion. Yangtze River Delta equipment fabricators capture procurement windows from disqualified legacy suppliers.
France
Mid-scale commercial bakeries deploy convection oven configurations to circumvent natural gas price volatility through electrification pilots. ANSM and national implementing measures of the EU F-Gas Regulation mandate leak detection systems in climate-controlled fermentation chambers. Lyon and Paris industrial baking suppliers unbundle maintenance contracts from equipment purchases through third-party service platforms.
Italy
Artisan bakeries specify sheeting equipment with adjustable roller gaps for laminated product precision. CE marking requirements under EU MDR framework govern food-contact material compliance for oven and mixer fabricators. Emilia-Romagna commercial bakeries pilot hybrid thermal configurations alongside traditional gas-fired architectures.
Bakery Processing Equipment Market Vendor Landscape
Swiss-engineering heritage specialists and integrated thermal processing conglomerates split the market along precision-versus-scale vectors. The vendor base concentrates around three strategic archetypes: premium industrial-scale system integrators, mid-market commercial bakery specialists, and emerging automated line fabricators from East Asian manufacturing zones. Competitive positioning hardens through technology licensing arrangements and strategic partnerships with industrial baking clusters rather than pure product differentiation.
Within the premium-tier vector, Bühler leverages Swiss engineering heritage to sustain positioning in industrial-scale mixing systems. GEA Group anchors European demand through integrated thermal processing solutions. The Middleby Corporation occupies a position among commercial bakery equipment consolidators. These three exemplify divergent geographic anchoring strategies—Swiss precision engineering, German thermal integration, and North American commercial-scale specialization—without implying specific market share claims.
| Leading Market Players |
|---|
| GEA Group |
| Bühler |
| The Middleby Corporation |
| Ali Group |
| John Bean Technologies Corporation |
| Baker Perkins |
| Heat and Control |
| Rheon Automatic Machinery |
| Markel Food Group |
| Others |
Supply Flow & Price Mechanics
Stainless steel price volatility for food-grade alloys determines both the spread between premium and economy equipment tiers and the geographic reconfiguration of fabrication capacity. Input cost swings compress margin buffers for oven and mixer manufacturers while forcing procurement managers toward longer-term contract structures with East Asian metal suppliers.
Pricing Analysis
German industrial baking clusters pay 15-25% premiums over Southeast Asian buyers for identical convection oven specifications due to EU MDR certification requirements and localized service bundling. Three-tier pricing structure across premium, standard, and economy levels separates Swiss-engineered mixing systems with predictive maintenance modules from Chinese fabricators competing on capital expenditure alone. Pricing pressure stems from supermarket private-label supplier consolidation in France and Britain, where asset utilization rates dictate total cost sensitivity. Commercial bakery chains exhibit highest price sensitivity due to unbundled maintenance contracts, while artisan bakeries absorb premiums for fermentation precision.
Supply Chain Analysis
Food-grade stainless steel feedstock concentrates in China, Indonesia, and India, with European mills capturing specialty alloy niches for high-temperature oven applications. Humidity sensors and thermal control modules draw from East Asian electronics manufacturing zones, particularly South Korea and Taiwan. Single-source vulnerability concentrates in precision fermentation instrumentation, where two suppliers dominate climate-controlled chamber production. Distribution runs through industrial baking cluster procurement consortia in Germany and equipment integrators serving North American frozen dough operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bakery processing equipment market tracks a cyclical recovery anchored to EU F-Gas Regulation compliance deadlines that compress replacement cycles for thermal processing assets.
For Market Incumbents: Insulate service revenue streams from equipment sales volatility by unbundling predictive maintenance modules as standalone subscriptions. Backward integration into humidity sensor production reduces exposure to East Asian electronics supply concentration. Prioritize certification investment for EU MDR food-contact material compliance to extend commercialization timelines ahead of competitor submissions. For New Entrants and Emerging Players: Automated proofing-to-baking lines for North American par-baked cookie production represent the most penetrable entry point given undersupply in frozen dough operations. Mid-scale commercial bakeries in Italy and France piloting hybrid gas-induction thermal configurations offer technology partnership opportunities. Go-to-market execution should anchor on third-party industrial service platforms that now procure maintenance separately from equipment in British and French retail bakery supply chains. For Investors and Strategic Acquirers: The EU F-Gas Regulation reshapes the acquisition landscape by accelerating depreciation schedules for legacy rotary oven assets and opening consolidation windows among distressed German and Dutch facilities. Long-term viability centers on equipment-as-a-service business models with recurring revenue attachment. Monitor refrigerant phase-down enforcement velocity as the signal for retrofit demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Components | Captive supply of humidity sensors reduces vulnerability to East Asian electronics concentration. |
| Hybrid Thermal Configuration Development | Gas-induction pilots in Italian commercial bakeries circumvent natural gas price volatility exposure. |
| Equipment-as-a-Service Model Launch | Unbundled maintenance contracts through third-party platforms align with French and British buyer consolidation. |
| EU MDR Certification Fast-Track | Accelerated conformity assessment timelines capture retrofit windows before F-Gas compliance deadlines. |
| Automated Line Manufacturing Expansion | Yangtze River Delta capacity serves both domestic Chinese upgrade cycles and export market demand. |
Methodological Framework
A standing panel of plant engineers at industrial baking clusters, OEM procurement managers, aftermarket service heads, and thermal system designers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings of listed equipment manufacturers, customs trade data for stainless steel alloy imports, and EU MDR conformity assessment databases. Bottom-up equipment shipment tallies triangulated against top-down capacity expansion announcements from German and Chinese baking hubs.
Scenario-bracketing anchored volume projections across low, base, and high cases reflecting divergent EU F-Gas enforcement timelines and natural gas price trajectories. Segmentation modeling incorporated product type, application, end-user category, and technology architecture dimensions. CAGRs derived from fitted growth curves applied to replacement cycle analysis and retrofit demand elasticity estimates, with thermal processing energy cost differentials and refrigerant phase-down schedules as key industry-specific inputs.
Practitioners should monitor refrigerant containment system adoption rates and hybrid thermal configuration pilot outcomes for early signals of technology transition velocity. Forecasts reflect assumptions about regulatory enforcement consistency and commodity input stability. Material shifts in stainless steel alloy pricing or EU MDR assessment timeline extensions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Ice-Cream Maker Market
Food Processing Equipment
Commercial Kettles and Braising Pans Market
Food Processing Equipment
Salmon Fish Scaling Machine Market
Food Processing Equipment
North America Ginger Processing Market
Food Processing Equipment
Nut Processing Machine Market
Food Processing Equipment
Soda Production Machine Market
Food Processing Equipment
Pan Feeder Market
Food Processing Equipment
Canning Machine Market
Food Processing Equipment
Multi Ovens Market
Food Processing Equipment
Dry Ice Market
Food Processing Equipment
Electric Meat Saw Market
Food Processing Equipment
Pizza Scissors Market
Food Processing Equipment
Aseptic Processing Equipment Market
Food Processing Equipment
Shawarma Grill Machine Market
Food Processing Equipment
Smart Food Machine Market
Food Processing Equipment
Global Non-Thermal Pasteurization Market