
 Global Meat Mixer Market | 2026-2036
Global Meat Mixer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Meat Mixer Market Outlook
Aftermarket service revenue is rewriting profitability expectations across the equipment base. Hobart leverages its North American service network to capture recurring maintenance contracts. Swedlinghaus anchors Central European demand through specialized vacuum mixer rebuild programs. Mainca USA competes on compact footprint designs tailored to independent butcher shops.
Meat mixers are industrial food processing machines designed to blend ground meat with additives, seasonings, and binders through rotating paddles or augers in stainless-steel chambers, typically operating at 15-40 RPM to preserve protein structure while achieving homogenous distribution. Vacuum mixers extract air during blending to extend shelf life and improve protein extraction, with chamber pressures commonly held below 95% atmospheric. Horizontal mixers dominate volume sales due to their throughput efficiency in large-scale facilities, while smart mixer adoption accelerates fastest among mid-cap processors seeking batch traceability and HACCP-compliant data logging. Paddle mixers remain the mature workhorse segment where margin pools have compressed, pushing vendors toward control system upgrades rather than hardware-only sales.
The EU Machinery Directive and FDA's Food Safety Modernization Act shape equipment design through mandatory stainless-steel contact surfaces, IP65 washdown ratings, and traceable control systems. BIS certification requirements in India and China's GB food machinery standards further fragment compliance burdens for exporters. Stakeholders must monitor how carbon accounting rules and energy efficiency labeling reshape capital equipment procurement criteria across multiple jurisdictions.
Market Dynamics
Aftermarket service revenue streams are restructuring profitability across the meat mixer installed base, pushing OEMs to reconfigure hardware margins around recurring maintenance contracts and control system upgrade cycles rather than unit sales alone.
Growth Catalysts
- EU Machinery Directive safety mandates:Stainless-steel hygiene standards and IP65 washdown ratings are accelerating replacement cycles among legacy processors in Germany and Italy.
- Vacuum mixing technology:Protein extraction improvements and shelf-life extension below 95% atmospheric pressure are pulling demand from mid-cap facilities in Brazil's southern states.
- Artisanal sausage segment expansion:Independent butcher shops across Bavaria and São Paulo are modernizing equipment to meet export-grade certification requirements.
Market Restraints
- Stainless-steel input cost volatility:Grade 304 and 316 price swings compress margin pools on standard paddle mixer configurations.
- Supply concentration in German drive component manufacturing:Gear motor and variable frequency drive sourcing creates lead time vulnerability for non-European assemblers.
- Technical limitation in legacy control retrofit:Analog-era batch documentation systems cannot achieve HACCP-compliant data logging without full chamber replacement.
Strategic Opportunities
- India's BIS certification pathway:Untapped mid-scale processing capacity in Maharashtra and Karnataka awaits compliant equipment suppliers.
- Smart mixer convergence with IoT sensors:Real-time protein temperature and torque monitoring enables predictive maintenance contracts.
- China's GB food machinery standards:Dual carbon goals and energy efficiency labeling are reshaping procurement criteria for state-owned protein processors.
Industry Challenges
- Electromechanical technician scarcity:Servo-driven paddle systems require skill sets absent in traditional meat plant maintenance departments.
- Capex intensity for vacuum chamber certification:Pressure vessel compliance and third-party validation extend project timelines for smaller processors.
- Integration complexity with legacy batch management software:Proprietary SCADA protocols from 1990s-era installations resist smart mixer data handshake.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Meat Mixer Market |
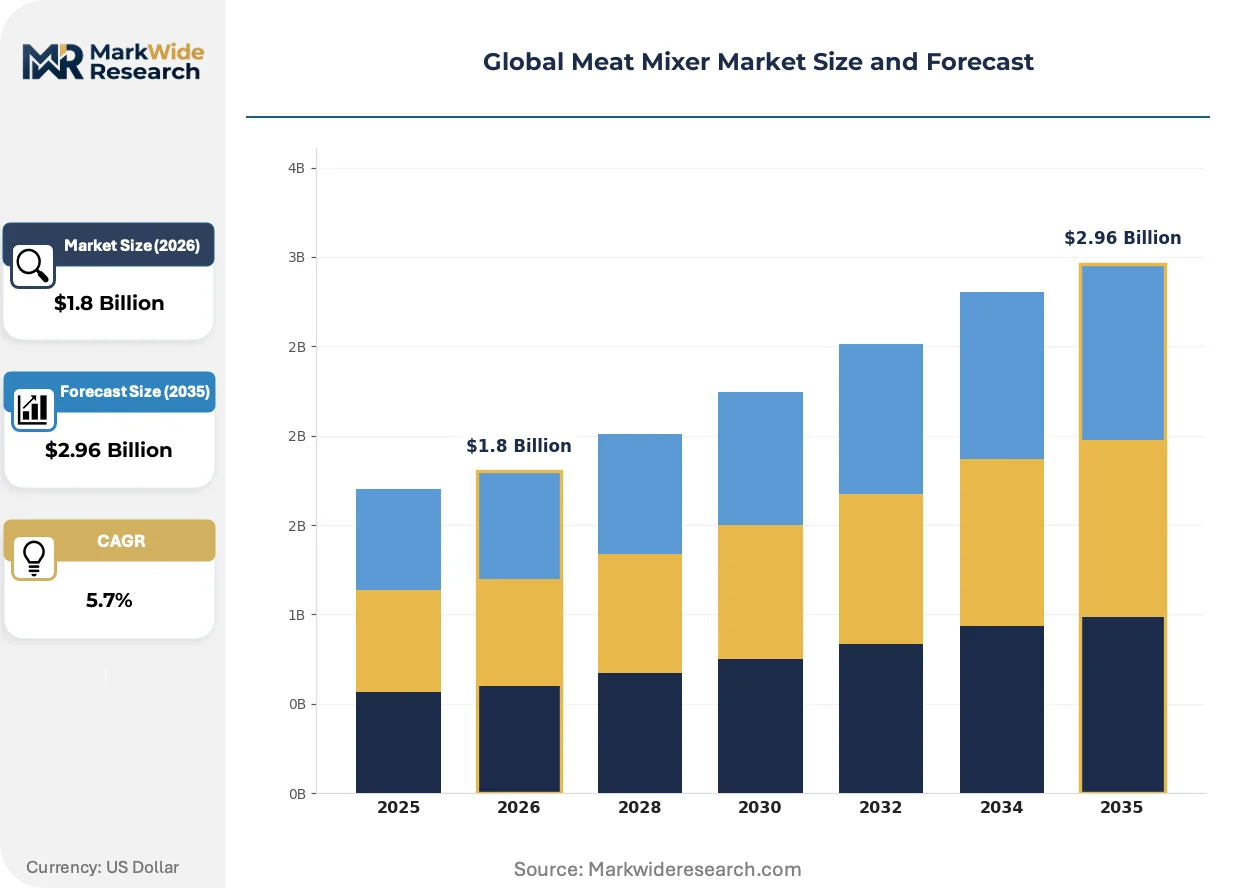
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Mixers, Vertical Mixers, Vacuum Mixers, Paddle Mixers End User: Meat Processors, Food Service Providers, Retail Chains, Butcher Shops Technology: Manual, Semi-Automatic, Fully Automatic, Smart Mixers Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Metos, ABM Company, Groupe PSV, Industrial Fuerpla, OMET FOODTECH SRL, Storm Engineering, Mainca USA, Swedlinghaus, Hobart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Meat Mixer Market Strategic Shifts
Control system digitization and predictive maintenance architectures are compressing the traditional hardware replacement cycle while elevating software and service contract value in vendor-customer relationships.
Variable frequency drive integration with torque-feedback paddle control is rendering obsolete fixed-speed mixer configurations in mid-cap facilities. Protein processors in Germany's Bavaria region are adopting these systems fastest, driven by batch consistency requirements for export sausage production. The technology is rendering obsolete manual speed adjustment protocols and the labor overhead they imposed on shift supervisors.
REACH chemical compliance and the EU Green Deal's embodied carbon tracking are mandating material passport documentation for stainless-steel contact surfaces. Equipment vendors must now certify alloy composition and sourcing back to mill origin for CE marking retention. Large-scale facilities in northern Italy face the steepest documentation burden, with procurement departments extending supplier qualification timelines by several months.
Service contract unbundling from equipment purchase is altering how independent butcher shops acquire mixing capacity. Monthly maintenance subscriptions with guaranteed uptime clauses are displacing traditional warranty-plus-breakdown repair models. This shift concentrates most visibly among artisanal producers in São Paulo's municipal markets, where cash flow constraints favor operational expenditure treatment over capital outlay.
Global Meat Mixer Market Segmentation
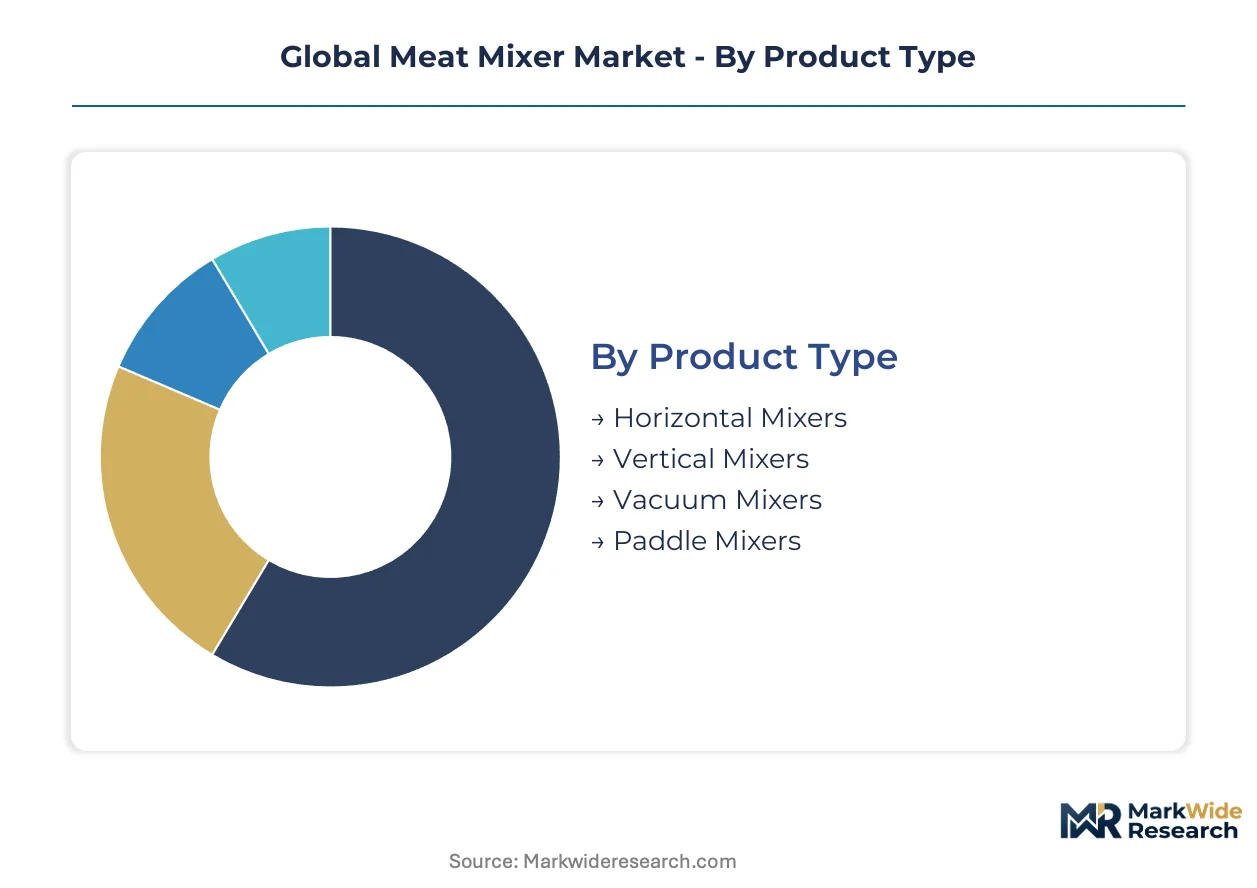
Equipment segmentation in meat mixing reveals divergent replacement rhythms. Horizontal and vacuum configurations cycle faster due to wear-intensive paddle mechanisms and seal degradation, while manual units in small butcher shops persist for decades with minimal parts turnover.
Product Type:
Cycle times stretch from three years on high-throughput horizontal units to fifteen-plus years on intermittent-use vertical designs, creating distinct aftermarket revenue windows for each configuration.
- Horizontal Mixers:Rotating drum or trough designs with twin-shaft paddle arrangements process bulk ground meat at 500-2000 kg hourly throughput. Bavarian mid-cap processors in Germany drive replacement demand as EU Machinery Directive mandates force stainless-steel chamber upgrades on legacy carbon-steel installations.
- Vacuum Mixers:Sealed chambers operating below 95% atmospheric pressure extract air during blending to enhance protein extraction and extend shelf life. Southern Brazil's expanding export-oriented sausage facilities adopt these systems to meet ANVISA certification requirements for chilled meat exports.
- Vertical Mixers:Upright bowl configurations with single or dual auger mechanisms suit lower-volume operations where floor space constraints dominate layout decisions.
- Paddle Mixers:Fixed-speed rotating blade systems represent the mature installed base where margin compression pushes vendors toward control system upgrades rather than hardware-only sales.
Horizontal mixers anchor the volume base while vacuum mixers gain share at the steepest rate.
End User:
Customer type determines procurement sophistication and service contract attachment rates more than any other segmentation dimension.
- Meat Processors:Industrial-scale facilities with HACCP-compliant batch documentation requirements and centralized maintenance departments. These buyers concentrate in northern Italy's Emilia-Romagna region, where REACH chemical compliance and material passport documentation extend supplier qualification timelines.
- Butcher Shops:Independent artisanal producers across São Paulo's municipal markets favor monthly maintenance subscriptions with guaranteed uptime clauses over capital-intensive equipment purchases, shifting spend to operational expenditure treatment.
- Food Service Providers:Central kitchens and commissary operations requiring standardized portion control and consistent texture across multiple outlet locations.
- Retail Chains:Supermarket meat departments with private-label sausage programs seeking traceable batch records for consumer-facing quality claims.
Meat processors command the largest average deal size while butcher shops expand the addressable base through subscription financing models.
Technology:
Automation tier correlates directly with data logging capabilities and regulatory compliance readiness across jurisdictions.
- Smart Mixers:IoT-enabled systems with real-time protein temperature, torque, and vibration monitoring enable predictive maintenance contracts. German Bavaria processors adopt these fastest for export sausage production where batch consistency requirements render manual speed adjustment protocols obsolete.
- Fully Automatic:Programmable logic controllers with recipe storage and automated cycle sequencing reduce labor overhead in high-volume facilities.
- Semi-Automatic:Hybrid designs requiring operator intervention for loading and unloading while automating mixing parameters.
- Manual:Hand-cranked or simple motor-driven units persisting in cash-constrained micro-enterprises with minimal regulatory exposure.
Smart mixers are climbing the fastest as mid-cap processors seek HACCP-compliant data logging without full chamber replacement.
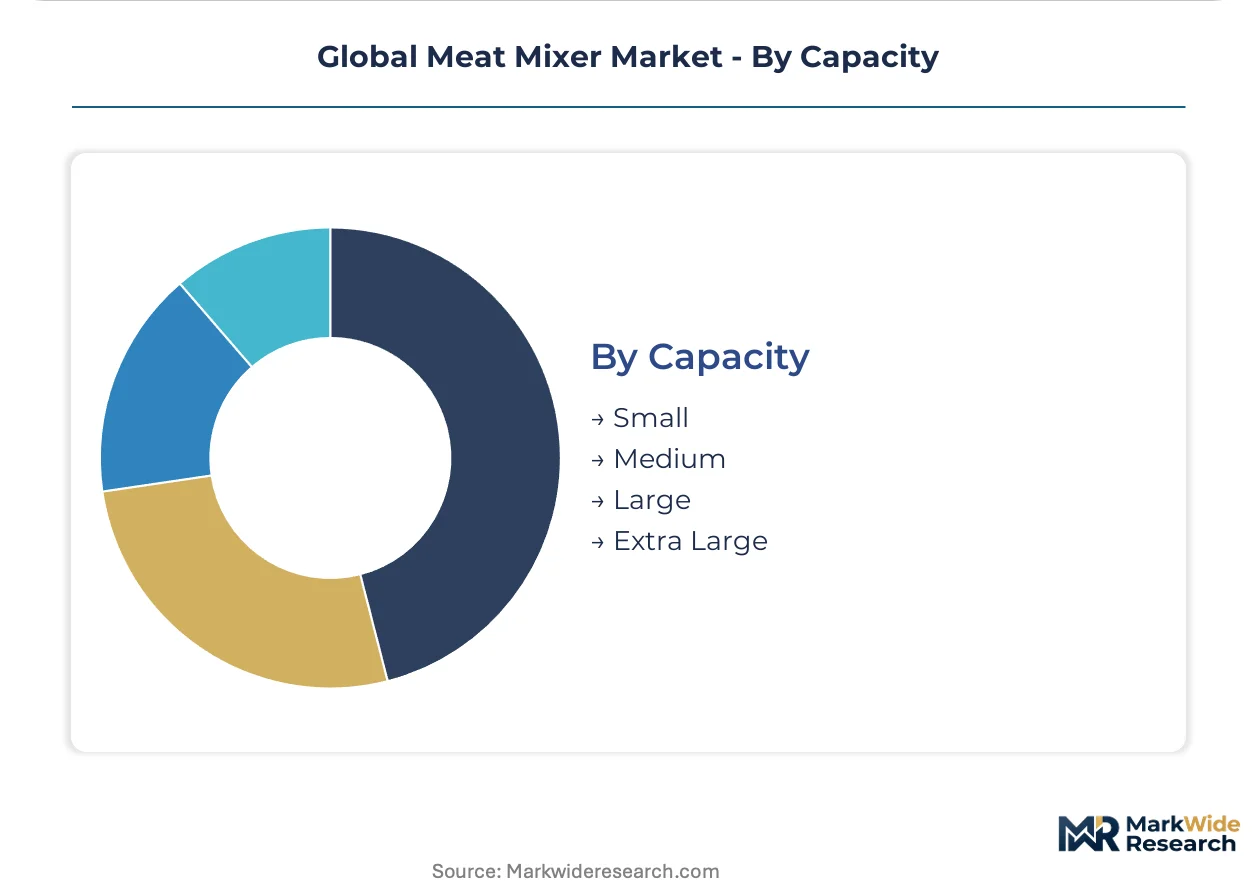
Capacity:
Scale tier maps to facility certification requirements and pressure vessel compliance burdens that disproportionately burden smaller processors.
- Large:Chambers exceeding 1000 kg batch capacity dominate industrial installations where throughput efficiency justifies dedicated electromechanical technician staffing.
- Extra Large:Custom-engineered systems for integrated protein processors with captive raw material supply.
- Medium:200-500 kg configurations serving regional processors balancing volume flexibility with capital efficiency.
- Small:Sub-100 kg units in independent butcher shops where capex intensity for vacuum chamber certification extends project timelines.
Large capacity installations generate the highest service contract value while small units proliferate through distributor finance programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Brazilian processors absorb stainless-steel cost volatility through local fabrication partnerships, while German buyers prioritize compliance documentation over unit economics. Indian mid-cap facilities face the steepest capital constraints.
Germany
Bavarian mid-cap processors drive replacement demand for horizontal vacuum mixers as EU Machinery Directive mandates force stainless-steel chamber upgrades on legacy carbon-steel installations. REACH chemical compliance and material passport documentation extend supplier qualification timelines by several months. The Emilia-Romagna corridor in northern Italy faces parallel documentation burdens, with procurement departments delaying equipment approvals pending alloy traceability certification.
Brazil
Export-oriented sausage facilities in Rio Grande do Sul adopt vacuum mixing systems to meet ANVISA certification requirements for chilled meat exports. Artisanal producers across São Paulo's municipal markets favor monthly maintenance subscriptions with guaranteed uptime clauses over capital-intensive purchases. Southern states concentrate the fastest equipment modernization as protein processors target European export quotas.
United States
Commercial butcher shops and regional processors upgrade paddle mixer control systems to achieve FDA Food Safety Modernization Act compliance without full chamber replacement. Mid-Atlantic and Midwest facilities lead smart mixer adoption for HACCP-compliant batch traceability. Hobart leverages its North American service network to capture recurring maintenance contracts across these upgrade cycles.
India
Untapped mid-scale processing capacity in Maharashtra and Karnataka awaits BIS-compliant equipment suppliers as national food safety standards tighten. Cash-constrained facilities favor operational expenditure models over capital purchases. Mumbai-Pune industrial corridor processors face electromechanical technician scarcity that complicates servo-driven system adoption.
China
State-owned protein processors reshape procurement criteria around dual carbon goals and energy efficiency labeling under GB food machinery standards. Yangtze River Delta facilities concentrate demand for large-capacity horizontal units with integrated variable frequency drives. Shanghai municipal regulators enforce stainless-steel sourcing documentation that mirrors EU material passport requirements.
Global Meat Mixer Market Competitive Environment
Capability concentration sits with specialized European fabricators; scale advantage sits with diversified North American equipment houses. The vendor base stratifies across three tiers: integrated foodservice conglomerates with captive distribution, regional machinery specialists with deep rebuild expertise, and emerging Asian fabricators competing on compact footprint designs. Consolidation pressure operates most intensely at the mid-market boundary where control system digitization demands R&D investment beyond standalone hardware margins. Dominant competitive moves include geographic expansion through distributor finance programs and technology licensing agreements for vacuum chamber certification protocols.
Within the European specialist tier, Swedlinghaus anchors Central European demand through vacuum mixer rebuild programs, while Metos exemplifies Nordic engineering concentration in stainless-steel fabrication. Hobart occupies a position among diversified North American equipment houses leveraging service network density for recurring revenue capture. These three represent distinct competitive archetypes: rebuild-centric specialization, materials engineering depth, and aftermarket infrastructure scale.
| Leading Market Players |
|---|
| Metos |
| ABM Company |
| Groupe PSV |
| Industrial Fuerpla |
| OMET FOODTECH SRL |
| Storm Engineering |
| Mainca USA |
| Swedlinghaus |
| Hobart |
| Others |
Value Chain & Pricing Dynamics
The Hamburg-Rotterdam freight corridor's container rate volatility feeds directly into landed cost spreads for stainless-steel chambers and German-sourced gear motors, compressing margin pools for non-European assemblers while amplifying price differentiation between CE-certified premium tiers and uncertified economy alternatives.
Pricing Analysis
Aftermarket service contracts and predictive maintenance subscriptions now drive lifetime value capture more than hardware margins alone. Three-tier pricing structure across premium smart-mixer, standard automatic, and economy manual levels separates buyers by certification grade and data-logging capability. Cost compression in standard paddle configurations is intensifying because Grade 304 stainless-steel input volatility transfers directly to bill-of-materials pressure. Independent butcher shops in São Paulo's municipal markets exhibit highest price sensitivity, while Bavarian mid-cap processors prioritize compliance documentation over unit economics.
Supply Chain Analysis
Supplier-financing instruments including extended payment terms and supply-chain finance facilities are proliferating among German drive-component manufacturers seeking to lock in assembler loyalty. Manufacturing concentration centers on Germany for precision gear motors, Italy for stainless-steel fabrication, and China for compact vertical units. Component sourcing draws from nickel-alloy suppliers in Indonesia, electric motor windings from China, and control systems from Taiwan. Single-source vulnerability in German variable-frequency drive production creates lead time exposure for Brazilian and Indian assemblers. Distribution runs through regional machinery distributors with captive service capabilities in Europe and North America, direct OEM relationships in Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as EU Machinery Directive replacement mandates force stainless-steel upgrades on legacy carbon-steel installations across Central Europe.
For Market Incumbents: Pre-empt margin erosion in standard paddle configurations by accelerating control system digitization roadmaps before smart-mixer adoption renders fixed-speed units obsolete. Hobart and Swedlinghaus should deepen backward integration into stainless-steel mill relationships to secure material passport documentation ahead of REACH compliance deadlines. Vertical integration into predictive maintenance software stacks represents the priority defensive lever against emerging IoT-native competitors. For New Entrants and Emerging Players: India's Maharashtra and Karnataka processing corridors offer geographic underpenetration where BIS certification requirements have stalled established European vendors. Target mid-cap facilities in Mumbai-Pune industrial corridor with compact vacuum mixer designs paired with technician training programs that address electromechanical skill scarcity. Service contract unbundling from equipment purchase provides the most penetrable go-to-market angle for cash-constrained buyers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors rebuild-centric specialists with vacuum chamber certification protocols and installed base data access over pure hardware fabricators. Long-term viability hinges on recurring revenue attachment rates rather than unit shipment volumes. Acquisition targets should demonstrate service contract penetration above industry norms in Germany or Brazil. Monitor ANVISA export certification timelines for chilled meat facilities as inflection indicator for vacuum mixer demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Chamber Certification Licensing | ANVISA-compliant protocols unlock Brazilian export-oriented sausage facility demand in Rio Grande do Sul. |
| Predictive Maintenance Platform Launch | IoT-enabled torque monitoring converts hardware sales into recurring subscription revenue from Bavarian processors. |
| Backward Integration into Stainless Supply | Mill-direct alloy sourcing secures material passport documentation required for CE marking retention. |
| Technician Training Program Partnership | Electromechanical skill development addresses adoption barriers for servo-driven systems in India's Mumbai-Pune corridor. |
| Subscription Financing Model Rollout | Operational expenditure treatment attracts São Paulo artisanal producers with cash flow constraints. |
Study Parameters
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings on compliance burden evolution. Plant engineers, maintenance directors at meat processing facilities, aftermarket service heads, and procurement leads at OEMs provided operational perspective. Secondary sources include EU Machinery Directive implementation guidance, ANVISA certification databases, FDA Food Safety Modernization Act facility inspection records, and BIS food machinery standard notifications. Bottom-up equipment shipment tracking and top-down protein processing capacity estimates were reconciled through iterative triangulation.
Calibration against historical replacement cycle data and regulatory enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include mixer configuration type, automation tier, capacity scale, end-user sophistication, and regional regulatory cluster. CAGRs were derived from installed base aging analysis and mandate-driven replacement scheduling. Industry-specific inputs encompass stainless-steel price index trajectories and vacuum chamber certification backlog data.
Practitioners should monitor EU Green Deal embodied carbon tracking implementation and China's dual carbon goal enforcement for early signals of procurement criteria shift. Forecasts reflect documented assumptions on regulatory compliance timelines and raw material cost stabilization. Macroeconomic contraction in protein processing, delayed BIS enforcement in India, or breakthrough alternative protein technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Asia-Pacific Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Butcher Equipment Market
Food Processing Equipment
Food Processing and Handling Equipment Market
Food Processing Equipment
Beer Brewing Equipment Market
Food Processing Equipment
Brewing Equipment Market
Food Processing Equipment
Food Processing Blades Market
Food Processing Equipment
Plastic Processing Machinery Market
Food Processing Equipment
Global Commercial Refrigeration Market
Food Processing Equipment
Canning Equipment Market
Food Processing Equipment
Multi Ovens Market
Food Processing Equipment
Electric Meat Saw Market
Food Processing Equipment
Edible Collagen Casing Market
Food Processing Equipment
Homogenizers Market
Food Processing Equipment
Global Powder Processing Equipment Market
Food Processing Equipment
Philippines Cold Storage Warehouse Market
Food Processing Equipment
Bottling Machinery Market