
 Walk-In Refrigerators & Freezers Market | 2026-2036
Walk-In Refrigerators & Freezers Market Size, Share, and Industry Trends Forecast 2026-2036
Walk-In Refrigerators & Freezers Market Insights
Polyurethane foam is expanding its share of walk-in panel insulation as manufacturers phase out legacy materials with higher thermal conductivity. Hussmann Corporation leverages captive foam-in-place manufacturing to control panel consistency and delivery timelines. Kolpak anchors its position through modular panel systems that simplify field assembly for independent restaurant operators. Amerikooler differentiates with quick-ship programs targeting regional distributors serving the southeastern United States.
Walk-in refrigerators and freezers are factory-built or field-assembled insulated enclosures maintaining temperatures from approximately -10°F to 55°F, constructed with interlocking polyurethane-injected panels and sealed gaskets to minimize thermal bridging. Their primary purpose is preserving perishable inventory in commercial environments where volume exceeds reach-in equipment capacity. The walk-in freezer category commands premium pricing due to thicker insulation requirements and more demanding compressor specifications. Digital controls technology is gaining share as operators prioritize remote temperature monitoring and alarm integration. Combination units occupy a stable niche in smaller food service installations where space constraints prohibit separate refrigerator and freezer compartments.
The EPA enforces refrigerant transition timelines under Section 608 of the Clean Air Act, compelling manufacturers to validate alternative refrigerant performance in walk-in systems. The Department of Energy mandates minimum efficiency standards for commercial refrigeration equipment, tightening test procedures that affect walk-in condensing unit ratings. NSF International certification governs food zone materials and cleanability for units installed in inspected kitchens. Stakeholders must weigh total cost of ownership against first cost as refrigerant regulations and efficiency standards converge on replacement cycles.
Market Dynamics
The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is compressing replacement cycles and forcing equipment decisions ahead of natural end-of-life, restructuring how food service operators and cold storage developers time capital deployment.
Growth Catalysts
- AIM Act refrigerant mandates:The EPA's phasedown schedule accelerates equipment turnover as operators replace HFC-dependent systems ahead of supply constraints and servicing restrictions.
- Prepared meal program expansion:Quick-service restaurant chains are enlarging cold storage footprints to support centralized commissary production and last-mile distribution of fresh-prepared items.
- Polyurethane foam insulation:Manufacturers are converting panel production to polyurethane-injected systems that deliver superior thermal performance and thinner wall profiles.
Market Restraints
- Copper and steel input volatility:Condensing unit fabrication and panel frame construction face margin pressure from commodity price swings in structural metals and refrigeration tubing.
- Specialized installation labor scarcity:Field assembly of modular walk-in systems requires certified refrigeration technicians, with qualified contractor availability concentrated in major metropolitan corridors.
- Alternative refrigerant validation gaps:Lower-GWP refrigerant formulations remain unproven across the full operating envelope of walk-in freezer applications, delaying manufacturer product certification.
Strategic Opportunities
- Remote monitoring convergence:Integration of IoT temperature sensors with building management systems is automating compliance documentation and reducing manual logging labor.
- US Southeast distribution gaps:Quick-ship programs targeting independent restaurant operators in Georgia, Florida, and the Carolinas address underserved regional demand with compressed lead times.
- Supermarket remodel cycles:Major US grocery chains are absorbing disproportionate unit volumes as legacy stores undergo refrigeration infrastructure modernization.
Industry Challenges
- Section 608 technician certification:The EPA's refrigerant handling requirements constrain service capacity, with certification backlogs delaying field commissioning of new installations.
- NSF International food zone compliance:Panel interior finishes and gasket materials must satisfy cleanability standards, extending product development timelines for new surface treatments.
- DOE test procedure alignment:Condensing unit efficiency ratings face recalculation under revised federal test methods, complicating specification comparisons during procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Walk-In Refrigerators & Freezers Market |
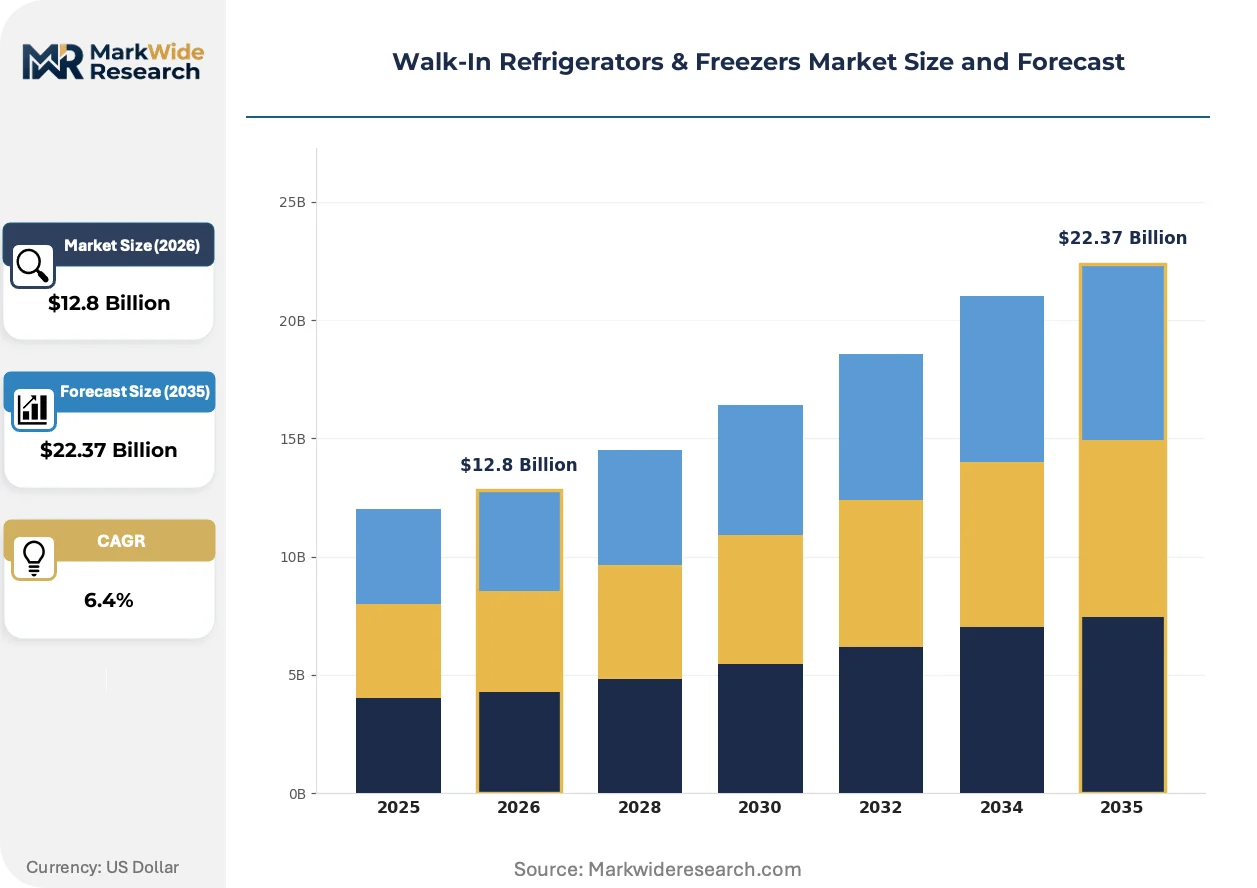
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walk-In Refrigerator, Walk-In Freezer, Combination Unit, Blast Chiller, Cold Room Technology: Direct Expansion, Remote Condensing, Self-Contained, Scroll Compressor, Digital Controls Application: Food Service, Pharmaceutical Storage, Floral Preservation, Beverage Storage, Hospitality Storage End User: Restaurants, Supermarkets, Cold Storage Facilities, Catering Services, Event Venues |
| Companies Covered | Hussmann Corporation, Kolpak, Nor-Lake, Arctic Walk in Coolers & Walk-In Freezers, Amerikooler, Danfoss A/S, Foster Refrigerator, Master-Bilt Products, Imperial Brown Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Walk-In Refrigerators & Freezers Market Trends and Innovations
Digital control architectures are displacing electromechanical thermostats across walk-in installations, embedding connectivity as a baseline expectation rather than premium upgrade. This shift is compressing the competitive window for legacy component suppliers.
Variable-speed compressor technology is automating capacity modulation in response to door-opening events and load fluctuations. Convenience store chains with 24-hour operations are adopting these systems most aggressively. The technology is automating energy consumption optimization that previously required manual defrost scheduling.
The EPA's Section 608 enforcement expansion is tightening leak detection and repair documentation requirements for commercial refrigeration systems. Equipment manufacturers are integrating permanently mounted leak detection sensors as standard features. Walk-in freezer installations above 500 pounds charge size face the most intensive compliance obligations.
Food service operators are consolidating vendor relationships and demanding single-source accountability for envelope, refrigeration, and controls performance. Independent distributors are losing specification influence to direct manufacturer engagement with national account chains. This concentration is most pronounced among burger and pizza franchise systems with standardized store formats.
Walk-In Refrigerators & Freezers Market Segmentation
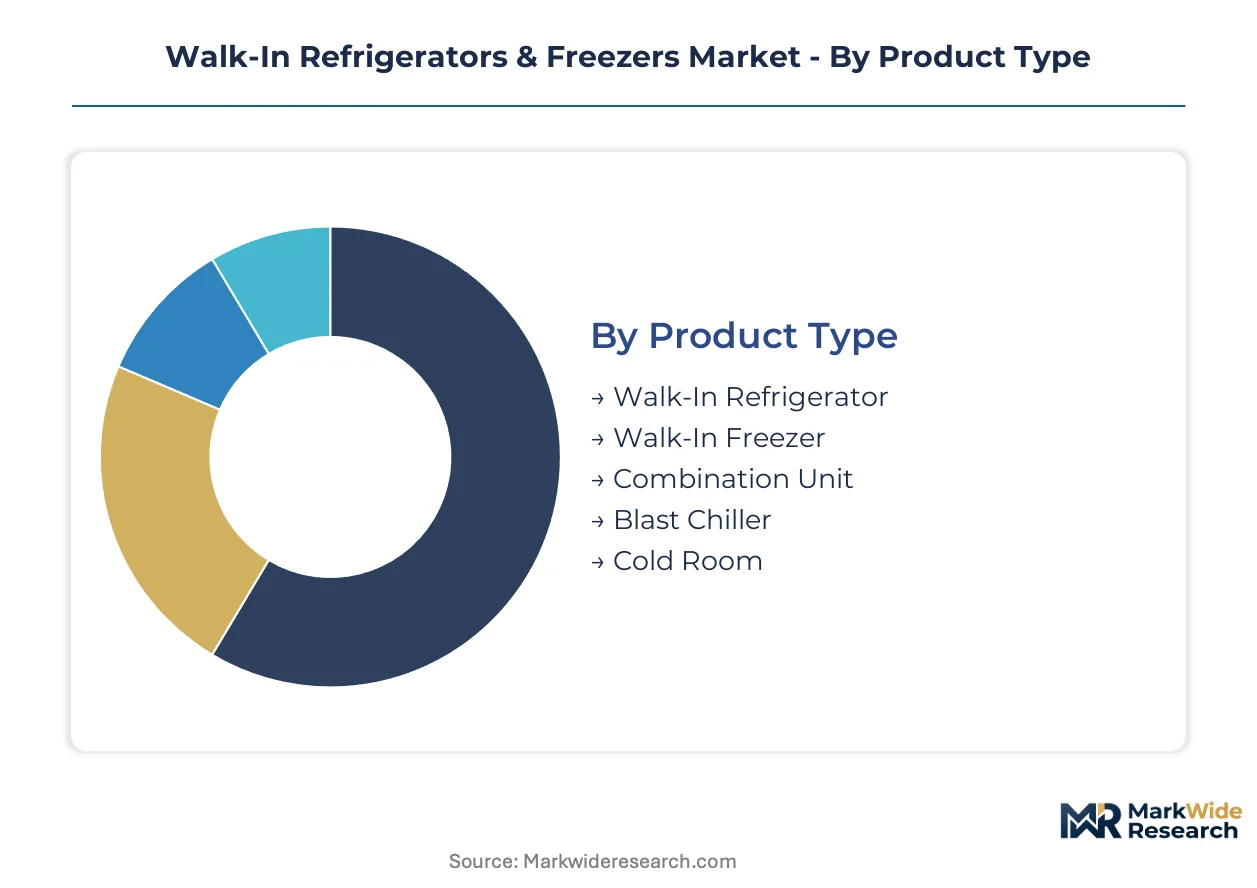
Walk-in refrigeration equipment serves heterogeneous operational requirements across temperature ranges, installation constraints, and regulatory exposures. Segmentation reveals how specification choices cascade into total cost of ownership and compliance obligations for distinct user profiles.
Product Type:
Temperature specification and insulation thickness define the engineering envelope and capital intensity of each product category.
- Walk-In Refrigerator:Maintains 34°F to 40°F through 4-inch polyurethane panels, serving quick-service restaurant back-of-house operations where door cycling frequency demands rapid temperature recovery. Demand concentrates in United States metropolitan corridors where franchise remodel cycles absorb standardized 8x10 and 10x12 foot modules.
- Walk-In Freezer:Requires 6-inch insulation and low-temperature compressors rated for -10°F operation, commanding premium pricing due to thicker envelope construction and defrost system complexity. Cold storage warehouse developers in Texas and Florida are absorbing disproportionate volumes as third-party logistics providers expand frozen capacity for e-commerce grocery fulfillment.
- Combination Unit:Integrates refrigerated and frozen compartments within a single envelope, optimizing floor space in independent restaurants with constrained mechanical room access.
- Blast Chiller:Rapidly reduces cooked product temperatures through forced airflow systems, addressing HACCP compliance in commissary kitchens preparing centralized meal components.
- Cold Room:Large-scale field-assembled enclosures exceeding 1,000 square feet, deployed by produce distributors requiring humidity-controlled bulk storage.
Mature deployment sits with Walk-In Refrigerator configurations in established quick-service chains. Newer deployment is concentrated in Blast Chiller systems supporting prepared meal centralization.
Technology:
Refrigeration system architecture determines energy efficiency, maintenance accessibility, and refrigerant charge management under evolving EPA mandates.
- Direct Expansion:Evaporator coils distribute refrigerant directly within the walk-in envelope, minimizing line set complexity and installation labor. Supermarket operators favor this approach for medium-temperature display case backup storage.
- Remote Condensing:Separates compressor and condenser from the conditioned space, reducing heat load and noise in occupied kitchens. Convenience store chains with 24-hour operations are specifying remote systems most aggressively as electricity rates climb in California and New York.
- Self-Contained:Factory-charged systems reduce field refrigerant handling, appealing to independent restaurant operators facing Section 608 technician certification constraints.
- Scroll Compressor:Delivers variable capacity modulation through digital unloading, automating energy optimization that previously required manual defrost scheduling.
- Digital Controls:IoT-enabled temperature monitoring and alarm integration are displacing electromechanical thermostats as baseline specifications rather than premium upgrades.
Remote Condensing systems dominate new supermarket construction. Self-Contained units are expanding fastest among independent operators prioritizing installation simplicity.
Application:
End-use temperature precision and contamination control requirements shape specification rigor and certification obligations.
- Food Service:Encompasses restaurant, cafeteria, and commissary operations where NSF International food zone compliance governs panel interior finishes and gasket materials. This application absorbs the majority of walk-in shipments due to franchise system standardization.
- Pharmaceutical Storage:Demands continuous temperature documentation and alarm redundancy for vaccine and biologic preservation, with FDA 21 CFR Part 11 compliance driving digital control adoption.
- Floral Preservation:Requires precise humidity control alongside temperature management, serving wholesale distributors supplying event and retail channels.
- Beverage Storage:High-volume, medium-temperature applications in stadium concessions and hotel banquet operations where rapid stock rotation reduces insulation demands.
- Hospitality Storage:Covers hotel kitchen and catering prep areas with intermittent usage patterns favoring energy-efficient standby modes.
Food Service maintains the largest installed base. Pharmaceutical Storage is climbing the fastest as cold chain integrity requirements tighten for temperature-sensitive therapeutics.
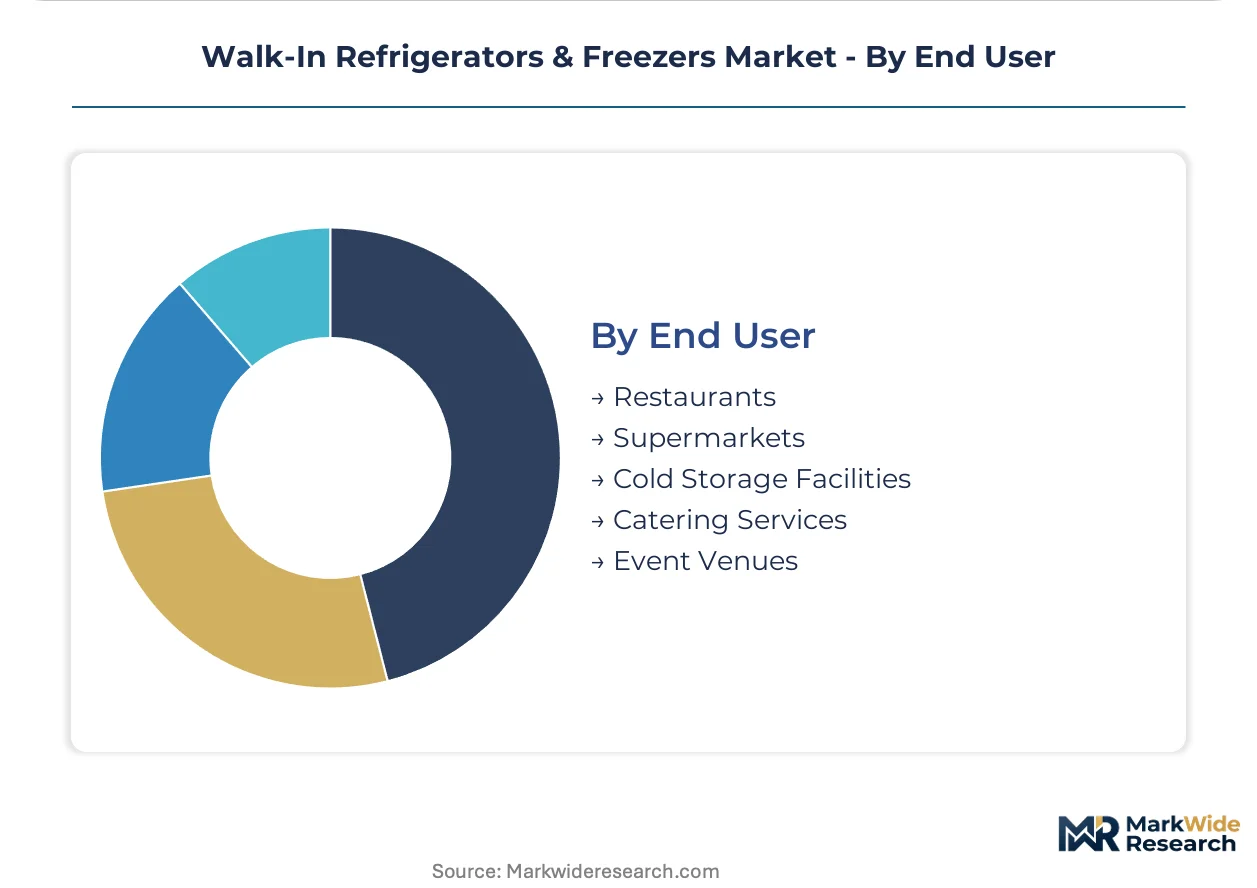
End User:
Procurement scale and specification authority concentrate differently across customer types, restructuring distribution channel influence.
- Restaurants:Independent operators purchase through regional distributors with quick-ship programs, while franchise systems engage manufacturers directly for standardized store formats. Burger and pizza chains with national footprints are consolidating vendor relationships and demanding single-source accountability.
- Supermarkets:Major United States grocery chains absorb disproportionate unit volumes as legacy stores undergo refrigeration infrastructure modernization, with remodel cycles timed to AIM Act refrigerant transition deadlines.
- Cold Storage Facilities:Third-party logistics providers specify engineered systems with 25-year envelope lifecycles, prioritizing thermal performance over first cost.
- Catering Services:Mobile and temporary installation requirements favor modular panel systems with rapid field assembly.
- Event Venues:Seasonal demand patterns and space constraints drive rental market preference for portable cold room solutions.
Supermarket procurement dominates capital-intensive project volume. Cold Storage Facilities are expanding specification influence fastest as warehouse construction accelerates in Georgia and the Carolinas.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States food service operators and cold storage developers absorb the dominant share of walk-in unit shipments, with supermarket remodel cycles and third-party logistics warehouse construction driving disproportionate demand concentration.
United States
Quick-service restaurant chains are expanding commissary cold storage footprints to support prepared meal centralization. The EPA's AIM Act refrigerant phasedown is compressing equipment replacement timelines ahead of natural end-of-life. Cold storage construction clusters in Texas and Florida as e-commerce grocery fulfillment demands frozen capacity expansion.
Germany
Industrial bakery and meat processing facilities are retrofitting legacy cold rooms to meet EU F-Gas Regulation hydrofluorocarbon reduction mandates. The country's national environmental regulator enforces leak detection documentation for commercial refrigeration systems above specific charge thresholds. Manufacturing concentration in Bavaria supports panel fabrication for Central European distribution.
China
Fresh food e-commerce platforms are driving cold chain infrastructure investment at the urban distribution layer. The Ministry of Ecology and Environment implements dual carbon goals that accelerate energy efficiency standards for commercial refrigeration equipment. Yangtze River Delta logistics hubs are absorbing walk-in freezer capacity for seafood and frozen produce consolidation.
Japan
Convenience store operators with 24-hour operations are specifying remote condensing systems to manage electricity costs. METI efficiency standards tighten test procedures for commercial refrigeration equipment ratings. Kanto region metropolitan corridors concentrate retrofit demand as aging supermarket refrigeration infrastructure reaches replacement age.
United Kingdom
Food service wholesalers are consolidating distribution centers and upgrading cold storage envelope performance. The country's environmental regulator enforces F-Gas compliance timelines that accelerate HFC-dependent system replacement. London and Southeast England absorb premium quick-ship walk-in configurations for high-turnover restaurant supply operations.
Walk-In Refrigerators & Freezers Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers align with controls suppliers and refrigerant technology providers to navigate EPA transition timelines. The vendor base organizes into three tiers: integrated envelope-refrigeration specialists, modular panel fabricators, and component-focused suppliers. Two archetypes define competitive positioning: captive foam-in-place manufacturers controlling panel consistency, and quick-ship distributors targeting compressed lead times for independent operators. M&A activity concentrates on regional distributor consolidation, while capacity expansion focuses on polyurethane panel injection lines in southeastern United States corridors.
Among North American envelope specialists, Hussmann Corporation and Kolpak exemplify divergent strategic archetypes. Hussmann represents the integrated manufacturing model with captive foam-in-place operations. Kolpak anchors the modular panel segment with field-assembly simplicity for independent restaurant operators. Amerikooler occupies a position within the quick-ship distribution tier, targeting compressed delivery timelines for southeastern United States regional markets. Danfoss A/S sits within the component supply layer as a refrigeration controls and compressor technology provider rather than an envelope fabricator.
| Leading Market Players |
|---|
| Hussmann Corporation |
| Kolpak |
| Nor-Lake |
| Arctic Walk in Coolers & Walk-In Freezers |
| Amerikooler |
| Danfoss A/S |
| Foster Refrigerator |
| Master-Bilt Products |
| Imperial Brown Inc. |
| Others |
Pricing and Supply Chain Analysis
Envelop-to-refrigeration integration depth bifurcates the market into premium single-source bundles and commodity panel-plus-condenser assemblies, with this divergence manifesting in both pricing power concentration among captive foam manufacturers and supply chain fragmentation across independent distributors serving price-sensitive independent restaurants.
Pricing Analysis
High-volume supermarket chains negotiate project-based contracts with 15-20% first-cost premiums for integrated performance guarantees, while independent operators face transactional spot pricing for modular panel kits. Price differentiation rests on NSF certification grade and polyurethane foam density specifications. Cost compression in economy tiers intensifies as Chinese panel imports and domestic quick-ship distributors compete for back-of-house restaurant replacement cycles. Franchise systems exhibit lowest price sensitivity due to standardized specification lock-in, whereas independent caterers and event venues drive aggressive bidding for portable cold room rentals.
Supply Chain Analysis
Freight cost sensitivity shapes regional manufacturing footprints, with polyurethane panel injection lines clustering in Georgia and the Carolinas to serve southeastern quick-ship demand. Supply concentrates in the United States for envelope fabrication, China for compressor components and digital control modules, and Germany for precision refrigeration valves and sensors. Raw material dependencies span copper tubing for condensing units, steel for panel frames, and isocyanate/polyol chemicals for foam insulation. Single-source vulnerability sits with EPA-certified refrigerant formulations facing AIM Act phasedown timelines. Distribution runs through manufacturer-direct national accounts for supermarket chains and two-step distributor networks for independent food service operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as envelope specialists acquire refrigeration controls capabilities and compressor manufacturers backward-integrate into panel fabrication to capture full-system margins.
For Market Incumbents: Extend captive foam-in-place manufacturing scale to defend against Chinese import price pressure in economy panel tiers. Consolidate regional distributor relationships in the US Southeast to preempt quick-ship competitors from capturing independent restaurant volume. Invest in EPA alternative refrigerant validation ahead of HFC servicing restrictions to lock in replacement cycle specification authority. For New Entrants and Emerging Players: The $2,000-4,000 per-linear-foot gap between premium integrated systems and economy modular kits opens white-space for mid-tier players offering NSF-certified panels with third-party condensing unit compatibility. Target cold storage warehouse developers in Texas and Florida seeking 25-year envelope lifecycle performance without single-source vendor lock-in. Pursue direct engagement with third-party logistics providers bypassing traditional distributor markup structures. For Investors and Strategic Acquirers: Re-rating potential sits with modular panel fabricators possessing EPA refrigerant transition readiness given accelerated replacement cycle demand. Long-term viability favors envelope-refrigeration integrators controlling polyurethane formulation and digital controls architecture. Watch Section 608 technician certification backlogs as an inflection signal—service capacity constraints that delay field commissioning will compress margins for manufacturers lacking installation support networks.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foam-in-Place Manufacturing Scale-Up | Hussmann's polyurethane injection control reduces panel thermal bridging and compresses delivery timelines for national supermarket accounts. |
| Alternative Refrigerant Validation Investment | Early EPA certification for R-448A and R-449A performance in low-temperature freezer applications secures specification authority ahead of HFC phasedown deadlines. |
| Quick-Sip Distribution Network Expansion | Amerikooler's compressed lead time programs capture independent restaurant demand in Georgia and Florida corridors underserved by national distributors. |
| Digital Controls Platform Integration | IoT temperature monitoring convergence automates HACCP compliance documentation and displaces electromechanical thermostat suppliers from retrofit specifications. |
| Regional Distributor Consolidation | Acquisition of independent refrigeration distributors in the Carolinas builds installation service capacity critical to AIM Act-driven replacement cycle capture. |
Research Methodology
Document review covered EPA Section 608 enforcement guidance, DOE commercial refrigeration efficiency rulemakings, and NSF International certification standards, complemented by interviews with food service equipment procurement directors at quick-service restaurant chains, cold storage warehouse development executives, independent refrigeration contractors, and polyurethane panel manufacturing plant managers. Secondary validation drew from customs trade data for refrigeration equipment imports, supermarket chain capital expenditure disclosures, and third-party logistics warehouse construction permits. Bottom-up unit shipment estimates triangulated against top-down construction spending allocations for food service and cold storage infrastructure.
Unit volume and value projections incorporate temperature specification segmentation, installation type differentiation between factory-built and field-assembled systems, and end-use concentration across food service, pharmaceutical, and cold storage applications across the analysis window. CAGRs derive from replacement cycle compression modeling under AIM Act refrigerant phasedown schedules and supermarket remodel pipeline tracking. Industry-specific forecast inputs include polyurethane foam raw material cost indices and Section 608 technician certification throughput rates affecting field commissioning capacity.
Underlying measurement precision varies by segment; supermarket procurement and national account chain specifications carry tighter precision than independent restaurant spot purchases and rental market transactions. Forecasts reflect assumptions regarding EPA refrigerant transition timeline adherence and commodity metal price stability. Stakeholders should weight assumptions against their own operating context and regional contractor availability constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Fish Filleting Machine Market
Food Processing Equipment
De-Agglomerating Equipment Market
Food Processing Equipment
Edible Oil Extracting Machine Market
Food Processing Equipment
Europe Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Vacuum Cooling Equipment Market
Food Processing Equipment
Canning Machine Market
Food Processing Equipment
Defrosting & Thawing Equipment for Food Market
Food Processing Equipment
Global Food Dehydrators Market
Food Processing Equipment
Food Extruder Market
Food Processing Equipment
Food Processor Market
Food Processing Equipment
Pet Food Extrusion Market
Food Processing Equipment
Wine Processing Equipment Market
Food Processing Equipment
Crossflow Wine Filters Market
Food Processing Equipment
Spray Dryer Market
Food Processing Equipment
Global Non Thermal Processing Market
Food Processing Equipment
Food Slicer and Dicer Market