
 Granular Ice Machine Market | 2026-2036
Granular Ice Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Granular Ice Machine Market Insights
A shift from single-source procurement to multi-source supplier portfolios is hardening across the granular ice equipment sector. Manitowoc Ice leverages its manufacturing scale to dominate the institutional channel, while Hoshizaki sustains technology leadership in energy-efficient refrigeration architectures. Scotsman Ice Systems anchors its position through deep specialization in nugget and flake ice formats for healthcare and foodservice.
Granular ice machines produce soft, chewable ice particles through extrusion or compression of frozen water slurry, typically operating at evaporator temperatures between negative ten and negative twenty degrees Fahrenheit to achieve the characteristic porous texture; these units serve hospitals, quick-service restaurants, and convenience stores where ice consumption rates exceed fifty pounds per day. Undercounter configurations command the largest installed base due to space constraints in commercial kitchens, while modular systems represent the fastest-expanding category as chain operators standardize across locations. Air-cooled technology leads unit shipments for its lower water consumption, though water-cooled variants retain share in high-ambient-temperature environments where heat rejection efficiency determines operational viability.
The U.S. FDA Food Code classifies ice as a food, subjecting equipment to sanitation standards enforced by state health departments and OSHA workplace safety protocols for ammonia-based industrial systems. The EPA's SNAP program restrictions on high-GWP refrigerants are accelerating R-290 and CO₂ system transitions among manufacturers. Stakeholders must monitor refrigerant phase-down schedules and emerging state-level efficiency mandates to align product roadmaps with compliance timelines.
Market Dynamics
The EPA's SNAP refrigerant phase-down is compressing equipment replacement cycles as operators accelerate R-290 and CO₂ system adoption ahead of compliance deadlines. This regulatory pressure is reshaping supplier portfolios and capital allocation across foodservice and healthcare channels.
Growth Catalysts
- Healthcare Hydration Protocols:Hospital systems are standardizing nugget ice for post-operative patient care and dysphagia management, driving specification requirements into new construction RFPs.
- FDA Food Code Enforcement:State health departments are tightening ice machine sanitation inspections, forcing equipment upgrades toward automated cleaning and antimicrobial materials.
- Southeastern U.S. Construction:Foodservice density and hospital expansion in Florida, Georgia, and Texas are concentrating demand above national baselines.
Market Restraints
- Copper and Aluminum Input Volatility:Evaporator coil manufacturing faces margin compression from commodity price swings in refrigeration-grade metals.
- Refrigerant Supply Concentration:R-290 and CO₂ system components depend on limited domestic compressor fabrication capacity, creating procurement bottlenecks.
- Water-Cooled System Limitations:High water usage rates restrict deployment in drought-prone municipalities with usage restrictions.
Strategic Opportunities
- Remote Monitoring Convergence:IoT sensor networks and predictive maintenance algorithms are enabling subscription-based service models for multi-location operators.
- Convenience Store Channel:Underserved rural and exurban locations present white space for compact undercounter configurations with high daily output.
- Energy Efficiency Incentives:Utility rebate programs for commercial refrigeration equipment are shortening payback periods for premium system upgrades.
Industry Challenges
- Refrigeration Technician Scarcity:Qualified service capacity for hydrocarbon and transcritical CO₂ systems lags behind equipment deployment rates.
- Legacy System Integration:Modular upgrades in existing kitchens face spatial constraints and electrical infrastructure incompatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Granular Ice Machine Market |
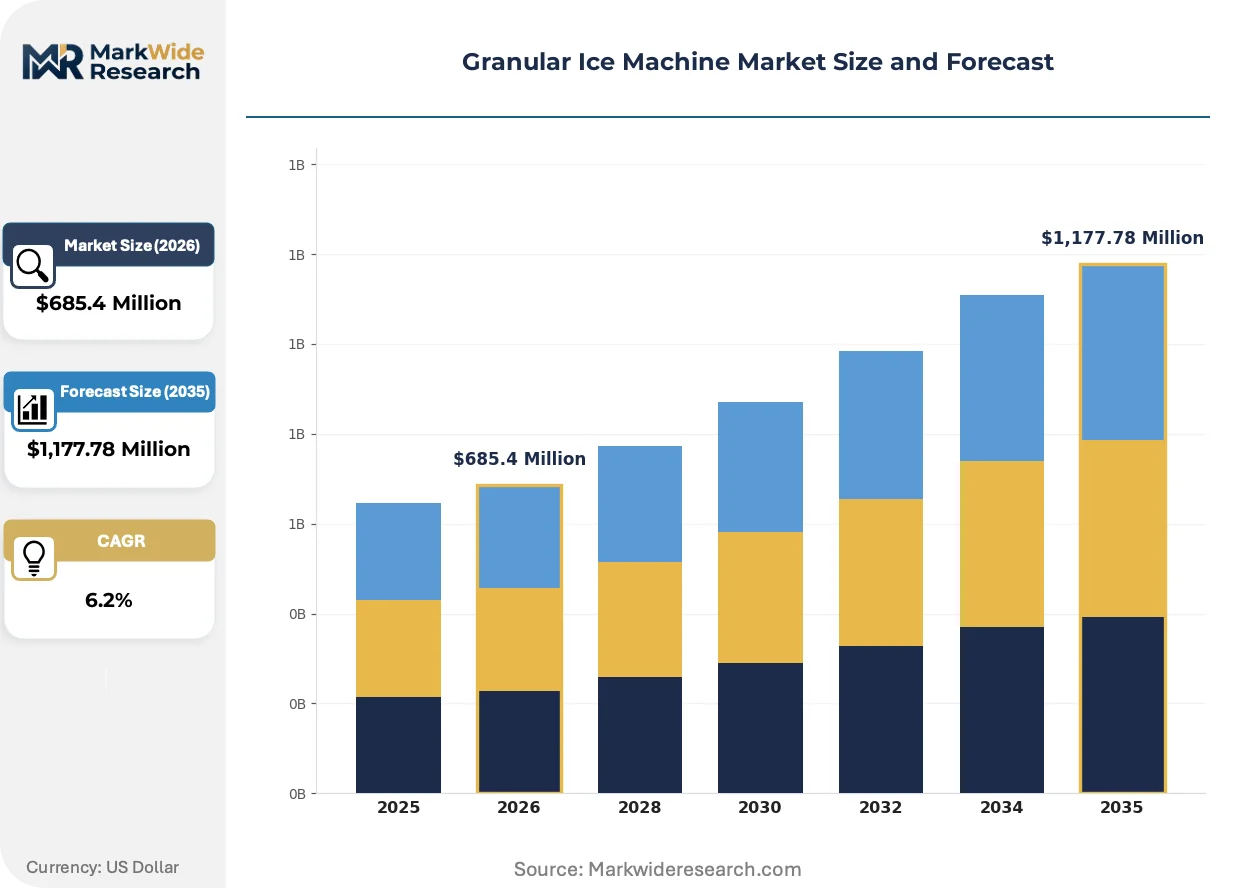
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Ice Machines, Portable Ice Machines, Undercounter Ice Machines, Countertop Ice Machines End User: Restaurants, Supermarkets, Bars, Hospitals Technology: Air-Cooled, Water-Cooled, Ice Storage Bins, Hybrid Systems Installation: Standalone, Integrated, Built-In, Custom Solutions |
| Companies Covered | Follett Corporation, Brema Ice Makers, Manitowoc Ice, Maxx Ice, Berg Chilling Systems, Hoshizaki, Ice-O-Matic, Atosa USA, Scotsman Ice Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Granular Ice Machine Market Trends and Innovations
Equipment architecture is pivoting toward connected, refrigerant-transition-ready platforms that compress total cost of ownership through predictive capabilities and energy optimization. This shift is redistributing value capture between manufacturers and service providers.
Variable-speed compressor technology is integrating with smart defrost algorithms to reduce energy consumption by matching output to real-time demand patterns. Quick-service restaurant chains with 24-hour operations are deploying these systems at scale in new-build locations. The technology is integrating operational data streams into centralized facility management platforms, compressing the role of traditional service intermediaries.
The EPA's SNAP program restrictions on high-GWP hydrofluorocarbons are mandating refrigerant transitions across commercial refrigeration categories. Equipment manufacturers are reengineering system architectures around R-290 and transcritical CO₂ to maintain market access. Healthcare facilities in California and New York are experiencing the most accelerated compliance timelines due to state-level efficiency mandates layered atop federal requirements.
Multi-source supplier portfolios are displacing single-vendor relationships as operators seek to mitigate concentration risk and improve service response times. Large foodservice management companies are unbundling equipment procurement from maintenance contracts, creating direct relationships with regional distributors. This pattern is most visible in the southeastern United States, where rapid chain expansion is forcing procurement function centralization.
Granular Ice Machine Market Segmentation
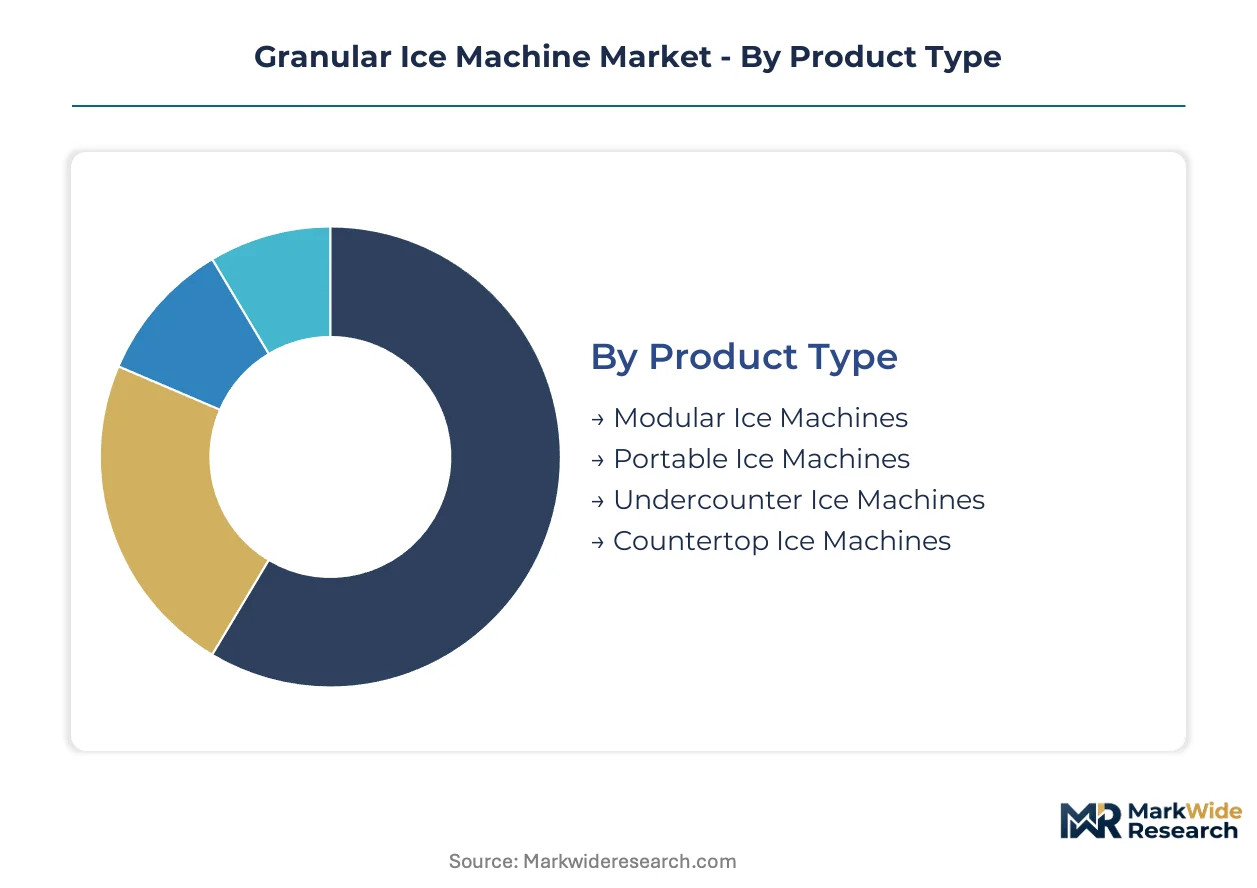
Granular ice equipment segmentation reflects divergent operational constraints across foodservice and healthcare channels. Equipment specifications vary sharply between high-volume centralized production and distributed point-of-use deployment. Understanding these divides clarifies procurement priorities for multi-location operators and facility managers.
Product Type:
Standalone units dominate remote and retrofit installations where kitchen infrastructure cannot accommodate complex refrigeration tie-ins. Embedded configurations require integration with building systems and centralized ice distribution networks.
- Modular Ice Machines:Stackable head units mount atop separate storage bins to scale output without floor space expansion. Chain operators in Texas and Florida deploy these in new-build locations to standardize across 50-plus unit footprints. The configuration supports 24-hour production cycles demanded by quick-service formats.
- Undercounter Ice Machines:Self-contained units slide beneath existing countertops to serve localized demand in compact kitchens. Hospital cafeterias and urgent care clinics in Georgia specify these for patient floor hydration stations where space constraints preclude remote ice rooms. The format sacrifices total output for proximity to consumption points.
- Portable Ice Machines:Mobile units on casters serve temporary foodservice operations and catering events. These units trade production capacity for deployment flexibility.
- Countertop Ice Machines:Compact dispensers integrate ice production and dispensing in single-footprint designs. Convenience stores and small-format bars favor these for front-of-counter placement.
Volume placements concentrate in undercounter configurations; the faster expansion belongs to modular systems.
End User:
Demand concentration varies by consumption intensity and regulatory exposure. Healthcare specifications prioritize antimicrobial materials and automated cleaning cycles. Foodservice operators emphasize output reliability and energy cost management.
- Restaurants:Full-service and quick-service formats drive the largest equipment procurement volumes. Nugget ice production rates exceeding 500 pounds per day characterize high-traffic locations in metropolitan Atlanta and Houston. Operators specify air-cooled systems to minimize water utility charges.
- Hospitals:Post-operative hydration protocols and dysphagia management requirements are embedding nugget ice specifications into new construction RFPs. The FDA Food Code classification of ice as food subjects hospital installations to enhanced sanitation inspections. Facilities in California and New York face accelerated compliance timelines from state-level mandates.
- Supermarkets:Seafood and produce departments deploy flake and nugget ice for display cooling. These applications prioritize continuous production over storage capacity.
- Bars:Craft cocktail operations specify chewable ice formats for texture and dilution control. Volume requirements remain modest compared to foodservice peers.
Procurement volumes cluster in restaurant channels; healthcare is climbing the fastest as construction pipelines harden nugget ice specifications.
Technology:
Heat rejection method determines operational economics and geographic viability. Water-cooled systems face deployment constraints in drought-affected municipalities with usage restrictions.
- Air-Cooled:Condenser coils reject heat to ambient air, eliminating water consumption for cooling. The technology commands dominant unit shipments across the southeastern United States where water utility rates are climbing. EPA SNAP refrigerant phase-downs are accelerating R-290 compressor adoption in this category.
- Water-Cooled:Heat exchangers use circulating water for condenser cooling, improving efficiency in high-ambient-temperature environments. Deployment concentrates in coastal Texas and Florida where heat rejection efficiency determines operational viability. Drought restrictions in Arizona and California are compressing addressable market scope.
- Ice Storage Bins:Insulated reservoirs decouple production timing from consumption patterns. These components enable modular system architectures.
- Hybrid Systems:Dual-mode units switch between air and water cooling based on ambient conditions. The complexity premium limits adoption to flagship locations.
Current shipments favor air-cooled architectures; water-cooled variants retain share in specific climate zones despite regulatory headwinds.
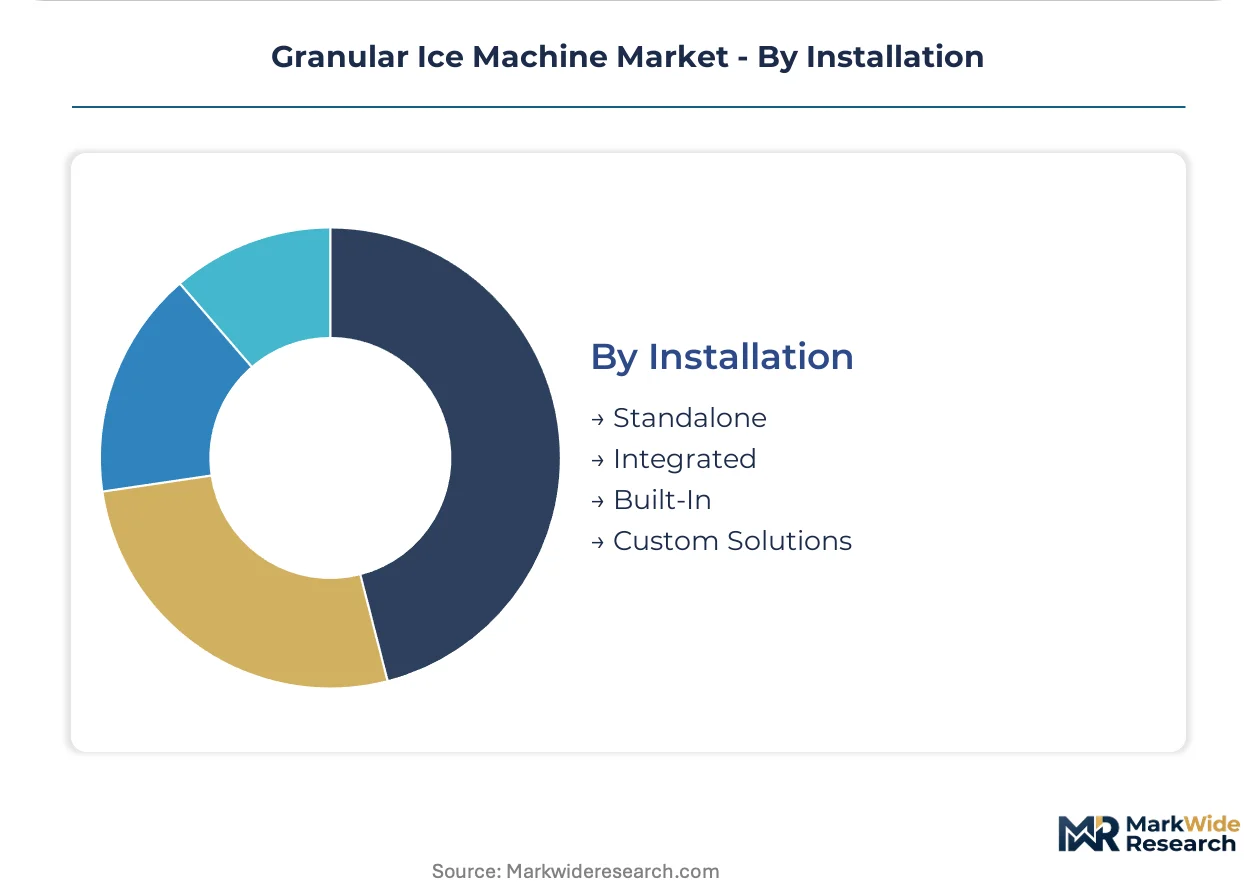
Installation:
Integration depth determines capital expenditure profiles and service contract structures. Custom configurations require specialized commissioning and extended warranty terms.
- Standalone:Self-sufficient units with independent power and drainage connections dominate retrofit markets. Foodservice operators in older urban buildings specify these to bypass infrastructure upgrade costs.
- Integrated:Units tie into building management systems for centralized monitoring and control. Healthcare systems deploying IoT sensor networks favor this architecture for predictive maintenance algorithms.
- Built-In:Flush-mounted designs conceal equipment behind cabinetry for front-of-house aesthetics. Hotel lobbies and premium bars specify these for visual integration.
- Custom Solutions:Engineered systems address atypical spatial constraints or production requirements. These engagements carry extended lead times and specialized service dependencies.
Standalone units capture the broadest installed base; integrated configurations are gaining share fastest as remote monitoring converges with facility management platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper and aluminum smelting capacity in the United States anchors the raw material foundation for evaporator coil fabrication, while refrigerant regulatory divergence across North America, Europe, and Asia-Pacific fragments equipment certification requirements.
United States
Hospital construction in Florida and Georgia is embedding nugget ice specifications into new facility RFPs. The FDA Food Code classification of ice as food subjects equipment to state health department sanitation inspections. Metropolitan Atlanta and Houston concentrate quick-service restaurant chain deployment of modular systems.
Germany
Industrial refrigeration engineering clusters in Bavaria and North Rhine-Westphalia supply compressor technology for transcritical CO₂ systems. The EU F-Gas Regulation mandates refrigerant phase-downs that accelerate R-290 and CO₂ transitions. Equipment fabricators in Baden-Württemberg specialize in energy-efficient architectures for export markets.
China
Commercial kitchen equipment manufacturing concentrates in Guangdong and Zhejiang provinces for cost-optimized export production. The country's national environmental regulator enforces dual carbon goals that compress industrial refrigeration energy intensity targets. Yangtze River Delta fabricators supply modular components for Southeast Asian foodservice expansion.
Japan
Precision refrigeration component manufacturing in Aichi and Osaka prefectures supplies variable-speed compressor technology. METI efficiency standards for commercial refrigeration equipment exceed baseline international requirements. Kanto region engineering groups integrate IoT sensor networks into predictive maintenance platforms.
India
Hospital infrastructure expansion in Maharashtra and Karnataka is creating specification demand for healthcare-grade ice equipment. BIS certification requirements for commercial refrigeration equipment are tightening import compliance barriers. Tamil Nadu manufacturing clusters are developing localized supply chains for hydrocarbon-compatible compressors.
Granular Ice Machine Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers reengineer system architectures around refrigerant transitions. The vendor base organizes into three tiers: multinational refrigeration conglomerates with institutional channel dominance, mid-scale specialists focused on healthcare and foodservice verticals, and regional fabricators serving price-sensitive replacement markets. Strategic archetypes include scale-driven procurement partners for chain operators, technology-led efficiency optimizers, and service-integrated solution providers. M&A activity and capacity expansion for R-290 and CO₂ component fabrication represent the dominant competitive vectors.
Within the multinational tier, Manitowoc Ice, Hoshizaki, and Scotsman Ice Systems occupy positions reflecting divergent strategic emphases. Manitowoc represents scale-driven manufacturing depth for institutional procurement. Hoshizaki exemplifies technology leadership in energy-efficient refrigeration architectures. Scotsman anchors specialization in nugget and flake ice formats for healthcare applications. These three entities collectively illustrate how competitive positioning fragments across manufacturing scale, technical differentiation, and vertical focus rather than converging on homogeneous capability sets.
| Leading Market Players |
|---|
| Follett Corporation |
| Brema Ice Makers |
| Manitowoc Ice |
| Maxx Ice |
| Berg Chilling Systems |
| Hoshizaki |
| Ice-O-Matic |
| Atosa USA |
| Scotsman Ice Systems |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap fabricators in Wisconsin and Ohio anchor the aftermarket replacement channel, their concentrated ownership structures enabling pricing discipline through direct customer relationships while limiting backward integration into compressor manufacturing.
Pricing Analysis
Warranty and service-bundling stratification separates premium OEM offerings from unbundled regional alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Cost compression in the economy tier is intensifying because copper and aluminum input volatility squeezes evaporator coil margins. Quick-service restaurant chains exhibit highest price sensitivity due to procurement centralization, while hospital systems prioritize antimicrobial certification over unit cost.
Supply Chain Analysis
UL and NSF certification gating restricts component sourcing to qualified domestic and German suppliers. Evaporator coil fabrication draws from copper smelting in Arizona and aluminum processing in Tennessee, while compressor manufacturing concentrates in Germany and Japan. Single-source vulnerability in R-290-compatible compressor supply creates procurement bottlenecks ahead of EPA SNAP deadlines. Distribution runs through manufacturer-authorized service dealers and regional foodservice equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a refrigerant-transition consolidation play, with EPA SNAP phase-down timelines forcing capital-constrained regional fabricators toward exit or acquisition.
For Market Incumbents: Anchor market position through captive supply of hydrocarbon-compatible compressors via joint ventures with German or Japanese engineering clusters. Defend against emerging IoT-enabled service disruptors by embedding predictive maintenance algorithms into standard warranty terms. Prioritize certification investment in California and New York to capture accelerated compliance timelines. For New Entrants and Emerging Players: Launch via direct relationships with convenience store chains in rural Texas and Georgia, bypassing established distributor networks. Target the underserved exurban quick-service segment with compact undercounter configurations featuring high daily output. Penetrate through utility rebate program partnerships that shorten customer payback periods. For Investors and Strategic Acquirers: Distressed-cycle entries favor R-290-ready fabrication assets in the southeastern United States, where hospital construction pipelines harden specification demand. Five-to-ten-year viability hinges on refrigerant transition execution rather than volume scale. Monitor EPA enforcement variance across state health departments as the inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Transition | R-290 and CO₂ system reengineering maintains EPA SNAP compliance and market access. |
| IoT Service Model Development | Predictive maintenance subscriptions capture recurring revenue from multi-location operators. |
| Healthcare Specification Embedding | Nugget ice protocols in hospital RFPs lock in long-term procurement relationships. |
| Regional Distribution Consolidation | Authorized service dealer networks compress response times in high-growth southeastern markets. |
| Utility Rebate Program Alignment | Energy efficiency certification unlocks incentive programs shortening customer payback periods. |
Research Methodology
Multi-period observation of refrigerant transition timelines, hospital construction permits, and foodservice chain expansion anchored the trend analysis, supplemented by interviews with equipment procurement directors at healthcare systems, aftermarket service technicians, regional distributor principals, and EPA regulatory affairs specialists. Secondary validation drew from FDA Food Code enforcement records, state health department inspection data, SNAP program rulings, and utility rebate program disclosures. Bottom-up unit shipment modeling triangulated against top-down equipment spending forecasts across foodservice and healthcare channels.
Input-output matrices mapped evaporator coil production capacity to end-use demand across installation types and cooling technologies. Segmentation dimensions spanned product configuration, end-user vertical, heat rejection method, and integration depth. CAGRs were derived from regression analysis of historical replacement cycles and regulatory compliance deadlines. Forecast inputs included commodity price indices for refrigeration-grade metals and state-level efficiency mandate adoption curves.
Refrigerant phase-down acceleration, copper price volatility spikes, and drought-driven water-cooled system restrictions are the dominant revision risks to installed base projections. Forecasts reflect assumptions regarding technician training pipeline development and compressor component availability. A model refresh is warranted upon material change in EPA enforcement posture or state-level efficiency mandate layering.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Insect Protein Processing Equipment Market
Food Processing Equipment
Tea Processing Equipment Market
Food Processing Equipment
Wine Processing Equipment Market
Food Processing Equipment
India Household Flour Milling Machines Market
Food Processing Equipment
Commercial Beverage Blender Market
Food Processing Equipment
Commercial Oven for Bakery Market
Food Processing Equipment
Tortilla Machine Market
Food Processing Equipment
Ribbon Blenders Market
Food Processing Equipment
Ice Cream Machine Market
Food Processing Equipment
Yogurt Makers Market
Food Processing Equipment
Continuous Fryer Machine Market
Food Processing Equipment
Clean in Place Market
Food Processing Equipment
Small Continuous Fryer Market
Food Processing Equipment
Industrial Food Slicers Market
Food Processing Equipment
Griddle Market
Food Processing Equipment
Pasta Machine Market