
 Magnetic Grill Market | 2026-2036
Magnetic Grill Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Grill Market Foresight
Multi-source procurement for rare-earth magnet assemblies is hardening across the magnetic grill supply chain as buyers hedge against neodymium price volatility and geopolitical concentration risks. MAGNET-SCHULTZ GmbH & Co. KG leverages its European manufacturing footprint to sustain just-in-time delivery contracts with German food equipment OEMs. TDK Corporation anchors its position through captive sintering capacity and long-term offtake agreements with Japanese rare-earth processors. Eriez Magnetics competes aggressively in North American bulk material handling, where its service network controls aftermarket replacement cycles.
A magnetic grill is a fixed or removable filtration device incorporating permanent magnet bars or grids arranged to capture ferrous contaminants from free-flowing powders, granules, and liquids in industrial processing lines; typical configurations employ rare-earth neodymium-iron-boron magnets generating surface field strengths from 8,000 to 12,000 gauss, with 304 or 316 stainless steel housings rated for sanitary washdown protocols. Stainless steel constructions dominate specification-driven food and pharmaceutical installations where corrosion resistance and cleanability are non-negotiable, while cast iron variants occupy cost-sensitive bulk mineral and recycling applications where abrasion tolerance outweighs hygiene priorities. Outdoor grills and portable grills represent the fastest-expanding product categories as mobile food service operators and remote mining camps adopt modular contamination control systems.
ISO 22000 food safety management frameworks and the FDA's Current Good Manufacturing Practice regulations shape design requirements for magnetic grills deployed in U.S. food processing, mandating documented validation of separation efficiency and traceable material certifications. ECHA's REACH restrictions on nickel migration and heavy metal leaching compel European manufacturers to certify housing alloys and surface coatings through notified body assessment. Stakeholders must monitor evolving rare-earth export licensing regimes and build magnet inventory buffers before supply rationing disrupts production schedules.
Market Dynamics
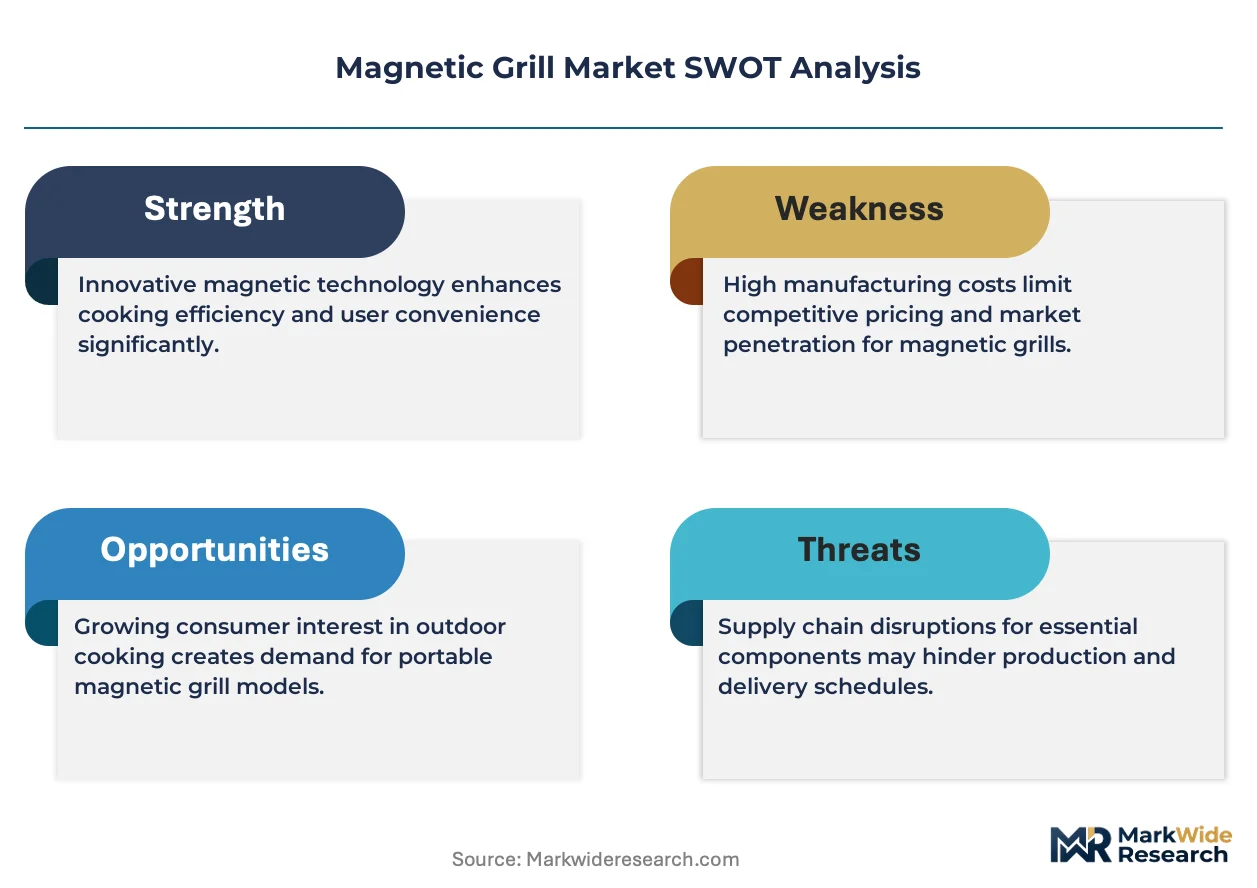
Rare-earth magnet supply concentration and volatile neodymium pricing are forcing food processors to reconfigure procurement strategies and inventory buffers across the magnetic grill value chain.
Growth Catalysts
- FDA Food Safety Modernization Act mandates:Documented validation requirements for ferrous contamination control are accelerating specification-grade magnetic grill deployments in U.S. dairy and meat processing facilities.
- German precision engineering clusters:Chemical processing hubs in Ludwigshafen and Leverkusen are driving demand for high-gauss neodymium-iron-boron systems with certified 316 stainless housings.
- Modular contamination control systems:Mobile food service operators and remote mining camps are adopting portable magnetic grill configurations for field-deployable quality assurance.
Market Restraints
- Neodymium price volatility:Rare-earth oxide spot market swings of 40-60% annually are compressing margin predictability for magnet assembly fabricators.
- Chinese rare-earth processing dominance:Over 85% of global separation and sintering capacity concentrates in Inner Mongolia and Jiangxi provinces, creating single-source vulnerability.
- REACH nickel migration limits:ECHA restrictions on housing alloy leaching are disqualifying lower-grade stainless formulations from European pharmaceutical installations.
Strategic Opportunities
- Indian food processing modernization:FSSAI enforcement of HACCP-aligned contamination protocols in Maharashtra and Gujarat is opening specification-grade procurement channels.
- Battery recycling feedstock recovery:Lithium-ion cell dismantling operations require magnetic separation for shredded copper-aluminum fractions, creating adjacent demand for high-field grill systems.
- EU Green Deal circular economy incentives:Capital subsidies for closed-loop material recovery systems are positioning magnetic grills as qualifying equipment in metals recycling grant applications.
Industry Challenges
- Rare-earth magnet inventory financing:Working capital requirements for 6-12 month neodymium stockpiles are straining mid-tier fabricator balance sheets.
- ISO 22000 audit documentation:Validation protocols for separation efficiency require third-party laboratory certification, extending sales cycles by 8-14 weeks in food sector tenders.
- Legacy pneumatic line integration:Retrofitting magnetic grills into existing bulk powder conveying systems demands custom flange engineering and downtime coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Grill Market |
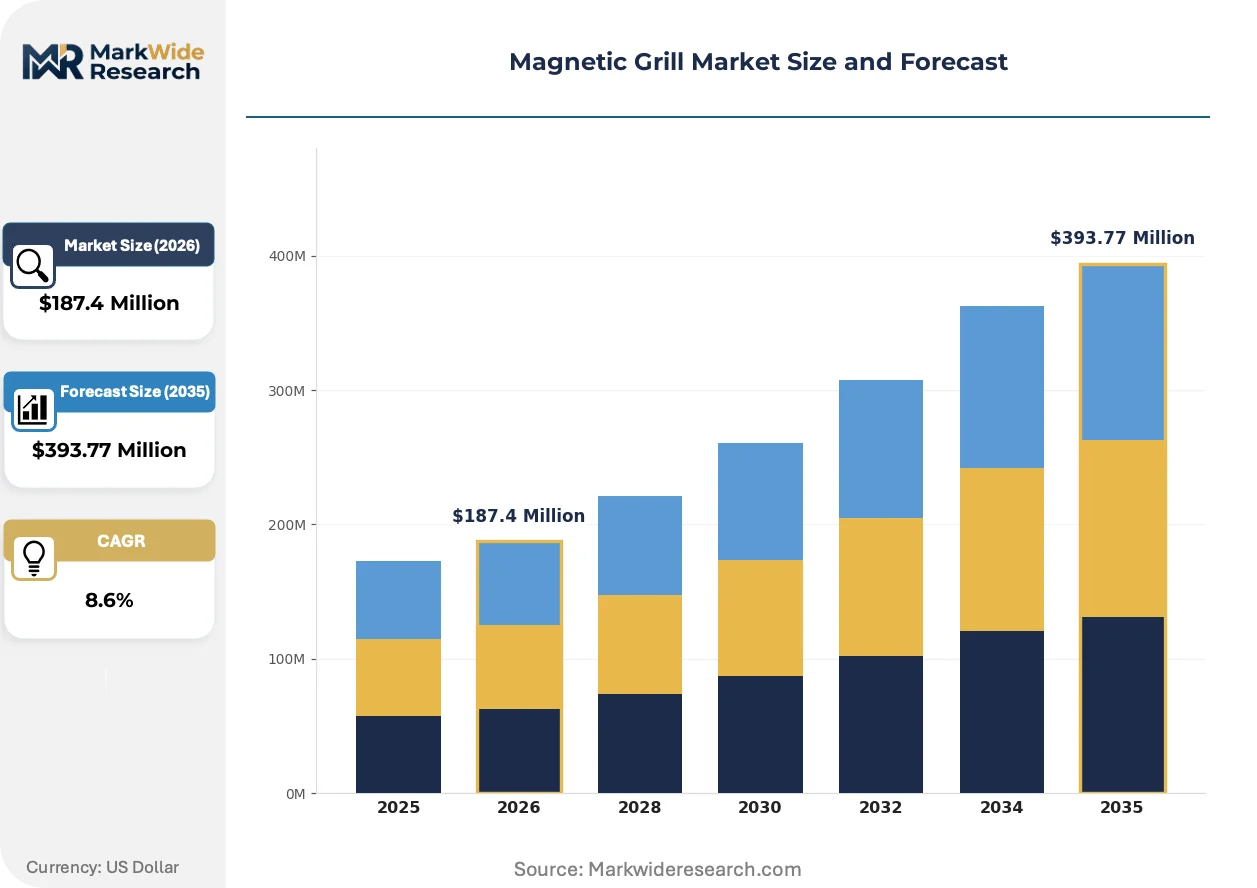
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Grills, Outdoor Grills, Portable Grills, Electric Grills Material: Stainless Steel, Cast Iron, Aluminum, Non-Stick Coating Use Case: Home Use, Commercial Use, Camping, Food Trucks Size: Small, Medium, Large, Extra Large |
| Companies Covered | MAGNET-SCHULTZ GmbH & Co. KG, Magnetic Solutions Pvt. Ltd., Permanent Magnets Limited, Weber-Stephen Products LLC, Traeger Grills, Shin-Etsu Chemical Co., Ltd., TDK Corporation, Eclipse Magnetics, Eriez Magnetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Grill Market Shifts & Advancements
Permanent magnet topology innovations and regulatory documentation requirements are compressing product lifecycles while opening service-based revenue models for equipment vendors.
Additive manufacturing of magnet assemblies is decentralizing production economics for low-volume, high-complexity grill configurations. Food equipment OEMs in Denmark and the Netherlands are adopting binder-jetted neodymium segments for rapid prototyping of custom grid geometries. Distributed manufacturing is compressing lead times from 14 weeks to 3 weeks for specialized pharmaceutical installations.
REACH SVHC candidate list expansions are tightening material traceability obligations across European supply chains. ECHA notification requirements for boron and cobalt compounds are forcing housing suppliers to requalify surface coatings through notified body assessment. German chemical processors are responding by mandating full material declaration certificates for all magnetic grill procurements above €50,000.
Buyer consolidation among multinational food processors is concentrating specification-setting power with centralized engineering teams. Category managers at Nestlé, Unilever, and Danone are unbundling equipment procurement from aftermarket service contracts, forcing vendors to compete on validation documentation and spare parts availability rather than upfront pricing. This shift is most visible in Benelux and Nordic markets where buyer concentration ratios exceed 70% in dairy processing.
Magnetic Grill Market Segmentation
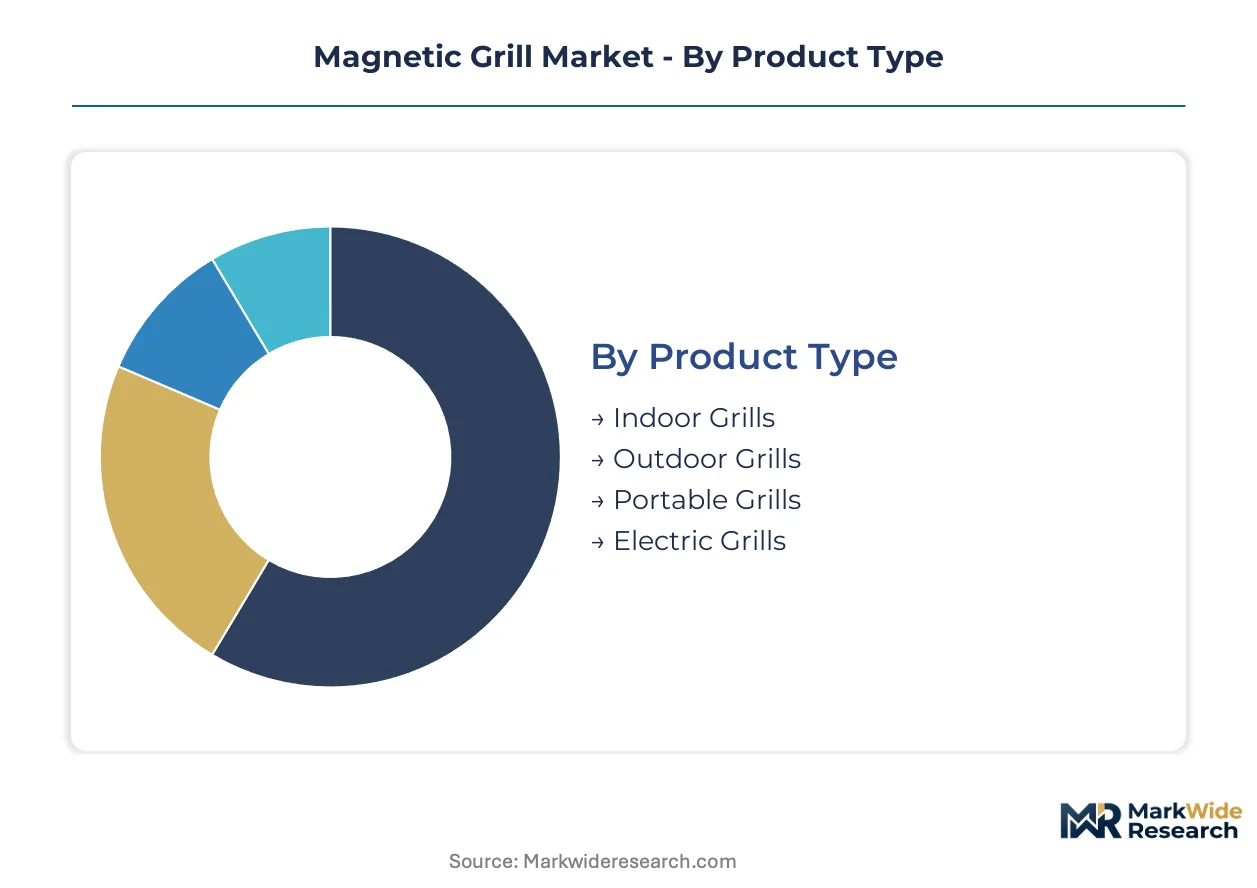
Magnetic grill procurement patterns diverge sharply across end-use environments, with food safety certification requirements and contamination risk profiles dictating specification intensity. Material selection and product configuration choices cascade directly into compliance obligations and total cost of ownership calculations for industrial buyers.
Product Type:
End-use mobility requirements and installation permanence separate buyers into distinct procurement workflows with diverging service expectations.
- Indoor Grills:Fixed installations in dairy processing facilities and pharmaceutical cleanrooms dominate specification-grade demand. FDA-validated separation efficiency documentation and 316 stainless steel housings are standard requirements in U.S. cheese processing plants.
- Outdoor Grills:Weather-resistant housings with IP65-rated enclosures serve mining camp bulk material handling and agricultural grain processing. Modular skids with forklift pockets enable rapid repositioning across remote extraction sites.
- Portable Grills:Mobile food service operators in Maharashtra and Gujarat deploy field-contamination control for street food HACCP compliance.
- Electric Grills:Electromagnetic variants with adjustable field strength suit battery recycling feedstock sorting operations.
Volume sits with Indoor Grills; growth tilts toward Portable Grills.
Material:
Corrosion tolerance and cleanability mandates stratify material selection between sanitary-process and abrasive-duty applications.
- Stainless Steel:304 and 316 grades capture pharmaceutical and dairy installations where REACH nickel migration limits and FDA washdown protocols apply. Full material declaration certificates are mandatory for European procurement above €50,000.
- Cast Iron:Abrasion-resistant housings dominate mineral processing and construction aggregate recycling where hygiene is secondary to mechanical durability. German chemical processors reject cast iron for any food-contact application.
- Aluminum:Lightweight frames suit airborne deployment in remote surveying and mobile exploration camps.
- Non-Stick Coating:PTFE and ceramic surface treatments reduce powder adhesion in pharmaceutical tablet coating operations.
Stainless Steel commands the revenue base; cast iron maintains cost-driven volume in bulk minerals.
Use Case:
Regulatory exposure and batch traceability requirements create tiered specification intensity across buyer categories.
- Home Use:Small-batch artisan food producers and farmstead operations require basic ferrous contamination control without validation documentation. Price sensitivity limits adoption to neodymium-iron-boron systems below 10,000 gauss.
- Commercial Use:Central kitchens and contract manufacturers face ISO 22000 audit requirements mandating third-party separation efficiency certification. Nestlé and Unilever category managers unbundle equipment from service contracts in Benelux tenders.
- Camping:Expeditionary mining and geological survey teams deploy collapsible magnetic grids for field assay preparation.
- Food Trucks:Mobile operators in Indian urban corridors adopt compact units for FSSAI-aligned contamination protocols.
Commercial Use anchors manufacturer margins; Food Trucks are expanding most quickly in emerging Asian markets.
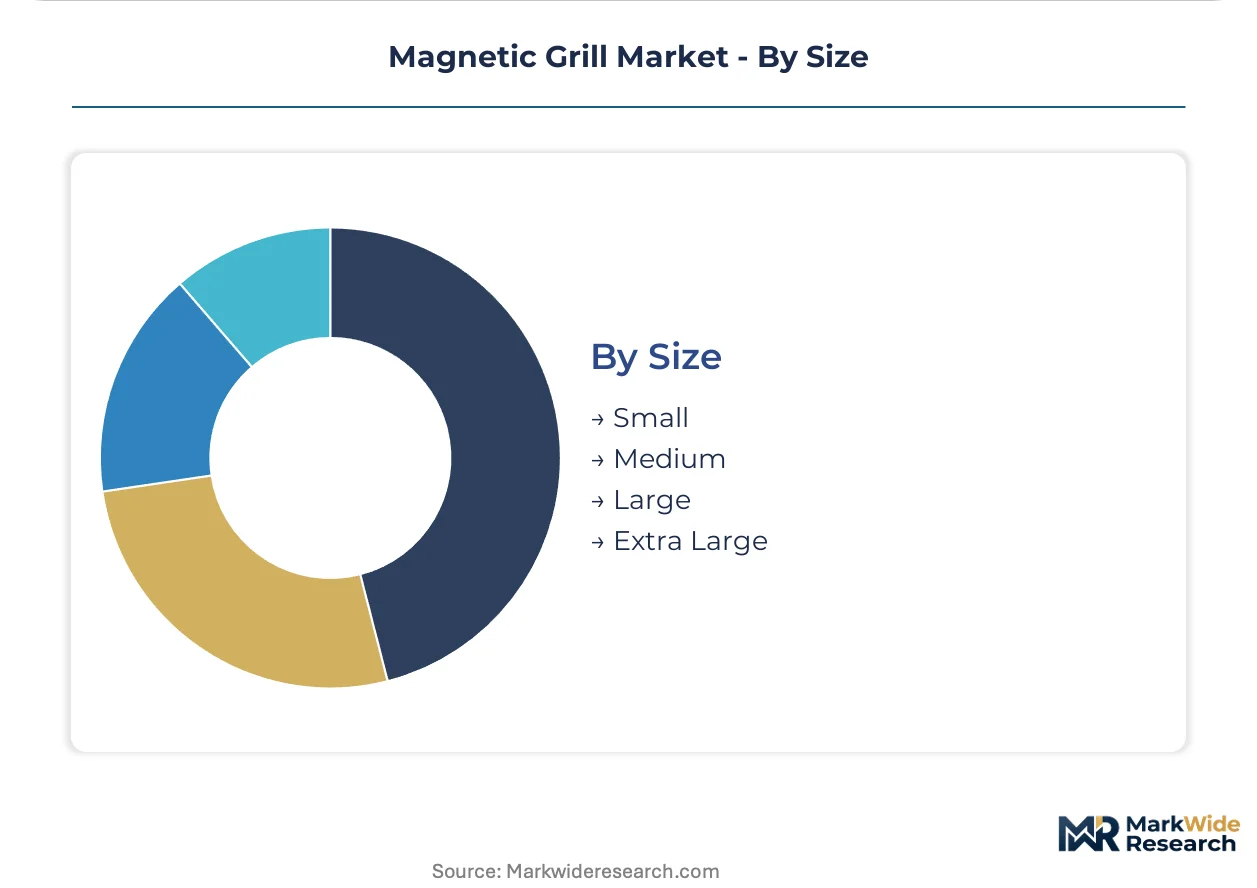
Size:
Throughput volume and line integration constraints determine dimensional procurement with direct implications for magnet assembly cost.
- Small:Benchtop units for R&D laboratories and pilot-scale food formulation. Binder-jetted neodymium segments from Danish additive manufacturing suppliers compress lead times to three weeks.
- Medium:Standard line widths in European dairy processing match pneumatic conveying diameters of 150-200mm.
- Large:Bulk grain elevators and port terminals require custom flange engineering for retrofit into existing pneumatic systems.
- Extra Large:Mining slurry processing and dredging operations demand sectionalized grids for crane-assisted maintenance access.
Medium sizes dominate unit shipments; Extra Large configurations carry the highest per-unit magnet content and pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Inner Mongolia and Jiangxi provinces in China host over 85% of global rare-earth separation capacity, yet specification-grade magnetic grill procurement concentrates in food processing clusters across Germany, the United States, and India.
United States
FDA Food Safety Modernization Act mandates accelerate specification-grade deployments in dairy and meat processing facilities. Third-party validation documentation for separation efficiency extends sales cycles by 8-14 weeks in federal tenders. Wisconsin and California cheese processing plants require 316 stainless steel housings with documented washdown protocol compliance.
Germany
Chemical processing hubs in Ludwigshafen and Leverkusen drive demand for high-gauss neodymium-iron-boron systems. ECHA REACH restrictions on nickel migration compel full material declaration certificates for procurements exceeding €50,000. Bavarian precision engineering clusters reject cast iron for any food-contact application.
India
FSSAI enforcement of HACCP-aligned contamination protocols in Maharashtra and Gujarat opens specification-grade procurement channels. Mobile food service operators in Mumbai and Ahmedabad deploy compact portable units for street food compliance. Central government PLI scheme incentives support domestic magnet assembly fabrication.
Japan
METI industrial standards shape high-performance magnet specifications for pharmaceutical cleanroom installations. TDK Corporation anchors supply security through captive sintering capacity and long-term offtake agreements with domestic rare-earth processors. Osaka-based food equipment OEMs prioritize just-in-time delivery contracts with validated documentation.
Netherlands
Buyer concentration ratios exceeding 70% in Benelux dairy processing unbundle equipment procurement from aftermarket service contracts. Unilever and Danone category managers mandate spare parts availability and validation documentation over upfront pricing. Rotterdam port terminals require custom flange engineering for retrofit into existing pneumatic conveying systems.
Magnetic Grill Market Competitive Landscape
Global majors compete with regional champions across magnet supply security and validation documentation capabilities. The vendor base stratifies into three tiers: integrated rare-earth processors with captive sintering, stainless steel fabricators with sanitary design expertise, and specialized magnetic assembly houses serving niche pharmaceutical installations. Dominant competitive moves include backward integration into magnet supply chains and geographic expansion through distributor partnerships in emerging food processing markets.
Among German precision engineering specialists, MAGNET-SCHULTZ GmbH & Co. KG exemplifies the European manufacturing footprint archetype, sustaining just-in-time delivery contracts through regional proximity to chemical processing clusters. TDK Corporation and Shin-Etsu Chemical Co., Ltd. occupy positions within the integrated rare-earth processor tier, leveraging captive upstream capacity to hedge against neodymium price volatility. Eriez Magnetics represents the North American service-network archetype, competing through aftermarket replacement cycle control in bulk material handling segments.
| Leading Market Players |
|---|
| MAGNET-SCHULTZ GmbH & Co. KG |
| Magnetic Solutions Pvt. Ltd. |
| Permanent Magnets Limited |
| Weber-Stephen Products LLC |
| Traeger Grills |
| Shin-Etsu Chemical Co., Ltd. |
| TDK Corporation |
| Eclipse Magnetics |
| Eriez Magnetics |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap fabricators across Bavaria and Baden-Württemberg anchor the European supply base, their conservative balance sheets limiting inventory financing capacity while reinforcing pricing discipline through just-in-time contracting with chemical processing OEMs. Their reliance on regional banking syndicates for working capital constrains magnet stockpiling depth, amplifying vulnerability to neodymium spot market swings and forcing selective customer prioritization during supply crunches.
Pricing Analysis
Warranty and validation documentation bundling separates premium tenders from commodity transactions, with ISO 22000-certified separation efficiency testing and spare parts availability guarantees commanding substantial premiums over bare-equipment pricing. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and housing alloy selection, with 316 stainless steel FDA-validated systems priced distinctly above 304-grade alternatives. Price differentiation stems from aftermarket service bundling and geographic delivery logistics, with remote mining camp deployments absorbing freight premiums. Cost compression in economy-tier cast iron configurations is intensifying because mineral processors prioritize abrasion tolerance over hygiene certification, squeezing margin predictability for non-sanitary fabricators.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for magnet assemblies, compelling multinational OEMs to qualify local fabrication partners in Maharashtra and Gujarat. Raw material flows draw from Chinese rare-earth separation capacity in Inner Mongolia and Jiangxi provinces, Japanese sintering operations, and German precision steel rolling mills for housing alloys. Single-source vulnerability concentrates in Chinese oxide processing, where export licensing volatility threatens magnet inventory security. Distribution runs through food equipment OEM channels in Benelux and Nordic dairy clusters, with direct sales dominating North American bulk material handling segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The magnetic grill sector is becoming a vertical-integration race as fabricators pursue captive magnet supply to hedge against Chinese rare-earth export restrictions and neodymium price volatility. Control over upstream sintering capacity or long-term offtake agreements now determines competitive sustainability.
For Market Incumbents: Anchor market position through backward integration into rare-earth magnet supply chains or binding offtake agreements with Japanese and Australian processors. Defend against emerging additive manufacturing disruptors by accelerating validation documentation capabilities and locking in multi-year service contracts with Nestlé and Unilever procurement teams. Prioritize certification investment for REACH SVHC compliance and FDA washdown protocol validation to maintain specification-grade eligibility in European and North American tenders. For New Entrants and Emerging Players: Begin with portable grill configurations for Indian mobile food service operators in Maharashtra and Gujarat, where FSSAI enforcement creates specification-grade demand without entrenched incumbent relationships. Target battery recycling feedstock recovery applications as the most penetrable adjacent segment, leveraging electromagnetic variant expertise from adjacent industrial magnet markets. Pursue additive manufacturing partnerships with Danish and Dutch equipment OEMs for rapid prototyping of custom grid geometries. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier stainless steel fabricators with sanitary design expertise in Germany and the Netherlands, where working capital constraints from magnet inventory financing are compressing valuations. Five-to-ten year viability hinges on securing non-Chinese rare-earth supply corridors through Australian or Vietnamese upstream assets. Watch Japanese METI industrial standard revisions as the critical inflection signal for pharmaceutical cleanroom specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Supply | Captive sintering capacity hedges TDK Corporation and Shin-Etsu against Chinese export licensing volatility. |
| Validation Documentation Investment | Third-party ISO 22000 certification extends Eriez Magnetics sales cycles but locks out unqualified competitors. |
| Additive Manufacturing Partnership | Binder-jetted neodymium segments from Danish suppliers compress MAGNET-SCHULTZ lead times from fourteen weeks to three. |
| Geographic Expansion in India | FSSAI enforcement in Maharashtra opens specification-grade procurement channels for domestic assembly fabricators. |
| Service Contract Unbundling | Nestlé and Unilever category managers in Benelux separate equipment from aftermarket, favoring spare parts availability. |
Research Methodology
Multi-period observation of neodymium spot pricing, REACH regulatory filing trajectories, and food processing equipment procurement patterns anchored the trend analysis, supplemented by interviews with plant engineers at dairy processing facilities, procurement leads at German chemical OEMs, aftermarket service heads at magnetic separation specialists, and regulatory affairs directors navigating FDA validation protocols. Secondary validation drew from ECHA SVHC candidate list publications, FDA Food Safety Modernization Act guidance documents, FSSAI enforcement circulars, and SEC filings from integrated magnet processors. Bottom-up fabrication capacity assessments triangulated against top-down food processing capital expenditure tracking.
Input-output matrices modeled magnet assembly cost structures against end-use pricing elasticity across product type, material grade, use case regulatory intensity, and dimensional throughput tiers. Segmentation dimensions included mobility configuration, housing alloy specification, compliance certification level, and installation scale category. CAGRs were derived from regression analysis of historical procurement volumes against regulatory implementation timelines and rare-earth supply availability indicators. Forecast inputs incorporated FSSAI enforcement progression in Indian states and EU Green Deal circular economy subsidy allocation patterns.
Underlying measurement precision varies by segment; specification-grade pharmaceutical and dairy installations carry tighter precision than cost-sensitive mineral processing deployments due to documented procurement transparency. Forecasts reflect assumptions regarding rare-earth export licensing stability and REACH nickel migration limit enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Vacuum Frying Machine Market
Food Processing Equipment
Deep Fryer Machine Market
Food Processing Equipment
Electric Kebab Machine Market
Food Processing Equipment
Griddle Market
Food Processing Equipment
Spray Dried Food Market
Food Processing Equipment
Destemmer Market
Food Processing Equipment
Soda Production Machine Market
Food Processing Equipment
Smart Food Machine Market
Food Processing Equipment
Blast Chillers Market
Food Processing Equipment
Commercial Winery Equipment Market
Food Processing Equipment
Ice Cream Processing Equipment Market
Food Processing Equipment
Portioning Machines Market
Food Processing Equipment
Small Brewery Equipment Market
Food Processing Equipment
Food Disinfection Equipment Market
Food Processing Equipment
India Household Flour Milling Machines Market
Food Processing Equipment
Commercial Tunnel Oven Market