
 Water Cooled Cube Ice Machines Market | 2026-2036
Water Cooled Cube Ice Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Water Cooled Cube Ice Machines Market Analytics
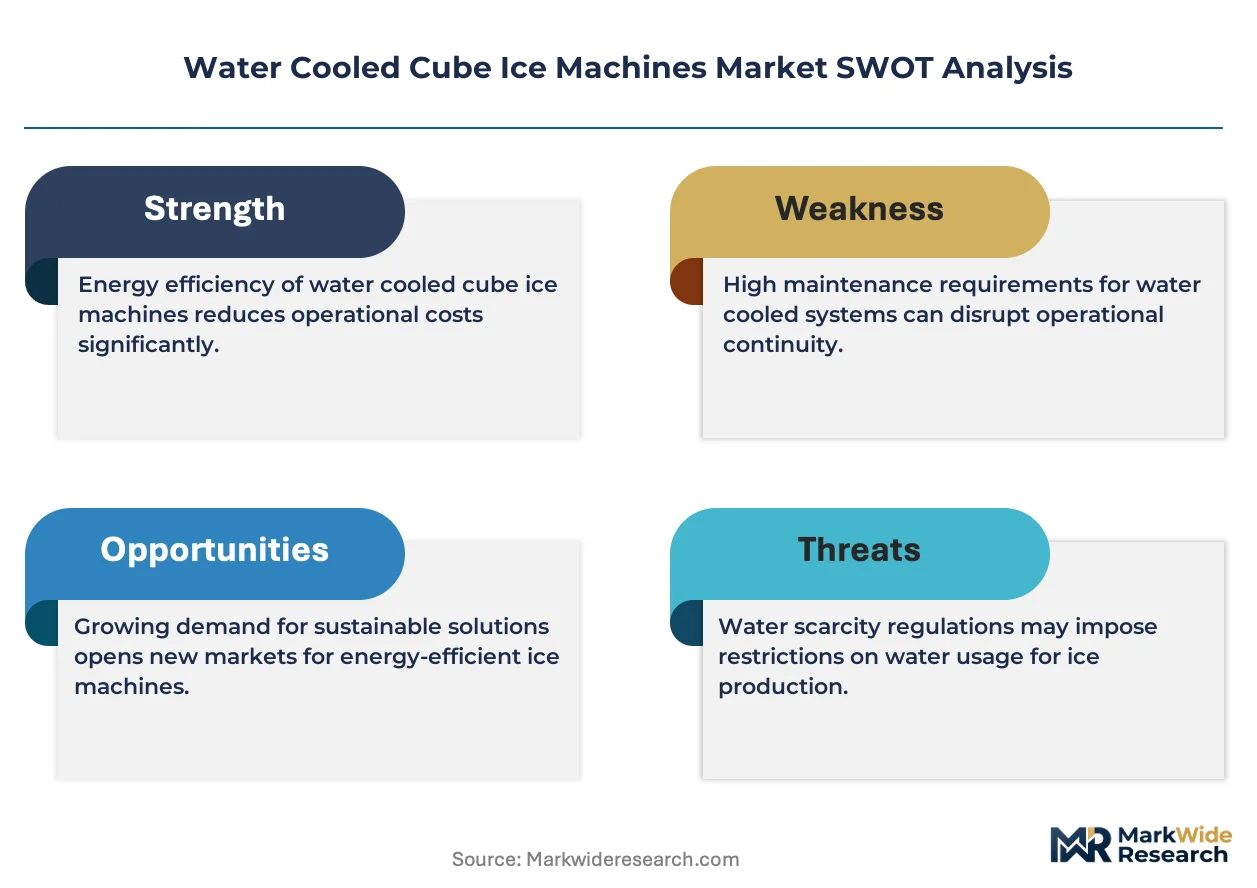
Equipment leasing and managed service contracts is fragmenting competitive dynamics by lowering capital barriers for independent restaurants and regional hospitality groups. Hoshizaki America leverages its distribution density across North American foodservice channels to sustain aftermarket revenue streams. Manitowoc Ice anchors its position through vertical control over compressor and condenser component supply. Scotsman Ice Systems differentiates via specialized ice shape engineering that commands premium placement in cocktail-forward bars.
Water cooled cube ice machines employ a closed-loop condensing system where water circulates across refrigerant coils, typically operating at ambient temperatures between 45°F and 100°F with production capacities ranging from 200 to 2,000 pounds per day. These systems discharge heat through a water line rather than ambient air, making them essential for high-output commercial kitchens with restricted ventilation or elevated ambient temperatures. Modular units lead the product type hierarchy by enabling scalable ice production that aligns with peak service periods in full-service restaurants. Undercounter configurations represent the fastest-growing format as bars and cafes prioritize spatial efficiency in dense urban locations. Large-capacity systems concentrate margin pools through extended service contracts and proprietary filtration attachments.
EPA ENERGY STAR specifications and DOE commercial refrigeration standards shape equipment efficiency mandates and testing protocols for water-cooled ice machine deployment across the United States. NSF International sanitation certification governs food-contact surfaces and bacterial control requirements that determine market access for domestic and imported units. OSHA workplace safety regulations influence installation specifications and maintenance access design. Stakeholders must monitor evolving refrigerant phase-down schedules and regional water-usage restrictions that will reshape condenser technology selection and geographic deployment priorities.
Market Dynamics
Equipment procurement patterns are fragmenting as full-service restaurants abandon capital ownership in favor of operational expenditure models, compressing traditional manufacturer margins while expanding recurring revenue pools for service-integrated suppliers.
Growth Catalysts
- EPA ENERGY STAR Phase 2:Tightened efficiency benchmarks are accelerating replacement cycles across existing installed bases in commercial kitchens.
- Full-service restaurant beverage program diversification:Specialty cocktail bars and craft beverage concepts are driving specification upgrades toward higher-output modular systems.
- Urban density constraints:Ventilation-restricted kitchen footprints in metropolitan United States locations are mandating water-cooled condensing configurations over air-cooled alternatives.
Market Restraints
- Copper and aluminum input volatility:Condenser coil material costs fluctuate with commodity markets, compressing margin stability for mid-tier equipment assemblers.
- Refrigerant phase-down schedules:EPA SNAP rules restricting hydrofluorocarbon blends are forcing premature R&D redirection before alternative chemistries achieve cost parity.
- Water infrastructure dependency:Municipal water quality variation and rising discharge fees in drought-prone United States regions are raising total cost of ownership calculations.
Strategic Opportunities
- Managed service contract penetration:Independent restaurants and regional hospitality groups represent underpenetrated accounts for subscription-based equipment and maintenance bundling.
- Filtration attachment monetization:Proprietary scale-inhibitor and antimicrobial cartridge systems create captive aftermarket revenue streams with recurring replacement intervals.
- Undercounter format expansion:Bars and cafes in dense urban United States markets are prioritizing spatial efficiency, opening specification windows for compact high-output configurations.
Industry Challenges
- EPA and DOE compliance timeline compression:Overlapping energy-efficiency and refrigerant transition mandates are straining engineering bandwidth and certification testing capacity.
- Integration complexity with legacy ventilation:Retrofit installations in existing commercial kitchens require custom plumbing configurations that extend deployment timelines and raise installation labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Cooled Cube Ice Machines Market |
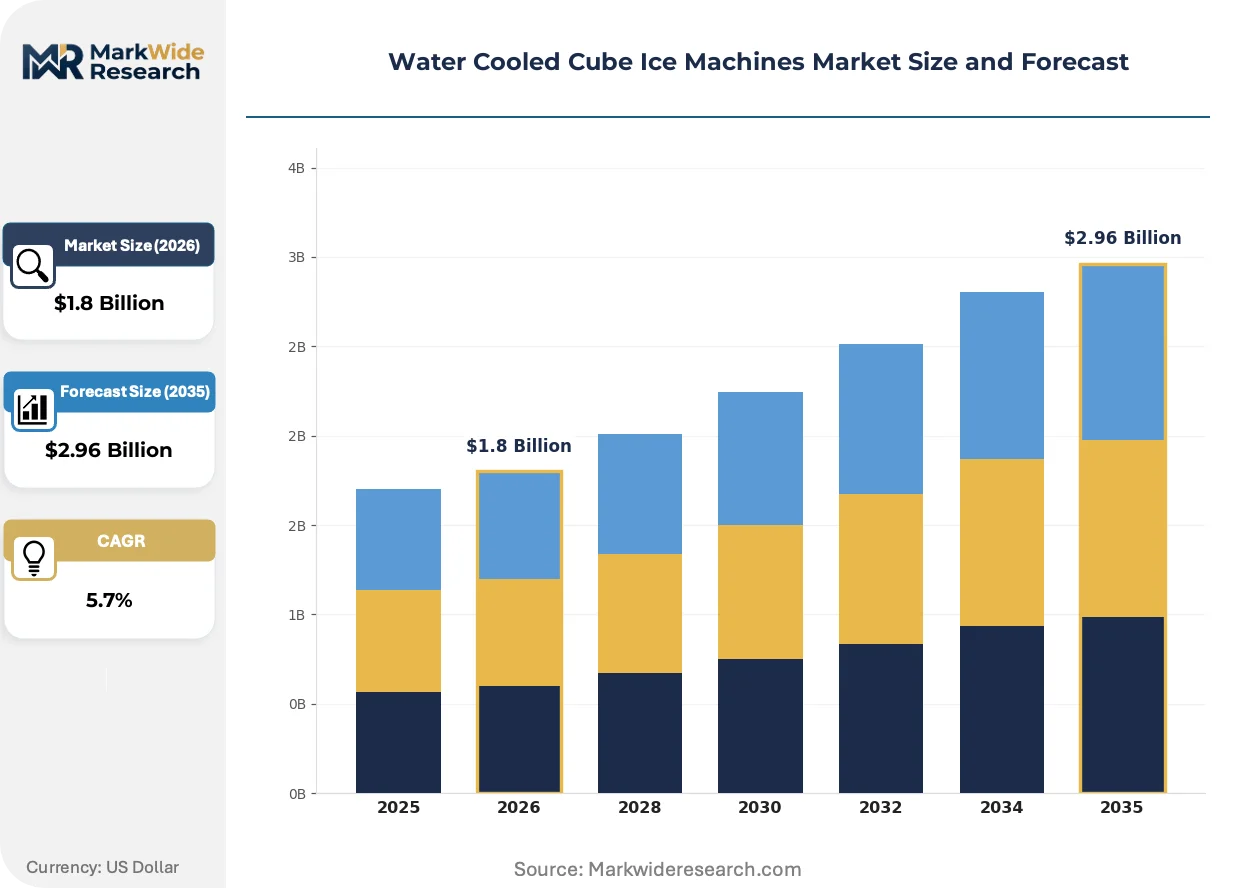
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular, Undercounter, Floor Standing, Ice Maker End User: Restaurants, Bars, Cafes, Hotels Technology: Air-Cooled, Water-Cooled, Direct-Cooling, Blast Freezing Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Ice-O-Matic, Grant Ice Systems, Hoshizaki America, Brema Ice Makers, Kold-Draft, Manitowoc Ice, Koller, Follett Ice, Scotsman Ice Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Cooled Cube Ice Machines Market Evolving Landscape
Remote monitoring architectures are virtualizing service relationships between equipment suppliers and commercial kitchen operators, compressing response times while generating predictive maintenance data streams that reshape competitive differentiation.
Cloud-connected ice machine controllers are virtualizing traditional break-fix service models. Full-service restaurant chains with multi-unit footprints are deploying these systems fastest, prioritizing uptime guarantees over capital cost minimization. This connectivity layer is virtualizing aftermarket revenue from parts replacement toward subscription-based performance contracts.
EPA refrigerant management regulations under Section 608 are tightening leak detection and repair documentation requirements. Equipment manufacturers must now integrate automated refrigerant monitoring sensors to maintain market access. The commercial refrigeration sector is responding by embedding compliance-grade telemetry as standard rather than optional configuration.
Leasing structures are displacing outright purchase for independent restaurants and regional hospitality groups. Equipment financiers and manufacturer captive finance arms are capturing margin pools previously held by traditional distributors. This shift concentrates most visibly in the United States, where commercial kitchen renovation rates and capital constraint pressures run highest among developed economies.
Water Cooled Cube Ice Machines Market Segmentation
Water cooled cube ice machines segment across equipment format, user environment, condensing technology, and output scale. Each dimension shapes procurement priorities, installation constraints, and total cost of ownership calculations for commercial kitchen operators.
Product Type:
Mature formats dominate installed bases while emerging configurations capture specification windows in renovation cycles.
- Modular:Stackable head units mount on separate storage bins, enabling output scaling from 500 to over 2,000 pounds daily. Full-service restaurants in the United States specify these for peak-period flexibility, though they require dedicated water line infrastructure and floor space allocation.
- Undercounter:Self-contained units integrate production and storage in compact footprints under 40 inches height. Bars and cafes in dense urban United States markets prioritize these for spatial efficiency, with demand climbing fastest in Manhattan, Chicago, and Los Angeles hospitality clusters.
- Floor Standing:High-capacity integrated systems serve institutional foodservice and large hotel banquet operations with continuous ice requirements.
- Ice Maker:Dispenser-integrated configurations target healthcare and quick-service environments requiring sanitary, hands-free ice delivery.
Modular handles the majority of throughput; Undercounter is expanding most quickly on share.
End User:
Customer type segmentation traces capital constraint severity and operational intensity across foodservice subsectors.
- Restaurants:Full-service establishments drive specification complexity with diversified beverage programs requiring multiple ice shapes and peak-output reliability. Leasing penetration runs highest here as independent operators avoid capital deployment.
- Bars:Cocktail-forward concepts command premium ice engineering—clear cubes, slow-melt spheres, and custom shapes—creating specification windows for specialized equipment at price premiums.
- Cafes:Limited-service beverage concepts prioritize undercounter formats with moderate daily output, typically 200-400 pounds.
- Hotels:Property-wide ice demand spanning restaurants, bars, room service, and guest floor dispensers favors centralized modular systems with distribution infrastructure.
Restaurants absorb the largest equipment volume; Bars generate the steepest specification premium trajectory.
Technology:
Condensing method selection hinges on ambient temperature, ventilation access, and local water cost structures.
- Air-Cooled:Ambient heat rejection suits well-ventilated kitchens with moderate climate exposure and lower water costs.
- Water-Cooled:Closed-loop water circulation across refrigerant coils operates reliably from 45°F to 100°F ambient, essential for high-output kitchens with restricted ventilation or elevated temperatures. This configuration commands specification priority in southwestern United States markets with extreme summer conditions.
- Direct-Cooling:Refrigerant-to-water heat exchange variants reduce water consumption versus traditional water-cooled designs.
- Blast Freezing:Rapid temperature reduction systems serve specialized applications requiring immediate ice hardening for transport or presentation.
Water-Cooled dominates high-reliability installations; Direct-Cooling is gaining specification traction in drought-prone jurisdictions.
Capacity:
Output tier selection aligns with peak demand periods, storage buffer requirements, and equipment redundancy strategy.
- Small:Sub-200 pound daily output serves limited-volume cafes and office breakrooms with intermittent demand.
- Medium:200-500 pound range captures independent restaurants and mid-size bars with predictable service patterns.
- Large:500-1,000 pound systems anchor multi-concept foodservice operations and hotel central production facilities.
- Extra Large:Exceeding 1,000 pounds daily, these units concentrate in stadium concessions, cruise ships, and institutional catering with extreme peak loads.
Large capacity handles the majority of revenue concentration; Extra Large is climbing the fastest on specification priority in new construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA ENERGY STAR Phase 2 specifications are accelerating equipment replacement cycles across commercial kitchen operators, concentrating procurement momentum in developed markets with stringent efficiency mandates and established foodservice infrastructure.
United States
Full-service restaurant renovation rates exceed other developed economies, with Manhattan, Chicago, and Los Angeles hospitality clusters driving undercounter format demand. EPA and DOE commercial refrigeration standards enforce testing protocols that reshape condenser technology selection. Southwestern markets including Phoenix and Las Vegas specify water-cooled configurations to manage extreme summer ambient temperatures.
Germany
Hotel and institutional foodservice operators prioritize modular systems for property-wide ice distribution infrastructure. EU F-Gas Regulation and REACH compliance frameworks constrain refrigerant chemistry options and condenser material specifications. Industrial equipment fabricators in North Rhine-Westphalia and Bavaria concentrate production of high-efficiency compressor assemblies for export markets.
Japan
Compact urban kitchen footprints in Tokyo and Osaka metropolitan areas favor space-optimized equipment formats with integrated storage. METI energy-efficiency labeling programs and JIS standards govern commercial refrigeration equipment certification. Nagoya-based industrial clusters supply precision-engineered heat exchange components to domestic and regional equipment assemblers.
United Kingdom
Cocktail-forward bar concepts in London and Manchester command premium ice shape engineering and specialized equipment specifications. CE marking and post-Brexit UKCA conformity requirements structure market access for imported and domestic units. Scotland's hospitality sector drives specification demand for high-output systems serving whisky tourism and event catering operations.
Canada
Healthcare and institutional foodservice operators specify dispenser-integrated configurations for sanitary ice delivery requirements. Health Canada and PMRA regulations intersect with provincial energy efficiency programs to shape procurement criteria. Ontario and Quebec commercial kitchen renovation activity concentrates equipment demand in Toronto and Montreal foodservice corridors.
Water Cooled Cube Ice Machines Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: integrated component manufacturers with captive compressor supply, specialized ice engineering firms commanding cocktail-bar premiums, and regional assemblers competing on lease-financing flexibility. Dominant competitive moves include backward integration into condenser coil production and the expansion of managed service contract portfolios to capture recurring revenue pools.
Among North American equipment suppliers, Hoshizaki America and Manitowoc Ice occupy positions as scale-driven integrators, while Scotsman Ice Systems exemplifies the specialized engineering archetype focused on premium placement. These three anchors represent distinct competitive vectors: distribution density, vertical control over critical components, and product differentiation through ice shape technology.
| Leading Market Players |
|---|
| Ice-O-Matic |
| Grant Ice Systems |
| Hoshizaki America |
| Brema Ice Makers |
| Kold-Draft |
| Manitowoc Ice |
| Koller |
| Follett Ice |
| Scotsman Ice Systems |
| Others |
Value Network & Pricing Analysis
Copper and aluminum commodity volatility cascades through condenser coil manufacturing costs, compressing margin stability for mid-tier assemblers while widening price spreads between NSF-certified premium units and uncertified economy alternatives. This input-cost uncertainty forces buyers toward longer-term service contracts that bundle equipment with predictable maintenance expenditure.
Pricing Analysis
Certification level creates the primary spread between equipment tiers, with EPA ENERGY STAR-qualified and NSF International-sanitized units commanding placement premiums in full-service restaurant chains. Three-tier pricing structure across premium, standard, and economy levels reflects filtration attachment bundling and remote monitoring integration. Cost compression in mid-tier configurations is intensifying because independent restaurants prioritize operational expenditure models over capital deployment. Quick-service operators exhibit highest price sensitivity, while cocktail-forward bars absorb premium positioning for specialized ice shape engineering.
Supply Chain Analysis
Export-control restrictions on advanced compressor technologies from Japan and Germany constrain component flows to regional assemblers in Southeast Asia and Latin America. Manufacturing concentrates in the United States, China, and Italy, with condenser coil fabrication drawing from copper smelters in Chile and aluminum processors in Russia. Single-source vulnerability runs through Japanese precision heat exchange component suppliers serving Nagoya-based industrial clusters. Distribution runs through foodservice equipment distributors with captive installation and aftermarket service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering bandwidth scarcity for simultaneous EPA refrigerant transition and DOE efficiency compliance creates competitive moats for manufacturers with dedicated R&D infrastructure and certification testing capacity.
For Market Incumbents: Insulate aftermarket revenue streams by expanding proprietary filtration cartridge systems with recurring replacement intervals. Backward integration into condenser coil production hedges copper and aluminum input volatility. Managed service contract portfolios should target independent restaurant accounts where leasing penetration remains below chain-level saturation. For New Entrants and Emerging Players: Regional hospitality groups in secondary United States metropolitan markets represent the most penetrable entry point for subscription-based equipment bundling. Undercounter format specialization for urban bar and cafe renovation cycles offers specification windows against entrenched modular-system incumbents. Channel partnership with foodservice equipment financiers accelerates customer acquisition without direct capital deployment. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors vertically integrated manufacturers with captive compressor supply and established EPA certification pathways. Long-term viability hinges on refrigerant chemistry flexibility and IoT-enabled service architecture. Acquisition targets should demonstrate installed base density for recurring revenue conversion. The signal to watch is EPA SNAP rule acceleration forcing premature R&D redirection among non-compliant competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Condenser Coil Production | Hoshizaki America and Manitowoc Ice anchor margin control through captive supply of copper and aluminum heat exchange components. |
| Managed Service Contract Expansion | Equipment financiers capture recurring revenue pools previously held by traditional distributors in independent restaurant accounts. |
| Remote Monitoring Platform Deployment | Cloud-connected controllers virtualize break-fix service models toward subscription-based performance guarantees for multi-unit chains. |
| Proprietary Filtration Attachment Development | Scale-inhibitor and antimicrobial cartridge systems create captive aftermarket revenue with predictable replacement intervals. |
| Undercounter Format Capacity Addition | Compact high-output configurations address spatial efficiency priorities in Manhattan, Chicago, and Los Angeles hospitality clusters. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA ENERGY STAR certification databases, NSF International sanitation standards documentation, and DOE commercial refrigeration test protocols. Interviews with foodservice equipment distributors, commercial kitchen maintenance directors, and restaurant procurement managers informed demand-side validation. SEC filings from publicly traded equipment manufacturers, customs trade data on compressor and condenser component flows, and industry association shipment statistics provided supply-side triangulation. Bottom-up equipment unit analysis and top-down foodservice infrastructure spending estimates were cross-referenced.
Forecast inputs include equipment format segmentation by modular, undercounter, and floor-standing configurations; condensing technology selection across water-cooled, air-cooled, and direct-cooling variants; and end-user categorization by restaurant, bar, cafe, and hotel operators. CAGRs were derived from replacement cycle acceleration under EPA Phase 2 efficiency benchmarks and renovation rate differentials across United States metropolitan markets. Water infrastructure cost trajectories and refrigerant phase-down schedules were modeled as scenario variables.
Macroeconomic conditions sit as an overlay; deviation in commercial kitchen construction activity, copper futures pricing, or municipal water rate escalation would shift the trajectory. Forecasts reflect assumptions regarding regulatory timeline adherence and supply chain continuity for Japanese precision components. Material shifts in EPA refrigerant management enforcement or DOE testing protocol revision would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Food Waste Disposers Market
Food Processing Equipment
Global Meat Mixer Market
Food Processing Equipment
Freshwater Flake Ice Machine Market
Food Processing Equipment
Ice Cream Processing Equipment Market
Food Processing Equipment
Oceania Commercial Ice Machine Market
Food Processing Equipment
Hygienic Easy to Clean Food Processing Equipment Market
Food Processing Equipment
Global Food and Beverage Processing Equipment Market
Food Processing Equipment
Contact and Convective Dryers Market
Food Processing Equipment
Continuous Fryer Machine Market
Food Processing Equipment
Smart Meat Thermometer Market
Food Processing Equipment
Cereal Rolling Machine Market
Food Processing Equipment
Refrigerated Vending Machines Market
Food Processing Equipment
Craft Beer Saccharification Equipment Market
Food Processing Equipment
Global Commercial Refrigeration Market
Food Processing Equipment
Global Conveyor Oven Market
Food Processing Equipment
Food Sterilization Equipment Market