
 Global Carbonated Beverage Processing Equipment Market | 2026-2036
Global Carbonated Beverage Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carbonated Beverage Processing Equipment Market Analysis
REACH is recalibrating the cost-of-entry calculus for stainless steel sourcing and chemical compliance in European carbonation equipment manufacturing. Krones AG leverages vertical integration across filling and packaging lines to sustain margin control in premium system sales. GEA Group Aktiengesellschaft anchors its position through R&D intensity in heat exchange and filtration subsystems. SPX Flow Inc. competes on modular skid-mounted designs that reduce installation downtime for mid-scale beverage producers.
Carbonated beverage processing equipment encompasses carbonation injectors, precision filtration arrays, multi-component mixing skids, and plate heat exchangers operating at pressures between 3 and 6 bar to achieve consistent CO₂ dissolution in liquid matrices. These systems serve the industrial purpose of transforming still beverages into shelf-stable carbonated products at throughputs exceeding 60,000 bottles per hour in large-scale configurations. Carbonation equipment occupies the largest value pool as bottlers prioritize precision CO₂ control to reduce product variance and rework rates. Micro-bubble technology represents the fastest-expanding segment because it achieves faster dissolution with lower gas consumption than traditional sparging methods. Filtration systems remain mature with incremental innovation focused on membrane longevity rather than throughput breakthroughs.
The EPA enforces Clean Air Act standards that constrain refrigerant selection in glycol chilling circuits tied to carbonation cooling stages. EMA food-contact material approvals shape stainless steel grade specifications for equipment sold into European beverage plants. China's SAMR enforces GB standards for pressure vessel certification that determine market access for imported carbonation systems. Stakeholders must monitor how F-Gas phase-down timelines in Europe and parallel MEE enforcement in China will reshape chiller technology roadmaps and supplier qualification requirements.
Market Dynamics
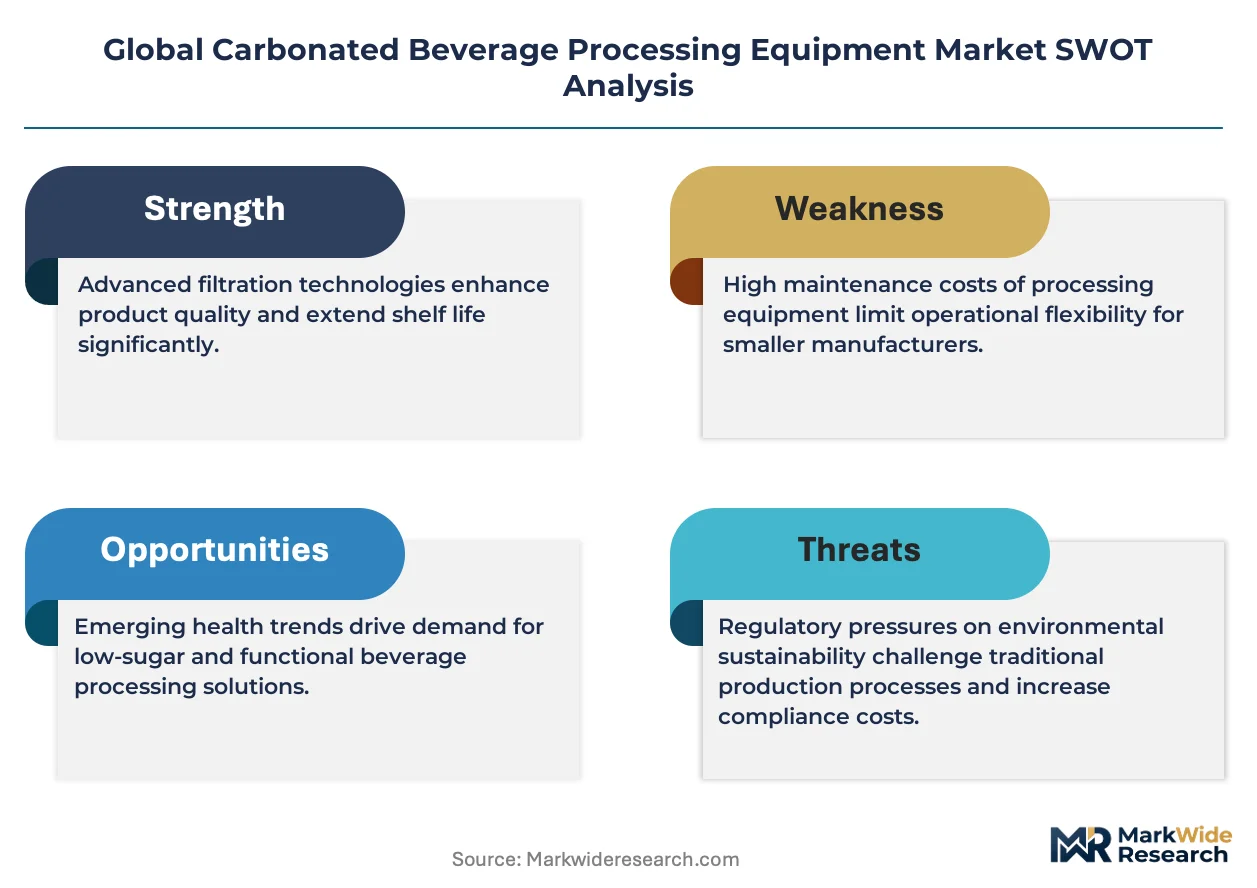
The EU F-Gas Regulation is compressing refrigerant options for glycol chilling circuits, forcing equipment suppliers to redesign carbonation cooling stages around low-GWP alternatives while maintaining thermal precision at 3-6 bar operating pressures.
Growth Catalysts
- Micro-bubble carbonation systems:Craft soda producers in Germany and the United States are retrofitting lines with micro-bubble injectors that achieve faster CO₂ dissolution rates and reduce gas consumption per liter versus traditional sparging methods.
- REACH compliance recalibration:Stainless steel grade specifications for European beverage plants now require enhanced chemical traceability, creating replacement demand for legacy equipment that cannot meet ECHA material documentation standards.
- Contract packaging expansion:Third-party bottlers are scaling automated carbonation lines to serve fragmented craft brands, generating equipment pull from mid-scale producers seeking flexible throughput configurations.
Market Restraints
- Specialized stainless steel supply concentration:Sourcing 316L and 304 grades with full REACH documentation chains faces bottlenecks from limited European mill capacity, extending procurement lead times for vessel fabrication.
- Pressure vessel certification complexity:China's SAMR enforces GB standards that require redundant testing protocols for imported carbonation systems, creating market access friction for non-domestic suppliers.
- Refrigerant transition costs:The F-Gas phase-down timeline compresses R&D budgets as engineering teams must validate alternative chiller chemistries without sacrificing cooling capacity at carbonation stages.
Strategic Opportunities
- Modular skid-mounted architectures:Mid-scale beverage producers in Brazil and Mexico are adopting containerized carbonation units that slash installation downtime and permit faster line reconfiguration for seasonal SKU shifts.
- EMA fast-track material approvals:Accelerated food-contact certification pathways for novel stainless steel surface treatments create first-mover advantages for suppliers with pre-validated coating technologies.
- Carbon capture integration:On-site CO₂ recovery systems that feed carbonation injectors are attracting sustainability-linked financing from bottlers facing Scope 3 emission disclosure requirements under CSRD.
Industry Challenges
- Cross-disciplinary engineering talent scarcity:Equipment manufacturers struggle to hire specialists who combine pressure vessel design expertise with refrigerant thermodynamics knowledge for integrated chiller-carbonator systems.
- Legacy control system integration:Brownfield beverage plants running proprietary SCADA architectures face protocol incompatibility when retrofitting modern carbonation skids with IoT-enabled pressure sensors.
- Dual certification timeline compression:Suppliers must simultaneously secure ASME and PED approvals for global product lines, stretching quality assurance resources across divergent documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carbonated Beverage Processing Equipment Market |
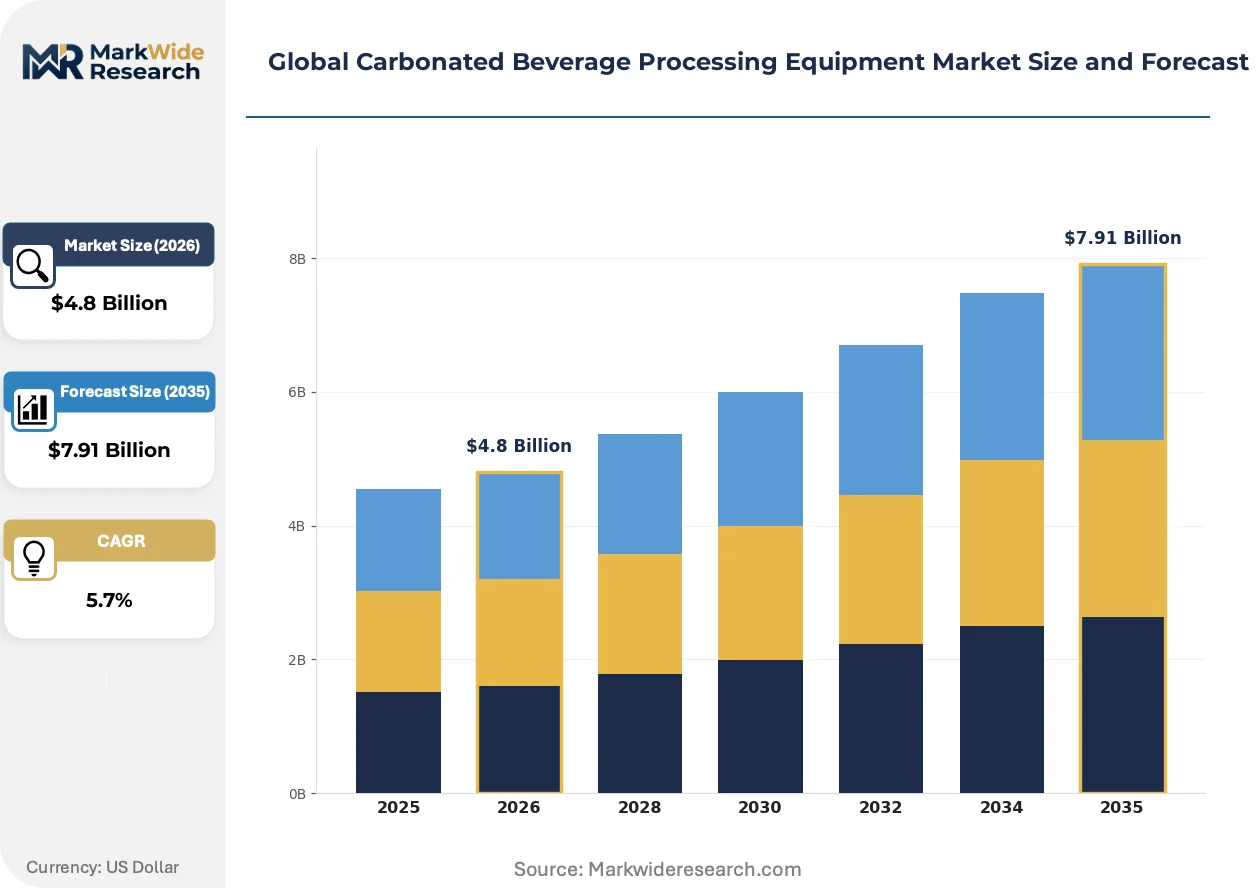
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonation Equipment, Filtration Systems, Mixing Units, Heat Exchangers End User: Beverage Manufacturers, Food Service Providers, Retail Outlets, Contract Packagers Technology: Traditional Carbonation, Micro-Bubble Technology, Counter Pressure, Insulated Storage Capacity: Small Scale, Medium Scale, Large Scale, High Capacity |
| Companies Covered | Krones AG, GEA Group Aktiengesellschaft, KHS GmbH, Tetra Laval, Alfa Laval AB, SPX Flow Inc., Sidel Group, Van Der Molen GmbH, A Due Di Squeri Donato & Cspa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carbonated Beverage Processing Equipment Market Emerging Trajectories
Digital pressure control architectures and membrane filtration advances are converging to reduce product variance in high-speed carbonation lines. Equipment suppliers are embedding predictive maintenance algorithms directly into injector skids.
Precision CO₂ mass flow controllers with real-time dissolved gas sensors are automating carbonation consistency across variable syrup formulations. Mid-scale contract packagers in Germany and the United States are deploying these systems at throughputs previously reserved for large-scale integrated bottlers. The technology is automating quality assurance staffing ratios while compressing batch-to-batch variance below 0.2 volumes CO₂.
REACH Annex XIV authorization requirements are recalibrating surface treatment chemistries for stainless steel vessels in European beverage plants. Chromium-free passivation layers now dominate new equipment specifications, displacing legacy hexavalent chromium processes. Suppliers with pre-certified alternative coatings capture preferential placement in EMA-regulated procurement tenders.
After-sales service unbundling is fragmenting traditional maintenance contracts into component-level subscription tiers. Craft soda producers in Brazil and India are purchasing carbonation injector refurbishment cycles separately from chiller service agreements, compressing total cost of ownership visibility. This pattern concentrates in markets where third-party technical labor pools reduce captive service team economics.
Global Carbonated Beverage Processing Equipment Market Segmentation
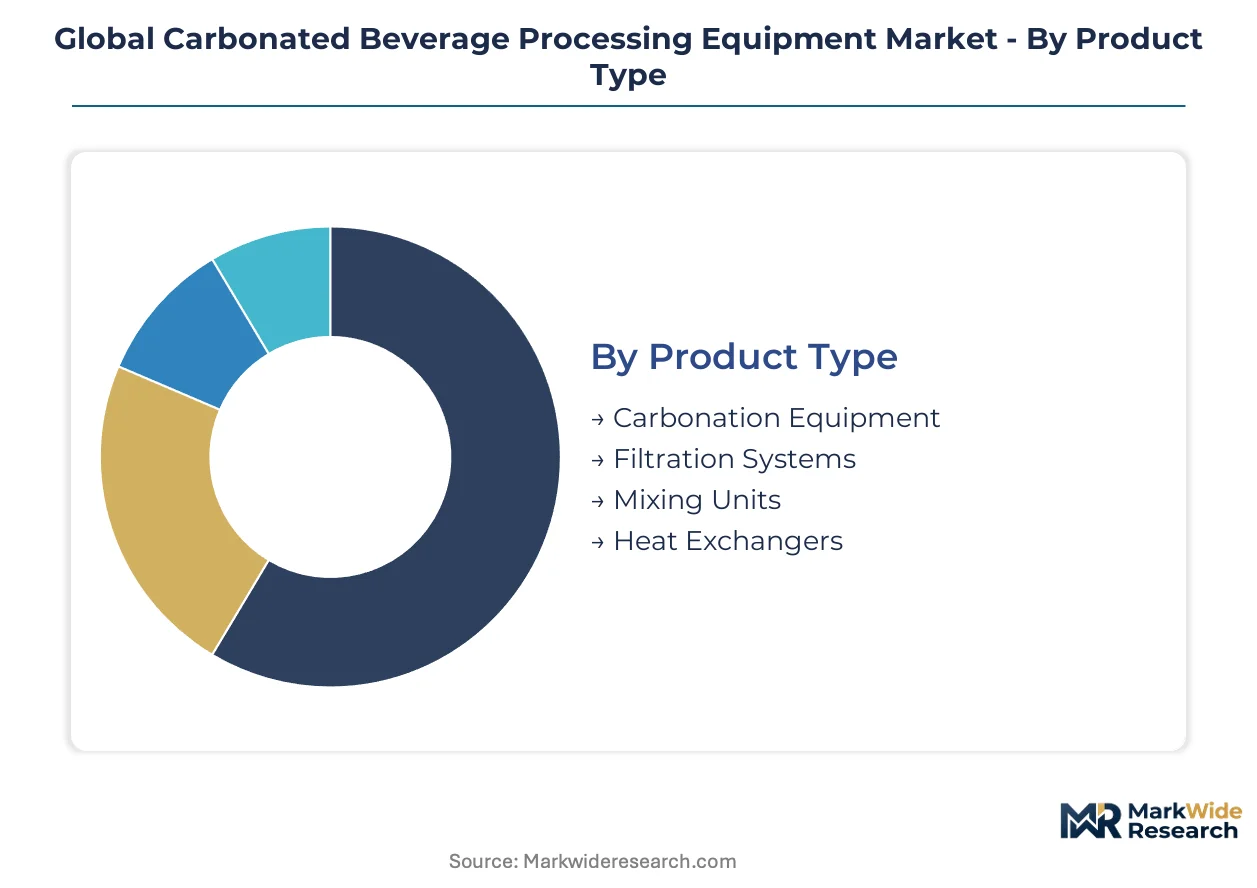
Segmentation in carbonated beverage processing equipment reveals how capital deployment varies by integration depth. Standalone carbonation skids command premium pricing against embedded filtration modules. Contract packagers in Germany and craft soda producers in Brazil select divergent configurations based on throughput flexibility requirements.
Product Type:
Standalone carbonation systems operate as discrete process islands while filtration and heat exchange modules embed into integrated lines. Integration depth determines maintenance access, upgrade pathways, and spare parts standardization.
- Carbonation Equipment:Precision CO₂ injectors operating at 3-6 bar pressure with real-time dissolved gas sensors. Demand concentrates among German contract packagers retrofitting lines for craft soda brands seeking batch-to-batch variance below 0.2 volumes CO₂.
- Filtration Systems:Membrane arrays and depth filtration skids removing particulates ahead of carbonation stages. European beverage plants facing REACH Annex XIV requirements drive replacement demand for vessels with chromium-free passivation layers.
- Mixing Units:Multi-component blending skids combining syrup, water, and additives prior to carbonation injection.
- Heat Exchangers:Plate and tubular designs cooling liquid matrices to optimal carbonation temperatures.
Volume placements concentrate in carbonation equipment; the faster expansion belongs to micro-bubble enabled injector systems.
End User:
Customer type shapes procurement scale, service contract structures, and financing arrangements. Large integrated bottlers negotiate multi-year equipment leases against spot purchases by fragmented craft operators.
- Beverage Manufacturers:Integrated bottlers operating owned production facilities with captive technical teams. Large-scale configurations exceeding 60,000 bottles per hour dominate capital allocation in this tier.
- Contract Packagers:Third-party bottlers serving multiple brand owners with flexible throughput configurations. Mid-scale automated lines in Brazil and Mexico adopt modular skid-mounted architectures permitting rapid seasonal reconfiguration.
- Food Service Providers:On-premise carbonation for fountain drink dispensing and bar operations.
- Retail Outlets:Store-based beverage production for private label carbonated drinks.
Procurement scale peaks with beverage manufacturers; contract packagers are climbing the fastest as craft brand fragmentation accelerates outsourcing.
Technology:
Technology selection trades dissolution efficiency against gas consumption and capital intensity. Traditional sparging methods face displacement pressure from precision micro-bubble architectures.
- Micro-Bubble Technology:Injectors producing sub-millimeter CO₂ bubbles achieving faster dissolution with lower gas consumption per liter. German and United States craft soda producers retrofit existing lines to reduce operating costs and environmental footprints.
- Traditional Carbonation:Conventional sparging methods using porous stone or nozzle-based gas injection. Legacy installations in mature markets face upgrade pressure from sustainability-linked financing requirements.
- Counter Pressure:Systems maintaining vessel pressure equilibrium during filling to preserve carbonation levels.
- Insulated Storage:Temperature-controlled holding tanks preserving dissolved CO₂ stability prior to packaging.
Installed base dominance sits with traditional carbonation; micro-bubble technology is gaining share fastest on efficiency metrics.
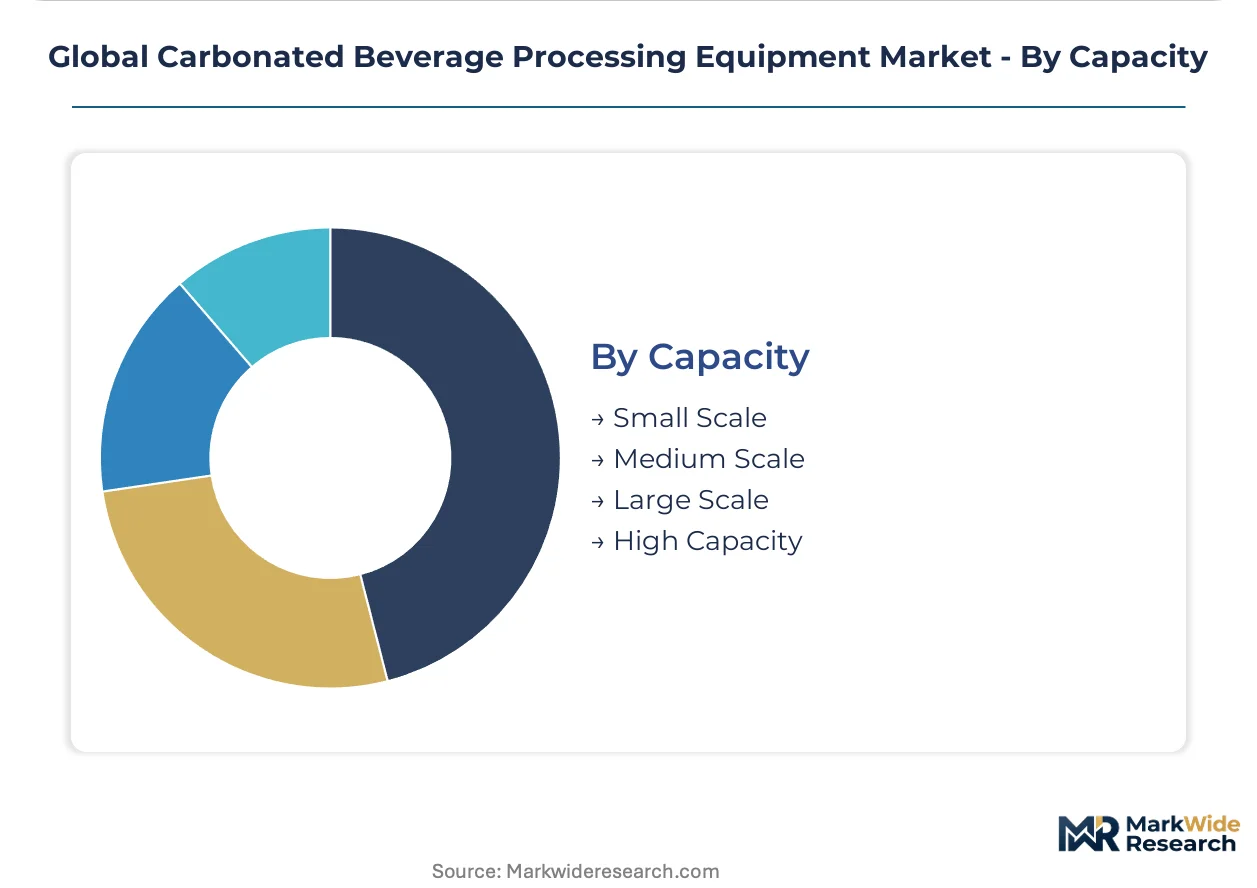
Capacity:
Scale tiers align with customer procurement power, technical staffing levels, and line utilization patterns. High-capacity lines amortize capital across volume while small-scale units prioritize flexibility.
- Large Scale:Configurations exceeding 60,000 bottles per hour with integrated quality control and predictive maintenance systems. Krones AG and KHS GmbH anchor precision-engineering clusters serving this tier from German manufacturing bases.
- Medium Scale:Throughput ranges serving regional bottlers and emerging market contract packagers. Containerized carbonation units in Brazil and Mexico slash installation downtime for mid-scale producers.
- Small Scale:Entry-level systems for craft startups and pilot production facilities.
- High Capacity:Maximum throughput configurations for multinational beverage conglomerates with dedicated engineering teams.
Revenue concentration favors large scale; medium scale shows the steepest expansion trajectory as contract packaging fragments demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bavaria and Baden-Württemberg concentrate precision-engineering clusters for high-speed filling systems. These tax-advantaged manufacturing corridors anchor European supply chains for carbonation equipment.
Germany
Contract packagers in Bavaria retrofit automated carbonation lines for craft soda brands. The EU F-Gas Regulation forces equipment redesigns around low-GWP refrigerants for glycol chilling circuits. Krones AG and KHS GmbH anchor precision-engineering clusters in Neutraubling and Dortmund serving throughput configurations exceeding 60,000 bottles per hour.
United States
Mid-scale craft soda producers in the Midwest adopt micro-bubble injector retrofits to reduce CO₂ consumption per liter. The EPA enforces Clean Air Act standards constraining refrigerant selection in carbonation cooling stages. Precision-engineering corridors in Wisconsin and Michigan concentrate stainless steel vessel fabrication serving regional bottlers.
China
Domestic beverage conglomerates in Guangdong and Zhejiang provinces scale automated carbonation lines for sparkling water brands. SAMR enforces GB standards for pressure vessel certification creating market access protocols for imported systems. Yangtze River Delta manufacturing bases produce modular skid-mounted units for Southeast Asian export markets.
Brazil
Contract packagers in São Paulo and Minas Gerais deploy containerized carbonation units permitting rapid seasonal line reconfiguration. ANVISA regulates food-contact material approvals for stainless steel surface treatments in beverage equipment. Mid-scale producers in the Southeast industrial corridor adopt subscription-tier maintenance contracts for carbonation injector refurbishment cycles.
India
Regional bottlers in Maharashtra and Gujarat install medium-scale automated lines serving fragmented soft-drink brands. BIS certification requirements for pressure equipment create qualification timelines for European and Asian suppliers. Pune-Ahmedabad manufacturing clusters assemble filtration skids and heat exchangers for domestic beverage plants.
Global Carbonated Beverage Processing Equipment Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment categories. The vendor base stratifies into three tiers: precision-engineering conglomerates with filling-to-packaging integration, subsystem specialists concentrating on heat exchange or filtration, and regional fabricators serving emerging market mid-scale producers. Strategic moves concentrate on modular architecture development and after-sales service unbundling into component-level subscription tiers.
Among German precision-engineering conglomerates, Krones AG exemplifies the integrated-systems archetype spanning carbonation through packaging lines. GEA Group Aktiengesellschaft occupies a position within the subsystem-specialist tier with concentration in heat exchange technologies. SPX Flow Inc. represents the modular-design archetype with containerized skid-mounted configurations reducing installation downtime for mid-scale producers.
| Leading Market Players |
|---|
| Krones AG |
| GEA Group Aktiengesellschaft |
| KHS GmbH |
| Tetra Laval |
| Alfa Laval AB |
| SPX Flow Inc. |
| Sidel Group |
| Van Der Molen GmbH |
| A Due Di Squeri Donato & Cspa |
| Others |
Supply Flow & Price Mechanics
REACH Annex XIV authorization requirements for chromium-free passivation layers are forcing European beverage plants to replace legacy stainless steel vessels, compelling mills to retool surface treatment lines and lifting input costs for equipment fabricators serving EMA-regulated procurement tenders.
Pricing Analysis
Short lead-time premiums now dominate carbonation equipment procurement as contract packagers in Germany and Brazil compress installation windows for seasonal SKU shifts. Three-tier pricing structure across premium, standard, and economy levels separates ASME-PED dual-certified systems from single-approval configurations and spot-market surplus units. Cost compression in mid-scale skid-mounted segments is intensifying because Brazilian and Mexican producers are consolidating purchases through third-party bottler cooperatives. Craft soda startups exhibit highest price sensitivity, while multinational beverage conglomerates prioritize certification grade over unit economics.
Supply Chain Analysis
China's GB standards for pressure vessel certification are reshaping sourcing patterns as domestic content mandates in SAMR enforcement push foreign suppliers toward joint-venture fabrication within Yangtze River Delta manufacturing bases. Stainless steel supply concentrates in Germany, China, and India, with 316L and 304 grade production feeding vessel fabrication clusters. Component sourcing draws from precision machining corridors in Bavaria, Guangdong stamping facilities, and Pune-Ahmedabad assembly hubs. Single-source vulnerability sits with European mill capacity for REACH-documented steel grades. Distribution runs through OEM direct sales for large-scale lines and regional distributor networks for containerized skid units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around subsystem specialists with pre-certified coating technologies, as dual ASME-PED approval timelines stretch quality assurance resources and force weaker fabricators toward exit.
For Market Incumbents: Acquire predictive maintenance algorithm portfolios to embed intelligence directly into carbonation injector skids before IoT-enabled pressure sensors become standard. Secure captive supply of chromium-free passivation capacity through backward integration into European surface treatment facilities, insulating margin control from REACH-driven input cost volatility. Defend against modular-design competitors by unbundling after-sales service into component-level subscription tiers that match SPX Flow's containerized architecture flexibility. For New Entrants and Emerging Players: Direct-to-contract-packager digital sales channels bypass incumbent field service networks and capture mid-scale producers in Brazil and Mexico seeking rapid seasonal reconfiguration. White-space concentration sits with micro-bubble retrofit kits for legacy sparging lines in United States craft soda facilities, where sustainability-linked financing favors gas-consumption reductions. Target penetration through EMA fast-track material approval pre-certification, accelerating procurement placement against established suppliers with documentation gaps. For Investors and Strategic Acquirers: Re-rating potential sits with heat exchange subsystem specialists given F-Gas phase-down timelines forcing chiller technology roadmaps toward low-GWP alternatives. Long-term viability favors pure-play filtration and heat exchange vendors with R&D intensity in thermal precision engineering, positioned for consolidation by integrated-systems conglomerates seeking to fill capability gaps. Watch for SAMR enforcement acceleration in China as the inflection signal determining which foreign suppliers secure domestic joint-venture partnerships versus market access exclusion.| Strategic Initiative | Industry Significance |
|---|---|
| Chromium-Free Passivation Pre-Certification | EMA fast-track approvals capture preferential placement in European beverage plant tenders. |
| Modular Skid-Mounted Architecture Expansion | Containerized units slash installation downtime for Brazilian contract packagers. |
| Predictive Maintenance Algorithm Integration | Embedded IoT sensors automate quality assurance staffing ratios in German retrofit lines. |
| Carbon Capture System Partnership | On-site CO₂ recovery attracts CSRD-linked sustainability financing from disclosure-facing bottlers. |
| Dual Certification Quality Assurance Investment | Simultaneous ASME-PED approval capacity stretches competitor resources and accelerates consolidation. |
Methodological Framework
Document review covered equipment specification databases, EMA food-contact material registries, and SAMR pressure vessel certification records, complemented by interviews with plant engineers at German contract packagers, procurement leads at Brazilian bottling cooperatives, and aftermarket service heads at filtration subsystem specialists. Secondary validation drew from SEC filings of listed processing equipment manufacturers, EU F-Gas Regulation implementation reports, and trade flow data for stainless steel grades. Bottom-up unit economics for carbonation skids were triangulated against top-down market sizing from integrated bottler capex disclosures.
Historical capacity utilization patterns at Krones AG and KHS GmbH manufacturing bases were cross-referenced against panel input from regional sales directors to anchor growth assumptions across the projection horizon. Segmentation modeling covered product type, end user archetype, technology selection, and capacity tier, with additional dimensioning by regulatory cluster. CAGRs were derived from slope analysis of installed base replacement cycles and craft brand fragmentation rates. Forecast inputs included F-Gas phase-down enforcement timelines and REACH Annex XIV authorization schedules.
The model holds under stable regulatory enforcement trajectories; deviation in SAMR certification acceleration or EU refrigerant substitution subsidies would shift equipment replacement timelines. Forecasts reflect assumptions regarding contract packaging outsourcing rates and stainless steel mill capacity expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Food Waste Shredder Market
Food Processing Equipment
Distillation Analyzer Market
Food Processing Equipment
Brewing Chiller Market
Food Processing Equipment
Sous Vide Cooking Appliances Market
Food Processing Equipment
Brewing Thermometer Market
Food Processing Equipment
Mill Mixer Market
Food Processing Equipment
Automatic Grilling Machine Market
Food Processing Equipment
Hand Blender Market
Food Processing Equipment
Global Fermenters Market
Food Processing Equipment
Pasta Machine Market
Food Processing Equipment
Deaeration Machine Market
Food Processing Equipment
Commercial Oven for Bakery Market
Food Processing Equipment
Philippines Cold Storage Warehouse Market
Food Processing Equipment
Fish Processing Equipment Market
Food Processing Equipment
Bread Maker Market
Food Processing Equipment
Bottled Water Processing Equipment Market