
 Nut Processing Machine Market | 2026-2036
Nut Processing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Nut Processing Machine Market Analytics
Aftermarket service revenue is fragmenting across original equipment manufacturers and third-party maintenance providers in the nut processing sector. Bühler Group leverages its global parts network to capture recurring service contracts from large-scale almond processors. TOMRA Systems differentiates through optical sorting technology leadership that sustains premium pricing on refurbishment and upgrade cycles. JBT Corporation competes by extending its roasting equipment lifecycle services into shelling and grinding line integrations.
Nut processing machines encompass mechanical systems designed to clean, shell, roast, grind, and sort tree nuts and peanuts with throughput rates ranging from 500 kg to 50 tonnes per hour depending on configuration. These systems serve commercial operations by converting raw in-shell nuts into finished food ingredients or packaged snack products while maintaining flavor profiles and reducing foreign material contamination. Sorting machines anchor the highest-margin segment due to optical and AI-driven foreign-object detection capabilities that processors prioritize over commodity shelling equipment. Steam roasting technology leads application growth among snack producers seeking reduced acrylamide formation compared to conventional thermal methods. Mechanical shelling occupies the most mature position with established supply chains for almonds and walnuts but faces displacement from hybrid automated systems.
FDA enforcement of FSMA preventive controls rules shapes equipment specifications by mandating hygienic design and validated kill-step documentation for roasting operations. USDA grading standards for almonds and pistachios directly influence sorting machine calibration requirements and export eligibility. Stakeholders must monitor how evolving FDA traceability rules for high-risk foods redirect capital toward integrated digital tracking systems rather than standalone mechanical upgrades.
Market Dynamics
Steam roasting technology is compressing capital allocation cycles as snack producers retrofit thermal processing lines to meet FDA acrylamide reduction mandates. Equipment replacement timelines have shortened from seven-year cycles to four-year intervals in California's Central Valley processing clusters.
Growth Catalysts
- FSMA Preventive Controls:FDA enforcement mandates validated kill-step documentation for roasting operations, forcing processors to upgrade to traceable automated systems with integrated digital logging capabilities.
- Clean-label snack demand:US snack producers are expanding automated processing lines to eliminate artificial preservatives, requiring optical sorting and precision roasting equipment that maintains flavor integrity without chemical additives.
- Almond processing cluster density:California's Central Valley concentration of almond and walnut operations drives equipment replacement cycles through shared technical labor pools and localized service infrastructure.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 stainless steel price swings compress fabrication margins for hygienic equipment manufacturers, particularly for roasting drum and conveyor fabricators.
- Optical sensor supply concentration:Near-infrared and hyperspectral imaging components concentrate among German and Japanese component suppliers, creating lead time vulnerability for sorting machine builders.
- Legacy shelling equipment saturation:Mechanical almond and walnut shelling systems face extended replacement timelines due to functional adequacy and sunk capital, slowing hybrid automated system penetration.
Strategic Opportunities
- Pistachio processing expansion:Iran and Turkey processing modernization creates demand for integrated shelling-sorting-roasting lines as these geographies seek export-grade equipment matching California standards.
- AI-driven predictive maintenance:Convergence of machine learning algorithms with vibration and thermal sensor networks enables shift from scheduled to condition-based service contracts, expanding aftermarket revenue pools.
- USDA export certification alignment:Grading standard harmonization for almonds and pistachios creates specification convergence, allowing equipment builders to design single-platform systems serving multiple export markets.
Industry Challenges
- Control systems integration:Legacy mechanical shelling lines require extensive PLC reprogramming and sensor retrofitting to interface with modern optical sorting and digital traceability modules, extending commissioning timelines.
- FSMA compliance documentation:Processors must maintain validated preventive control records spanning multi-year equipment lifecycles, creating administrative burden and audit preparation costs that strain mid-scale operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nut Processing Machine Market |
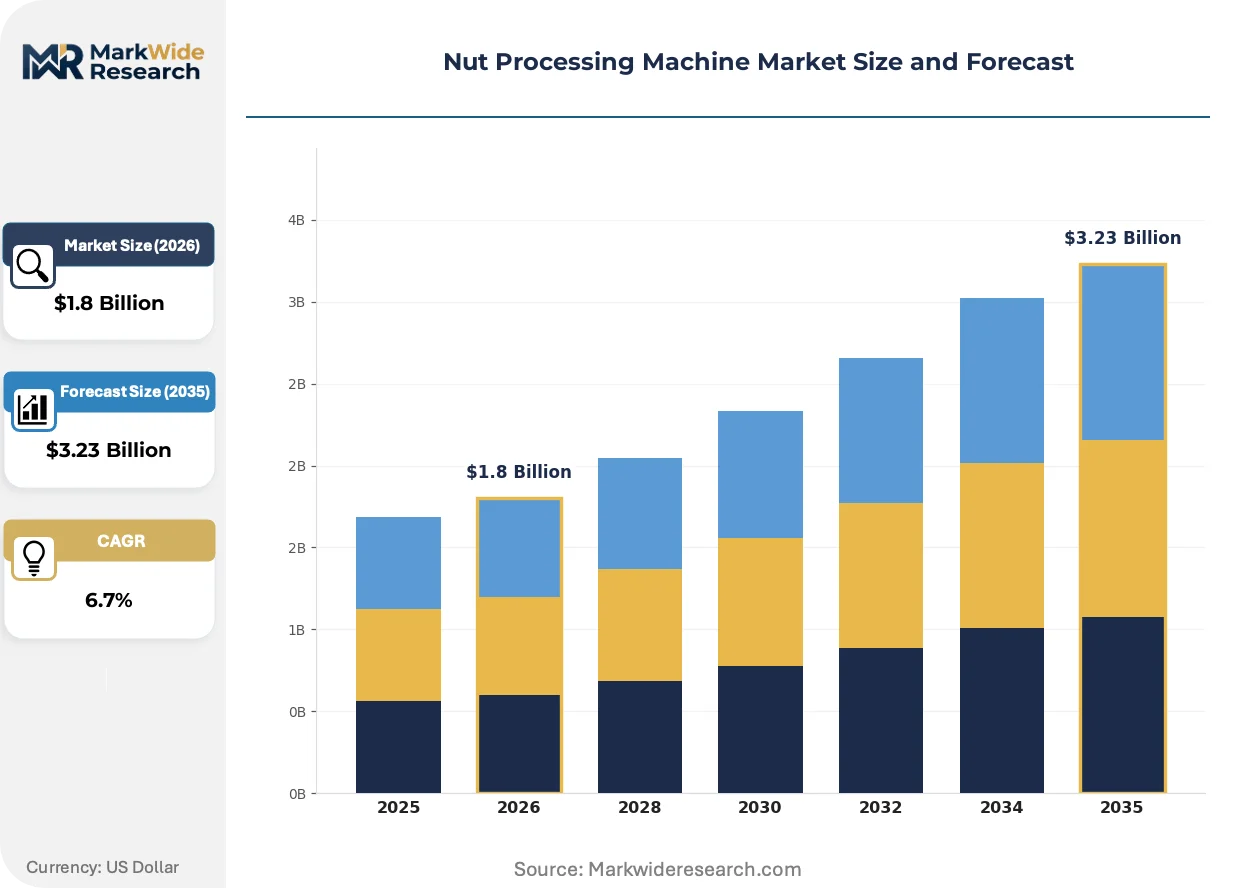
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shelling Machine, Roasting Machine, Grinding Machine, Sorting Machine End User: Food Manufacturers, Restaurants, Snack Producers, Nut Retailers Technology: Steam Roasting, Infrared Heating, Mechanical Shelling, Microwaving Application: Snack Food Production, Ingredient Processing, Bakery Applications, Confectionery |
| Companies Covered | Bühler Group, TOMRA Systems, JBT Corporation, The Middleby Corporation, Key Technology, Lewis M. Carter Manufacturing, Modern Process Equipment Corporation, AC Horn Manufacturing, Savage Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nut Processing Machine Market Evolving Landscape
Equipment architecture is fragmenting between integrated turnkey lines and modular component systems as processors balance capital flexibility against operational efficiency. Technology trajectories increasingly center on data capture and autonomous adjustment capabilities.
Hyperspectral imaging systems for foreign material detection is migrating from premium pistachio and almond applications toward mid-volume peanut and cashew operations. Mid-scale processors in the southeastern United States are adopting refurbished optical sorters originally deployed in California's high-value tree nut sector. This technology diffusion is compressing price premiums for basic color-sorting equipment while expanding addressable market for AI-enhanced defect classification modules.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants are accelerating adoption of ammonia-based and transcritical CO2 cooling systems in European nut storage and tempering operations. Equipment suppliers must redesign thermal management architectures to maintain product moisture specifications under alternative refrigerant chemistries. German and Italian processing equipment builders are most advanced in certified low-global-warming-potential system integration, creating regulatory compliance advantage in EU export markets.
Aftermarket service unbundling is fragmenting traditional OEM maintenance relationships as third-party technical service providers capture calibration and refurbishment contracts. Large-scale almond processors in California's Central Valley are separating parts procurement from labor services, driving price transparency and compressing OEM service margins. This procurement model evolution is most pronounced among cooperatives and investor-owned processing facilities with dedicated in-house mechanical teams.
Nut Processing Machine Market Segmentation
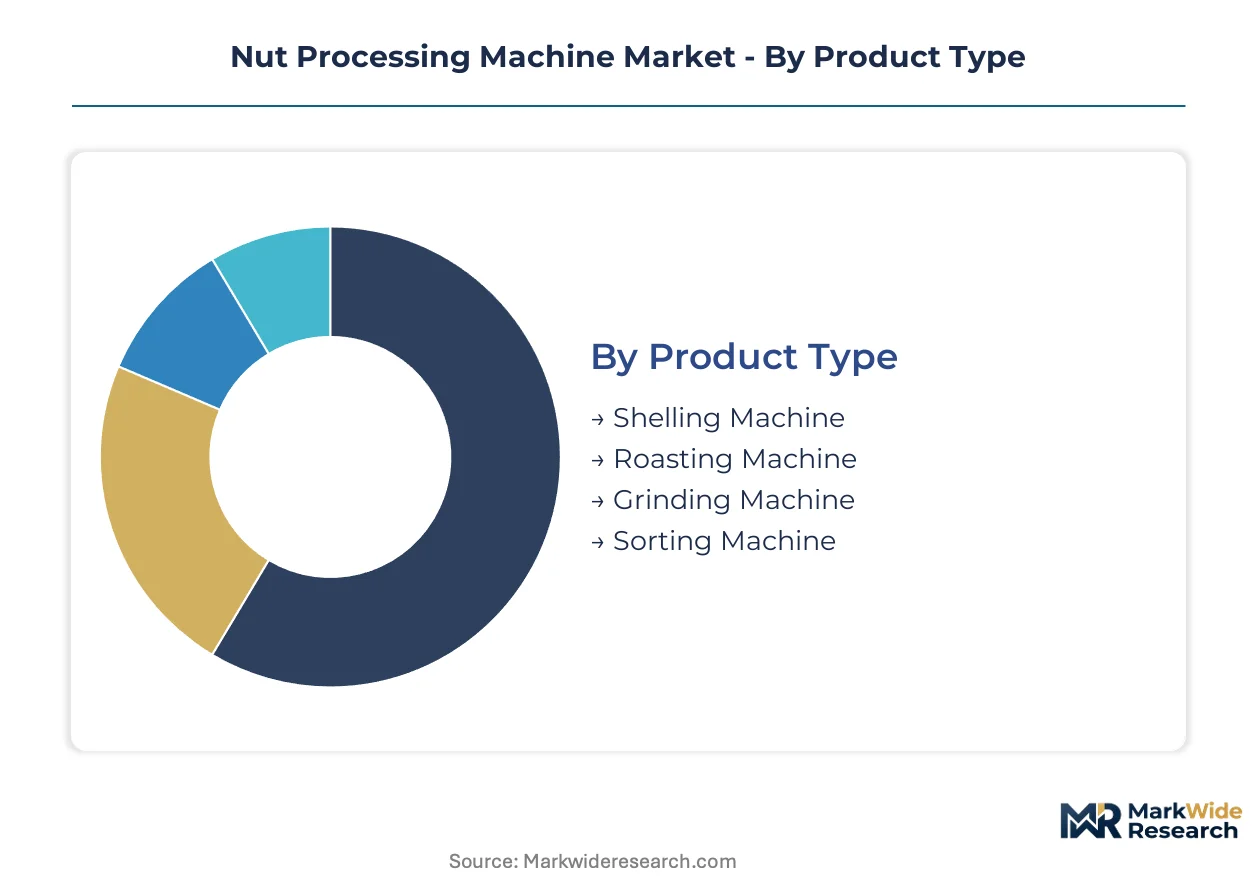
Segmentation in nut processing equipment reveals how capital allocation splits between precision sorting systems and commodity shelling infrastructure. Equipment specifications diver sharply based on whether processors serve export-grade almond markets or domestic snack ingredient channels.
Product Type:
Equipment selection spans from high-margin optical systems to mature mechanical infrastructure, with throughput requirements and contamination risk driving purchasing decisions.
- Sorting Machine:Optical and AI-driven foreign-object detection systems command premium pricing due to hyperspectral imaging capabilities. California almond processors prioritize these units to meet USDA export grading standards and FDA traceability mandates.
- Roasting Machine:Steam roasting configurations are displacing conventional thermal drums as snack producers retrofit lines for acrylamide reduction. Equipment replacement cycles in California's Central Valley have compressed from seven years to four years for this category.
- Shelling Machine:Mechanical almond and walnut shelling systems face extended replacement timelines due to functional adequacy and sunk capital investment.
- Grinding Machine:Precision particle-size reduction equipment serves bakery and confectionery ingredient channels with throughput rates from 500 kg to 50 tonnes per hour.
The dominant share belongs to Sorting Machine, while Roasting Machine is closing the gap fastest.
End User:
Customer type determines equipment specification intensity, with scale and export orientation creating divergent procurement patterns.
- Snack Producers:Automated line expansions for clean-label product ranges drive demand for integrated roasting-sorting systems. These operators prioritize flavor integrity without chemical preservatives, requiring precision thermal control and optical contamination removal.
- Food Manufacturers:Ingredient suppliers to bakery and confectionery channels require validated kill-step documentation under FSMA preventive controls. Multi-year equipment lifecycles and audit preparation costs strain mid-scale operations in this segment.
- Nut Retailers:Small-batch roasting and packaging equipment serves direct-to-consumer channels with lower throughput requirements.
- Restaurants:Limited commercial kitchens utilize compact grinding and tempering units for in-house nut-based menu preparations.
Snack Producers capture the largest equipment spend, though Food Manufacturers show the steepest expansion trajectory as ingredient outsourcing accelerates.
Technology:
Thermal processing methods are fragmenting between legacy mechanical systems and precision-controlled alternatives.
- Steam Roasting:Reduced acrylamide formation compared to conventional thermal methods positions this technology for snack producer retrofit cycles. FDA enforcement of food safety modernization rules accelerates capital allocation toward validated kill-step documentation.
- Mechanical Shelling:Established supply chains for almonds and walnuts occupy the most mature technology position, facing displacement from hybrid automated systems.
- Infrared Heating:Rapid thermal processing for small-batch operations provides energy efficiency advantages in mid-volume configurations.
- Microwaving:Emerging tempering and pre-treatment applications serve niche product development channels with limited commercial deployment.
Mechanical Shelling retains installed base dominance, while Steam Roasting gains share fastest on regulatory compliance tailwinds.
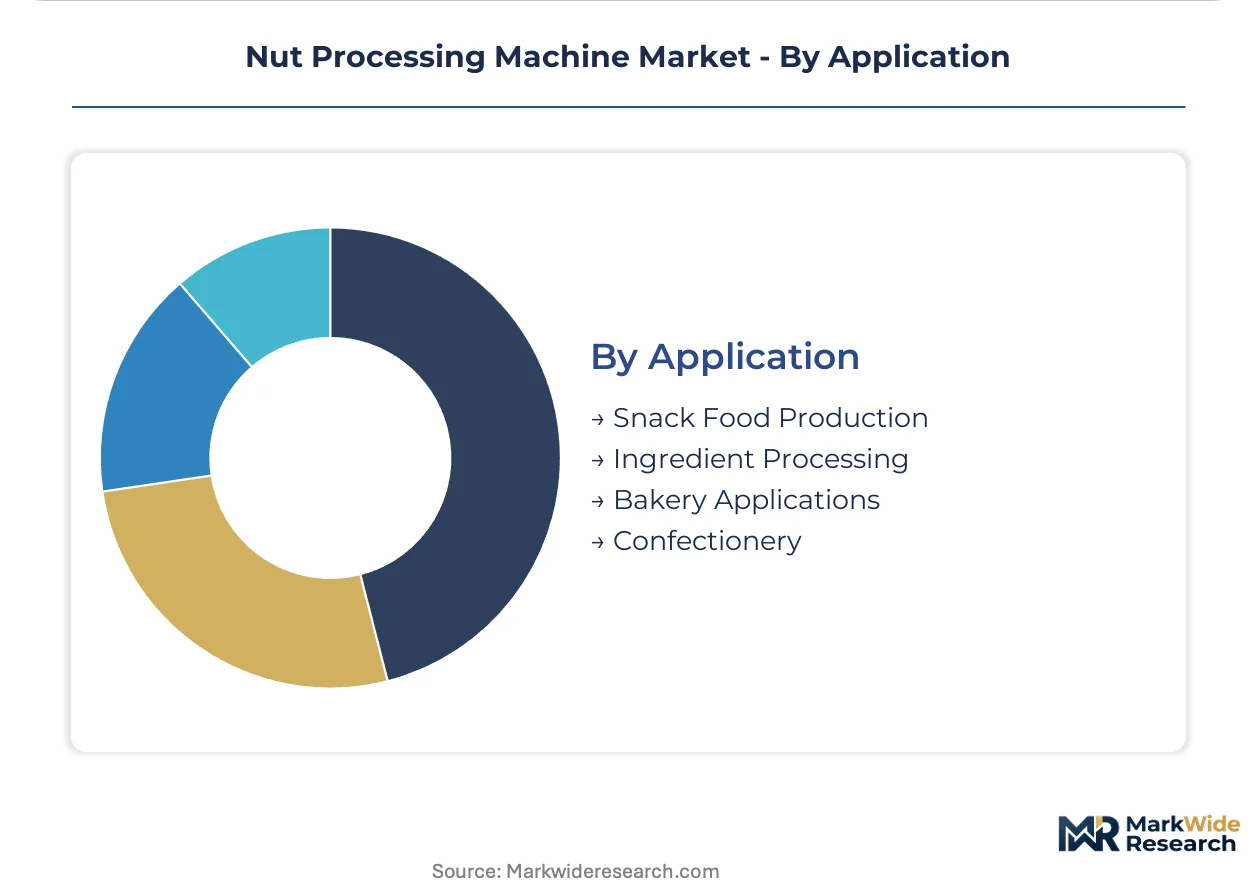
Application:
End-use channel requirements shape equipment hygiene grades and contamination tolerance thresholds.
- Snack Food Production:Clean-label demands eliminate artificial preservatives, requiring optical sorting and precision roasting that maintains flavor integrity. California processing clusters concentrate demand for high-throughput automated lines.
- Ingredient Processing:Bulk almond and walnut supply to bakery and confectionery manufacturers requires USDA grading standard compliance for export eligibility.
- Bakery Applications:Precise particle-size specifications for flour and paste applications drive grinding equipment calibration requirements.
- Confectionery:Roasting profiles tailored to chocolate coating compatibility require thermal control precision distinct from snack channels.
Snack Food Production holds the dominant application share, with Ingredient Processing climbing fastest on export market expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between export-grade processing clusters and domestic snack manufacturing hubs. California almond processors prioritize optical sorting and traceability systems, while European operators emphasize refrigerant compliance and energy efficiency. Asian markets concentrate on integrated shelling-to-packaging lines for local consumption.
United States
California's Central Valley hosts the densest concentration of almond and walnut processing infrastructure worldwide. FDA enforcement of FSMA preventive controls mandates validated kill-step documentation, accelerating equipment replacement cycles from seven years to four years. Modesto and Fresno processing clusters drive demand for high-throughput optical sorting and steam roasting systems.
Germany
EU F-Gas Regulation phase-down schedules push equipment buyers toward ammonia-based and transcritical CO2 cooling architectures. German fabricators lead certified low-global-warming-potential system integration, creating regulatory compliance advantages for export-oriented processors. Stuttgart and Munich engineering centers supply precision thermal management equipment to nut storage and tempering operations across the continent.
China
Domestic cashew and peanut processing expansion drives demand for integrated shelling-sorting-roasting lines. The country's national food safety regulator enforces stricter hygienic design standards for equipment serving branded snack channels. Shandong Province and the Yangtze River Delta concentrate mid-scale processing facilities upgrading from manual to semi-automated configurations.
Turkey
Pistachio processing modernization creates demand for export-grade equipment matching California quality standards. Harmonization with USDA grading specifications for almonds and pistachios enables single-platform system designs serving multiple export markets. Gaziantep and Şanlıurfa processing clusters retrofit mechanical shelling lines with optical sorting modules for European market access.
Australia
Macadamia and almond export orientation prioritizes contamination detection and traceability systems. The country's national food standards regulator aligns with international codex requirements for foreign material limits in tree nut shipments. Queensland and New South Wales processing facilities invest in hyperspectral imaging equipment to maintain premium pricing in Asian export markets.
Nut Processing Machine Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The vendor base separates between precision technology specialists and integrated line builders. Three archetypes dominate: optical sorting technology leaders, thermal processing equipment fabricators, and integrated turnkey system providers. Competitive moves center on aftermarket service contract capture and modular system architecture development.
Within the precision technology tier, Bühler Group and TOMRA Systems exemplify divergent approaches to recurring revenue generation. Bühler leverages global parts networks to capture service contracts from large-scale processors, while TOMRA sustains premium positioning through optical technology leadership. JBT Corporation occupies a position extending equipment lifecycle services into integrated line configurations. Among North American fabricators, The Middleby Corporation and Key Technology represent scale-driven equipment builders serving snack producer retrofit cycles.
| Leading Market Players |
|---|
| Bühler Group |
| TOMRA Systems |
| JBT Corporation |
| The Middleby Corporation |
| Key Technology |
| Lewis M. Carter Manufacturing |
| Modern Process Equipment Corporation |
| AC Horn Manufacturing |
| Savage Equipment |
| Others |
Value Network & Pricing Analysis
Overcapacity in China's peanut processing belt is compressing equipment utilization rates below 65%, forcing domestic fabricators to absorb stainless steel cost volatility rather than pass through input increases. This utilization squeeze redirects capital toward modular system architectures that preserve buyer flexibility while supplier margins tighten across all equipment tiers.
Pricing Analysis
Long-term offtake contracts dominate capital equipment procurement for California almond processors, locking in four-year replacement cycles with bundled service provisions. Pricing stratifies across premium, standard, and economy tiers based on optical sensor resolution grades and FSMA compliance certification levels. Cost compression in economy-tier mechanical shelling equipment is intensifying because Iranian and Turkish fabricators are flooding export markets with functional equivalents. Snack producers with dedicated in-house mechanical teams exhibit highest price sensitivity, while export-grade almond cooperatives prioritize traceability premiums over unit economics.
Supply Chain Analysis
German and Japanese export-control regimes on hyperspectral imaging components restrict optical sensor flows to sorting machine builders outside allied technology frameworks. Component manufacturing concentrates in Germany, Japan, and China, with near-infrared sensor fabrication anchored in Stuttgart engineering corridors and Osaka precision optics clusters. Raw material dependencies span Grade 304/316 stainless steel from Chinese mills, specialized bearing assemblies from Swedish suppliers, and PLC control modules from German automation houses. Single-source vulnerability concentrates in hyperspectral camera modules, where two Japanese suppliers control 80% of commercial-grade output. Distribution runs through OEM-direct channels for large-scale processors and regional equipment distributors serving mid-volume snack operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as steam roasting retrofits penetrate California's Central Valley ahead of FDA acrylamide enforcement deadlines. Equipment replacement velocity is accelerating beyond historical seven-year baselines.
For Market Incumbents: Harden service contract capture by embedding predictive maintenance sensors into roasting equipment before third-party providers can displace OEM relationships. Consolidate position through backward integration into optical sensor calibration services, countering the threat of independent technical service firms fragmenting aftermarket revenue pools. Prioritize certification investment for ammonia-based cooling architectures to secure EU export eligibility ahead of F-Gas Regulation phase-down deadlines.
For New Entrants and Emerging Players: Turkey's pistachio processing modernization offers the most penetrable white-space target, as Gaziantep and Şanlıurfa clusters seek California-grade equipment without incumbent service relationships. Iran's constrained access to Western optical sorting technology creates parallel demand for refurbished hyperspectral systems with localized technical support. Pursue go-to-market partnerships with German engineering firms holding transcritical CO2 cooling certifications to bypass direct regulatory compliance investment.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across steam roasting sub-segments as modular architectures displace integrated turnkey lines. Long-term viability favors equipment builders with recurring service revenue exceeding 35% of total mix. Target acquisition profiles should emphasize optical sorting specialists with established USDA calibration protocols. Monitor FDA traceability rule implementation timelines as the critical inflection signal for capital allocation toward digital tracking-integrated systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Optical Sensor Technology Licensing | Hyperspectral imaging partnerships bypass German-Japanese supply concentration for mid-tier builders. |
| Aftermarket Service Unbundling | Separating parts procurement from labor contracts captures price-transparent California cooperative demand. |
| Backward Integration into Sensor Calibration | In-house optical module refurbishment defends OEM margins against third-party technical providers. |
| Modular System Architecture Development | Component-based configurations preserve processor capital flexibility amid compressed replacement cycles. |
| EU F-Gas Compliance Certification | Ammonia-based cooling credentials unlock export sales to German and Italian nut storage operators. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with equipment procurement directors, plant engineers, aftermarket service heads, and optical sorting specialists; and secondary validation against USDA grading bulletins, FDA FSMA guidance documents, EU F-Gas Regulation implementation schedules, and customs trade data on stainless steel equipment imports. Bottom-up triangulation across California Central Valley processing clusters and top-down reconciliation with reported equipment shipments anchored volume estimates.
Forecast inputs span product type segmentation across sorting, roasting, shelling, and grinding equipment; technology trajectories from mechanical through steam and infrared thermal methods; and end-user channels distinguishing snack producers from ingredient suppliers and nut retailers. CAGRs were derived from equipment replacement cycle compression observed in California clusters and technology diffusion patterns for hyperspectral imaging into mid-volume peanut operations. Industry-specific inputs include FDA preventive control enforcement timelines and EU refrigerant phase-down schedules.
Practitioners should monitor stainless steel price volatility, hyperspectral sensor export license delays, and FDA traceability rule finalization for early signals of forecast deviation. Material shifts in California water allocation policy affecting almond planting acreage, or abrupt changes in US-Turkey trade terms impacting pistachio equipment demand, would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Pet Food Processing Market
Food Processing Equipment
Nugget Ice Machines Market
Food Processing Equipment
Air Cooled Cube Ice Machines Market
Food Processing Equipment
Global Carbonated Beverage Processing Equipment Market
Food Processing Equipment
Automatic Canning Machine Market
Food Processing Equipment
Global Fermenters Market
Food Processing Equipment
Global Nutating Mixers Market
Food Processing Equipment
Commercial Food Refrigeration Equipment Market
Food Processing Equipment
Global Meat Mixer Market
Food Processing Equipment
Plastic Processing Equipment Market
Food Processing Equipment
Spray Drying Market
Food Processing Equipment
Dough Processing System Market
Food Processing Equipment
Commercial Food Processors Market
Food Processing Equipment
Ice Flaking Machine Market
Food Processing Equipment
Middle East and Africa Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Hot Food Processing Equipment Market