
 Defrosting & Thawing Equipment for Food Market | 2026-2036
Defrosting & Thawing Equipment for Food Market Size, Share, and Industry Trends Forecast 2026-2036
Defrosting & Thawing Equipment for Food Market Insights
Food processing plants is shifting toward higher-capacity automated thawing systems as labor scarcity and throughput targets reshape procurement priorities. GEA Group Aktiengesellschaft dominates European industrial installations with its large-scale contact heating platforms. JBT Corporation specializes in integrated thawing-to-cooking lines for poultry processors across North America. Bühler AG anchors premium microwave defrosting systems for seafood and red meat applications.
Defrosting and thawing equipment encompasses engineered systems designed to raise frozen food products from storage temperatures to processing-ready states through controlled thermal transfer, typically operating within precise time-temperature windows to prevent bacterial proliferation and quality degradation. Microwave ovens deliver rapid volumetric heating through dielectric energy absorption at frequencies near 2.45 GHz, while commercial thawing cabinets circulate conditioned air to maintain surface temperatures below pathogenic growth thresholds. Heated water baths represent the most mature product category, capturing established margin pools in commodity meat processing, whereas infrared systems command premium positioning for high-value seafood and ready-meal applications where surface integrity determines yield.
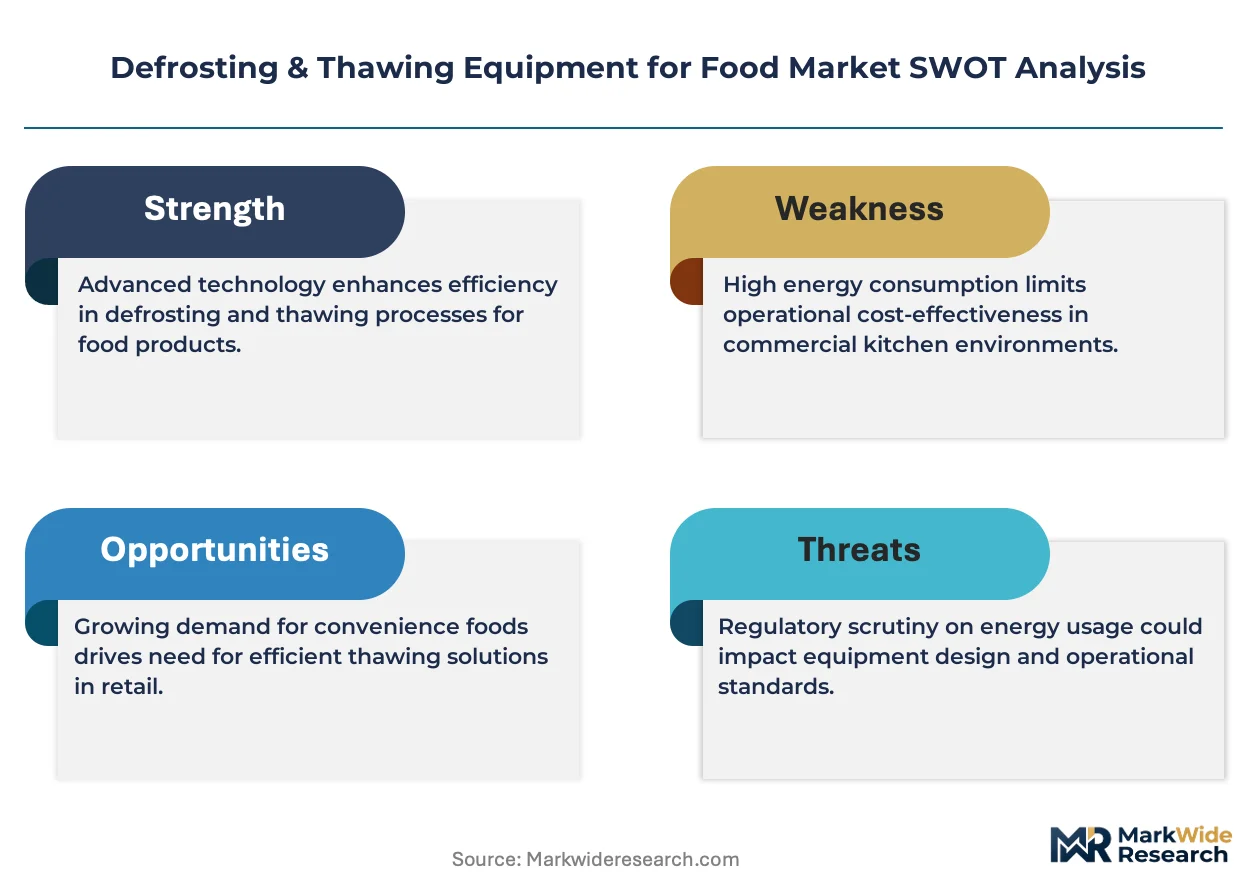
FDA food safety regulations and USDA HACCP guidelines in the United States impose validated thawing protocols that equipment must document through integrated data logging, directly shaping R&D investment toward traceable control systems. The EU's general food law framework, enforced by national agencies under EFSA guidance, mandates equivalent temperature control documentation across member states, creating harmonized compliance barriers for non-certified imports. Stakeholders must monitor evolving energy efficiency standards and carbon accounting rules, as thawing operations represent measurable thermal loads in scope emissions disclosures.
Market Dynamics
Automated thawing lines are displacing manual batch operations across food processing facilities as labor scarcity intensifies and throughput targets harden. FDA validated time-temperature controls now mandate documented thermal protocols, forcing capital deployment toward certified integrated systems.
Growth Catalysts
- FDA Food Safety Modernization Act:Validated thawing protocols require equipment with integrated data logging, compelling processors to upgrade from unvalidated manual methods.
- Microwave volumetric heating:Dielectric energy absorption at 2.45 GHz delivers rapid uniform thawing for high-value seafood and ready-meal applications where surface integrity determines yield.
- German meat processing cluster:Europe's densest concentration of industrial-scale defrosting installations generates concentrated demand for large-capacity contact heating platforms.
Market Restraints
- Stainless steel input volatility:Equipment fabrication depends on nickel and chromium prices, compressing margins for heated water bath manufacturers serving commodity meat processors.
- Energy cost escalation:Thawing operations represent measurable thermal loads; carbon accounting disclosures under EU CSRD expose processors to scope emissions penalties.
- Technical throughput ceilings:Infrared systems face watt-density limitations preventing scale-up beyond boutique seafood applications.
Strategic Opportunities
- India cold chain expansion:FSSAI enforcement of temperature-controlled handling creates first-mover advantage for microwave defrosting vendors in underpenetrated poultry processing.
- EU Green Deal thermal efficiency mandates:Equipment retrofit subsidies favor heat pump-integrated thawing cabinets over legacy resistance-heated models.
- Convergence of RFID traceability and thermal control:Combined batch tracking and temperature logging enables premium pricing for integrated systems in North American contract manufacturing.
Industry Challenges
- Commissioning timeline compression:USDA HACCP validation protocols require extended factory acceptance testing, delaying revenue recognition for custom thawing line deployments.
- Electrical infrastructure retrofit costs:High-capacity microwave installations demand 480V three-phase service upgrades that stall adoption at smaller processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Defrosting & Thawing Equipment for Food Market |
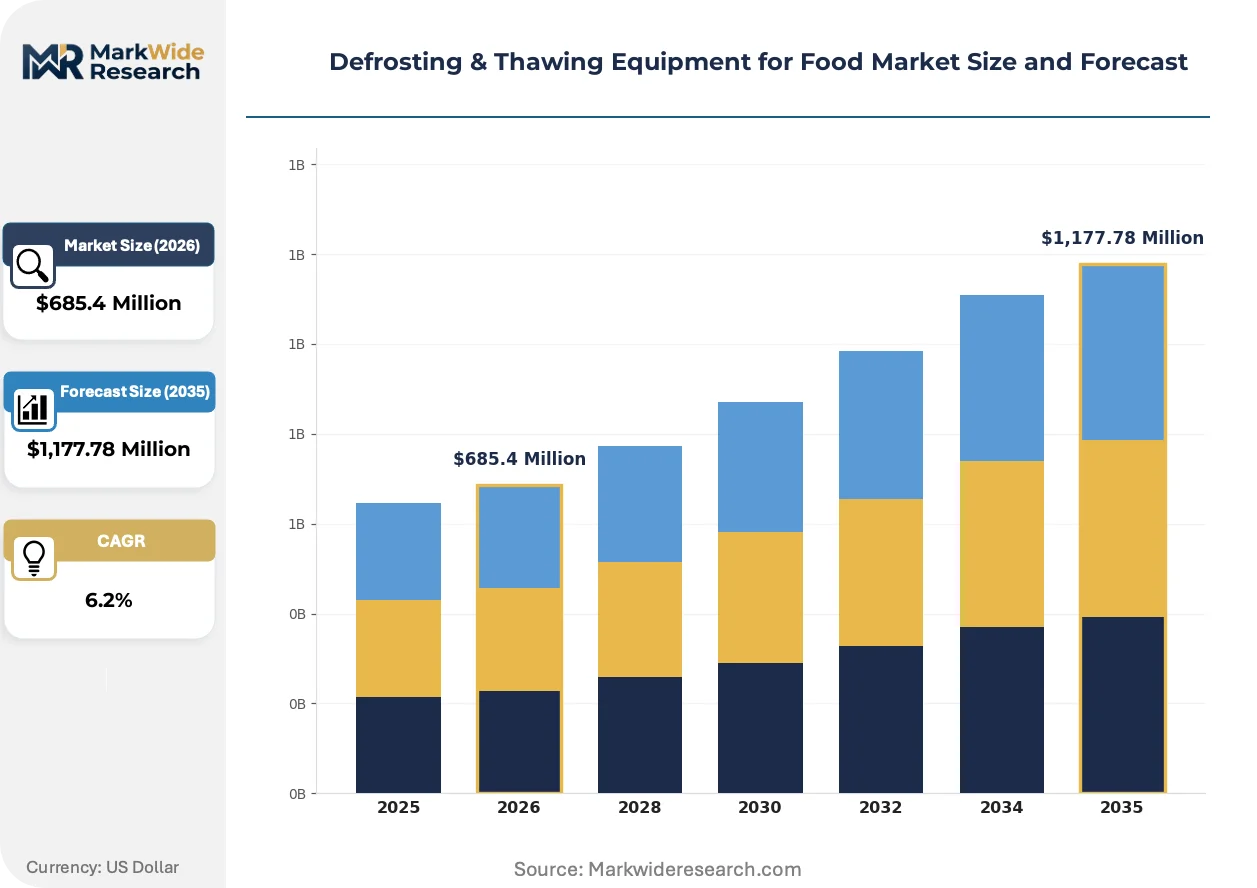
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microwave Ovens, Heated Water Baths, Infrared Systems, Commercial Thawing Cabinets End User: Restaurants, Catering Services, Grocery Stores, Food Processing Plants Technology: Convection Heating, Direct Contact Heating, Radiant Heating, Cryogenic Freezing Capacity: Small Scale, Medium Scale, Large Scale, Industrial Scale |
| Companies Covered | Bühler AG, SPX FLOW, Inc., Electrolux, JBT Corporation, Marel hf., GEA Group Aktiengesellschaft, Alfa Laval AB, Provisur Technologies, Inc., Tetra Pak International S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Defrosting & Thawing Equipment for Food Market Trends and Innovations
Equipment architecture is pivoting from standalone thawing units toward integrated processing lines that feed directly into cooking or packaging stages. This convergence is compressing footprint requirements and reshaping vendor competitive sets.
Radio-frequency defrosting at 27.12 MHz is rewriting thermal transfer economics for dense protein blocks. Beef and pork processors in the Midwestern United States are piloting these systems to replace 24-hour tempering rooms with 90-minute cycles. The technology is compressing working capital requirements by enabling same-day processing of frozen inventory.
EU F-Gas Regulation phase-down schedules are accelerating heat pump adoption in thawing cabinet design. Equipment manufacturers must now certify refrigerant circuits below 150 GWP thresholds, raising R&D costs but creating regulatory moats against non-compliant imports. German and Dutch poultry processors are prioritizing suppliers with pre-certified low-GWP platforms.
Service unbundling is fragmenting procurement patterns across North American meatpacking. Large processors now separate equipment purchase from validation support and aftermarket thermal probe calibration, favoring vendors with modular service tiers. This shift is most visible in Texas and Nebraska beef operations where third-party HACCP consultants now specify equipment independently of capital procurement teams.
Defrosting & Thawing Equipment for Food Market Segmentation
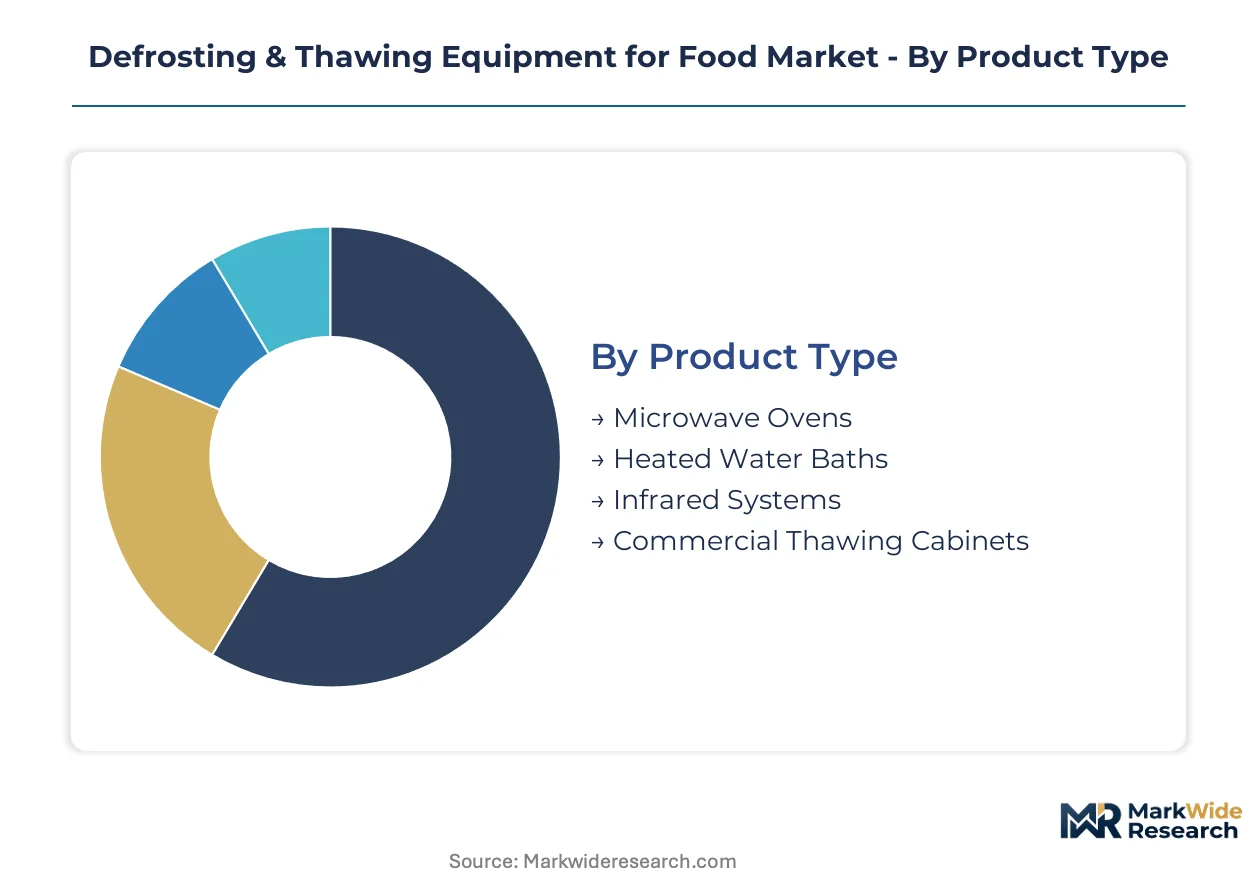
Segmentation in defrosting and thawing equipment reveals divergent technology stacks across end-use intensities. Procurement patterns split between high-throughput industrial installations and distributed foodservice units with contrasting thermal load profiles and compliance documentation requirements.
Product Type:
Supply concentration clusters around mature thermal transfer platforms with established fabrication ecosystems and aftermarket service networks.
- Heated Water Baths:Submersion systems circulate temperature-controlled fluid around sealed product containers, achieving uniform heat distribution through conductive transfer. Commodity meat processors in the United States deploy these systems most densely, driven by USDA HACCP validation protocols that favor documented, repeatable thermal profiles over speed. Heated water baths absorb the bulk of installed capacity; microwave ovens are expanding most quickly.
- Microwave Ovens:Dielectric heating at 2.45 GHz generates volumetric energy absorption that reduces thawing cycles from hours to minutes. Seafood processors and ready-meal manufacturers prioritize these systems where surface integrity determines yield recovery rates.
- Infrared Systems:Radiant energy transfer at precise wavelengths enables controlled surface heating for high-value protein applications. Boutique seafood operations in Germany favor this technology for premium product lines.
- Commercial Thawing Cabinets:Conditioned air circulation maintains surface temperatures below pathogenic growth thresholds through forced convection. European poultry processors under EFSA guidance deploy these for batch compliance documentation.
Heated water baths retain the largest installed base; microwave ovens are gaining share fastest in high-value protein processing.
End User:
Cost tier stratification separates capital-intensive industrial installations from distributed foodservice equipment with lower technical specifications and shorter replacement cycles.
- Food Processing Plants:Automated thawing lines integrate directly into continuous production flows with validated time-temperature logging for FDA compliance. German meat and poultry processors operate Europe's densest cluster of industrial-scale installations.
- Restaurants:Compact under-counter units serve high-turnover kitchen environments where space constraints dominate procurement decisions. Urban foodservice operators in the United States prioritize rapid cycle times over energy efficiency metrics.
- Catering Services:Mobile or modular equipment supports event-based volume surges with limited fixed infrastructure. Volume volatility shapes preference for lease-based procurement over capital purchase.
- Grocery Stores:Back-of-house tempering units support in-house prepared food operations and bakery defrosting requirements. Retail chains under FDA food safety modernization rules increasingly require data-logging capabilities.
Food processing plants command the highest average equipment values; grocery stores are expanding unit installations most rapidly under fresh prepared food strategies.
Technology:
Application-specific thermal physics determines technology selection, with each method optimizing for distinct product geometries and throughput requirements.
- Direct Contact Heating:Conductive transfer through heated platens or drums delivers precise temperature control for uniform protein blocks. GEA Group anchors European supply for large-scale meat processing installations.
- Convection Heating:Forced air circulation enables batch processing flexibility across variable product formats. Commercial thawing cabinets rely on this mechanism for regulatory compliance in temperature-sensitive applications.
- Radiant Heating:Infrared wavelength targeting provides surface-penetrating energy for crustacean and finfish applications where moisture retention determines quality grades.
- Cryogenic Freezing:Rapid temperature reduction through liquid nitrogen or carbon dioxide contact, used in specialized applications requiring immediate preservation post-thaw.
Direct contact heating dominates red meat processing capacity; convection heating serves the broadest cross-section of end-use segments.
Capacity:
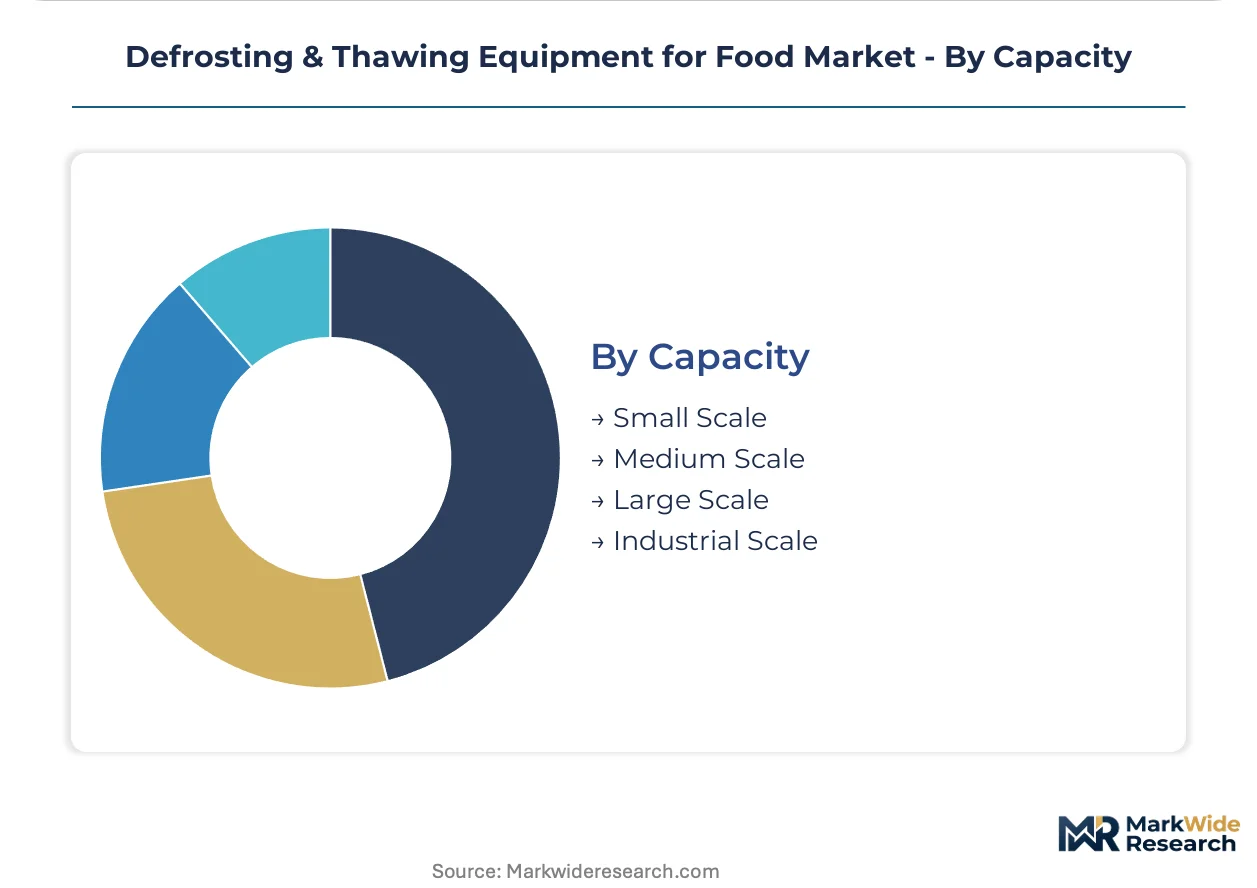
Volume scale determines equipment architecture, with industrial-scale installations requiring integrated material handling and small-scale units optimized for footprint minimization.
- Industrial Scale:Continuous-feed systems with automated loading, thermal monitoring, and discharge mechanisms process multiple tons per hour. JBT Corporation specializes in integrated thawing-to-cooking lines for North American poultry processors at this scale.
- Large Scale:Batch systems serving mid-sized processing facilities with throughput requirements below continuous-line thresholds but above foodservice norms.
- Medium Scale:Standalone cabinets and baths serving regional processors and central kitchen operations with moderate volume consistency.
- Small Scale:Countertop and under-counter units for restaurants, cafes, and retail delis with intermittent, low-volume defrosting needs.
Industrial scale captures the greatest cumulative thermal load; large scale is climbing the fastest as mid-tier processors automate legacy manual operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the United Arab Emirates concentrate regional distribution hubs for Middle Eastern food processing equipment. Tax incentives in these zones attract multinational vendors establishing regional service centers. Cold chain infrastructure investments across emerging markets reshape equipment procurement patterns.
United States
Midwestern beef and pork processors drive demand for radio-frequency defrosting systems that compress 24-hour tempering cycles into 90-minute operations. FDA food safety modernization rules mandate validated time-temperature controls with integrated data logging. Nebraska and Texas host dense clusters of automated thawing line deployments where third-party HACCP consultants specify equipment independently.
Germany
Meat and poultry processors operate Europe's densest concentration of industrial-scale defrosting installations. EU F-Gas Regulation phase-down schedules accelerate heat pump adoption in thawing cabinet design. Bavarian and North Rhine-Westphalian processing facilities prioritize suppliers with pre-certified low-GWP refrigerant platforms under 150 GWP thresholds.
India
FSSAI enforcement of temperature-controlled handling creates first-mover opportunities in underpenetrated poultry processing. The country's national food safety regulator mandates cold chain compliance across expanding processing capacity. Maharashtra and Gujarat host emerging clusters where microwave defrosting vendors target mid-tier processor automation upgrades.
China
Dual carbon goals and energy efficiency standards reshape thermal equipment procurement in coastal processing zones. The Ministry of Ecology and Environment enforces carbon accounting disclosures that expose thawing operations to scope emissions penalties. Yangtze River Delta seafood processors pilot heat pump-integrated systems to meet provincial energy intensity targets.
Brazil
Beef and poultry export processors invest in validated thawing protocols to maintain USDA equivalence certifications. ANVISA food safety guidelines align with international HACCP standards for equipment documentation. São Paulo and Paraná processing corridors concentrate demand for large-capacity contact heating platforms serving commodity export volumes.
Defrosting & Thawing Equipment for Food Market Competitive Landscape
Top-tier vendors anchor premium integrated systems, while mid-tier fabricators compete on modular equipment and aftermarket service unbundling. Market structure tilts toward consolidation among European industrial automation conglomerates with captive food processing divisions. Three archetypes dominate: diversified engineering groups with cross-sector thermal platforms, specialized protein processing equipment vendors, and regional fabricators serving emerging market price sensitivity. Competitive moves center on portfolio diversification into adjacent cooking and packaging stages, plus geographic expansion through distribution partnerships in underpenetrated cold chain markets.
Among diversified European engineering groups, GEA Group Aktiengesellschaft and Bühler AG exemplify the premium-tier archetype with established industrial automation ecosystems. JBT Corporation occupies a position representing North American specialists in integrated processing lines. These three anchors demonstrate how vendor competitive sets fragment across geographic origin and vertical integration depth rather than converging on uniform technology platforms.
| Leading Market Players |
|---|
| Bühler AG |
| SPX FLOW, Inc. |
| Electrolux |
| JBT Corporation |
| Marel hf. |
| GEA Group Aktiengesellschaft |
| Alfa Laval AB |
| Provisur Technologies, Inc. |
| Tetra Pak International S.A. |
| Others |
Pricing and Supply Chain Analysis
Radio-frequency defrosting adoption at 27.12 MHz is compressing tempering cycles from 24 hours to 90 minutes, simultaneously raising equipment price premiums for speed-critical buyers and concentrating fabrication expertise among vendors with electromagnetic engineering capabilities. This technology transition rewards suppliers with captive RF component sourcing while penalizing commodity bath manufacturers facing stainless steel cost volatility.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent deployments from planned capacity additions, with 90-day delivery slots commanding substantial premiums over standard 180-day schedules. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—FDA-validated systems with integrated data logging anchor the premium tier, while commodity water baths without documentation capabilities populate the economy segment. Pricing pressure stems from nickel and chromium input volatility squeezing margins for heated bath fabricators serving commodity meat processors. Food processing plants exhibit lowest price sensitivity due to throughput-critical operations, whereas catering services and small-scale restaurants prioritize capital minimization over performance specifications.
Supply Chain Analysis
Stainless steel feedstock supply rests on Chinese and Indonesian nickel smelting capacity, German cold-rolling expertise for precision platens, and Japanese specialty electromagnetic component fabrication for RF and microwave generators. Critical input dependencies span nickel-chromium alloys for corrosion-resistant tank construction, magnetron assemblies for 2.45 GHz dielectric heating, and low-GWP refrigerant circuits for EU-compliant thawing cabinets. Single-source vulnerability concentrates in high-power magnetron supply, where two Japanese manufacturers dominate global output. Distribution runs through regional equipment distributors with captive installation and validation service capabilities, particularly dense in Germany's meat processing corridor and the US Midwestern beef belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The defrosting equipment sector sits in a technology-transition phase, with radio-frequency and heat pump-integrated systems displacing legacy resistance-heated water baths and tempering rooms. This substitution wave rewards vendors with electromagnetic and thermal engineering depth while threatening commodity fabricators.
For Market Incumbents: Cement defensible positioning through backward integration into magnetron and RF generator supply chains, insulating against Japanese component bottlenecks. Prioritize pre-certification of low-GWP refrigerant platforms under EU F-Gas thresholds to capture German and Dutch poultry processor upgrades. Defend margin structure by unbundling validation support and aftermarket thermal probe calibration into recurring revenue streams, responding to Texas and Nebraska beef operations where third-party HACCP consultants now specify equipment independently of capital procurement teams. For New Entrants and Emerging Players: Capture first-mover advantage in India's underpenetrated poultry processing corridor, where FSSAI enforcement of temperature-controlled handling creates compliance-driven replacement demand. Target mid-tier processors in Maharashtra and Gujarat with microwave defrosting systems priced below European premium tiers but above commodity bath alternatives. Pursue lease-based procurement models for catering services and grocery store delis, where volume volatility and capital constraints favor operational expenditure structures over equipment ownership. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified European engineering groups seeking protein processing thermal platform expansion. Long-term viability favors vendors with integrated thawing-to-cooking line capabilities and established FDA validation documentation protocols. Acquisition target archetype: mid-scale RF defrosting specialists with proprietary 27.12 MHz electromagnetic tuning expertise and existing Midwestern US beef processor pilot installations. Watch for inflection signals in EU Green Deal thermal efficiency subsidy disbursement rates, which will accelerate heat pump-integrated cabinet adoption and compress legacy resistance-heated equipment residual values.| Strategic Initiative | Industry Significance |
|---|---|
| RF Defrosting Platform Development | 27.12 MHz systems compress tempering cycles from 24 hours to 90 minutes for beef processors. |
| Heat Pump Refrigerant Retrofit | Sub-150 GWP platform certification secures EU F-Gas compliance for German poultry installations. |
| Validation Service Unbundling | Modular HACCP support tiers capture recurring revenue from Nebraska and Texas beef operations. |
| India Distribution Partnership | FSSAI compliance positioning targets Maharashtra and Gujarat poultry processor automation upgrades. |
| Integrated Thawing-to-Cooking Lines | Continuous-feed architecture reduces footprint and labor for North American poultry processors. |
Research Methodology
Multi-period observation of equipment installation rates, regulatory filing patterns, and thermal technology patent publications anchored the trend analysis, supplemented by interviews with plant engineers at meat and poultry processing facilities, procurement leads at foodservice equipment distributors, aftermarket service heads, and regulatory compliance officers. Secondary validation drew from FDA equipment validation guidance documents, USDA HACCP implementation records, EU F-Gas Regulation compliance databases, and EFSA temperature control enforcement reports. Bottom-up triangulation across named vendor shipment estimates and top-down reconciliation against food processing capital expenditure disclosures ensured cross-verified market sizing.
Segment-weighting approaches modeled product type splits across heated water baths, microwave ovens, infrared systems, and commercial thawing cabinets; end-user differentiation between food processing plants, restaurants, catering services, and grocery stores; technology distinctions in direct contact, convection, radiant, and cryogenic heating; and capacity tiers from industrial scale through small scale. CAGRs were derived from fitted growth curves against historical installation trajectories, with industry-specific inputs including energy cost escalation curves, stainless steel price indices, and regulatory compliance deadline schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU carbon accounting enforcement stringency, RF component supply consolidation, and FSSAI inspection capacity expansion in India. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory implementation timelines. A small set of triggers warrants ongoing watch: EU Green Deal subsidy disbursement acceleration, Japanese magnetron manufacturer capacity decisions, and FDA validation protocol amendments for automated thawing lines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Wine Processing Equipment Market
Food Processing Equipment
Brewing Chiller Market
Food Processing Equipment
Cider Brewing Equipment Market
Food Processing Equipment
Wine Crusher Market
Food Processing Equipment
Dough Processing System Market
Food Processing Equipment
Food Preservation Equipment Market
Food Processing Equipment
Global Wine Tanks Market
Food Processing Equipment
Steam Blanching Equipment Market
Food Processing Equipment
Global Powder Processing Equipment Market
Food Processing Equipment
Food Waste Composting Machine Market
Food Processing Equipment
Spray Drying Equipment Market
Food Processing Equipment
Coffee Processing Machine Market
Food Processing Equipment
Food Processing and Handling Equipment Market
Food Processing Equipment
Asia-Pacific Commercial Sous Vide Machine Market
Food Processing Equipment
Countertop Food Blenders Market
Food Processing Equipment
Automatic Evisceration System Market