
 Portable Clean-In-Place Market | 2026-2036
Portable Clean-In-Place Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Clean-In-Place Market Analytics
Multi-source procurement for hygienic processing equipment is hardening as pharmaceutical and beverage manufacturers diversify supplier relationships beyond traditional single-vendor dependencies. GEA Group leverages its deep integration of pump and valve technologies to sustain captive supply advantages in automated CIP skids. Alfa Laval competes through heat exchanger specialization that extends into recovery-efficient cleaning circuits. Sani-Matic anchors North American demand with stainless-steel fabrication scale tailored to mid-sized dairy and brewery operators.
Portable Clean-In-Place equipment comprises self-contained skids with programmable logic controllers, stainless-steel tanks, and centrifugal pumps designed to circulate cleaning chemicals through process piping without equipment disassembly. Systems typically operate at temperatures between 60°C and 85°C with conductivity sensors verifying rinse completeness, serving industries where microbial control and allergen elimination are non-negotiable. Mobile Systems dominate current procurement as facilities prioritize flexible deployment across multiple production lines, while Automated Solutions capture expanding margin pools through validation documentation and reduced operator intervention. Food Processing applications lead volume demand, though Pharmaceutical Production commands premium pricing due to FDA-mandated cleaning validation protocols.
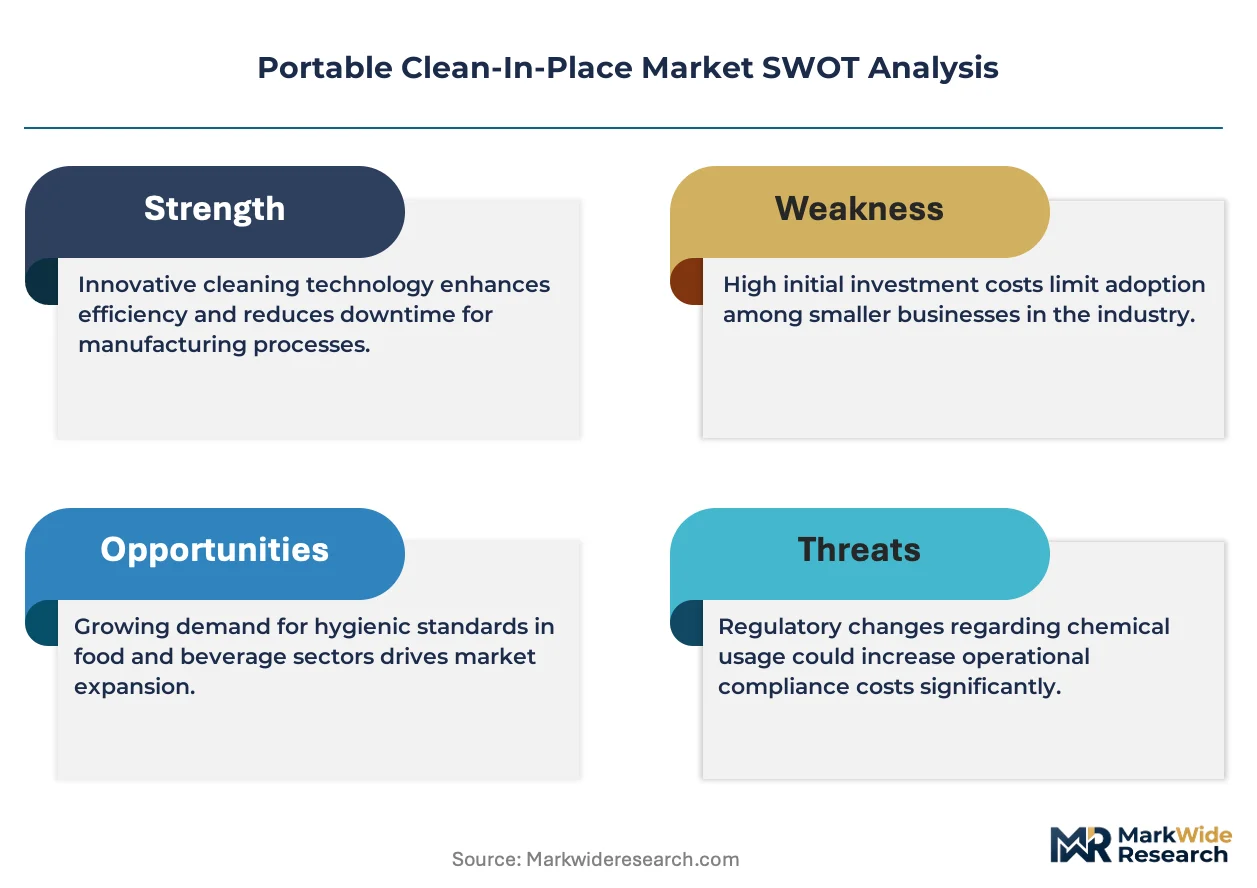
FDA validation requirements and the EU's MDR framework for hygienic equipment safety shape product development priorities, with both bodies emphasizing documented repeatability in cleaning cycles. The EPA's effluent guidelines for chemical discharge further constrain formulation choices, pushing vendors toward lower-phosphonate detergent chemistries. Stakeholders must monitor how evolving ISO hygiene standards for cleanability testing intersect with site-specific water scarcity constraints to determine optimal system specifications and service model investments.
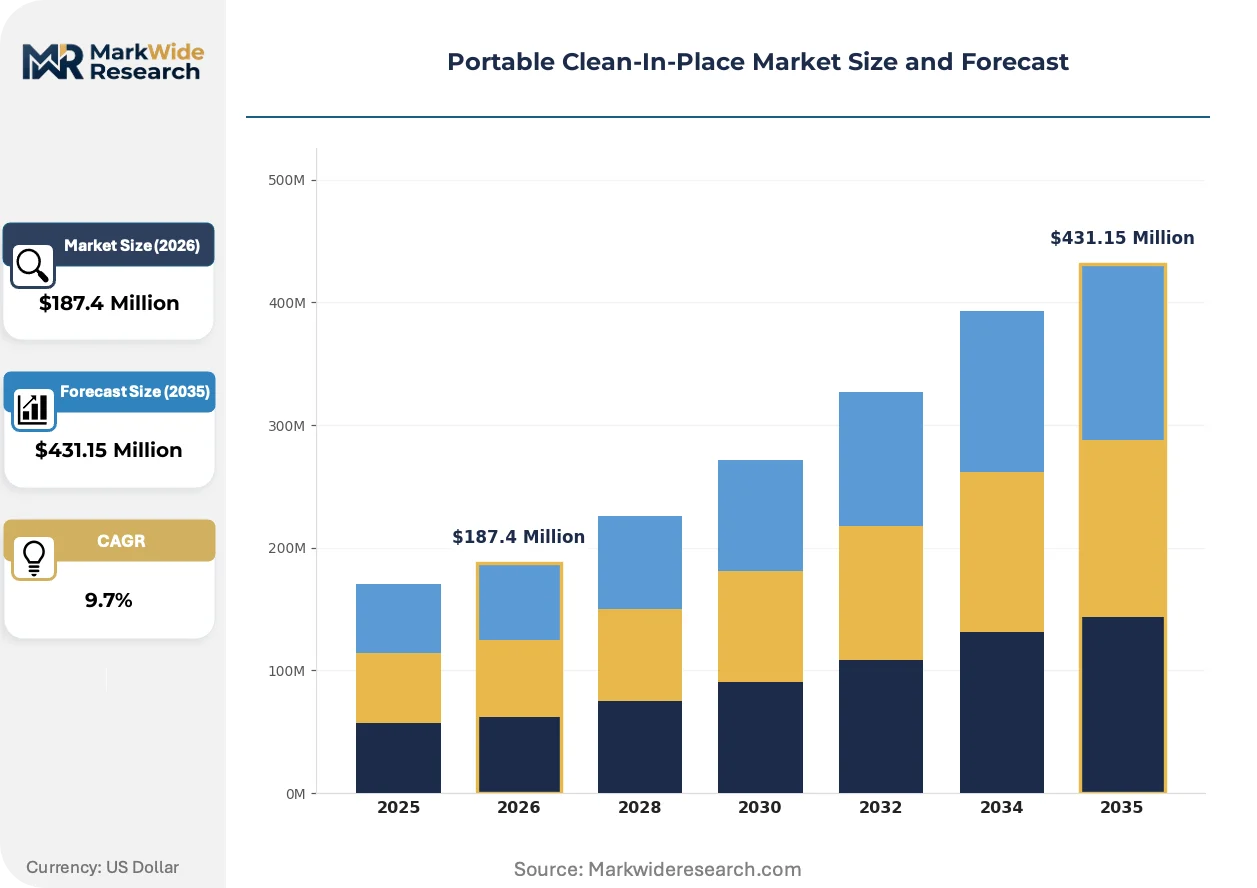
Market Dynamics
Pharmaceutical manufacturers are consolidating cleaning validation documentation into automated portable CIP systems to satisfy FDA inspection protocols, compressing procurement cycles and raising technical barriers for equipment vendors.
Growth Catalysts
- EU MDR framework:Medical device manufacturers in Germany and Ireland must demonstrate hygienic equipment compliance, accelerating replacement of manual cleaning stations with validated automated skids.
- Water recovery circuits:Heat exchanger integration into CIP return loops cuts freshwater consumption by half, attracting dairy processors in water-stressed regions of Spain and California.
- Batch manufacturing flexibility:Contract pharmaceutical facilities deploy mobile CIP units across multiple suites to minimize downtime between product changeovers.
Market Restraints
- Stainless steel price volatility:316L grade tank fabrication costs swing with nickel supply disruptions from Indonesian mining curbs, squeezing mid-sized skid builders.
- Specialized fabricator concentration:Precision orbital welding capacity clusters in northern Italy and southern Germany, creating bottlenecks for North American project timelines.
- EPA effluent limits:Phosphonate discharge restrictions in the US force detergent reformulation, extending qualification cycles for new chemical suppliers.
Strategic Opportunities
- Saudi pharmaceutical manufacturing:SFDA's tightened GMP enforcement creates first-mover advantage for vendors offering Arabic-language validation documentation packages.
- Cell therapy production:Closed-system bioreactor cleaning demands single-use CIP components, opening premium pricing tiers for disposable manifold suppliers.
- ISO 14001 alignment:Carbon footprint disclosure requirements push beverage multinationals toward energy-recovery CIP designs with heat pump integration.
Industry Challenges
- Orbital welding certification:ASME BPE-qualified technicians command wage premiums that inflate field installation costs by double-digit percentages.
- Legacy SCADA integration:Brownfield dairy plants struggle to connect modern CIP PLCs to 1990s-era distributed control systems without custom protocol gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Clean-In-Place Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Systems, Stationary Units, Automated Solutions, Manual Devices Application: Food Processing, Pharmaceutical Production, Beverage Manufacturing, Chemical Processing End User: Manufacturers, Distributors, Service Providers, Research Laboratories Installation: On-Site Setup, Off-Site Configuration, Integrated Solutions, Standalone Equipment |
| Companies Covered | GEA Group, Alfa Laval, SPX Flow, Krones AG, Tetra Pak, Sani-Matic, Millitec Food Systems, Central States Industrial, Melegari Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Clean-In-Place Market Evolving Landscape
Sensor-driven rinse verification and modular chemical dosing architectures are compressing cleaning cycle durations while expanding service revenue pools for equipment vendors.
Conductivity-based endpoint detection is expanding into pharmaceutical applications where TOC validation previously required offline laboratory sampling. Biologics manufacturers in Massachusetts and North Carolina adopt these sensors to release production suites within four-hour windows. The technology is expanding into contract manufacturing organizations that compete on batch turnaround speed.
REACH restrictions on peracetic acid concentrations force European CIP operators toward enzyme-based cleaning chemistries with narrower temperature windows. Formulators must revalidate entire cleaning protocols, delaying new product introductions by six to eighteen months. German dairy cooperatives absorb these costs fastest due to consolidated technical service teams.
Equipment-as-a-service contracts now bundle chemical supply, sensor calibration, and validation documentation into per-cycle fees. Mid-sized breweries in the US Pacific Northwest prefer this model over capital purchases to preserve balance sheet flexibility. The shift concentrates vendor risk on uptime guarantees and accelerates consolidation among regional service providers.
Portable Clean-In-Place Market Segmentation
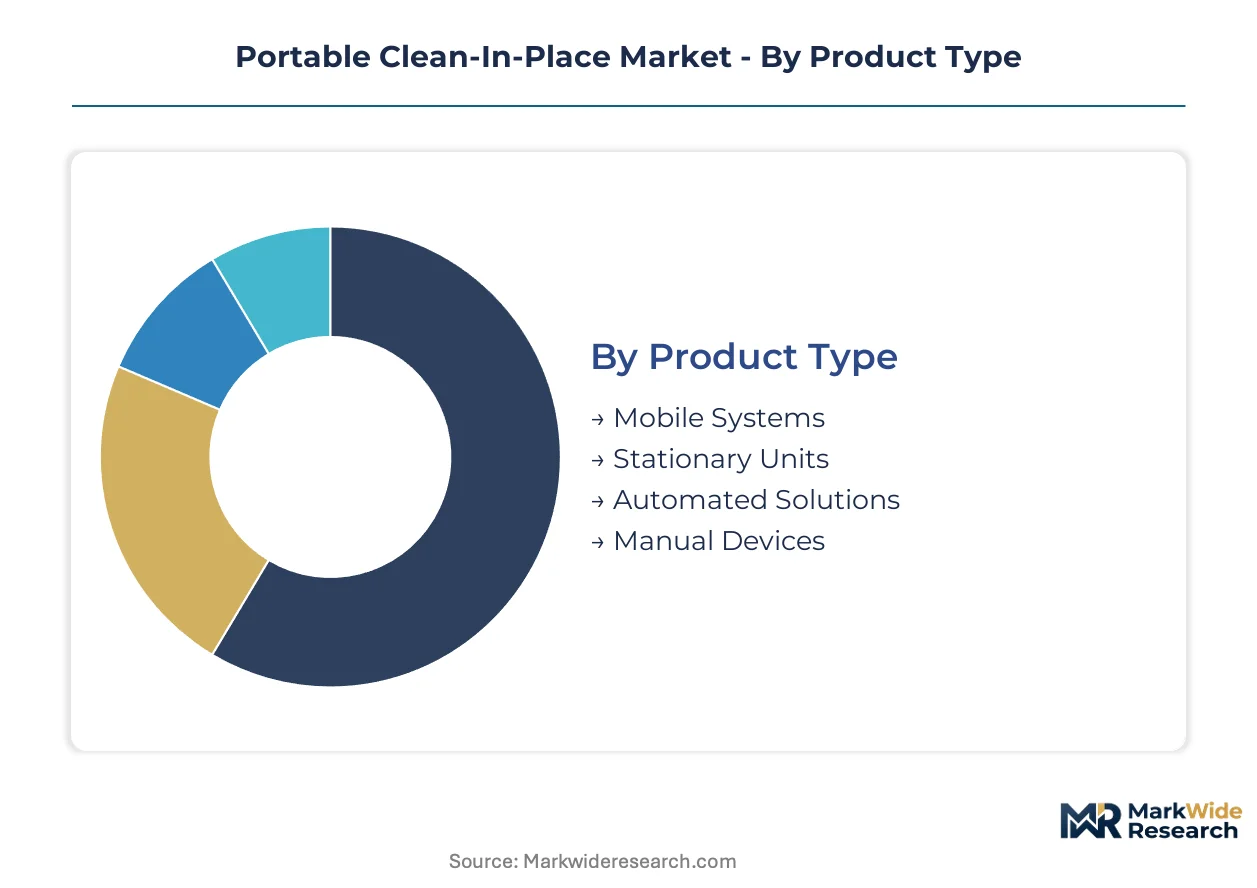
Portable CIP procurement splits sharply between capital-intensive automated installations and flexible mobile deployments. Understanding these segment boundaries reveals where margin pools concentrate and where vendor consolidation pressures build fastest.
Product Type:
Mobile Systems command volume leadership while Automated Solutions extract premium pricing through validation bundling.
- Mobile Systems:Self-contained skids with casters and quick-connect manifolds enable redeployment across production suites within the same facility. Pharmaceutical contract manufacturers in Germany and Ireland prioritize these units to satisfy EU MDR documentation requirements without permanent line modifications.
- Automated Solutions:PLC-controlled units with integrated conductivity sensors and automated chemical dosing reduce operator intervention and generate continuous validation logs. FDA inspection protocols in the US are compressing procurement cycles toward these systems despite 40-60% capital premiums over manual alternatives.
- Stationary Units:Fixed-installation systems serving single production lines with dedicated tank and pump configurations.
- Manual Devices:Basic pressure-fed spray balls and portable tanks requiring operator-managed chemical mixing and timing.
Today's leader: Mobile Systems. Tomorrow's challenger: Automated Solutions.
Application:
Food Processing generates unit volume while Pharmaceutical Production sustains margin through regulatory complexity.
- Pharmaceutical Production:Biologics facilities in Massachusetts and North Carolina deploy sensor-verified CIP to release suites within four-hour windows. FDA cleaning validation protocols mandate documented repeatability that only automated systems satisfy.
- Food Processing:Dairy cooperatives in water-stressed Spanish regions adopt heat-recovery CIP circuits to halve freshwater consumption. Allergen elimination between batch runs drives replacement of manual washdown stations.
- Beverage Manufacturing:Mid-sized US Pacific Northwest breweries increasingly favor equipment-as-a-service contracts bundling chemical supply and sensor calibration.
- Chemical Processing:Aggressive solvent formulations demand 316L stainless construction with specialized gasket materials.
Food Processing anchors current procurement volumes. Pharmaceutical Production climbs fastest on regulatory tailwinds.
End User:
Direct manufacturers control specification while service intermediaries reshape ownership economics.
- Manufacturers:Own-operate models dominate pharmaceutical and dairy verticals where cleaning protocols are proprietary and batch documentation is legally mandated.
- Service Providers:Equipment-as-a-service contracts concentrate vendor risk on uptime guarantees and accelerate regional provider consolidation among mid-sized beverage operators.
- Distributors:Channel partners with technical service capabilities capture aftermarket revenue streams in fragmented brewery and specialty chemical markets.
- Research Laboratories:Small-batch flexibility requirements favor compact mobile units with rapid changeover protocols.
Manufacturers retain specification authority. Service Providers are gaining share fastest through balance-sheet-friendly contracting.
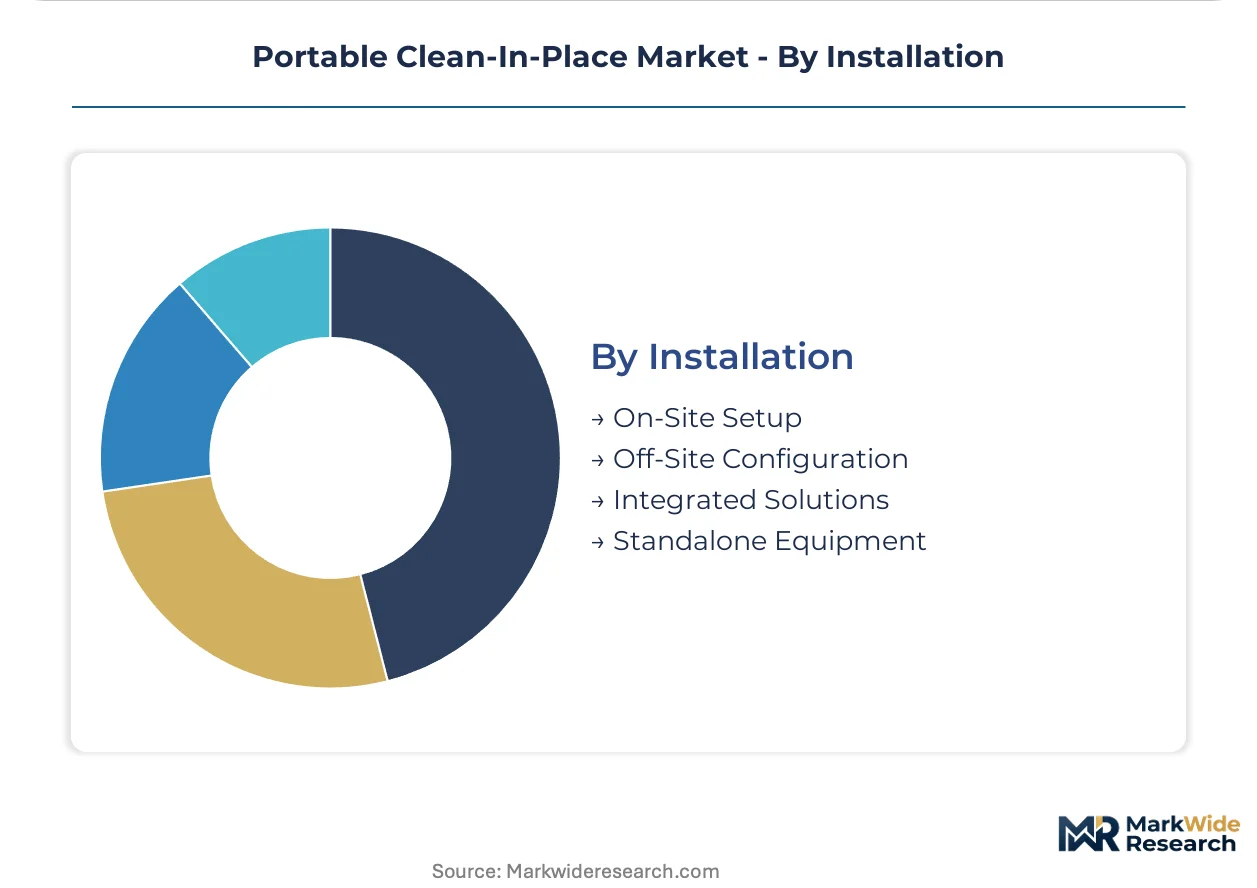
Installation:
On-Site Setup preserves customization while Integrated Solutions capture brownfield retrofit demand.
- On-Site Setup:Field-welded manifolds and location-specific tank configurations accommodate irregular plant layouts common in legacy dairy facilities.
- Integrated Solutions:Pre-engineered skids with SCADA compatibility modules address brownfield pharmaceutical plants struggling to connect modern PLCs to 1990s-era distributed control systems.
- Off-Site Configuration:Factory acceptance testing at vendor facilities reduces commissioning risk for greenfield pharmaceutical builds.
- Standalone Equipment:Plug-and-play units for temporary production campaigns and contract manufacturing overflow capacity.
On-Site Setup leads project counts. Integrated Solutions expand most quickly on legacy plant modernization demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hygienic equipment engineering cluster around Düsseldorf and Hamburg anchors portable CIP procurement volumes, with precision fabricators supplying validated skids to pharmaceutical and dairy processors across Western Europe.
United States
Biologics manufacturers in Massachusetts and North Carolina deploy sensor-verified CIP systems to compress batch release windows. FDA inspection protocols mandate documented cleaning repeatability that only automated skids satisfy. The Greater Boston corridor concentrates contract manufacturing demand for mobile units with rapid suite redeployment.
Germany
Dairy cooperatives in Bavaria and Baden-Württemberg adopt heat-recovery CIP circuits to halve freshwater consumption amid regional water stress. EU MDR framework compliance accelerates replacement of manual cleaning stations with validated automated systems. The Hamburg-Düsseldorf industrial belt hosts precision orbital welding capacity serving pan-European pharmaceutical builds.
India
Domestic pharmaceutical formulation facilities in Maharashtra and Gujarat expand CIP adoption to meet CDSCO GMP enforcement tightening. FSSAI allergen elimination mandates between batch runs drive replacement of manual washdown stations in dairy processing. The Mumbai-Pune corridor concentrates mid-sized skid demand from contract manufacturers serving export markets.
Saudi Arabia
SFDA tightened GMP enforcement creates first-mover opportunity for vendors offering Arabic-language validation documentation packages. Domestic pharmaceutical manufacturing expansion in Riyadh and Jeddah generates demand for automated CIP with integrated conductivity sensing. The King Abdullah Economic City zone attracts greenfield biologics investment requiring closed-system cleaning protocols.
Spain
Dairy processors in Catalonia and Andalusia prioritize water recovery circuits to address chronic regional scarcity. REACH restrictions on peracetic acid concentrations force reformulation toward enzyme-based chemistries with narrower temperature windows. The Barcelona-Tarragona cluster hosts technical service teams capable of absorbing extended revalidation cycles.
Portable Clean-In-Place Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular chemical dosing architectures and equipment-as-a-service contracting. The vendor base stratifies across three tiers: integrated hygienic equipment conglomerates with captive pump and valve technologies; specialized stainless-steel fabricators serving regional dairy and brewery markets; and disposable component suppliers addressing cell therapy production demands. Dominant competitive moves include vertical integration into precision orbital welding capacity and strategic bundling of chemical supply with sensor calibration services.
Among German-based engineering groups, GEA Group and Krones AG exemplify integrated equipment conglomerates with deep captive supply advantages in automated CIP skids. Alfa Laval occupies a position within the heat exchanger specialization archetype, extending recovery-efficient cleaning circuits into premium system configurations. Sani-Matic anchors North American demand as a stainless-steel fabrication specialist tailored to mid-sized dairy and brewery operators.
| Leading Market Players |
|---|
| GEA Group |
| Alfa Laval |
| SPX Flow |
| Krones AG |
| Tetra Pak |
| Sani-Matic |
| Millitec Food Systems |
| Central States Industrial |
| Melegari Technology |
| Others |
Value Network & Pricing Analysis
FDA-mandated cleaning validation documentation is compressing procurement cycles toward automated CIP skids, forcing suppliers to absorb ASME BPE-qualified welding premiums and sensor integration costs that filter through to capital premiums over manual alternatives.
Pricing Analysis
316L stainless steel tank fabrication costs swing with nickel supply disruptions, passing through to skid pricing within one to two quarters. Pricing stratifies across premium, standard, and economy tiers based on validation bundling and conductivity sensor integration. Cost compression in economy-tier mobile units is intensifying because Indonesian mining curbs feed nickel volatility. Contract pharmaceutical manufacturers show highest price sensitivity due to batch-volume variability, while biologics facilities prioritize uptime guarantees over capital expenditure.
Supply Chain Analysis
Domestic-content mandates in Saudi Arabia and India's PLI scheme for pharmaceutical manufacturing are reshaping sourcing toward localized stainless-steel fabrication and Arabic-language validation documentation. Precision orbital welding capacity clusters in Germany, Italy, and select North American hubs. Supply draws from nickel ore processing in Indonesia, 316L steel mills in Germany and Japan, and specialized pump casting in Denmark. Single-source vulnerability concentrates in precision welding technician certification. Distribution runs through OEM direct sales for pharmaceutical builds and regional service intermediaries for dairy and brewery verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The portable CIP market functions as a geographic-arbitrage play where EU MDR compliance costs in Germany and Ireland run double those in India's CDSCO-regulated facilities, creating margin expansion for vendors with modular validation documentation capabilities.
For Market Incumbents: To counter equipment-as-a-service entrants compressing capital-sale margins, GEA Group and Krones AG should deepen captive supply of pump and valve technologies while acquiring precision orbital welding capacity in North America to bypass Italian and German bottlenecks.
For New Entrants and Emerging Players: The forty-to-sixty percent capital premium gap between automated and manual systems opens white-space in mid-sized dairy cooperatives and US Pacific Northwest breweries. Target water-stressed Spanish regions with heat-recovery CIP circuits. Lead with equipment-as-a-service contracts bundling chemical supply and sensor calibration.
For Investors and Strategic Acquirers: Asymmetric upside sits with disposable manifold suppliers addressing cell therapy production demands. Five-to-ten year viability hinges on closed-system bioreactor cleaning protocols expanding beyond Massachusetts and North Carolina. Watch SFDA enforcement tightening in Saudi Arabia as inflection indicator for Arabic-language validation documentation demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Welding | Captive ASME BPE technician capacity bypasses Italian and German bottlenecks for North American pharmaceutical builds. |
| Equipment-as-a-Service Contracting | Per-cycle fee bundling preserves balance-sheet flexibility for mid-sized US Pacific Northwest breweries. |
| Heat Recovery Circuit Integration | Heat exchanger additions halve freshwater consumption for dairy processors in water-stressed Spanish regions. |
| Arabic-Language Validation Packages | SFDA GMP enforcement in Saudi Arabia creates first-mover advantage for compliant vendors in Riyadh and Jeddah. |
| Disposable Manifold Development | Single-use CIP components capture premium pricing tiers from closed-system bioreactor cleaning in cell therapy production. |
Research Methodology
Coverage spans Germany, the United States, India, Saudi Arabia, and Spain, with primary inputs from each market. The research combines interviews with pharmaceutical plant engineers, dairy cooperative technical directors, CIP system procurement managers, and aftermarket service heads with secondary validation from FDA warning letters, EMA GMP inspection databases, EU MDR technical documentation requirements, and trade flow data for 316L stainless steel. Bottom-up skid shipment tallies triangulate against top-down pharmaceutical and dairy capital expenditure estimates.
Granularity-level modeling operates at product-type, application, end-user, and installation-method dimensions, with additional disaggregation by regulatory compliance tier and water-stress geography. CAGRs derive from regression analysis of historical shipment patterns against pharmaceutical batch manufacturing growth and dairy processing capacity expansion. Key inputs include nickel price volatility indices, ASME BPE technician wage surveys, and equipment-as-a-service contract penetration rates.
Caveats apply where EPA effluent guideline revisions or REACH restrictions on peracetic acid could materially shift the outlook for chemical formulation costs and revalidation timelines. Forecasts reflect assumptions about stainless steel price stability and orbital welding capacity expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global Powder Processing Equipment Market
Food Processing Equipment
Fish Deboning Machine Market
Food Processing Equipment
Electric Brewing System Market
Food Processing Equipment
Pea Protein Processing Equipment Market
Food Processing Equipment
Dual-Ovenable Cook Trays Market
Food Processing Equipment
Pasteuriser Market
Food Processing Equipment
Plastic Processing Equipment Market
Food Processing Equipment
Frozen Food Processing Machinery Market
Food Processing Equipment
Commercial Tunnel Oven Market
Food Processing Equipment
Food Processing Blades Market
Food Processing Equipment
Global Food Sterilization Machines Market
Food Processing Equipment
Contact and Convective Dryers Market
Food Processing Equipment
Global Food Blenders and Mixers Market
Food Processing Equipment
Small Brewery Equipment Market
Food Processing Equipment
Nigeria Cocoa Processing Market
Food Processing Equipment
Global Food and Beverage Processing Equipment Market