
 Home Care Chemicals Market | 2026-2036
Home Care Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Home Care Chemicals Market Outlook
A skilled formulation chemist shortage across European and North American manufacturing hubs is unwinding capacity expansion timelines for specialty surfactant producers. BASF SE leverages its integrated ethylene oxide derivatives chain to sustain captive supply of key anionic intermediates. Evonik Industries AG anchors its position through R&D intensity in biosurfactant platforms, while Croda International Plc differentiates via lipid-based mild surfactants targeting premium fabric care segments.
Home care chemicals comprise functional ingredients—surfactants, builders, enzymes, fragrances, and preservatives—blended into formulations that reduce surface tension, suspend soils, or modify fabric texture, typically manufactured through batch sulfonation, ethoxylation, or enzymatic catalysis processes to achieve specific active concentrations and pH stability for consumer safety. Surface cleaners and laundry detergents occupy the largest volume positions within product type segmentation, though concentrated containers and eco-friendly grades are capturing disproportionate margin expansion as refill economics and biobased certification reshape household purchasing patterns.
REACH in Europe, EPA Safer Choice in the United States, and China's GB standards collectively tighten permissible preservative chemistries and mandate biodegradability thresholds, forcing reformulation cycles that favor suppliers with regulatory affairs depth. The EU Green Deal's chemical sustainability targets are accelerating substitution pressure on petrochemical-derived builders. Stakeholders must monitor how divergent national biobased labeling standards reshape export competitiveness and raw material qualification costs.
Market Dynamics
Concentrated formulation economics are compressing packaging intensity and freight costs while forcing raw material suppliers to requalify active chemistries for higher potency stability. Residential cleaning service networks now specify bulk concentrate procurement, rewiring traditional retail-centric distribution architectures toward institutional supply contracts.
Growth Catalysts
- EU Green Deal chemical sustainability targets:Mandatory substitution timelines for petrochemical-derived builders are accelerating biobased qualification programs among European formulators.
- Urban household formation in Southeast Asia:Rapid apartment construction in Vietnam, Indonesia, and the Philippines is absorbing disproportionate volume growth for surface cleaners and laundry detergents.
- Enzymatic catalysis platforms:Cold-water wash enzymes are reducing energy consumption requirements and enabling reformulation with lower surfactant loads.
Market Restraints
- Ethylene oxide supply concentration:Captive production of this anionic intermediate concentrates among integrated petrochemical majors, constraining independent surfactant manufacturers.
- REACH surfactant disclosure thresholds:ECHA's tightening data requirements are extending registration timelines and elevating compliance expenditures for specialty chemical importers.
- Petrochemical feedstock volatility:Crude-linked ethylene and propylene pricing swings are compressing margin predictability for alkoxylate producers.
Strategic Opportunities
- Refill station networks in Germany:Packaging-free retail formats are creating direct-to-consumer channels that bypass conventional supermarket shelf-space constraints.
- GB standards biodegradability mandates:China's national standards are opening qualification pathways for biosurfactant suppliers with documented aquatic toxicity profiles.
- Smart dosing dispenser convergence:IoT-enabled dispensing hardware paired with subscription concentrate refills is locking in recurring revenue models.
Industry Challenges
- Formulation chemist scarcity:European and North American manufacturing hubs face acute talent gaps in surfactant synthesis and stability testing.
- Reformulation cycle compression:Divergent national biobased labeling standards are forcing parallel qualification tracks for export-bound products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Care Chemicals Market |
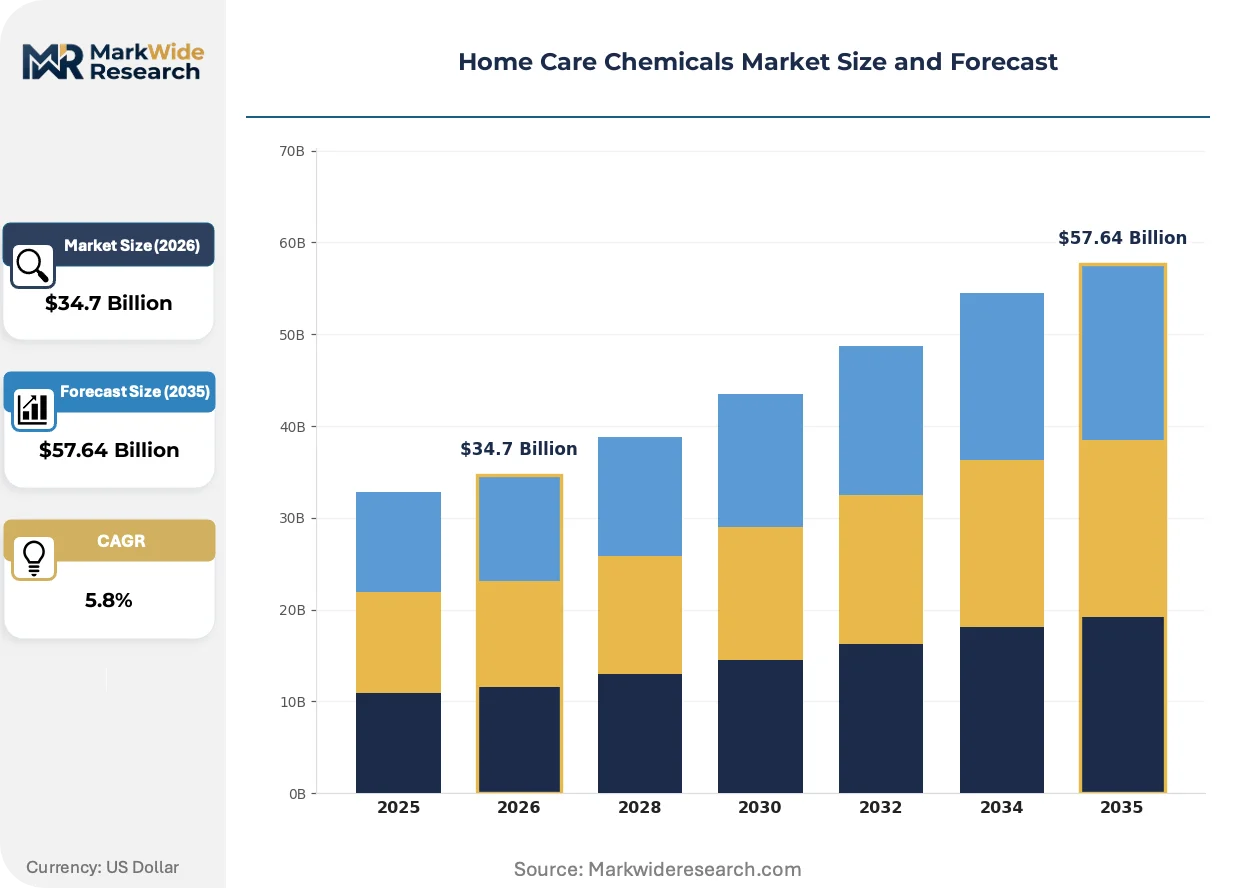
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $57.64 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Cleaners, Laundry Detergents, Dishwashing Liquids, Fabric Softeners Application: Household Cleaning, Fabric Care, Dish Care, Personal Care Grade: Industrial Grade, Commercial Grade, Consumer Grade, Eco-Friendly Packaging Type: Bulk Packaging, Single-Use Packs, Spray Bottles, Concentrated Containers |
| Companies Covered | BASF SE, The Lubrizol Corporation, Evonik Industries AG, Clariant AG, Akzo Nobel N.V., The Dow Chemical Company, Croda International Plc, Ashland Inc., Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Care Chemicals Market Strategic Shifts
Active chemistry platforms are splitting into high-performance synthetic routes and certified-biobased alternatives, with formulation houses now maintaining parallel development pipelines to serve divergent customer specifications.
Biosurfactant technology is bifurcating the surfactant procurement landscape. Rhamnolipid and sophorolipid platforms deliver comparable foaming and emulsification to petrochemical analogs. Premium fabric care brands in Germany and France are adopting these chemistries at accelerated qualification cycles. The market is compressing mid-tier synthetic surfactant volumes while expanding price-separated tiers.
EPA Safer Choice certification requirements are tightening preservative chemistry permissible lists. Formulators must substitute isothiazolinone biocides with alternative preservation systems. Laundry detergent and hard surface cleaner segments face the most acute reformulation pressure, with US-based manufacturers accelerating phenoxyethanol and organic acid trials.
Refill economics are reshaping household purchasing patterns. Concentrate containers and bulk dispensing formats are displacing unit-dose pods in environmentally positioned consumer segments. German and Dutch retail channels exhibit the most visible adoption velocity, with dedicated refill aisles expanding floor space allocation.
Home Care Chemicals Market Segmentation
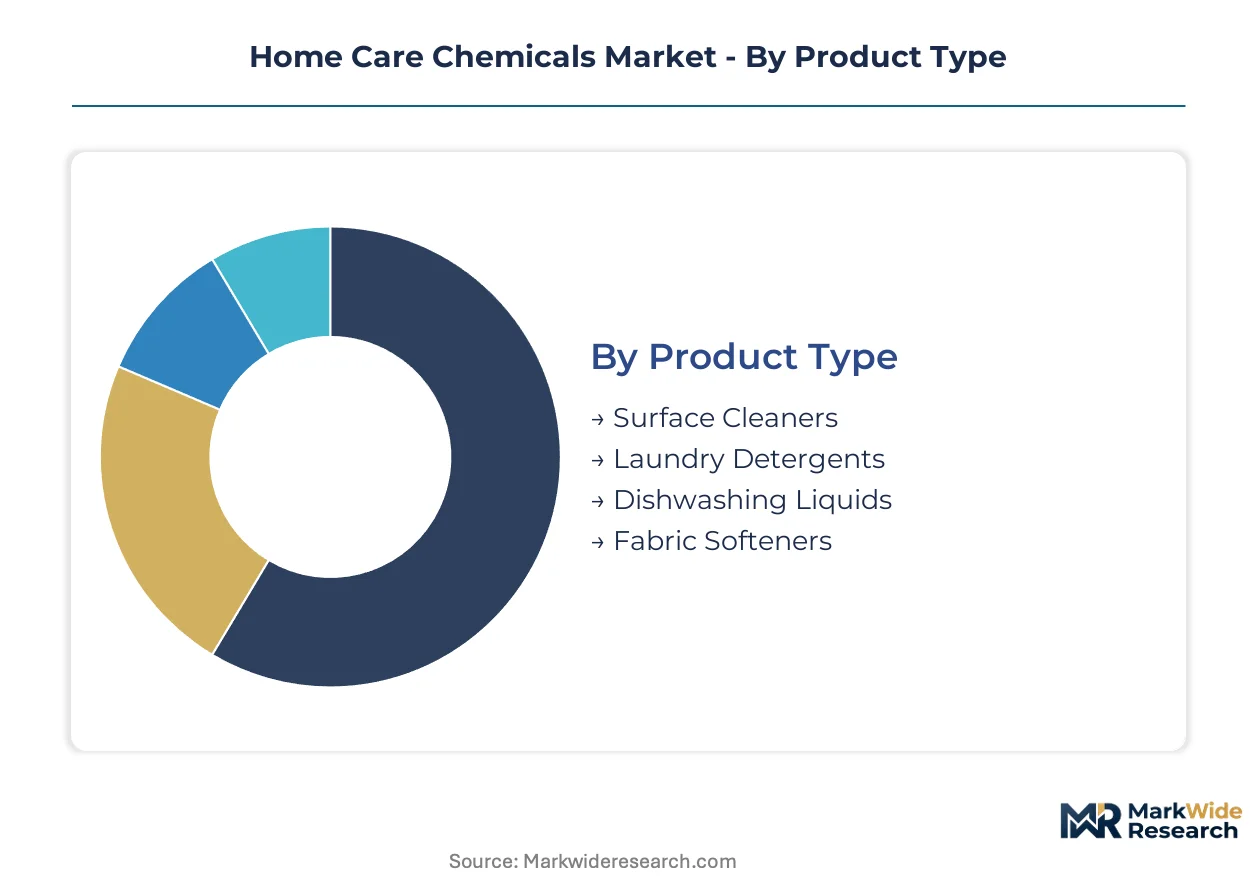
Home care chemicals flow through divergent channel architectures depending on formulation concentration, regulatory certification, and end-use intensity. Segmentation clarity determines where suppliers must build regulatory affairs depth versus where scale manufacturing suffices.
Product Type:
Channel allocation splits sharply: surface cleaners and laundry detergents dominate mass retail and institutional procurement, while dishwashing liquids and fabric softeners concentrate in specialty retail and subscription direct-to-consumer models.
- Surface Cleaners:Comprise solvent-based, alkaline, and disinfectant formulations with pH stability requirements between 2 and 12. Residential cleaning service networks in Germany and the Netherlands now specify bulk concentrate procurement, rewiring distribution toward institutional supply contracts. REACH disclosure thresholds for surfactant content are extending registration timelines for import-dependent formulators.
- Laundry Detergents:Encompass anionic and nonionic surfactant blends with builder systems for water hardness management. Cold-water wash enzyme platforms are reducing energy consumption requirements in Southeast Asian urban households. China's GB standards biodegradability mandates are opening qualification pathways for biosurfactant suppliers with documented aquatic toxicity profiles.
- Dishwashing Liquids:High-foaming anionic surfactant systems with skin-mildness additives for manual wash applications.
- Fabric Softeners:Cationic surfactant and silicone emulsion formulations targeting textile fiber conditioning.
By volume, laundry detergents lead. By growth pace, surface cleaners are climbing the fastest.
Application:
Cost tier stratification separates commodity bulk supply from premium certified formulations across end-use segments.
- Household Cleaning:Hard surface and floor care applications driving concentrate adoption in German refill station networks.
- Fabric Care:Washing, conditioning, and stain removal functions with premium lipid-based mild surfactant differentiation.
- Dish Care:Manual and automatic dishwashing applications where EPA Safer Choice certification is tightening preservative chemistry requirements.
- Personal Care:Home-use cosmetic and hygiene applications with distinct regulatory pathways from institutional cleaning.
Fabric care commands premium pricing tiers. Household cleaning shows steepest expansion trajectory in concentrate formats.
Grade:
Margin structures widen between certified biobased qualifications and conventional petrochemical-derived supply.
- Industrial Grade:High-active formulations for commercial laundries and food processing facilities with bulk tanker delivery.
- Commercial Grade:Mid-concentration products for hospitality and institutional procurement with private label prevalence.
- Consumer Grade:Retail-packaged formulations with fragrance and aesthetic differentiation driving shelf-space competition.
- Eco-Friendly:Certified biobased and biodegradable formulations qualifying for EU Green Deal procurement preferences and EPA Safer Choice labeling.
Eco-friendly grade is gaining share fastest. Consumer grade still dominates absolute volume.
Packaging Type:
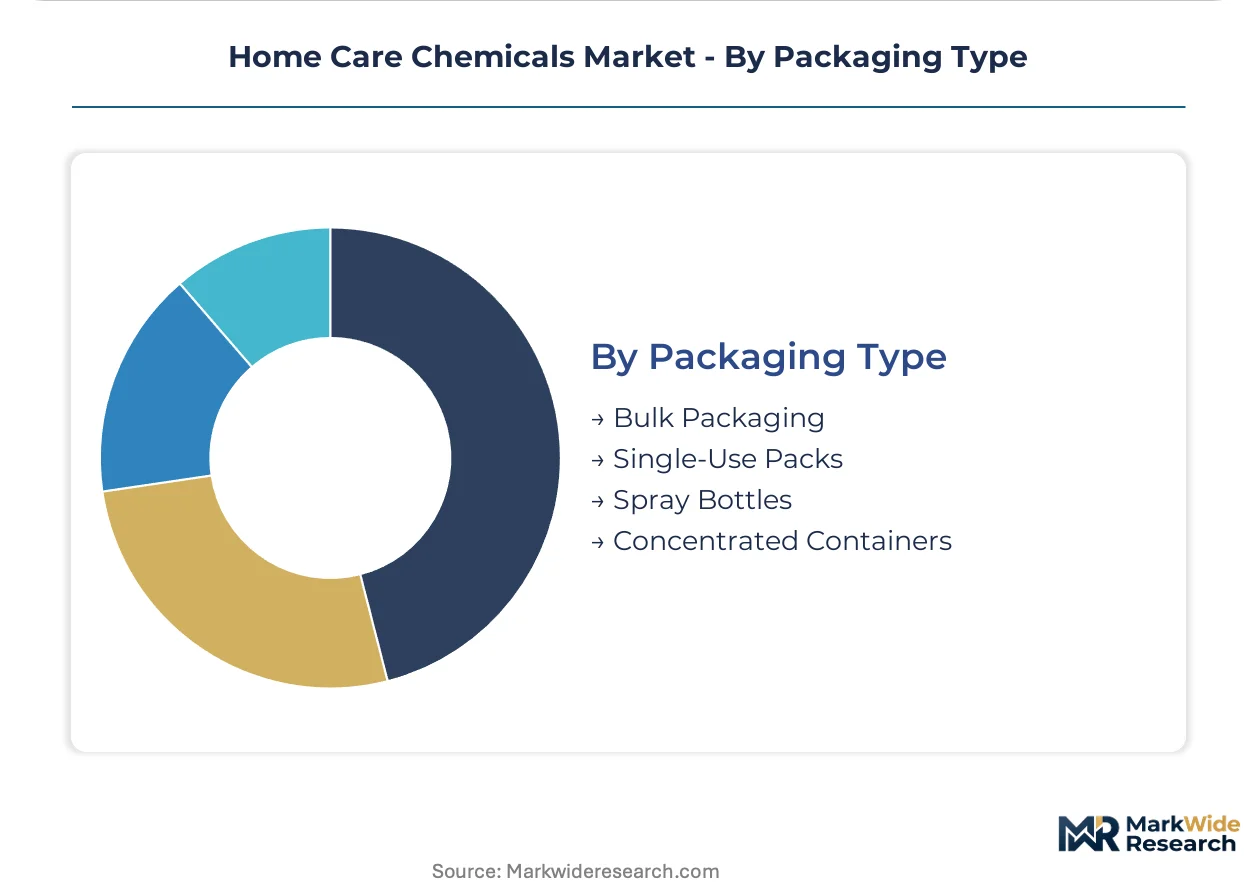
Supply concentration in ethylene oxide derivatives chains favors integrated producers of bulk and concentrate formats.
- Bulk Packaging:Drum and tote formats for commercial laundries and cleaning service networks with captive dispensing systems.
- Single-Use Packs:Pre-measured unit-dose formats facing displacement by refill economics in environmentally positioned consumer segments.
- Spray Bottles:Trigger-dispense packaging for hard surface cleaners with secondary packaging intensity under sustainability pressure.
- Concentrated Containers:Small-format refillable vessels paired with smart dosing dispenser convergence in subscription revenue models.
Concentrated containers are expanding most quickly. Bulk packaging retains largest volume position in institutional channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: German households prioritize refillable concentrate systems, while Southeast Asian markets absorb volume growth through first-time urban apartment formation. Regulatory stringency in the EU contrasts with China's GB standards enforcement, creating divergent qualification burdens for multinational suppliers.
Germany
Refill station networks in Berlin, Hamburg, and Munich are displacing conventional retail shelf-space allocation for pre-packaged formats. The EU Green Deal's chemical sustainability targets mandate substitution timelines for petrochemical-derived builders, forcing formulators to requalify biobased alternatives. The North Rhine-Westphalia chemical cluster around Leverkusen and Düsseldorf concentrates integrated surfactant production with captive ethylene oxide derivatives capacity.
United States
Residential cleaning service networks in Texas, Florida, and California specify bulk concentrate procurement, rewiring distribution toward institutional supply contracts. EPA Safer Choice certification tightens permissible preservative chemistries, accelerating phenoxyethanol and organic acid trials among Midwest formulators. The Gulf Coast petrochemical corridor maintains concentrated supply of anionic intermediates for domestic alkoxylate producers.
China
Urban household formation in the Yangtze River Delta and Pearl River Delta absorbs disproportionate volume growth for laundry detergents and surface cleaners. GB standards biodegradability mandates open qualification pathways for biosurfactant suppliers with documented aquatic toxicity profiles. The Shandong Peninsula chemical cluster around Qingdao and Yantai concentrates nonionic surfactant manufacturing for both domestic consumption and export qualification.
Vietnam
Rapid apartment construction in Ho Chi Minh City and Hanoi drives first-time purchaser demand for hard surface cleaners and fabric care formats. The country's national chemical regulator enforces import registration timelines that extend surfactant disclosure documentation for European and Japanese suppliers. The southern industrial zone around Bình Dương Province concentrates contract manufacturing for regional ASEAN distribution.
France
Premium fabric care brands in Paris and Lyon accelerate qualification cycles for rhamnolipid and sophorolipid biosurfactant platforms. ECHA's REACH framework tightens surfactant disclosure thresholds, extending registration timelines for specialty chemical importers. The Lyon chemical valley maintains R&D intensity in enzymatic catalysis platforms for cold-water wash applications.
Home Care Chemicals Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the former commanding captive supply of ethylene oxide derivatives and the latter competing on formulation services and biobased certification depth. The market structure rewards backward integration into anionic intermediates while penalizing pure-play surfactant manufacturers exposed to feedstock volatility. Two dominant archetypes emerge: integrated petrochemical majors with ethoxylation assets, and lipid-based specialty houses targeting premium fabric care segments. Competitive moves concentrate on M&A to secure enzymatic catalysis platforms and strategic partnerships to access refill station distribution channels.
Among Germany-based integrated chemical conglomerates, BASF SE anchors the captive supply archetype through its ethylene oxide derivatives chain, while Evonik Industries AG exemplifies R&D-intensive positioning in biosurfactant platforms. Croda International Plc, a UK-registered specialty chemical house, occupies a position within the lipid-based mild surfactant tier targeting premium certification requirements. These three entities represent divergent strategic vectors: upstream control over petrochemical intermediates, biotechnology platform development, and premium-grade qualification expertise.
| Leading Market Players |
|---|
| BASF SE |
| The Lubrizol Corporation |
| Evonik Industries AG |
| Clariant AG |
| Akzo Nobel N.V. |
| The Dow Chemical Company |
| Croda International Plc |
| Ashland Inc. |
| Huntsman Corporation |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day surfactant inventory cycles at European alkoxylate producers concentrate pricing power among integrated petrochemical majors with captive ethylene oxide supply, while independent formulators absorb margin compression from feedstock volatility.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between integrated producers and institutional cleaning service networks, while spot transactions persist for specialty surfactant imports subject to REACH registration delays. Price differentiation rests on biobased certification tier and volume scale, with EU Green Deal-compliant grades commanding premium positioning against conventional petrochemical-derived supply. Cost compression in mid-tier synthetic surfactants is intensifying as enzymatic catalysis platforms enable lower active-load formulations. Residential cleaning service networks exhibit lowest price sensitivity due to concentrate economics, while independent retail formulators face acute margin pressure from disclosure compliance burdens.
Supply Chain Analysis
Strategic stockpile preferences prevail among German and Dutch refill station operators buffering against ethylene oxide supply concentration, whereas Southeast Asian distributors maintain lean just-in-time inventories aligned with rapid urban household formation. Manufacturing gravity centers on Germany's North Rhine-Westphalia cluster, China's Shandong Peninsula, and the US Gulf Coast petrochemical corridor. Supply chains draw from ethylene oxide derivatives, palm kernel oil feedstocks, and enzymatic biocatalyst inputs. Single-source vulnerability concentrates in anionic intermediate production among integrated majors. Distribution runs through institutional supply contracts rewiring traditional retail-centric architectures toward bulk concentrate procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription concentrate refill models and smart dosing dispenser hardware represent a service-attach opportunity expanding faster than base surfactant chemistry sales, locking in recurring revenue through IoT-enabled household dispensing systems.
For Market Incumbents: Consolidate backward integration into ethylene oxide derivatives capacity to defend against feedstock volatility eroding alkoxylate margins, while accelerating biosurfactant platform R&D to preempt EU Green Deal substitution mandates. Captive supply of anionic intermediates remains the critical lever for margin defense as REACH disclosure timelines extend for import-dependent competitors. For New Entrants and Emerging Players: EPA Safer Choice certification fast-track offers entry into US institutional procurement channels tightening permissible preservative chemistries, with phenoxyethanol and organic acid preservation systems representing the most penetrable white-space. Target refill station networks in Germany and the Netherlands where packaging-free retail formats bypass supermarket shelf-space barriers. Lead with direct-to-consumer subscription models paired with smart dispensing hardware to establish recurring revenue before scaling manufacturing. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates spinning non-core surfactant assets lacking biobased certification depth or enzymatic catalysis capabilities. Five-to-ten-year viability favors specialists with documented aquatic toxicity profiles qualifying for China's GB standards biodegradability mandates. Monitor divergence between national biobased labeling standards as the inflection signal forcing parallel qualification tracks and elevating regulatory affairs depth as acquisition premium driver.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide Derivatives | Captive anionic intermediate supply insulates margin from crude-linked feedstock volatility at integrated German and US Gulf Coast producers. |
| Biosurfactant Platform Acquisition | Rhamnolipid and sophorolipid R&D capabilities secure EU Green Deal qualification pathways ahead of petrochemical builder substitution timelines. |
| Refill Station Distribution Partnership | Direct-to-consumer channels in Berlin and Hamburg bypass conventional retail shelf-space constraints for concentrate container formats. |
| Enzymatic Catalysis Scale-Up | Cold-water wash enzyme production reduces surfactant active loads for Southeast Asian urban household energy efficiency requirements. |
| Smart Dosing Hardware Integration | IoT-enabled dispenser convergence locks in recurring subscription revenue models alongside concentrate chemistry supply contracts. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with formulation chemists, procurement leads at residential cleaning service networks, distribution channel partners, and regulatory affairs directors; alongside secondary validation through customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA registration databases. Bottom-up triangulation across surfactant grade volumes and top-down reconciliation against end-use consumption patterns ensured cross-verified outputs.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning grade tier, end-use application intensity, packaging format concentration, and regional production hub regulatory stringency. CAGRs were derived through trend extrapolation of enzymatic catalysis adoption rates and biobased certification penetration curves, with ethylene oxide supply concentration and REACH disclosure timeline extensions serving as key scenario variables.
Decision-makers should treat outputs as directional under assumptions of continued EU Green Deal enforcement and stable crude-linked feedstock pricing; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as China's GB standards biodegradability mandates and US EPA Safer Choice preservative restrictions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Cleaning Nozzles Market
Cleaning Chemicals
North America Metal Cleaning Chemicals Market
Cleaning Chemicals
South Africa Cleaning Products Market
Cleaning Chemicals
Latin America Detergent Market
Cleaning Chemicals
Bio-Enzymatic Odor Control Chemicals for Restrooms and Waste Areas Market
Cleaning Chemicals
Eco-Label Certified Cleaning Chemicals for Professional Users Market
Cleaning Chemicals
Cleaning Products Market
Cleaning Chemicals
Concentrated Laundry Powder Market
Cleaning Chemicals
Fragrance-Free Cleaning Chemicals for Sensitive Environments Market
Cleaning Chemicals
Korea Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Metal Polish Products Market
Cleaning Chemicals
Mastic Remover Market
Cleaning Chemicals
Instrument Detergents for Manual Cleaning Market
Cleaning Chemicals
Instrument Cleaners and Detergents Market
Cleaning Chemicals
Multi-Residue Detoxifying Field Wash Aid Market
Cleaning Chemicals
Soap and Detergent Market