
 Liquid Applied Membranes Market | 2026-2036
Liquid Applied Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Applied Membranes Market Analysis
Specialty distributor networks for commercial roofing is tilting toward direct manufacturer partnerships in key construction corridors. Sika AG leverages its integrated supply chain across European waterproofing channels to sustain specification loyalty among tier-one contractors. BASF SE anchors its position through captive resin production that feeds formulated membrane systems. Mapei S.p.A. competes on application training infrastructure that locks in applicator preference across Mediterranean markets.
Liquid applied membranes constitute fluid-applied, fully adhered waterproofing systems that cure in situ to form seamless elastomeric barriers typically ranging from 1.5 to 3.0 mm dry film thickness, with elongation properties exceeding 300% for polyurethane chemistries. These systems serve primarily to eliminate joint-dependent leakage paths in complex geometries where sheet membranes prove impractical. Polyurethane formulations command the dominant value share due to superior tensile strength and chemical resistance in exposed roofing applications, while acrylic systems represent the fastest-expanding category driven by water-based formulations and cool-roof reflectivity compliance. Bituminous technology retains mature volume in below-grade waterproofing where cost sensitivity dominates, though margin pools increasingly shift toward silicone hybrids specified for façade restoration with service life guarantees exceeding 25 years.
Germany's ECHA REACH framework restricts hazardous substance content in construction chemicals, while the EU Green Deal's embodied carbon thresholds reshape product certification requirements across member states. China's MEE enforces VOC emission standards for building materials in 15 key cities, and India's BIS mandates performance testing for liquid membranes used in infrastructure projects. Stakeholders must monitor divergence between regional chemical compliance regimes and invest in formulation platforms that span multiple regulatory jurisdictions without SKU proliferation.
Market Dynamics
Water-based polyurethane and silicone hybrid formulations are compressing solvent-based market share as regulatory pressure intensifies across major construction corridors, forcing reformulation investments that reshape competitive economics.
Growth Catalysts
- ECHA REACH restrictions:Germany's solvent-VOC limits accelerate specification of low-emission acrylic and polyurethane systems in commercial roofing and below-grade applications.
- Green building certification:LEED and BREEAM point systems for cool-roof reflectivity drive water-based acrylic membrane uptake across North American and European commercial construction.
- Yangtze River Delta infrastructure:China's urban renewal and subway expansion programs concentrate waterproofing demand for seamless membrane systems in complex geometries.
Market Restraints
- MDI feedstock volatility:Polyurethane membrane margins compress when methylene diphenyl diisocyanate prices spike, squeezing mid-tier formulators without captive resin supply.
- Applicator certification scarcity:Proper installation of high-performance silicone hybrids requires trained crews, creating bottlenecks in markets with limited contractor training infrastructure.
- Sheet membrane substitution:Pre-fabricated TPO and EPDM systems retain cost advantage in simple roof geometries, limiting liquid applied penetration in price-sensitive segments.
Strategic Opportunities
- Façade restoration segment:Silicone hybrids with 25-year service guarantees open premium positioning in European heritage building envelope refurbishment.
- India infrastructure buildout:BIS-mandated performance testing for liquid membranes in metro rail and airport projects creates specification entry points for compliant suppliers.
- Direct contractor channels:Bypassing traditional distributor networks through manufacturer-applicator partnerships captures margin and specification control in concentrated construction corridors.
Industry Challenges
- Multi-jurisdiction formulation complexity:Divergent VOC limits between ECHA REACH, China's GB standards, and US EPA state-level rules force SKU proliferation without volume scale.
- Application quality control:Seamless membrane performance depends on film thickness uniformity and substrate preparation, creating warranty exposure where applicator training is inconsistent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Applied Membranes Market |
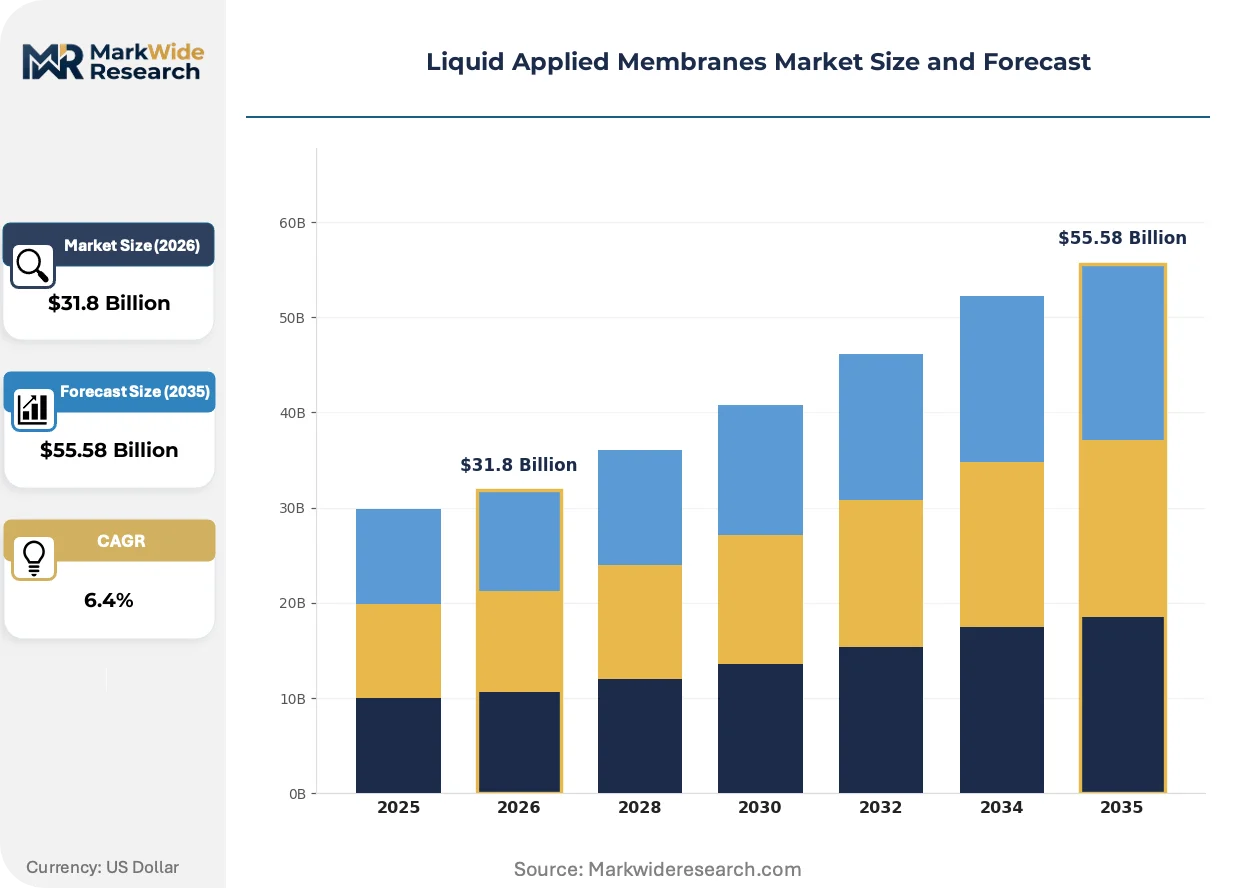
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $55.58 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bituminous, Polyurethane, Acrylic, Silicone Application: Roofing, Flooring, Water Proofing, Façade End User: Construction, Industrial, Residential, Infrastructure Technology: Spray, Roller, Brush, Manual |
| Companies Covered | Soprema, Saint-Gobain, Sika AG, Carlisle Companies, H.B. Fuller, BASF SE, Fosroc International, RPM International, Mapei S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Applied Membranes Market Emerging Trajectories
Formulation chemistry, regulatory compliance architecture, and procurement channel structure are simultaneously transforming how membrane systems reach end-use specifications and construction sites.
Two-component water-based polyurethane technology is rendering obsolete solvent-based systems in exposed roofing applications. Tier-one commercial contractors across Germany and the Netherlands now specify these formulations for green building envelopes. The shift compresses margins for formulators still dependent on solvent-borne resin platforms.
ECHA REACH substance restrictions and the EU Green Deal's embodied carbon thresholds are tightening certification requirements for construction chemicals sold across member states. Formulators must now document cradle-to-gate carbon intensity to maintain specification eligibility. German industrial refurbishment corridors show the most aggressive compliance timelines, with contractors demanding third-party verified environmental product declarations.
Specification authority is migrating from general contractors to specialty roofing applicators with direct manufacturer relationships. These trained crews now influence membrane system selection through performance guarantees and maintenance bundling. Mediterranean markets exhibit this shift most clearly, where applicator loyalty programs lock in recurring specification across multi-project portfolios.
Liquid Applied Membranes Market Segmentation
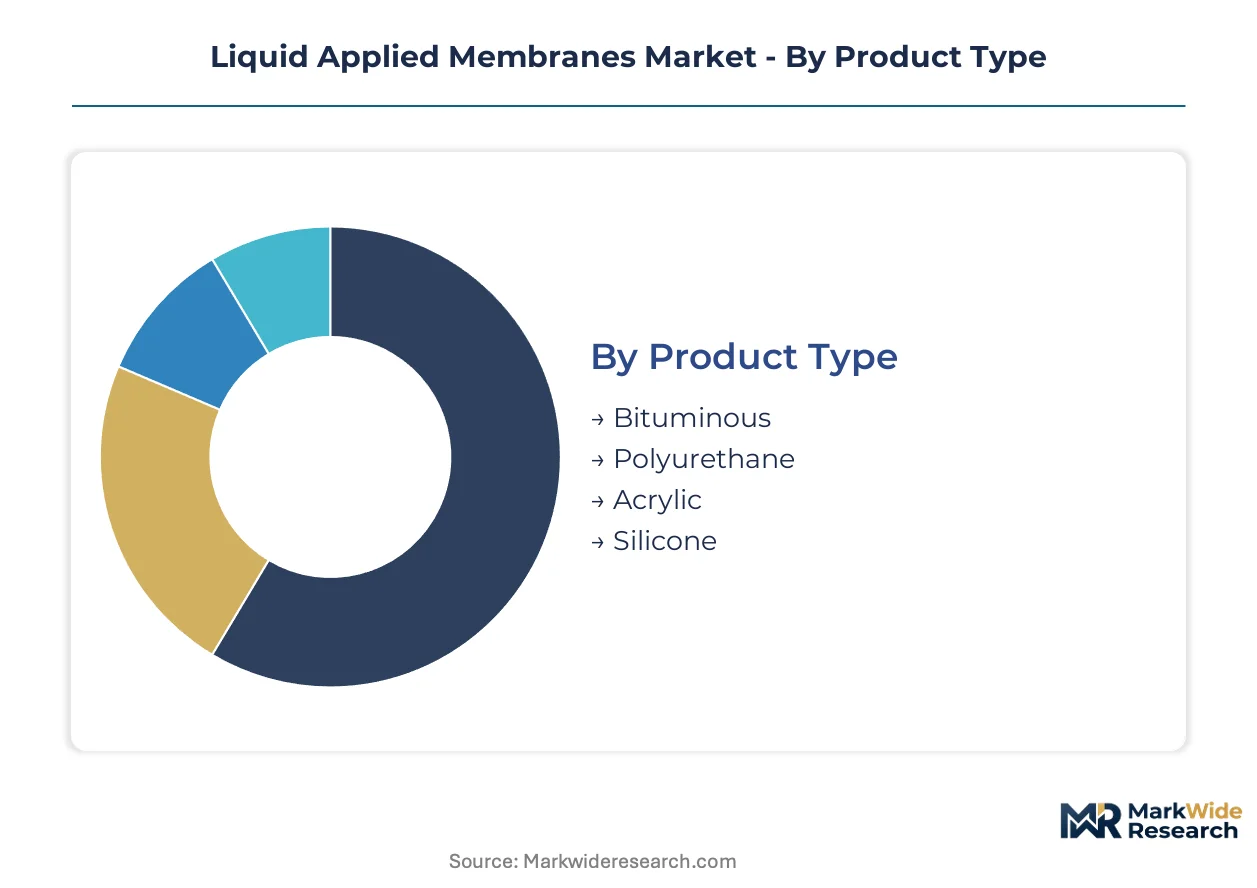
Liquid applied membrane demand fragments across four analytical dimensions: chemistry determines performance envelope, application defines installation complexity, end-user dictates specification authority, and technology governs labor economics. Each segmentation axis reveals distinct margin pools and competitive dynamics.
Product Type:
Polyurethane and silicone formulations anchor premium positioning through superior elongation and weathering resistance, while bituminous systems compete on first-cost economics in below-grade applications.
- Polyurethane:Two-component aromatic and aliphatic formulations deliver tensile strength exceeding 6 MPa with 300%+ elongation. Commercial roofing contractors in Germany and the Netherlands specify these systems for green building envelopes where ECHA REACH compliance is mandatory. MDI feedstock volatility compresses margins for non-integrated formulators.
- Acrylic:Water-based formulations with cool-roof reflectivity above 0.70 solar reflectance index dominate LEED and BREEAM point accumulation. Demand concentrates in North American commercial construction where utility rebate programs reward thermal performance. This segment climbs the fastest as VOC regulations tighten.
- Bituminous:Solvent-modified and emulsion systems retain mature volume in foundation waterproofing where cost sensitivity dominates specification.
- Silicone:Moisture-cure hybrids with 25-year service guarantees command premium positioning in European façade restoration and heritage building envelopes.
Established volume favors polyurethane; emerging adoption favors acrylic.
Application:
Roofing commands the dominant value share due to exposed service conditions and warranty complexity, while façade applications represent the steepest expansion trajectory driven by building envelope refurbishment cycles.
- Roofing:Exposed membrane systems must withstand thermal cycling, UV degradation, and ponding water. Specification concentrates in commercial and industrial new construction across China's Yangtze River Delta infrastructure belt. Complex geometries and penetration detailing favor fluid-applied systems over sheet membranes.
- Façade:Silicone hybrid membranes penetrate curtain wall restoration and heritage building envelope refurbishment. European contractors demand 25-year performance guarantees. Application quality control and film thickness uniformity create warranty exposure where applicator training is inconsistent.
- Water Proofing:Below-grade and wet-area applications prioritize hydrostatic pressure resistance and crack-bridging capability.
- Flooring:Industrial and commercial traffic-bearing surfaces require abrasion-resistant formulations with chemical spill tolerance.
Roofing generates the deepest specification relationships; façade commands the highest margin per square meter.
End User:
Construction sector procurement patterns vary sharply between general contractors, specialty applicators, and direct owner specifications, reshaping channel economics across each segment.
- Construction:Commercial and institutional building developers specify membrane systems through design-build contracts. Tier-one contractors in Mediterranean markets lock in recurring specification through applicator loyalty programs and maintenance bundling.
- Infrastructure:Metro rail, airport, and tunnel projects in India require BIS-mandated performance testing for liquid membranes. China's urban renewal programs concentrate waterproofing demand for seamless systems in complex geometries.
- Industrial:Manufacturing facilities and process plants prioritize chemical resistance and rapid return-to-service characteristics.
- Residential:Single-family and multi-family construction segments remain price-sensitive with limited specification sophistication.
Infrastructure delivers the longest contract tenors; construction offers the highest repeat-purchase frequency.
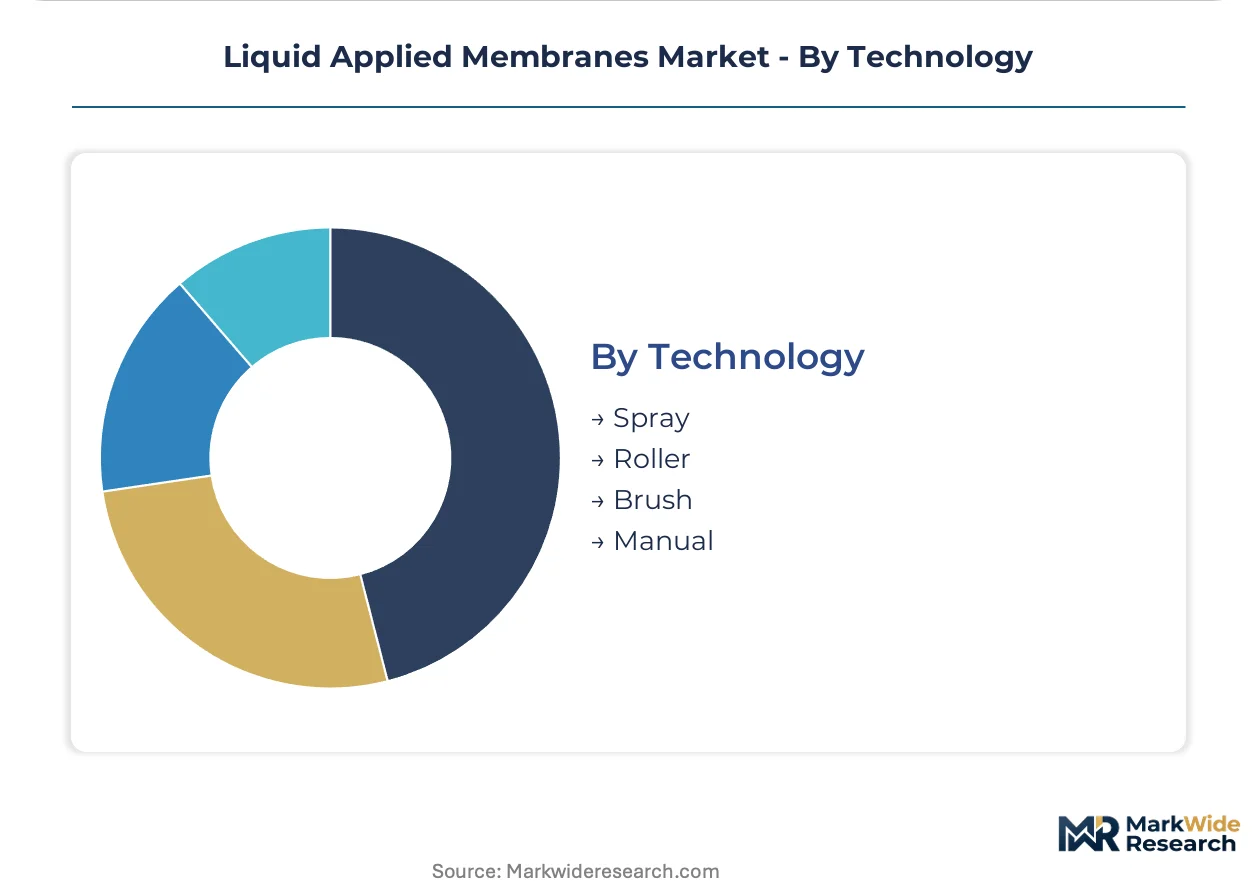
Technology:
Application method determines labor productivity, film thickness control, and substrate accessibility, with spray systems commanding premium equipment investment for large-scale deployment.
- Spray:Airless and plural-component spray equipment achieves 500+ square meters per crew-day on large roof decks. German and Dutch commercial roofing contractors specify spray-applied polyurethane for green building envelopes. Capital equipment requirements create barriers for small applicators.
- Roller:Conventional application suits detail work and confined spaces where spray overspray is prohibitive.
- Brush:Manual application persists in repair and maintenance contexts with limited area coverage.
- Manual:Trowel and squeegee methods retain relevance in thick-film buildups and complex geometries.
Spray technology captures the largest project scale; roller application retains the broadest contractor accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's subway expansion and Germany's industrial refurbishment corridor anchor liquid applied membrane demand in their respective hemispheres.
United States
Commercial roofing contractors specify water-based acrylic systems for LEED point accumulation across new construction. EPA state-level VOC rules tighten formulation requirements in California and Northeast markets. Dallas-Fort Worth and Atlanta construction corridors concentrate demand for spray-applied polyurethane on large roof decks.
Germany
Industrial envelope refurbishment drives specification of two-component water-based polyurethane systems. ECHA REACH substance restrictions mandate low-emission formulations across commercial and below-grade applications. The Rhine-Ruhr industrial belt concentrates waterproofing demand for seamless membrane systems in complex geometries.
China
Urban renewal programs and metro rail expansion concentrate demand for fluid-applied waterproofing in foundation and tunnel applications. MEE enforces VOC emission standards for building materials in 15 key cities including Shanghai and Nanjing. The Yangtze River Delta infrastructure belt generates the densest project concentration for seamless membrane systems.
India
Metro rail and airport projects create specification entry points for compliant liquid membrane suppliers. BIS mandates performance testing for liquid membranes used in infrastructure applications. Mumbai and Delhi-NCR construction corridors concentrate waterproofing demand in complex foundation geometries.
Netherlands
Green building envelope specifications accelerate adoption of water-based polyurethane systems in commercial construction. EU Green Deal embodied carbon thresholds reshape product certification requirements. The Randstad urban cluster concentrates demand for spray-applied systems on large-scale roofing projects.
Liquid Applied Membranes Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in resin and additive supply. The vendor base organizes around three tiers: multinational chemical conglomerates with captive raw material supply, regional formulators with applicator training infrastructure, and specialty distributors migrating toward direct manufacturer partnerships. Consolidation pressures concentrate among mid-tier formulators exposed to MDI feedstock volatility without backward integration. Capacity expansion and applicator certification programs represent the dominant competitive vectors.
Among European-based integrated suppliers, Sika AG, BASF SE, and Mapei S.p.A. occupy positions that exemplify distinct strategic archetypes. Sika AG represents the supply chain-integrated model spanning waterproofing channels. BASF SE anchors the captive resin production approach feeding formulated membrane systems. Mapei S.p.A. exemplifies the application training infrastructure model that locks in applicator preference across concentrated construction corridors.
| Leading Market Players |
|---|
| Soprema |
| Saint-Gobain |
| Sika AG |
| Carlisle Companies |
| H.B. Fuller |
| BASF SE |
| Fosroc International |
| RPM International |
| Mapei S.p.A. |
| Others |
Supply Flow & Price Mechanics
MDI resin concentration in Germany and China anchors margin distribution across formulated membrane tiers, with captive producers capturing value pools that escape non-integrated competitors during feedstock volatility cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates silicone hybrids with 25-year guarantees from water-based polyurethane systems and cost-optimized bituminous emulsions. Price differentiation hinges on certification grade under ECHA REACH and China's GB standards, plus volume scale in project procurement. Cost compression in the standard tier is intensifying because mid-tier formulators lack backward integration into MDI supply. Infrastructure contractors in India and China exhibit the highest price sensitivity, while European heritage restoration specialists accept premium positioning.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize procurement between tier-one formulators and specialty distributors across Mediterranean and North American construction corridors. Raw material sourcing draws from German and Chinese petrochemical complexes for isocyanates, plus Italian and Spanish additive specialists for silicone intermediates. Single-source vulnerability concentrates in MDI supply where three producers dominate European and Asian markets. Distribution runs through manufacturer-direct partnerships with certified applicators in Germany's Rhine-Ruhr belt and China's Yangtze River Delta infrastructure cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based polyurethane chemistry disruption is compressing solvent-based margins while ECHA REACH substance restrictions accelerate specification migration toward low-emission platforms.
For Market Incumbents: Insulate specification loyalty through captive resin production and applicator certification infrastructure that locks in recurring procurement across multi-project portfolios. BASF SE's integrated model demonstrates how backward integration into MDI supply defends margin compression during feedstock spikes. Prioritize EPD certification investment to maintain eligibility under EU Green Deal embodied carbon thresholds. For New Entrants and Emerging Players: Mid-market commercial roofing in India's Mumbai and Delhi-NCR corridors represents the most penetrable entry point given BIS-mandated performance testing that levels competitive qualification barriers. Water-based acrylic formulations for LEED point accumulation in North American utility rebate programs offer a second white-space target. Partner with regional distributors possessing established contractor training capacity rather than building applicator networks from zero. For Investors and Strategic Acquirers: Capital is best deployed toward regional formulators with applicator training infrastructure and demonstrated specification traction in concentrated construction corridors. Long-term viability in this market rests on formulation platforms that span ECHA REACH, China's GB standards, and US EPA state-level rules without SKU proliferation. Watch for MDI price inflection as the signal to assess integration economics for mid-tier targets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI Resin | Captive isocyanate supply insulates margin compression during feedstock volatility cycles affecting German and Chinese producers. |
| Applicator Certification Program Expansion | Trained crew networks lock in specification authority across Mediterranean markets where Mapei S.p.A. demonstrates infrastructure leverage. |
| EPD Certification Investment | Third-party verified environmental declarations maintain eligibility under EU Green Deal embodied carbon thresholds for Rhine-Ruhr contractors. |
| Direct Contractor Channel Partnerships | Bypassing distributor networks captures margin and specification control in China's Yangtze River Delta infrastructure belt. |
| Silicone Hybrid Formulation Platform | Moisture-cure chemistry with 25-year guarantees commands premium positioning in European heritage façade restoration segments. |
Methodological Framework
A spread of perspectives from commercial roofing contractors, waterproofing applicators, resin procurement managers, and EHS compliance officers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with tier-one contractors across Germany's industrial refurbishment corridor and China's Yangtze River Delta infrastructure belt. Secondary validation drew from ECHA substance restriction databases, China's MEE VOC emission filings, BIS performance testing protocols, and SEC disclosures from integrated chemical suppliers. Bottom-up project pipeline assessment and top-down construction spending analysis were triangulated against formulation chemistry adoption curves.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation modeled across chemistry type, application surface, end-use procurement pattern, and application technology. CAGRs were derived from project-level volume buildups aggregated to national construction forecasts. Industry-specific inputs included MDI price trajectory assumptions, green building certification penetration rates, and regulatory compliance timeline divergence between ECHA REACH and China's GB standards.
Macroeconomic conditions sit as an overlay; deviation in construction spending cycles, petrochemical feedstock pricing, or regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about specification migration speed and applicator training capacity expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Membrane Skinners Market
Membrane Materials
Nanofiltration Membrane Market
Membrane Materials
Membrane Filter Cartridge Market
Membrane Materials
Geosynthetic Clay Liner Market
Membrane Materials
Global Ceramic Membrane Market
Membrane Materials
Polyarylsulfone (PAS) Market
Membrane Materials
Membrane Polymers Market
Membrane Materials
Global Membrane Water and Wastewater Treatment Market
Membrane Materials
Global Medical Membranes Market
Membrane Materials
Expansion Vessel Membrane Market
Membrane Materials
SBS Modified Bitumen Membrane Market
Membrane Materials
Global Nanomembrane Market
Membrane Materials
North America Transparent Conductive Films Market
Membrane Materials
Specialty Breathable Membranes Market
Membrane Materials
Membrane Separation Market
Membrane Materials
Europe Gas Barrier Membrane Market