
 Hydrogen Sulphide Market | 2026-2036
Hydrogen Sulphide Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Sulphide Market Analysis
Sulphur dioxide scrubbing alternatives in metallurgical roasting are pivoting toward hydrogen sulphide-based reduction pathways, altering feedstock economics for sulphur producers. Linde leverages captive hydrogen networks to integrate hydrogen sulphide supply with on-purpose sulphuric acid output. Air Liquide sustains geographic dominance through pipeline-connected production hubs near Rotterdam and Antwerp refining corridors. Dow Chemical Company anchors North American demand via long-term offtake contracts tied to Gulf Coast petrochemical complexes.
Hydrogen sulphide is a colourless, flammable gas with the chemical formula H₂S, typically generated through the reaction of hydrogen with elemental sulphur or as a by-product of hydrocarbon processing; it serves primarily as a feedstock for sulphur and sulphuric acid production and as a reducing agent in metal extraction. Industrial grade material dominates volume flows into oil refinery sulphur recovery units, while reagent grade commands margin concentration from pharmaceutical and analytical laboratory buyers. Agricultural fertilizer application competes for supply with petrochemical offtake during seasonal planting windows in grain-producing regions.
EPA oversight under the Clean Air Act and OSHA permissible exposure limits constrain handling protocols and transport modalities for hydrogen sulphide across the United States. ECHA REACH registration requirements in Europe mandate comprehensive toxicity dossiers that raise compliance costs for importers and smaller blenders. Stakeholders must monitor regulatory divergence between EPA risk evaluations and EU CLP classification updates, as misaligned hazard communication rules threaten cross-border shipment fluidity and contract standardization.
Market Dynamics
EPA emissions standards under the Clean Air Act are forcing Gulf Coast refiners to upgrade sulphur recovery infrastructure, concentrating hydrogen sulphide demand in Texas and Louisiana corridor clusters.
Growth Catalysts
- Clean Air Act enforcement:Tightening EPA sulphur dioxide limits mandate Claus unit retrofits at US refineries, pulling hydrogen sulphide into sulphur recovery applications.
- Metallurgical roasting pivot:Sulphur dioxide scrubbing alternatives in copper and zinc smelting are adopting hydrogen sulphide-based reduction pathways, opening feedstock substitution.
- Rotterdam-Antwerp refining density:Pipeline-connected production hubs concentrate European offtake within a 150-kilometer industrial corridor, reducing logistics friction.
Market Restraints
- Elemental sulphur price volatility:Feedstock cost swings for on-purpose hydrogen sulphide production compress margin predictability for merchant suppliers.
- REACH dossier burdens:ECHA toxicity registration requirements raise fixed compliance costs for European importers and smaller blenders, consolidating importer tiers.
- Carbonyl sulphide substitution:Alternative sulphur carriers in some agricultural fumigation applications displace hydrogen sulphide volumes during price spikes.
Strategic Opportunities
- Pharmaceutical reagent grade:Analytical laboratory and API synthesis buyers command margin premiums above industrial grade, with limited qualified suppliers.
- India petrochemical buildout:Reliance Industries and Indian Oil are expanding refining capacity on the Gujarat coast, creating new offtake nodes without established supply contracts.
- Carbon capture integration:Hydrogen sulphide co-capture with CO₂ in amine-based acid gas removal systems enables dual-credit monetization at integrated complexes.
Industry Challenges
- Process safety technician scarcity:Hydrogen sulphide handling certification programs produce fewer qualified operators than Gulf Coast capacity expansion requires.
- Claus unit catalyst replacement cycles:Sulphur recovery unit turnarounds demand synchronized hydrogen sulphide supply continuity, straining just-in-time logistics.
- Cross-border hazard communication:Divergent EPA risk evaluations and EU CLP classification updates create documentation friction for Atlantic shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Sulphide Market |
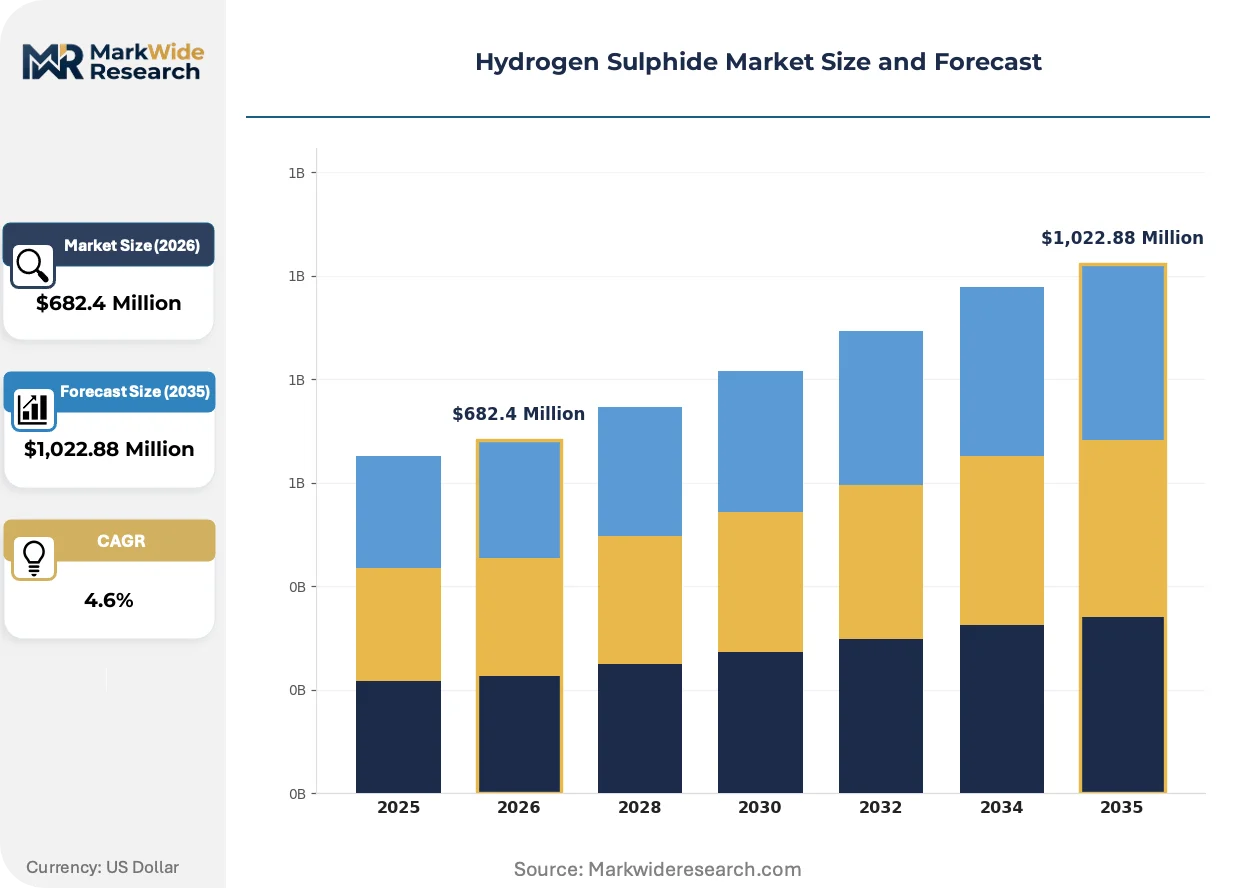
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,022.88 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Reagent Grade, Purity Grade, Laboratory Grade Application: Petrochemical Production, Metal Processing, Water Treatment, Agricultural Fertilizer End User: Chemical Manufacturers, Oil Refineries, Wastewater Treatment Plants, Agricultural Enterprises Distribution Channel: Direct Sales, Distributors, Online Platforms, Retail |
| Companies Covered | Air Liquide, Linde, Praxair, Messer Group, Matheson, SLB, Veolia, BASF SE, Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Sulphide Market Emerging Trajectories
Membrane separation technology and electrochemical sulphur recovery are reshaping how hydrogen sulphide is extracted, purified, and converted into merchantable products across refining and gas processing.
Membrane-based acid gas removal is expanding into offshore natural gas treatment platforms, replacing amine absorption trains. Operators in the North Sea and Gulf of Mexico are piloting polymeric membrane modules that cut footprint and solvent handling. The technology is expanding into floating production storage and offloading vessels where deck space constraints previously blocked conventional unit installation.
REACH registration deadlines for phase-in substances are compressing importer qualification timelines across European chemical supply chains. ECHA dossier completeness checks now average fourteen months, forcing hydrogen sulphide blenders to pre-commit tonnage bands before customer contracts finalize. German and Belgian downstream users are consolidating supplier panels to reduce audit duplication.
Long-term offtake contracting is displacing spot market purchases among Gulf Coast petrochemical buyers. Dow Chemical and LyondellBasell have shifted procurement toward five-year minimum-volume agreements with pipeline-connected producers. This pattern concentrates supplier risk on merchant traders while securing feedstock for integrated sulphuric acid output.
Hydrogen Sulphide Market Segmentation
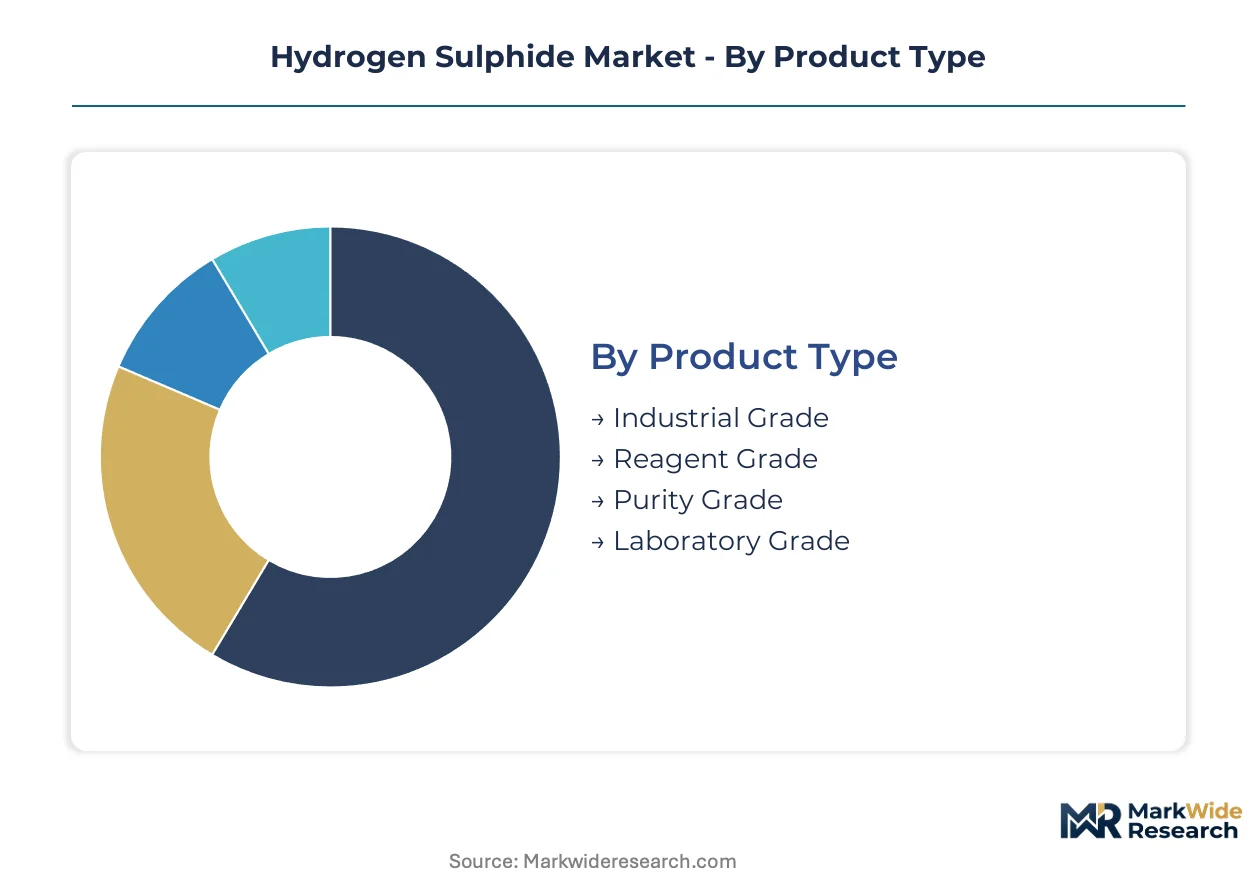
Segmentation in the hydrogen sulphide market reveals divergent margin structures across purity specifications and end-use applications. Product grade determines handling protocols and regulatory burden, while application mix shapes geographic demand clustering and contract duration.
Product Type:
Customization intensity rises sharply from industrial bulk supply to laboratory-certified batches, with specification tolerance tightening at each tier.
- Industrial Grade:Material meeting 99.5% minimum purity serves Claus sulphur recovery units and bulk chemical synthesis. Gulf Coast refineries in Texas and Louisiana consume the largest volumes under long-term pipeline contracts tied to sulphuric acid output.
- Reagent Grade:Higher purity material with documented impurity profiles supports pharmaceutical API synthesis and analytical method development. FDA inspection readiness requirements constrain the supplier base to qualified blenders with validated quality systems.
- Purity Grade:Intermediate specification material bridges industrial and reagent tiers for specialty chemical manufacturing. German and Belgian downstream users consolidate purchases to reduce ECHA audit duplication across supplier panels.
- Laboratory Grade:Small-batch certified material for research institutions and calibration standards. Procurement runs through specialized distributors with cold-chain handling capabilities.
Most installed capacity flows through Industrial Grade. Expansion is steepest in Reagent Grade.
Application:
Volume concentration versus margin capture splits this category between commodity offtake and specialized reduction chemistry.
- Petrochemical Production:Feedstock for on-purpose sulphuric acid and sulphur derivatives at integrated complexes. EPA Clean Air Act enforcement is pulling additional hydrogen sulphide into Claus unit retrofits across US refineries.
- Metal Processing:Hydrogen sulphide-based reduction pathways in copper and zinc smelting displace conventional sulphur dioxide scrubbing. Rotterdam-Antwerp refining corridor clusters concentrate European demand within pipeline-connected supply networks.
- Water Treatment:Precipitation agent for heavy metal removal in industrial effluent systems. Municipal procurement cycles favor lowest-qualified-bid suppliers, compressing margins.
- Agricultural Fertilizer:Sulphur nutrient source competing with elemental sulphur and sulphate salts. Seasonal planting windows in grain-producing regions create demand spikes that strain just-in-time logistics.
Petrochemical Production absorbs the highest tonnage. Metal Processing is climbing the fastest.
End User:
Integration depth separates captive producers from merchant market buyers, reshaping contract structures and pricing mechanisms.
- Chemical Manufacturers:Integrated sulphuric acid and derivative producers with backward control over hydrogen sulphide supply. Dow Chemical and LyondellBasell anchor North American demand through five-year minimum-volume agreements.
- Oil Refineries:Claus unit operators recovering sulphur from acid gas streams. Turnaround synchronization demands supply continuity that strains spot market availability.
- Wastewater Treatment Plants:Industrial effluent processors using precipitation chemistry. OSHA permissible exposure limits constrain on-site storage quantities, forcing frequent small-lot deliveries.
- Agricultural Enterprises:Sulphur nutrient applicators competing for supply during peak planting seasons. Carbonyl sulphide substitution displaces volumes during price spikes.
Chemical Manufacturers command the deepest integration. Oil Refineries are expanding offtake most rapidly.
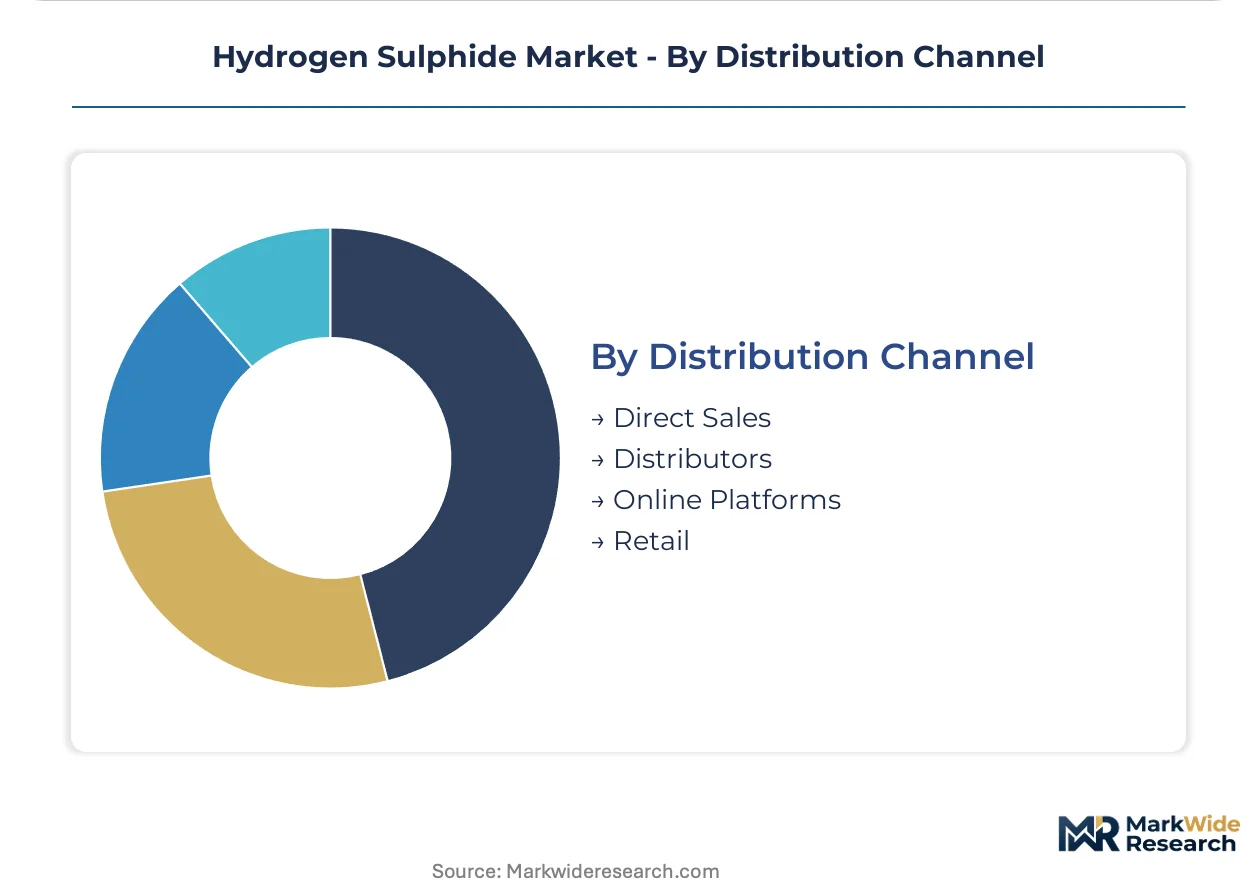
Distribution Channel:
Logistics complexity and hazard classification determine channel selection, with pipeline infrastructure dominating high-volume movements.
- Direct Sales:Pipeline-connected supply from production hub to integrated consumer. Linde leverages captive hydrogen networks to coordinate hydrogen sulphide delivery with on-purpose acid output.
- Distributors:Regional blenders and repackagers serving qualified industrial accounts. REACH dossier completeness checks averaging fourteen months are consolidating European importer tiers.
- Online Platforms:Small-lot procurement for research institutions and analytical laboratories. Limited to reagent and laboratory grades with documented chain-of-custody.
- Retail:Minimal presence given hazardous material handling certification requirements. Restricted to pre-mixed solutions and derivative compounds.
Direct Sales moves the highest volumes. Distributors are gaining share fastest in fragmented European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Coast petrochemical corridors in Texas and Louisiana anchor hydrogen sulphide consumption through dense refinery clustering and sulphur recovery unit expansion.
United States
EPA Clean Air Act enforcement mandates Claus unit retrofits at Gulf Coast refineries, pulling additional hydrogen sulphide into sulphur capture applications. OSHA permissible exposure limits constrain handling protocols across Texas and Louisiana processing facilities. Houston-Beaumont-Port Arthur corridor clusters concentrate pipeline-connected supply networks serving Dow Chemical and LyondellBasell complexes.
Germany
REACH registration requirements compress importer qualification timelines for hydrogen sulphide blenders serving pharmaceutical and specialty chemical sectors. ECHA dossier completeness checks averaging fourteen months force pre-commitment to tonnage bands before customer contracts finalize. BASF SE operations in Ludwigshafen and Leverkusen chemical parks anchor domestic offtake through backward-integrated sulphuric acid production.
Netherlands
Rotterdam-Antwerp refining corridor density creates pipeline-connected hydrogen sulphide demand within a 150-kilometer industrial zone. EU CLP classification alignment with EPA risk evaluations remains unresolved, threatening Atlantic shipment documentation fluidity. Port of Rotterdam storage and blending terminals serve as the primary European import node for merchant supply.
India
Reliance Industries and Indian Oil Corporation expand refining capacity on the Gujarat coast, creating new hydrogen sulphide offtake nodes without established supply contracts. BIS certification requirements for industrial gas imports raise qualification barriers for European and North American exporters. Jamnagar refinery complex represents the largest single emerging demand concentration in Asia-Pacific.
Saudi Arabia
SABIC integrated petrochemical complexes at Jubail and Yanbu consume captive hydrogen sulphide for on-purpose sulphur derivative production. SFDA industrial chemical registration requirements align with Gulf Cooperation Council standardization initiatives. Eastern Province gas processing infrastructure extracts acid gas streams for downstream sulphur recovery unit feedstock.
Hydrogen Sulphide Market Vendor Landscape
Global majors compete with regional champions across pipeline infrastructure and captive hydrogen network integration. Market structure tilts toward consolidated supply tiers where industrial gas incumbents control production hubs and merchant traders fill geographic gaps. Three archetypes dominate: integrated chemical producers with backward sulphur control, industrial gas specialists leveraging hydrogen co-production, and regional distributors managing REACH compliance for European importers. Capacity expansion along Gulf Coast corridors and strategic partnerships for Indian market entry represent the dominant competitive moves.
Within the industrial gas specialist tier, Air Liquide and Linde exemplify divergent geographic strategies. Air Liquide sustains European positioning through pipeline-connected production hubs near Rotterdam and Antwerp refining corridors. Linde leverages captive hydrogen networks to integrate hydrogen sulphide supply with on-purpose sulphuric acid output across North American complexes. Dow Chemical Company anchors demand-side concentration through long-term offtake contracts rather than merchant supply participation.
| Leading Market Players |
|---|
| Air Liquide |
| Linde |
| Praxair |
| Messer Group |
| Matheson |
| SLB |
| Veolia |
| BASF SE |
| Dow Chemical Company |
| Others |
Supply Flow & Price Mechanics
Membrane separation technology adoption across North Sea and Gulf of Mexico offshore platforms is compressing purification costs while concentrating supply control among industrial gas incumbents with proprietary module access. This dual effect tightens margin capture for merchant traders even as it secures feedstock economics for integrated producers with captive hydrogen networks.
Pricing Analysis
Elemental sulphur feedstock cost pass-through dominates hydrogen sulphide pricing, with contract-based long-term offtake structures displacing spot transactions among Gulf Coast petrochemical buyers. Price differentiation separates reagent grade certified for FDA inspection readiness from industrial bulk supply, with pharmaceutical and analytical laboratory buyers showing least price sensitivity. Cost compression in industrial grade is intensifying because REACH dossier burdens consolidate European importer tiers and reduce qualified supplier counts.
Supply Chain Analysis
Single-source vulnerability sits with Gulf Coast pipeline infrastructure concentrated in Texas and Louisiana, where Houston-Beaumont-Port Arthur corridor clusters anchor North American supply. Production draws from elemental sulphur, hydrogen feedstock, and amine-based acid gas removal systems. Tariff exposure threatens Atlantic shipment fluidity amid unresolved EPA-EU CLP classification divergence. Distribution runs through direct pipeline sales for integrated complexes and regional distributors managing REACH compliance for fragmented European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrogen sulphide functions as a stable compounder anchored by EPA Clean Air Act enforcement that mandates continuous Claus unit retrofits across US refineries. Regulatory-driven demand creates predictable offtake volumes resistant to cyclical downturns.
For Market Incumbents: Extend pipeline-connected capacity along Gulf Coast corridors to lock in Dow Chemical and LyondellBasell five-year minimum-volume agreements. Backward integration into captive hydrogen production protects margin position against elemental sulphur price volatility. Certification investment for pharmaceutical reagent grade creates defensive moats against carbonyl sulphide substitution threats in agricultural applications.
For New Entrants and Emerging Players: Enter via Gujarat coast petrochemical buildout where Reliance Industries and Indian Oil Corporation lack established supply contracts. Target pharmaceutical reagent grade in European markets where ECHA dossier completeness checks averaging fourteen months consolidate incumbent panels and create qualification gaps. Pursue joint venture structures with Indian distributors holding BIS certification for industrial gas imports.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors managing REACH compliance for European importers, where fixed dossier costs compress smaller blender margins. Long-term viability frames around carbon capture integration enabling dual-credit monetization at integrated complexes. Watch membrane separation technology adoption rates as inflection indicator for cost structure disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Gulf Coast pipeline-connected builds secure Dow Chemical and LyondellBasell offtake commitments. |
| Backward Integration | Captive hydrogen production shields Linde from elemental sulphur feedstock cost volatility. |
| Long-term Supply Agreement | Five-year minimum-volume contracts displace spot purchases among Rotterdam-Antwerp refining clusters. |
| Joint Venture | Indian market entry partnerships overcome BIS certification barriers for European exporters. |
| Green Manufacturing Transition | Carbon capture integration enables dual-credit monetization at amine-based acid gas removal facilities. |
Methodological Framework
Direct dialogue with plant managers at Gulf Coast refineries, procurement leads at downstream petrochemical complexes, distribution channel partners managing REACH compliance, and technical R&D directors at industrial gas specialists grounded qualitative findings. Secondary validation drew from EPA enforcement databases, ECHA registration filings, SEC 10-K disclosures, and customs trade records. Bottom-up capacity tallies and top-down demand estimates were triangulated to cross-check volume assumptions.
Bottom-up modeling tracked hydrogen sulphide across grade tier, end-use industry, and regional production hub dimensions over the projection horizon. Top-down approaches validated aggregate consumption against sulphuric acid output and Claus unit capacity. CAGRs were derived from segment-level volume trajectories weighted by purity-grade margin structures. Forecast inputs incorporated EPA Clean Air Act implementation timelines and membrane technology adoption curves.
Inputs from ECHA dossier status reports and EPA enforcement actions were available through the study window; gaps in Indian BIS certification pipeline data introduce uncertainty bands around Gujarat coast demand projections. Forecasts reflect assumptions about regulatory implementation pace and technology substitution thresholds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Molecular Sieve for Air Separation Market
Industrial Chemicals
Global Continuous Stirred Tank Reactors Market
Industrial Chemicals
Babassu Oil Market
Industrial Chemicals
Froth Flotation Chemicals Market
Industrial Chemicals
Process Fluid Market
Industrial Chemicals
Antiscalant Market
Industrial Chemicals
Aluminium Production Chemicals Market
Industrial Chemicals
Singapore Sealants Market
Industrial Chemicals
South Africa Lime Market
Industrial Chemicals
India Thermic Fluid Market
Industrial Chemicals
Global Foundry Chemicals Market
Industrial Chemicals
Ultra-High-Purity Lithium Bis(fluorosulfonyl)imide (LiFSI) Electrolyte Salt Market
Industrial Chemicals
Europe Starch Derivatives Market
Industrial Chemicals
6-KT Mother Liquor Market
Industrial Chemicals
Europe Surface Treatment Chemicals Market
Industrial Chemicals
Global Industrial Oils Market