
 Waterborne Polyurethane Dispersions for Automotive Synthetic Leather Market | 2026-2036
Waterborne Polyurethane Dispersions for Automotive Synthetic Leather Market Size, Share, and Industry Trends Forecast 2026-2036
Waterborne Polyurethane Dispersions for Automotive Synthetic Leather Market Insights
Buyer concentration among vehicle manufacturers is shifting as premium OEMs consolidate upholstery sourcing while electric vehicle specialists fragment specifications across new tier-2 fabricators. Covestro leverages its polyether-based dispersion portfolio to anchor supply relationships with German automotive seating suppliers. BASF competes through backward integration into aliphatic isocyanate precursors, sustaining cost advantages in polyester-based formulations. Wanhua Chemical Group dominates Asia-Pacific supply through captive MDI production and localized dispersion capacity in Ningbo.
Waterborne polyurethane dispersions for automotive synthetic leather constitute aqueous colloidal systems of polyurethane particles, typically 50-200 nanometers in diameter, stabilized by internal ionic or non-ionic groups and applied via direct coating or transfer processes to polyester or polyamide textile substrates to achieve abrasion resistance exceeding 100,000 Martindale cycles. Polyester-based product types lead current volume owing to hydrolysis resistance and cost efficiency in mass-market seating, while polycarbonate-based grades command margin pools in luxury segments requiring superior UV stability and low fogging performance. Emulsion polymerization technology occupies the largest process share, though solvent-free chain extension methods are gaining traction as OEMs tighten interior air quality specifications.
EPA regulations on hazardous air pollutants from coating operations and REACH restrictions on N-methyl-2-pyrrolidone usage are reshaping formulation requirements and cross-border material compliance obligations for suppliers serving multiple automotive manufacturing regions. China's MEE enforcement of GB standards on volatile organic compound emissions from coating processes is forcing domestic dispersion producers to accelerate waterborne technology transitions or face production curtailments. Stakeholders must monitor evolving OEM interior air quality protocols and regulatory divergence between jurisdictions to anticipate specification shifts and capacity allocation decisions.
Market Dynamics
REACH and EU Green Deal mandates on volatile organic compound emissions are accelerating solvent-to-waterborne technology transitions across European manufacturing, forcing dispersion producers to reconfigure formulation architectures and supply relationships with tier-1 seating suppliers.
Growth Catalysts
- REACH VOC restrictions:European coating operations face binding emission limits that eliminate solvent-based alternatives in automotive upholstery specifications.
- Aliphatic isocyanate advances:Improved light stability in waterborne systems enables exterior-grade synthetic leather applications previously reserved for solvent coatings.
- China's MEE enforcement:Domestic producers accelerating waterborne transitions to avoid production curtailments under GB standards on coating emissions.
Market Restraints
- Raw material concentration:MDI and polyether polyol supply concentrates among petrochemical majors in Germany and China, exposing formulators to input cost volatility.
- Drying energy intensity:Waterborne systems require substantially higher thermal energy for film formation compared to solvent alternatives, compressing margins in energy-price-sensitive markets.
- Performance gap in extreme climates:Hydrolysis resistance of polyester-based dispersions degrades faster than polycarbonate grades in high-humidity environments, limiting adoption in tropical vehicle specifications.
Strategic Opportunities
- India's automotive upholstery localization:PLI scheme incentives for component manufacturing create entry points for dispersion producers establishing compounding partnerships with domestic textile coaters.
- Aviation interior crossover:Fire-smoke-toxicity certification protocols from aircraft seating are migrating into premium electric vehicle cabin specifications, favoring polycarbonate-based dispersion grades with inherent flame retardancy.
- Direct-to-OEM digital specification platforms:Volkswagen's We Connect and similar systems enable real-time material qualification, bypassing traditional tier-1 gatekeeper relationships for specialized dispersion developers.
Industry Challenges
- Formulation chemist scarcity:Expertise in ionic stabilization mechanisms and particle size distribution control resides with aging technical workforces in Germany and Japan, constraining capacity expansion.
- Multi-jurisdiction compliance synchronization:Divergent EPA hazardous air pollutant rules, REACH substance restrictions, and China's GB standards force parallel formulation tracks that fragment R&D resources.
- Transfer coating line retrofits:Existing solvent-optimized equipment requires substantial capital modification for waterborne viscosity profiles and drying curves, slowing adoption at smaller tier-2 fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waterborne Polyurethane Dispersions for Automotive Synthetic Leather Market |
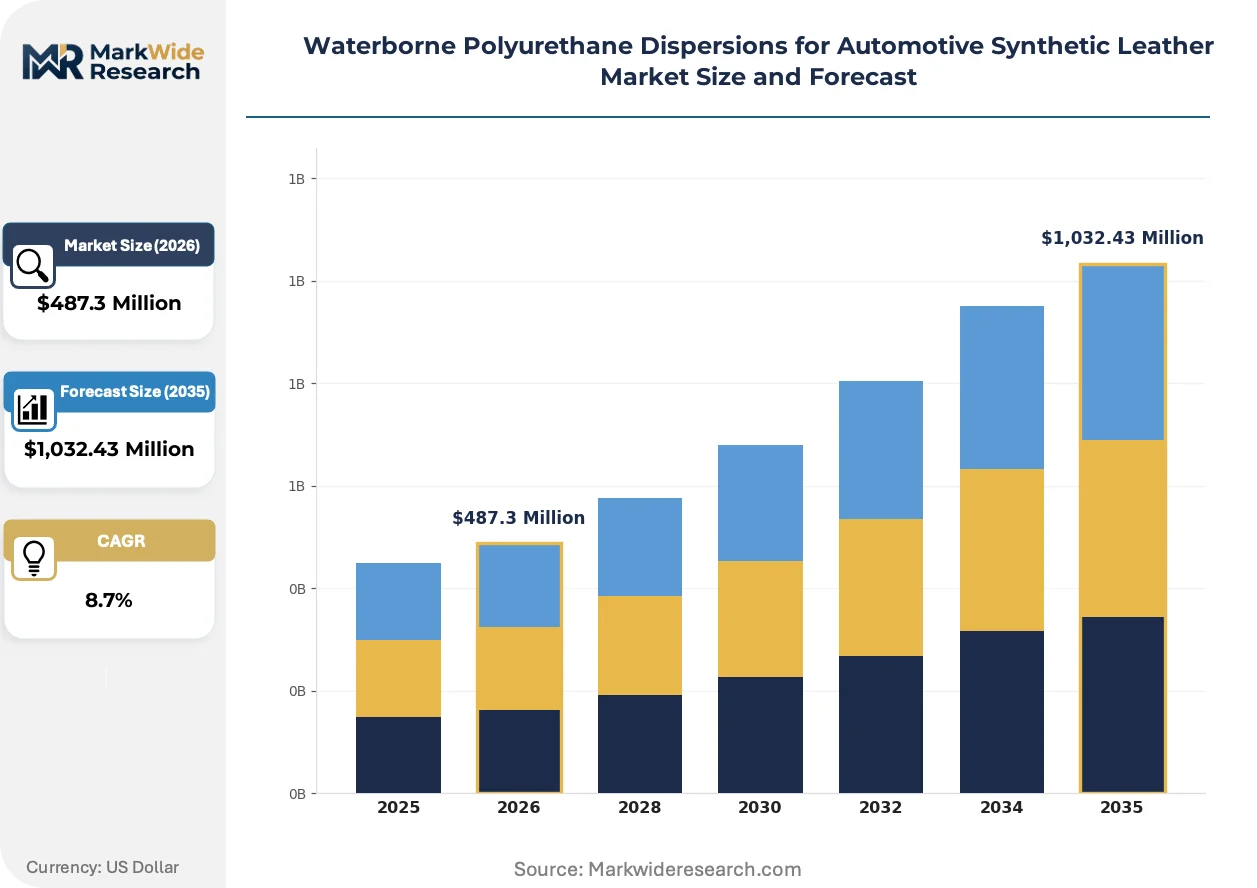
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyether-Based, Polyester-Based, Polycarbonate-Based, Hybrid Polyurethane Technology: Solvent-Free, Emulsion Polymerization, Dispersion Polymerization, Chain Extension Application: Automotive Upholstery, Footwear Components, Furniture Covering, Apparel Materials End User: Vehicle Manufacturers, Leather Goods Producers, Upholstery Fabricators, Apparel Brands |
| Companies Covered | Covestro, BASF, The Lubrizol Corporation, Wanhua Chemical Group, DIC Corporation, Mitsui Chemicals, Stahl Holdings, Dow, Huntsman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waterborne Polyurethane Dispersions for Automotive Synthetic Leather Market Trends and Innovations
Solvent-free chain extension methods are gaining traction as OEMs tighten interior air quality specifications, while polycarbonate-based grades command margin pools in luxury segments requiring superior UV stability and low fogging performance.
Polycarbonate diol-based polyurethane dispersions deliver exceptional hydrolysis resistance and optical clarity for instrument panel surfaces and steering wheel wraps. Premium German OEMs specify these grades for vehicles operating in high-UV environments. This chemistry is expanding into mass-market electric vehicle platforms as interior air quality protocols tighten.
EPA hazardous air pollutant regulations from coating operations and REACH restrictions on N-methyl-2-pyrrolidone usage are reshaping formulation requirements. Cross-border material compliance obligations now require dual-track qualification for suppliers serving multiple automotive manufacturing regions. European formulators are eliminating NMP entirely, while US operations face parallel state-level amendments to federal rules.
Buyer concentration among vehicle manufacturers is fragmenting as electric vehicle specialists distribute specifications across new tier-2 fabricators. Traditional tier-1 seating suppliers face disintermediation from direct OEM-materials relationships. This pattern concentrates in China where NIO, XPeng, and Li Auto operate decentralized upholstery sourcing models distinct from legacy joint-venture structures.
Waterborne Polyurethane Dispersions for Automotive Synthetic Leather Market Segmentation
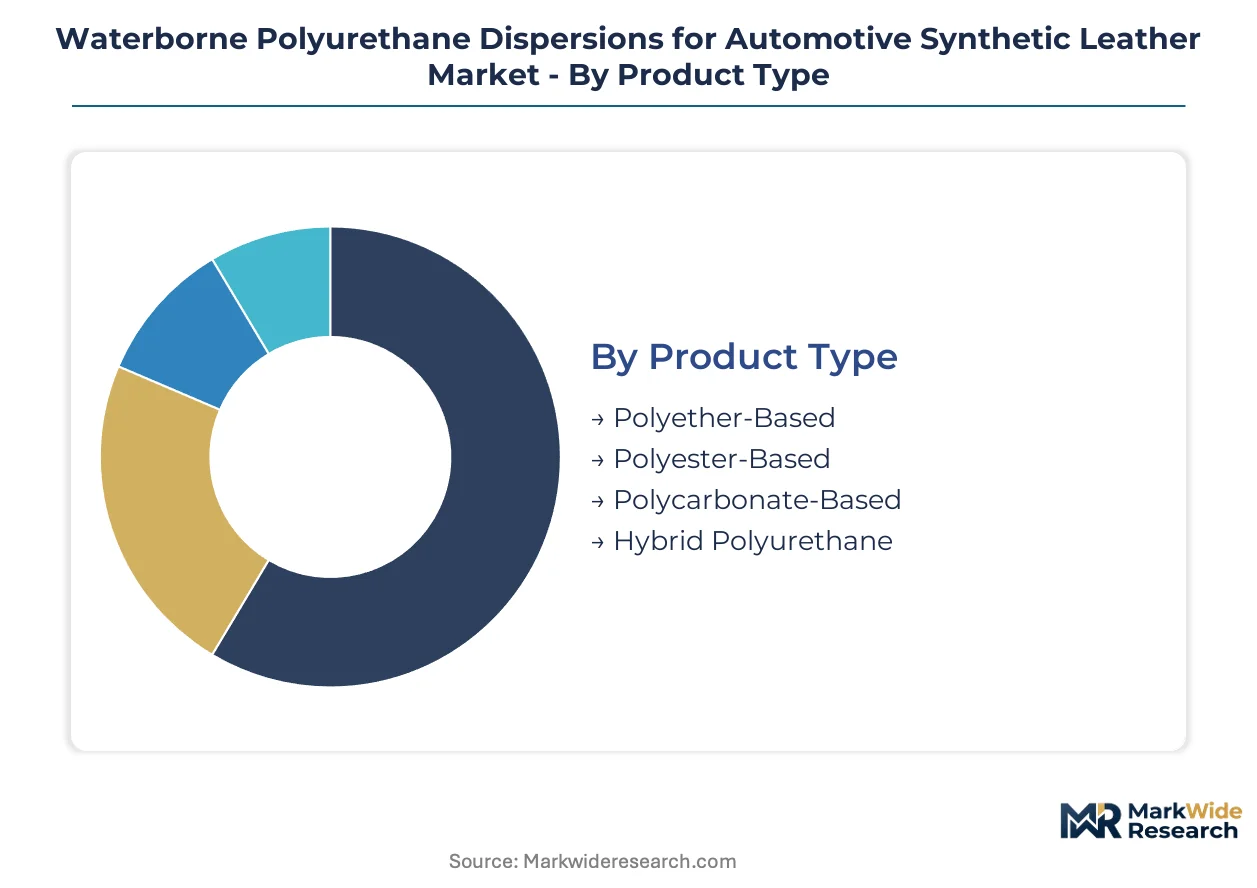
Segmentation in waterborne polyurethane dispersions reveals how formulation chemistry, production technology, and end-use specifications create distinct margin pools and technical barriers. Understanding these divisions exposes where procurement power concentrates and where new entrants can bypass entrenched supplier relationships.
Product Type:
Cost tier determines specification authority, with mass-market seating programs prioritizing hydrolysis resistance per dollar while luxury cabins trade up for optical clarity and fogging performance.
- Polyester-Based:Formulations built from adipic acid and glycol condensation deliver hydrolysis resistance exceeding industry baselines at moderate cost. Demand concentrates in German and Chinese mass-market seating where tier-1 suppliers face OEM price-down schedules.
- Polycarbonate-Based:Diol backbones derived from phosmine chemistry provide exceptional UV stability and low fogging for instrument panels and steering wheel wraps. Premium German OEMs specify these grades for vehicles operating in high-UV environments, creating margin pools inaccessible to polyester competitors.
- Polyether-Based:Polytetramethylene ether glycol architectures offer flexibility at low temperatures for cold-climate specifications.
- Hybrid Polyurethane:Blended polyol systems balance cost and performance for mid-tier electric vehicle platforms.
Polyester-based grades lead on scale; polycarbonate-based grades lead on momentum.
Technology:
Volume throughput and capital intensity separate production methods, with high-throughput operations favoring established polymerization routes while specialized lines adopt solvent-free methods for premium certification.
- Emulsion Polymerization:Aqueous phase dispersion of pre-polymerized urethane segments with surfactant stabilization dominates current installed capacity. German and Chinese producers operate this technology at scale for tier-1 automotive contracts where qualification timelines exceed three years.
- Solvent-Free:Reactive extrusion and melt dispersion methods eliminate residual volatile organic compounds for interior air quality protocols. European formulators are converting lines to meet REACH substance restrictions and OEM cabin air specifications.
- Dispersion Polymerization:Organic phase particle formation with subsequent aqueous transfer suits niche medical and aviation crossover applications.
- Chain Extension:Post-polymerization molecular weight building enables viscosity tuning for specific coating line configurations.
Emulsion polymerization leads on scale; solvent-free methods lead on momentum.
Application:
End-use performance requirements and certification burdens fragment demand, with automotive specifications imposing abrasion and fogging standards that footwear and furniture applications rarely match.
- Automotive Upholstery:Seat covers, door panels, and headliners requiring Martindale abrasion resistance above 100,000 cycles and fogging values below 2 milligrams. German OEM specification centers in Wolfsburg and Stuttgart drive qualification protocols adopted across their global manufacturing footprints.
- Footwear Components:Synthetic leather uppers and linings prioritize flex resistance and breathability over thermal stability.
- Furniture Covering:Residential and contract seating applications emphasize stain resistance and hand feel.
- Apparel Materials:Fashion and performance outerwear specifications focus on drape and moisture vapor transmission.
Automotive upholstery leads on scale; furniture covering leads on momentum.
End User:
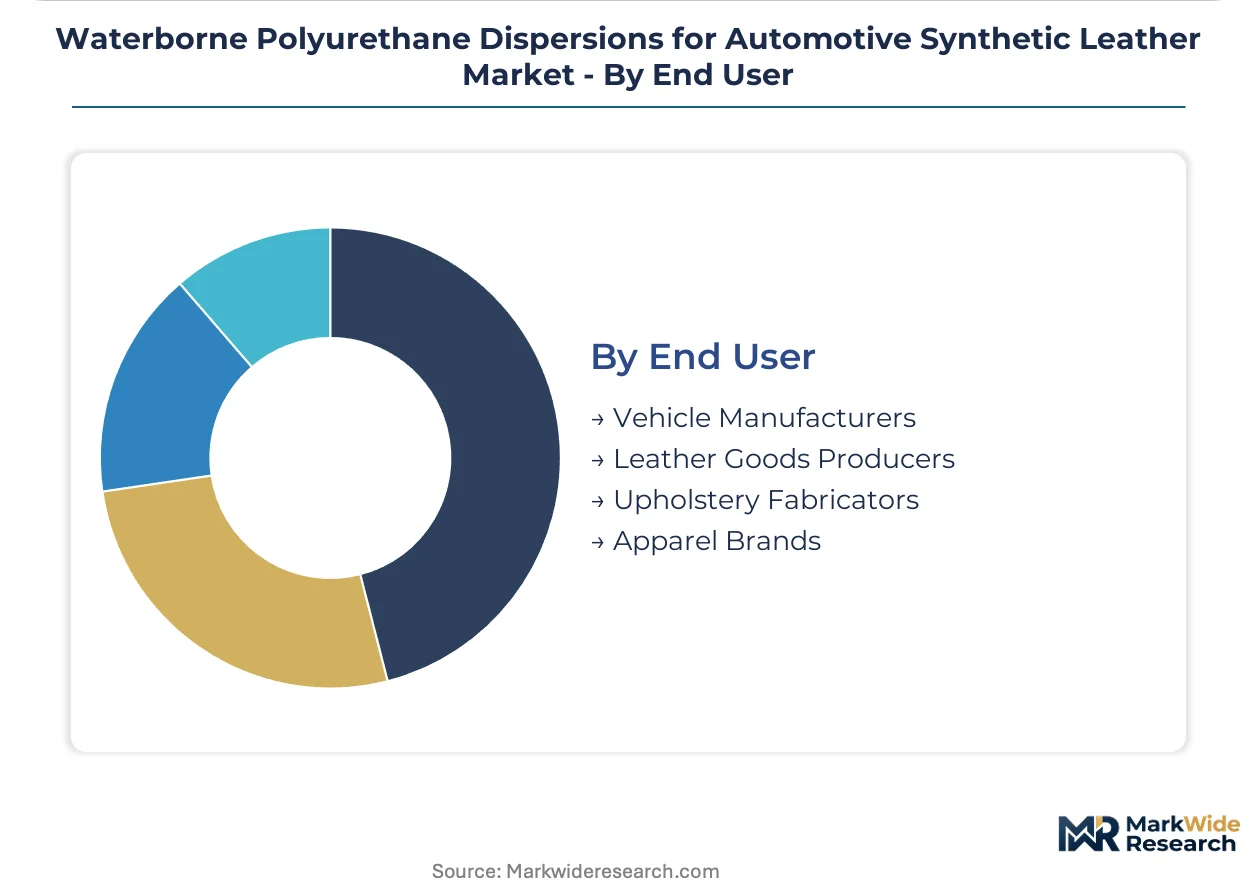
Customer type determines procurement structure, with concentrated vehicle manufacturers exercising specification authority while fragmented fabricators compete on conversion efficiency.
- Vehicle Manufacturers:OEMs in Germany, China, and the United States operate centralized upholstery specification centers that pre-qualify dispersion grades for tier-1 seating suppliers. Volkswagen's We Connect and similar digital platforms are enabling direct materials relationships that bypass traditional tier-1 gatekeepers.
- Upholstery Fabricators:Tier-1 and tier-2 converters in Poland, Mexico, and Vietnam process dispersions into coated textiles for multiple end-use markets.
- Leather Goods Producers:Luxury accessories manufacturers in Italy and France specify small-batch dispersion grades for handbag and luggage applications.
- Apparel Brands:Performance and fashion labels in Japan and South Korea source dispersions for synthetic suede and technical outerwear.
Vehicle manufacturers lead on scale; upholstery fabricators lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates premium automotive upholstery specification authority while China dominates volume production capacity, creating divergent competitive dynamics across the two largest national markets.
United States
Detroit-based OEM specification centers and EPA hazardous air pollutant regulations from coating operations are accelerating waterborne dispersion adoption. The EPA maintains binding emission limits that eliminate solvent-based alternatives in automotive upholstery manufacturing. Michigan and Ohio industrial clusters host tier-1 seating suppliers converting transfer coating lines to accommodate waterborne viscosity profiles.
Germany
REACH substance restrictions and EU Green Deal VOC mandates are forcing complete solvent-to-waterborne technology transitions across automotive manufacturing. Wolfsburg and Stuttgart specification centers drive qualification protocols adopted across German OEM global footprints. Covestro and BASF anchor supply relationships with domestic seating suppliers through localized dispersion capacity.
China
NIO, XPeng, and Li Auto operate decentralized upholstery sourcing models that fragment traditional tier-1 supplier relationships. MEE enforcement of GB standards on coating emissions is forcing domestic producers to accelerate waterborne transitions or face production curtailments. Ningbo and Shanghai industrial zones concentrate captive MDI production and localized dispersion capacity for Asia-Pacific supply.
Japan
METI industrial standards and aging technical workforces with expertise in ionic stabilization mechanisms constrain capacity expansion opportunities. Japanese formulators specialize in particle size distribution control for premium synthetic leather applications. Nagoya and Osaka manufacturing clusters supply polycarbonate-based grades for instrument panel surfaces requiring exceptional UV stability.
India
PLI scheme incentives for component manufacturing are creating entry points for dispersion producers establishing compounding partnerships with domestic textile coaters. The country's national automotive regulator is aligning with international interior air quality protocols. Maharashtra and Gujarat industrial corridors are attracting tier-2 fabricators seeking to localize automotive upholstery supply chains.
Waterborne Polyurethane Dispersions for Automotive Synthetic Leather Market Competitive Landscape
German producers anchor one tier; Chinese specialists hold volume-scale positions through captive raw material supply. The market structures around three to four dominant suppliers controlling polyether and polyester formulation architectures, with mid-tier players competing on regional qualification timelines. Strategic archetypes include petrochemical majors with backward integration into isocyanate precursors, specialized dispersion formulators with ionic stabilization expertise, and regional champions with localized regulatory compliance capabilities. Competitive moves concentrate on capacity expansion in Asia-Pacific manufacturing zones and technology licensing agreements to bypass multi-year OEM qualification barriers.
Within the petrochemical-major tier, Covestro, BASF, and Wanhua Chemical Group occupy positions defined by geographic anchoring and raw material integration depth. Covestro represents the polyether-based dispersion archetype with supply relationships concentrated in European automotive seating. BASF exemplifies backward integration into aliphatic isocyanate precursors that sustain cost advantages in polyester-based formulations. Wanhua Chemical Group anchors Asia-Pacific supply through captive MDI production, illustrating how regional champions leverage localized raw material access to displace multinational incumbents in high-volume specifications.
| Leading Market Players |
|---|
| Covestro |
| BASF |
| The Lubrizol Corporation |
| Wanhua Chemical Group |
| DIC Corporation |
| Mitsui Chemicals |
| Stahl Holdings |
| Dow |
| Huntsman |
| Others |
Pricing and Supply Chain Analysis
Captive MDI production in Ningbo and Shanghai anchors Wanhua Chemical Group's cost position while insulating its dispersion pricing from petrochemical volatility that compresses margins for European formulators facing REACH compliance costs. This backward integration into isocyanate precursors creates divergent pricing power between Asia-Pacific volume producers and specialty-grade suppliers in Germany.
Pricing Analysis
Capacity additions in China are reshaping price floors for polyester-based grades as domestic producers exploit captive raw material access to undercut multinational incumbents in mass-market seating specifications. Three-tier pricing structure across polycarbonate premium, polyester standard, and hybrid economy levels reflects certification burden and performance tier differentiation. Cost compression in mass-market tiers is intensifying because tier-1 suppliers face OEM price-down schedules in Germany and China. Fleet procurement teams at electric vehicle specialists exhibit highest price sensitivity; luxury German OEM specification centers remain least sensitive, prioritizing low-fogging and UV stability performance.
Supply Chain Analysis
Single-source vulnerability sits with German and Chinese petrochemical majors controlling MDI and polyether polyol feedstock for dispersion synthesis. Manufacturing concentrates in Germany, China, and the United States where automotive OEMs operate centralized upholstery specification centers. Formulation draws from aliphatic isocyanates, polycarbonate diols, and ionic stabilizers with multi-step synthesis dependencies. Tariff exposure on Chinese dispersion exports to European tier-1 suppliers represents the dominant structural risk. Distribution runs through tier-1 seating suppliers in Poland, Mexico, and Vietnam that process dispersions into coated textiles for vehicle manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where European REACH compliance costs and energy-price differentials against Chinese captive production create relocation incentives for dispersion compounding capacity.
For Market Incumbents: Lock in aliphatic isocyanate supply agreements with German petrochemical majors before capacity constraints tighten under EU Green Deal enforcement. Secure qualification timelines exceeding three years at Wolfsburg and Stuttgart specification centers to block emerging Chinese entrants from premium electric vehicle platforms. Capacity expansion in Asia-Pacific manufacturing zones anchors volume positions against Wanhua's localized cost structure. For New Entrants and Emerging Players: The premium-to-economy price-point gap in polycarbonate-based grades creates entry space for specialized formulators with solvent-free chain extension expertise. Target India's PLI scheme incentives for component manufacturing where domestic textile coaters seek compounding partnerships. Aviation interior crossover applications requiring fire-smoke-toxicity certification offer the most penetrable white-space. Go-to-market angle: direct OEM qualification through Volkswagen's We Connect and similar digital specification platforms that bypass tier-1 gatekeepers. For Investors and Strategic Acquirers: Consolidation pressure builds where aging technical workforces in Germany and Japan constrain formulation chemist availability for capacity expansion. Long-term viability favors petrochemical majors with backward integration into isocyanate precursors and regional champions with localized regulatory compliance capabilities. Acquisition target archetype: mid-tier dispersion formulators with ionic stabilization expertise and existing OEM qualification timelines. Signal to watch: tier-2 fabricator bankruptcy filings in Poland and Mexico indicating transfer coating line retrofit failures and waterborne adoption stalls.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Precursors | BASF's aliphatic isocyanate production sustains cost advantages in polyester-based formulations against non-integrated competitors. |
| Solvent-Free Chain Extension Technology Licensing | European formulators convert lines to meet REACH substance restrictions and OEM cabin air specifications. |
| Capacity Expansion in Asia-Pacific Manufacturing Zones | Ningbo and Shanghai industrial zones concentrate captive MDI production for regional supply displacement. |
| Long-term Supply Agreement with Tier-1 Seating Suppliers | Covestro anchors polyether-based dispersion relationships with German automotive seating suppliers through localized capacity. |
| Direct-to-OEM Digital Qualification Platform Partnership | Volkswagen's We Connect enables real-time material qualification bypassing traditional tier-1 gatekeeper relationships. |
Research Methodology
Coverage spans Germany, China, the United States, Japan, and India, with primary inputs from each market's automotive manufacturing clusters. The approach combines structured interviews with tier-1 supplier procurement directors, OEM platform engineers, dispersion formulator R&D leads, and textile coater operations managers with secondary validation. Sources include customs and trade flow data, SEC and European exchange filings from petrochemical majors, vehicle production databases, and regulatory filings from EPA, ECHA, and China's MEE. Bottom-up volume modeling triangulates against top-down market sizing from raw material consumption patterns.
Granularity-level framing models product type at chemistry-grade resolution, technology at process-generation level, application at performance-certification tier, and end user at procurement-structure archetype. Segmentation dimensions include polyester-polycarbonate-polyether-hybrid chemistry splits, emulsion versus solvent-free process routes, automotive upholstery versus crossover applications, and vehicle manufacturer versus fabricator procurement channels. CAGRs derive from regression against vehicle production forecasts and content-per-vehicle assumptions for synthetic leather interior surfaces. Industry-specific inputs capture REACH and GB standards enforcement timelines and OEM interior air quality protocol evolution.
Caveats apply where regulatory divergence between EPA hazardous air pollutant rules, REACH substance restrictions, and China's GB standards could materially shift the outlook through parallel formulation track requirements that fragment R&D resources. Forecasts reflect assumptions about waterborne technology transition rates at tier-2 fabricators and electric vehicle platform adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
United States Polymer Emulsion Market
Polymers & Resins
Optically Clear Resin Market
Polymers & Resins
Europe Polymer Emulsion Market
Polymers & Resins
Polymethacrylimide Foam Market
Polymers & Resins
Global Acrylic Emulsions Market
Polymers & Resins
Liquid Polybutadiene [LPBD] Market
Polymers & Resins
Global Polyoxymethylene (POM) Market
Polymers & Resins
Epoxy Resin Reactive Diluent Market
Polymers & Resins
Global Polyol and Polyurethane Market
Polymers & Resins
Paste PVC Resin Market
Polymers & Resins
Synthetic and Bio-Based PMMA (Polymethyl Methacrylate) Market
Polymers & Resins
Global One Component Polyurethane Foam Market
Polymers & Resins
Thermoplastic Polyurethane (TPU) Market
Polymers & Resins
PA66 Market
Polymers & Resins
Polyvinyl Butyral (PVB) Resins Market
Polymers & Resins
Homopolymer Resins Market