
 Indonesia Polypropylene Market | 2026-2036
Indonesia Polypropylene Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Polypropylene Market Outlook
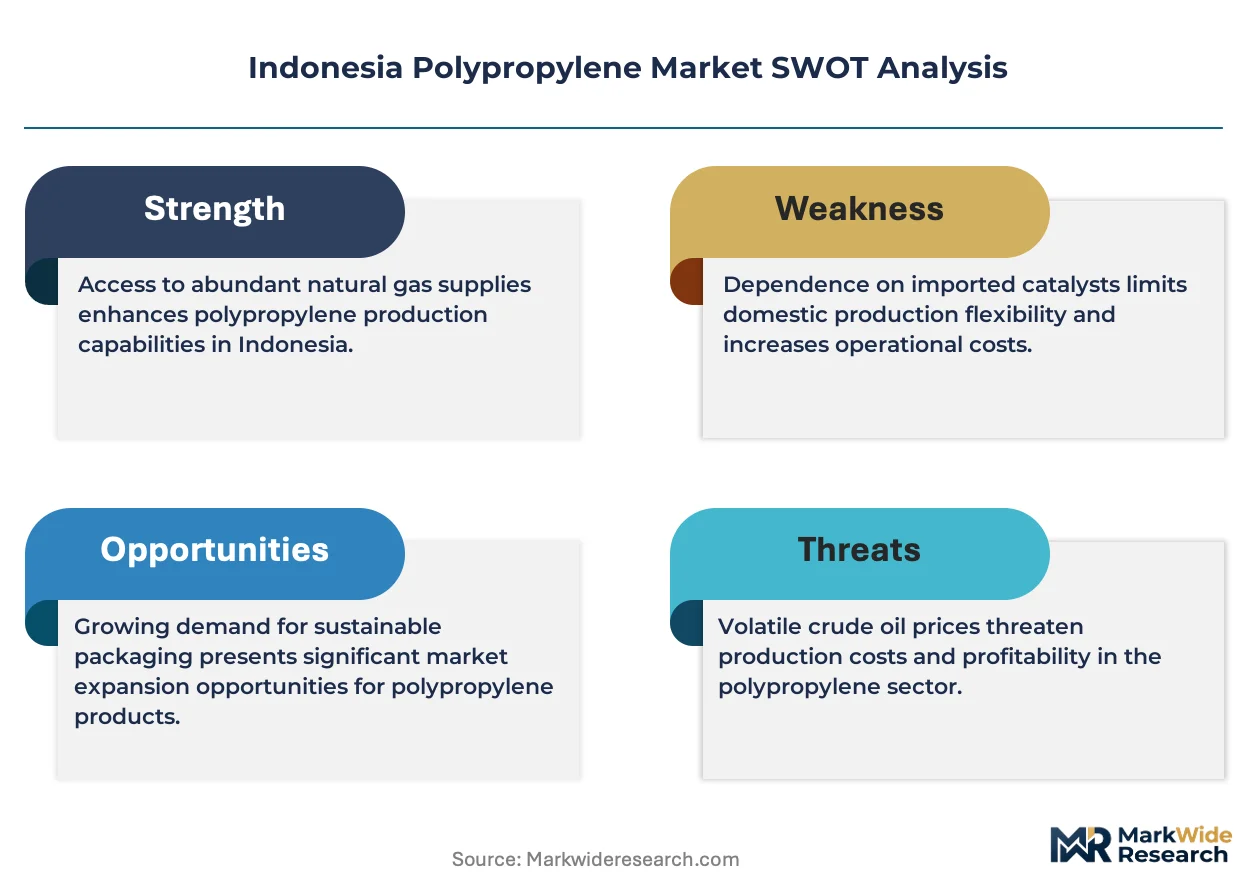
Indonesia's evolving plastic waste management regulations is broadening compliance burdens for imported resin while creating protected terrain for domestic producers. PT Chandra Asri Petrochemical leverages its integrated naphtha-to-polymer complex in Cilegon to sustain cost advantages against seaborne competitors. PT Polytama Propindo anchors its position through dedicated supply contracts with Indonesian flexible packaging converters. Exxon Mobil Corporation navigates the regulatory perimeter through specialized impact copolymer grades that meet emerging food-contact standards.
Polypropylene is a semi-crystalline thermoplastic polymer produced via Ziegler-Natta or metallocene catalysis of propylene monomer, with melt flow indices spanning 0.3 to 100 g/10 min and density near 0.90 g/cm³, serving primarily as a lightweight, chemically resistant material for molded containers, woven sacks, and automotive interior components. Homopolymer grades dominate volume flows into injection-molded rigid packaging and houseware applications where stiffness and heat resistance command premium positioning. Copolymer formulations, particularly block copolymers, are capturing accelerated growth in automotive bumper and interior panel applications as Indonesian vehicle assembly rates climb. Film manufacturing through cast and biaxially oriented extrusion lines represents a mature margin pool serving snack and confectionery flexible packaging.
BIS-equivalent national standards enforced by Indonesia's Ministry of Industry, alongside ASEAN harmonized technical regulations for food-contact materials, are tightening testing protocols for migration limits and heavy metal content. The country's national circular economy roadmap and emerging extended producer responsibility frameworks are reshaping resin procurement criteria toward recyclability certification and post-consumer recycled content compatibility. Stakeholders must monitor regulatory divergence between Jakarta's domestic standards and ASEAN-wide mutual recognition agreements to anticipate compliance cost trajectories and localized supply advantages.
Market Dynamics
Indonesia's Ministry of Industry circular economy mandates are compressing procurement timelines for virgin resin while elevating post-consumer recycled content compatibility to a threshold specification across Banten-based packaging clusters.
Growth Catalysts
- Food-contact migration standards:BIS-equivalent national standards for heavy metal limits are compelling converters toward certified homopolymer grades, tightening supplier qualification pools and locking in volume commitments with domestic producers.
- Automotive block copolymer uptake:Indonesian vehicle assembly expansion is accelerating specification of impact-modified grades for bumper and interior panel applications, displacing ABS in cost-sensitive segments.
- Banten province feedstock integration:Naphtha-to-polymer complex proximity is reducing logistics exposure for Java-based converters, anchoring procurement decisions to Cilegon supply security.
Market Restraints
- Propylene feedstock volatility:Crude-linked naphtha pricing transmits directly to polypropylene cost curves, compressing margin buffers for non-integrated compounders during upstream spikes.
- Import resin compliance friction:Extended producer responsibility frameworks impose traceability documentation burdens on seaborne suppliers, creating clearance delays at Tanjung Priok and Surabaya ports.
- Recycled content technical ceiling:Food-grade applications face mechanical property degradation thresholds at post-consumer recycled loadings above 30%, limiting circular economy roadmap targets.
Strategic Opportunities
- Sumatra flexible packaging expansion:Underpenetrated converter capacity outside Java offers first-mover positioning for metallocene-grade suppliers establishing dedicated distribution.
- Metallocene catalysis convergence:Narrow molecular weight distribution technology is unifying clarity and stiffness performance previously requiring grade trade-offs, opening premium thin-wall injection opportunities.
- Extended producer responsibility credits:Ministry of Environment and Forestry offset mechanisms reward recyclability certification, creating margin recovery pathways for compliant domestic producers.
Industry Challenges
- Migration testing laboratory capacity:BIS-equivalent protocol expansion has outpaced accredited testing infrastructure, extending certification timelines for new grade introductions.
- Legacy extrusion line reconfiguration:Cast film converters face capital intensity for biaxial orientation retrofits required to meet emerging snack packaging clarity specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Polypropylene Market |
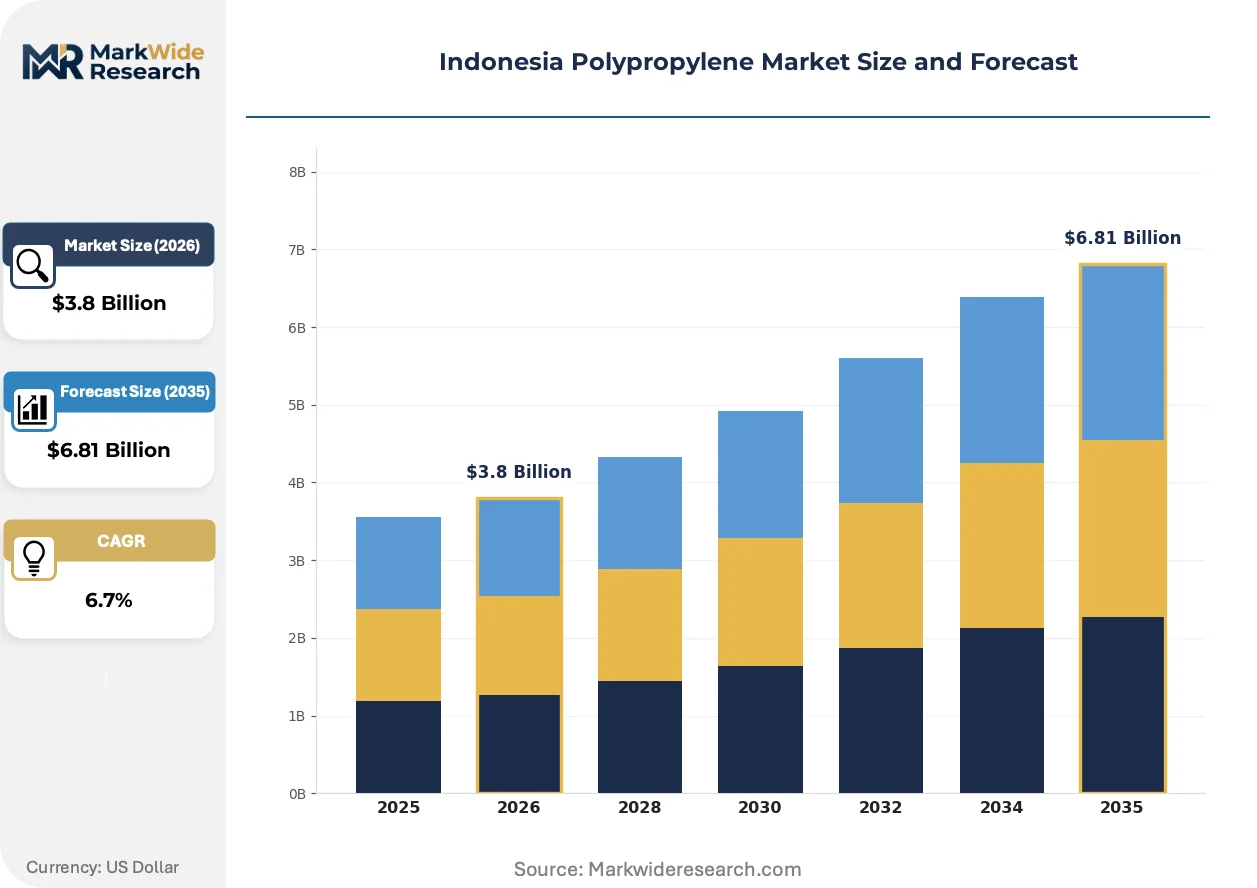
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homopolymer, Copolymer, Random Copolymer, Block Copolymer End Use Industry: Packing, Automotive, Consumer Goods, Textiles Manufacturing Stage: Injection Molding, Blow Molding, Extrusion, Film Manufacturing Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | LyondellBasell Industries Holdings BV, LOTTE Chemical Corporation, Exxon Mobil Corporation, PT Polytama Propindo, Mitsubishi Chemical Corporation, LG Chem, PT Toray International Indonesia, PT Chandra Asri Petrochemical, BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Polypropylene Market Strategic Shifts
Processing technology convergence and regulatory protocol tightening are compressing grade differentiation while elevating certification complexity as the primary competitive filter across Indonesian resin procurement.
Metallocene-catalyzed polypropylene is unifying optical clarity and flexural modulus performance in thin-wall injection applications. Multinational food packaging converters in Banten are adopting these grades at accelerated specification rates. The technology is unifying previously segmented premium and standard tier positioning, collapsing price stratification in houseware and dairy container segments.
Indonesia's Ministry of Industry circular economy roadmap is mandating recycled content quotas with phased compliance thresholds. Domestic petrochemical complexes are retrofitting compounding lines for post-consumer recycled feedstock integration. Flexible packaging converters in Java are responding by consolidating supplier relationships around vertically integrated producers with captive recycling infrastructure.
Buyer concentration among multinational fast-moving consumer goods companies is compressing procurement cycles from annual to quarterly negotiations. Tier-one packaging converters are displacing spot market purchases with framework agreements indexed to naphtha spreads. This pattern is most visible in Banten province, where integrated supply security outweighs price optimization in vendor selection criteria.
Indonesia Polypropylene Market Segmentation
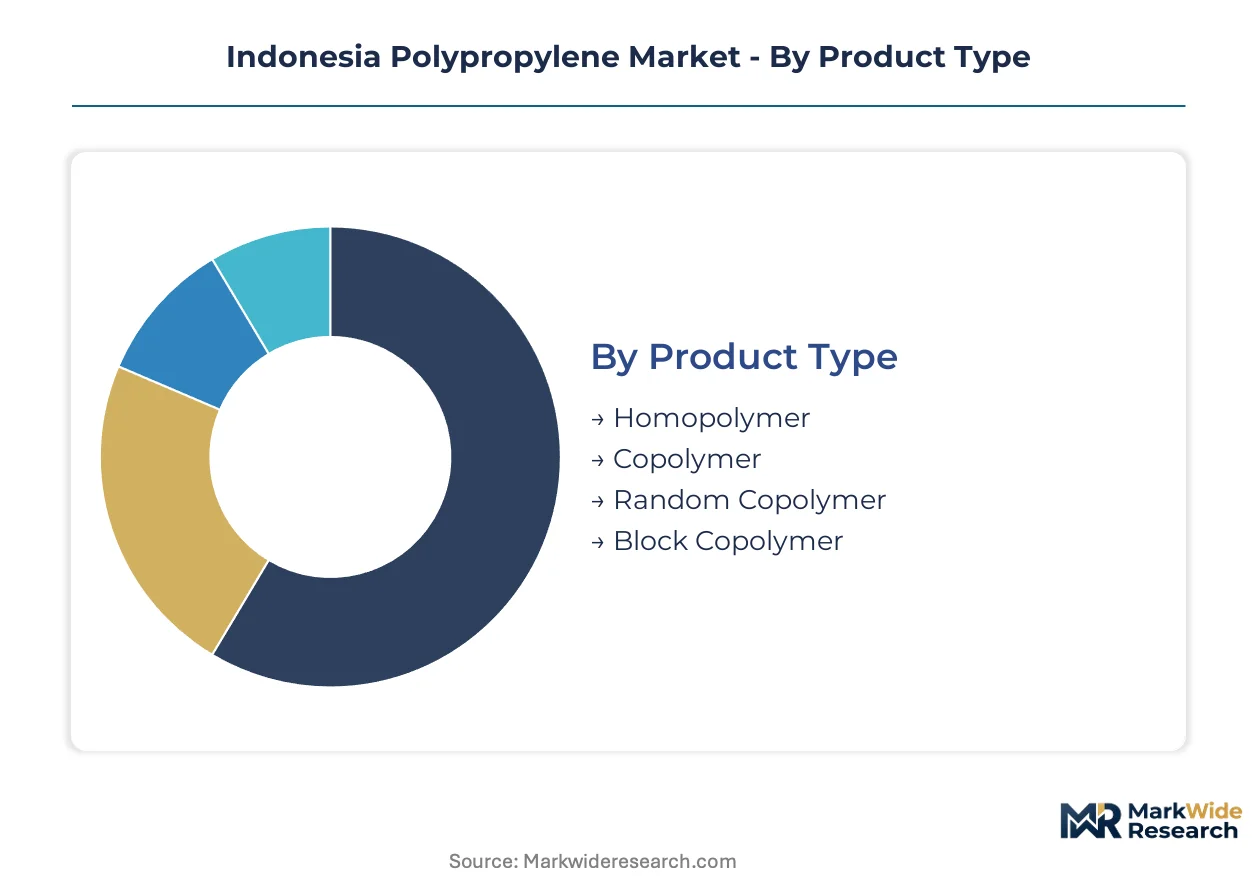
Segmentation in Indonesia's polypropylene market reveals how procurement decisions cluster around technical specifications, regulatory compliance burdens, and feedstock integration geography. Understanding these divisions exposes where margin pools concentrate and where supplier qualification barriers create protected competitive positions.
Product Type:
Buyers differentiate primarily by mechanical property requirements and heat resistance thresholds, with certification complexity widening the gap between commodity and specialty grades.
- Homopolymer:High crystallinity polypropylene with stiffness and heat resistance superior to copolymer variants, produced through Ziegler-Natta catalysis. Demand concentrates in Banten province injection-molded rigid packaging where Indonesia's Ministry of Industry food-contact migration standards compel converters toward certified domestic supply.
- Copolymer:Propylene-ethylene copolymerization yielding impact resistance and flexibility trade-offs against homopolymer rigidity. Automotive assembly plants in West Java specify block copolymer grades for bumper applications as Indonesian vehicle production rates climb.
- Random Copolymer:Ethylene incorporation at random intervals disrupts crystallinity for optical clarity in transparent packaging. Medical and food container converters in Jakarta prioritize these grades for visibility requirements.
- Block Copolymer:Segmented ethylene blocks deliver impact strength without sacrificing stiffness, serving automotive interior panels and industrial crates. Specifications from Japanese OEM assembly operations in Bekasi drive qualification protocols.
Volume sits with Homopolymer; growth tilts toward Block Copolymer.
End Use Industry:
Application-driven procurement separates converters facing circular economy compliance deadlines from those chasing automotive specification cycles.
- Packing:Flexible and rigid food packaging, woven sacks, and industrial containers represent the dominant consumption channel. Banten-based converters face compressed procurement timelines under Ministry of Industry recycled content mandates.
- Automotive:Interior panels, bumper fascias, and under-hood components specify impact-modified grades. Assembly expansion at MMKI and Toyota Motor Manufacturing Indonesia drives specification volumes.
- Consumer Goods:Houseware, furniture, and appliances utilize homopolymer stiffness for structural integrity. Modern retail channel growth in Surabaya and Medan shapes demand patterns.
- Textiles:Filament yarn, staple fiber, and non-woven applications serve geotextiles and hygiene products. South Sumatra converter investments expand regional capacity.
Revenue concentrates in Packing; Automotive exhibits the steepest expansion trajectory.
Manufacturing Stage:
Process technology requirements fragment the buyer base between capital-intensive extrusion operators and agile injection molders.
- Injection Molding:High-pressure melt injection into precision molds for thin-wall containers and complex geometries. Metallocene-grade adoption accelerates among dairy packaging converters seeking clarity-stiffness unification.
- Blow Molding:Parison inflation for hollow articles including bottles and fuel tanks. Lubricant and chemical packaging demand in Cilegon industrial corridors anchors regional supply.
- Extrusion:Continuous profile production for pipe, sheet, and monofilament. Infrastructure project pipelines in East Java sustain procurement volumes.
- Film Manufacturing:Cast and biaxially oriented processes for flexible packaging substrates. Snack food converters face capital intensity for biaxial orientation retrofits.
Throughput dominates in Injection Molding; Film Manufacturing gains share fastest from flexible packaging expansion.
Distribution Channel:
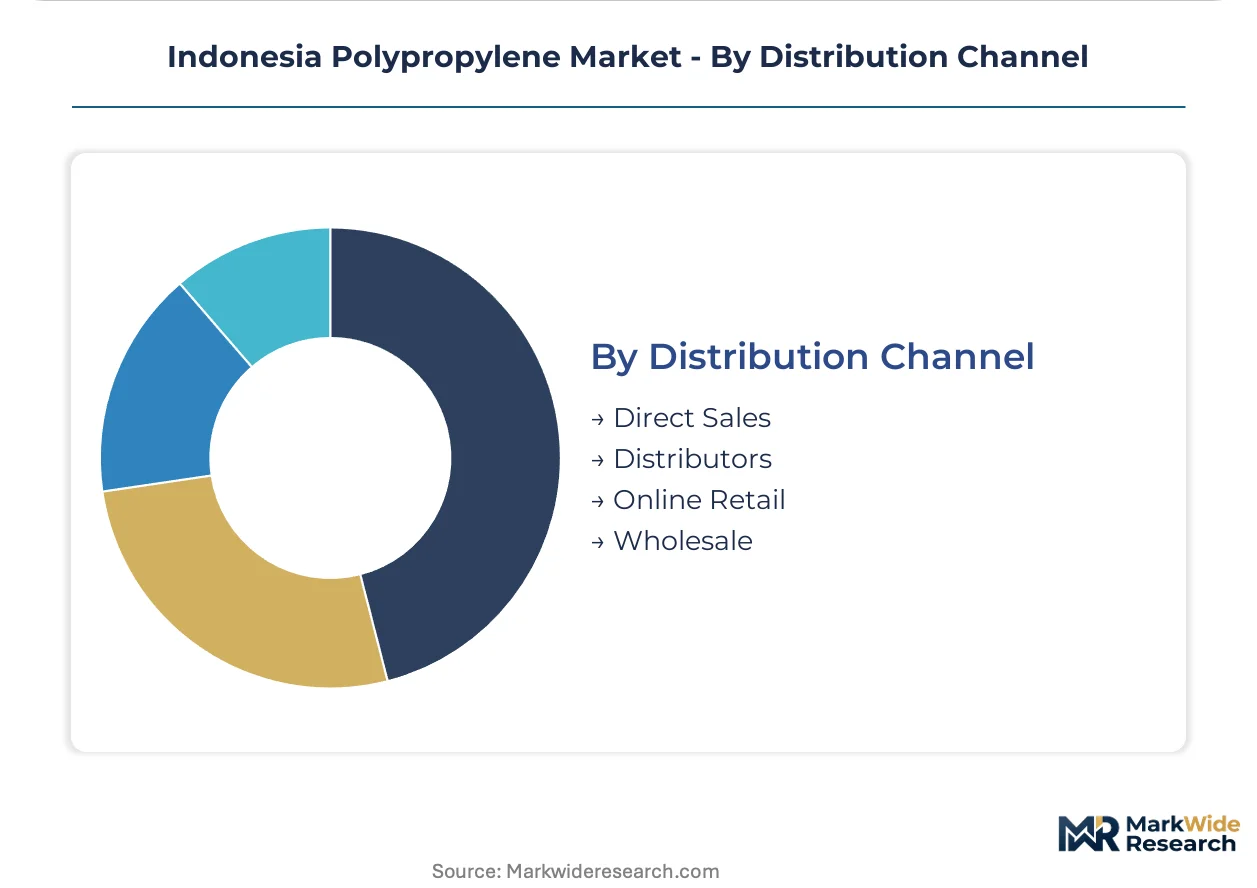
Supply security priorities and documentation burdens split procurement between relationship-based direct supply and fragmented intermediary channels.
- Direct Sales:Long-term offtake agreements between integrated petrochemical producers and tier-one converters. PT Chandra Asri Petrochemical leverages Cilegon complex proximity for Banten cluster lock-in.
- Distributors:Regional stockholding intermediaries serving mid-scale converters with fragmented demand. Inventory positioning in Surabaya and Medan reduces lead times for Sumatra-based processors.
- Online Retail:Digital platforms for small-batch procurement and specialty grade sourcing. Technical documentation gaps limit food-contact grade transactions.
- Wholesale:Volume aggregation for commodity grades serving non-integrated compounders. Price transparency pressures margin capture.
Contracted volume flows through Direct Sales; Distributors expand most quickly in underpenetrated Sumatra markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Java's industrial corridor, where Banten province petrochemical clusters feed integrated downstream processing. Sumatra's flexible packaging sector shows accelerated procurement expansion as converters diversify beyond Java-centric supply chains.
Banten Province
Food-grade homopolymer procurement dominates as packaging converters expand capacity around Cilegon's naphtha-to-polymer complexes. Indonesia's Ministry of Industry mandates stricter recycled content quotas under its circular economy roadmap. PT Chandra Asri Petrochemical's integrated complex anchors supply security for regional injection molders facing compressed certification timelines.
West Java
Automotive block copolymer specifications accelerate with Toyota Motor Manufacturing Indonesia and MMKI assembly expansion in Bekasi. BIS-equivalent national standards for food-contact migration limits tighten supplier qualification pools. Japanese OEM operations drive impact-modified grade procurement for bumper and interior panel applications.
East Java
Infrastructure project pipelines sustain extrusion-grade demand for pipe and sheet applications across Surabaya industrial zones. Extended producer responsibility frameworks impose traceability documentation burdens on imported resin. Local converters consolidate procurement around vertically integrated producers with captive recycling infrastructure.
North Sumatra
Underpenetrated flexible packaging capacity offers first-mover positioning for metallocene-grade suppliers establishing dedicated distribution. ASEAN harmonized technical regulations for food-contact materials reshape resin procurement criteria toward recyclability certification. Medan-based stockholding intermediaries reduce lead times for regional processors.
South Sumatra
Textile filament and non-woven applications expand with geotextile and hygiene product manufacturing investments. Post-consumer recycled content compatibility thresholds limit circular economy roadmap targets at loadings above 30%. Converter investments in Palembang corridor diversify procurement geography beyond Java dominance.
Indonesia Polypropylene Market Competitive Environment
Domestic Indonesian producers anchor one tier; multinational petrochemical specialists hold premium-grade positioning through technology licensing. The vendor base splits between integrated naphtha-to-polymer complexes and import-dependent compounders facing compliance friction. Three archetypes dominate: integrated domestic producers with captive feedstock, multinational technology licensors with metallocene capabilities, and regional distributors serving fragmented mid-scale converters. Capacity expansion and strategic partnerships represent the dominant competitive vectors as stakeholders secure recycled-content-ready supply chains.
Among multinational technology holders, LyondellBasell Industries Holdings BV and Exxon Mobil Corporation occupy positions defined by specialized copolymer grades and food-contact certification depth. Domestic integrated producers exemplified by PT Chandra Asri Petrochemical and PT Polytama Propindo anchor supply security for Banten-based packaging clusters through Cilegon complex proximity. Korean and Japanese chemical conglomerates represented by LOTTE Chemical Corporation and Mitsubishi Chemical Corporation sit within the import-tier segment navigating extended producer responsibility documentation requirements.
| Leading Market Players |
|---|
| LyondellBasell Industries Holdings BV |
| LOTTE Chemical Corporation |
| Exxon Mobil Corporation |
| PT Polytama Propindo |
| Mitsubishi Chemical Corporation |
| LG Chem |
| PT Toray International Indonesia |
| PT Chandra Asri Petrochemical |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Process engineering talent concentration in Banten province compresses labor-cost differentials between integrated producers and import-dependent compounders, widening pricing-tier spreads as certification burdens accumulate on seaborne resin.
Pricing Analysis
Volume flows concentrate in contract-based long-term offtake agreements while margin capture tilts toward metallocene-grade specialty tiers. Price differentiation separates food-contact certified homopolymer from commodity import grades, with BIS-equivalent protocol compliance acting as the primary tier separator. Cost compression in standard-grade segments is intensifying because naphtha-linked feedstock volatility transmits directly to non-integrated compounders. Mid-scale converters in Sumatra exhibit highest price sensitivity; multinational FMCG packaging partners in Banten prioritize supply security over unit cost optimization.
Supply Chain Analysis
Certification gating through Indonesia's Ministry of Industry food-contact migration standards filters supplier qualification pools, concentrating qualified volume around Cilegon-integrated producers. Geographic supply concentration centers on Indonesia, South Korea, and Singapore, with naphtha feedstock drawing from regional refining complexes. Raw material dependencies rest on propylene monomer, Ziegler-Natta and metallocene catalyst systems, and specialized additive packages. Single-source vulnerability persists for metallocene technology licensing held by limited multinational licensors. Distribution runs through direct sales contracts for tier-one converters and regional stockholding intermediaries for fragmented mid-scale processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's polypropylene sector sits in a catalysis-transition phase as metallocene technology displaces legacy Ziegler-Natta systems for clarity-critical applications.
For Market Incumbents: Hedge against feedstock volatility through captive naphtha cracking capacity or indexed supply agreements with regional refiners. Defend qualification status by accelerating BIS-equivalent certification laboratory investments before accreditation bottlenecks extend. Secure block copolymer specification lock-in with expanding Japanese OEM assembly operations in Bekasi as ABS substitution accelerates. For New Entrants and Emerging Players: Enter via metallocene-grade distribution partnerships targeting underpenetrated Sumatra flexible packaging converters outside Java-centric supply chains. White-space concentration sits in North Sumatra stockholding infrastructure and South Sumatra textile filament applications. A technical service-led go-to-market approach bypasses incumbent relationship barriers. For Investors and Strategic Acquirers: The window for entry favors vertically integrated domestic producers with captive recycling infrastructure and circular economy roadmap compliance readiness. Long-term viability hinges on post-consumer recycled content compatibility capabilities as Ministry of Environment and Forestry offset mechanisms mature. Monitor accreditation timeline compression at BIS-equivalent testing laboratories as the inflection signal for qualification-constrained supply tightness.| Strategic Initiative | Industry Significance |
|---|---|
| Metallocene Catalysis Adoption | Unifies clarity-stiffness performance for thin-wall dairy packaging specifications in Banten. |
| Post-Consumer Recycling Integration | Captures Ministry of Environment and Forestry offset credits under circular economy mandates. |
| BIS-Equivalent Certification Investment | Accelerates supplier qualification timelines amid accredited laboratory capacity constraints. |
| Sumatra Distribution Infrastructure | Reduces lead times for flexible packaging converters diversifying beyond Java supply chains. |
| Long-Term Naphtha Supply Indexing | Stabilizes margin buffers against crude-linked feedstock volatility for non-integrated compounders. |
Study Parameters
Multi-period observation of naphtha-to-polymer margin spreads, converter capacity expansion announcements, and regulatory protocol evolution anchored the trend analysis, supplemented by interviews with Banten-based plant managers, procurement leads at tier-one packaging converters, Ministry of Industry regulatory affairs officers, and distribution channel partners. Secondary validation drew from customs and trade data, ASEAN harmonized technical regulation filings, petrochemical complex SEC disclosures, and circular economy roadmap documentation. Bottom-up volume aggregation across grade tiers and end-use segments triangulated against top-down macroeconomic demand elasticity estimates.
Segment-weighting applied product type classifications, end-use industry demand clusters, manufacturing stage process technologies, and distribution channel structures across the modeling period. CAGRs were derived from slope analysis of fitted trend lines against historical consumption patterns and projected capacity utilization rates. Key forecast inputs included Indonesian vehicle assembly expansion schedules, Ministry of Industry recycled content mandate phase-in trajectories, and metallocene technology licensing availability.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt naphtha price dislocation or accelerated circular economy roadmap enforcement. Projections reflect documented assumptions regarding feedstock integration economics and regulatory compliance timeline elasticity. A model refresh is warranted upon material change in BIS-equivalent testing laboratory accreditation capacity or Ministry of Environment and Forestry offset mechanism implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Silyl Acrylate Polymer (SAP) Market
Polymers & Resins
APAC Polyethylene Terephthalate Market
Polymers & Resins
Global Specialty Polystyrene Resin Market
Polymers & Resins
US Polymethyl Methacrylate Market
Polymers & Resins
Polycarbonate Glazing Market
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
Photocurable Resins Market
Polymers & Resins
Formaldehyde-Free Resin Market
Polymers & Resins
Polymer Excipients Market
Polymers & Resins
Vinyl Acetate Homopolymer Emulsion Market
Polymers & Resins
EVA Resins and Films Market
Polymers & Resins
Polymethacrylimide Foam Market
Polymers & Resins
Paste PVC Resin Market
Polymers & Resins
North America Polymer Emulsion Market
Polymers & Resins
Middle East Polycarbonate (PC) Market
Polymers & Resins
Polyurethane (PU) Foam Market