
 Global Base Metal Mining Market | 2026-2036
Global Base Metal Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Global Base Metal Mining Market Foresight
Battery-grade nickel specifications is unwinding long-standing quality benchmarks across the base metal mining sector. BHP Group leverages its Western Australia nickel operations to supply cathode precursor markets. Rio Tinto sustains large-scale copper exposure through its Oyu Tolgoi underground expansion. Glencore dominates integrated cobalt-nickel trading and concentrates European battery supply chain access.
Base metal mining encompasses the extraction of non-ferrous metals including copper, nickel, zinc, lead, and tin from sulfide and laterite ore bodies, typically yielding concentrates with metal contents ranging from 20% to 30% that undergo smelting and refining for industrial use. These metals serve as foundational inputs for electrical conductivity, corrosion-resistant alloys, and energy storage systems across manufacturing economies. Copper concentrates command premium pricing tied to treatment and refining charges, while nickel laterite operations face higher energy intensity and margin compression. Underground mining methods gain traction where ore body geometry favors selective extraction and surface disturbance minimization.
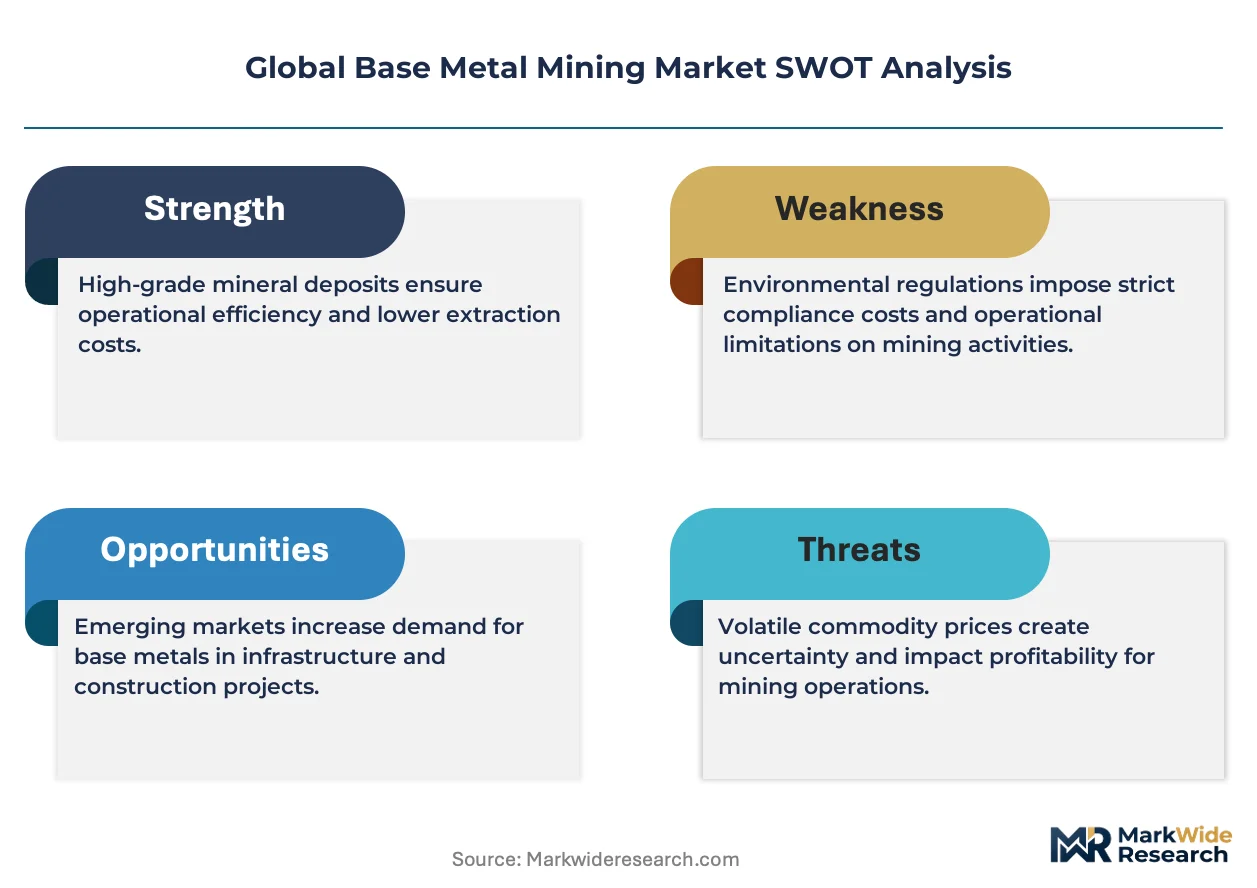
Chile's environmental regulator enforces stricter tailings management protocols that elevate capital requirements for new copper projects. Indonesia's Ministry of Energy and Mineral Resources mandates domestic processing of nickel ore, redirecting investment toward hydrometallurgical facilities. China's Ministry of Ecology and Environment applies emissions ceilings on zinc and lead smelters, constraining regional supply elasticity. Stakeholders must weigh jurisdictional regulatory trajectory against reserve quality and processing technology readiness when allocating exploration and development capital.
Market Dynamics
Electrification infrastructure buildout is concentrating copper and nickel demand into discrete project pipelines, while regulatory pressure on tailings management and carbon intensity is bifurcating capital allocation between legacy assets and greenfield developments. Mining economics now hinge on processing technology readiness and jurisdictional compliance trajectory rather than ore grade alone.
Growth Catalysts
- Renewable energy infrastructure:Offshore wind farms and grid-scale battery installations are consuming copper at three to four times the intensity of conventional power generation. China's State Grid Corporation is commissioning ultra-high voltage transmission corridors that require specialized conductor alloys.
- REACH battery material compliance:The European Chemicals Agency's substance authorization protocols are creating premium market tiers for ethically sourced cobalt and nickel, rewarding operations with certified supply chain traceability.
- Hydrometallurgical processing:High-pressure acid leach facilities at Indonesian nickel laterite deposits are unlocking previously uneconomic reserves for electric vehicle cathode precursor production.
Market Restraints
- Energy cost volatility:Nickel laterite processing via rotary kiln-electric furnace routes faces margin compression when natural gas and coal prices spike, rendering Indonesian operations sensitive to Indonesian domestic fuel subsidy adjustments.
- Supply concentration risk:Cobalt refining capacity clusters in the Democratic Republic of Congo and Zambia, exposing cathode manufacturers to concentrated geopolitical and logistics disruption.
- Substitution pressure from sodium-ion:Battery chemistry diversification toward sodium-ion systems threatens to displace lithium and nickel demand in stationary storage and entry-level electric vehicle segments.
Strategic Opportunities
- Underpenetrated African copperbelt:Zambia and the Democratic Republic of Congo hold substantial undeveloped sediment-hosted copper reserves where infrastructure investment could unlock tier-one production.
- EU Critical Raw Materials Act:The European Union's domestic processing mandates and strategic stockpiling incentives are creating offtake guarantees for compliant African and European operators.
- Direct shipping ore bypass:Indonesian nickel producers are experimenting with rotary kiln-electric furnace matte exports that circumvent intermediate refining steps, capturing margin previously lost to Chinese processors.
Industry Challenges
- Geotechnical engineering talent scarcity:Qualified tailings dam design engineers and hydrogeologists command premium compensation, delaying project permitting timelines in Chile and Peru.
- Capex intensity for deep ore bodies:Block cave mining at Oyu Tolgoi and similar deposits requires billion-dollar upfront development before revenue generation, straining balance sheets.
- Indigenous consultation protocols:Free, prior, and informed consent processes in Canada and Australia are extending project approval cycles by two to four years.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Base Metal Mining Market |
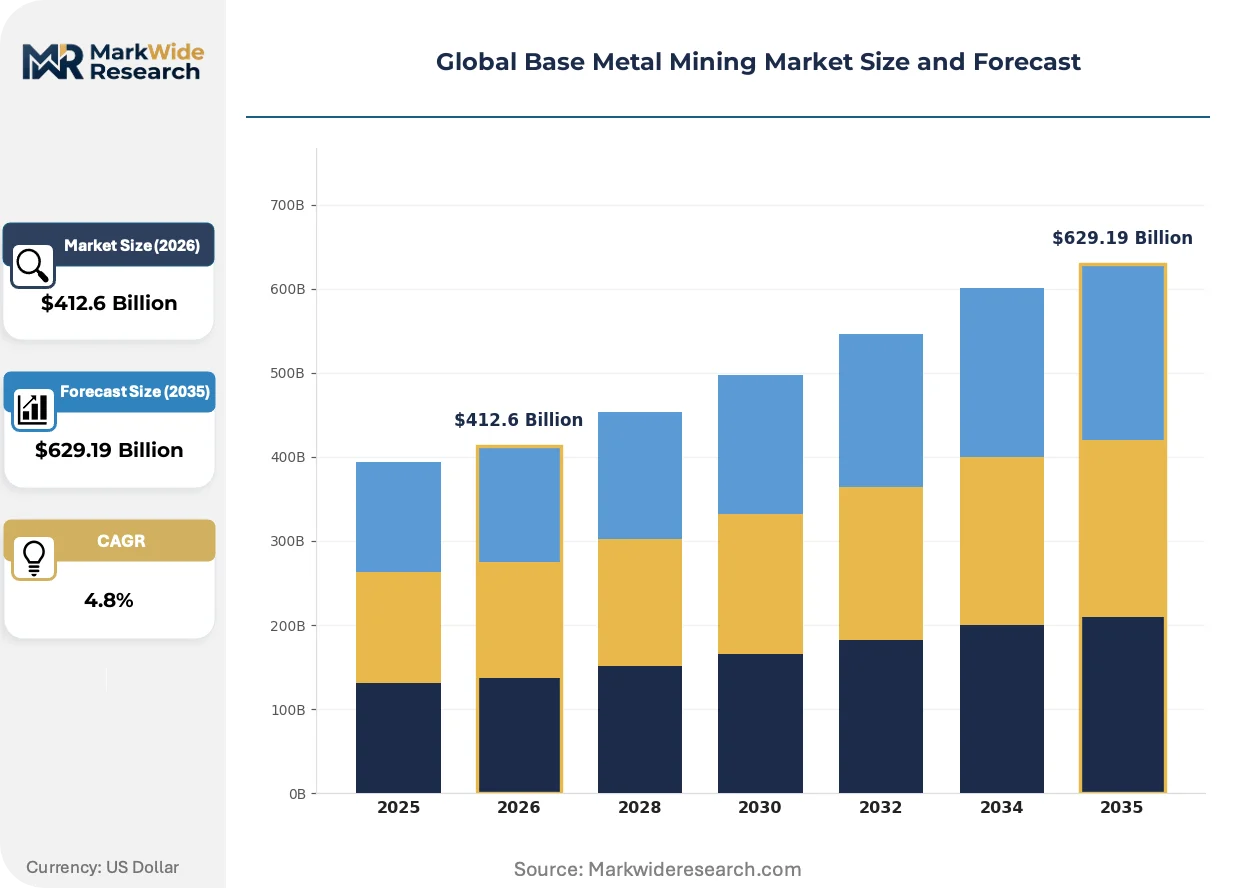
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $629.19 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Metal Type: Copper, Nickel, Zinc, Lead, Tin Mining Method: Open Pit, Underground, Placer, In-Situ Leaching, Cut & Fill End User Industry: Construction, Electronics Manufacturing, Renewable Energy, Aerospace, Shipbuilding Processing Technique: Froth Flotation, Hydrometallurgy, Pyrometallurgy, Gravity Separation, Bioleaching |
| Companies Covered | BHP Group, Rio Tinto, Glencore, Freeport-McMoRan Inc., Vale S.A., Antofagasta plc, Teck Resources Limited, First Quantum Minerals Ltd., Southern Copper Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Base Metal Mining Market Shifts & Advancements
Processing technology and regulatory architecture are diverging paths for base metal extraction, with selective adoption determining competitive position. Capital deployment increasingly favors operations capable of certifying low-carbon production and battery-grade material purity.
In-situ recovery and bioleaching methods are bifurcating extraction economics for low-grade copper deposits. Rio Tinto and BHP Group are piloting microbial-assisted heap leaching at Arizona and South Australian oxide operations, reducing energy intensity by sixty percent versus conventional milling. This technology is compressing the minimum viable ore grade threshold and enabling development of previously stranded resources.
The EU F-Gas Regulation and its phasedown of hydrofluorocarbon blowing agents is redirecting nickel demand toward foams and insulation applications requiring high-purity metal feedstock. European smelters are retrofitting sulfur capture systems to meet tightening emissions ceilings. Nickel sulfate producers in Finland and Norway are capturing premium pricing from battery manufacturers seeking supply chain defensibility.
Automotive OEMs are consolidating cathode precursor procurement through direct offtake agreements with mining operations, bypassing traditional trader intermediaries. Tesla, Volkswagen Group, and BMW have established multi-year supply contracts with Indonesian and Australian nickel producers. This disintermediation is most advanced in the European battery supply chain, where OEMs seek IRA-compliant sourcing for North American vehicle assembly.
Global Base Metal Mining Market Segmentation
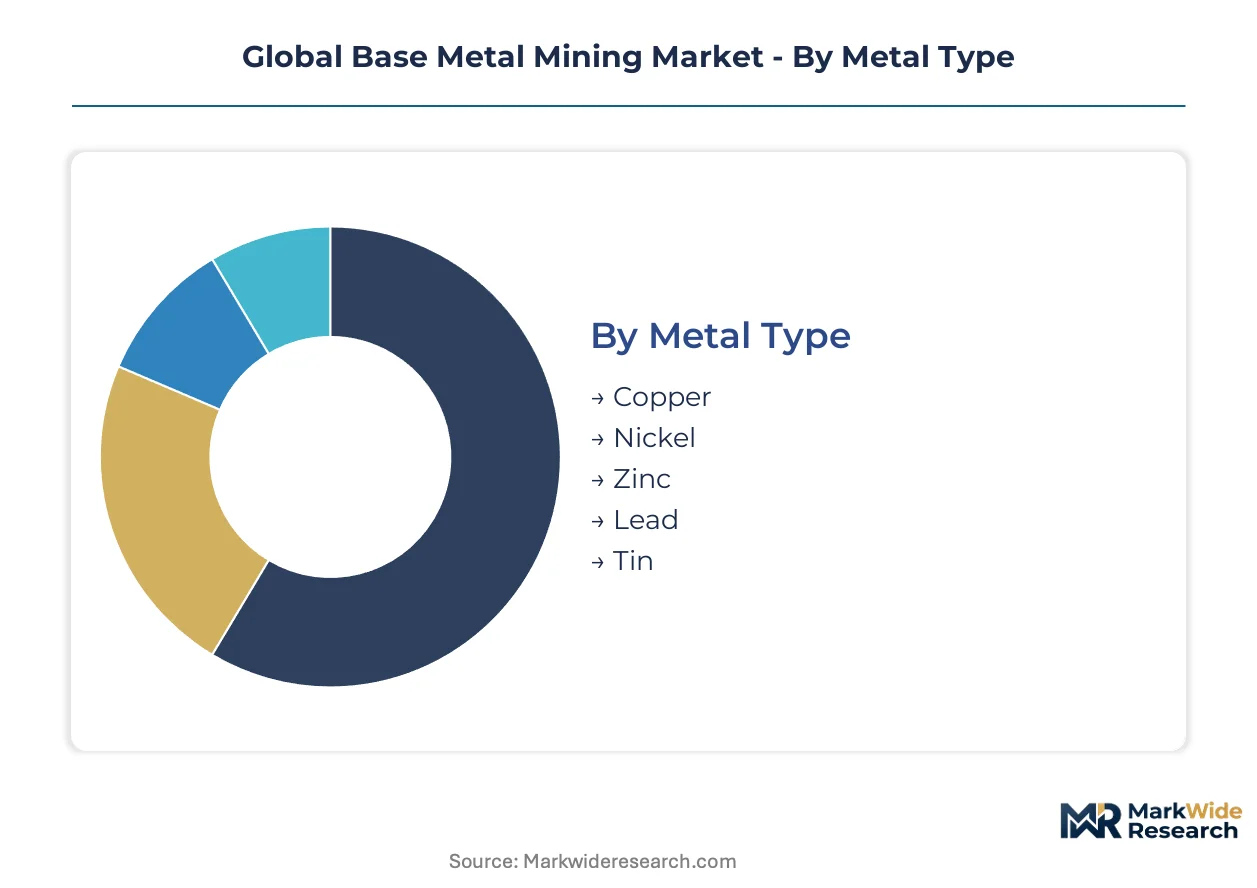
Base metal mining segmentation reveals how ore body characteristics, processing economics, and end-use specifications fragment capital allocation across extraction and refining operations. Regulatory thresholds on emissions and material purity are sharpening the boundaries between segment profitability.
Metal Type:
China's Ministry of Ecology and Environment applies differentiated emissions ceilings on copper versus zinc-lead smelters, while Indonesia's Ministry of Energy and Mineral Resources mandates domestic processing thresholds specifically for nickel exports.
- Copper:Sulfide ore bodies yield concentrates with metal contents between 20% and 30% that command premium pricing tied to treatment and refining charges. Chile's tightening tailings dam standards under its environmental regulator are elevating capital requirements for new porphyry projects while China's State Grid Corporation commissions ultra-high voltage transmission corridors requiring specialized conductor alloys.
- Nickel:Laterite deposits in Indonesia and the Philippines demand hydrometallurgical processing via high-pressure acid leach facilities to unlock battery-grade sulfate for electric vehicle cathode precursors. The European Chemicals Agency's REACH authorization protocols reward operations with certified supply chain traceability through premium market tiers.
- Zinc:Mississippi Valley-type deposits and volcanic-hosted massive sulfide bodies supply galvanizing applications and die-casting alloys with strict impurity tolerances.
- Lead:Carbonate replacement deposits and sedimentary exhalative ore bodies feed battery manufacturing and radiation shielding with declining demand intensity in automotive starter batteries.
- Tin:Greisen-bordered hydrothermal veins and alluvial placer deposits support solder alloys and tinplate packaging with concentrated supply from Indonesia and Myanmar.
Copper handles the majority of throughput; nickel is the fastest mover on share.
Mining Method:
Capital intensity and permitting timelines diverge sharply between surface disturbance regimes, with Chile and Peru favoring underground alternatives to minimize environmental review duration.
- Open Pit:Bulk tonnage extraction of low-grade porphyry copper deposits employs truck-and-shovel fleets with economies of scale that compress unit costs below underground alternatives. Bingham Canyon and Chuquicamata demonstrate century-long operational lifespans where ore body geometry permits phased pit expansion.
- Underground:Block cave and sublevel stoping methods access deeper ore bodies at Oyu Tolgoi and Escondida Norte where surface footprint constraints or overburden thickness preclude open pit development. Chile's stricter tailings management protocols are accelerating permitting for paste backfill operations that reduce surface storage requirements.
- Placer:Alluvial tin and gold-base metal associations in Southeast Asia employ dredging and sluicing with minimal overburden removal.
- In-Situ Leaching:Low-grade oxide copper deposits in Arizona and Kazakhstan utilize sulfuric acid injection and recovery wells without mechanical excavation.
- Cut & Fill:Steeply dipping, narrow vein deposits in Canadian shield terranes employ selective extraction with cemented rock fill for ground support.
Open pit operations capture the bulk of tonnage; in-situ leaching is expanding most quickly as water-stressed jurisdictions restrict fresh water allocation to conventional milling.
End User Industry:
Application-specific purity standards and volume contracting patterns concentrate procurement power among automotive and renewable energy OEMs seeking direct offtake agreements.
- Construction:Structural steel galvanization, plumbing alloys, and architectural cladding consume zinc and copper in specifications governed by ASTM and EN standards for corrosion resistance.
- Electronics Manufacturing:Printed circuit board laminates, semiconductor packaging, and connector alloys demand high-purity copper cathode with oxygen-free specifications and tin-lead or tin-silver solder formulations.
- Renewable Energy:Offshore wind turbine generators and grid-scale battery installations consume copper at three to four times the intensity of conventional power generation, with nickel sulfate for lithium-ion cathodes commanding battery-grade premiums.
- Aerospace:Nickel-based superalloys for turbine blades and copper-beryllium connectors for avionics require vacuum induction melted feedstock with trace element certification.
- Shipbuilding:Copper-nickel hull cladding and lead-acid battery banks for vessel propulsion follow Lloyd's Register and DNV classification society material specifications.
Renewable energy applications are gaining share fastest; construction retains the largest installed demand base.
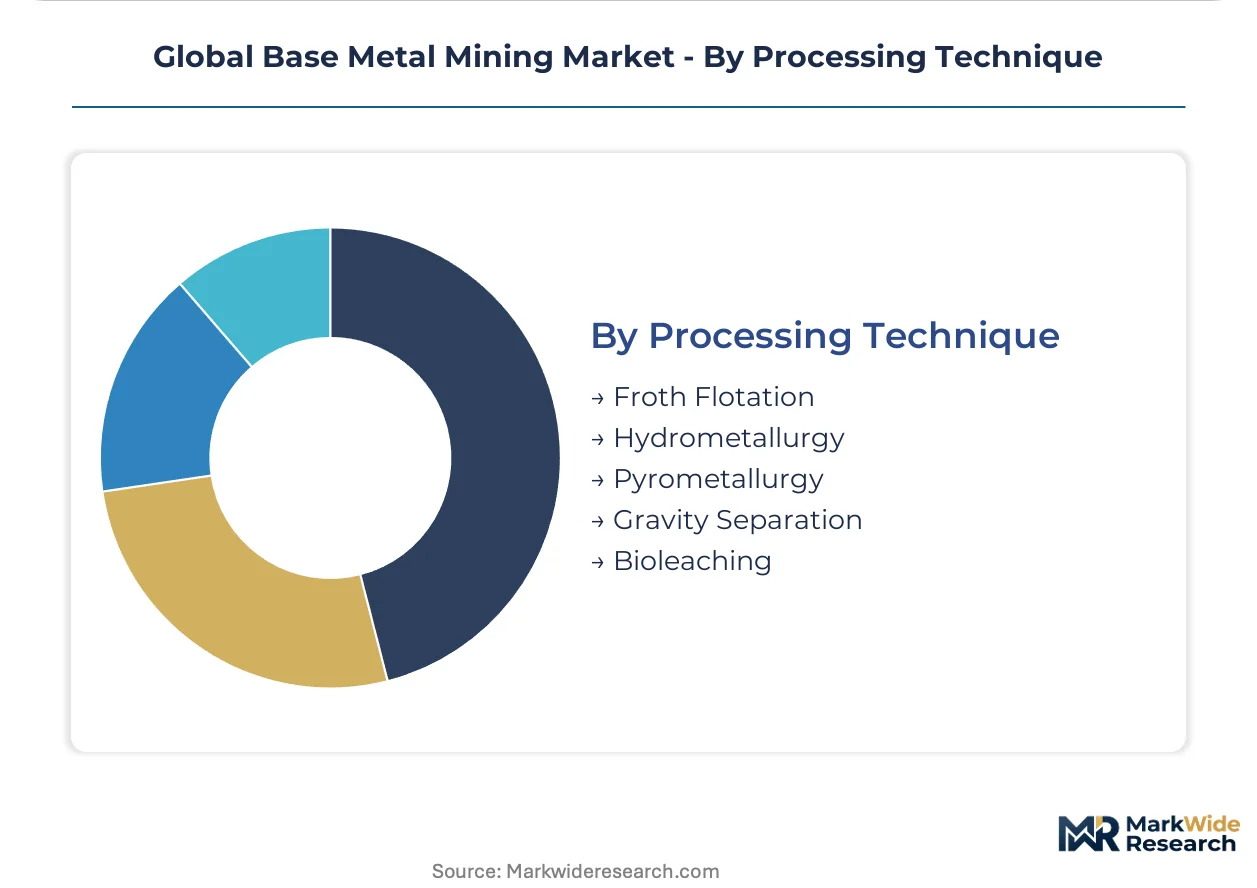
Processing Technique:
Energy intensity and reagent chemistry differentiate competitive position, with European smelters retrofitting sulfur capture systems to meet tightening emissions ceilings under the EU Green Deal framework.
- Froth Flotation:Conventional sulfide concentration employs xanthate collectors and frothers to separate chalcopyrite and sphalerite from gangue minerals, yielding concentrates for smelter feed with 20% to 30% metal content.
- Hydrometallurgy:High-pressure acid leach and atmospheric tank leaching of nickel laterites in Indonesia generates mixed hydroxide precipitate and nickel sulfate for battery precursor markets, bypassing energy-intensive pyrometallurgical routes.
- Pyrometallurgy:Flash smelting and converting of copper concentrates in Chile and Zambia employs oxygen-enriched air to produce blister copper with sulfur dioxide capture for acid production.
- Gravity Separation:Dense medium separation and shaking tables pre-concentrate coarse sulfide particles before flotation circuits.
- Bioleaching:Microbial-assisted heap leaching at Arizona and South Australian oxide operations reduces energy intensity versus conventional milling while compressing minimum viable ore grade thresholds.
Pyrometallurgy processes the majority of sulfide feedstock; hydrometallurgy is climbing the fastest as battery-grade specifications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper concentrate flows cluster in the Atacama Desert and Pilbara region, while nickel laterite processing gravitates toward Sulawesi and Halmahera. Regulatory divergence between Chile's tailings protocols and Indonesia's domestic beneficiation mandates is fragmenting capital deployment across extraction jurisdictions.
Chile
State Grid Corporation of China contracts for ultra-high voltage transmission alloys sustain concentrate offtake from Escondida and Collahuasi. The environmental regulator enforces stricter tailings dam management protocols that elevate permitting timelines for new porphyry developments. Antofagasta anchors northern copper production where paste backfill systems reduce surface storage requirements.
Australia
BHP Group's Olympic Dam and Mount Keith operations feed cathode precursor demand from South Korean battery manufacturers. The Western Australian Department of Mines, Industry Regulation and Safety applies progressive rehabilitation bonds that accelerate closure planning for nickel laterite pits. Kalgoorlie-Boulder concentrates gold-copper processing infrastructure that supports regional concentrate blending.
Indonesia
High-pressure acid leach facilities on Obi Island and Sulawesi unlock battery-grade nickel sulfate for Tesla and Volkswagen Group offtake agreements. The Ministry of Energy and Mineral Resources mandates domestic processing thresholds that redirect investment from ore export toward hydrometallurgical complexes. Morowali Industrial Park hosts integrated ferronickel-to-matte operations that circumvent intermediate Chinese refining.
Peru
Antamina and Cerro Verde copper-molybdenum concentrates supply Asian smelters under long-term treatment charge contracts. The Ministry of Energy and Mines imposes community consultation requirements that extend permitting for Quellaveco-style greenfield projects. Arequipa anchors southern copper logistics where concentrate pipelines bypass Andean transport bottlenecks.
Canada
First Quantum Minerals' Cobre Panama concentrates and Teck Resources' Highland Valley copper feed North American rod mill demand. Impact Assessment Agency protocols require free, prior, and informed consent processes that extend approval cycles for British Columbia porphyry expansions. Sudbury Basin hosts nickel-copper-platinum group metal operations with integrated smelter-refinery complexes serving automotive catalyst markets.
Global Base Metal Mining Market Competitive Landscape
Concentration sits with diversified majors controlling tier-one ore bodies across multiple geographies. Tier-one diversified miners, mid-tier copper specialists, and integrated trading houses occupy distinct competitive positions. Capacity expansion through block cave development and strategic partnerships for battery material offtake dominate competitive moves.
Among diversified majors, BHP Group, Rio Tinto, and Glencore exemplify scale-driven positioning across copper, nickel, and cobalt value chains. BHP Group represents Australian-based diversified extraction with Western Australian nickel and Chilean copper exposure. Rio Tinto occupies a position anchored by Mongolian underground copper expansion and Arizona bioleaching pilots. Glencore sits within the integrated trading archetype, connecting African cobalt concentrates with European battery supply chain access.
| Leading Market Players |
|---|
| BHP Group |
| Rio Tinto |
| Glencore |
| Freeport-McMoRan Inc. |
| Vale S.A. |
| Antofagasta plc |
| Teck Resources Limited |
| First Quantum Minerals Ltd. |
| Southern Copper Corporation |
| Others |
Supply & Pricing Matrix
Sodium-ion battery chemistry substitution is redirecting procurement budgets away from nickel sulfate premiums and toward aluminum-intensive anode foils, simultaneously compressing Indonesian laterite margins and elevating bauxite-rich jurisdictions in pricing negotiations. This displacement dynamic fragments long-term offtake contracting as cathode manufacturers hedge chemistry exposure.
Pricing Analysis
REACH authorization protocols dictate the pricing tier structure across European battery material procurement, separating ethically certified cobalt and nickel sulfate from standard-grade concentrates. Battery-grade premiums attach to supply chain traceability documentation, while treatment and refining charges for copper concentrates soften as Chinese smelter capacity expands. OEM direct procurement teams exhibit lowest price sensitivity, prioritizing compliance certification over unit cost.
Supply Chain Analysis
Indonesia and Chile anchor global nickel laterite and copper concentrate production respectively, with the Democratic Republic of Congo feeding cobalt hydroxide intermediates. High-purity sulfuric acid and energy-dense metallurgical coal constitute critical reagent dependencies. Single-source vulnerability concentrates in Indonesian hydrometallurgical complexes. Distribution runs through long-term offtake contracts direct to automotive OEM cathode precursor facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified tailings dam engineers and hydrogeologists command compensation premiums that extend permitting timelines, constraining expansion velocity for tier-one ore bodies.
For Market Incumbents: Secure captive nickel sulfate capacity through high-pressure acid leach partnerships in Indonesia before Indonesian domestic processing mandates tighten further. Secure block cave development sequencing at deep copper porphyries to maintain concentrate output as Chilean tailings protocols elevate surface storage costs. For New Entrants and Emerging Players: Differentiate on low-carbon production certification for European battery supply chain access, targeting Finnish and Norwegian nickel sulfate markets where EU Critical Raw Materials Act stockpiling incentives create offtake guarantees. Target Zambian copperbelt greenfield development where infrastructure investment gaps deter majors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed African copper developers holding sediment-hosted reserves but lacking concentrate logistics infrastructure. Five-to-ten year viability hinges on successful commissioning of paste backfill systems and concentrate pipeline construction. Watch Indonesian domestic fuel subsidy adjustments as margin compression signal for rotary kiln-electric furnace operations.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Acid Leach Capacity Buildout | Unlocks battery-grade nickel sulfate from Indonesian laterite deposits for Tesla and Volkswagen Group offtake. |
| Backward Integration into Cobalt Concentrate Trading | Glencore's African sourcing network secures European cathode manufacturer compliance with REACH protocols. |
| Block Cave Mining Technology Deployment | Rio Tinto's Oyu Tolgoi expansion sustains tier-one copper concentrate supply to Chinese State Grid Corporation. |
| Direct OEM Cathode Precursor Partnership | BHP Group's Western Australian nickel bypasses trader intermediaries for South Korean battery manufacturer feedstock. |
| Paste Backfill Tailings Management Retrofit | Antofagasta's Chilean operations reduce surface dam requirements under tightening environmental regulator protocols. |
Research Methodology
A spread of perspectives from mine operations directors, smelter procurement managers, battery cathode precursor engineers, and environmental compliance officers converged on the working assumptions. Primary fieldwork combined with trade flow databases, SEC 10-K extraction disclosures, and customs concentrate export records anchored the analysis. Bottom-up reserve-to-production modeling and top-down end-use demand aggregation triangulated volume estimates.
Segmentation dimensions modeled span metal type, mining method, end-use industry, and processing technique across the analysis window. Copper concentrate treatment charge trajectories and nickel laterite energy intensity curves informed CAGR derivation. Hydrometallurgical capacity commissioning schedules and renewable energy installation pipelines served as industry-specific forecast inputs.
Material uncertainties — regulatory tailings dam standard revisions, battery chemistry substitution velocity, and Indonesian domestic fuel subsidy adjustments — sit outside the modeled envelope. Forecasts reflect assumptions documented in primary interview transcripts and secondary source validation. Recalibration cycles align with material shifts in cathode chemistry adoption and jurisdictional permitting velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Global Magnesium Market
Metals & Minerals
Boron Ore Market
Metals & Minerals
Gold Recycling Market
Metals & Minerals
Saudi Arabia and GCC Ferrosilicon Market
Metals & Minerals
Diamond Market
Metals & Minerals
India Colored Gemstones Market
Metals & Minerals
Tantalum Pentoxide Market
Metals & Minerals
Recycled Scrap Metal Market
Metals & Minerals
Manganese Mining Market
Metals & Minerals
Silver Mining Market
Metals & Minerals
Global Chromium Salt Market
Metals & Minerals
Lithium Ingots Market
Metals & Minerals
Mineral Screening Market
Metals & Minerals
Testing Inspection and Certification TIC for the Metals and Minerals Market
Metals & Minerals
India CRNO Steel Lamination Market
Metals & Minerals
Cobalt Carbonate Market