
 Synthetic and Bio Emulsion Polymers Market | 2026-2036
Synthetic and Bio Emulsion Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
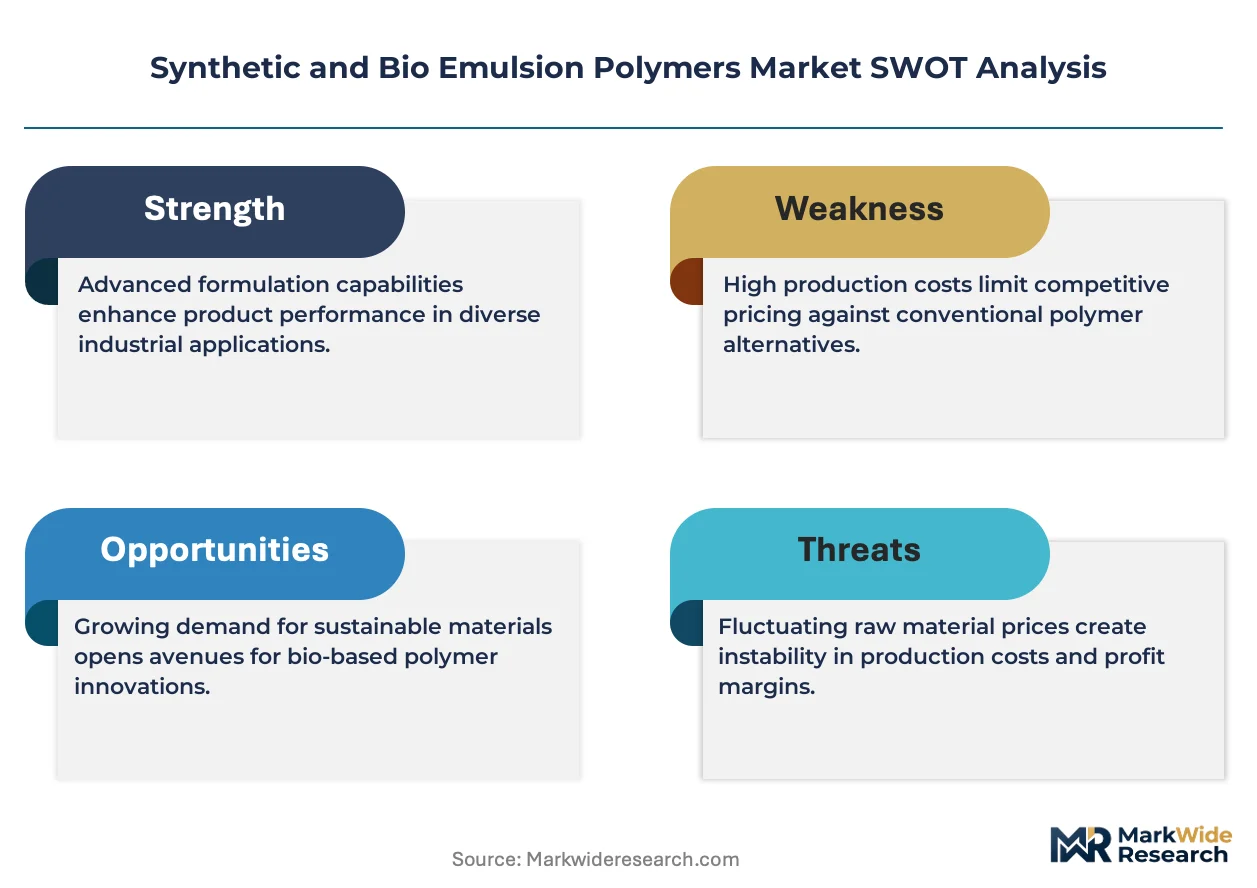
Synthetic and Bio Emulsion Polymers Market Analysis
China is narrowing the technology gap in continuous emulsification systems through state-backed polymer research parks. BASF SE leverages its Ludwigshafen integrated site to sustain captive acrylic acid supply for emulsion derivatives. Dow Inc. anchors North American vinyl acetate-ethylene capacity with downstream control into paints and coatings channels.
Synthetic and bio emulsion polymers are aqueous dispersions of polymer particles stabilized by surfactant systems, typically manufactured via free-radical emulsion polymerization at 40-80°C with particle sizes ranging from 50-500 nanometers; they serve primarily as film-forming binders that replace solvent-borne systems in coatings, adhesives, and sealants. Acrylic emulsions dominate architectural coatings applications where weatherability and UV resistance command premium positioning. Polyurethane emulsions represent the fastest-expanding product class as footwear and textile laminators shift from solvent-based polyurethane dispersions to waterborne alternatives.
EPA VOC regulations and REACH substance restrictions are tightening permissible solvent content in consumer-facing coatings, forcing reformulation toward high-solids emulsion systems across US and European supply chains. China's MEE enforcement of GB standards on industrial emissions is accelerating domestic producer migration from batch to continuous emulsification technology. Stakeholders must monitor regulatory divergence between bio-based content mandates in Europe and performance-driven specifications in Asia to align R&D portfolios with divergent compliance pathways.
Market Dynamics
Waterborne formulation mandates across major economies are compressing solvent-borne capacity while concentrating procurement among integrated resin suppliers capable of certifying bio-based content. This regulatory compression favors producers with backward integration into acrylic acid and surfactant feedstocks.
Growth Catalysts
- REACH substance restrictions:ECHA's tightening authorization lists for hazardous monomers are redirecting European coatings procurement toward certified bio-based emulsion systems.
- Construction sector water-based specification:Green building certification schemes in Germany and China now mandate low-VOC interior coatings, pulling architectural emulsion demand upward.
- Continuous emulsification technology:China's state-backed polymer research parks are scaling automated reactor trains that improve batch consistency and reduce energy intensity.
Market Restraints
- Acrylic acid supply concentration:Captive production at Ludwigshafen and select Gulf Coast complexes leaves merchant buyers exposed to force majeure disruptions.
- Technical performance gaps in exterior durability:Bio-based alkyd emulsions currently fail to match solvent-borne benchmarks in tropical humidity cycling.
- Propylene feedstock volatility:Crude-linked naphtha cracking economics transmit directly to acrylic ester cost structures.
Strategic Opportunities
- EU Green Deal bio-content mandates:Renewable carbon certification pathways open premium positioning for fermentation-derived lactic acid copolymers.
- Textile laminating waterborne conversion:Footwear and automotive seating producers in Vietnam and Indonesia remain underpenetrated by polyurethane dispersions.
- MEE enforcement acceleration:China's GB standard compliance deadlines are forcing domestic batch producers toward technology licensing partnerships.
Industry Challenges
- Emulsion polymerization process control expertise:Continuous reactor operation demands scarce chemical engineering talent familiar with radical kinetics at scale.
- REACH registration dossier timelines:New bio-based monomers face multi-year substance evaluation periods before commercial authorization.
- Legacy coating line retrofit costs:Waterborne viscosity and drying profiles require capital-intensive spray booth modifications at mid-tier applicators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic and Bio Emulsion Polymers Market |
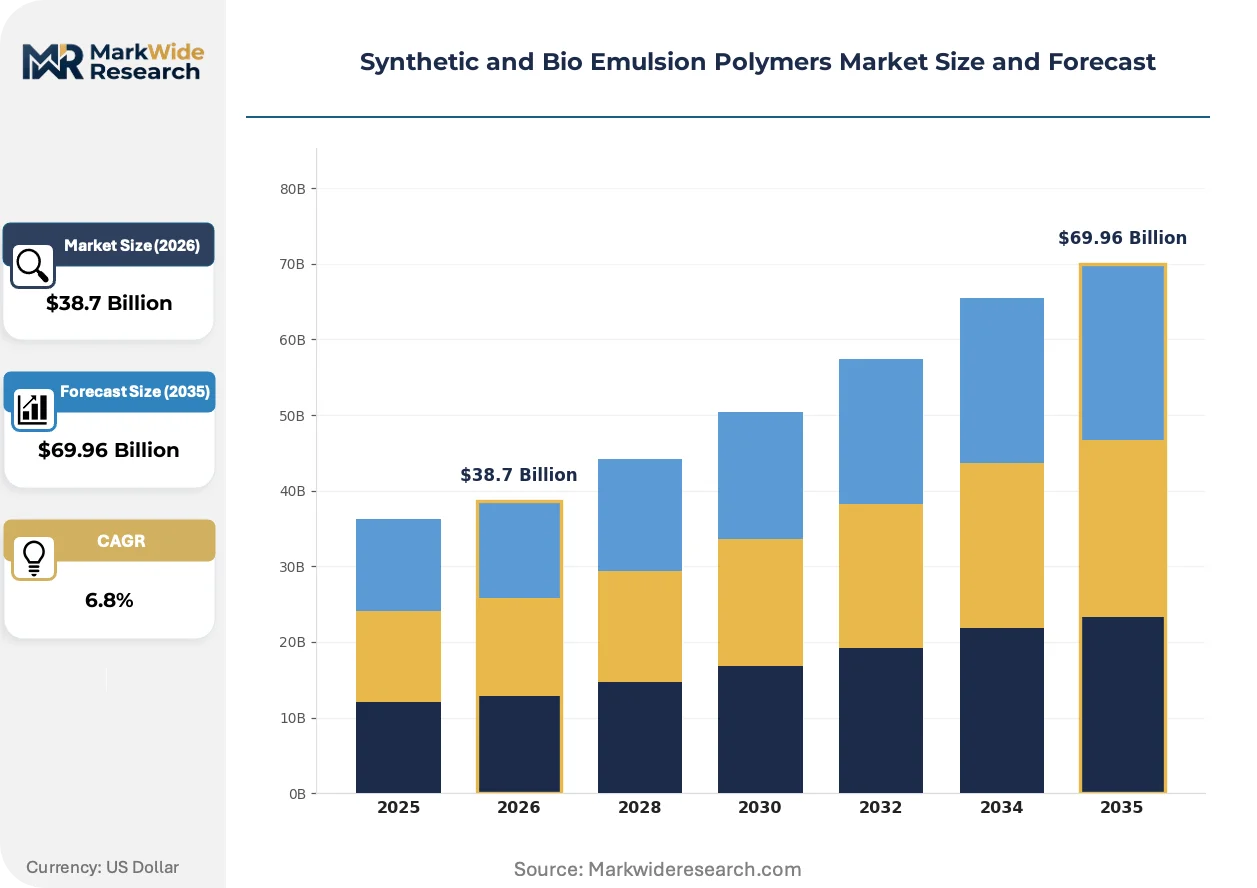
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic Emulsions, Polyurethane Emulsions, Vinyl Acetate Emulsions, Polystyrene Emulsions End User: Construction, Paints & Coatings, Adhesives, Textiles Technology: Batch Emulsification, Continuous Emulsification, High-Pressure Homogenization, Ultrasonic Emulsification Application: Coating, Sealants, Inks, Specialty Products |
| Companies Covered | BASF SE, Dow Inc., Arkema, Wacker Chemie AG, Celanese Corporation, Synthomer plc, Trinseo PLC, Evonik Industries AG, Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic and Bio Emulsion Polymers Market Emerging Trajectories
Formulation science is pivoting toward hybrid architectures that combine bio-derived feedstock content with synthetic performance reliability. This convergence is compressing traditional product category boundaries.
Core-shell particle morphology engineering is rendering obsolete single-phase acrylic emulsions in premium architectural coatings. Tier-one paint manufacturers in Germany and the United States are qualifying gradient-composition particles that deliver block resistance without coalescent solvents. The technology is rendering obsolete conventional minimum film formation temperature trade-offs.
EPA VOC regulations are tightening permissible solvent content in consumer-facing coatings, forcing reformulation across US supply chains. The Industrial Maintenance Coatings NESHAP is compressing allowable HAP emissions from 340 g/L toward 250 g/L equivalents. Marine and protective coatings segments are responding with high-solids emulsion hybrids that sacrifice some gloss retention for compliance security.
Specification-driven procurement now dominates large construction projects, with EPD and HPD documentation requirements filtering supplier pools. Master specification writers at major architecture firms in China and Germany are embedding bio-based content minimums that exclude uncertified emulsion sources. Healthcare and education verticals show the fastest adoption of material health screening protocols.
Synthetic and Bio Emulsion Polymers Market Segmentation
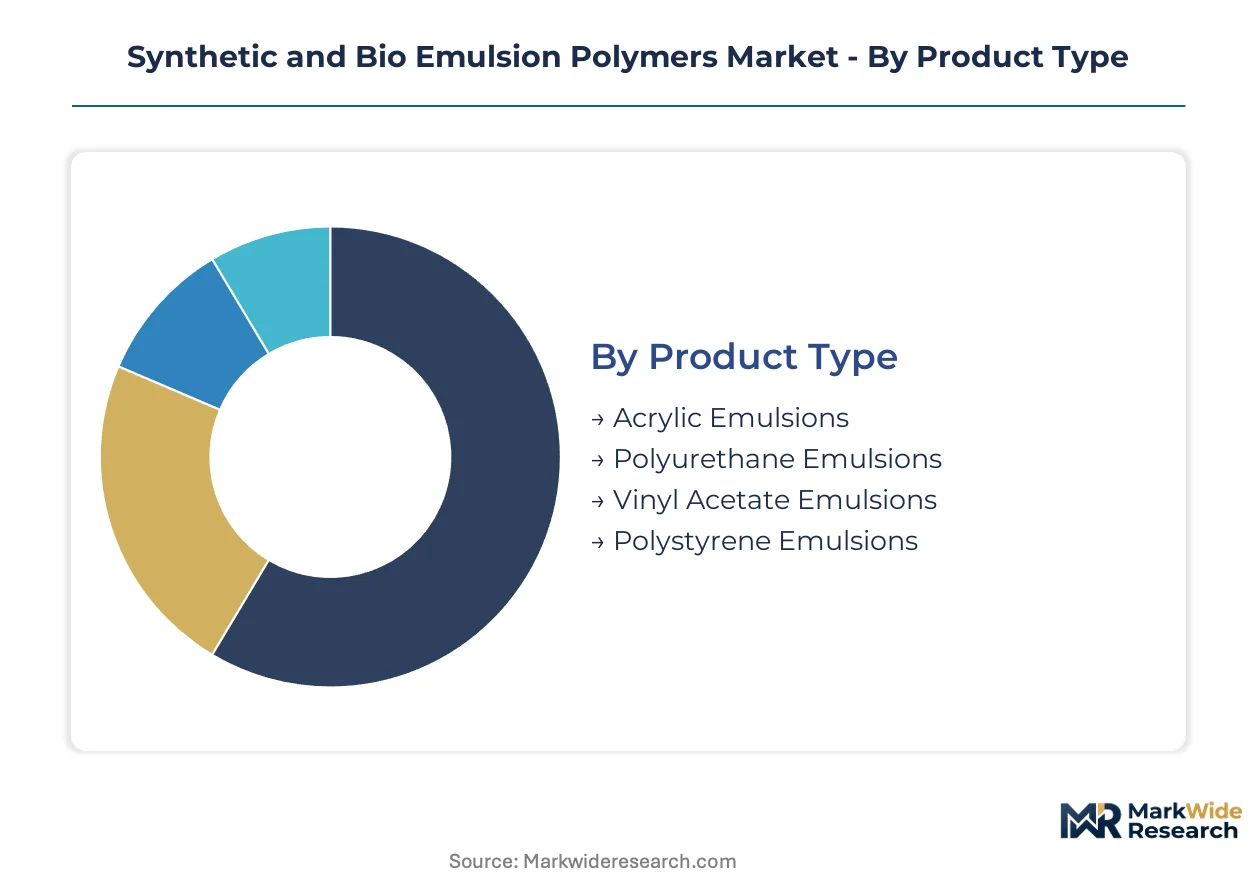
Emulsion polymer value chains fragment across four distinct taxonomies that reshape procurement criteria and margin structures. Product type determines raw material exposure and performance ceiling. Technology choice separates capital-intensive continuous operators from batch-dependent regional suppliers.
Product Type:
Use-case spectrum spans weatherable architectural coatings to flexible textile laminates, with each chemistry commanding distinct specification regimes and certification requirements.
- Acrylic Emulsions:Copolymer and homopolymer dispersions of acrylate and methacrylate esters deliver UV stability and exterior durability. German and US architectural coatings procurement concentrates here as EPD documentation requirements filter supplier pools toward certified low-VOC formulations.
- Polyurethane Emulsions:Aliphatic and aromatic polyurethane dispersions provide abrasion resistance and flexibility without solvent carriers. Footwear laminators in Vietnam and automotive seating producers in Indonesia are converting from solvent-borne systems as MEE-aligned GB standards tighten industrial emissions enforcement.
- Vinyl Acetate Emulsions:Vinyl acetate-ethylene and vinyl acetate homopolymer systems dominate interior architectural adhesives and economical coatings. Dow Inc. anchors captive VAE capacity with downstream integration into North American distribution channels.
- Polystyrene Emulsions:Styrene-butadiene and styrene-acrylic hybrids serve carpet backing and paper coating applications. Cost-driven procurement in Chinese packaging sectors sustains volume despite inferior weatherability versus pure acrylics.
Established volume favors acrylic emulsions; emerging adoption favors polyurethane dispersions.
End User:
Customer type segmentation separates project-driven construction procurement from specification-dominated industrial coatings channels.
- Construction:Green building certification schemes in Germany and China mandate low-VOC interior coatings, pulling architectural emulsion demand upward through master specification requirements at major architecture firms.
- Paints & Coatings:Industrial maintenance and protective coatings segments respond to EPA NESHAP compression with high-solids emulsion hybrids that sacrifice some gloss retention for compliance security.
- Adhesives:Pressure-sensitive and construction adhesive formulations favor vinyl acetate systems for cost-sensitive packaging and woodworking applications.
- Textiles:Footwear and automotive seating producers drive waterborne polyurethane penetration as laminators abandon solvent-based bonding in tropical manufacturing zones.
Construction procurement concentrates in Germany and China; textile conversion accelerates across Southeast Asian manufacturing hubs.
Technology:
Process maturity separates legacy batch operators from state-backed continuous reactor deployments that improve batch consistency and reduce energy intensity.
- Batch Emulsification:Conventional stirred-tank reactors with surfactant-stabilized free-radical polymerization dominate mid-tier Chinese producers facing MEE enforcement deadlines.
- Continuous Emulsification:Automated reactor trains with inline mixing and real-time particle size control enable BASF SE's Ludwigshafen complex to sustain captive acrylic acid integration.
- High-Pressure Homogenization:Mechanical shear systems produce sub-100 nanometer particle distributions for inkjet ink and specialty coating applications.
- Ultrasonic Emulsification:Cavitation-based dispersion methods serve niche pharmaceutical and cosmetic emulsion production with minimal thermal degradation.
Batch infrastructure dominates installed base; continuous systems claim steepest expansion trajectory through technology licensing partnerships.
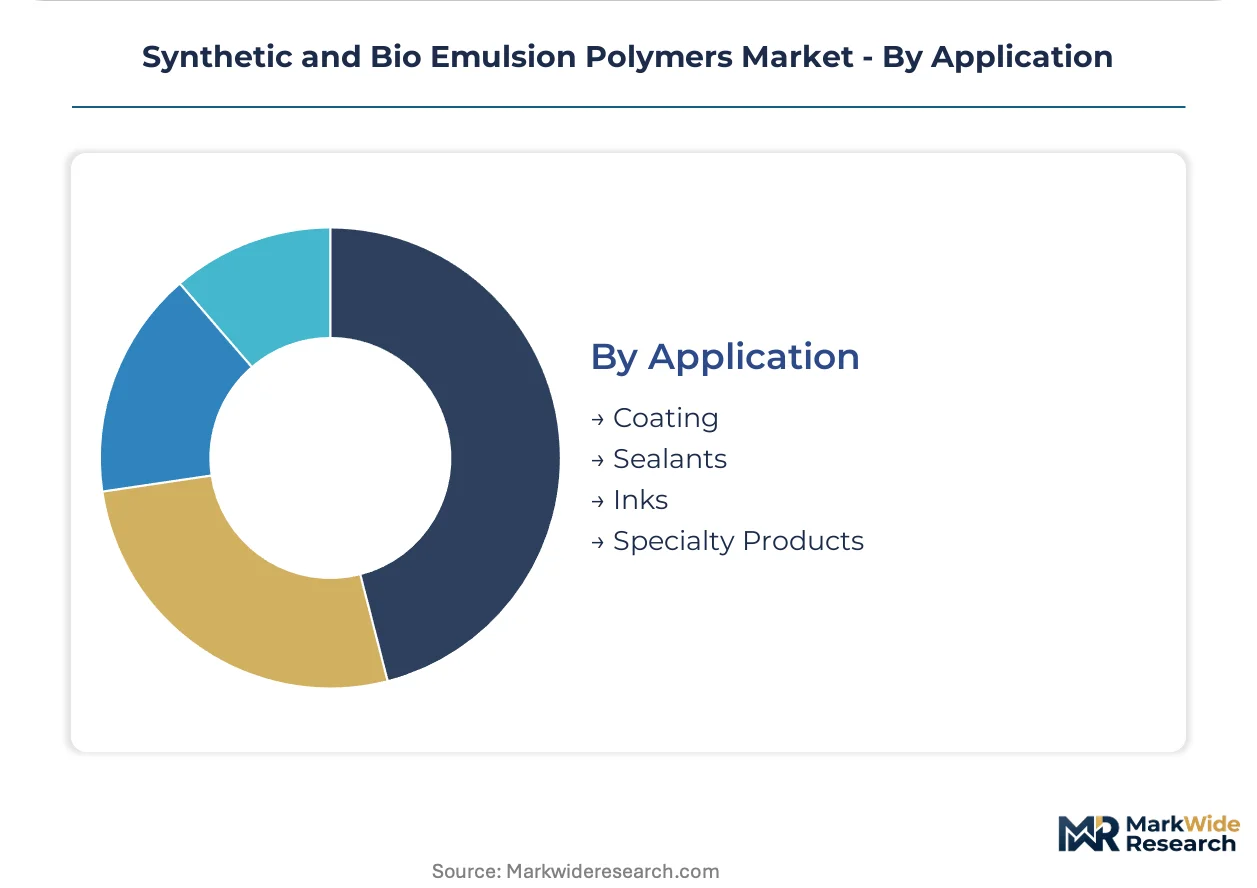
Application:
Functional requirement tiering separates commodity coating volumes from sealant durability specifications and specialty product margins.
- Coating:Architectural and industrial protective films represent the largest consumption category, with core-shell particle morphology engineering displacing single-phase acrylics in premium positioning.
- Sealants:Construction joint and automotive seam sealing applications demand elastomeric recovery and adhesion to diverse substrates.
- Inks:Flexographic and gravure printing formulations require sub-micron particle size distributions and rapid drying profiles.
- Specialty Products:Cosmetics, pharmaceuticals, and agricultural formulations command formulation confidentiality and regulatory dossier completeness.
Coating volumes anchor revenue concentration; specialty products capture margin premiums through certification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE enforcement of GB standards on industrial emissions is redirecting Chinese formulation strategies toward waterborne systems. REACH substance restrictions and EU Green Deal bio-content mandates are compressing solvent-borne capacity across European supply chains. EPA VOC regulations are forcing reformulation toward high-solids emulsion systems in US architectural and industrial coatings channels.
China
Construction sector procurement of water-based binders is intensifying as green building certification schemes mandate low-VOC interior coatings. MEE enforcement of GB standards on industrial emissions is accelerating domestic producer migration from batch to continuous emulsification technology. State-backed polymer research parks in Jiangsu and Zhejiang provinces are scaling automated reactor trains that improve batch consistency.
Germany
Green building certification schemes are pulling architectural emulsion demand upward through master specification requirements at major architecture firms. REACH authorization lists for hazardous monomers are redirecting European coatings procurement toward certified bio-based emulsion systems. The Ludwigshafen chemical complex sustains captive acrylic acid supply for emulsion derivatives through backward integration.
United States
Industrial maintenance and protective coatings segments are responding to EPA NESHAP compression with high-solids emulsion hybrids. The Industrial Maintenance Coatings NESHAP is compressing allowable HAP emissions from 340 g/L toward 250 g/L equivalents. Gulf Coast petrochemical complexes anchor vinyl acetate-ethylene capacity with downstream control into paints and coatings distribution channels.
Vietnam
Footwear laminators are converting from solvent-borne polyurethane systems to waterborne alternatives as MEE-aligned standards tighten regional supply chain requirements. Textile and apparel export growth is driving specification-driven procurement of waterborne polyurethane dispersions. Manufacturing zones near Ho Chi Minh City remain underpenetrated by polyurethane dispersion suppliers relative to regional demand growth.
Indonesia
Automotive seating producers are abandoning solvent-based bonding systems in tropical manufacturing zones. Export-oriented textile laminators face compliance pressure from EU and US brand owners to eliminate solvent carriers from supply chains. Industrial clusters in Java are licensing continuous emulsification technology to meet international buyer certification requirements.
Synthetic and Bio Emulsion Polymers Market Vendor Landscape
Capability concentration sits with integrated petrochemical majors possessing captive acrylic acid and surfactant feedstocks; scale advantage sits with regional batch operators serving cost-sensitive packaging and woodworking applications. The vendor base stratifies across three archetypes: backward-integrated multinational chemical conglomerates, specialty polymer houses with formulation expertise, and regional commodity emulsion suppliers. Dominant competitive moves include technology licensing partnerships for continuous reactor deployment and portfolio diversification into bio-based monomer certification pathways.
Within the integrated chemical conglomerate tier, BASF SE and Dow Inc. represent archetypes of backward integration into acrylic acid and vinyl acetate-ethylene feedstocks respectively. Arkema occupies a position exemplifying specialty polymer expertise with differentiated polyurethane dispersion portfolios. These three anchors demonstrate how geographic concentration of petrochemical infrastructure shapes competitive positioning across European, North American, and Asian supply corridors.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Arkema |
| Wacker Chemie AG |
| Celanese Corporation |
| Synthomer plc |
| Trinseo PLC |
| Evonik Industries AG |
| Lubrizol Corporation |
| Others |
Supply Flow & Price Mechanics
Undercapacity in German acrylic acid derivatives is compressing regional pricing power toward Ludwigshafen-integrated suppliers while forcing merchant buyers into long-term offtake negotiations. This utilization imbalance propagates through European coatings supply chains as REACH-compliant bio-based alternatives command certification premiums.
Pricing Analysis
Price spreads between German-certified bio-based emulsions and Chinese batch-produced acrylics are widening as EPD documentation requirements filter supplier pools. Three-tier pricing structure across premium certified, standard compliant, and economy unverified levels separates specification-driven construction procurement from cost-sensitive packaging buyers. Cost compression in the economy tier is intensifying because Vietnamese and Indonesian textile laminators are consolidating volume toward waterborne polyurethane suppliers. Brand-owning architectural coatings manufacturers show least price sensitivity; mid-tier Chinese woodworking adhesive buyers exhibit highest.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are emerging as competitive weapons among integrated resin suppliers serving undercapitalized Southeast Asian textile laminators. Feedstock concentration in Germany, China, and the United States shapes procurement security calculations for downstream coatings formulators. Acrylic acid, surfactant systems, and VAE monomers draw from naphtha-cracking economics tethered to crude volatility. Single-source vulnerability sits with Ludwigshafen captive production disruptions. Distribution runs through regional resin distributors with technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterborne formulation mandates across major economies position this market in early-cycle expansion, with polyurethane dispersion penetration into Southeast Asian footwear manufacturing representing the clearest adoption tailwind.
For Market Incumbents: Entrench specification control through EPD certification pre-qualification at major German and Chinese architecture firms before REACH authorization lists expand. Backward integration into fermentation-derived lactic acid copolymers secures EU Green Deal compliance pathways against emerging bio-based entrants. Capacity addition in Jiangsu province captures MEE-driven technology licensing demand from domestic batch producers. For New Entrants and Emerging Players: Vietnam's footwear laminating corridor remains underpenetrated by polyurethane dispersion suppliers relative to regional demand growth. White-space targets include Indonesian automotive seating producers abandoning solvent-based bonding and mid-tier Chinese batch operators seeking continuous emulsification technology partnerships. Go-to-market through MEE compliance consulting bundled with reactor licensing accelerates credibility. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty polymer houses with formulation expertise and certified bio-based monomer pathways. Long-term viability over the next decade favors targets with backward integration into acrylic acid or surfactant feedstocks rather than pure formulation plays. The inflection signal to watch is GB standard enforcement acceleration forcing domestic Chinese producer consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Captive feedstock supply insulates BASF and Dow from force majeure disruptions in merchant markets. |
| Continuous Emulsification Technology Licensing | Automated reactor trains enable Chinese producers to meet MEE GB standard compliance deadlines. |
| Bio-Based Monomer Certification Investment | EU Green Deal mandates open premium positioning for fermentation-derived lactic acid copolymers. |
| EPD Documentation Pre-Qualification | Master specification requirements at German architecture firms filter supplier pools toward certified sources. |
| Southeast Asian Distribution Expansion | Vietnamese and Indonesian textile laminators remain underpenetrated by waterborne polyurethane suppliers. |
Methodological Framework
Initial hypotheses were tested against primary input from coatings formulators, resin procurement managers, plant engineers at integrated petrochemical complexes, and regulatory affairs specialists, then refined through secondary validation. Trade data from customs authorities, SEC 10-K filings from disclosed resin segments, ACC and Cefic industry reports, and ECHA REACH registration dossiers anchored quantitative baselines. Bottom-up volume estimates from end-use consumption patterns triangulated against top-down capacity assessments across major production hubs.
Demand-supply balance modeling across the analysis window integrated construction sector specification trends, MEE enforcement timelines, and REACH authorization trajectories. Segmentation dimensions included product chemistry tier, end-use industry vertical, technology maturity level, and regional regulatory cluster. CAGRs derived from slope-intercept fitting of normalized adoption curves against historical penetration benchmarks. Forecast inputs incorporated green building certification scheme adoption rates and continuous reactor deployment schedules.
Macroeconomic conditions sit as an overlay; deviation in crude-linked naphtha pricing, construction spending cycles, or propylene feedstock availability would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology licensing uptake. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Emulsion Polymer Market
Polymers & Resins
Global Polyamide Market
Polymers & Resins
Global Polypropylene Homopolymer (PPH) Market
Polymers & Resins
Global Vinyl Ester Market
Polymers & Resins
India Epoxy Resins Market
Polymers & Resins
Global Polyalkylene Glycol (PAG) and Esters Market
Polymers & Resins
Europe Superabsorbent Polymers Market
Polymers & Resins
Africa Polyether Ether Ketone (PEEK) Market
Polymers & Resins
Polysulfide Market
Polymers & Resins
India Flooring Resins Market
Polymers & Resins
Global High Performance Polyethylene Market
Polymers & Resins
Global Graft Polyols Market
Polymers & Resins
Global Polyether Ether Ketone (PEEK) Market
Polymers & Resins
Polyether Ketone (PEK) Market
Polymers & Resins
Epoxy Resin Reactive Diluent Market
Polymers & Resins
Global High Temperature Resin Market