
 Semi-Crystalline Polymers Market | 2026-2036
Semi-Crystalline Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Semi-Crystalline Polymers Market Analytics
The semi-crystalline polymers market is pivoting on a widening divergence between premium high-performance grades and commodity polyolefin tiers, with the former commanding specialized supply chains and the latter facing margin compression from capacity overshoot. BASF SE leverages its integrated polyamide and PPS portfolio to anchor premium positioning in automotive under-hood applications. Celanese Corporation differentiates through captive acetyl chain control and medical-grade POM specialization. DuPont de Nemours, Inc. sustains technology leadership in aramid-reinforced crystalline thermoplastics for aerospace structural components.
Semi-crystalline polymers exhibit ordered molecular regions with melting points typically spanning 120°C to 340°C, depending on backbone chemistry and crystallinity fraction achieved through controlled cooling rates during injection molding or extrusion. These materials deliver fatigue resistance, chemical inertness, and dimensional stability that amorphous polymers cannot match, making them indispensable for load-bearing automotive and industrial parts. Polyamide and polybutylene terephthalate segments lead in value contribution due to replacement of metal in powertrain and electrical housing applications. Polypropylene occupies the highest volume tier but faces margin stagnation as Chinese producers extend cost advantages through coal-to-olefin integration. Medical-grade and food-grade certifications represent the fastest-expanding margin pools as healthcare and packaging buyers tighten contamination protocols.
REACH substance restrictions and the EU F-Gas Regulation shape material selection in European automotive and electrical markets, while EPA emissions standards and NHTSA fuel economy mandates in the United States drive lightweight polymer substitution in vehicle platforms. China's GB standards and MIIT industrial policy directives enforce localized testing protocols that foreign suppliers must navigate for market access. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance cost asymmetries will increasingly determine which material grades and which producers capture premium positioning in cross-border supply chains.
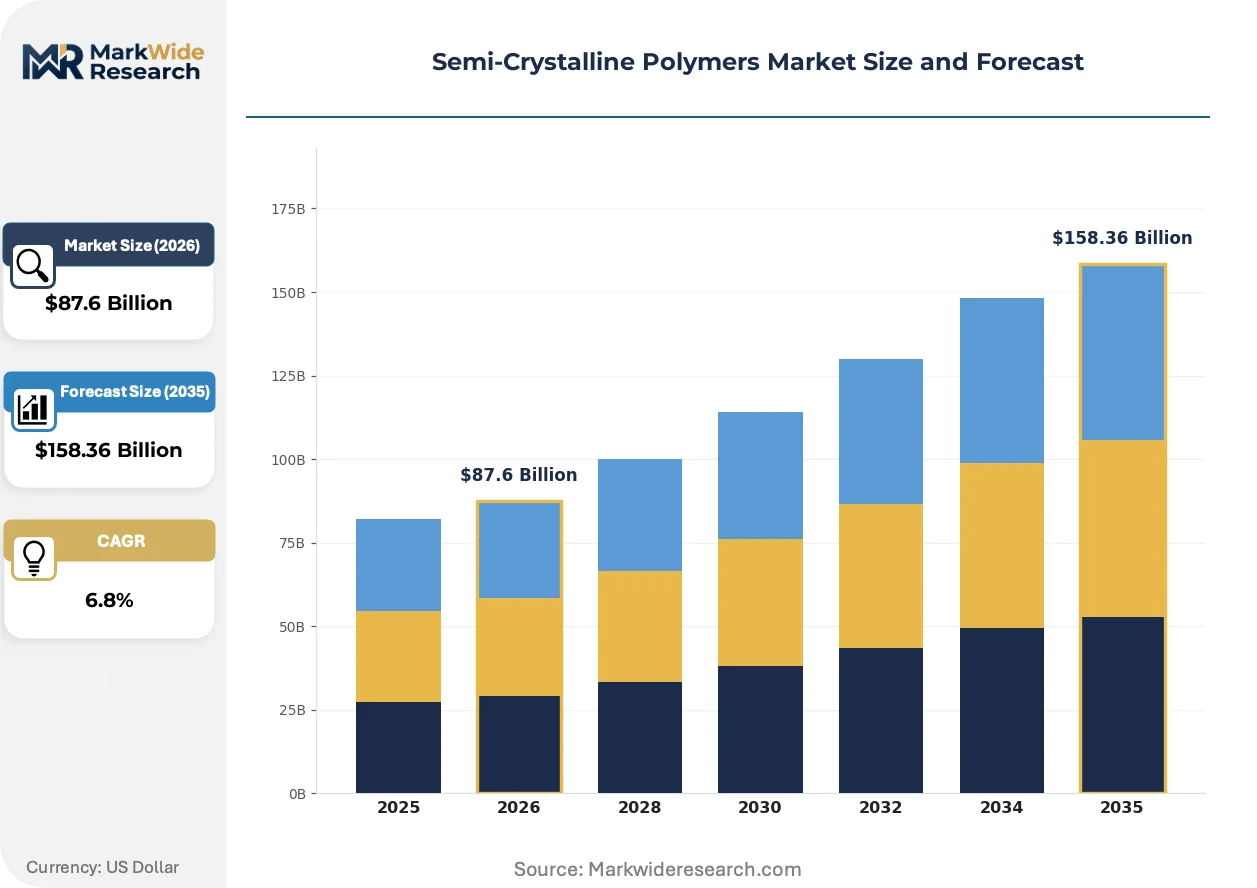
Market Dynamics
Automotive lightweighting mandates and REACH substance restrictions are forcing material substitution decisions across European and Asian supply chains, compressing qualification timelines while expanding specification complexity for engineering polymer grades.
Growth Catalysts
- Automotive Lightweighting Mandates:NHTSA fuel economy standards and EU CO₂ fleet targets are accelerating nylon and PBT penetration in powertrain housings. German OEMs now specify crystalline thermoplastics for engine bay components previously cast in aluminum.
- REACH Compliance Deadlines:ECHA substance restrictions on halogenated flame retardants are redirecting electrical housing demand toward phosphorus-based polyamide compounds. Compounders with pre-certified material libraries capture accelerated qualification pathways.
- Coal-to-Olefins Integration:Chinese producers leveraging coal feedstock economics are expanding polypropylene capacity in Ningbo and Dalian clusters. This input-cost advantage is displacing naphtha-based supply in Asian packaging export chains.
Market Restraints
- Caprolactam Price Volatility:Benzene and cyclohexane input costs swing with crude differentials, compressing polyamide 6 margins for non-integrated compounders. European producers without captive intermediates face margin pressure during upstream spikes.
- Capacity Concentration Risk:Polypropylene homopolymer supply concentrates in Saudi Arabian and Chinese state-controlled complexes. Disruptions at Ras Tanura or Zhoushan facilities transmit rapidly through Asian derivative markets.
- Amorphous Polymer Substitution:Polycarbonate and ABS grades improved with silicone additives are capturing interior automotive panels where heat resistance requirements relaxed. This technical encroachment limits crystalline polymer expansion in cabin applications.
Strategic Opportunities
- Medical Device Certification Pools:USP Class VI and ISO 10993 compliant POM and PBT grades command 40-60% price premiums over industrial equivalents. DuPont and Celanese are expanding cleanroom compounding lines to capture this margin tier.
- India PLI Scheme Alignment:Production-linked incentives for electronics manufacturing are attracting polymer compounders to Gujarat and Tamil Nadu. Medical-grade and connector-grade material demand from smartphone and medical device assemblers is outpacing local supply.
- Bio-Based Feedstock Convergence:Braskem's sugarcane-derived polyethylene and Arkema's castor-oil polyamide 11 are converging with mechanical recycling streams. Brand-owner sustainability commitments are creating specification pull for certified renewable content grades.
Industry Challenges
- Multi-Jurisdiction Certification Timelines:FDA 510(k) clearances for medical-grade polymers run 12-18 months, while EU MDR technical documentation requirements extended review periods post-2021. Synchronized global launches require parallel-track regulatory investment.
- Recycling Stream Separation Complexity:Semi-crystalline polymers require density-based or NIR-sorting separation from amorphous waste streams. Mixed-polymer contamination in mechanical recycling output degrades performance properties below automotive specification thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semi-Crystalline Polymers Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyethylene, Polybutylene, Nylon Application: Packaging, Automotive Components, Electrical Insulation, Consumer Goods End Use Industry: Healthcare, Electronics, Construction, Aerospace Grade: High-Performance, Standard, Medical, Food-Grade |
| Companies Covered | BASF SE, Celanese Corporation, Solvay S.A., DuPont de Nemours, Inc., Evonik Industries AG, Sumitomo Chemical Co., Ltd., Polyplastics Co., Ltd., Arkema Group, Mitsubishi Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semi-Crystalline Polymers Market Evolving Landscape
Advanced nucleating agents and process-controlled crystallinity modulation are rewriting performance benchmarks for injection-molded components, while regulatory substance restrictions and buyer consolidation reshape specification authority.
High-speed nucleating technology for polypropylene is rewriting cycle-time economics in thin-wall packaging and automotive interior applications. Milliken's Hyperform HPN-20E and similar additive packages enable 15-20% faster injection molding through accelerated crystallization kinetics. Tier-1 automotive suppliers in Stuttgart and Toyota City are adopting these grades to meet compressed program timelines without capital expansion.
EU F-Gas Regulation phase-down schedules are compressing demand for fluoropolymer-lined hoses and seals in refrigeration and automotive climate systems. Polyamide 612 and PPS compounds with improved refrigerant compatibility are capturing specification shifts in German compressor manufacturing and French cold-chain equipment assembly. Compounders with pre-validated material cards against R-1234yf and R-454B blends secure accelerated OEM approval.
Consolidated buying desks at automotive Tier-1s and medical device OEMs are compressing supplier rosters to three qualified sources per material grade. This concentration transfers specification authority from compounders to OEM material engineering teams. The shift is most visible in Michigan and southern Germany, where Magna, Bosch, and Continental have centralized polymer procurement under technical category managers with veto power over plant-level sourcing decisions.
Semi-Crystalline Polymers Market Segmentation
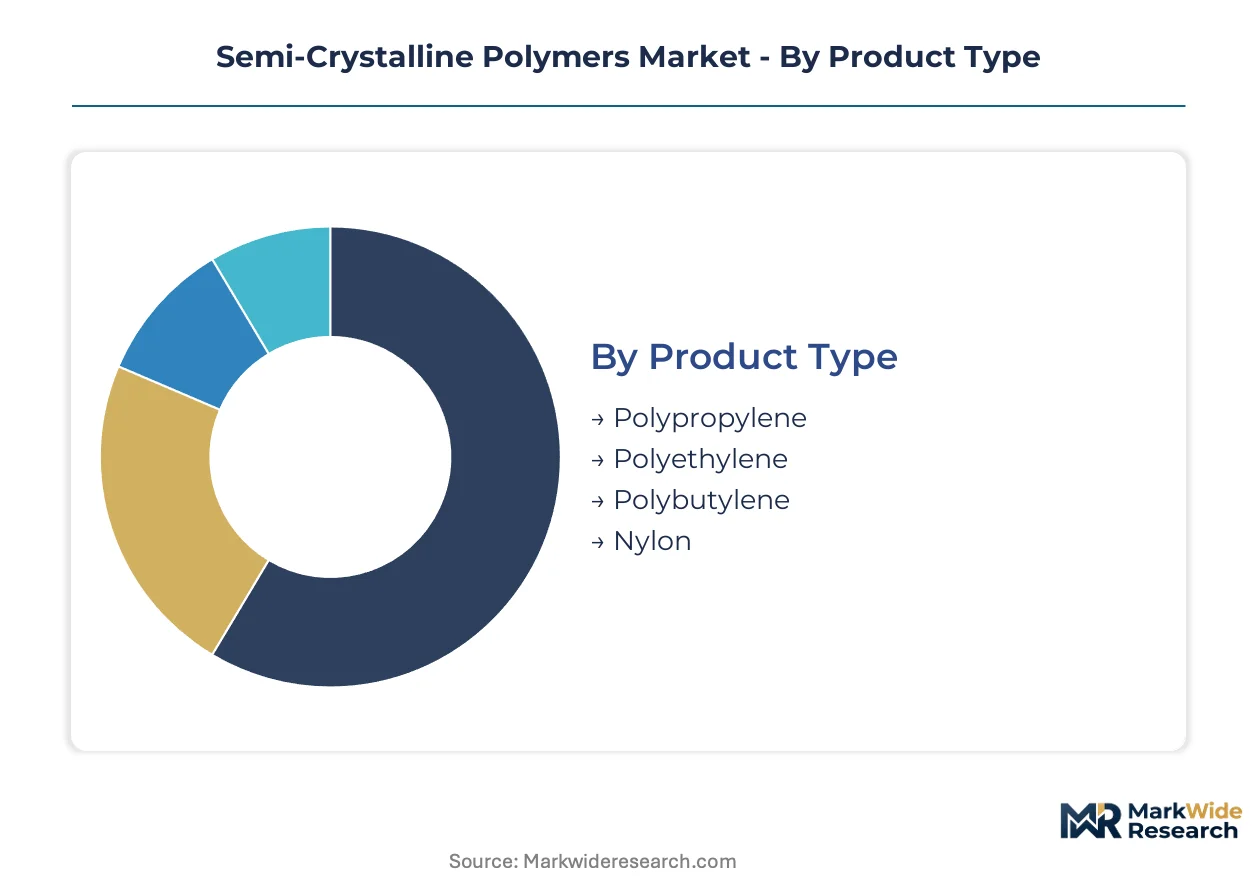
Segmentation in semi-crystalline polymers separates volume-driven commodity tiers from certification-dependent premium grades, with each category commanding distinct supply chain configurations and margin structures. Buyers specify across four intersecting dimensions that determine compounding complexity, regulatory burden, and pricing power.
Product Type:
Supply concentration varies sharply across polymer chemistries, with integrated producers controlling feedstock-intensive grades while specialty compounders dominate engineered alternatives.
- Polypropylene:Homopolymer and copolymer grades crystallize between 120°C and 165°C, delivering chemical resistance and fatigue life for living hinge designs. Demand concentrates in Ningbo and Dalian manufacturing clusters where coal-to-olefin integration enables cost leadership in Asian packaging export chains.
- Nylon:Polyamide 6 and 66 grades achieve crystallinity fractions exceeding 40% through controlled cooling, yielding dimensional stability for under-hood automotive components. German OEMs specify glass-filled nylon for engine bay housings previously cast in aluminum, accelerating qualification timelines for REACH-compliant flame-retardant compounds.
- Polyethylene:HDPE and LDPE semi-crystalline variants serve blow-molded containers and film applications where barrier properties and processability balance cost. Braskem's sugarcane-derived bio-polyethylene is converging with mechanical recycling streams under brand-owner sustainability commitments.
- Polybutylene:PBT and PBAT grades offer faster crystallization kinetics than polyamides, enabling thin-wall electrical housing production with cycle time advantages. Connector-grade demand from smartphone assemblers in Gujarat and Tamil Nadu is outpacing local Indian supply under PLI scheme incentives.
Polypropylene absorbs the bulk of installed capacity; Nylon is expanding most quickly.
Application:
Application-driven segmentation reflects diverging performance thresholds, with automotive and electrical specifications tightening while packaging tolerances widen.
- Automotive Components:Powertrain housings, under-hood brackets, and structural clips require heat deflection temperatures above 150°C and resistance to glycol-based coolants. NHTSA fuel economy standards and EU CO₂ fleet targets are accelerating crystalline thermoplastic penetration in Stuttgart and Toyota City supply chains.
- Electrical Insulation:Connector housings, breaker components, and motor laminations demand tracking resistance and dielectric strength under humidity cycling. ECHA restrictions on halogenated flame retardants are redirecting demand toward phosphorus-based polyamide compounds with pre-certified material libraries.
- Packaging:Thin-wall containers, caps, and closures prioritize cycle time economics and seal integrity over mechanical load-bearing. High-speed nucleating technology from Milliken enables 15-20% faster injection molding through accelerated crystallization kinetics.
- Consumer Goods:Appliance housings, power tool bodies, and sporting equipment balance aesthetics with impact resistance. Amorphous polymer substitution with silicone-modified polycarbonate is capturing interior panels where heat requirements have relaxed.
Packaging claims the highest volume throughput; Electrical Insulation commands the steepest expansion trajectory.
End Use Industry:
Industry verticals impose distinct certification protocols, with healthcare and aerospace specifications filtering supplier rosters most aggressively.
- Healthcare:Surgical instruments, drug delivery devices, and diagnostic housings require USP Class VI and ISO 10993 compliance with extractables testing. DuPont and Celanese are expanding cleanroom compounding lines to capture 40-60% price premiums over industrial equivalents.
- Electronics:Smartphone frames, laptop chassis, and connector systems demand dimensional stability for surface-mount assembly compatibility. India's PLI scheme for electronics manufacturing is attracting compounders to serve medical-grade and connector-grade material demand from device assemblers.
- Construction:Geosynthetics, pipe fittings, and insulation boards prioritize UV resistance and long-term creep performance. Standard polypropylene grades dominate this price-sensitive segment with limited differentiation opportunity.
- Aerospace:Aramid-reinforced crystalline thermoplastics serve structural brackets and interior panels where flame-smoke-toxicity ratings apply. DuPont sustains technology leadership in this specification-intensive niche with extended qualification timelines.
Electronics consumes the widest grade range; Healthcare is climbing the fastest on certification-driven margin expansion.
Grade:
Grade stratification separates specification authority between OEM material engineering teams and plant-level procurement, with premium tiers consolidating supplier rosters.
- Medical:ISO 10993 and FDA 510(k) compliant POM and PBT grades require dedicated cleanroom compounding and batch traceability. Synchronized global launches demand parallel-track regulatory investment with 12-18 month clearance timelines.
- High-Performance:Glass-filled, mineral-filled, and impact-modified compounds achieve tailored mechanical and thermal properties for load-bearing applications. Magna, Bosch, and Continental have centralized procurement under technical category managers with veto power over plant-level sourcing.
- Food-Grade:FDA and EU 10/2011 compliant grades for food contact applications require migration testing and substance inventory documentation. This certification tier is expanding as packaging buyers tighten contamination protocols.
- Standard:Unfilled base resins serve general-purpose molding where performance thresholds permit cost minimization. Chinese coal-to-olefin producers are extending cost advantages through integrated polypropylene capacity.
Standard grade absorbs baseline volume; Medical grade is gaining share fastest on healthcare procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors semi-crystalline polymer demand through integrated compounding facilities serving electronics and automotive export chains. Ningbo and Dalian clusters leverage coal-to-olefin economics to supply Asian packaging markets. Regulatory divergence across major economies is reshaping material qualification pathways and supplier access.
China
MIIT industrial policy directives enforce localized GB standards testing that foreign suppliers must navigate for market access. The eastern manufacturing corridor from Shanghai to Suzhou concentrates integrated polymer compounding for smartphone frames and connector systems. Domestic producers extend cost advantages through coal-based polypropylene capacity expansions.
Germany
EU CO₂ fleet targets and REACH substance restrictions are accelerating crystalline thermoplastic penetration in Stuttgart automotive supply chains. ECHA halogenated flame retardant bans redirect electrical housing demand toward phosphorus-based polyamide compounds. Bavarian and Baden-Württemberg industrial zones host centralized procurement operations for Magna and Bosch.
United States
NHTSA fuel economy standards drive lightweight polymer substitution in Michigan-based vehicle platforms. EPA emissions standards tighten material certification requirements for under-hood applications. The Southeast automotive corridor concentrates Tier-1 supplier demand for high-performance nylon grades.
India
PLI scheme incentives for electronics manufacturing attract compounders to Gujarat and Tamil Nadu assembly zones. CDSCO medical device regulations create parallel certification requirements for USP Class VI compliant grades. Connector-grade material demand from smartphone assemblers outpaces local supply capacity.
Japan
METI energy efficiency mandates support crystalline thermoplastic adoption in Toyota City powertrain operations. JIS standards govern material specifications for precision electrical components. Kansai industrial zones maintain specialized compounding capabilities for medical-grade POM applications.
Semi-Crystalline Polymers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade stratification, with medical and aerospace tiers commanding 40-60% price premiums over industrial equivalents. The vendor base separates into three archetypes: integrated petrochemical giants with captive feedstock control, specialty compounders with cleanroom certification capabilities, and regional producers competing on polypropylene volume. Dominant competitive moves include backward integration into acetyl chain intermediates and geographic expansion into PLI-aligned Indian manufacturing zones.
Within the integrated chemical conglomerate tier, BASF SE and Celanese Corporation exemplify divergent strategic positioning—BASF anchoring European automotive supply chains through polyamide portfolio breadth, Celanese representing North American medical-grade specialization. DuPont de Nemours, Inc. occupies a position in high-performance aramid-reinforced segments where extended qualification timelines protect incumbent positions. These three entities collectively illustrate how certification depth and feedstock control determine margin capture across the premium-standard divide.
| Leading Market Players |
|---|
| BASF SE |
| Celanese Corporation |
| Solvay S.A. |
| DuPont de Nemours, Inc. |
| Evonik Industries AG |
| Sumitomo Chemical Co., Ltd. |
| Polyplastics Co., Ltd. |
| Arkema Group |
| Mitsubishi Chemical Corporation |
| Others |
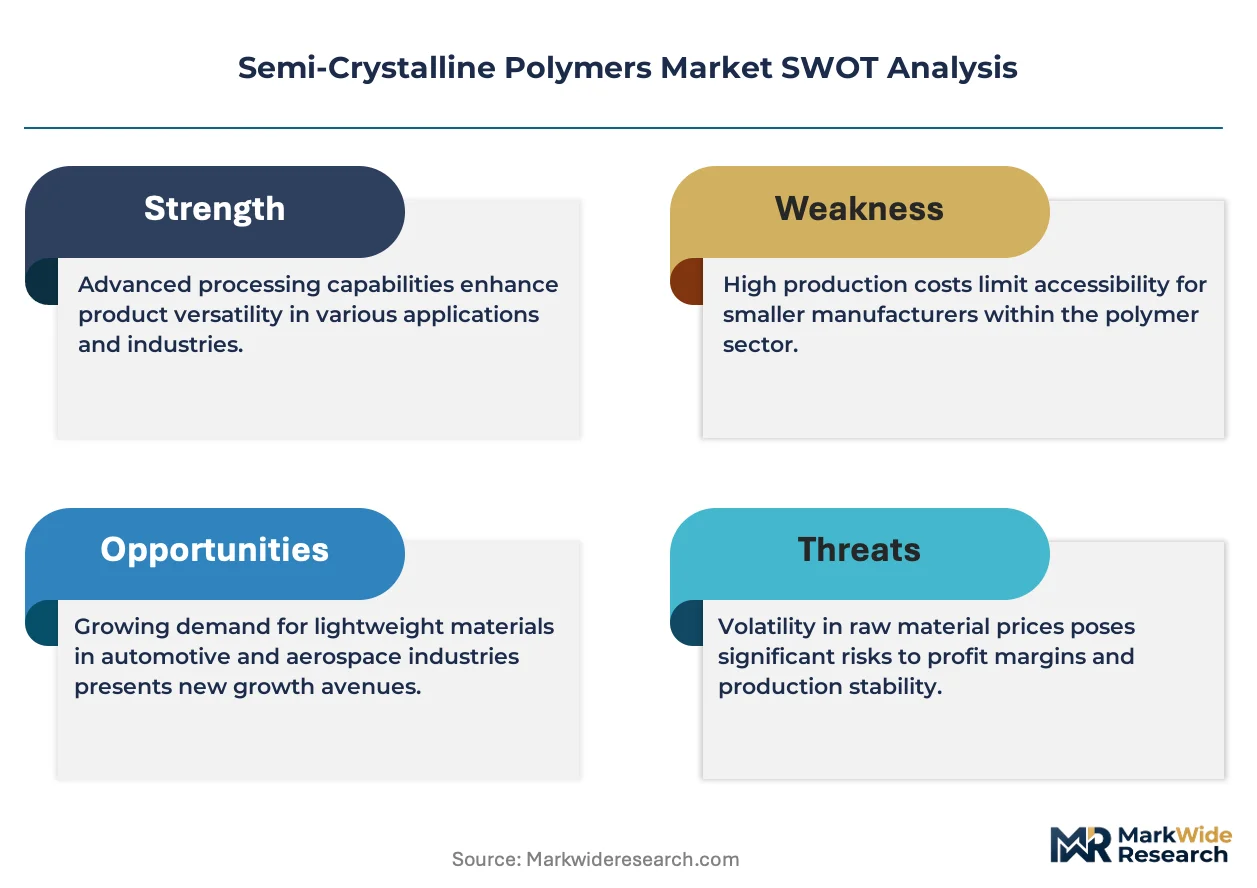
Value Network & Pricing Analysis
Benzene and cyclohexane price indices cascade through semi-crystalline polymer supply chains into three distinct pricing tiers. Coal-to-olefin economics in Ningbo and Dalian compress polypropylene margins while REACH-compliant polyamide compounds command certification premiums in Stuttgart supply chains.
Pricing Analysis
Medical-grade certification anchors value-based pricing at 40-60% premiums over industrial equivalents. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 10993 compliance depth and flame-retardant certification status. Cost compression in commodity polypropylene intensifies because Chinese coal-based capacity expansions displace naphtha-derived supply. Packaging buyers exhibit highest price sensitivity while healthcare procurement teams prioritize contamination protocols over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Magna and Bosch procurement centers in Michigan and Baden-Württemberg. Supply concentrates in Germany, China, and Saudi Arabia for feedstock-integrated polyamide and polypropylene grades. Raw material flows draw from benzene, caprolactam, and acetyl chain intermediates. Single-source vulnerability concentrates at Ras Tanura and Zhousan complexes where disruptions transmit rapidly through Asian derivative markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semi-crystalline polymers occupy a technology-transition phase as high-speed nucleating agents displace conventional cooling-rate engineering. Phosphorus-based flame-retardant polyamides are supplanting halogenated legacy compounds under ECHA restrictions.
For Market Incumbents: Acquire cleanroom compounding assets to anchor medical-grade certification capabilities. Backward integration into caprolactam intermediates defends margin position against benzene price volatility. Expand capacity in Gujarat and Tamil Nadu to capture PLI-aligned electronics demand before local supply catches up. For New Entrants and Emerging Players: Bio-based feedstock convergence represents a technology-first wedge into sustainability-driven specification pools. Underpenetrated connector-grade PBT demand in Indian electronics assembly offers the most penetrable entry point. Lead with USP Class VI pre-certification to bypass 12-18 month FDA clearance timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty compounders with captive acetyl chain control in North American medical markets. Long-term viability hinges on certification depth rather than volume scale. Watch ECHA substance restriction expansion as the inflection signal for phosphorus-based compound demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Intermediates | Captive caprolactam supply insulates BASF and Celanese from benzene cost swings. |
| Cleanroom Compounding Expansion | DuPont's medical-grade POM lines capture 40-60% price premiums in surgical instrument supply chains. |
| PLI Scheme Geographic Alignment | Gujarat and Tamil Nadu facilities serve smartphone assemblers under India's electronics manufacturing incentives. |
| Bio-Based Feedstock Certification | Braskem's sugarcane-derived polyethylene converges with mechanical recycling under brand-owner sustainability commitments. |
| High-Speed Nucleating Technology Deployment | Milliken's Hyperform HPN-20E enables 15-20% faster injection molding for thin-wall automotive applications. |
Research Methodology
SEC 10-K filings, Cefic polymer trade reports, and customs import-export databases formed the secondary backbone for this analysis. Primary interviews with polymer plant managers, Tier-1 automotive procurement leads, medical device regulatory affairs directors, and distribution channel partners validated demand assumptions. Bottom-up grade-by-grade volume estimates triangulated against top-down industry association aggregates.
Historical trendline analysis across automotive production cycles and electronics assembly expansion patterns anchored the projection framework. Segmentation modeling incorporated grade tier, end-use industry, certification level, and regional production hub dimensions. CAGRs derived from elasticity-adjusted demand curves for nylon, PBT, and polypropylene chemistries. Forecast inputs included NHTSA fuel economy standard stringency and EU F-Gas Regulation phase-down schedules.
Several conditions sit outside the modeled scope, including force majeure disruptions at Ras Tanura or Zhoushan facilities and unanticipated ECHA substance restriction expansions. Forecasts reflect assumptions about sustained coal-to-olefin cost advantages and stable REACH compliance timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Styrene Acrylonitrile (SAN) Market
Polymers & Resins
Natural Oil Polyols (NOP) Market
Polymers & Resins
Chlorinated Polyvinyl Chloride (CPVC) Market
Polymers & Resins
Polybenzoxazine Resins Market
Polymers & Resins
Global Solid Masterbatches Market
Polymers & Resins
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Global Flexible Polyurethane Foam Market
Polymers & Resins
Bio-Based PVC Market
Polymers & Resins
Liquid Saturated Polyester Resin Market
Polymers & Resins
Amorphous Polyolefin Market
Polymers & Resins
North America Epoxy Resins Market
Polymers & Resins
Asia-Pacific Super Absorbent Polymers (SAP) Market
Polymers & Resins
Poly Alpha Olefin (PAO) Market
Polymers & Resins
PET Foam Market
Polymers & Resins
Global Polymer Market
Polymers & Resins
Resin Dispersion Market