
 Peristaltic Pumps Market | 2026-2036
Peristaltic Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Peristaltic Pumps Market Analysis
Aftermarket service revenue is reconfiguring margin pools across the peristaltic pumps landscape. Watson-Marlow Fluid Technology Group leverages its global tubing replacement network to sustain recurring income streams. ProMinent GmbH anchors its position through chemical-resistant pump specialization for harsh industrial environments. IDEX Corporation competes via modular platform architectures that reduce customer downtime across diversified process lines.
Peristaltic pumps are positive-displacement devices that compress and release a flexible tube or hose to propel fluids without contamination, achieving flow rates from microliters per minute to hundreds of cubic meters per hour depending on tube diameter and rotor speed. Their primary purpose centers on sterile, abrasive, or shear-sensitive fluid handling where product isolation from mechanical components remains critical. Tube pumps command premium positioning in laboratory and pharmaceutical dosage applications where disposable fluid paths eliminate cross-contamination risks. Hose pumps dominate heavy-duty chemical processing and mining slurry transfer where reinforced elastomer constructions withstand sustained compression cycles. Laboratory pumps represent the fastest-expanding product category as automated liquid-handling workstations proliferate in genomic and cell-therapy workflows.
FDA enforces Current Good Manufacturing Practice standards that mandate validated cleaning protocols or single-use disposable pump heads in pharmaceutical production, directly elevating demand for certified tubing materials. EPA effluent limitations under the Clean Water Act compel water treatment facilities to specify corrosion-resistant peristaltic dosing systems for precise chemical injection. ISO 13485 quality management requirements for medical devices extend compliance burdens to OEM pump suppliers serving diagnostic instrument manufacturers. Stakeholders must monitor evolving USP Class VI and ISO 10993 biocompatibility testing protocols as cell and gene therapy manufacturing scales from clinical batches toward commercial volumes.
Market Dynamics
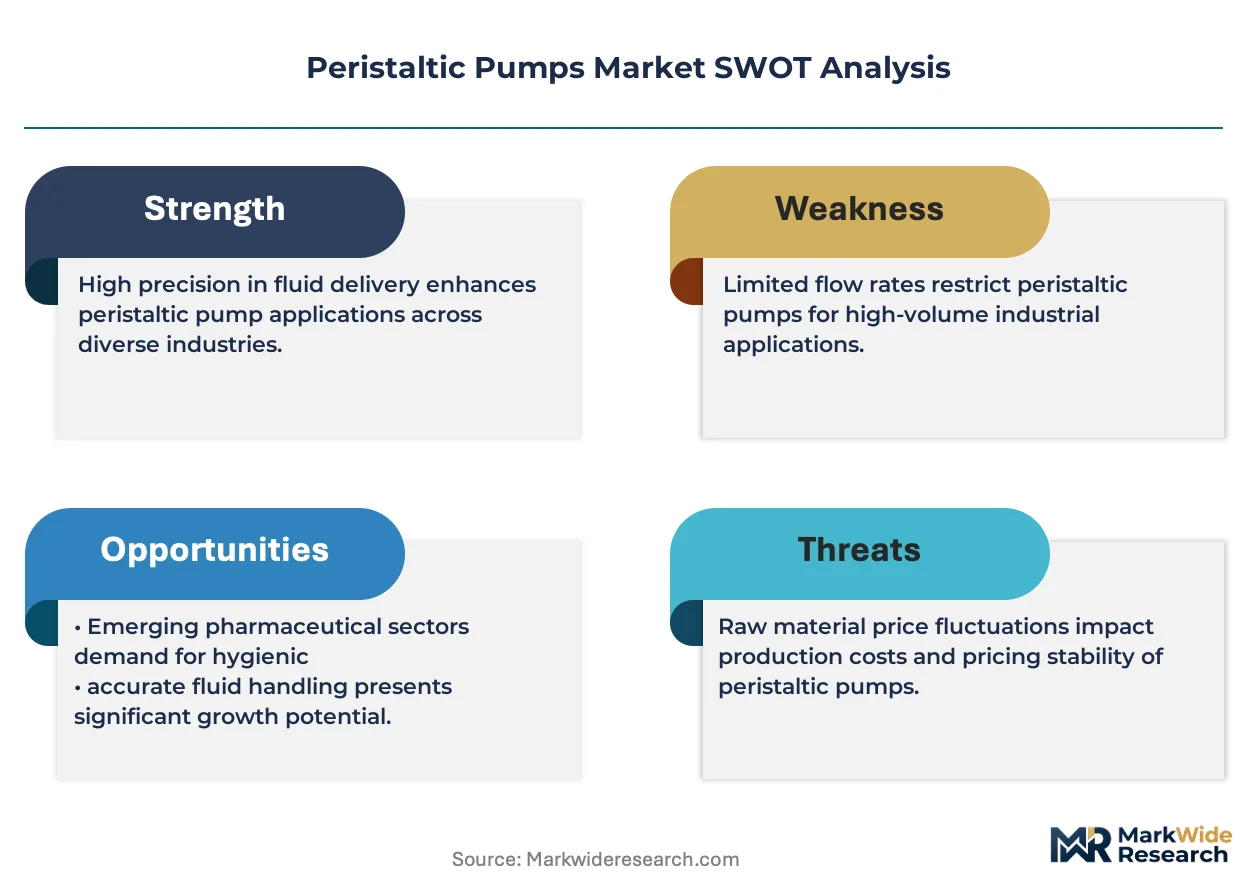
Single-use disposable pump heads are displacing stainless-steel infrastructure across biopharmaceutical manufacturing, forcing incumbent suppliers to revalidate entire tubing portfolios under tightened FDA material standards while absorbing elastomer cost volatility from concentrated specialty polymer suppliers.
Growth Catalysts
- Cell and gene therapy commercialization:USP Class VI biocompatibility mandates for cell therapy manufacturing are accelerating certified tubing demand as batch sizes scale from clinical to commercial volumes.
- EMA's Annex 1 revision:The European sterile manufacturing guideline is compelling pharmaceutical producers to adopt closed-system peristaltic configurations for contamination-critical fill-finish operations.
- Water treatment chemical dosing:EPA Clean Water Act effluent limitations are driving corrosion-resistant pump specifications across municipal and industrial wastewater facilities.
Market Restraints
- Specialty elastomer supply concentration:USP Class VI silicone and platinum-cured tubing feedstocks depend on a limited supplier base concentrated in Germany and the United States, exposing OEMs to price volatility.
- Shear rate limitations:Peristaltic compression mechanics impose maximum velocity constraints that exclude the technology from high-throughput continuous bioprocessing above specific cell density thresholds.
- Diaphragm pump substitution:Aseptic diaphragm technologies are capturing share in high-pressure pharmaceutical applications where tube fatigue limits operational lifespan.
Strategic Opportunities
- India's biopharmaceutical capacity expansion:CDSCO manufacturing license reforms and PLI scheme incentives are attracting peristaltic pump suppliers to serve domestic vaccine and biosimilar production.
- IoT-enabled predictive maintenance:Sensor-integrated pump heads combined with cloud analytics platforms are creating aftermarket service revenue streams independent of hardware replacement cycles.
- Modular skidded systems:Pre-validated pump-tubing-sensor assemblies are reducing commissioning timelines for cell therapy contract manufacturers under ISO 13485 quality frameworks.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization studies for new elastomer formulations extend product development cycles by 18-24 months.
- Legacy system integration:SCADA and distributed control system compatibility requirements complicate deployment of next-generation digitally-enabled pumps in established pharmaceutical facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peristaltic Pumps Market |
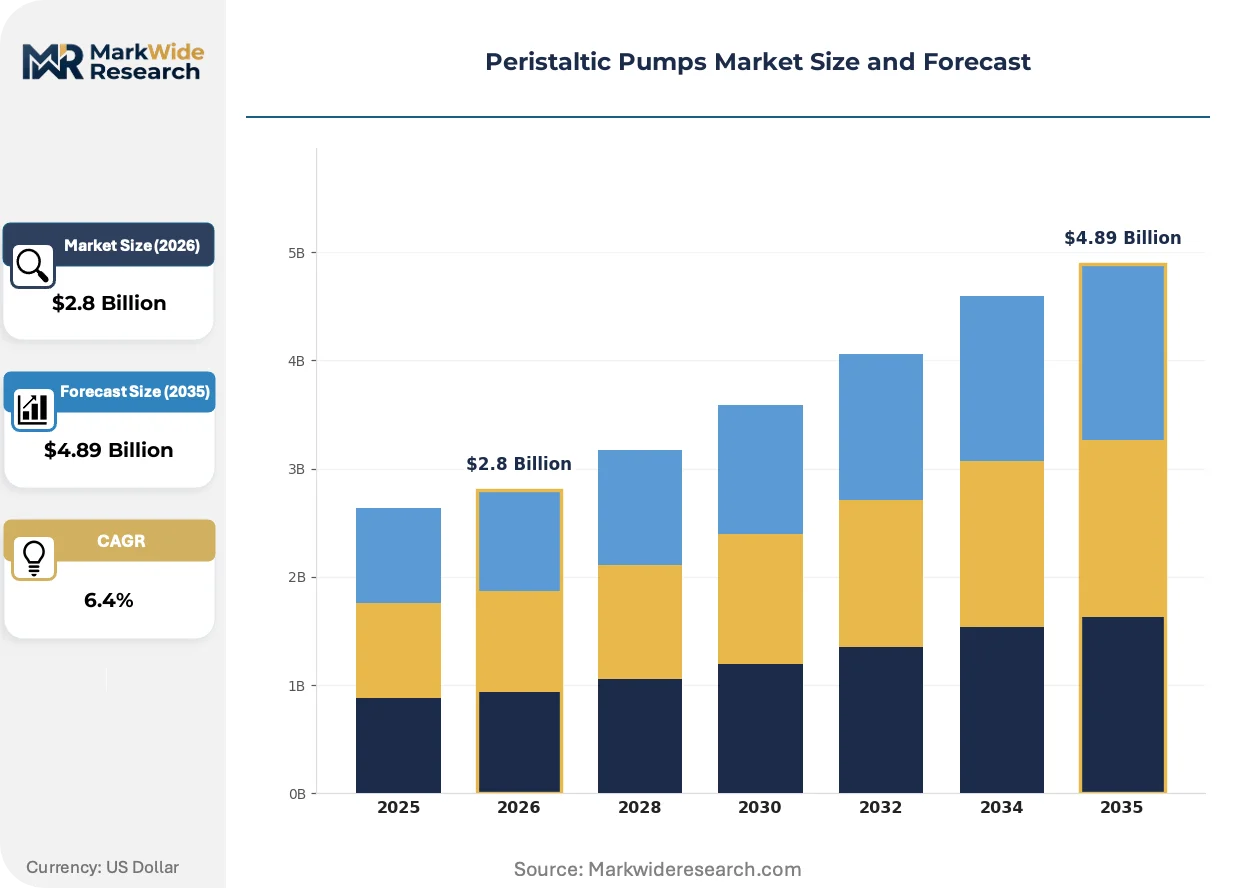
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hose Pumps, Tube Pumps, OEM Pumps, Laboratory Pumps End User: Pharmaceuticals, Food & Beverages, Water Treatment, Chemical Processing Application: Fluid Transfer, Dosage & Dispensing, Waste Management, Laboratory Testing Drive Type: Electric, Pneumatic, Hydraulic, Manual |
| Companies Covered | Watson-Marlow Fluid Technology Group, ProMinent GmbH, IDEX Corporation, Randolph Austin, Gilson Incorporated, Graco, Inc, Verder Group, Ingersoll Rand, Cole-Parmer Instrument Company LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peristaltic Pumps Market Emerging Trajectories
Digitalization of fluid-handling workflows is compressing equipment replacement cycles while elevating software and service components in supplier value propositions. Three developments are restructuring competitive positioning.
Multi-layer composite tubing is hybridizing thermoplastic elastomer cores with reinforced outer braids to extend compression fatigue life in continuous bioprocessing applications. Contract manufacturers operating 24/7 cell culture perfusion systems are adopting these constructions to reduce changeout frequency. This materials evolution is hybridizing the traditional separation between laboratory-grade tube pumps and industrial hose pumps, enabling single platforms to span broader operating envelopes.
REACH Annex XVII restrictions on phthalate plasticizers are forcing reformulation of legacy PVC tubing compounds used in pharmaceutical and food-contact applications. Compounders must validate replacement plasticizers through full USP Class VI and EU 10/2011 migration testing suites. German and Swiss medical device manufacturers are responding fastest, accelerating procurement of pre-certified alternative elastomers ahead of 2025 enforcement deadlines.
Service unbundling is separating hardware ownership from performance guarantees across pharmaceutical capital equipment procurement. Large molecule CDMOs are negotiating availability-based contracts where pump suppliers retain asset ownership and assume maintenance liability. This model is most advanced in Massachusetts and North Carolina biopharma clusters, where facility utilization rates above 85 percent justify premium service pricing over traditional capital purchase structures.
Peristaltic Pumps Market Segmentation
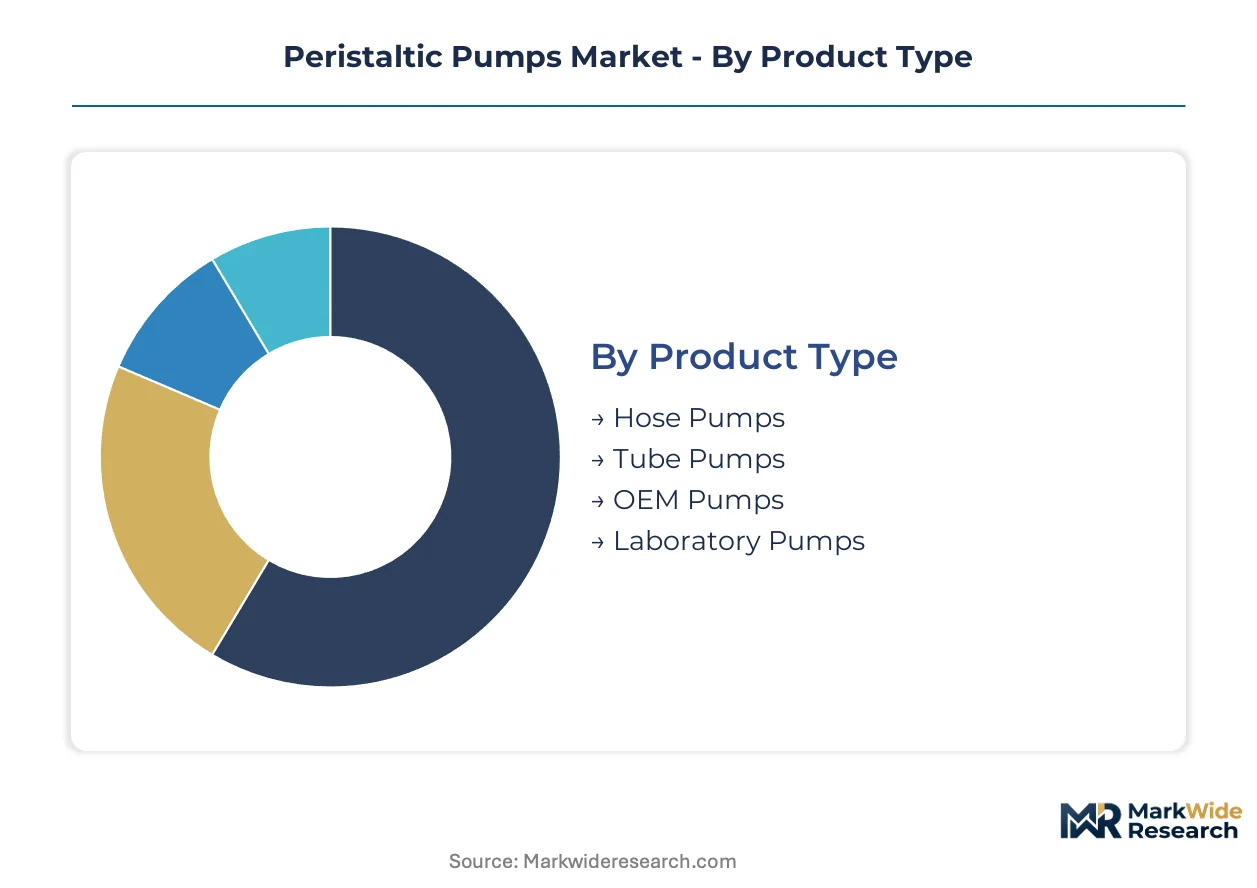
Peristaltic pump segmentation reveals divergent replacement dynamics across product architectures. Tube-based systems in pharmaceutical dosing require quarterly tubing swaps, while industrial hose pumps operate on multi-year maintenance cycles. Understanding these temporal patterns exposes margin concentration and aftermarket opportunity zones.
Product Type:
Cycle-time differentials separate disposable fluid-path systems from capital-intensive industrial configurations. Laboratory and OEM pumps turn over fastest through single-use protocols, while hose pumps anchor long-horizon installed bases.
- Tube Pumps:These compress flexible tubing through rotating rollers or shoes, achieving flow precision within ±1% for microliter-to-liter ranges. Pharmaceutical fill-finish lines in Massachusetts and North Carolina biopharma clusters specify platinum-cured silicone tubes under FDA validation protocols, driving recurring material revenue streams.
- Hose Pumps:Reinforced elastomer hoses withstand sustained compression in mining slurry and chemical processing applications. German industrial facilities specify these for 24/7 abrasive media transfer where tube fatigue would limit operational lifespan.
- OEM Pumps:Compact integrated units designed for embedding in diagnostic instruments and automated liquid-handling workstations.
- Laboratory Pumps:Benchtop configurations for genomic workflows and cell-therapy process development in academic and contract research settings.
Hose pumps anchor the volume base while laboratory pumps gain share at the steepest rate.
End User:
Cost-tier stratification separates validated pharmaceutical systems from price-sensitive industrial specifications. Premium-grade pumps command 3-5x hardware multiples in regulated environments versus standardized chemical-processing units.
- Pharmaceuticals:Aseptic manufacturing mandates USP Class VI elastomer compliance and ISO 13485 quality management certification. Single-use disposable pump heads eliminate cleaning validation burdens in cell therapy commercialization.
- Water Treatment:Municipal and industrial facilities specify corrosion-resistant dosing systems for precise chemical injection under EPA effluent limitations.
- Chemical Processing:Harsh media handling requires reinforced hose constructions and chemically inert tubing compounds.
- Food & Beverages:Hygienic design standards and EU 10/2011 migration compliance govern pump selection for ingredient dosing and CIP applications.
Pharmaceuticals concentrates margin capture while water treatment expands most quickly through infrastructure renewal cycles.
Application:
Volume throughput separates continuous-process specifications from intermittent laboratory operations. High-duty-cycle applications demand fatigue-resistant materials and predictive maintenance integration.
- Dosage & Dispensing:Precision volumetric control for pharmaceutical batching and reagent addition. Automated workstations in genomic laboratories specify these for nanoliter-accurate liquid handling.
- Fluid Transfer:Bulk movement of shear-sensitive and abrasive media without product contamination.
- Waste Management:Secure handling of biohazardous and chemical effluent streams in laboratory and production environments.
- Laboratory Testing:Analytical sample preparation and diagnostic reagent distribution in clinical and research settings.
Fluid transfer dominates installed capacity while dosage and dispensing climbs the fastest on biopharma automation trends.
Drive Type:
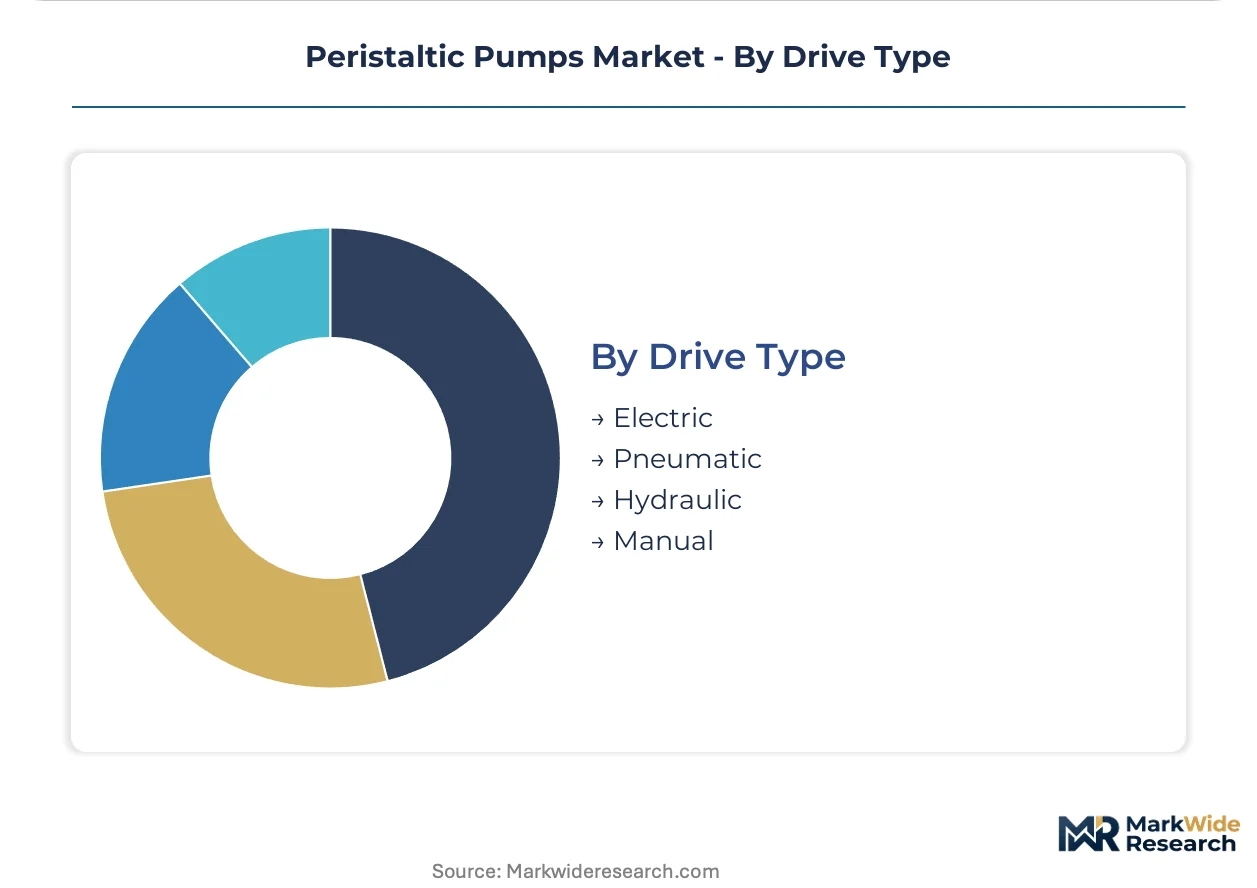
Customer-type preferences split between integrated electric systems for automated processes and pneumatic configurations for explosion-risk environments. Hydraulic and manual drives serve niche specifications.
- Electric:Servo-controlled motors enable precise speed modulation and IoT-enabled predictive maintenance integration. Pharmaceutical manufacturers specify these for closed-loop process control.
- Pneumatic:Compressed-air operation eliminates ignition risks in chemical processing and solvent-handling environments.
- Hydraulic:High-torque drive for heavy-duty mining and slurry applications requiring sustained compression force.
- Manual:Hand-cranked operation for field sampling and emergency backup in remote installations.
Electric drives command the majority position while pneumatic systems retain defensive share in hazardous-area specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland demonstrate the least price elasticity, absorbing premium multiples for USP Class VI validated systems, while Indian and Chinese procurement teams drive hard volume discounts on standardized chemical-processing units.
United States
FDA Current Good Manufacturing Practice enforcement and EPA Clean Water Act effluent rules sustain dual demand tracks for pharmaceutical and water treatment specifications. Massachusetts and North Carolina biopharma clusters concentrate cell therapy manufacturing capacity, with contract manufacturers negotiating availability-based service contracts that transfer maintenance liability to pump suppliers.
Germany
EMA Annex 1 sterile manufacturing guidelines and REACH Annex XVII phthalate restrictions are forcing rapid tubing compound reformulation ahead of enforcement deadlines. B. Braun and Sartorius anchor precision fluid-handling clusters in Hesse and Baden-Württemberg, where medical device manufacturers are accelerating procurement of pre-certified alternative elastomers.
China
NMPA medical device registration requirements and MIIT industrial automation incentives are expanding domestic pump assembly capacity for diagnostic instrument integration. Yangtze River Delta pharmaceutical manufacturers are adopting closed-system peristaltic configurations for contamination-critical fill-finish operations.
India
CDSCO manufacturing license reforms and PLI scheme incentives are attracting peristaltic pump suppliers to serve domestic vaccine and biosimilar production. Maharashtra and Gujarat pharmaceutical hubs are scaling from clinical batch manufacturing toward commercial volumes, tightening demand for certified tubing materials.
Switzerland
Swissmedic medical device quality requirements and ISO 13485 certification frameworks elevate compliance burdens for OEM pump suppliers serving diagnostic instrument manufacturers. Basel and Zurich biotech clusters are driving specification for single-use disposable pump heads that eliminate cleaning validation burdens.
Peristaltic Pumps Market Vendor Landscape
Capability concentration sits with precision pharmaceutical specialists; scale advantage sits with diversified industrial fluid-handling conglomerates. The vendor base stratifies across three tiers: premium-tier validated system suppliers serving FDA-regulated environments, mid-tier modular platform providers optimizing customer downtime reduction, and price-competitive fabricators capturing emerging market chemical-processing volume. Dominant competitive moves include strategic partnerships for pre-validated skidded system assemblies and backward integration into specialty elastomer compounding to secure USP Class VI tubing feedstocks.
Within the precision-tier segment, Watson-Marlow Fluid Technology Group and ProMinent GmbH exemplify divergent specialization archetypes—one leveraging global aftermarket service networks for recurring tubing replacement revenue, the other anchoring position through chemical-resistant pump engineering for harsh industrial environments. IDEX Corporation occupies a modular-platform position that reduces customer downtime across diversified process lines. These three entities represent the competitive spectrum from service-integrated to specification-driven to architecture-flexible positioning.
| Leading Market Players |
|---|
| Watson-Marlow Fluid Technology Group |
| ProMinent GmbH |
| IDEX Corporation |
| Randolph Austin |
| Gilson Incorporated |
| Graco, Inc |
| Verder Group |
| Ingersoll Rand |
| Cole-Parmer Instrument Company LLC |
| Others |
Supply Flow & Price Mechanics
Hesse and Baden-Württemberg pump manufacturing clusters in Germany concentrate USP Class VI tubing compounding capacity, transmitting elastomer cost volatility directly downstream to OEM pricing power across pharmaceutical and industrial segments.
Pricing Analysis
Aftermarket tubing replacement revenue drives lifetime value capture across installed bases. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical systems from industrial chemical-processing units. Cost compression in standard-grade configurations is intensifying because Indian and Chinese procurement teams negotiate volume discounts aggressively. Water treatment municipalities demonstrate highest price sensitivity while Swiss and German biopharma clusters absorb premium multiples for certified single-use systems.
Supply Chain Analysis
Contract manufacturing for pump assemblies concentrates in Germany, Switzerland, and the United States where ISO 13485-certified facilities serve diagnostic instrument OEMs. Platinum-cured silicone feedstocks and reinforced thermoplastic elastomer cores draw from specialty polymer compounders in the Rhineland and New England regions. Single-source vulnerability in USP Class VI elastomer supply exposes OEMs to raw material allocation constraints. Distribution runs through authorized service networks for validated pharmaceutical systems and direct industrial distribution for chemical-processing specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell and gene therapy commercialization represents an early-cycle expansion story as batch scaling from clinical to commercial volumes multiplies addressable pump head demand per manufacturing suite.
For Market Incumbents: Pre-empt diaphragm pump substitution in high-pressure pharmaceutical applications by accelerating multi-layer composite tubing fatigue-life improvements. Secure backward integration into platinum-cured silicone compounding to reduce feedstock cost volatility exposure. Anchor position through pre-validated skidded system partnerships with Massachusetts and North Carolina contract manufacturers.
For New Entrants and Emerging Players: Maharashtra and Gujarat pharmaceutical hubs in India offer underpenetrated white-space as CDSCO reforms accelerate domestic vaccine and biosimilar capacity buildout. Target IoT-enabled predictive maintenance service unbundling for availability-based contracts that transfer asset ownership from capital purchase structures. Pursue modular platform architectures that reduce commissioning timelines for cell therapy CDMOs under ISO 13485 frameworks.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because aftermarket tubing replacement generates annuity-like income streams independent of hardware replacement cycles. Acquisition candidates include specialty elastomer compounders with USP Class VI certification and regional service networks with validated pharmaceutical customer relationships. Monitor CDSCO manufacturing license issuance velocity as inflection indicator for Indian market penetration acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Compounding | Captive supply of USP Class VI tubing reduces exposure to German and US specialty polymer price volatility. |
| Pre-Validated Skidded System Partnerships | Reduces commissioning timelines for cell therapy CDMOs in Massachusetts and North Carolina clusters. |
| IoT-Enabled Predictive Maintenance Platform | Creates service revenue streams independent of hardware replacement cycles for pharmaceutical installed bases. |
| Geographic Expansion into Indian Manufacturing Hubs | CDSCO reforms and PLI incentives attract suppliers to Maharashtra and Gujarat vaccine production capacity. |
| Multi-Layer Composite Tubing Development | Extends compression fatigue life for 24/7 cell culture perfusion systems in continuous bioprocessing applications. |
Methodological Framework
A spread of perspectives from pharmaceutical manufacturing engineers, biomedical equipment procurement managers, aftermarket service directors, and regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EMA Annex 1 guidance documents, ISO 13485 certification registries, and customs trade data for pump and tubing imports. Bottom-up installed base modeling and top-down industry revenue triangulation anchored volume and value estimates.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture (tube, hose, OEM, laboratory), end-use industry (pharmaceutical, water treatment, chemical processing, food and beverage), application type (dosage, fluid transfer, waste management, laboratory testing), and drive configuration (electric, pneumatic, hydraulic, manual). CAGRs were derived from elasticity-adjusted adoption curves and replacement cycle analysis. Industry-specific forecast inputs incorporated EMA Annex 1 sterile manufacturing guideline compliance timelines and EPA Clean Water Act effluent rule implementation schedules.
Practitioners should monitor specialty elastomer supplier allocation announcements, CDSCO manufacturing license issuance rates, and REACH Annex XVII enforcement actions for early signals of forecast revision. Quarterly review of USP Class VI tubing spot pricing, Indian PLI scheme beneficiary lists, and Massachusetts biopharma facility utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Pressure Washer Pump Oil Market
Pumps and Control Devices
Radial Split Pump Market
Pumps and Control Devices
Dry Vacuum Pumps Market
Pumps and Control Devices
India Solar Water Pump Systems Market
Pumps and Control Devices
Industrial Oil Filter Machine Market
Pumps and Control Devices
Wind Powered Water Pumps Market
Pumps and Control Devices
Global Commercial Pumps Market
Pumps and Control Devices
Centrifugal Pump Market
Pumps and Control Devices
Magnetic Drive Pumps Market
Pumps and Control Devices
Cooling Pump Market
Pumps and Control Devices
Global Vacuum Pump Market
Pumps and Control Devices
Air Breathing Hose Market
Pumps and Control Devices
Dosing Pumps Market
Pumps and Control Devices
Pool Heat Pumps Market
Pumps and Control Devices
Chemical Pump Market
Pumps and Control Devices
Mist Sprayer Pumps Market