
 Electrostatic Spraying System Market | 2026-2036
Electrostatic Spraying System Market Size, Share, and Industry Trends Forecast 2026-2036
Electrostatic Spraying System Market Insights
The EPA's emerging guidance on electrostatic sprayer efficacy validation is restructuring procurement criteria across institutional cleaning programs. Graco leverages its industrial fluid handling heritage to anchor positions in automotive paint coating installations. Victory Innovations specializes in portable disinfection architectures for healthcare and education facilities. EvaClean competes through chemical-system bundling that simplifies operator training and compliance documentation.
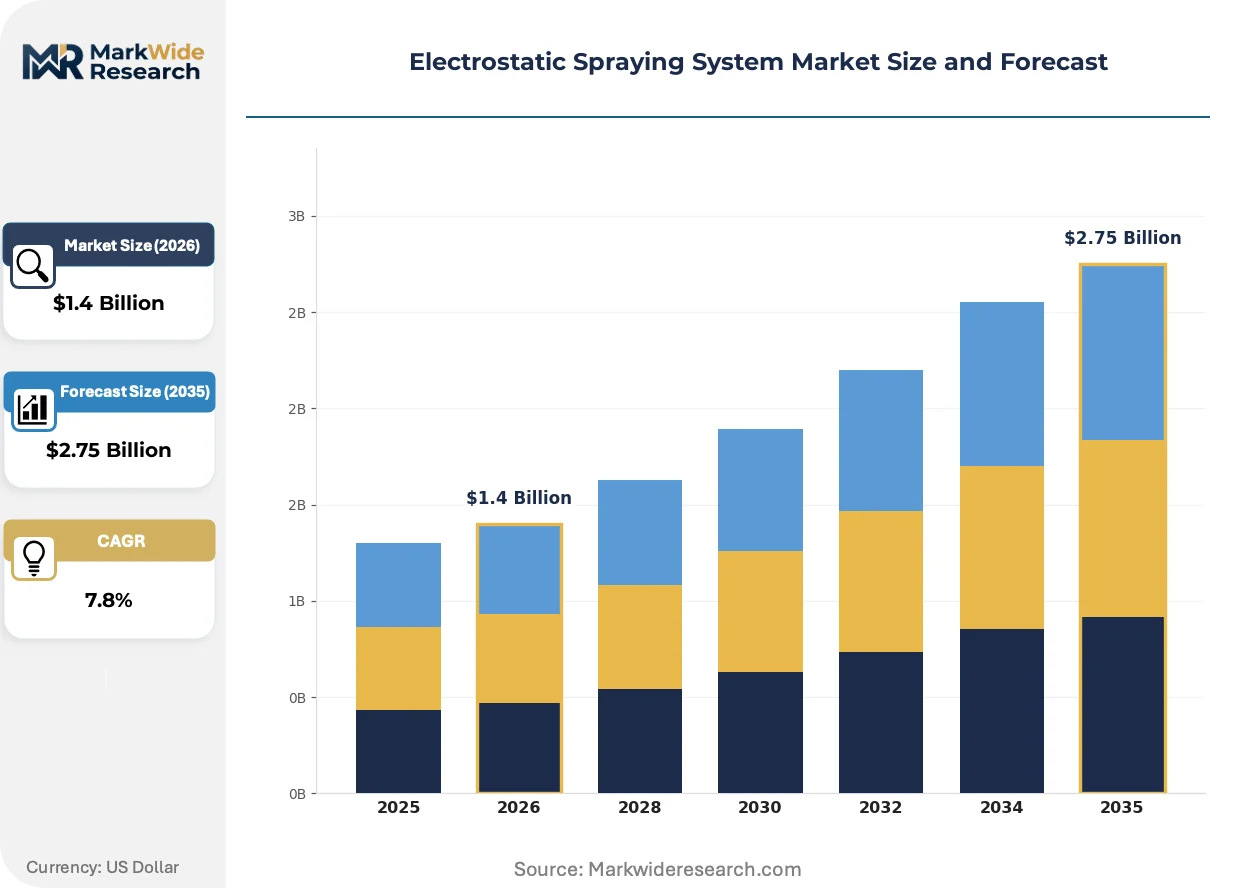
An electrostatic spraying system charges liquid droplets to 20-80 kV, creating electrostatic attraction that wraps coated surfaces with transfer efficiency exceeding 80 percent versus 30-40 percent for conventional pressure spraying. The technology serves precision coating, disinfection, and agricultural chemical application where uniform coverage and reduced waste command operational priority. Air-assisted technology dominates installed base volumes while handheld units represent the fastest-expanding solution category as facilities decentralize cleaning protocols. Disinfection application generates the densest margin pool, driven by healthcare and building maintenance end users with stringent pathogen-control mandates.
EPA registration requirements, OSHA worker exposure standards, and FDA device classification pathways collectively shape product development timelines and market access conditions for electrostatic spraying equipment in the United States. State-level health department adoption guidelines for hospital environmental services further fragment compliance requirements across jurisdictions. Stakeholders must monitor evolving efficacy testing protocols and chemical compatibility certifications to sustain competitive positioning as regulatory scrutiny intensifies.
Market Dynamics
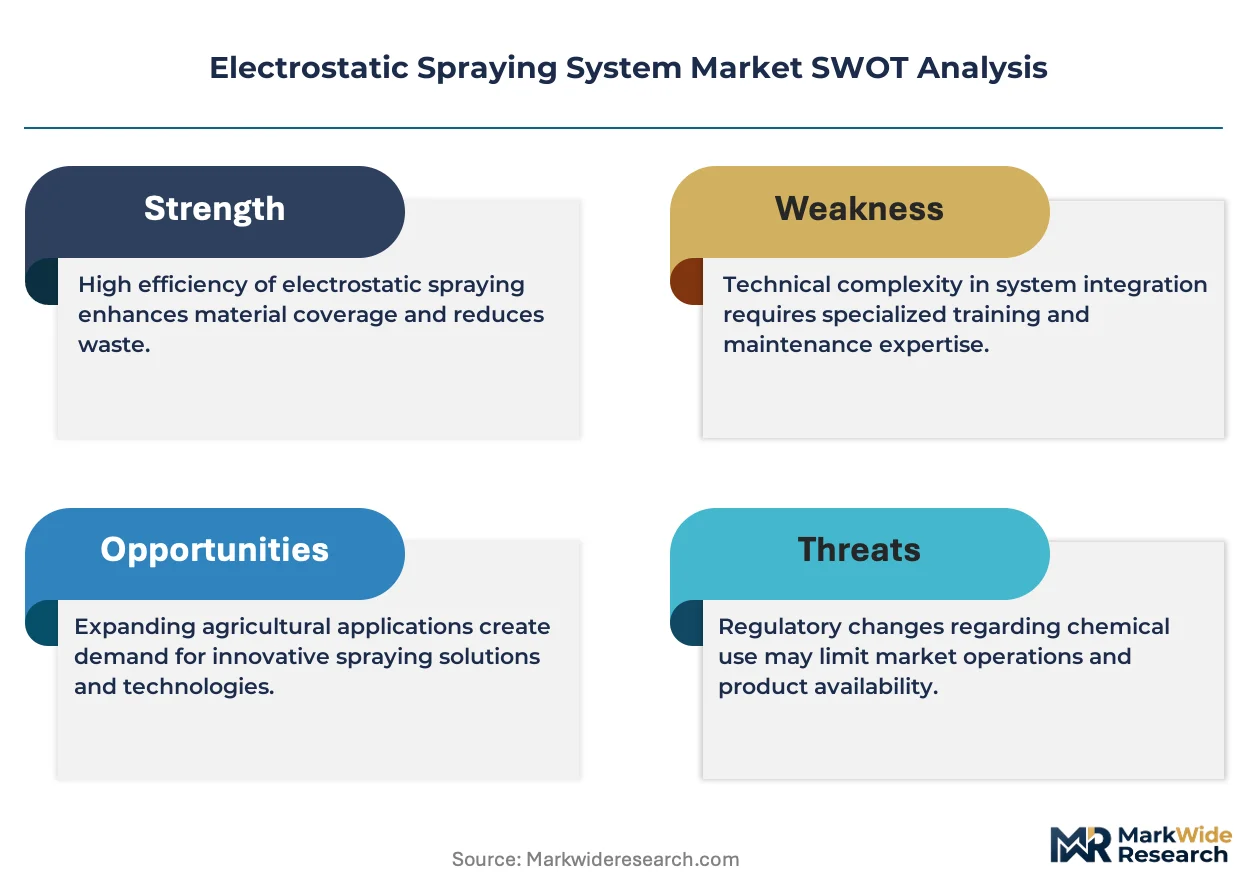
EPA efficacy validation protocols for electrostatic sprayers are restructuring procurement criteria across institutional cleaning programs, forcing manufacturers to redesign testing documentation and chemical compatibility frameworks before market access.
Growth Catalysts
- Healthcare Infection Prevention Mandates:Hospital-acquired infection control budgets in the United States are elevating capital allocation toward touchless disinfection infrastructure. EPA-registered antimicrobial claims now require device-specific efficacy validation.
- REACH Chemical Compliance:European industrial coating facilities are retrofitting legacy spray systems to meet volatile organic compound emission thresholds. Electrostatic transfer efficiency above 80 percent reduces solvent waste and compliance exposure.
- Precision Agriculture Chemical Application:Crop protection operations in Brazil and Argentina are adopting charged-droplet technology to reduce pesticide drift and improve canopy penetration. Uniform coverage requirements are displacing conventional aerial and ground spraying methods.
Market Restraints
- High-Voltage Power Electronics Cost Volatility:Semiconductor shortages in 20-80 kV charging module supply chains have extended lead times for handheld unit manufacturers. German and Japanese component suppliers concentrate critical transformer production.
- Substitution by Ultraviolet-C Disinfection:Fixed UVC installations in healthcare corridors are capturing budget share from portable electrostatic disinfection programs. UVC requires no chemical inventory management or operator certification.
- FDA Device Classification Friction:Antimicrobial device claims trigger 510(k) pathway requirements that extend product launch timelines by 12-18 months. Small manufacturers lack regulatory affairs capacity to navigate parallel EPA and FDA submissions.
Strategic Opportunities
- Indian Food Processing Sanitization:FSSAI hygiene mandates for cold chain facilities are creating first-time demand for electrostatic sanitization in dairy and meat processing plants. Domestic manufacturing incentives reduce import duty exposure.
- CE Marking Convergence with MDR:European medical device regulation alignment is enabling electrostatic disinfection equipment to access clinical settings through unified conformity assessment. Dual-use certification opens hospital and pharmaceutical manufacturing verticals.
- Battery Chemistry Advancements:Lithium-ion energy density improvements are extending cordless handheld unit runtime beyond 4 hours. Lighter battery packs are expanding operator acceptance in education and hospitality facilities.
Industry Challenges
- Electrostatic Physics Training Deficits:Facility maintenance staff lack grounding and charge-field comprehension to optimize wrap-around coverage. Manufacturers must develop video-based certification modules to reduce operator error rates.
- Legacy Building Electrical Infrastructure:Older healthcare and school facilities lack dedicated 240V circuits for cart-based electrostatic systems. Retrofit electrical work adds 15-25 percent to total installed cost and delays deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrostatic Spraying System Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Air-Assisted, Electrostatic, Ultrasonic, Manual End User: Agriculture, Healthcare, Automotive, Building Maintenance Application: Pesticide Application, Disinfection, Paint Coating, Surface Treatment Solution: Mobile Systems, Fixed Systems, Handheld Units, Accessories |
| Companies Covered | CloroxPro, Victory Innovations, EMist, Electrostatic Spraying Systems, ByoPlanet International, EvaClean, Graco, Ecolab, Jereh Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrostatic Spraying System Market Trends and Innovations
Electrostatic spraying architecture is fragmenting into application-specific form factors, with power electronics miniaturization and chemical-system bundling reshaping competitive differentiation across disinfection, coating, and agricultural verticals.
Portable electrostatic disinfection equipment is modularizing around swappable battery packs and interchangeable nozzle configurations. School districts and hospitality chains in the United States are standardizing on single-manufacturer fleets to simplify operator training and spare parts inventory. This modularity is compressing total cost of ownership calculations and displacing fixed-installation disinfection systems in mid-sized facilities.
EPA's emerging guidance on electrostatic sprayer efficacy validation is mandating third-party laboratory testing against specific pathogen panels. Equipment manufacturers must now submit droplet size distribution data and surface contact time studies alongside antimicrobial chemical registrations. Healthcare procurement committees in California, Texas, and Florida are rewriting vendor qualification questionnaires to incorporate these validation requirements.
Building service contractors are unbundling electrostatic disinfection from comprehensive janitorial contracts and pricing it as a standalone line item. Facility managers in commercial real estate are comparing per-square-foot electrostatic treatment costs against fogging and manual wipe-down alternatives. This unbundling is most visible in United States Class A office buildings, where tenant health and wellness certifications drive transparent service documentation.
Electrostatic Spraying System Market Segmentation
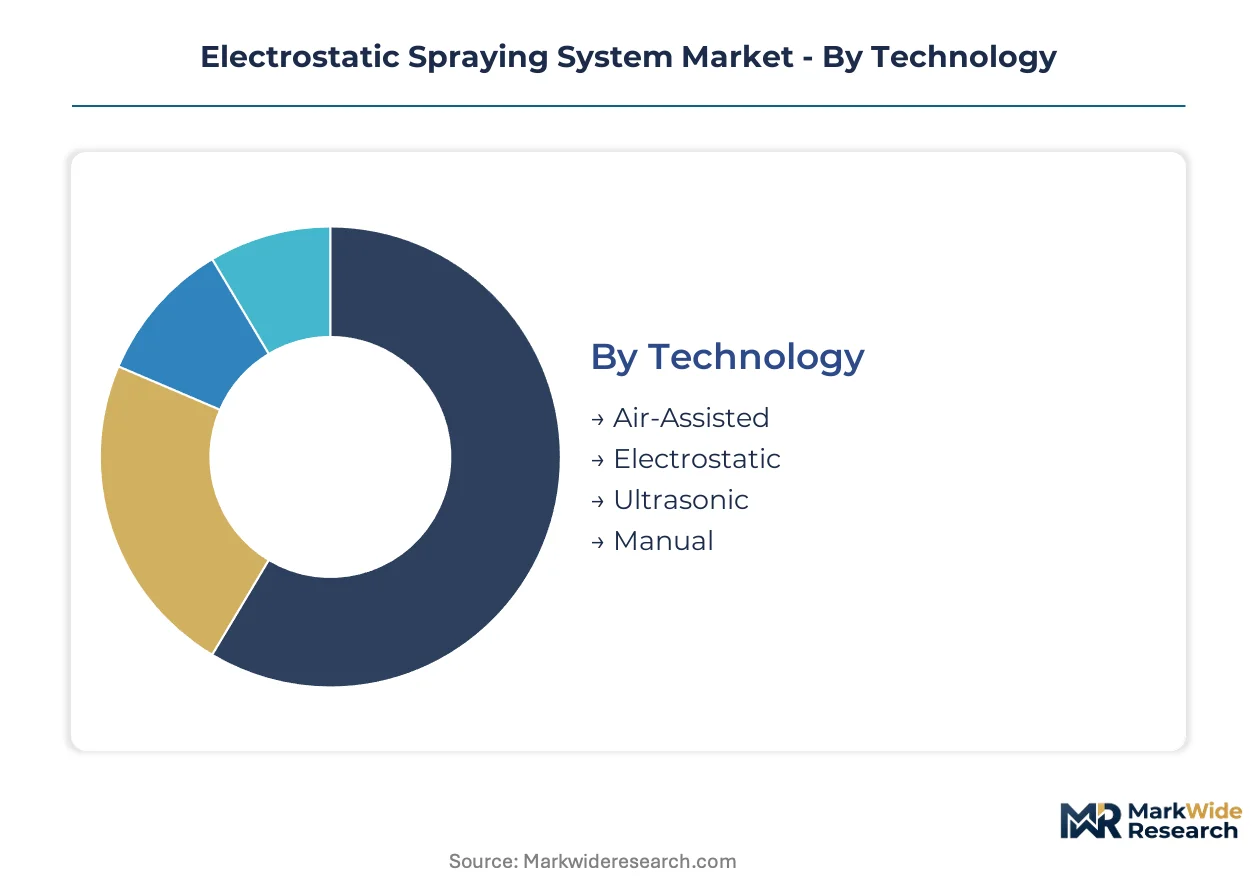
Electrostatic spraying systems fragment across four distinct classification axes that reshape procurement economics and vendor positioning. Technology choice determines capital intensity and operating precision. End-user concentration in healthcare and agriculture pulls divergent product specifications. Application type governs regulatory exposure and margin structure. Solution architecture dictates deployment flexibility versus throughput optimization.
Technology:
Buyers weigh transfer efficiency against capital outlay and maintenance complexity when selecting charging architectures.
- Air-Assisted:Compressed air shears liquid into charged droplets while propelling them toward targets. Hospital environmental services departments in Texas and California specify air-assisted systems for corridor disinfection where rapid coverage and minimal overspray reduce labor hours.
- Electrostatic:High-voltage charging electrodes impart 20-80 kV potential to liquid streams without pneumatic assistance. Automotive paint shops in Michigan and Ohio favor pure electrostatic configurations for primer and base coat applications where wrap-around coverage on complex geometries reduces material waste and rework.
- Ultrasonic:Piezoelectric transducers generate fine aerosol mists with minimal kinetic energy. Precision coating operations in pharmaceutical manufacturing suites employ ultrasonic systems where substrate thermal sensitivity prohibits heated air streams.
- Manual:Operator-controlled pressure spraying without electrostatic charging capability. Budget-constrained school districts in Florida retain manual equipment for outdoor grounds maintenance where coverage uniformity requirements remain relaxed.
Air-Assisted leads on scale; Electrostatic leads on momentum.
End User:
Regulatory stringency and pathogen-control mandates concentrate purchasing power across institutional verticals.
- Agriculture:Crop protection operations in Brazil and Argentina deploy charged-droplet sprayers to reduce pesticide drift and improve canopy penetration in soybean and corn fields. EPA-equivalent regulators in São Paulo state are tightening aerial application restrictions that favor ground-based electrostatic systems.
- Healthcare:Hospital-acquired infection prevention programs in the United States command premium pricing for EPA-validated disinfection equipment. Joint Commission accreditation surveys now incorporate environmental cleaning protocol documentation that elevates capital allocation toward touchless technologies.
- Automotive:OEM paint shops and tier-one coating facilities prioritize transfer efficiency above 80 percent to meet volatile organic compound emission thresholds. REACH compliance pressures in German and Czech manufacturing plants are accelerating electrostatic retrofit cycles.
- Building Maintenance:Commercial real estate operators and janitorial service contractors balance labor substitution against chemical inventory management complexity. Class A office buildings in Manhattan and Chicago are unbundling electrostatic disinfection as a standalone line item in service contracts.
Healthcare commands the densest margin pool; Agriculture expands most quickly.
Application:
Surface chemistry requirements and dwell time specifications fragment equipment configuration across use cases.
- Pesticide Application:Charged-droplet technology reduces active ingredient volume per hectare while maintaining biological efficacy. Brazilian soybean producers are displacing conventional aerial spraying with ground-based electrostatic rigs to comply with buffer zone regulations.
- Disinfection:EPA-registered antimicrobial claims now require device-specific efficacy validation against pathogen panels. Healthcare procurement committees are rewriting vendor qualification questionnaires to incorporate droplet size distribution and surface contact time data.
- Paint Coating:Automotive primer and clear coat operations demand uniform film thickness without runs or orange peel. Graco and Wagner industrial divisions anchor positions in North American automotive assembly plant installations.
- Surface Treatment:Corrosion protection and functional coating applications in oilfield equipment and marine structures require thick-film deposition with edge coverage. Gulf Coast petrochemical facilities specify air-assisted electrostatic systems for offshore platform maintenance.
Disinfection captures the steepest expansion trajectory; Paint Coating retains the most mature installed base.
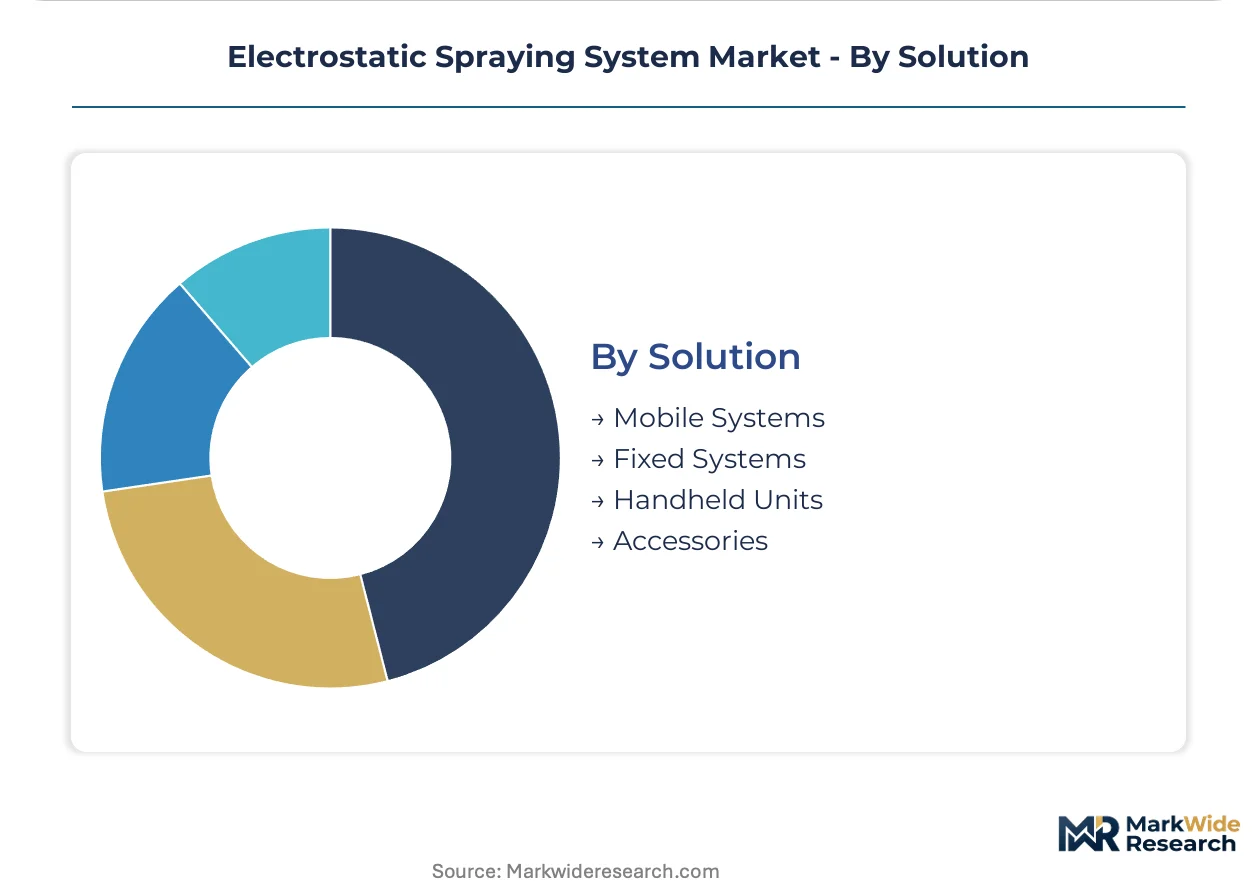
Solution:
Deployment architecture determines operator mobility, throughput capacity, and total cost of ownership calculations.
- Mobile Systems:Cart-mounted units with onboard power and chemical reservoirs enable corridor-to-corridor disinfection without fixed infrastructure. Older healthcare facilities lacking dedicated 240V circuits face retrofit electrical costs that compress mobile system adoption.
- Fixed Systems:Overhead conveyor and reciprocating arm installations dominate automotive paint shop throughput requirements. German and Japanese automotive OEMs specify fixed electrostatic stations with robotic path programming for body-in-white coating operations.
- Handheld Units:Battery-powered portable devices are climbing the fastest as facilities decentralize cleaning protocols. Lithium-ion energy density improvements extending runtime beyond four hours are expanding operator acceptance in education and hospitality verticals.
- Accessories:Nozzle sets, charging modules, and grounding equipment generate recurring revenue streams. Fleet standardization strategies among school districts and hospitality chains concentrate aftermarket parts demand with single-manufacturer ecosystems.
Fixed Systems anchor industrial throughput; Handheld Units gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrostatic spraying technology first achieved industrial scale in United States automotive paint shops during the 1940s, then migrated to agricultural chemical application in the 1970s. Contemporary demand clusters around infection control mandates, environmental compliance pressures, and precision agriculture economics across four major national markets.
United States
Hospital-acquired infection prevention programs in Texas and California command premium capital allocation for EPA-validated disinfection equipment. The EPA's emerging efficacy validation protocols are rewriting procurement criteria for institutional cleaning programs. Chicago and Manhattan Class A office buildings are unbundling electrostatic disinfection as standalone contract line items driven by tenant wellness certification requirements.
Germany
REACH compliance pressures are accelerating electrostatic retrofit cycles in automotive OEM paint shops and tier-one coating facilities. The ECHA volatile organic compound emission thresholds favor transfer efficiency above 80 percent. Bavarian and Baden-Württemberg manufacturing plants anchor European industrial coating demand for fixed electrostatic installations with robotic path programming.
Brazil
Soybean and corn producers in São Paulo state are displacing conventional aerial spraying with ground-based electrostatic rigs to comply with tightening buffer zone regulations. ANVISA-equivalent state regulators are restricting aerial pesticide application near populated areas. Mato Grosso and Paraná agricultural clusters are adopting charged-droplet technology to reduce active ingredient volume per hectare while maintaining biological efficacy.
China
Domestic manufacturing incentives under industrial upgrading programs are expanding local production capacity for electrostatic disinfection equipment. The MIIT standards framework is converging with international electrical safety certifications for high-voltage charging modules. Yangtze River Delta pharmaceutical manufacturing suites are deploying ultrasonic electrostatic systems where substrate thermal sensitivity prohibits heated air streams.
India
FSSAI hygiene mandates for dairy and meat cold chain facilities are creating first-time demand for electrostatic sanitization in food processing plants. The PLI scheme for domestic manufacturing reduces import duty exposure for locally assembled equipment. Maharashtra and Gujarat processing clusters are retrofitting legacy spray infrastructure to meet centralized food safety audit requirements.
Electrostatic Spraying System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory certification intensity and chemical-system bundling depth. The vendor base stratifies into three tiers: multinational industrial fluid handling conglomerates with automotive heritage, portable disinfection specialists with healthcare-focused product architectures, and regional fabricators serving price-sensitive agricultural markets. Two dominant competitive moves are reshaping positioning: chemical-equipment bundling that simplifies operator compliance documentation, and battery chemistry partnerships that extend cordless runtime specifications.
Among industrial coating specialists, Graco leverages its Minnesota-based fluid handling heritage to anchor positions in North American automotive assembly plant installations. Victory Innovations exemplifies the portable disinfection archetype through healthcare and education facility focus. EvaClean occupies a bundling-specialist position where integrated chemical-system offerings compress total cost of ownership calculations for facility managers.
| Leading Market Players |
|---|
| CloroxPro |
| Victory Innovations |
| EMist |
| Electrostatic Spraying Systems |
| ByoPlanet International |
| EvaClean |
| Graco |
| Ecolab |
| Jereh Group |
| Others |
Pricing and Supply Chain Analysis
EPA efficacy validation mandates for antimicrobial device claims are compressing procurement timelines and forcing manufacturers to absorb third-party testing costs before market access. This specification tightening concentrates pricing power with vendors possessing pre-certified chemical-system bundles, while budget-constrained buyers in education and hospitality verticals retreat toward rental and lease structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EPA-validated healthcare systems from commercial-grade disinfection units and basic agricultural sprayers. Price differentiation hinges on certification tier and after-sales service bundling, with FDA 510(k) pathway completion commanding substantial premiums. Pricing pressure stems from semiconductor cost volatility in 20-80 kV charging modules. School districts and small food processors exhibit highest price sensitivity; hospital infection prevention programs demonstrate lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive and pharmaceutical manufacturing demand, while distributor networks serve decentralized education and building maintenance procurement. Manufacturing concentrates in the United States, Germany, and China for finished systems, with critical transformer components sourcing from Japanese and German suppliers. Raw material dependencies include high-voltage semiconductors, lithium-ion battery cells, and precision nozzle ceramics. Single-source vulnerability in charging module supply chains creates structural risk. Distribution runs through specialized industrial fluid handling distributors and janitorial supply cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery chemistry advancements and chemical-system bundling are compressing total cost of ownership and enabling premium-tier migration among mid-market buyers. Margin expansion rests on these cost-down trajectories displacing price-competitive manual spraying alternatives.
For Market Incumbents: Hedge against UVC disinfection substitution by deepening chemical-equipment bundling that locks in recurring revenue streams. Prioritize backward integration into battery pack assembly to secure cordless handheld supply chains against semiconductor volatility. Defensive patent filings around droplet size optimization algorithms create switching costs for healthcare procurement committees. For New Entrants and Emerging Players: Begin with FSSAI-mandated food processing sanitization in Maharashtra and Gujarat, where import duty exposure disadvantages foreign competitors and domestic assembly incentives lower effective entry costs. Target mid-sized dairy cooperatives lacking legacy spray infrastructure. Pursue chemical-system partnerships with established antimicrobial registrants to bypass EPA validation bottlenecks. For Investors and Strategic Acquirers: Asymmetric upside sits with portable disinfection specialists possessing healthcare-focused product architectures and established GPO contract relationships. Five-to-ten year viability favors vendors converging CE marking with MDR dual-use certification. Monitor EPA registration backlog clearance rates as inflection indicator for working capital efficiency and revenue recognition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical-System Bundling | Integrated EPA-validated offerings simplify operator compliance documentation for hospital procurement committees. |
| Battery Chemistry Partnership | Lithium-ion energy density improvements extend cordless runtime beyond four hours in education facilities. |
| Dual-Use Certification Convergence | CE marking alignment with MDR opens pharmaceutical manufacturing and clinical setting verticals simultaneously. |
| Domestic Manufacturing Incentives | PLI scheme participation in India reduces import duty exposure for food processing equipment entrants. |
| Third-Party Efficacy Validation | Pre-submitted droplet size distribution data accelerates procurement cycles for institutional cleaning programs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital environmental services directors, janitorial supply cooperative procurement managers, automotive paint shop engineers, and agricultural equipment distributors with secondary validation. EPA registration databases, FDA 510(k) filings, REACH compliance filings, and customs trade data anchored supply-side assessment. Bottom-up equipment shipment tracking and top-down end-use spending analysis provided triangulation.
Segment-weighting across technology type, end-user vertical, application purpose, and solution architecture shaped volume and value outputs throughout the forecast period. Technology adoption curves, regulatory pathway timelines, and chemical compatibility certification rates informed CAGR derivation. Pricing elasticity assumptions reflected procurement committee behavior in healthcare and budget constraint severity in education.
Several conditions sit outside the modeled scope, including potential UVC technology cost breakthroughs, abrupt EPA protocol revisions, and geopolitical disruptions to semiconductor supply chains. Forecasts reflect assumptions about battery energy density improvement trajectories and regulatory harmonization timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Radial Split Pump Market
Pumps and Control Devices
Air-Operated Double Diaphragm (AODD) Pumps Market
Pumps and Control Devices
Global Solar-Powered Pump Market
Pumps and Control Devices
Plate Heat Exchanger Market
Pumps and Control Devices
Southeast Asia Industrial Pumps Market
Pumps and Control Devices
Worm Pumps Market
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
India Solar Water Pump Systems Market
Pumps and Control Devices
APAC Positive Displacement Pumps Market
Pumps and Control Devices
Liquid Dispensing Pump Market
Pumps and Control Devices
Fluid Power Equipment Market
Pumps and Control Devices
Europe Positive Displacement Pumps Market
Pumps and Control Devices
North America Axial Flow Pump Market
Pumps and Control Devices
Double Suction Pump Market
Pumps and Control Devices
Flow Back Equipment Market
Pumps and Control Devices
North America Dispensing Pumps Market