
 Hydraulic Pumps Market | 2026-2036
Hydraulic Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Pumps Market Analysis
Modular pump-motor assemblies is expanding as a preferred configuration across fluid power systems, letting buyers swap displacement modules without replacing entire units. Bosch Rexroth AG leverages captive manufacturing of precision valve blocks to anchor its position in electro-hydraulic architectures. Eaton Corporation plc competes through aftermarket channel control, while Danfoss A/S specializes in hydrostatic transmissions for mobile machinery.
Hydraulic pumps convert mechanical energy into fluid power through positive displacement, with operating pressures ranging from 3,000 to 10,000 PSI depending on piston or gear architecture; their primary purpose is transmitting force in heavy-load industrial and mobile equipment. Piston pumps command premium positioning in aerospace and metal forming applications where pressure fidelity matters most. Gear pumps occupy mature, cost-sensitive territory across material handling fleets. Variable displacement technology is displacing fixed-volume designs in construction and marine segments where load variability is high.
EPA emissions standards for off-road diesel equipment and the EU F-Gas Regulation on fluorinated working fluids are tightening design requirements for seal compatibility and thermal efficiency. China's MIIT mandates GB-standard efficiency grades that restrict market access for non-compliant imports. Stakeholders must monitor how converging energy-efficiency codes across Washington, Brussels, and Beijing reshape supplier qualification criteria.
Market Dynamics
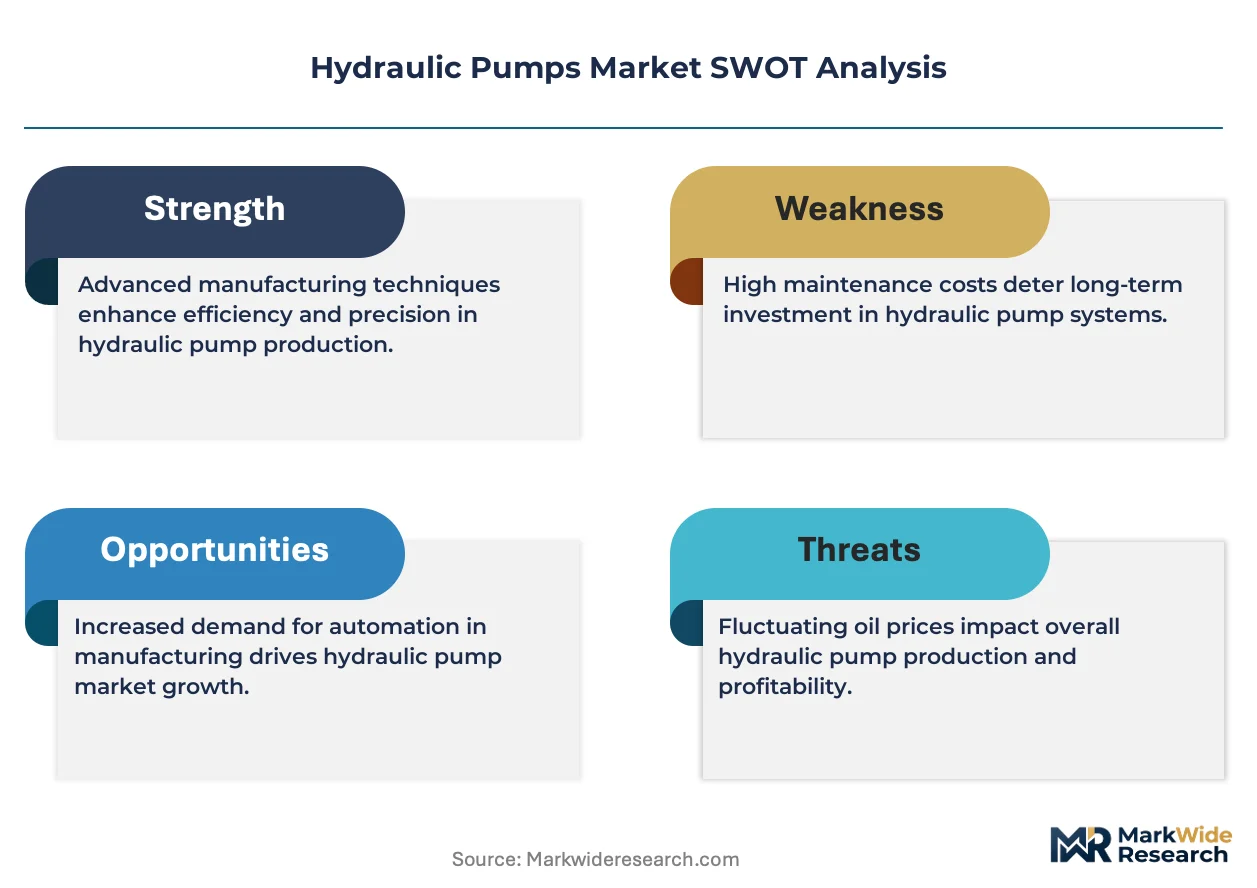
Variable displacement technology is compressing fixed-volume architectures across construction and marine equipment fleets as energy-efficiency mandates from Beijing, Brussels, and Washington converge on thermal performance thresholds. This technological pivot is redrawing supplier qualification criteria and procurement specifications simultaneously.
Growth Catalysts
- MIIT Efficiency Mandates:China's GB-standard grades restrict market access for non-compliant imports, forcing domestic manufacturers to upgrade displacement control systems and thermal management architectures.
- Electro-hydraulic Convergence:Precision valve block integration with sensor feedback loops enables real-time pressure modulation in metal forming and aerospace applications where pressure fidelity commands premium positioning.
- German Automotive Demand:Hydraulic system suppliers serving Stuttgart and Wolfsburg clusters are expanding high-pressure piston pump capacity to meet lightweight chassis forming requirements.
Market Restraints
- Seal Material Input Volatility:Fluorinated elastomer prices fluctuate with EU F-Gas Regulation phase-down schedules, compressing margin stability for high-pressure unit manufacturers dependent on perfluoropolymer compounds.
- Supply Concentration Risk:Precision casting capacity for hardened valve housings concentrates in select German and Japanese tier-two foundries, creating bottleneck exposure during demand surges.
- Electromechanical Substitution:Linear electric actuators advance in material handling and packaging machinery below 5,000 PSI thresholds, eroding gear pump volume in cost-sensitive fleet applications.
Strategic Opportunities
- Indian Agricultural Mechanization:Tractor OEMs in Punjab and Maharashtra are specifying variable displacement units for implements where load variability previously forced fixed-volume oversizing.
- Remanufactured Module Channels:Modular pump-motor assemblies enable displacement cartridge swaps without full unit replacement, creating aftermarket service revenue streams independent of new equipment sales.
- IRA Clean Manufacturing Credits:US-based fluid power suppliers can access tax incentives for energy-efficient production lines serving construction equipment electrification programs.
Industry Challenges
- Embedded Systems Integration:CAN bus and IoT sensor deployment in hydraulic architectures demands cross-functional teams fluent in both fluid mechanics and firmware architecture, talent scarce in traditional mechanical engineering pipelines.
- Multi-jurisdiction Certification Timelines:Simultaneous EPA off-road diesel compliance, EU F-Gas seal compatibility testing, and MIIT GB efficiency verification extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Pumps Market |
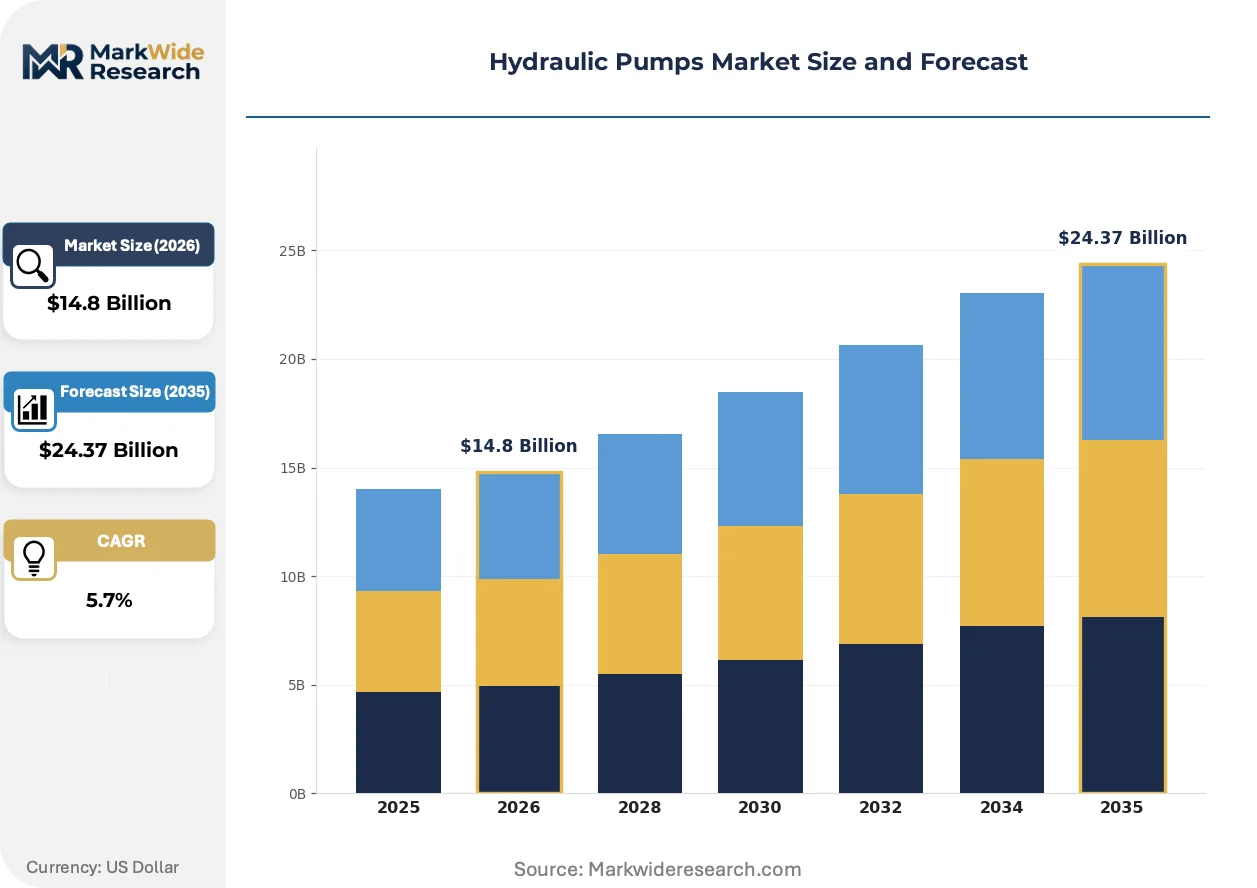
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gear Pumps, Piston Pumps, Vane Pumps, Screw Pumps End User: Aerospace, Manufacturing, Construction, Agriculture Application: Metal Forming, Fluid Power, Material Handling, Marine Technology: Hydrostatic, Hydraulic Actuation, Electro-Hydraulic, Variable Displacement |
| Companies Covered | Danfoss A/S, Bucher Hydraulics, Parker Hannifin Corporation, HAWE Hydraulik GmbH, Linde Hydraulics GmbH & Co. KG, Bosch Rexroth AG, Kawasaki Heavy Industries Ltd., Casappa S.p.A., Eaton Corporation plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Pumps Market Emerging Trajectories
Digital fluid monitoring and predictive maintenance algorithms are embedding intelligence directly into hydraulic architectures, shifting value capture from hardware shipments toward lifecycle performance contracts. This intelligence layer is redrawing competitive differentiation beyond displacement specifications alone.
Electro-hydraulic pump systems is absorbing control functions previously executed by standalone valve manifolds, collapsing component count in mobile machinery architectures. Construction equipment manufacturers in China and Germany are specifying these integrated units for excavators and wheel loaders where space constraints and wiring complexity previously limited electronic control penetration. The technology is absorbing margin from discrete valve suppliers while compressing assembly labor content at OEM facilities.
EPA Tier 4 Final and Stage V emissions standards for off-road diesel equipment are tightening thermal efficiency requirements that cascade into hydraulic system design. Seal compatibility with bio-based and synthetic working fluids now determines qualification for federal procurement contracts in US infrastructure projects. Piston pump architectures with advanced thermal management are capturing specification preference in aerial work platforms and compaction equipment where duty cycles stress fluid temperatures.
Equipment-as-a-service contracts are unbundling hydraulic system ownership from operational availability, shifting buyer preference toward modular architectures with field-replaceable displacement modules. Fleet operators in material handling and agriculture are specifying these service-inclusive arrangements to transfer obsolescence risk onto suppliers. This procurement evolution is most visible in German intralogistics and Indian combine harvester segments where uptime guarantees determine contract awards.
Hydraulic Pumps Market Segmentation
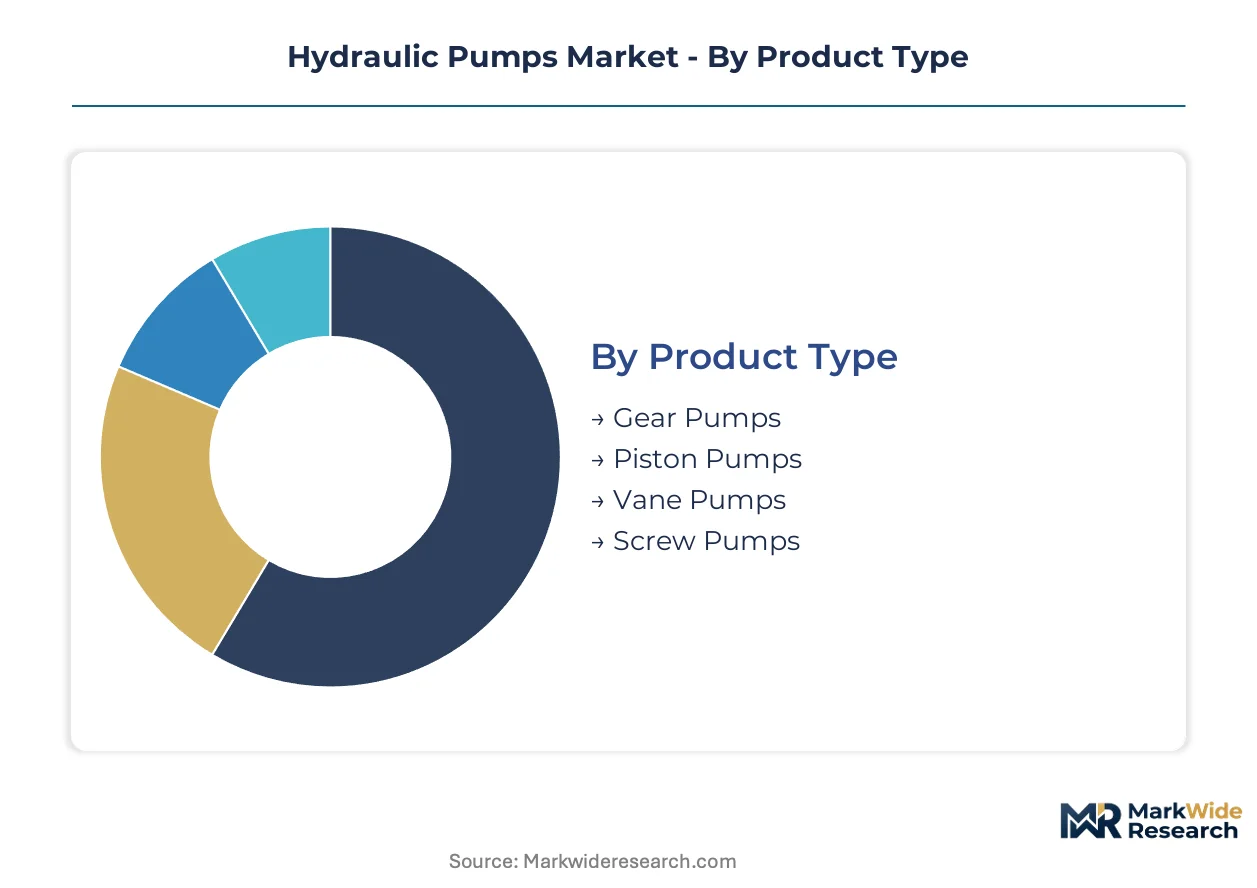
Hydraulic pump architectures vary sharply in pressure fidelity, thermal efficiency, and displacement control precision. Procurement specifications diverge across mobile machinery, stationary industrial systems, and aerospace platforms, forcing suppliers to maintain parallel product lineups with incompatible design priorities.
Product Type:
Standardization dominates gear and vane architectures, while piston and screw configurations require extensive customization for pressure ratings and port geometry.
- Gear Pumps:External and internal meshing designs deliver continuous flow at moderate pressures up to 3,000 PSI. Material handling fleets in India and Germany specify these units for forklift and conveyor applications where cost sensitivity outweighs precision requirements.
- Piston Pumps:Axial and radial piston architectures achieve operating pressures exceeding 10,000 PSI with variable displacement control. Metal forming presses in Stuttgart and Wolfsburg clusters demand these units for lightweight chassis manufacturing where pressure fidelity commands specification preference.
- Vane Pumps:Balanced and unbalanced vane designs offer medium-pressure performance with quiet operation characteristics. Compact construction equipment specifies these for auxiliary hydraulic circuits.
- Screw Pumps:Twin-screw and triple-screw configurations handle high-viscosity fluids with minimal pulsation. Marine applications in Hamburg and Rotterdam specify these for lubrication and fuel transfer systems.
Leading the category by volume: Gear Pumps. Expanding most quickly: Piston Pumps.
End User:
Margin structures vary dramatically across end-use verticals, with aerospace and construction commanding premium positioning against price-sensitive agricultural procurement.
- Aerospace:Aircraft hydraulic systems demand piston pumps with redundant channels and fire-resistant phosphate ester fluid compatibility. FAA certification timelines extend 18-24 months for new pump designs.
- Manufacturing:Metal forming and injection molding equipment specifies variable displacement units for energy recovery during deceleration cycles. German automotive suppliers anchor demand in this vertical.
- Construction:Excavators and wheel loaders in China and Germany absorb electro-hydraulic pump-motor assemblies where MIIT efficiency mandates and space constraints converge. Beijing's dual carbon goals accelerate displacement of fixed-volume designs.
- Agriculture:Tractor OEMs in Punjab and Maharashtra specify variable displacement units for implements where load variability previously forced oversizing. Cost sensitivity limits specification to mid-tier pressure ratings.
Dominant by revenue concentration: Manufacturing. Steepest expansion trajectory: Construction.
Application:
Application-specific duty cycles determine thermal management requirements, seal material selection, and predictive maintenance integration intensity.
- Metal Forming:Press brakes and stamping equipment demand precise pressure modulation with rapid response times. Stuttgart automotive clusters specify servo-pump systems with real-time feedback loops.
- Fluid Power:General industrial hydraulic systems span material handling, machine tools, and packaging machinery. Gear pumps dominate this cost-sensitive territory.
- Material Handling:Forklifts and automated guided vehicles specify compact units with CAN bus integration for fleet telematics. German intralogistics operators are unbundling ownership through equipment-as-a-service contracts.
- Marine:Offshore platforms and commercial vessels demand corrosion-resistant architectures with classification society approval. Screw pumps capture specification preference for continuous-duty lubrication systems.
Highest specification intensity: Metal Forming. Fastest service-model adoption: Material Handling.
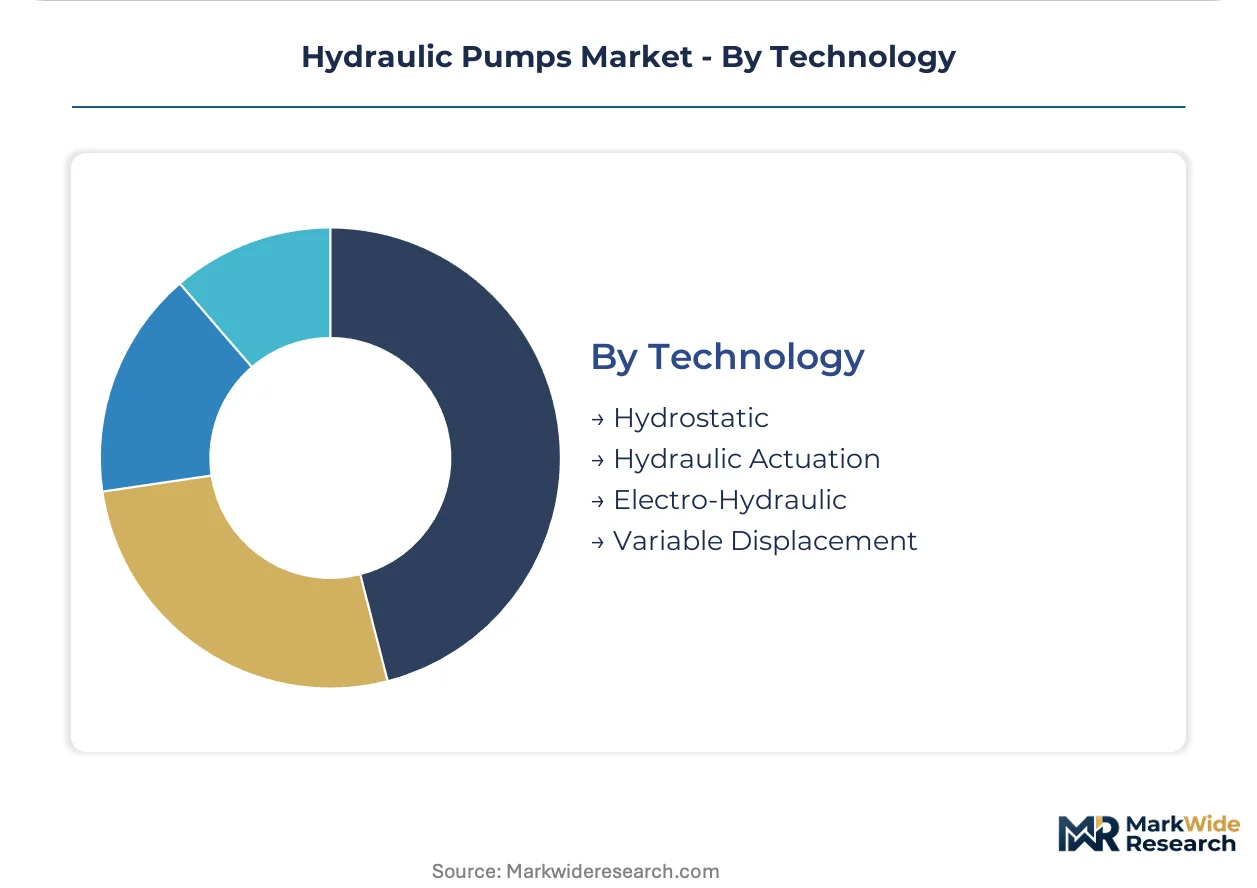
Technology:
Technology selection increasingly determines supplier qualification rather than serving as a downstream procurement choice.
- Hydrostatic:Closed-loop transmission systems convert engine power to wheel or track drive with infinite speed variation. Mobile machinery in construction and agriculture specifies these for traction control.
- Hydraulic Actuation:Conventional valve-controlled systems persist in legacy equipment fleets and cost-constrained applications. Replacement demand sustains aftermarket channels.
- Electro-Hydraulic:Integrated pump-motor units with embedded sensors and electronic displacement control absorb functions previously executed by standalone valve manifolds. Bosch Rexroth AG and Danfoss A/S compete aggressively in this segment.
- Variable Displacement:Swashplate and bent-axis designs modulate output flow to match load demand, reducing energy consumption and thermal load. MIIT GB standards and EPA Tier 4 Final regulations mandate this technology for new equipment certification.
Widest installed base: Hydraulic Actuation. Gaining share fastest: Variable Displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of hydraulic pump capacity while Germany and the United States absorb premium-tier consumption. India and Japan complete the demand map with distinct procurement patterns shaped by agricultural mechanization and precision manufacturing respectively.
China
Construction equipment OEMs in Beijing and Shanghai are expanding orders for variable displacement units as MIIT enforces GB-standard efficiency grades under dual carbon goals. Domestic foundries in Jiangsu province are upgrading precision casting lines to meet hardened valve housing specifications for electro-hydraulic architectures. Xuzhou's construction machinery cluster is integrating sensor-enabled pump-motor assemblies into excavator platforms for real-time pressure modulation.
Germany
Automotive hydraulic system suppliers serving Stuttgart and Wolfsburg are scaling high-pressure piston pump capacity for lightweight chassis forming applications. The EU F-Gas Regulation is compressing seal material availability, forcing thermal management redesigns across Baden-Württemberg production lines. Hamburg's marine equipment sector specifies corrosion-resistant screw pumps for offshore platform lubrication systems requiring classification society approval.
United States
Material handling fleet operators in Illinois and Ohio are unbundling hydraulic system ownership through equipment-as-a-service contracts with uptime guarantees. EPA Tier 4 Final emissions standards are tightening thermal efficiency thresholds for off-road diesel equipment deployed in federal infrastructure projects. The Pacific Northwest's timber machinery sector is retrofitting fixed-volume gear pumps with variable displacement units to qualify for IRA Clean Manufacturing Credits.
India
Tractor OEMs in Punjab and Maharashtra are specifying variable displacement pumps for agricultural implements where load variability previously forced fixed-volume oversizing. The PLI scheme for manufacturing is incentivizing domestic assembly of precision valve blocks previously imported from German tier-two suppliers. Chennai's construction equipment distributors are expanding service networks for modular pump-motor cartridge replacement programs.
Japan
Metal forming press manufacturers in Nagoya are integrating servo-pump systems with real-time feedback loops for automotive stamping applications. METI energy efficiency guidelines are accelerating displacement of legacy hydraulic actuation in Kansai region machine tool fleets. Yokohama's port machinery sector is adopting hydrostatic transmission systems for container handling equipment requiring infinite speed variation under heavy load cycles.
Hydraulic Pumps Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. Consolidation concentrates around electro-hydraulic integration capabilities and captive precision casting capacity. Three archetypes dominate: diversified fluid power conglomerates with full-system portfolios, specialized pump manufacturers with displacement control expertise, and regional fabricators serving aftermarket remanufacturing channels. Competitive moves center on modular architecture licensing and backward integration into hardened valve housing foundries.
Among diversified European-headquartered conglomerates, Bosch Rexroth AG and Danfoss A/S exemplify full-system positioning across mobile and industrial verticals. Eaton Corporation plc occupies a position within the North American fluid power tier. Specialists including HAWE Hydraulik GmbH and Linde Hydraulics GmbH & Co. KG represent German-focused precision engineering archetypes. Parker Hannifin Corporation and Kawasaki Heavy Industries Ltd. anchor trans-Pacific supply relationships. Bucher Hydraulics and Casappa S.p.A. sit within the European mid-tier specialist segment.
| Leading Market Players |
|---|
| Danfoss A/S |
| Bucher Hydraulics |
| Parker Hannifin Corporation |
| HAWE Hydraulik GmbH |
| Linde Hydraulics GmbH & Co. KG |
| Bosch Rexroth AG |
| Kawasaki Heavy Industries Ltd. |
| Casappa S.p.A. |
| Eaton Corporation plc |
| Others |
Supply Flow & Price Mechanics
MIIT efficiency mandates in China are compressing procurement timelines for variable displacement units, forcing foundries in Jiangsu province to absorb thermal management redesign costs that cascade into piston pump pricing tiers. Buyers in German automotive clusters and Indian agricultural machinery now face extended qualification cycles that reshape supplier selection criteria and contract structures.
Pricing Analysis
Cost-down pressure on mid-tier gear pump manufacturers accelerates because electromechanical substitution below 5,000 PSI thresholds erodes volume in material handling fleets. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified piston architectures from construction-grade variable displacement units and cost-sensitive fixed-volume gear pumps. Price differentiation rests on GB-standard efficiency grades and EU F-Gas seal compatibility certification. Agricultural OEMs in India exhibit highest price sensitivity, while German automotive hydraulic system suppliers tolerate premium positioning for pressure fidelity.
Supply Chain Analysis
Freight cost volatility from German and Japanese tier-two foundries to assembly plants in China and the United States compresses margin stability for high-pressure unit manufacturers. Precision casting capacity for hardened valve housings concentrates in Germany, Japan, and select Chinese provinces. Raw material dependencies draw from fluorinated elastomer compounds, hardened steel alloys, and precision-machined valve blocks. Single-source vulnerability in precision casting creates bottleneck exposure during demand surges. Distribution runs through OEM direct procurement channels, aftermarket remanufacturing networks, and specialized fluid power distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around electro-hydraulic integration capabilities as multi-jurisdiction certification timelines extend product launch cycles beyond the survival threshold for undercapitalized fabricators.
For Market Incumbents: Cement specification control through captive manufacturing of precision valve blocks and backward integration into hardened valve housing foundries. Defend against electromechanical substitution by embedding CAN bus and IoT sensor architectures into pump-motor assemblies. Prioritize certification investment for simultaneous EPA Tier 4 Final, EU F-Gas, and MIIT GB compliance to lock out smaller competitors. For New Entrants and Emerging Players: Enter via modular displacement cartridge aftermarket channels where equipment-as-a-service contracts create service revenue independent of new equipment sales. Target Indian agricultural mechanization and German intralogistics segments where uptime guarantees determine contract awards. Pursue licensing arrangements with construction equipment OEMs in China seeking rapid MIIT compliance without internal R&D burden. For Investors and Strategic Acquirers: The window for entry favors electro-hydraulic specialists with embedded firmware capabilities and existing precision casting relationships. Long-term viability hinges on capturing lifecycle performance contracts that shift value capture from hardware shipments to predictive maintenance revenue. Watch for consolidation signals when tier-two foundry capacity utilization exceeds sustainable thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captive valve housing production insulates Bosch Rexroth and Danfoss from German-Japanese foundry bottlenecks. |
| Modular Architecture Licensing | Displacement cartridge swap programs transfer obsolescence risk to suppliers in Indian combine harvester fleets. |
| Electro-Hydraulic Platform Integration | Sensor-enabled pump-motor assemblies collapse component count for Beijing excavator manufacturers under MIIT mandates. |
| Remanufacturing Channel Expansion | Field-replaceable modules create aftermarket revenue streams decoupled from new equipment sales cycles. |
| Multi-Jurisdiction Certification Pre-Investment | Simultaneous EPA, EU F-Gas, and MIIT compliance locks specification preference in federal procurement contracts. |
Methodological Framework
Document review covered technical standards from EPA, EU F-Gas Regulation, and MIIT GB efficiency grades, complemented by interviews with fluid power engineering directors, OEM procurement managers at construction equipment manufacturers, aftermarket service heads, and precision casting facility operators. Secondary validation drew from customs trade data, SEC filings of diversified industrial conglomerates, and industry association technical publications. Bottom-up unit economics triangulated against top-down market sizing across product architectures and end-use verticals.
Cross-referencing historical displacement technology adoption curves with panel input from Stuttgart automotive clusters and Xuzhou construction machinery manufacturers anchored the analytical framework. Segmentation modeling spanned pump architecture, end-use vertical, application duty cycle, and technology integration level. CAGRs were derived from installed base turnover rates and regulatory mandate compliance deadlines. Forecast inputs incorporated MIIT dual carbon goal timelines and EPA Tier 4 Final implementation patterns.
Revisions become necessary when fluorinated elastomer supply disruptions, precision casting capacity constraints, or electromechanical substitution acceleration materialize beyond modeled parameters. Forecasts reflect documented assumptions about regulatory enforcement consistency and OEM procurement cycle stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Sanitary Pumps Market
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Ultra High Pressure Water Pump Market
Pumps and Control Devices
Electric Submersible Pump Market
Pumps and Control Devices
Vertical Inline Pumps Market
Pumps and Control Devices
Global Smart Pumps Market
Pumps and Control Devices
Glycol Pumps Market
Pumps and Control Devices
Europe Submersible Pump Market
Pumps and Control Devices
North America Axial Flow Pump Market
Pumps and Control Devices
Mud Pumps Market
Pumps and Control Devices
API 610 Pumps Market
Pumps and Control Devices
Rotary Pump Market
Pumps and Control Devices
Industrial Vacuum Pumps Market
Pumps and Control Devices
Air-Operated Double Diaphragm (AODD) Pumps Market
Pumps and Control Devices
Subsea Pump System Market
Pumps and Control Devices
Fine Bubble Diffusers Market