
 Wind Power Couplings Market | 2026-2036
Wind Power Couplings Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Power Couplings Market Insights
Specialized drivetrain engineering talent is unwinding as a bottleneck across European and Asian supply chains, forcing manufacturers to restructure apprenticeship pipelines and automate precision machining workflows. Siemens AG leverages captive foundry capacity in Germany to control casting quality for multi-megawatt turbine couplings. ABB Ltd anchors its position through integrated condition-monitoring systems embedded in coupling housings. Altra Industrial Motion Corp. competes by specializing in modular flexible coupling architectures that reduce installation hours in offshore nacelles.
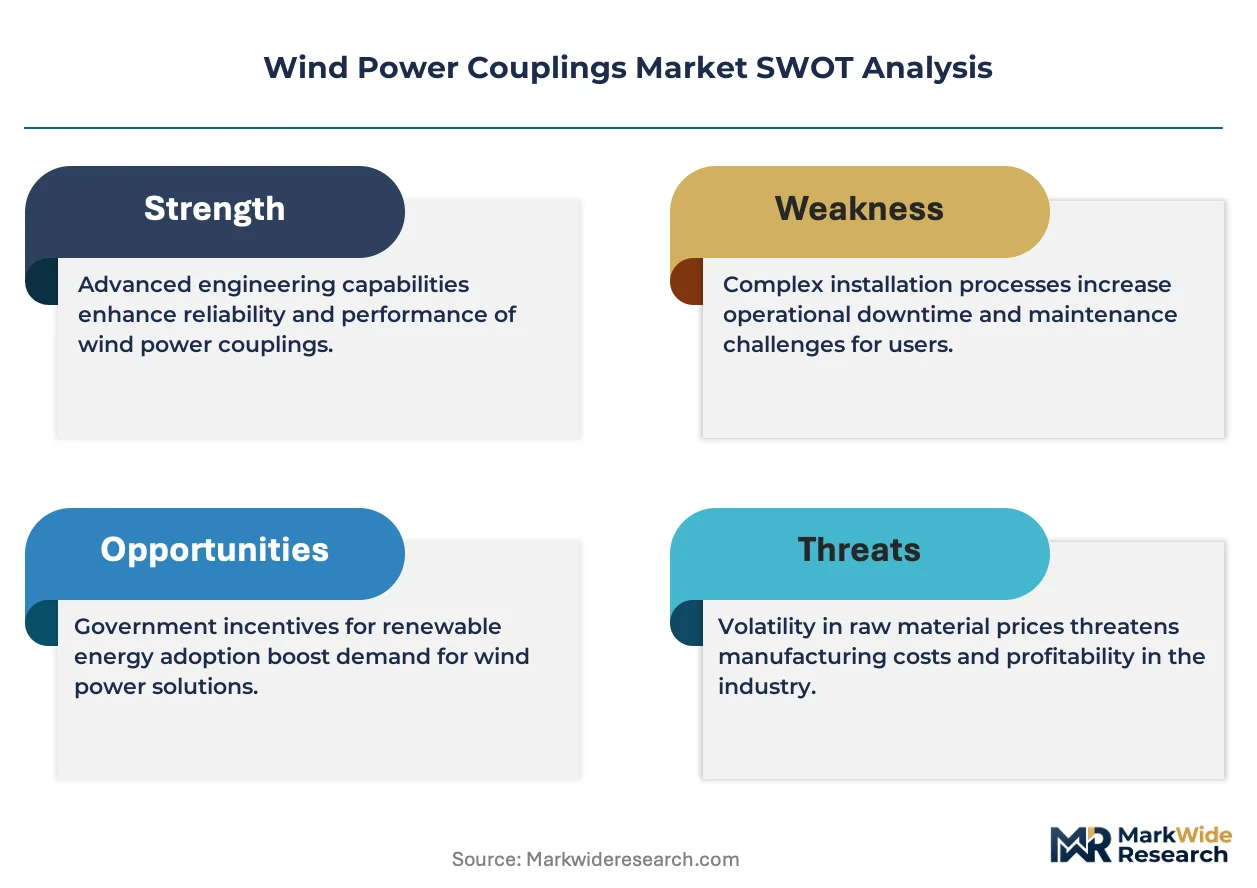
Wind power couplings are torque-transmitting mechanical interfaces that connect the main shaft, gearbox, and generator in wind turbine drivetrains, typically forged from alloy steel and heat-treated to withstand cyclic loads exceeding rated torque by safety factors. Their primary purpose is to accommodate angular and axial misalignment while damping torsional vibrations that would otherwise fatigue gearbox bearings and generator windings. Flexible couplings dominate installed capacity due to their misalignment tolerance and maintenance accessibility in offshore environments, while disc couplings are gaining share in direct-drive turbines where elimination of the gearbox stage demands higher torsional stiffness. Hydraulic couplings remain a niche margin pool concentrated in retrofits of aging onshore fleets where soft-start capability protects aging generator windings.
FDA oversight applies to composite coupling materials used in offshore platforms with potable water systems, while EPA emissions rules shape foundry energy costs for steel forging operations in the United States. The EU F-Gas Regulation and REACH chemical restrictions are pushing European coupling manufacturers toward fluorinated-gas-free lubrication and reduced-cadmium surface coatings. Stakeholders must monitor how China's GB standards for offshore wind equipment and India's CEA grid-code amendments will reshape import certification requirements and local content thresholds for coupling suppliers entering Asian markets.
Market Dynamics
Offshore wind turbine scaling toward 15 MW ratings is forcing coupling architectures to absorb torque spikes beyond legacy design envelopes, compressing supplier qualification timelines and fragmenting procurement pools.
Growth Catalysts
- EU F-Gas Regulation:The phase-down of fluorinated greenhouse gases is accelerating demand for hermetically sealed coupling housings with synthetic ester lubrication in North Sea installations.
- China's coastal provincial auctions:Jiangsu, Guangdong, and Fujian provinces are mandating gigawatt-scale offshore clusters that require high-torque flexible couplings rated for typhoon-grade cyclic loading.
- Direct-drive generator architectures:Elimination of gearbox stages in permanent-magnet generators is creating specification pull for torsionally stiff disc couplings with integrated electrical isolation.
Market Restraints
- Alloy steel input volatility:Nickel and molybdenum price swings in European spot markets are compressing foundry margins for heat-treated coupling forgings.
- Foundry capacity concentration:Germany and China control 70% of large-diameter steel casting capacity for multi-megawatt turbine couplings, creating single-source vulnerability.
- REACH chemical restrictions:Cadmium plating bans on corrosion-resistant coatings are forcing costly conversion to zinc-nickel alternatives with unproven 25-year offshore durability.
Strategic Opportunities
- India's CEA grid-code amendments:New interconnection standards for wind farms above 50 MW are opening certification pathways for European and Chinese coupling suppliers.
- Condition-monitoring convergence:Integration of torque telemetry and vibration sensing into coupling housings enables predictive maintenance contracts with offshore O&M providers.
- Floating offshore wind:Platform motion-induced drivetrain misalignment is creating specification demand for high-angular-tolerance flexible couplings in pre-commercial projects.
Industry Challenges
- Precision machining talent scarcity:European and Asian supply chains face depleted apprenticeship pipelines for 5-axis CNC operators capable of finishing large-bore coupling hubs to ISO 1940 balance grades.
- Type certification timelines:DNV-ST-0126 and IEC 61400-4 qualification protocols for novel coupling designs extend 18-24 months, lagging turbine OEM development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Power Couplings Market |
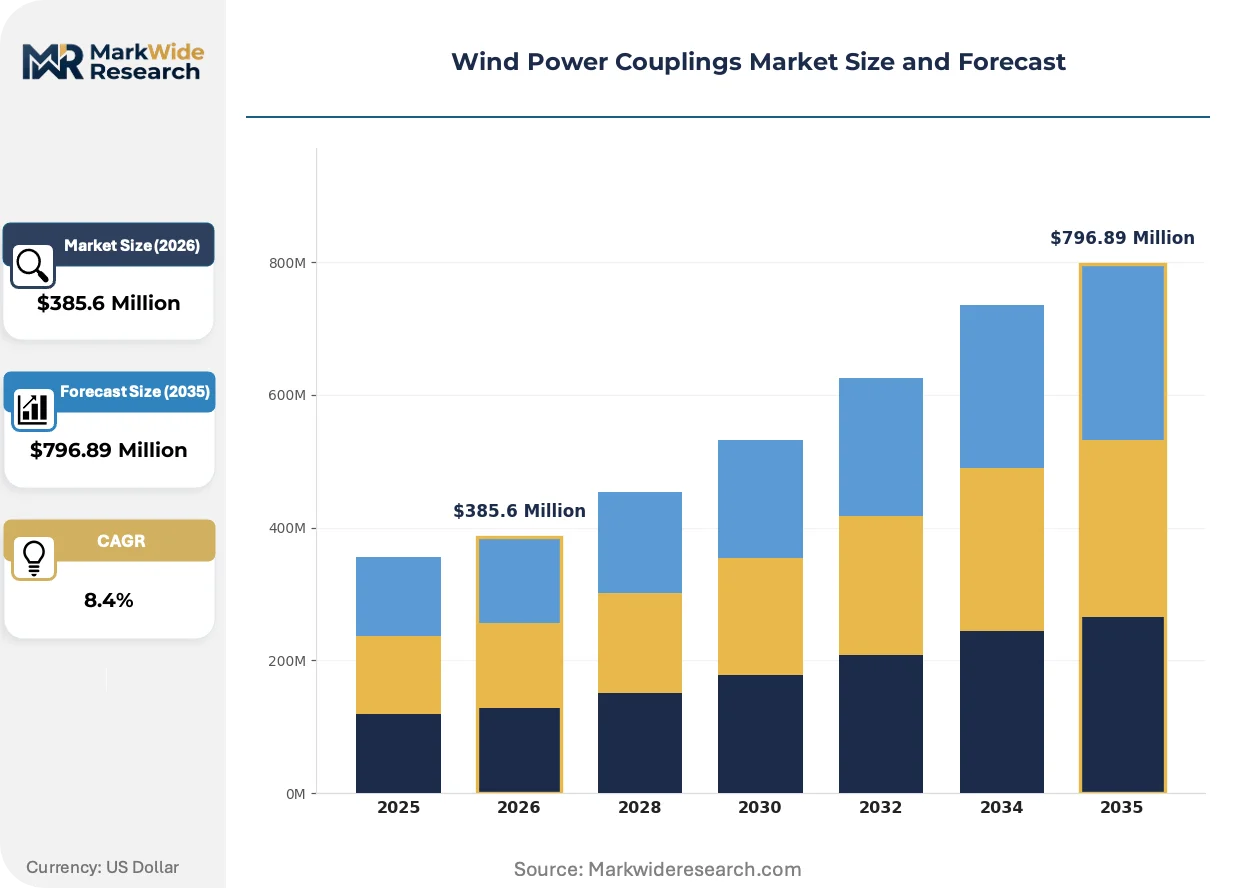
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Couplings, Rigid Couplings, Disc Couplings, Hydraulic Couplings Technology: Gearbox, Direct Drive, Synchronous, Asynchronous End User: Onshore Wind Farms, Offshore Wind Farms, OEMs, Maintenance Service Providers Installation: Turbine Mounting, Secondary Systems, Retrofit, New Development |
| Companies Covered | Siemens AG, ABB Ltd, Altra Industrial Motion Corp., SKF Group, Voith GmbH & Co. KGaA, KTR Systems GmbH, Flender, Rexnord Corporation, John Crane, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Power Couplings Market Trends and Innovations
Material science advances and embedded sensor integration are splitting the coupling market into performance tiers, with premium architectures commanding qualification premiums and standard designs facing commoditization pressure.
Disc coupling technology is bifurcating the high-power drivetrain segment. These laminated steel disc packs transmit torque through flexure rather than sliding contact, eliminating backlash and wear points. Siemens Gamesa and Vestas are specifying disc couplings for 12 MW+ direct-drive platforms entering serial production. The technology is bifurcating procurement pools into torsionally rigid disc architectures versus legacy gear coupling suppliers facing obsolescence in the upper power band.
REACH and EU F-Gas Regulation are tightening material compliance burdens. The European Chemicals Agency's restrictions on per- and polyfluoroalkyl substances are prohibiting traditional PTFE-based shaft seals in coupling assemblies. Manufacturers are responding with fluorosilicone alternatives and labyrinth seal redesigns, though validation data for 25-year offshore lifecycles remains incomplete. German and Danish coupling houses are absorbing the highest compliance costs due to their integrated European supply chains.
Buyer consolidation among offshore wind developers is compressing supplier negotiation leverage. Orsted, Equinor, and SSE Renewables are centralizing drivetrain procurement through framework agreements that bundle couplings with gearbox and generator packages. Tier-2 coupling specialists are losing direct OEM relationships and must qualify through gearbox integrators like ZF Wind Power and Winergy. This channel compression is most advanced in the United Kingdom's Round 4 and Round 5 auction rounds, where developer concentration exceeds any other offshore wind market.
Wind Power Couplings Market Segmentation
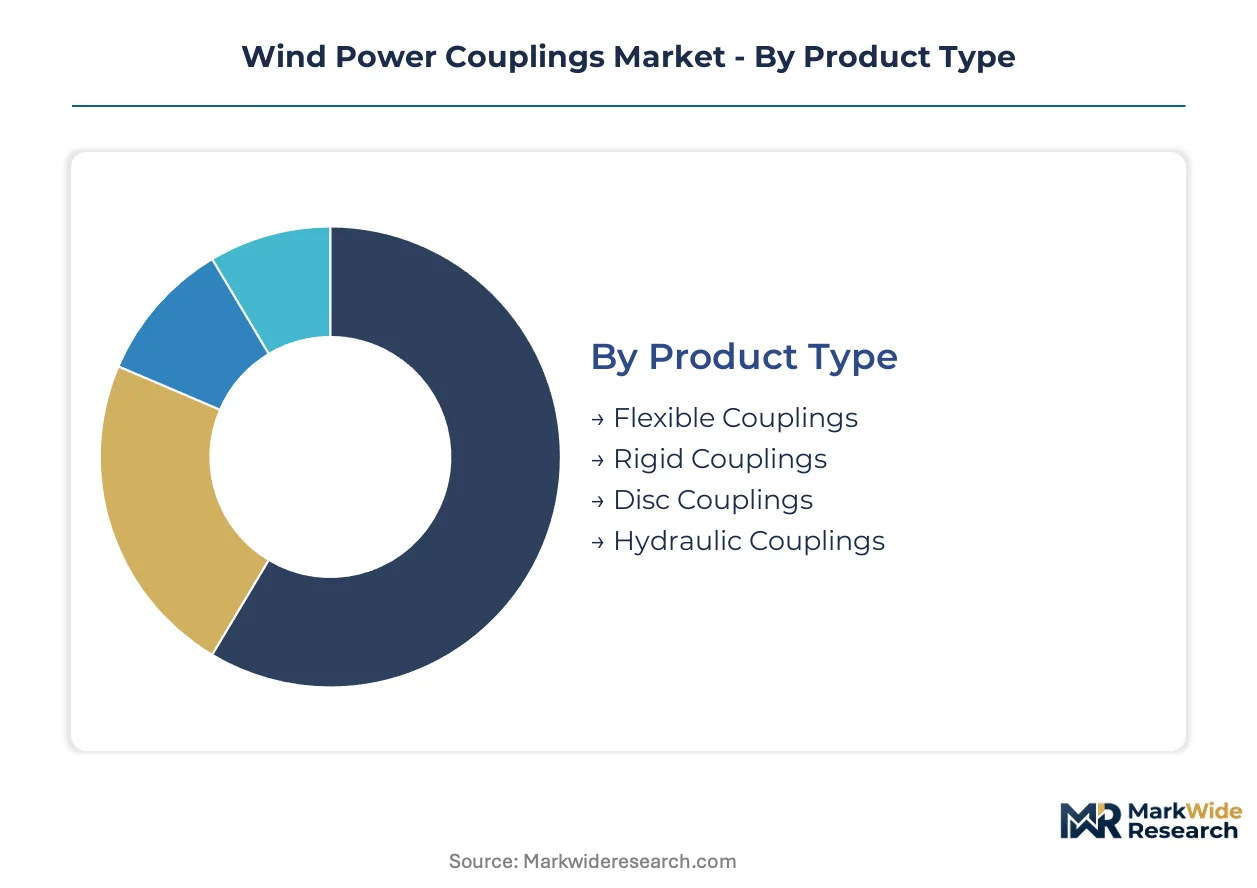
Segmentation in wind power couplings reveals how drivetrain architectures, installation contexts, and regulatory environments fragment procurement specifications. Manufacturers must align product portfolios across torque ratings, misalignment tolerance, and environmental sealing requirements to capture value in distinct application tiers.
Product Type:
Disc couplings face the strongest substitution pressure as direct-drive turbines displace gearbox architectures, while hydraulic couplings confront terminal decline in new installations.
- Flexible Couplings:Laminated elastomer or metallic element designs accommodate angular misalignment up to multiple degrees while damping torsional oscillations. Demand concentrates in Jiangsu and Guangdong provinces where typhoon-rated offshore turbines require maintenance-accessible drivetrain interfaces.
- Disc Couplings:Torsionally rigid laminated steel disc packs transmit torque through flexure without backlash, matching the stiffness requirements of permanent-magnet direct-drive generators. Vestas and Siemens Gamesa specify these for 12 MW+ platforms entering serial production.
- Rigid Couplings:Solid forged steel sleeves demand precise shaft alignment, limiting deployment to nacelle designs with integrated bearing housings that control relative motion.
- Hydraulic Couplings:Fluid-filled torque converters enable soft-start capability for aging onshore generator windings, surviving primarily in retrofit markets for pre-2010 turbine fleets.
Flexible couplings anchor the volume base while disc couplings gain share at the steepest rate.
Technology:
Cost tier stratification separates precision-machined components for high-megawatt turbines from standardized designs serving smaller installations.
- Gearbox:Multi-stage planetary and helical gearboxes remain the dominant drivetrain architecture, requiring flexible couplings with high misalignment tolerance between main shaft and high-speed stage. European foundries supply heat-treated alloy steel hubs for these applications.
- Direct Drive:Elimination of gearbox stages demands torsionally stiff couplings with electrical isolation properties to prevent bearing currents in permanent-magnet generators. Specifications from Goldwind and Envision Energy drive procurement volumes.
- Synchronous:Doubly-fed induction and wound-rotor synchronous machines require couplings rated for slip-ring electrical interfaces, common in older European onshore installations.
- Asynchronous:Squirrel-cage induction generators with full-power converters tolerate higher torsional compliance, accepting simpler coupling designs in cost-sensitive markets.
Gearbox technology retains the largest installed base though direct drive expands most quickly in offshore procurement.
End User:
Customer type determines margin structure, with offshore developers demanding integrated condition-monitoring packages and maintenance providers seeking interchangeable spare architectures.
- Offshore Wind Farms:Orsted, Equinor, and SSE Renewables centralize procurement through framework agreements bundling couplings with drivetrain packages. Specifications mandate hermetically sealed housings with synthetic ester lubrication to satisfy EU F-Gas Regulation.
- OEMs:Vestas, Siemens Gamesa, and Goldwind qualify suppliers through 18-24 month DNV-ST-0126 certification protocols, creating barrier-protected supply relationships.
- Onshore Wind Farms:Distributed procurement across independent power producers favors standardized flexible couplings with field-replaceable elastomer elements.
- Maintenance Service Providers:Independent O&M contractors stock modular coupling kits compatible with multiple turbine vintages, prioritizing interchangeability over optimized performance.
Offshore wind farms command premium pricing tiers while maintenance service providers drive standardization pressure.
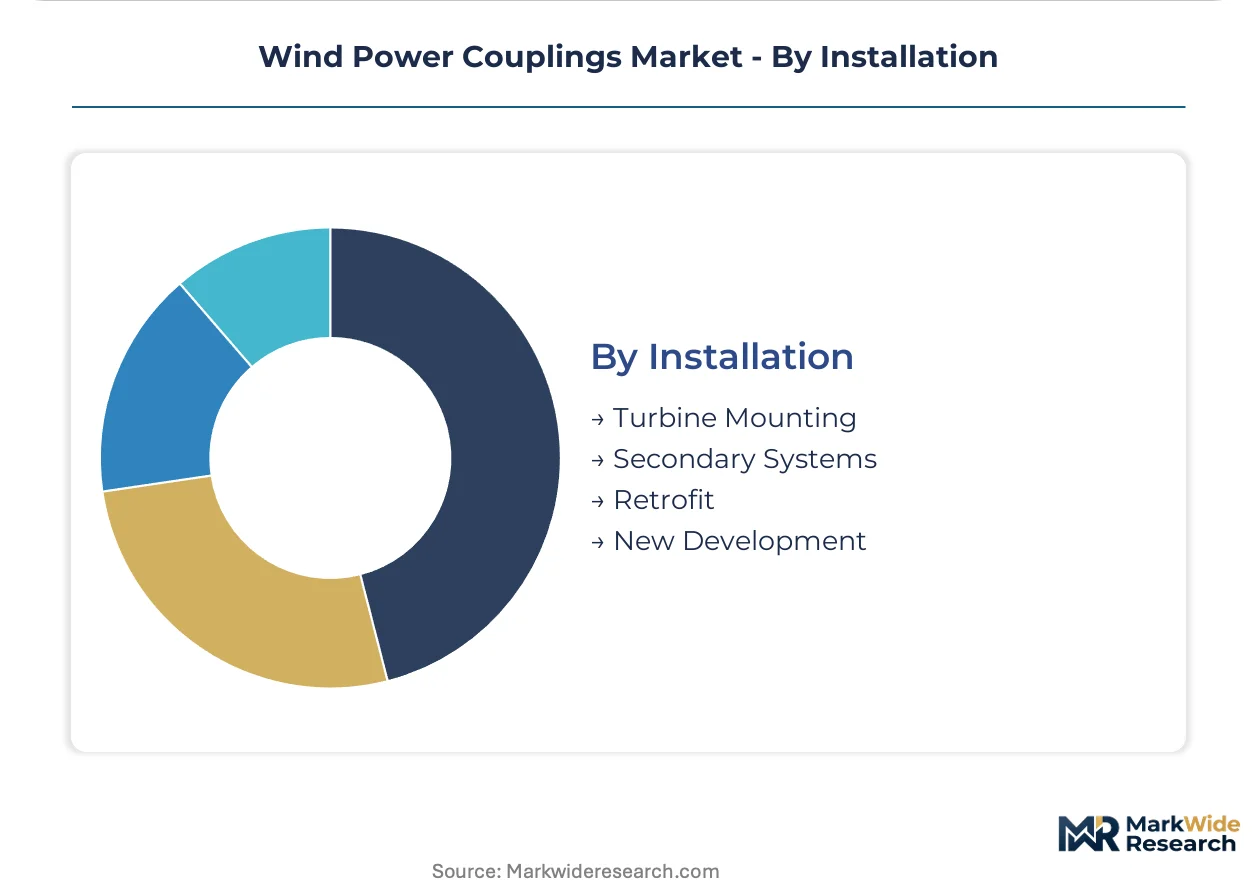
Installation:
Volume concentration in new offshore development contrasts with margin opportunities in precision retrofit applications.
- New Development:Gigawatt-scale auction awards in Germany, the United Kingdom, and China specify coupling architectures during turbine design phase, locking in suppliers for project lifecycles.
- Retrofit:Aging onshore fleets in Spain and the United States require coupling replacement to address fatigue failures, creating demand for dimensionally interchangeable designs.
- Turbine Mounting:Primary drivetrain couplings between main shaft, gearbox, and generator face the highest torque loads and cyclic stress amplitudes.
- Secondary Systems:Auxiliary couplings for yaw drives, pitch mechanisms, and cooling systems operate at lower power densities with standardized industrial designs.
New development absorbs the majority of procurement volume while retrofit applications offer the highest margin per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB standards for offshore wind equipment and the EU F-Gas Regulation are reshaping procurement requirements across the three dominant manufacturing geographies. Germany, China, and the United Kingdom concentrate foundry capacity and final assembly for multi-megawatt turbine couplings.
China
Jiangsu, Guangdong, and Fujian provinces are accelerating gigawatt-scale offshore clusters that demand typhoon-rated flexible couplings. Provincial governments under China's dual carbon goals are mandating local content thresholds that favor domestic coupling suppliers. The Yangtze River Delta manufacturing belt around Shanghai hosts precision machining facilities serving Goldwind and Envision Energy drivetrain programs.
Germany
North Sea offshore auction rounds are specifying hermetically sealed coupling housings with synthetic ester lubrication to satisfy REACH chemical restrictions. The country's central bank monitors foundry energy costs shaped by EU emissions trading scheme compliance. Industrial clusters in North Rhine-Westphalia and Bavaria retain captive steel casting capacity for heat-treated alloy hubs.
United Kingdom
Round 4 and Round 5 offshore wind awards concentrate developer procurement through framework agreements bundling couplings with drivetrain packages. Orsted and SSE Renewables are centralizing supplier qualification under DNV-ST-0126 protocols. Scottish fabrication yards around Aberdeen are pivoting from oil and gas to floating offshore wind coupling installation.
United States
EPA emissions rules are elevating foundry energy costs for steel forging operations serving onshore retrofit markets. Independent power producers in Texas and the Midwest favor standardized flexible couplings with field-replaceable elements. The Great Lakes manufacturing corridor retains machining capacity for legacy gearbox coupling architectures.
India
CEA grid-code amendments for wind farms above 50 MW are opening certification pathways for European and Chinese coupling suppliers. Gujarat and Tamil Nadu states are auctioning utility-scale onshore projects requiring torsionally compliant drivetrain interfaces. Domestic fabrication clusters in Pune and Chennai are developing ISO 1940 balance-grade machining capabilities.
Wind Power Couplings Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in wind power coupling supply. German and Chinese foundry groups control roughly seventy percent of large-diameter steel casting capacity for multi-megawatt applications. Three strategic archetypes dominate: vertically integrated drivetrain OEMs with captive coupling production, standalone coupling specialists with modular architectures, and condition-monitoring integrators embedding sensors into housing assemblies. Competitive moves concentrate on M&A to secure foundry capacity and strategic partnerships with gearbox integrators to bypass direct OEM qualification timelines.
Within the integrated tier, Siemens AG exemplifies foundry-backward positioning through German casting operations. ABB Ltd anchors the condition-monitoring convergence archetype with integrated sensor architectures. Altra Industrial Motion Corp. occupies the modular specialist position with flexible coupling designs reducing offshore nacelle installation hours. These three represent distinct competitive vectors without implying specific market share claims.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| Altra Industrial Motion Corp. |
| SKF Group |
| Voith GmbH & Co. KGaA |
| KTR Systems GmbH |
| Flender |
| Rexnord Corporation |
| John Crane |
| Others |
Pricing and Supply Chain Analysis
Synthetic ester lubrication replacing fluorinated greases under EU F-Gas Regulation is simultaneously redrawing foundry economics and compressing margin structures for coupling suppliers serving North Sea installations. This substitution dynamic concentrates pricing power with German and Danish manufacturers possessing integrated lubrication-system capabilities while fragmenting procurement pools for legacy suppliers.
Pricing Analysis
Price spreads between German-engineered couplings and Chinese-manufactured alternatives exceed fifty percent for equivalent torque ratings, reflecting certification-grade premiums attached to DNV-ST-0126 qualification. Three-tier pricing structure across premium certified, standard industrial, and economy retrofit levels differentiates procurement channels, with offshore developers absorbing premium tiers and independent power producers driving cost compression in onshore replacement markets. Pricing pressure stems from alloy steel input volatility in European spot markets, particularly nickel and molybdenum fluctuations. Maintenance service providers exhibit highest price sensitivity due to inventory standardization mandates, while offshore wind farm developers prioritize qualification premiums over unit cost.
Supply Chain Analysis
Germany and China anchor large-diameter steel casting capacity for multi-megawatt turbine couplings, controlling roughly seventy percent of heat-treated alloy hub production. The supply chain draws from nickel-molybdenum alloy steel feedstocks, synthetic ester lubricants, and precision-machined disc pack laminations. Single-source vulnerability concentrates in German foundry clusters where energy costs from EU emissions trading scheme compliance constrain expansion. Distribution runs through gearbox integrators like ZF Wind Power and Winergy, which bundle couplings into drivetrain packages for turbine OEMs, compressing direct supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-drive generator architectures fragmenting drivetrain specifications create specialist niches alongside integrated incumbents, rewarding modular suppliers with certification agility.
For Market Incumbents: Consolidate captive foundry capacity in Germany and China to secure alloy steel casting supply against nickel price volatility. Deepen backward integration into precision machining workflows to offset depleted apprenticeship pipelines for 5-axis CNC operators. Prioritize DNV-ST-0126 certification maintenance as emerging disc coupling specialists threaten obsolescence in 12 MW+ segments. For New Entrants and Emerging Players: DNV-ST-0126 fast-track qualification through strategic partnerships with gearbox integrators bypasses direct OEM timeline barriers. Target India's CEA grid-code amendment pathways for wind farms above 50 MW, where certification infrastructure remains underdeveloped. Pursue floating offshore wind pre-commercial projects demanding high-angular-tolerance flexible couplings as specification entry points. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors condition-monitoring integrators over pure mechanical component suppliers. Five-to-ten year viability hinges on embedded sensor convergence creating predictive maintenance revenue streams. Acquisition screening should prioritize coupling houses with torque telemetry integration capabilities. Watch for inflection when floating offshore wind moves from pre-commercial to serial deployment, triggering specification demand surges.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Expansion | Captive alloy steel casting in Germany insulates against ETS-driven energy cost volatility. |
| Condition-Monitoring Integration | Torque telemetry embedding enables predictive maintenance contracts with Orsted and Equinor. |
| Synthetic Ester Lubrication Transition | F-Gas Regulation compliance opens North Sea procurement to qualified European suppliers. |
| Certification Fast-Track Partnership | gearbox integrator alliances compress DNV-ST-0126 timelines for emerging disc coupling architectures. |
| Floating Wind Specification Development | High-angular-tolerance designs address platform motion misalignment in pre-commercial projects. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from drivetrain OEMs, and IEC certification databases. Primary interviews engaged procurement directors at offshore wind developers, drivetrain engineering leads at turbine OEMs, foundry operations managers, and aftermarket service heads. Secondary validation drew from DNV certification registries, EU ETS emissions data, and Chinese provincial auction announcements. Bottom-up coupling unit estimates triangulated against top-down drivetrain market projections.
Segmentation dimensions modeled include coupling product type, drivetrain technology architecture, end-user category, and installation context across the analysis window. CAGRs derived from regression analysis of historical procurement volumes against turbine deployment forecasts, incorporating alloy steel price indices and regulatory phase-in schedules. Industry-specific inputs encompassed DNV-ST-0126 certification timelines, REACH chemical restriction implementation dates, and CEA grid-code amendment adoption curves.
Decision-makers should treat outputs as directional under assumptions of continued offshore wind auction momentum and stable alloy steel supply; material deviation in nickel-molybdenum pricing or certification timeline extensions would warrant model refresh. Recalibration cycles align with material shifts in EU F-Gas Regulation enforcement, Chinese provincial auction awards, and floating offshore wind commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Floating Wind Turbine Market
Wind Energy Systems
Wind Power Hubcap Market
Wind Energy Systems
Offshore Wind Tower Market
Wind Energy Systems
Wind Electric Power Generation Market
Wind Energy Systems
Wind Energy Rescue System Market
Wind Energy Systems
North America Wind Power Market
Wind Energy Systems
Global Wind Turbine Operations Market
Wind Energy Systems
Thailand Wind Energy Market
Wind Energy Systems
Global Wind LIDAR Market
Wind Energy Systems
Poland Wind Energy Market
Wind Energy Systems
Italy Wind Energy Market
Wind Energy Systems
Wind Turbine Gearbox and Direct Drive Systems Market
Wind Energy Systems
Wind Turbine Control System Market
Wind Energy Systems
Global Wind Power Equipment Market
Wind Energy Systems
Wind Turbine Market
Wind Energy Systems
Germany Offshore Wind Energy Market