
 Fluid Handling Systems Market | 2026-2036
Fluid Handling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Fluid Handling Systems Market Intelligence
API 674 and ISO 5199 compliance tiers are unwinding legacy procurement patterns as end users specify higher reliability grades for critical service. Alfa Laval leverages its heat transfer integration to anchor premium positions in hygienic applications. Flowserve Corporation sustains dominance in severe-service valve engineering through captive casting and machining capacity. KSB SE & Co. KGaA specializes in standardized water pump platforms that compete aggressively on lifecycle cost metrics.
Fluid handling systems encompass engineered equipment for the controlled movement, measurement, and conditioning of liquids, gases, and slurries, typically operating at pressures from vacuum to 10,000 psi with materials selected for corrosion resistance and thermal stability. Their primary purpose is to ensure safe, efficient, and precise transport of process media across continuous and batch operations. Pumps and valves together constitute the core revenue pool, though digital control technology is capturing disproportionate margin expansion as facilities retrofit analog installations. Chemical processing and pharmaceuticals applications are leading volume contribution, while water treatment represents the fastest structural growth vector given municipal infrastructure renewal mandates.
EPA regulations on fugitive emissions and the EU F-Gas Regulation are tightening seal and packing specifications, forcing redesign cycles across installed bases. ISO 5199 and API standards govern international project eligibility, effectively filtering market access for non-certified suppliers. The EU Green Deal's embodied carbon tracking is beginning to shape material selection and foundry sourcing decisions. Stakeholders must monitor how digital twin integration requirements in process industries reshape service revenue models and aftermarket attachment rates.
Market Dynamics
Water treatment utilities are accelerating procurement of smart pumping infrastructure as EPA Lead and Copper Rule revisions force infrastructure replacement cycles across municipal networks. This regulatory pressure is compressing legacy equipment lifecycles and redirecting capital toward digitally integrated fluid handling platforms.
Growth Catalysts
- EPA Lead and Copper Rule revisions:Municipal water authorities in the United States face mandated infrastructure replacement timelines, driving demand for compliant valve and pump systems with enhanced monitoring capabilities.
- EU F-Gas Regulation:Industrial refrigeration and HVAC applications across Germany, France, and Italy require sealed system retrofits, expanding addressable market for low-emission fluid handling components.
- Smart sensor integration:Chemical processors deploy predictive maintenance architectures that embed vibration and temperature monitoring directly into pump housings and valve actuators.
Market Restraints
- Specialized alloy supply concentration:Duplex stainless steel and super-austenitic grades depend on concentrated European and Japanese foundry capacity, exposing procurement to geopolitical disruption.
- REACH compliance costs:EU chemical registration requirements elevate material certification expenses for seal compounds and coating systems, compressing margins on standardized product lines.
- Mechanical seal substitution:Magnetic drive and canned motor pump technologies eliminate seal maintenance entirely, threatening traditional packed pump aftermarket revenue streams.
Strategic Opportunities
- India industrial corridor expansion:Petroleum refining and petrochemical investments along the Gujarat-Maharashtra belt create demand for severe-service valve and high-pressure pump systems.
- Hydrogen infrastructure buildout:Liquid hydrogen transport and gaseous compression applications require cryogenic-compatible fluid handling equipment with novel sealing architectures.
- EU Green Deal embodied carbon tracking:Foundry sourcing decisions increasingly favor low-carbon steel and aluminum suppliers, rewarding early supply chain reconfiguration.
Industry Challenges
- API 674 and ISO 5199 certification timelines:Third-party validation for reciprocating pumps and centrifugal pump testing extends product launch schedules by 8-14 months.
- Digital-physical integration complexity:Legacy analog installations resist retrofit with IoT-enabled actuators and edge computing nodes without complete control system replacement.
- Specialized welding technician scarcity:Orbital welding for hygienic tubing and high-purity piping systems faces constrained certified labor pools in North American and European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluid Handling Systems Market |
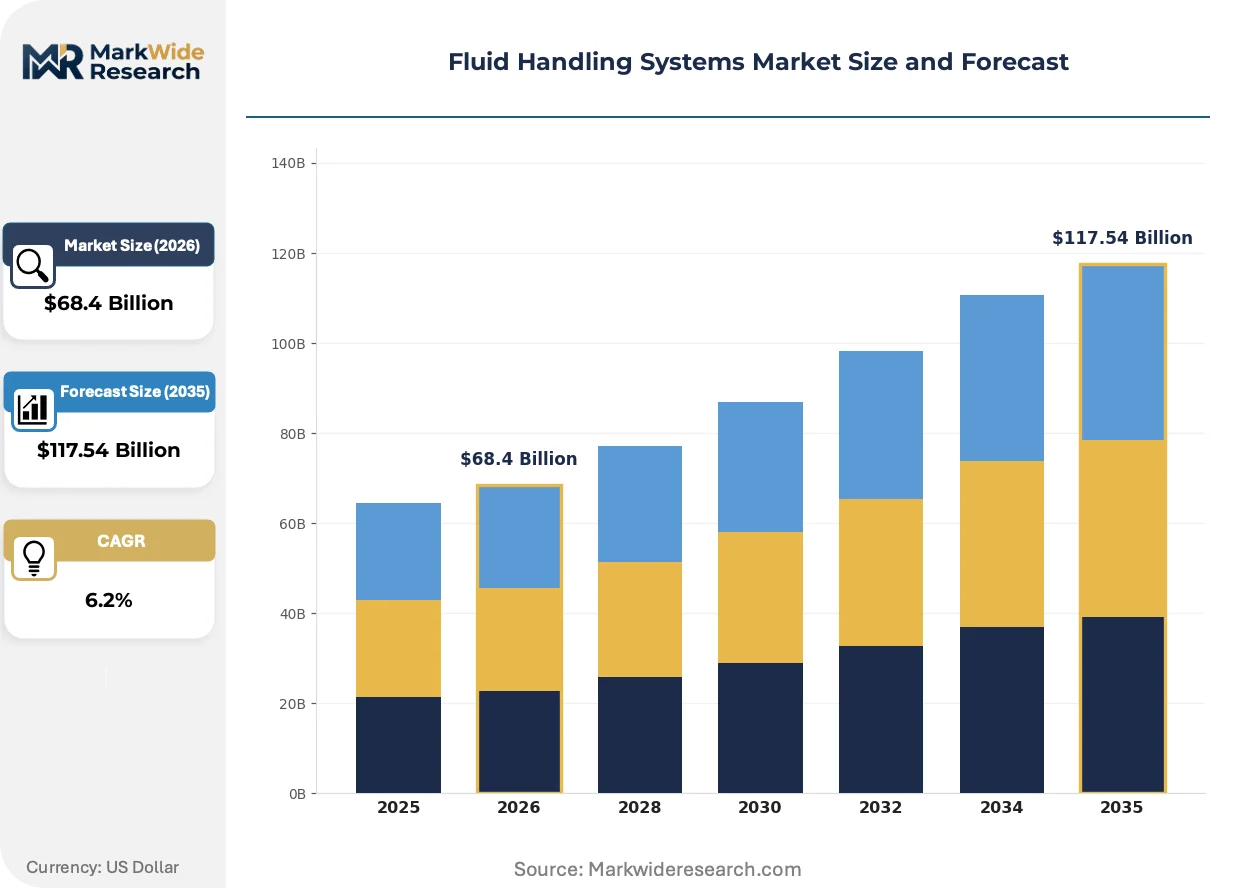
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $117.54 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pumps, Valves, Actuators, Flow Meters, Filters Technology: Hydraulic, Pneumatic, Electric, Mechanical, Digital Control Application: Chemical Processing, Water Treatment, Food & Beverage, Pharmaceuticals, Pulp & Paper End User Industry: Oilfield Services, Power Generation, Mining, Marine, Construction |
| Companies Covered | Alfa Laval, Flowserve Corporation, Graco Inc., Crane Co., SPX FLOW, KSB SE & Co. KGaA, Colfax Fluid Handling, Emerson Electric Co., ITT Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluid Handling Systems Market Strategic Shifts & Innovations
Digital twin architectures are reshaping how process industries specify, procure, and maintain fluid handling assets. Equipment vendors now compete on embedded software capabilities and predictive analytics integration rather than mechanical specifications alone.
Magnetic levitation bearing technology is miniaturizing. These contact-free support systems eliminate mechanical wear in high-speed centrifugal pumps, extending mean time between failures beyond 100,000 hours. Pharmaceutical bioprocessing facilities in Switzerland and Singapore adopt mag-lev pumps for sterile media transfer where contamination risks prohibit conventional lubrication. The technology is miniaturizing into compact skids that displace traditional multistage pump configurations in cleanroom environments.
REACH authorization lists now restrict per- and polyfluoroalkyl substances in seal and gasket compounds. ECHA's evolving candidate list forces compounders to reformulate fluoroelastomer and PTFE-based materials with reduced environmental persistence. Chemical processors in Belgium and the Netherlands face accelerated material qualification cycles as 2025 sunset dates approach for legacy sealing technologies.
Buyer consolidation among integrated oil companies compresses supplier lists to tier-one vendors with full lifecycle service capabilities. Engineering-procurement-construction firms now bundle fluid handling packages into larger mechanical contracts, marginalizing standalone pump and valve distributors. This concentration is most visible in Middle Eastern downstream projects where national oil companies mandate single-source accountability for rotating equipment packages.
Fluid Handling Systems Market Segmentation
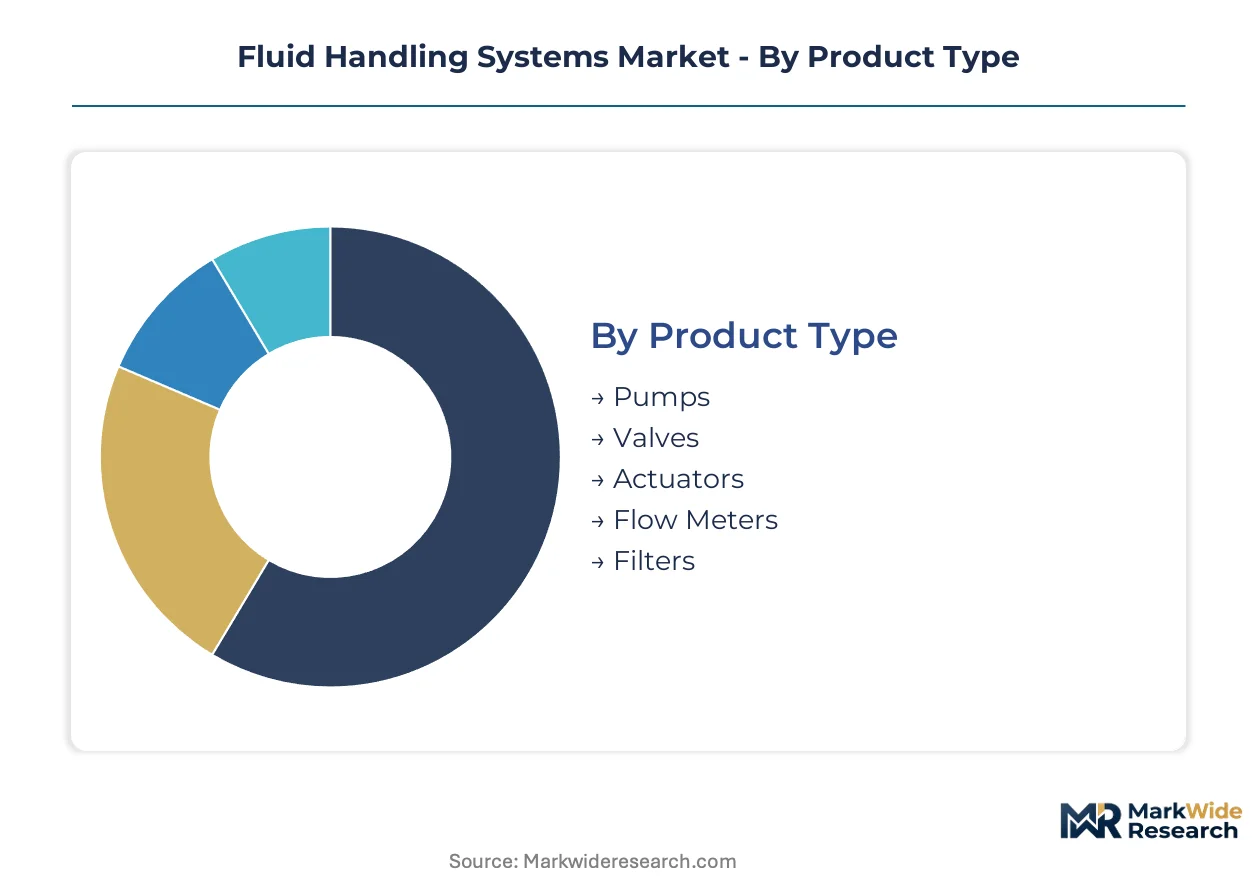
Fluid handling systems fragment across multiple technical and commercial dimensions. Equipment specification varies sharply by pressure rating, media compatibility, and regulatory compliance tier. Procurement patterns diverge between capital-intensive project markets and recurring aftermarket replacement cycles.
Product Type:
API 674 and ISO 5199 certification requirements split procurement into compliant and non-compliant tiers, with project eligibility hanging on test documentation.
- Pumps:Centrifugal and positive displacement configurations handle pressures from vacuum to 10,000 psi. Chemical processors in Germany's industrial corridor specify API 674-compliant reciprocating pumps for high-pressure injection duties. Municipal water authorities facing EPA Lead and Copper Rule mandates prioritize smart pumping platforms with embedded vibration monitoring.
- Valves:Severe-service metal-seated designs withstand erosive slurries and cryogenic temperatures. Flowserve's captive casting capacity anchors positions in oil sands and LNG applications. The EU F-Gas Regulation is forcing refrigeration system retrofits across Italy and France, expanding demand for low-emission sealed valves.
- Actuators:Pneumatic, hydraulic, and electric drive mechanisms position valves with precision. Electric actuators gain share in cleanroom environments where compressed air contamination poses risks.
- Flow Meters:Coriolis, ultrasonic, and electromagnetic technologies measure mass and volumetric flow. Custody transfer applications in petroleum refining demand certified accuracy grades.
- Filters:Cartridge, bag, and membrane configurations remove particulates from process streams. Bioprocessing facilities in Switzerland specify single-use filtration skids to eliminate cleaning validation burdens.
Pumps dominate installed base. Digital control integration is where expansion concentrates.
Technology:
Cost tier differentiation separates premium digital architectures from standardized mechanical systems, with mid-range pneumatic and hydraulic options occupying project-specific niches.
- Hydraulic:High power density suits mobile equipment and heavy industrial positioning. Mining operations in Western Australia deploy hydraulic actuators for valve control in remote, electrically constrained sites.
- Pneumatic:Compressed air systems offer intrinsic safety in explosive atmospheres. Pulp and paper mills favor pneumatic valve actuation for their reliability in humid, corrosive environments.
- Electric:Servo motors and variable frequency drives enable precise flow modulation. Pharmaceutical facilities in Singapore specify electric actuators for sterile isolator integration where air lines cannot penetrate.
- Mechanical:Direct-coupled and gear-driven systems persist in cost-sensitive water distribution. India's municipal infrastructure projects source mechanical pump configurations to minimize lifecycle complexity.
- Digital Control:Embedded sensors, edge computing, and predictive analytics transform asset management. Predictive maintenance architectures are climbing the fastest as chemical processors retrofit analog installations.
Mechanical systems anchor low-cost procurement. Digital control is capturing disproportionate margin expansion.
Application:
Customer type stratification separates project-driven capital equipment buyers from recurring aftermarket purchasers, with divergent specification and pricing dynamics.
- Chemical Processing:Corrosion-resistant alloys and specialized seals handle aggressive acids, caustics, and solvents. Belgian and Dutch processors face accelerated material qualification cycles as REACH sunset dates approach for legacy fluoroelastomer compounds.
- Water Treatment:Municipal and industrial facilities demand scalable, reliable flow control. EPA Lead and Copper Rule revisions are compressing replacement cycles across United States municipal networks.
- Food & Beverage:Hygienic design standards govern surface finish, drainability, and cleanability. Alfa Laval's heat transfer integration anchors premium positions in dairy and brewing applications.
- Pharmaceuticals:ASME BPE compliance and sterile design requirements elevate specification rigor. Magnetic levitation pumps eliminate contamination risks in bioprocessing media transfer.
- Pulp & Paper:Erosive stock handling and chemical recovery processes demand abrasion-resistant materials. Scandinavian mills modernize legacy fluid networks with severe-service valve configurations.
Chemical processing anchors volume contribution. Water treatment is gaining share fastest given infrastructure renewal mandates.
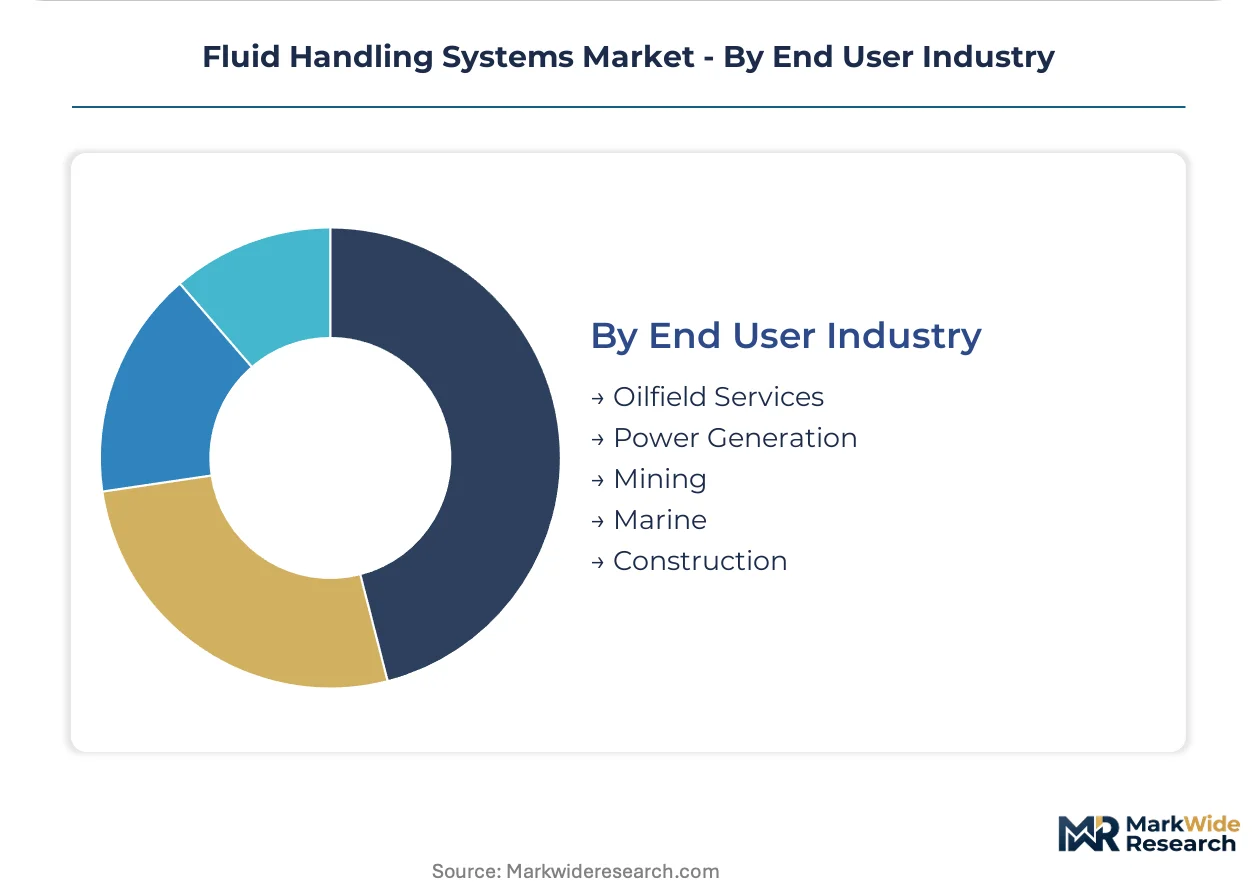
End User Industry:
Supply concentration in specialized alloy foundries shapes procurement risk profiles, with European and Japanese capacity exposure elevating sourcing scrutiny.
- Oilfield Services:High-pressure pumping and well control equipment operates in abrasive, corrosive downhole conditions. National oil companies in the Middle East are compressing supplier lists to tier-one vendors with full lifecycle accountability.
- Power Generation:Boiler feed pumps and cooling water systems require reliability-centered maintenance. Combined cycle gas turbine plants specify digital twins for rotating equipment optimization.
- Mining:Slurry transport and dewatering applications consume wear-resistant pump configurations. Chilean copper concentrators source severe-service valves for tailings management.
- Marine:Ballast water treatment and fuel handling systems face IMO compliance pressures. Shipyards in South Korea integrate smart pumping platforms for operational efficiency.
- Construction:Dewatering, concrete pumping, and HVAC systems drive mobile equipment demand. Infrastructure projects along India's Gujarat-Maharashtra belt create demand for standardized water pump platforms.
Oilfield services concentrate premium specification. Water treatment utilities are redirecting capital toward digitally integrated platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor established manufacturing bases with captive foundry capacity. Germany and Japan maintain surplus positions in specialized alloy components. The United States and China balance substantial domestic demand against selective component sourcing.
United States
Municipal water authorities accelerate smart pumping procurement under EPA Lead and Copper Rule mandates. Infrastructure replacement timelines compress legacy equipment cycles across Midwestern and Northeastern networks. Chicago and Detroit metropolitan utilities deploy digitally integrated valve systems with embedded monitoring.
Germany
Chemical processors along the Rhine-Ruhr industrial corridor modernize high-pressure injection systems. EU F-Gas Regulation enforcement drives sealed refrigeration retrofits across Bavarian and Baden-Württemberg facilities. Stuttgart automotive suppliers specify ISO 5199-compliant centrifugal pumps for precision manufacturing lines.
China
Petrochemical investments in the Yangtze River Delta and Shandong Peninsula demand severe-service valve configurations. National dual carbon goals reshape foundry sourcing toward low-emission steel suppliers. Shanghai and Ningbo process engineering clusters integrate predictive maintenance architectures into new plant designs.
India
Petroleum refining expansion along the Gujarat-Maharashtra belt creates demand for high-pressure pump systems. Bureau of Indian Standards certification requirements filter import eligibility for critical service equipment. Reliance Industries and public sector refineries in Jamnagar and Mumbai source API-compliant rotating equipment packages.
Japan
Specialized super-austenitic alloy production concentrates in Osaka-Kobe and Nagoya manufacturing zones. METI industrial efficiency directives accelerate digital twin adoption in process industries. Yokkaichi chemical complexes deploy magnetic levitation pumps for sterile media transfer in pharmaceutical applications.
Fluid Handling Systems Market Key Industry Players
Concentration sits with diversified industrial conglomerates possessing captive casting capacity and full-lifecycle service networks. Mid-tier specialists compete on standardized water pump platforms and regional aftermarket proximity. Three archetypes dominate: integrated flow control conglomerates with in-house metallurgy, hygiene-focused heat transfer specialists, and severe-service valve engineers with project execution scale. Competitive moves center on backward integration into specialized alloy supply and predictive analytics platform development.
Among European-based industrial groups, Alfa Laval exemplifies the hygiene-integrated archetype through its heat transfer positioning. Flowserve Corporation occupies a position in severe-service engineering with project-scale execution capabilities. KSB SE & Co. KGaA anchors the standardized platform tier with lifecycle cost-focused water pump systems. These three represent divergent specialization vectors rather than direct overlap.
| Leading Market Players |
|---|
| Alfa Laval |
| Flowserve Corporation |
| Graco Inc. |
| Crane Co. |
| SPX FLOW |
| KSB SE & Co. KGaA |
| Colfax Fluid Handling |
| Emerson Electric Co. |
| ITT Inc. |
| Others |
Cost & Logistics Intelligence
API 674 and ISO 5199 certification tiers gate both supplier qualification and price differentiation simultaneously, forcing procurement officers to pay premiums for compliant documentation while compressing margins on non-certified alternatives. This dual-gating mechanism concentrates pricing power with foundries possessing captive testing capacity.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation centers on certification grade and after-sales service bundling, with API-compliant severe-service configurations commanding substantial premiums over standardized water pump platforms. Pricing pressure stems from REACH compliance costs elevating material certification expenses for seal compounds. Municipal water authorities exhibit highest price sensitivity due to budget-constrained procurement cycles, while pharmaceutical bioprocessors prioritize contamination risk mitigation over unit economics.
Supply Chain Analysis
European and Japanese foundry capacity for duplex stainless steel and super-austenitic grades constitutes a critical chokepoint for specialized alloy procurement. Raw material dependencies center on nickel, chromium, and molybdenum feedstocks. Single-source vulnerability concentrates in Osaka-Kobe and Nagoya manufacturing zones for super-austenitic production. Distribution runs through engineering-procurement-construction firms bundling fluid handling packages into larger mechanical contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin integration is reshaping competitive positioning in fluid handling systems, with predictive maintenance architectures climbing fastest as chemical processors retrofit analog installations.
For Market Incumbents: Shield aftermarket revenue streams from magnetic drive and canned motor pump substitution by deepening predictive analytics platform development. Capture certification investment returns through API 674 and ISO 5199 documentation services that lock in long-term service contracts. Prioritize backward integration into specialized alloy supply to mitigate foundry concentration risk. For New Entrants and Emerging Players: ISO 5199 fast-track certification opens municipal water utility procurement in Germany's industrial corridor where legacy network modernization accelerates. Target India's Gujarat-Maharashtra petroleum refining belt for severe-service valve and high-pressure pump demand. Pursue joint-venture structures with established EPC firms to bypass standalone distribution marginalization. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-tier water pump specialists lacking digital control integration capabilities. Five-to-ten year viability favors vendors with captive casting capacity and full-lifecycle service networks. Monitor hydrogen infrastructure buildout signals as cryogenic-compatible equipment demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialized Alloy Supply | Captive foundry capacity insulates Flowserve and KSB from geopolitical disruption in European and Japanese super-austenitic production. |
| Predictive Maintenance Platform Development | Embedded vibration monitoring in pump housings transforms Alfa Laval's heat transfer integration into recurring software revenue. |
| Hydrogen Infrastructure Equipment Qualification | Cryogenic-compatible sealing architectures open liquid hydrogen transport applications for early movers in Japan and Germany. |
| REACH-Compliant Seal Compound Reformulation | Fluoroelastomer alternatives with reduced environmental persistence secure Belgian and Dutch chemical processor contracts. |
| Smart Pumping Infrastructure Deployment | EPA Lead and Copper Rule compliance drives Chicago and Detroit metropolitan utilities toward digitally integrated valve systems. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, and industry association reports. Plant engineers, OEM procurement teams, aftermarket service heads, and EPC contractors provided operational perspective. Bottom-up equipment unit economics triangulated against top-down capital expenditure tracking across chemical processing and water treatment verticals.
Segmentation dimensions modeled include product type, technology tier, application vertical, and end-user industry across the projection horizon. CAGRs derived from historical replacement cycle analysis and regulatory mandate acceleration curves. Hydrogen infrastructure investment pipelines and municipal infrastructure renewal timelines served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained EPA enforcement and EU F-Gas Regulation compliance timelines; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as REACH authorization list evolution and specialized alloy supply concentration patterns shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Electronic Expansion Valves Market
Valves
Hybrid Valve Market
Valves
Global Pressure Relief Valves Market
Valves
Steel Cylinder Market
Valves
Global Valves Market
Valves
Dense Phase Vessels Market
Valves
North America Residential Ball Valves Market
Valves
Expansion Valves Market
Valves
Hydraulic Valves Market
Valves
Harmonic Dampers Market
Valves
Low Voltage (LV) and Medium Voltage (MV) Switchgear Market
Valves
China Explosion-Proof Equipment Market
Valves
Manual Control Valve Market
Valves
Cryogenic Valve Market
Valves
Global Control Valves Market
Valves
Railway Emergency Valves Market