
 Electrohydraulic Pumps Market | 2026-2036
Electrohydraulic Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Electrohydraulic Pumps Market Analysis
Modular pump-motor assemblies is decoupling traditional bundled hydraulic power units into standalone, replaceable subsystems. Bosch Rexroth leverages its integrated drive technology to dominate electromechanical pump configurations for mobile machinery. Danfoss Power Solutions sustains competitive pressure through its Editron division's electric powertrain expertise in marine and off-highway segments.
Electrohydraulic pumps combine electric servomotors with positive-displacement hydraulic pumps to generate controlled fluid power, typically operating at pressures from 250 to 700 bar with flow rates calibrated to load-sensing demands. Their primary purpose is converting electrical energy into precise mechanical actuation for heavy machinery, aircraft control surfaces, and industrial presses. Compact pumps and high-pressure pumps capture diverging margin pools, with the former expanding through space-constrained mobile equipment designs and the latter commanding premium positioning in aerospace landing gear and deep-sea applications. Directional control valves and proportional control technology represent the fastest-growing intersection, as closed-loop electronic feedback replaces mechanical pilot stages.
EPA Tier 4 Final and upcoming Stage V compliance pathways in the United States and Europe are forcing hydraulic OEMs to redesign power units around electrified prime movers, while the EU Machinery Directive and ISO 4413 safety standards govern fluid power system certification. China's GB standards for construction machinery efficiency and Japan's METI energy conservation benchmarks are adding parallel compliance layers for exporters. Stakeholders must weigh the capital intensity of smart hydraulic system development against the risk of ceding position to pure electromechanical actuator suppliers in precision control applications.
Market Dynamics
Electrification of hydraulic powertrains is compressing the traditional boundary between fluid power and electromechanical actuation, forcing OEMs to rearchitect power units around servomotor-driven pumps rather than diesel prime movers.
Growth Catalysts
- EPA Tier 4 Final:Off-road diesel emissions standards in the United States are mandating electrified prime movers in construction equipment, accelerating replacement of engine-driven hydraulic systems.
- Load-sensing pump technology:Electronic displacement control enables precise flow matching to demand cycles, cutting parasitic losses in excavator and loader duty profiles.
- Germany supplier density:Stuttgart and Ulm corridor concentration of precision hydraulics engineering accelerates prototype-to-production cycles for automotive and aerospace applications.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings embedded in servomotor rotors compress margin predictability for pump-motor assembly manufacturers.
- High-pressure seal supply concentration:Specialized fluoroelastomer seals for 700-bar operation source predominantly from Japanese and German chemical compounders, creating single-source vulnerability.
- Electromechanical substitution:Linear electromechanical actuators displace electrohydraulic solutions in sub-50 kW precision positioning applications, narrowing addressable market scope.
Strategic Opportunities
- Marine electrification:Harbor craft and workboat segments underpenetrated by electrohydraulic systems present white space for compact pump-motor units with IP67 sealing.
- EU Green Deal industrial incentives:Carbon border adjustment mechanisms and green procurement mandates favor electrified hydraulic architectures in European manufacturing capital expenditure.
- Digital hydraulic valve convergence:Integration of high-speed switching valves with electrohydraulic pumps enables software-defined pressure and flow control, opening precision agriculture and autonomous construction markets.
Industry Challenges
- Mechatronics skill scarcity:Cross-functional engineering talent fluent in both hydraulic circuit design and motor control algorithms commands premium compensation, constraining R&D team scaling.
- ISO 4413 certification timelines:Safety validation for closed-loop electronic feedback systems extends product launch schedules by 8-14 months versus traditional pilot-operated architectures.
- Legacy fleet retrofit complexity:Integration of electrohydraulic pumps with existing mechanical control linkages in installed construction equipment base requires custom adapter engineering, fragmenting project economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrohydraulic Pumps Market |
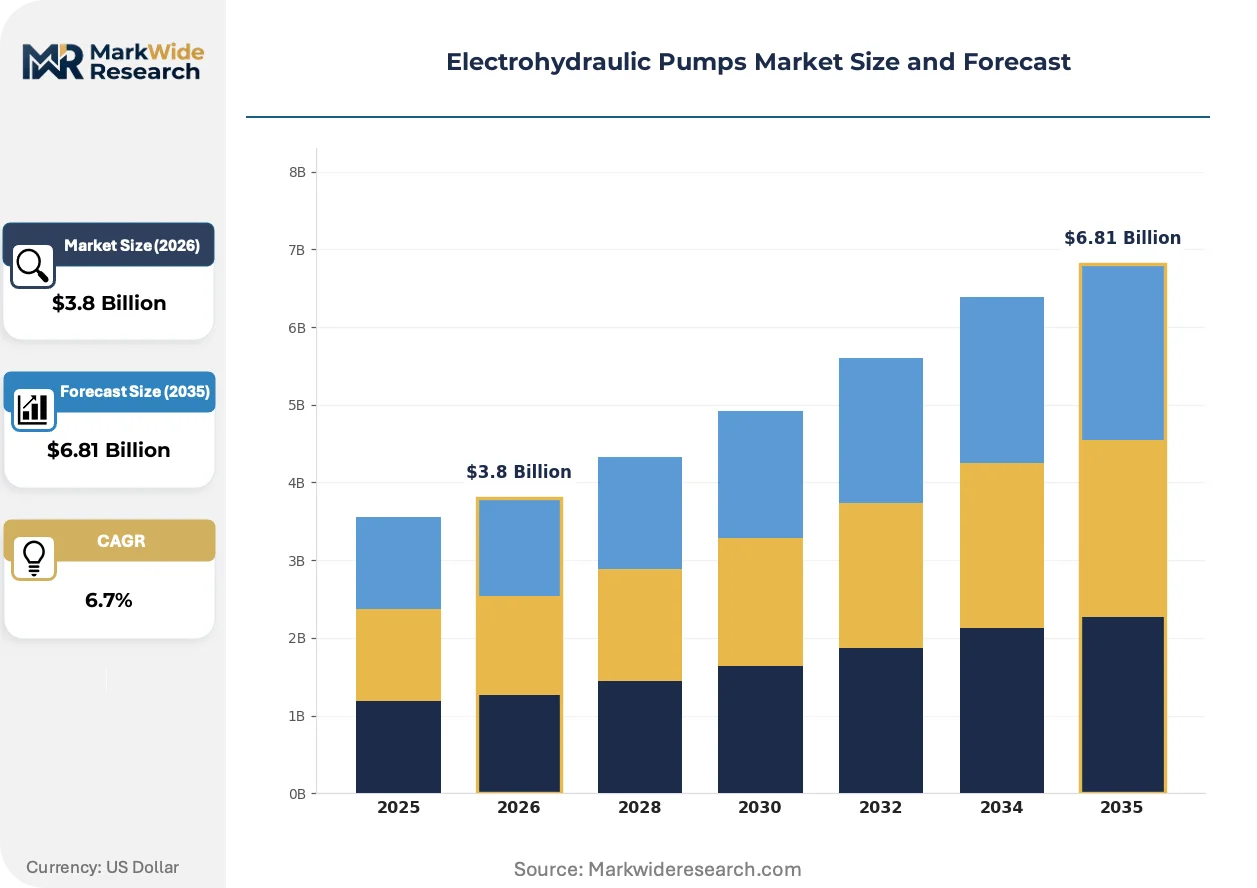
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Directional Control Valves, Pressure Relief Valves, Compact Pumps, High-Pressure Pumps End User: Aerospace, Automotive Manufacturers, Marine Sector, Construction Equipment Application: Hydraulic Systems, Lifting Equipment, Precision Control, Fluid Power Systems Technology: Electromechanical, Smart Hydraulic Systems, Proportional Control, Wireless Control Systems |
| Companies Covered | Danfoss Power Solutions, Hydac International, Bosch Rexroth, Bucher Hydraulics, Moog, Parker Hannifin, HAWE Hydraulik, Kawasaki Heavy Industries, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrohydraulic Pumps Market Emerging Trajectories
Digitalization of hydraulic control loops is collapsing the traditional separation between power generation and motion control, enabling software-configurable machines that adapt duty cycles in real time rather than through mechanical hardware swaps.
Electrohydraulic pump-motor units are converging with onboard edge computing platforms to enable autonomous load recognition and predictive pressure modulation. Mining truck and material handler OEMs pilot these configurations in Australian and Chilean operations. The technology is compressing the historical trade-off between hydraulic power density and electronic precision, enabling single-platform architectures to span multiple machine classes.
Stage V emissions frameworks in Europe are banning diesel-only hydraulic power units in urban construction zones, forcing rental fleet operators to electrify compact excavators and telehandlers. The regulation is accelerating development of battery-integrated pump modules with thermal management systems. German and French municipal procurement specifications now mandate zero-emission hydraulics for publicly funded infrastructure projects.
Equipment-as-a-service contracting is displacing outright purchase in North American construction rental channels, shifting specification authority from owner-operators to fleet managers who prioritize telemetry-enabled maintenance predictability. Electrohydraulic pumps with embedded vibration and temperature sensors command contract premiums in this channel. The pattern is most visible in Texas and Florida equipment rental markets where utilization-based billing dominates mid-size excavator deployments.
Electrohydraulic Pumps Market Segmentation
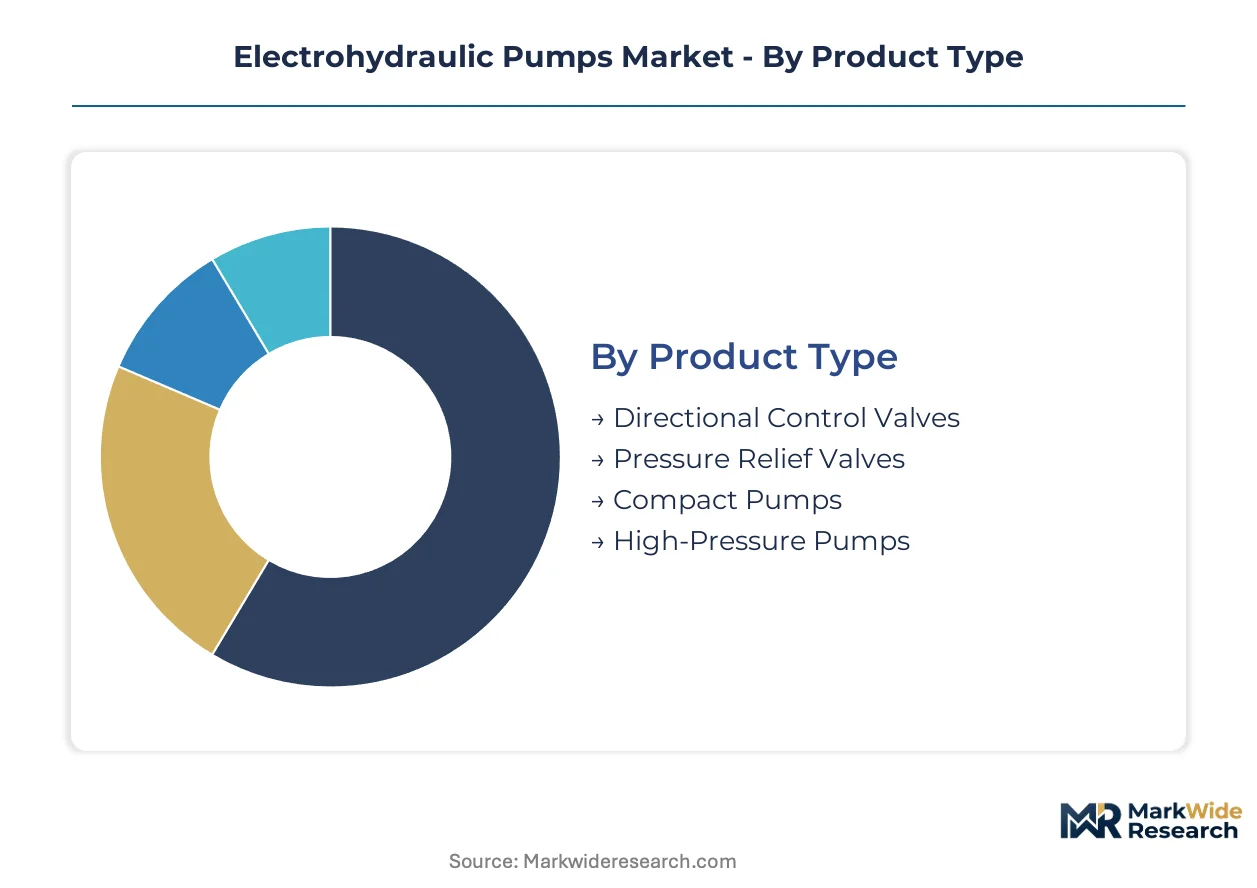
Electrohydraulic pump architectures diverge sharply across pressure ratings, control modalities, and duty cycle profiles. Buyers prioritize either compact footprint for mobile machinery or precision response for closed-loop positioning systems.
Product Type:
Pressure tolerance and displacement volume separate procurement decisions across construction, aerospace, and industrial press applications.
- Compact Pumps:These units integrate servomotor drives with axial piston or gear pump architectures in sub-15 kW power envelopes. Excavator and telehandler OEMs in Germany specify these for space-constrained boom and bucket circuits where diesel engine replacement demands minimal envelope expansion.
- High-Pressure Pumps:Operating at 400-700 bar with hardened steel housings and ceramic-coated plungers, these serve aircraft landing gear extension and deep-sea ROV tooling. Japanese and German aerospace tier-1 suppliers source these for FAA and EASA-certified flight control systems where failure modes must be deterministic.
- Directional Control Valves:Spool-type configurations with solenoid pilot stages route pressurized fluid to actuator ports in mobile hydraulic circuits.
- Pressure Relief Valves:Spring-biased or electronically modulated poppet designs protect system components from overpressure events in industrial presses.
Volume sits with Compact Pumps; growth tilts toward High-Pressure Pumps.
End User:
Certification burden and duty cycle predictability shape specification authority across buyer categories.
- Construction Equipment:OEMs and rental fleet operators procure electrohydraulic units for excavators, loaders, and telehandlers under EPA Tier 4 Final compliance deadlines. Texas and Florida rental channels now mandate telemetry-enabled pumps for utilization-based billing contracts.
- Aerospace:Airframe manufacturers and landing gear specialists specify MIL-STD-810 tested pump-motor assemblies for primary flight control surfaces. FAA certification timelines and deterministic failure mode requirements constrain supplier qualification to established German and Japanese hydraulics houses.
- Automotive Manufacturers:Press shops and assembly line fixture builders deploy these pumps for clamping and stamping operations.
- Marine Sector:Harbor craft operators and workboat builders represent underpenetrated demand for IP67-sealed pump modules.
Revenue concentrates in Construction Equipment; Aerospace commands the steepest expansion trajectory.
Application:
Control loop architecture—open versus closed feedback—determines electronic integration depth.
- Precision Control:Closed-loop electrohydraulic systems with sub-millisecond response times serve CNC machine tool axes and aircraft flight surface actuation. German automotive press builders and French aerospace suppliers specify these where positional accuracy must hold within 0.01 mm under varying load.
- Hydraulic Systems:Broad category encompassing power generation circuits for industrial machinery and mobile equipment where flow rate modulation replaces mechanical throttling.
- Lifting Equipment:Forklifts, cranes, and aerial work platforms utilize load-holding valves and meter-out flow control for safety-critical elevation functions.
- Fluid Power Systems:Integrated power units combining pumps, reservoirs, and filtration for stationary industrial installations.
Installed base favors Hydraulic Systems; Precision Control gains share fastest.
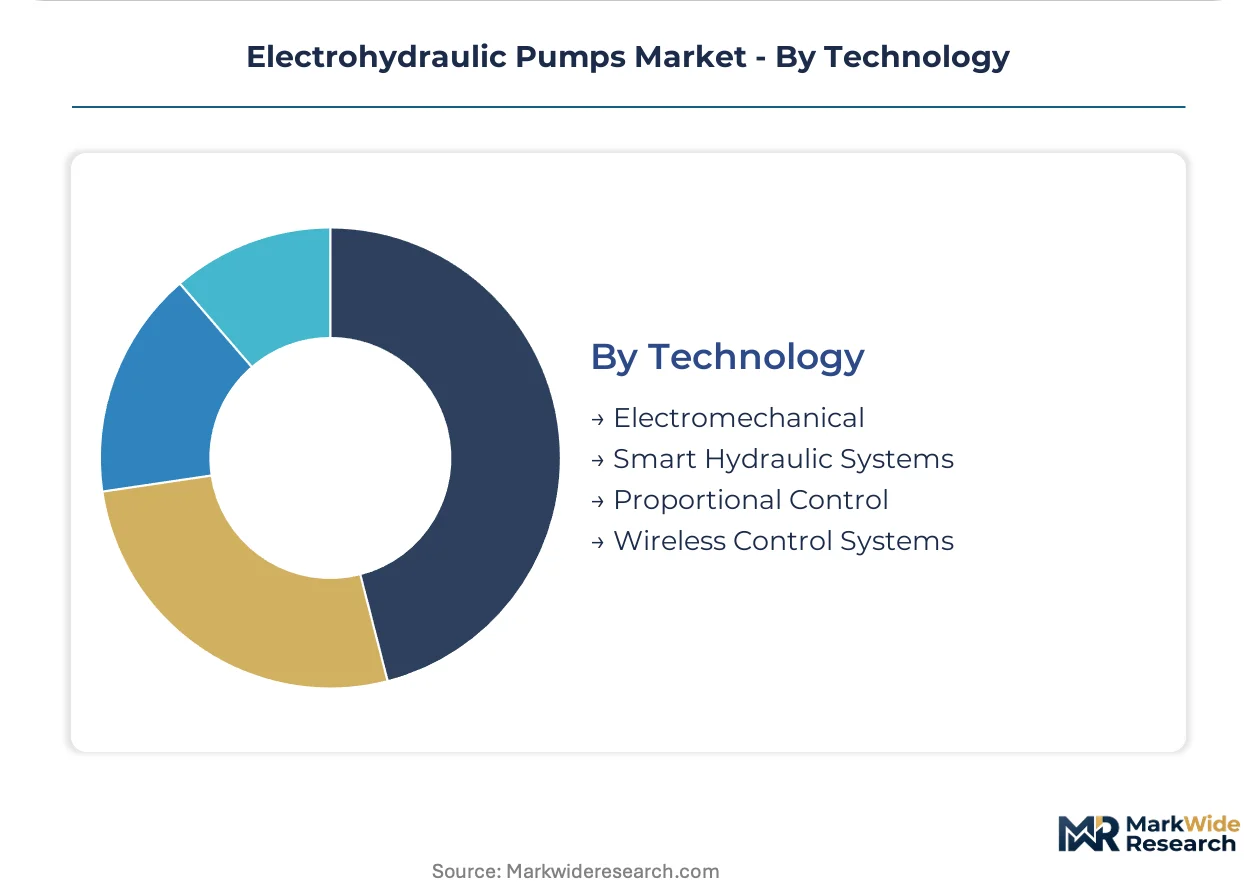
Technology:
Software-defined functionality separates legacy electromechanical implementations from digitally native architectures.
- Smart Hydraulic Systems:Edge-computing-enabled pump-motor units with embedded vibration, temperature, and pressure sensors transmit telemetry for predictive maintenance algorithms. Mining truck OEMs in Australia pilot these configurations for autonomous load recognition and real-time pressure modulation.
- Proportional Control:Variable displacement pumps with electronic pilot stages enable continuous flow adjustment without discrete valve switching.
- Electromechanical:Conventional servomotor-driven fixed-displacement pumps without onboard intelligence or network connectivity.
- Wireless Control Systems:Bluetooth or proprietary RF-linked pump controllers for retrofit installations where cable routing is impractical.
Electromechanical dominates current shipments; Smart Hydraulic Systems expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's industrial corridor functions as the primary tax-incentive zone concentrating electrohydraulic engineering talent and precision manufacturing infrastructure. Germany's dense supplier ecosystem accelerates prototype-to-production cycles for automotive and aerospace hydraulics applications.
United States
EPA Tier 4 Final emissions mandates are forcing construction equipment OEMs toward electrified hydraulic architectures. The regulation compresses diesel prime mover replacement timelines for excavators and loaders. Texas and Florida rental fleet operators now specify telemetry-enabled pumps for utilization-based billing contracts.
Germany
EU Green Deal industrial incentives and carbon border adjustment mechanisms favor electrified hydraulic capital expenditure. The EU Machinery Directive and ISO 4413 safety standards govern fluid power system certification. Stuttgart and Ulm anchor a precision hydraulics corridor serving automotive press shops and aerospace tier-1 suppliers.
Japan
METI energy conservation benchmarks add compliance layers for construction machinery efficiency. The country's national industrial regulator pushes exporters toward lower-carbon hydraulic powertrains. Tokyo and Osaka metropolitan areas concentrate high-pressure seal compounders and aerospace hydraulics specialists.
China
GB standards for construction machinery efficiency mandate progressive electrification of hydraulic systems. The country's national standards administration enforces dual carbon goals across industrial equipment imports. Yangtze River Delta manufacturing clusters integrate electrohydraulic units into locally produced excavators and material handlers.
Electrohydraulic Pumps Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: integrated drive technology conglomerates, precision hydraulics specialists, and diversified motion control multinationals. Dominant competitive moves include strategic partnerships for marine electrification and portfolio diversification into smart hydraulic systems with embedded sensing.
Within the integrated drive technology tier, Bosch Rexroth and Danfoss Power Solutions exemplify archetypes combining electromechanical expertise with hydraulic domain knowledge. Among precision hydraulics specialists, HAWE Hydraulik and Bucher Hydraulics occupy positions emphasizing high-pressure applications and compact pump architectures. These named entities represent competitive positioning patterns rather than discrete strategic actions.
| Leading Market Players |
|---|
| Danfoss Power Solutions |
| Hydac International |
| Bosch Rexroth |
| Bucher Hydraulics |
| Moog |
| Parker Hannifin |
| HAWE Hydraulik |
| Kawasaki Heavy Industries |
| Eaton |
| Others |
Supply Flow & Price Mechanics
EPA Tier 4 Final compliance gates qualified supply for electrohydraulic pump-motor assemblies, restricting premium-tier pricing access to OEMs with certified electrified architectures. Construction equipment manufacturers in the United States absorb cost premiums for EPA-validated units, while rental fleet operators in Texas and Florida negotiate telemetry-enabled configurations for utilization-based contracts.
Pricing Analysis
Cost-down pressure on compact pump-motor units accelerates because rare earth magnet volatility in servomotor rotors compresses margin predictability. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified aerospace configurations from industrial press applications and mobile machinery commodity pumps. Certification grade and volume scale drive price differentiation, with German automotive press builders least sensitive and Chinese construction OEMs most price-sensitive. Pricing pressure stems from electromechanical actuator substitution in sub-50 kW positioning applications.
Supply Chain Analysis
Dual-sourcing requirements for high-pressure fluoroelastomer seals mandate multi-supplier qualification across Japanese and German chemical compounders. Manufacturing concentrates in Germany, Japan, and China, with Stuttgart and Ulm anchoring precision hydraulics engineering and Yangtze River Delta clusters integrating units for local excavator production. Supply chain risk rests on single-source vulnerability for 700-bar ceramic-coated plungers and neodymium-dysprosium magnet supply. Distribution runs through OEM direct procurement for construction and aerospace tier-1 supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrohydraulic pumps market constitutes a vertical-integration race where captive control over servomotor production and high-pressure seal supply determines margin defense. Players pursue upstream integration into rare earth magnet sourcing and downstream into telemetry-enabled aftermarket service contracts.
For Market Incumbents: To counter electromechanical actuator substitution in precision positioning, Bosch Rexroth and Danfoss Power Solutions should deepen backward integration into servomotor manufacturing and anchor certification investment in FAA and EASA flight control qualifications. Channel control through exclusive rental fleet telemetry partnerships in Texas and Florida defends installed base positions against emerging smart hydraulic entrants. For New Entrants and Emerging Players: Harbor craft operators in marine electrification represent an underserved buyer archetype with minimal incumbent penetration. IP67-sealed compact pump-motor units for workboat applications and battery-integrated thermal management modules for European municipal procurement offer white-space entry points. A go-to-market angle targeting French and German zero-emission infrastructure mandates bypasses saturated construction OEM channels. For Investors and Strategic Acquirers: German municipal procurement specifications mandating zero-emission hydraulics for publicly funded projects is the leading indicator that electrified hydraulic architectures will consolidate market share over the mid-term horizon. Acquisition targets should display captive high-pressure seal supply relationships or embedded edge-computing telemetry platforms. The signal to monitor is Stage V enforcement acceleration in urban construction zones.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Captive neodymium-dysprosium sourcing insulates servomotor rotors from price volatility. |
| Smart Hydraulic System Development | Edge-computing pump-motor units with embedded sensors command telemetry premiums in rental channels. |
| Marine Electrification Partnership | IP67-sealed configurations for harbor craft open underpenetrated workboat demand segments. |
| FAA-EASA Certification Investment | Deterministic failure mode validation qualifies suppliers for aerospace landing gear actuation. |
| Battery-Integrated Thermal Management | Modular pump-motor-reservoir units meet Stage V zero-emission mandates in European urban zones. |
Methodological Framework
SEC 10-K filings, EPA certification databases, and EU Machinery Directive compliance registries formed the secondary backbone for market sizing and competitive positioning. Primary interviews with construction equipment OEM procurement directors, aerospace tier-1 hydraulic system engineers, rental fleet operations managers, and marine workboat builders validated demand assumptions. Bottom-up unit shipment estimates triangulated against top-down value projections across pressure rating, control modality, and end-use segmentation.
Bottom-up modeling tracked electrohydraulic pump-motor assembly shipments by pressure tier, servomotor power envelope, and certification grade across the projection horizon. Top-down analysis calibrated total addressable market value against construction equipment production forecasts, aerospace OEM delivery schedules, and industrial press capital expenditure patterns. CAGRs derived from regression analysis of historical electrification adoption curves in off-road machinery and marine propulsion segments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth magnet price volatility and electromechanical actuator substitution rates. Deviation in EPA enforcement timelines or Stage V implementation acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Vertical Turbine Pumps Market
Pumps and Control Devices
Middle East and Africa Centrifugal Pumps Market
Pumps and Control Devices
Progressive Cavity Pump (PCP) Market
Pumps and Control Devices
Worm Pumps Market
Pumps and Control Devices
Oil and Gas Actuators Market
Pumps and Control Devices
Industrial Vacuum Pumps Market
Pumps and Control Devices
Slurry Pumps Market
Pumps and Control Devices
Global Compressor Control Systems Market
Pumps and Control Devices
North America Positive Displacement Pumps Market
Pumps and Control Devices
Volute Pump Market
Pumps and Control Devices
Jetting Pumps Market
Pumps and Control Devices
Multi-Stage Centrifugal Pumps Market
Pumps and Control Devices
Latin America Positive Displacement Pumps Market
Pumps and Control Devices
Chemical Pump Market
Pumps and Control Devices
Subsea Pumps Market
Pumps and Control Devices
Dry Vacuum Pumps Market