
 Oil and Gas Fittings Market | 2026-2036
Oil and Gas Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Fittings Market Outlook
Offshore exploration is repositioning demand toward high-pressure subsea fittings. Parker Hannifin dominates hydraulic connector engineering for deepwater riser systems. Swagelok specializes in precision instrumentation fittings for sour gas applications. Victaulic anchors grooved mechanical coupling standards across floating production platforms.
Oil and gas fittings are pressure-rated mechanical joining components, typically forged from alloy steels or corrosion-resistant alloys and tested to API 6A/6D specifications, designed to contain hydrocarbon flow across upstream through downstream infrastructure. Flanges and valves command the largest product share due to replacement cycles in aging pipeline networks. Stainless steel material grades capture premium margin pools in corrosive offshore environments where duplex and super-duplex specifications dominate tender requirements. Subsea installation types represent the fastest-growing structural segment as tieback architectures multiply field developments without fixed platform capital.
API publishes material and testing standards that govern product qualification across North American upstream procurement. NORSOK M-001 and DNV ST-F101 specifications shape North Sea and broader European offshore project engineering requirements. Brazil's national petroleum regulator mandates local content thresholds that constrain foreign supplier participation in pre-salt developments. Stakeholders must monitor evolving subsea integrity management regulations and qualification protocol harmonization between regional certification bodies.
Market Dynamics
Deepwater field architectures are compressing procurement cycles for subsea-rated alloy fittings, forcing vendors to pre-qualify duplex stainless grades against harmonized API-NORSOK test protocols before tender participation.
Growth Catalysts
- Pre-salt development mandates:Brazil's national petroleum regulator enforces local content thresholds that redirect fabrication contracts toward domestic forging capacity, expanding the addressable supplier base for high-pressure connectors.
- API 6A specification upgrades:Tightened material traceability requirements for wellhead equipment are disqualifying legacy inventory, generating replacement demand across Permian and Bakken shale basins.
- Subsea tieback proliferation:Floating production operators in the Gulf of Mexico are standardizing on compact flange systems to reduce offshore welding hours, accelerating specification convergence among engineering contractors.
Market Restraints
- Nickel alloy input volatility:Super-duplex and Inconel feedstock prices swing with London Metal Exchange nickel contract movements, compressing margin predictability for forged component specialists.
- Fabrication concentration risk:Heavy-wall forging capacity for pressure classes above 15,000 psi concentrates among a handful of European and Japanese mill operators, creating single-source vulnerability for critical path projects.
- DNV ST-F101 compliance friction:Subsea pipeline qualification protocols require extensive strain-based design testing that extends lead times for novel fitting geometries beyond standard project schedules.
Strategic Opportunities
- Decommissioning infrastructure wave:North Sea operators face statutory removal obligations under OSPAR Convention timelines, creating demand for hot-tap fittings and isolation tools that enable safe pipeline sectioning.
- Hydrogen-ready material certification:Emerging embrittlement testing standards for high-pressure hydrogen service open premium positioning for 316L and 347H stainless grades in repurposed natural gas networks.
- Digital twin integration:Sensor-embedded fittings that stream pressure and corrosion data to asset integrity platforms are capturing specification preference among integrated majors deploying predictive maintenance systems.
Industry Challenges
- Weld procedure qualification backlog:Specialized orbital welding technicians for super-duplex and titanium systems remain scarce relative to project demand, extending fabrication schedules for subsea manifolds.
- Legacy flange standard fragmentation:In-service pipelines across the US Gulf Coast deploy obsolete API and MSS flange dimensions that complicate replacement sourcing and inventory rationalization for maintenance contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Fittings Market |
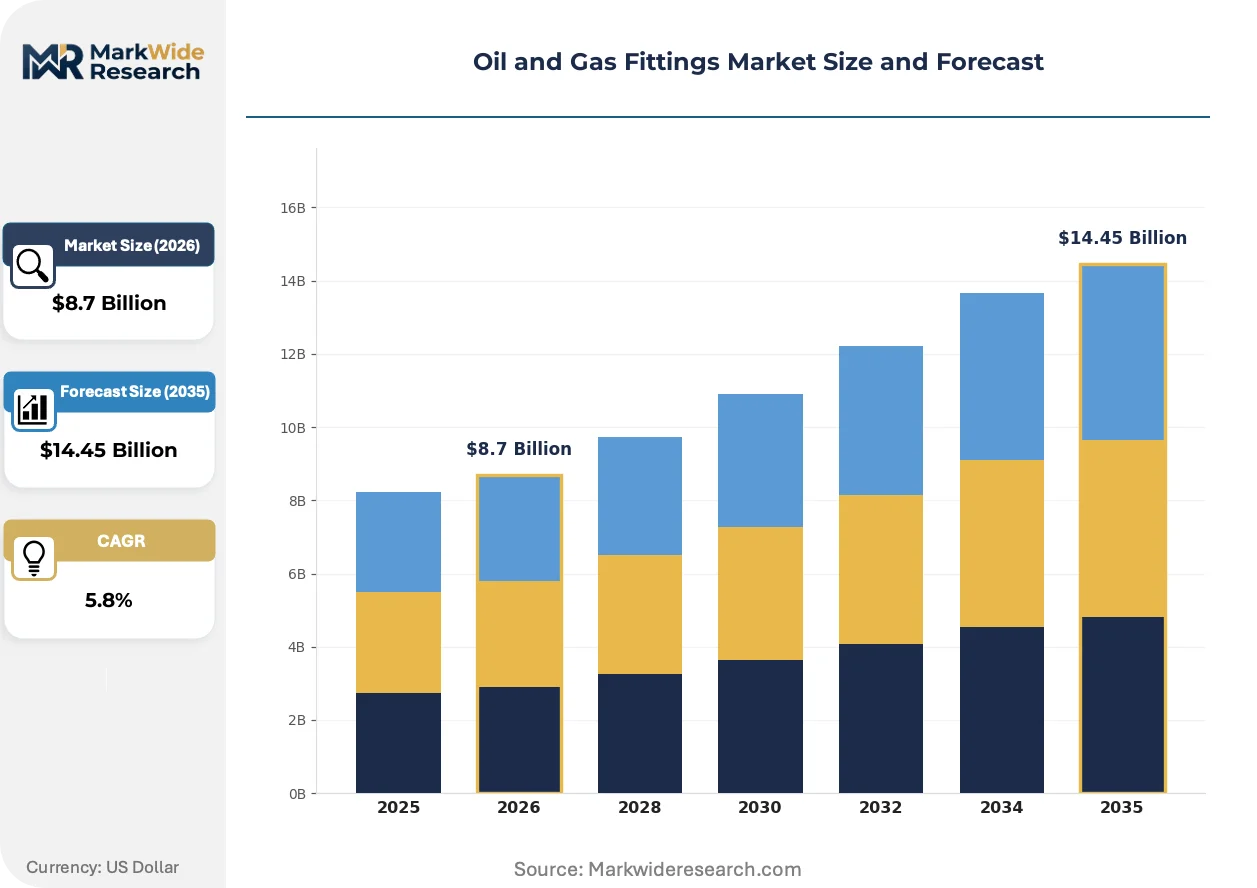
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flanges, Valves, Tees, Couplings Material: Stainless Steel, Carbon Steel, PVC, Copper Installation Type: Onshore, Offshore, Subsea, Above Ground End User: Exploration, Production, Refining, Distribution |
| Companies Covered | Parker Hannifin, Swagelok, Victaulic, Bonney Forge, Crane Co., Tylok International, Anvil International, Hy-Lok USA, FitTech Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Fittings Market Strategic Shifts
Material science advances and integrity management digitization are converging to redefine qualification protocols and procurement specifications across upstream through midstream infrastructure.
Metallurgical bonding via inertia friction welding is overtaking conventional threaded and flanged connections in subsea flowline applications. Deepwater engineering contractors at Petrobras and Equinor projects are specifying integral forged tees and wyes to eliminate leak paths. This fabrication method is overtaking legacy multi-piece assemblies in pressure ratings above 10,000 psi, compressing field installation time and reducing NDT inspection points by half.
REACH Annex XVII restrictions on chromium trioxide conversion coatings are forcing European forging houses to adopt trivalent chromium and zirconium-based passivation alternatives. The industrial consequence is elevated surface treatment costs and extended qualification timelines for corrosion-resistant finishes. Offshore projects in the North Sea and Norwegian Continental Shelf are most affected, with operators accepting 12-18 month coating validation cycles to maintain EU market access.
Integrated majors are consolidating supplier panels to capture volume leverage on standardized fitting specifications. Engineering procurement teams at ExxonMobil and Shell are reducing qualified vendor lists from dozens to single-digit preferred partnerships, displacing fragmented spot-buying through distributor networks. This concentration is most visible in US onshore shale developments, where pad drilling standardization enables multi-year master service agreements with fixed pricing mechanisms.
Oil and Gas Fittings Market Segmentation
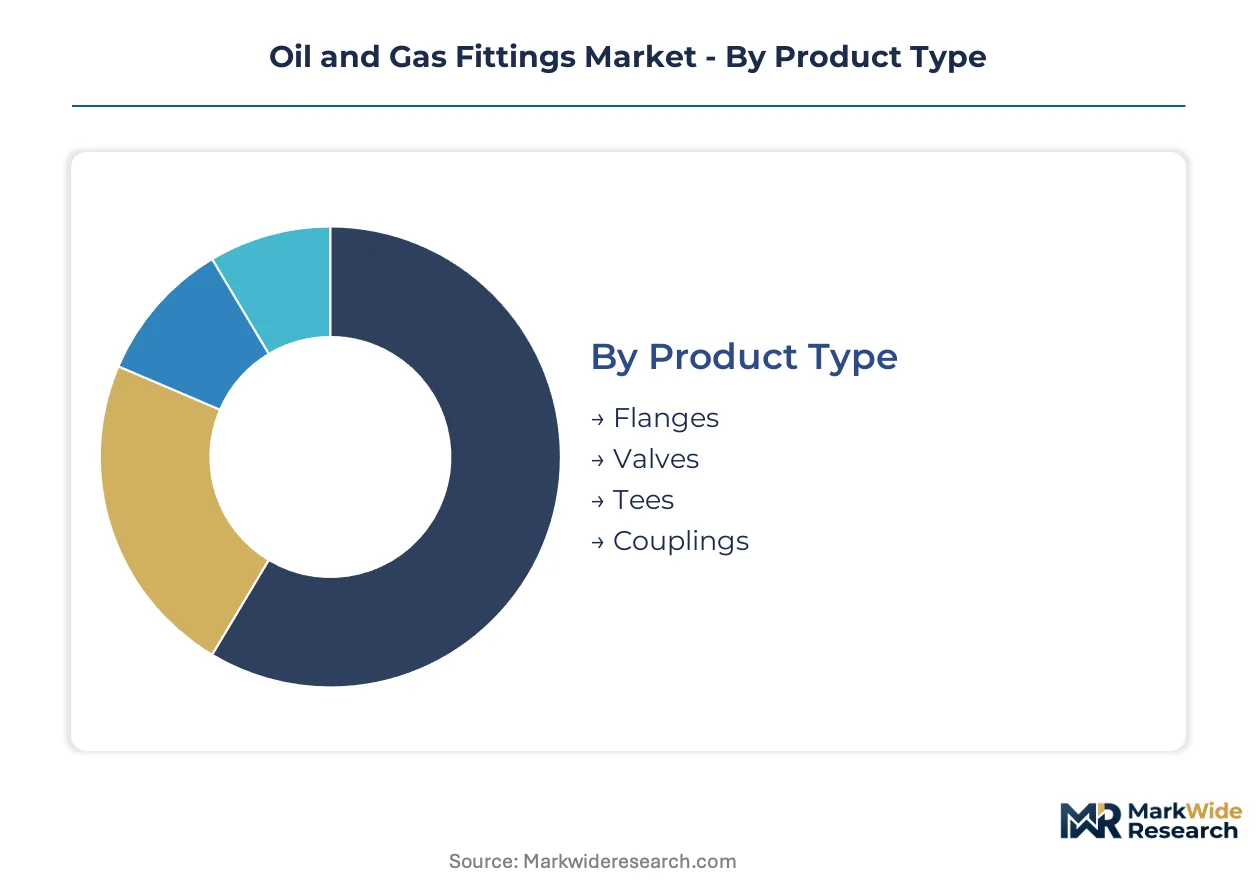
Segmentation in oil and gas fittings reflects divergent certification burdens across pressure ratings and corrosion environments. Procurement teams weight material traceability, subsea qualification protocols, and end-use criticality when qualifying vendors for specific infrastructure tiers.
Product Type:
API 6A governs wellhead and christmas tree equipment, while API 6D covers pipeline valves, creating distinct approval pathways across product categories.
- Flanges:Forged alloy steel connection points rated to 20,000 psi for wellhead and manifold assemblies. Demand concentrates in Permian Basin pad drilling where standardized flange dimensions enable rapid rig mobilization between wells.
- Valves:Flow control devices including gate, ball, and check configurations with stem sealing tested to API 598 leakage criteria. Brazilian pre-salt developments drive specification for metal-seated ball valves rated to 15,000 psi working pressure.
- Tees:Branch connection fittings integrating forged bodies with welded or flanged outlets.
- Couplings:Threaded or compression-sleeve joining components for tubular assemblies.
Leading the category by volume: Flanges. Growing fastest: Valves.
Material:
Cost tiers separate commodity carbon grades from premium corrosion-resistant alloys required in sour service and subsea applications.
- Stainless Steel:Austenitic and duplex grades including 316L, 2205, and 2507 specifications for chloride-rich environments. Norwegian Continental Shelf operators mandate super-duplex for subsea jumpers exposed to seawater and produced fluids.
- Carbon Steel:ASTM A105 and A350 LF2 forgings for onshore gathering and transmission lines in non-corrosive service. US midstream operators specify carbon steel for crude oil trunk lines where internal corrosion rates remain manageable.
- PVC:Thermoplastic piping for low-pressure water handling and secondary containment.
- Copper:Non-ferrous alloy for instrumentation tubing and cryogenic transfer lines.
Dominating procurement spend: Stainless steel. Expanding most quickly: Carbon steel in US shale gathering systems.
Installation Type:
Structural classification determines hydrostatic testing protocols, coating specifications, and inspection intervals mandated by integrity management programs.
- Subsea:Wet-mate and dry-mate connectors rated for full ocean depth with cathodic protection integration. Gulf of Mexico tieback developments multiply demand for compact flange systems reducing offshore welding hours.
- Offshore:Platform-mounted piping and riser components exposed to marine atmospheric corrosion. North Sea operators face OSPAR decommissioning timelines driving replacement demand for aging topside fittings.
- Onshore:Buried and above-ground pipeline assemblies in temperate and arctic climates.
- Above Ground:Elevated piping racks and compressor station interconnects requiring fire-safe valve specifications.
Capturing the largest installed base: Onshore. Gaining share fastest: Subsea.
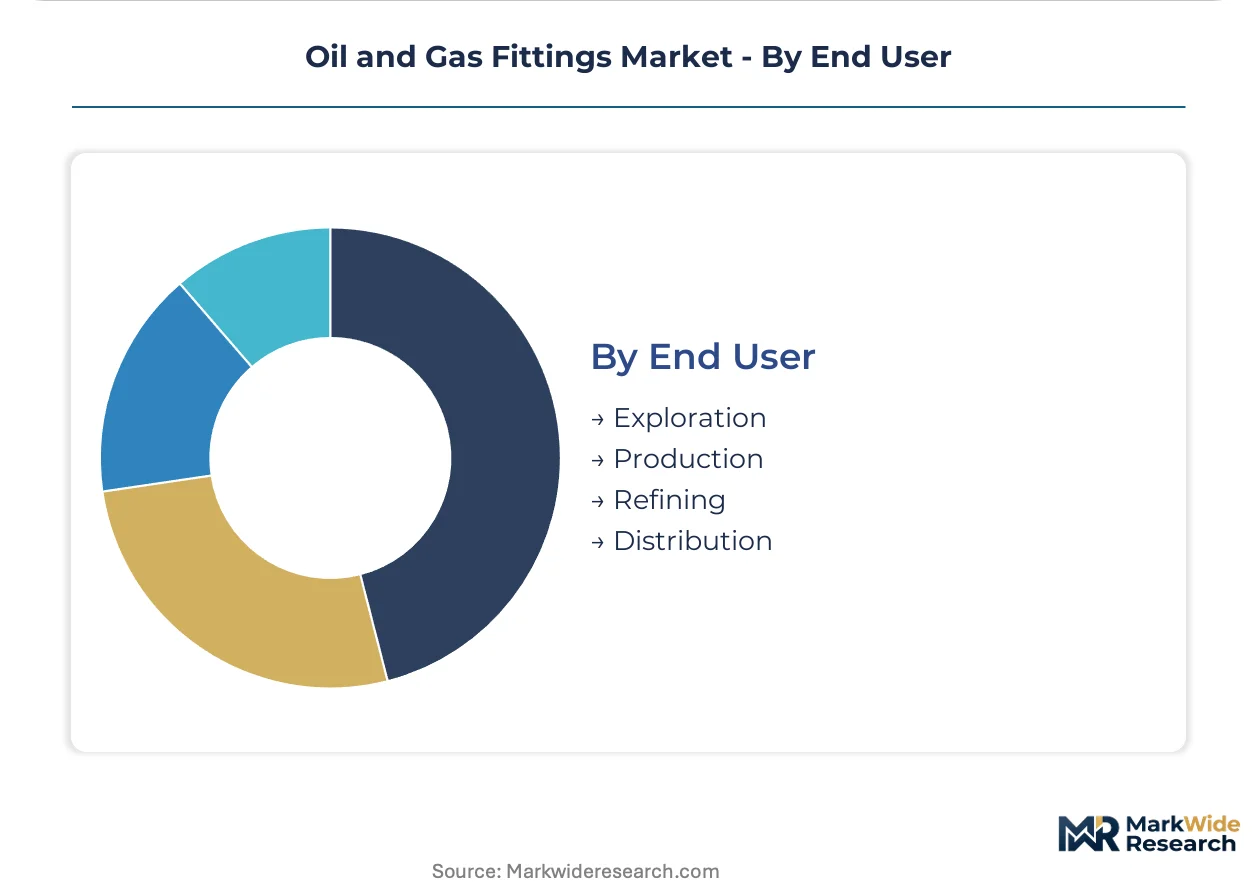
End User:
Customer maturity and procurement sophistication vary sharply between integrated majors and independent operators across the value chain.
- Production:Artificial lift, separation, and injection systems requiring high-cycle valve reliability. Bakken shale producers prioritize ball valve specifications with automated actuator integration for pad drilling efficiency.
- Exploration:Drilling riser and BOP stack connections with dynamic pressure loading. Deepwater contractors in Brazil specify fatigue-resistant riser couplings for extended reach wells.
- Refining:High-temperature catalytic cracking and hydrotreating unit piping.
- Distribution:City gate and custody transfer metering stations.
Generating highest fitting intensity: Production. Climbing the fastest: Exploration in deepwater basins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's pre-salt special maritime zones concentrate deepwater procurement activity, redirecting fabrication contracts toward domestic forging capacity under local content enforcement. Norway's North Sea tax depreciation frameworks accelerate subsea infrastructure replacement cycles. Gulf of Mexico shallow-water royalty relief programs sustain tieback development economics despite marginal field pressures.
United States
Permian Basin pad drilling standardizes flange specifications across multi-well pads, compressing rig mobilization intervals. FERC interstate pipeline safety regulations mandate material traceability for replacement cycles in aging gathering systems. Houston-Galveston corridor houses compact flange engineering contractors serving Gulf of Mexico floating production operators.
Brazil
Pre-salt carbonate reservoirs drive specification for 15,000 psi metal-seated ball valves in extended reach wells. ANP local content thresholds redirect high-pressure connector procurement toward domestic forging licensees. Macaé fabrication cluster hosts subsea manifold assembly yards qualifying duplex stainless grades under harmonized test protocols.
Norway
OSPAR decommissioning timelines force replacement demand for aging topside fittings across Ekofisk and Statfjord installations. NORSOK M-001 specifications shape super-duplex procurement for subsea jumpers exposed to seawater and produced fluids. Stavanger engineering centers anchor fatigue-resistant riser coupling design for Norwegian Continental Shelf deepwater developments.
United Kingdom
North Sea asset integrity programs accelerate hot-tap fitting demand for pipeline sectioning under statutory removal obligations. HSE offshore safety case regulations tighten weld procedure qualification requirements for subsea intervention systems. Aberdeen supply chain cluster concentrates grooved mechanical coupling distribution for platform modification contractors.
China
Shale gas development in Sichuan-Chongqing basin expands carbon steel gathering line specifications for non-corrosive service. MIIT equipment manufacturing standards govern pressure vessel certification for domestic exploration contractors. Shanghai-Pudong fabrication yards supply compact flange systems for CNOOC deepwater tieback projects in South China Sea.
Oil and Gas Fittings Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated majors consolidating supplier panels to capture volume leverage on standardized specifications. The vendor base concentrates around three strategic archetypes: forged alloy specialists with API 6A pre-qualification, precision instrumentation fabricators serving sour gas applications, and grooved mechanical coupling standard-setters for floating production platforms. Competitive moves center on multi-year master service agreements with fixed pricing mechanisms and pre-emptive duplex stainless grade qualification against harmonized test protocols.
Among North American-based system integrators, Parker Hannifin and Victaulic occupy positions at opposite ends of the engineering spectrum, with the former representing hydraulic connector specialization for deepwater riser systems and the latter anchoring mechanical coupling standardization across offshore platforms. Swagelok exemplifies the precision-tier archetype, with its instrumentation fitting focus aligning with sour gas application requirements. These three entities collectively illustrate how procurement concentration among integrated majors favors vendors with pre-established qualification depth across multiple regional certification regimes.
| Leading Market Players |
|---|
| Parker Hannifin |
| Swagelok |
| Victaulic |
| Bonney Forge |
| Crane Co. |
| Tylok International |
| Anvil International |
| Hy-Lok USA |
| FitTech Industries |
| Others |
Value Chain & Pricing Dynamics
Orbital welding technician scarcity in the Gulf Coast corridor widens labor-cost spreads between super-duplex fabrication tiers and standard carbon steel production, compressing margins for contractors without certified in-house welding capacity while enabling premium capture by qualified specialists serving deepwater projects.
Pricing Analysis
Lead-time premiums dominate transaction economics, with spot inventory of API 6A-qualified flanges trading at discounts to forged-to-order super-duplex jumpers requiring 26-week qualification cycles. Three-tier pricing structure across premium, standard, and economy levels separates subsea-rated alloy grades from gathering-line carbon specifications and distributor spot stock. Pricing pressure stems from nickel alloy input volatility on the London Metal Exchange, which erodes margin predictability for forged component specialists. Independent shale operators exhibit highest price sensitivity in standard flange procurement, while integrated majors absorb premiums for pre-qualified subsea inventory to compress project schedules.
Supply Chain Analysis
Freight costs for heavy-wall forgings pressure landed economics, with European and Japanese mill operators commanding logistics premiums on pressure classes above 15,000 psi. Geographic supply concentrates in Germany, Japan, and Italy for critical forging capacity, while China and India expand mid-pressure carbon steel fabrication. Raw material dependencies center on nickel cathode, molybdenum concentrate, and scrap alloy feedstock. Single-source vulnerability pervades super-duplex forging for subsea manifolds. Distribution runs through engineering-procurement-construction contractors and integrated major direct procurement panels, displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where API 6A specification upgrades and harmonized API-NORSOK test protocols erect qualification barriers that protect incumbents with pre-established certification depth while excluding capital-constrained challengers.
For Market Incumbents: Hedge nickel alloy exposure through long-term offtake agreements with Japanese and European mill operators to stabilize feedstock economics. Defend margin position by accelerating duplex stainless grade qualification against emerging subsea integrity management regulations before tender windows compress. Prioritize capacity addition in Macaé and Stavanger clusters to capture Brazil local content mandates and North Sea replacement cycles. For New Entrants and Emerging Players: Independent shale producers in the Permian Basin represent the most penetrable buyer archetype, as pad drilling standardization creates demand for rapid-turn carbon steel flange supply without subsea certification burdens. Target hot-tap fitting and isolation tool segments under North Sea OSPAR decommissioning timelines, where statutory removal obligations outrun incumbent capacity. Pursue go-to-market positioning through regional distributor partnerships rather than direct EPC contractor qualification. For Investors and Strategic Acquirers: Re-rating potential sits with forged alloy specialists holding API 6A pre-qualification across multiple regional certification regimes given procurement panel consolidation among integrated majors. Long-term viability favors vendors with backward integration into heavy-wall forging capacity and captive heat-treatment facilities. Watch for hydrogen-ready material certification inflection as 316L and 347H stainless grades capture specification preference in repurposed natural gas network tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-emptive Duplex Grade Qualification | Harmonized API-NORSOK protocols accelerate tender participation before competitors complete validation cycles. |
| Backward Integration into Forging Capacity | Captive heavy-wall production insulates margin from European and Japanese mill operator concentration risk. |
| Hydrogen-Ready Material Certification | Early 316L and 347H embrittlement testing positions vendors for repurposed natural gas infrastructure tenders. |
| Digital Twin Integration Partnerships | Sensor-embedded fittings capture specification preference among majors deploying predictive maintenance platforms. |
| Local Content Compliance Investment | Brazil ANP threshold adherence redirects pre-salt procurement toward domestic forging licensees. |
Study Parameters
Independent corroboration across API certification databases, NORSOK M-001 compliance registries, and ANP local content filings underwrites the qualitative findings. Primary interviews with subsea engineering contractors, forging house procurement directors, and integrated major supplier qualification managers combined with secondary validation from customs trade data, SEC equipment supplier filings, and project development databases. Bottom-up and top-down triangulation cross-checks vendor shipment records against operator capital expenditure disclosures.
Rate-of-change decomposition separates volume growth from price-mix effects across the analysis window. Segmentation dimensions modeled include pressure rating tier, material specification grade, installation environment, and end-use criticality. CAGRs derive from fitted trend extrapolation adjusted for regulatory inflection points. Forecast inputs incorporate subsea tieback proliferation rates and decommissioning obligation timelines.
Revisions become necessary when nickel alloy price volatility exceeds historical bands, when regional certification bodies introduce unscheduled protocol harmonization, or when local content enforcement thresholds shift materially. Forecasts reflect documented assumptions about project sanctioning rates and forging capacity expansion schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
US Oil and Gas Infrastructure Market
Oil & Gas
Ecuador Oil and Gas Midstream Market
Oil & Gas
Oil and Gas Pipeline and Transportation Automation Market
Oil & Gas
Uzbekistan Oil and Gas Market
Oil & Gas
Russian Federation Oil and Gas Downstream Market
Oil & Gas
Saudi Arabia Drilling Services Market
Oil & Gas
Indonesia Oil and Gas Market
Oil & Gas
Asia-Pacific Well Intervention Market
Oil & Gas
Well Abandonment Services Market
Oil & Gas
Singapore LNG Storage Tank Market
Oil & Gas
Flexible Pipes for Oil and Gas Market
Oil & Gas
Australia LNG Bunkering Market
Oil & Gas
US Sand Control Systems Market
Oil & Gas
Pipeline Pigging Services Market
Oil & Gas
Oil and Gas Hose Assemblies Market
Oil & Gas
Oilwell Spacer Fluids Market